
 Global Commercial Pumps Market | 2026-2036
Global Commercial Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Pumps Market Analysis
Subscription-based predictive maintenance is hardening into a core revenue layer for pump OEMs. Grundfos Holding A/S leverages its digital service platform to lock in recurring revenue from commercial water systems. Xylem anchors its growth through smart monitoring integrations that reduce client downtime. KSB SE & Co. KGaA differentiates with condition-based service contracts tied to critical infrastructure uptime.
Commercial pumps are mechanical devices engineered to move fluids through pressure differentials, typically operating at flow rates from 10 to over 10,000 gallons per minute and heads exceeding 500 feet for industrial applications. Their primary purpose is to sustain circulation, transfer, and pressurization across building services, process industries, and municipal infrastructure. Centrifugal pumps occupy the dominant volume position due to their efficiency in high-flow, low-viscosity water applications, while positive displacement pumps command premium margins in chemical processing where precise dosing and high-pressure output matter. Solar-powered technology segments are expanding fastest in off-grid agricultural and remote mining deployments, though electric drives retain the structural majority across urban commercial installations.
The US EPA Energy Star program and the EU Ecodesign Directive enforce minimum efficiency standards that filter non-compliant products from transatlantic procurement channels. China's GB standards for motor efficiency and India's BIS certification for agricultural pump sets add compliance layers that shape regional product portfolios. Stakeholders must monitor how tightening carbon accounting under the EU CSRD redirects capital toward lifecycle-optimized pump systems over first-cost procurement.
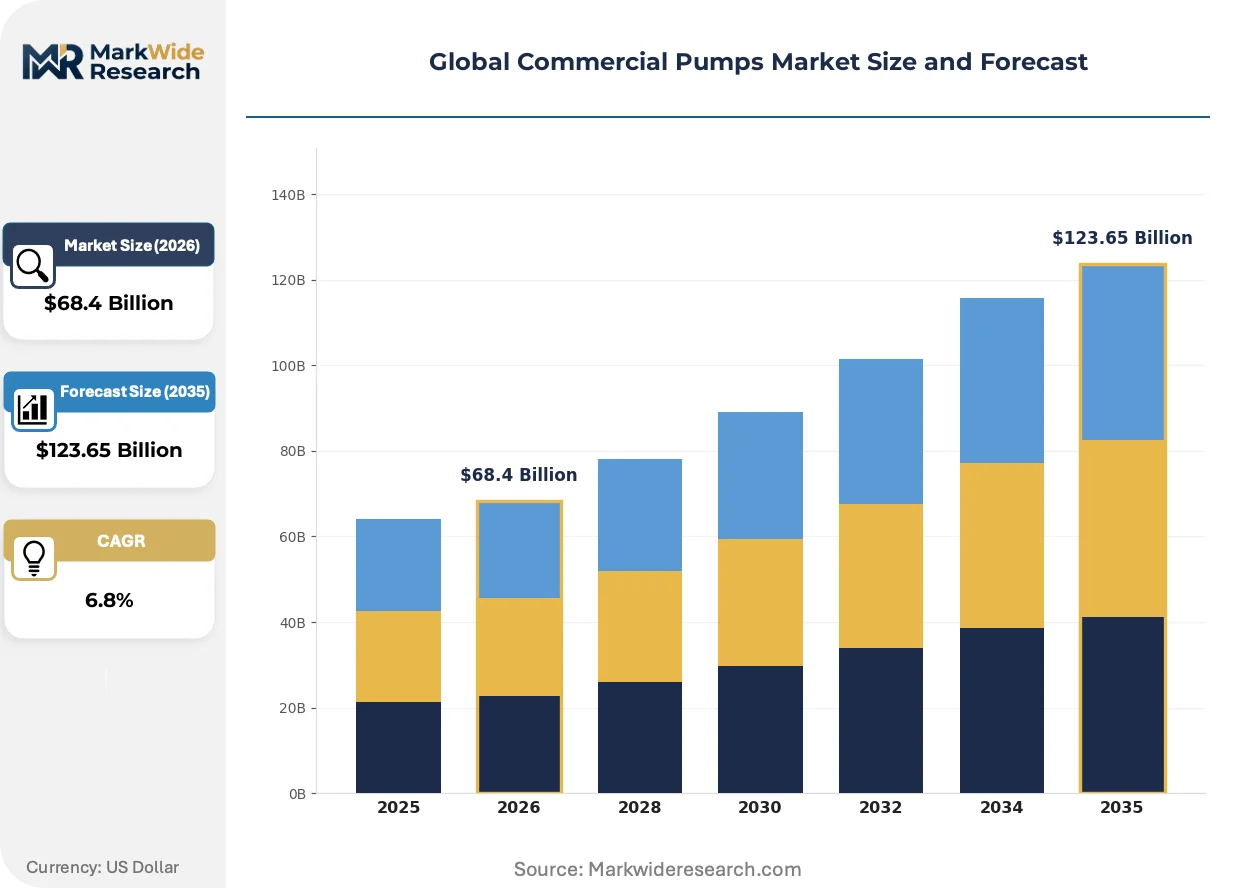
Market Dynamics
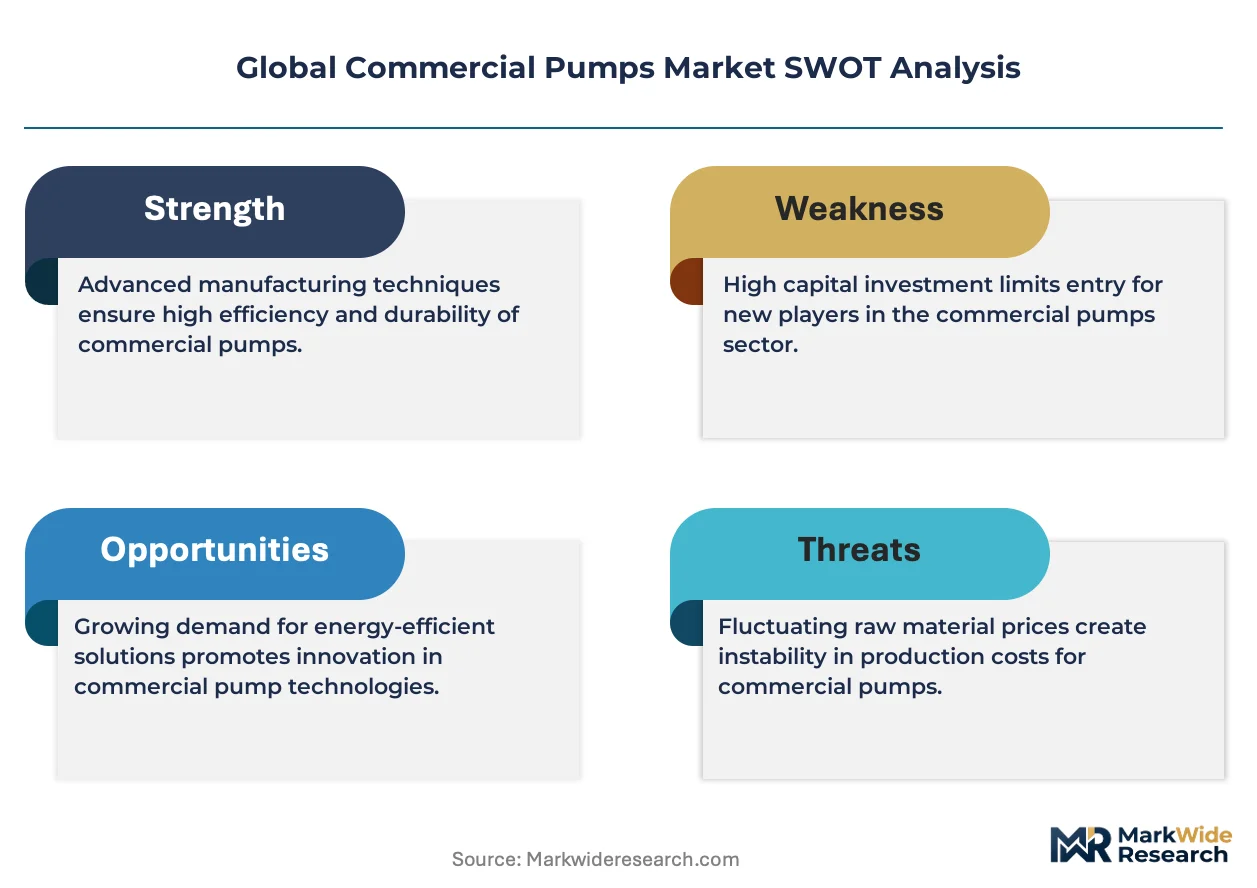
Energy-efficiency mandates are compressing product lifecycles as water utilities and industrial operators face simultaneous pressure from carbon accounting rules and electricity cost volatility. The EU Ecodesign Directive's escalating motor efficiency tiers now force premature replacement of installed pump bases.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency requirements for rotating equipment are filtering non-compliant products from transatlantic procurement channels, creating replacement demand across municipal water systems.
- India's solar pump subsidies:The PM-KUSUM scheme accelerates off-grid agricultural installations, expanding addressable market for DC-powered submersible units in groundwater-dependent farming belts.
- China's industrial corridor concentration:Petrochemical clusters in Jiangsu and Zhejiang provinces are consolidating process water infrastructure, driving bulk procurement of high-head centrifugal systems.
Market Restraints
- Copper and rare earth price volatility:Permanent magnet motor costs fluctuate with neodymium supply from Chinese processing facilities, squeezing margins on premium efficiency tiers.
- Foundry capacity concentration:Ductile iron casting for pump housings concentrates in Indian and Chinese supplier networks, exposing lead times to regional energy rationing.
- Submersible motor sealing limitations:Current elastomer technology caps reliable operation depth at 800 feet in high-salinity aquifers, blocking deep geothermal and offshore applications.
Strategic Opportunities
- Indonesia's nickel processing boom:Hydrometallurgical facilities in Sulawesi and Halmahera require corrosion-resistant chemical transfer pumps at scale unmatched by local supply.
- Digital twin convergence:Integration of vibration sensors with cloud-based hydraulic modeling enables predictive maintenance contracts that capture lifetime service revenue.
- US IRA clean water funding:The Infrastructure Investment and Jobs Act directs capital toward lead service line replacement, expanding demand for precision excavation dewatering equipment.
Industry Challenges
- Mechatronics skill scarcity:Field technicians capable of diagnosing integrated variable frequency drive faults are concentrated in OEM service networks, limiting third-party maintenance competition.
- ATEX certification timelines:European explosion-proof pump approvals for Zone 1 chemical environments average 14 months, delaying product launches for specialty applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Pumps Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Diaphragm Pumps Application: Water Supply, Fire Protection, Chemical Processing, HVAC End User: Agriculture, Mining, Manufacturing, Construction Technology: Electric, Diesel, Solar, Pneumatic |
| Companies Covered | Grundfos Holding A/S, Xylem, KSB SE & Co. KGaA, Flowserve Corporation, Pentair, Sulzer Ltd., Ebara Corporation, ITT Inc., Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Pumps Market Emerging Trajectories
Digital service platforms are hardening into primary competitive battlegrounds as hardware commoditization accelerates. OEMs now capture value through uptime guarantees rather than unit sales alone.
Plug-and-play pump skids with integrated controls are modularizing project delivery for commercial building services. MEP contractors in Germany and the Netherlands are specifying pre-configured packages that compress installation schedules from weeks to days. This standardization is modularizing the traditional split between equipment procurement and controls integration, eroding margins for pure-play distributors.
The EU Corporate Sustainability Reporting Directive tightens lifecycle disclosure requirements for capital equipment. Water utilities in France and Italy must now document Scope 3 emissions from supplier networks, redirecting procurement toward vendors with verified Environmental Product Declarations. Pump OEMs with ISO 14040-compliant lifecycle assessments are securing preferred supplier status in competitive tenders.
Building operators are unbundling maintenance from capital purchase, forcing distributors to restructure service capabilities. Facility management platforms in Singapore and the UAE are aggregating multi-site pump portfolios into single-source performance contracts. This aggregation is compressing supplier counts per geography and privileging vendors with regional spare parts depots over import-dependent competitors.
Global Commercial Pumps Market Segmentation
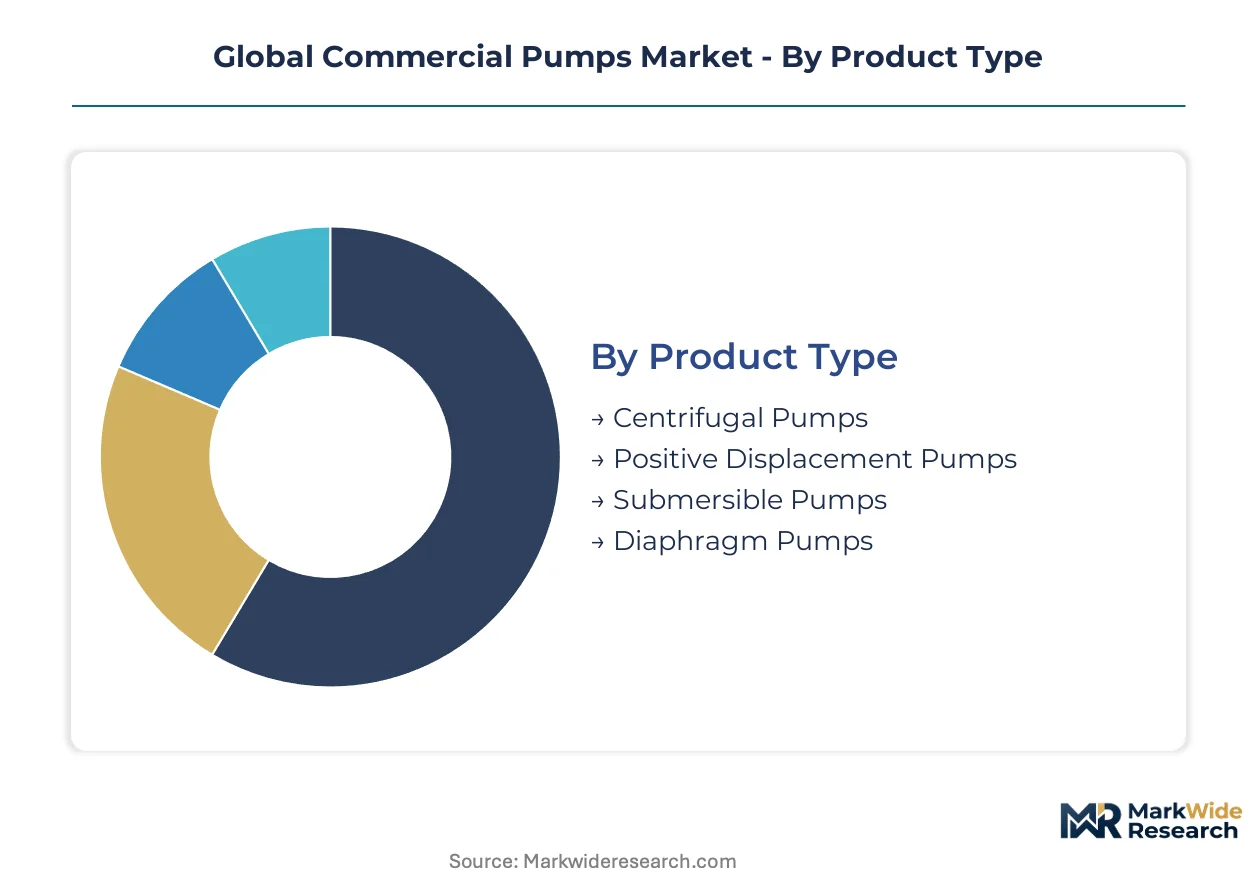
Commercial pump procurement splits sharply between high-volume, low-margin water infrastructure and premium-priced process equipment. Segment boundaries increasingly blur as OEMs bundle predictive digital services with hardware across all tiers.
Product Type:
Centrifugal pumps dominate unit volumes while positive displacement systems command the steepest price premiums per kilowatt.
- Centrifugal Pumps:Radial and mixed-flow impeller designs handle 90% of commercial water transfer applications at flow rates exceeding 1,000 GPM. Municipal utilities in Germany and the Netherlands specify these for district heating networks under EU Ecodesign Directive pressure.
- Positive Displacement Pumps:Rotary lobe and gear configurations deliver precise volumetric output for viscous fluids and high-pressure chemical injection. Petrochemical clusters in Texas and Louisiana deploy these for hydrocracker feed systems where shearing losses disqualify centrifugal alternatives.
- Submersible Pumps:Wet-wound motor designs with dual mechanical seals serve groundwater extraction in India's agricultural belts under PM-KUSUM subsidy programs.
- Diaphragm Pumps:Air-operated double-diaphragm configurations isolate pumped media from mechanical components in semiconductor chemical handling.
Mature deployment sits with centrifugal pumps. Newer deployment is concentrated in positive displacement systems for precision chemical processing.
Application:
Water supply absorbs the largest capital allocation while chemical processing generates the highest service contract attach rates.
- Water Supply:Booster stations and raw water intake systems constitute the baseline procurement category for municipal utilities. China's Jiangsu province is consolidating rural water networks, driving bulk orders for multi-stage vertical turbine configurations.
- Fire Protection:UL-listed and FM-approved centrifugal units with diesel backup power serve high-rise commercial structures. Dubai's building code mandates jockey pump systems with automated testing protocols for structures exceeding 75 meters.
- Chemical Processing:ANSI and ISO 2858 standard pumps with Alloy 20 or Hastelloy wetted parts handle corrosive process streams.
- HVAC:Inline circulators with ECM motors replace fixed-speed legacy units in European building retrofits under Energy Performance of Buildings Directive targets.
Installed base concentration favors water supply. Fastest expansion is occurring in chemical processing as reshoring accelerates specialty chemical production.
End User:
Mining and agriculture drive the most demanding duty cycles while manufacturing presents the most standardized specification environments.
- Agriculture:Solar-powered submersible sets with MPPT controllers extract groundwater for irrigation in off-grid farming regions. India's BIS certification requirements for agricultural pump sets filter out low-efficiency imports.
- Mining:High-head slurry pumps with hardened impellers and volutes manage tailings transport and pit dewatering. Chile's copper belt operators specify these for altitude-compensated performance at 4,000+ meter elevations.
- Manufacturing:Process cooling and washdown systems utilize standardized close-coupled centrifugal units with minimal customization.
- Construction:Portable dewatering pumps with automatic level controls serve excavation and tunneling projects.
Equipment longevity requirements peak in mining. Solar integration is advancing most quickly in agriculture.
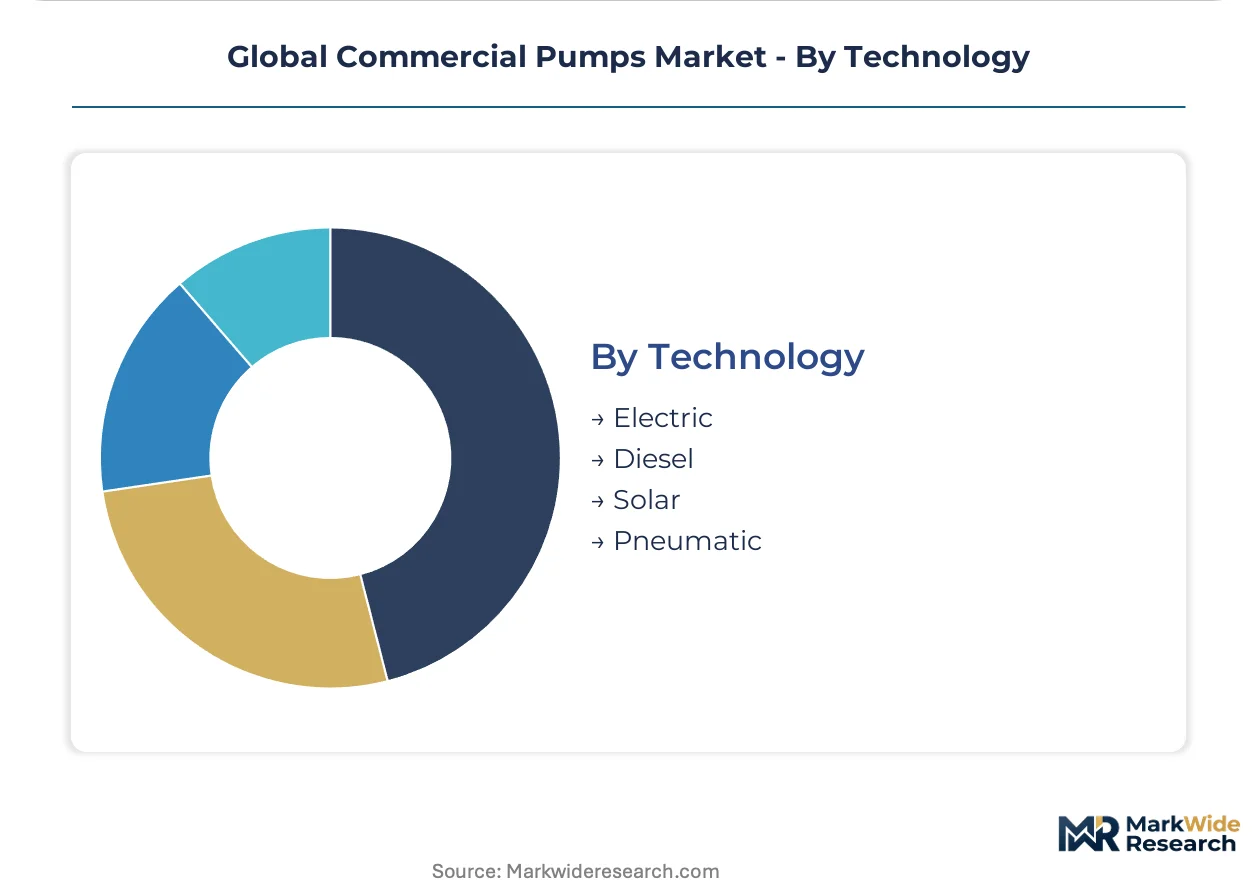
Technology:
Electric drives retain structural majority while solar segments expand fastest in regions with weak grid infrastructure.
- Electric:IE4 and IE5 premium efficiency motors with integrated variable frequency drives dominate commercial building services. US EPA Energy Star certification filters procurement for federal and municipal projects.
- Solar:DC brushless motor designs with surface-mounted permanent magnets eliminate inverter losses in off-grid deployments. Kenya's irrigation cooperatives are aggregating demand for these systems under World Bank rural electrification programs.
- Diesel:Mobile and emergency backup configurations serve fire protection and construction dewatering where grid reliability is insufficient.
- Pneumatic:Compressed-air-driven diaphragm pumps operate in explosive atmospheres without electrical ignition risks.
Established infrastructure favors electric technology. Pneumatic systems retain niche dominance in ATEX Zone 1 chemical environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Chinese and Indian foundry networks while consumption splits between mature replacement cycles in Western Europe and capacity expansion across Asian industrial corridors. The EU Ecodesign Directive and India's PM-KUSUM scheme are reshaping procurement specifications in their respective markets.
United States
Water infrastructure replacement and data center cooling expansion drive demand across municipal and commercial sectors. The EPA Energy Star program filters federal procurement toward premium efficiency tiers. Texas petrochemical clusters along the Gulf Coast are consolidating process water systems, requiring high-head centrifugal configurations.
Germany
District heating network modernization and industrial decarbonization targets accelerate pump replacement cycles. The EU Ecodesign Directive enforces IE4 motor minimums that disqualify legacy installed bases. The Ruhr industrial region is retrofitting multi-stage vertical turbine systems for combined heat and power integration.
China
Jiangsu and Zhejiang petrochemical corridors are consolidating process water infrastructure at scale unmatched elsewhere. GB motor efficiency standards and dual carbon goals redirect procurement toward lifecycle-optimized systems. Shanghai's municipal water authority is bulk-procuring smart monitoring-integrated booster stations.
India
PM-KUSUM subsidies are accelerating solar-powered agricultural pump deployment across groundwater-dependent farming belts. BIS certification requirements for agricultural pump sets filter out low-efficiency imports. Gujarat's industrial estates are specifying corrosion-resistant chemical transfer pumps for specialty chemical manufacturing expansion.
Indonesia
Hydrometallurgical nickel processing facilities in Sulawesi and Halmahera require corrosion-resistant chemical transfer pumps at volumes exceeding local supply capacity. The country's national industrial regulator is tightening environmental discharge standards for mining operations. Jababeka industrial estate near Jakarta is attracting pump system integrators serving Southeast Asian project markets.
Global Commercial Pumps Market Vendor Landscape
Top-tier vendors anchor premium service-contract revenue, while mid-tier fabricators compete on first-cost procurement in emerging markets. The vendor base stratifies across three tiers: integrated digital service platforms, regional pump specialists with foundry-to-assembly control, and import-dependent distributors. Two strategic archetypes dominate: OEMs capturing lifetime value through predictive maintenance subscriptions, and foundry-integrated manufacturers defending margin through captive casting capacity. Competitive moves center on M&A for digital capability acquisition and backward integration into permanent magnet motor production.
Within the integrated digital service tier, Grundfos Holding A/S and Xylem exemplify platform-based recurring revenue models. KSB SE & Co. KGaA occupies a position bridging premium European manufacturing with condition-based service contract penetration in critical infrastructure. These three represent divergent archetypes: Danish platform integration, US smart monitoring anchoring, and German condition-based uptime guarantees.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Xylem |
| KSB SE & Co. KGaA |
| Flowserve Corporation |
| Pentair |
| Sulzer Ltd. |
| Ebara Corporation |
| ITT Inc. |
| Parker Hannifin |
| Others |
Supply Flow & Price Mechanics
Foundry technicians with wet-wound motor expertise concentrate in Jiangsu and Zhejiang provinces, creating labor-cost differentials that separate premium European OEM pricing from mid-tier Asian manufacturing spreads across centrifugal and submersible pump categories.
Pricing Analysis
Margin tightening in standard-efficiency tiers traces to neodymium price volatility squeezing permanent magnet motor costs, while premium IE4 and IE5 configurations defend spreads through Energy Star and EU Ecodesign Directive compliance bundling. Three-tier pricing structure across premium, standard, and economy levels separates condition-based service contracts from transactional hardware sales from unbranded foundry-direct procurement. Municipal utilities in Germany and the Netherlands exhibit lowest price sensitivity due to lifecycle accounting mandates, whereas agricultural cooperatives in India demonstrate highest sensitivity under PM-KUSUM subsidy caps.
Supply Chain Analysis
Dual-sourcing requirements from European water utilities now mandate qualified foundries in both China and India for ductile iron castings, compressing single-source dependency risks that dominated procurement through 2020. Permanent magnet motors draw from Chinese rare earth processing and Japanese magnet fabrication, while mechanical seals and bearings rest on German and Swiss precision manufacturing. Tariff exposure on Chinese castings threatens margin structures for import-dependent distributors. Distribution runs through OEM-direct service networks for critical infrastructure and regional pump specialists for commercial building projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into permanent magnet motor production and captive foundry capacity represents the decisive vertical-integration race, as hardware commoditization accelerates and service-contract attach rates determine lifetime value capture.
For Market Incumbents: Cement platform-based recurring revenue through predictive maintenance subscriptions that lock municipal utilities into multi-year uptime guarantees. Acquire regional service networks in Southeast Asia to defend against emerging Chinese OEMs expanding through Indonesia's nickel processing boom. Prioritize ISO 14040-compliant lifecycle assessments to secure preferred supplier status under EU CSRD procurement filters.
For New Entrants and Emerging Players: Launch via solar-powered DC submersible specialization targeting Kenya's irrigation cooperatives and India's PM-KUSUM agricultural belts, where incumbent service infrastructure remains underdeveloped. Target corrosion-resistant chemical transfer pumps for Indonesia's hydrometallurgical facilities, where local supply capacity lags demand from Sulawesi and Halmahera processing clusters. Pursue white-label foundry partnerships with Indian ductile iron casters to bypass capital-intensive backward integration.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier foundry-integrated manufacturers given EU Ecodesign Directive replacement cycles accelerating hardware refresh demand across German and Dutch municipal systems. Long-term viability favors vendors with captive casting capacity and digital service platform architecture over pure-play distributors exposed to margin compression. Watch ATEX certification backlog durations as inflection indicator for specialty chemical pump supply constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive neodymium supply hedges Chinese processing concentration and defends IE4/IE5 tier margins. |
| Digital Twin Platform Deployment | Vibration sensor integration with cloud hydraulic modeling enables predictive maintenance contract revenue capture. |
| Regional Foundry Acquisition in India | Ductile iron casting capacity secures supply chain resilience against Chinese energy rationing disruptions. |
| ISO 14040 Lifecycle Assessment Certification | Environmental Product Declaration compliance unlocks preferred supplier status under EU CSRD procurement mandates. |
| Solar Pump System Specialization | DC brushless motor designs with MPPT controllers penetrate off-grid agricultural markets in Kenya and India. |
Methodological Framework
Multi-period observation of municipal procurement patterns, motor efficiency tier adoptions, and service contract penetration rates anchored the trend analysis, supplemented by interviews with maintenance directors at water utilities, plant engineers in petrochemical clusters, OEM procurement teams, and aftermarket service heads. Secondary validation drew from customs trade data for pump and motor imports, SEC 10-K filings for publicly traded vendors, EU Ecodesign Directive implementation reports, and Indian BIS certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for industrial capital expenditure.
Input-output matrices modeled unit shipments and average selling prices across product type, application, end user, and technology dimensions throughout the forecast period. CAGRs derived from regression analysis against industrial production indices, water infrastructure investment flows, and agricultural mechanization rates. Forecast inputs incorporated PM-KUSUM subsidy allocation trajectories, EU Ecodesign Directive tier escalation schedules, and nickel processing capacity buildouts in Indonesia.
Neodymium supply disruptions, EU regulatory timeline accelerations, and Chinese foundry energy rationing are the dominant revision risks to baseline projections. Deviation in rare earth magnet pricing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Solar Fountain Pumps Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Global Lubrication Pumps Market