
 Global Hydraulic Gear Pump Market | 2026-2036
Global Hydraulic Gear Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Gear Pump Market Outlook
OEMs in construction equipment are bifurcating from aftermarket rebuilders as the primary volume purchasers of hydraulic gear pumps. Bosch Rexroth AG leverages its captive foundry and machining network to anchor supply contracts with European excavator builders. Eaton Corporation sustains a dominant position in North American mobile hydraulics through extensive distributor channel control. Parker Hannifin Corporation differentiates via integrated motion and control systems that bundle gear pumps with valves and electronic controllers.
A hydraulic gear pump converts mechanical rotational energy into fluid power through the meshing of precisely machined gear profiles, typically achieving volumetric efficiencies above 85% at pressures ranging from 175 to 250 bar. These units serve as the primary fluid displacement source in open-circuit hydraulic systems for mobile machinery and industrial power units. External gear pumps occupy the largest share of unit volume due to simpler manufacturing and lower cost thresholds, while internal gear pumps command margin premiums in noise-sensitive applications such as aerial work platforms and precision material handling. Fixed displacement designs dominate the installed base across construction and agricultural machinery, though variable displacement configurations are gaining traction in hybrid drivetrain prototypes where energy recovery functions require flow modulation.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine downsizing that increases hydraulic system operating pressures and demands tighter volumetric efficiency tolerances from pump suppliers. ISO 4406 cleanliness standards and REACH material restrictions on certain seal compounds shape product design cycles and qualification timelines for European and North American manufacturers. Stakeholders must monitor how Chinese GB standards for construction machinery hydraulics evolve, as domestic certification requirements could redirect sourcing patterns for multinational OEMs operating joint ventures in Asia.
Market Dynamics
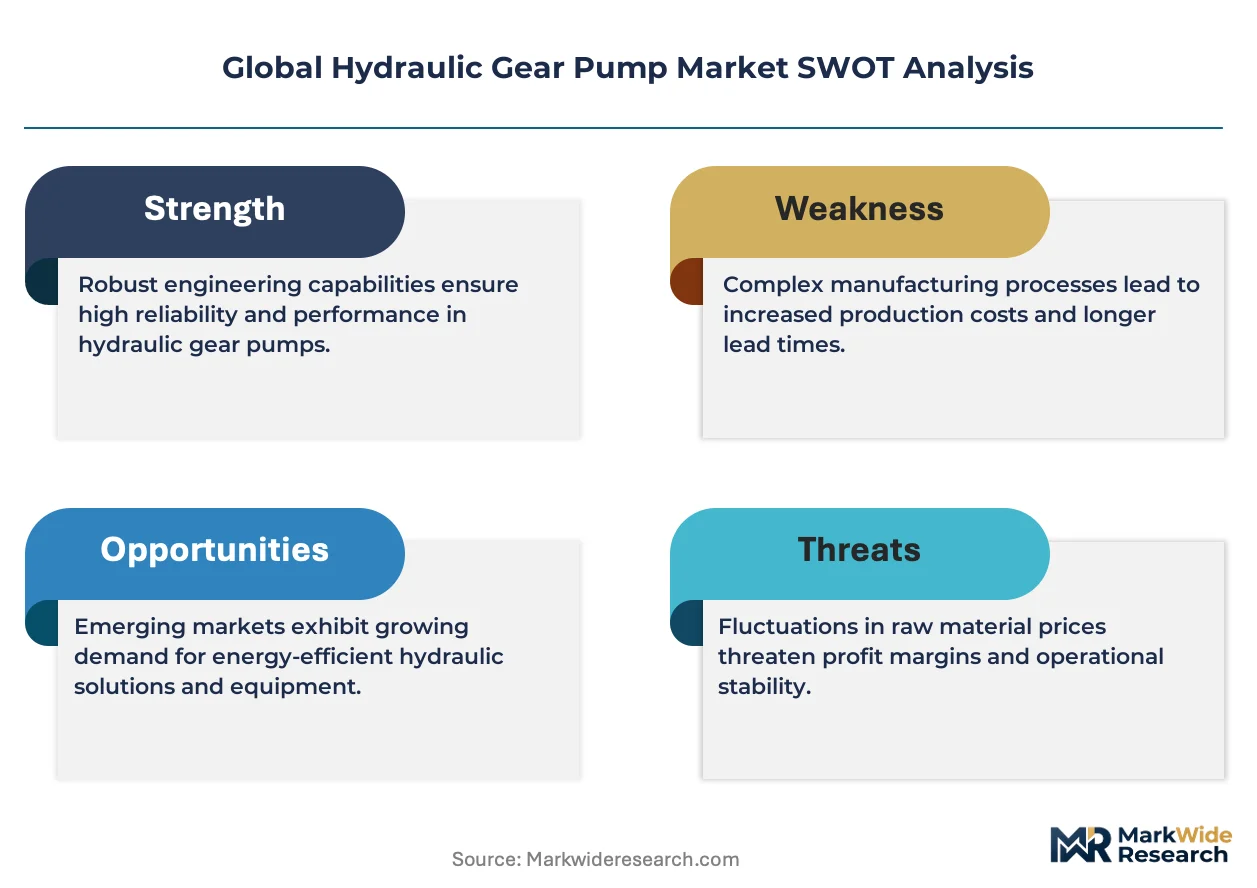
Engine downsizing mandates from EPA Tier 4 Final and EU Stage V are forcing hydraulic system redesigns that demand higher-pressure gear pumps with tighter volumetric tolerances, compressing supplier qualification timelines and favoring foundry-integrated manufacturers.
Growth Catalysts
- Excavator fleet electrification:Hybrid drivetrain prototypes require variable displacement gear pumps for energy recovery functions, opening specification windows for flow-modulation-capable suppliers.
- EU Stage V compliance:Emissions frameworks push OEMs toward higher-efficiency hydraulic architectures that prioritize pumps achieving 85%+ volumetric efficiency at 250 bar operating pressure.
- German precision manufacturing clusters:Concentrated machine tool and construction equipment production sustains premium consumption of low-noise internal gear pumps for noise-sensitive applications.
Market Restraints
- Aluminum alloy casting supply:Captive foundry capacity concentrates among vertically integrated majors, limiting second-tier suppliers' access to precision housing castings at scale.
- REACH seal compound restrictions:Material limitations on certain elastomer formulations extend qualification timelines for European and North American manufacturers serving regulated markets.
- Electronic displacement control:Electromechanical actuation systems threaten fixed-displacement gear pump volumes in next-generation hybrid architectures.
Strategic Opportunities
- Chinese GB standard evolution:Domestic certification requirements for construction machinery hydraulics could redirect sourcing patterns for multinational OEMs operating joint ventures in Asia.
- Integrated motion systems:Bundling gear pumps with proportional valves and CAN-enabled electronic controllers addresses OEM demand for simplified hydraulic architectures.
- Aerial work platform electrification:Noise-sensitive applications favor internal gear pump configurations that command margin premiums over external gear alternatives.
Industry Challenges
- ISO 4406 cleanliness compliance:Tighter fluid contamination standards require manufacturing environments and testing protocols that strain capital budgets for mid-tier suppliers.
- Legacy system integration:Open-circuit hydraulic architectures in installed construction and agricultural machinery constrain retrofit opportunities for advanced pump designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Gear Pump Market |
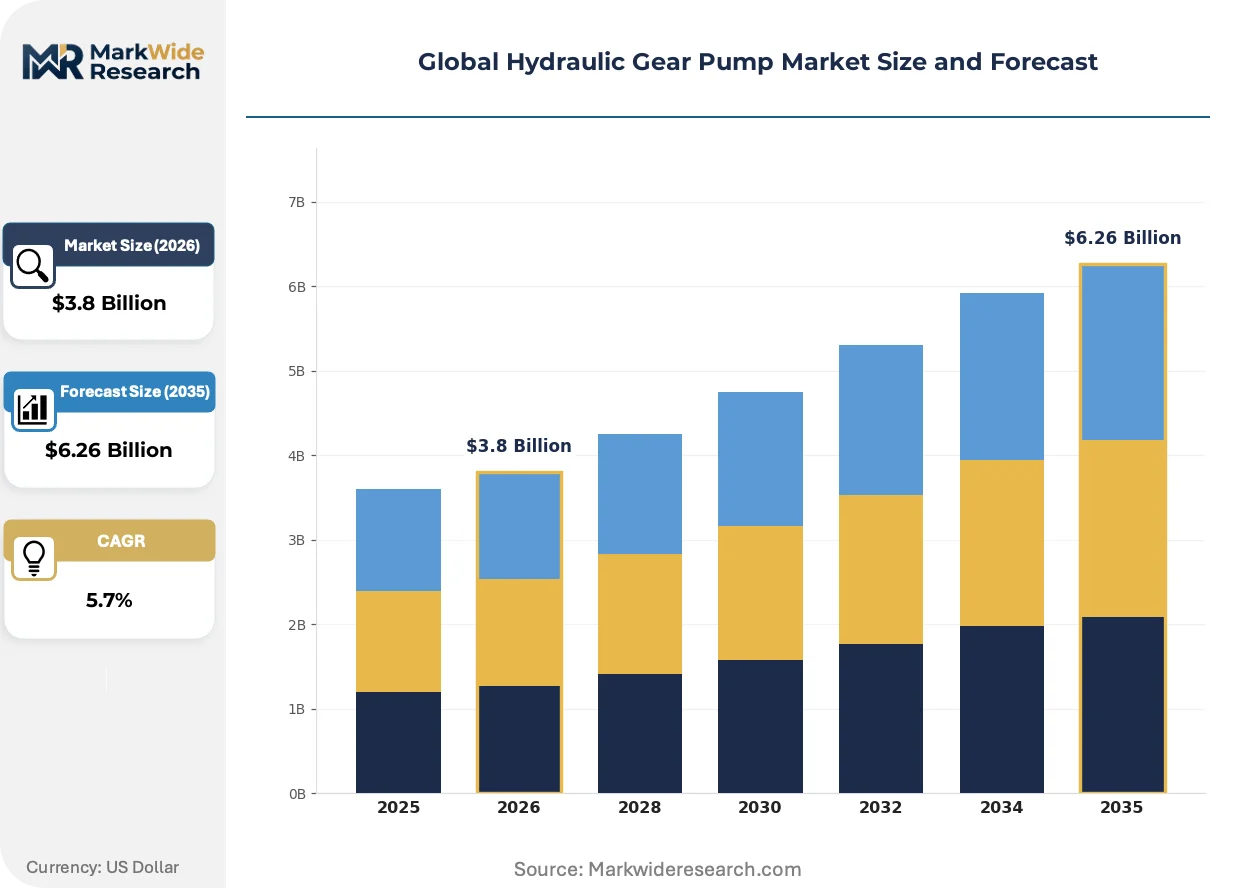
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Gear Pumps, Internal Gear Pumps, Gear Motors, Others Application: Construction Equipment, Agricultural Machinery, Material Handling, Automotive End User: Manufacturing, Oil & Gas, Transportation, Aerospace Design Type: Fixed Displacement, Variable Displacement, Special Design, Custom Solutions |
| Companies Covered | Bosch Rexroth AG, Eaton Corporation, Parker Hannifin Corporation, Bucher Hydraulics, KYB Corporation, CASAPPA S.p.A., Linde Hydraulics GmbH & Co. KG, Kawasaki Heavy Industries Ltd., Dynamatic Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Gear Pump Market Strategic Shifts
Compact power density requirements are reshaping gear pump architectures across mobile machinery segments. Suppliers are integrating electronic controls directly into pump housings while pursuing material innovations that withstand elevated thermal loads from downsized powertrains.
Advanced composite gear materials are miniaturizing pump footprints without sacrificing displacement capacity. Aerial work platform OEMs in Europe and North America specify these configurations for weight-critical boom lift applications. The technology is miniaturizing hydraulic power units in confined installation envelopes while maintaining 175-250 bar pressure ratings.
REACH material restrictions are forcing seal compound reformulations across European supply chains. Manufacturers must qualify alternative elastomers that satisfy both chemical compatibility and temperature performance requirements. German and Italian pump producers face the steepest recertification burdens as they serve Stage V-regulated excavator and loader markets.
Buyer concentration among construction equipment OEMs is consolidating procurement leverage around multi-year supply agreements. Distributor channels serving aftermarket rebuilders face margin compression as volume concentrates with fleet operators and authorized service networks. China and the United States exhibit the most pronounced buyer consolidation, with top-ten excavator manufacturers controlling dominant specification influence.
Global Hydraulic Gear Pump Market Segmentation
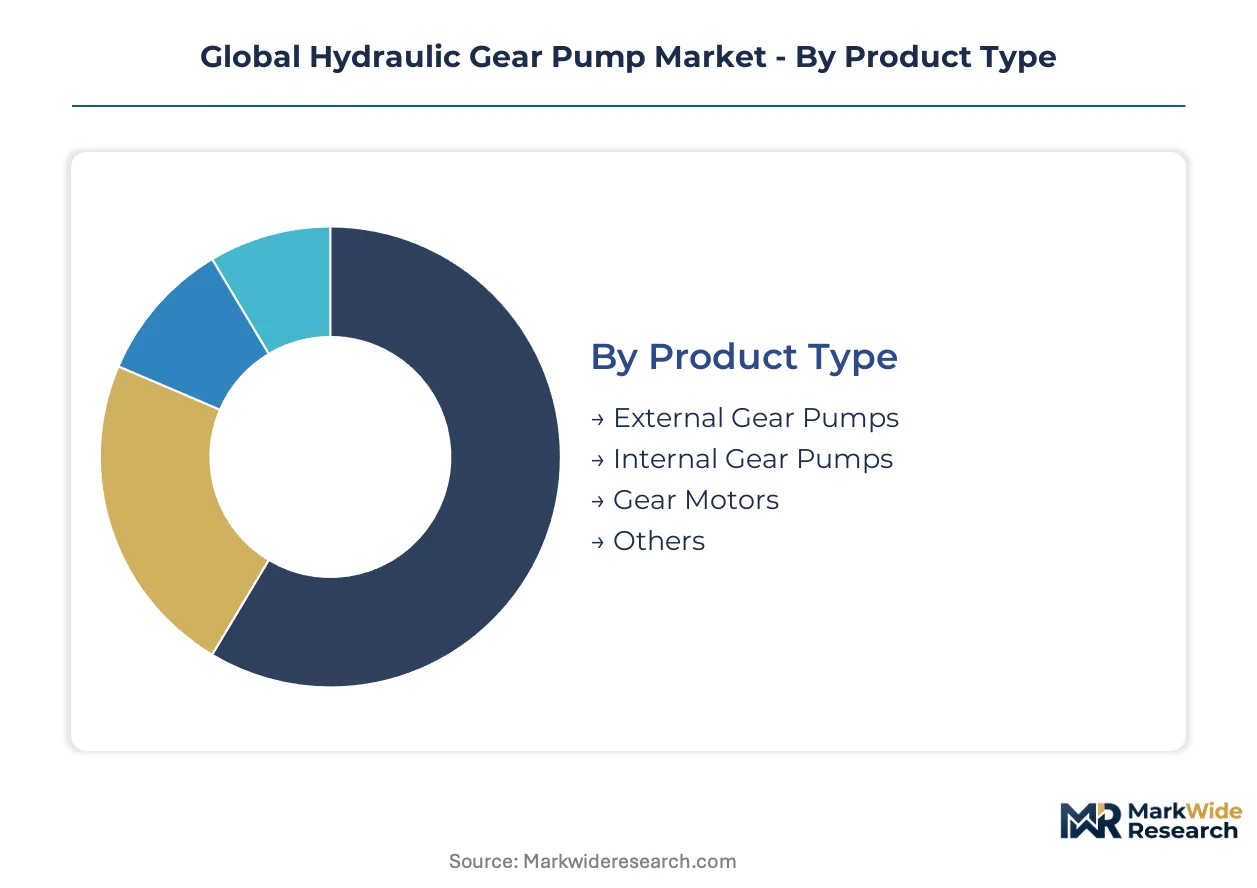
Segmentation in hydraulic gear pumps reveals how technical specifications align with end-use economics. Substitution threats from electromechanical actuation and piston pump alternatives vary sharply across product architectures, reshaping supplier investment priorities.
Product Type:
External gear configurations face the most acute substitution pressure from compact piston pumps in high-pressure mobile applications, while internal gear designs defend position through noise-performance differentiation.
- External Gear Pumps:Meshing of identical external gears in a close-tolerance housing delivers the simplest manufacturing pathway among positive-displacement pumps. Demand concentrates in Chinese and US construction equipment fleets where cost-per-unit dominates procurement criteria and EPA Tier 4 Final engine downsizing has not yet displaced fixed-displacement architectures.
- Internal Gear Pumps:A crescent-shaped partition separates the larger driving rotor from the smaller internal idler gear, reducing flow pulsation and acoustic signature. German aerial work platform OEMs and precision material handling equipment builders in Stuttgart and Milan specify these configurations for noise-sensitive indoor operations.
- Gear Motors:Reversed fluid flow geometry converts hydraulic pressure into rotational mechanical output for winch and conveyor drives.
- Others:Specialized configurations including gerotor and screw-type variants serve niche medical and aerospace auxiliary power applications.
External gear pumps anchor the volume base while internal gear pumps gain share at the steepest rate.
Application:
Cost tier stratification separates premium-specification mobile machinery from price-sensitive agricultural implements.
- Construction Equipment:Excavator and loader hydraulic systems demand continuous-duty pumps rated for 250 bar peak pressure with ISO 4406 cleanliness compliance. Japanese and Korean OEMs operating in China specify these units for hybrid drivetrain prototypes requiring flow modulation capability.
- Agricultural Machinery:Tractor implement circuits and harvester drives prioritize unit cost over volumetric efficiency at elevated pressure. Brazilian and Indian farm equipment manufacturers source fixed-displacement external gear pumps through distributor channels with minimal electronic integration.
- Material Handling:Forklift and automated guided vehicle hydraulic power units require compact envelope dimensions with acceptable noise thresholds for warehouse environments.
- Automotive:Power steering assist and transmission lubrication circuits consume small-displacement pumps with automotive-grade production scale economics.
Construction equipment commands the dominant revenue share while material handling applications expand most quickly through warehouse automation investment.
End User:
Customer type concentration creates divergent procurement patterns between specification-driven OEMs and price-sensitive aftermarket rebuilders.
- Manufacturing:Machine tool hydraulic power units and metal forming presses require precision-manufactured pumps with tight volumetric tolerances. German automotive stamping plants and Japanese precision equipment builders specify low-noise internal gear configurations with integrated proportional valve packages.
- Oil & Gas:Offshore platform power units and wellhead control systems demand corrosion-resistant materials and explosion-proof certifications.
- Transportation:Commercial vehicle power take-off units and rail maintenance equipment utilize robust external gear pumps with extended service intervals.
- Aerospace:Auxiliary hydraulic systems for flight control surface actuation require lightweight aluminum housings with stringent FAA certification documentation.
Manufacturing absorbs the largest installed base while aerospace specifications deliver the highest margin realization per unit.
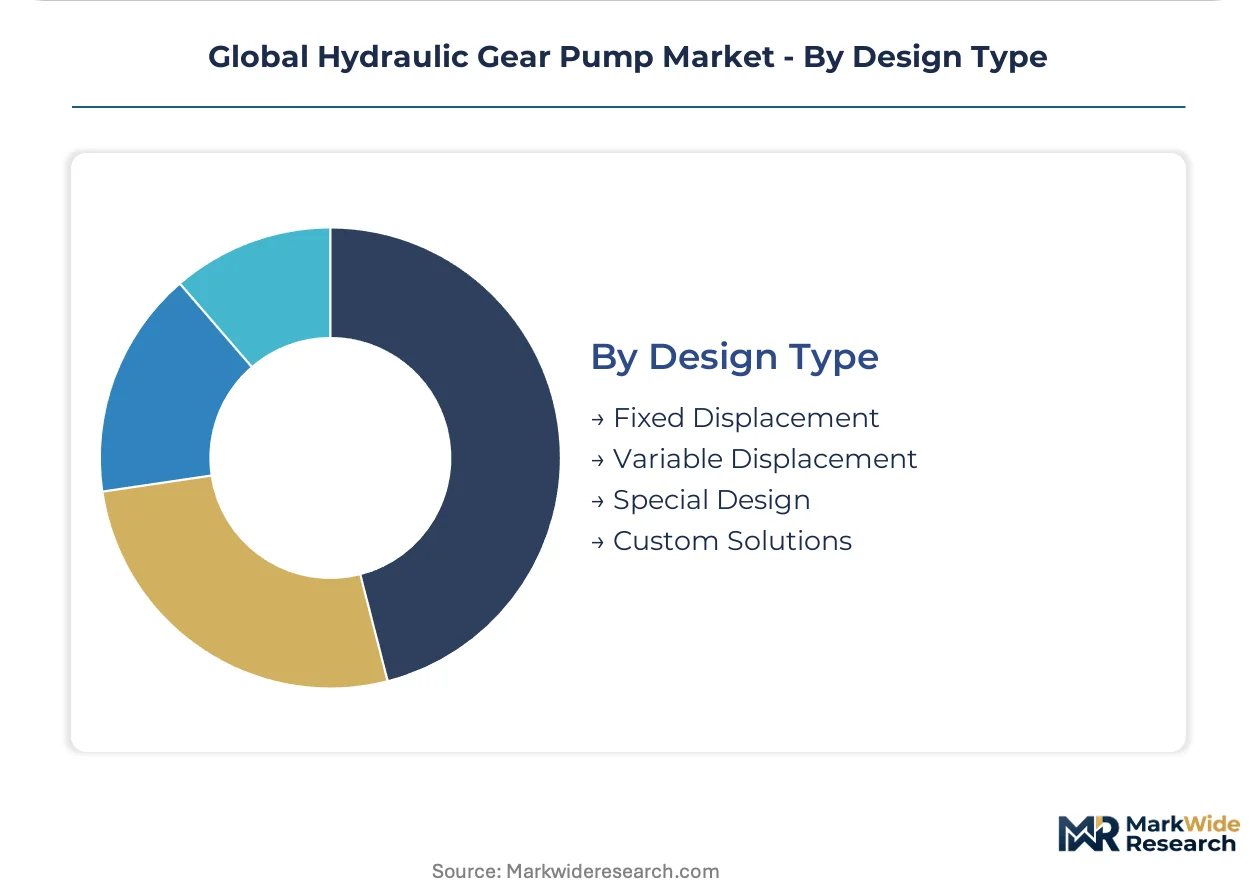
Design Type:
Volume concentration in mature fixed-displacement architectures contrasts with emerging specification for flow-modulation capability in hybrid drivetrains.
- Fixed Displacement:Constant flow-per-revolution output simplifies system architecture and minimizes electronic complexity. Chinese excavator OEMs and Indian backhoe loader manufacturers specify these designs for cost-optimized fleet production where energy recovery functions remain absent.
- Variable Displacement:Swashplate or porting geometry modifications enable flow modulation in response to load demand signals. European construction equipment hybrid prototypes utilize these configurations to capture regenerative braking energy and reduce engine parasitic losses.
- Special Design:Seal-less magnetic drive configurations and high-temperature alloy variants serve chemical processing and steel mill applications.
- Custom Solutions:Application-specific porting arrangements, shaft geometries, and mounting interfaces address legacy equipment retrofit requirements.
Fixed displacement designs retain the dominant unit volume while variable displacement configurations climb the fastest through electrification roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pump exports supply precision-manufactured units to Japanese and Korean excavator builders operating joint ventures in China. This trade corridor channels premium hydraulic components toward Asia-Pacific construction equipment assembly plants.
United States
EPA Tier 4 Final emissions rules drive hydraulic system redesigns for domestic excavator and loader fleets. The EPA mandates higher-efficiency architectures that prioritize pumps achieving elevated volumetric efficiency ratings. Midwest manufacturing clusters around Detroit and Chicago sustain demand for fixed-displacement external gear pumps in cost-optimized agricultural machinery.
Germany
EU Stage V compliance frameworks push OEMs toward low-noise internal gear configurations for noise-sensitive applications. ECHA REACH restrictions on certain seal compounds extend qualification timelines for domestic manufacturers. Stuttgart and Milan precision manufacturing clusters specify these premium pumps for aerial work platforms and material handling equipment.
China
Domestic excavator OEMs expand procurement of fixed-displacement units for fleet production amid infrastructure investment cycles. MIIT and evolving GB standards for construction machinery hydraulics reshape certification requirements. Yangtze River Delta manufacturing bases concentrate assembly capacity for multinational joint ventures sourcing localized pump supply.
Japan
Hybrid drivetrain prototypes from Tokyo and Osaka-based OEMs require variable displacement gear pumps for energy recovery functions. METI industrial policy supports electrification roadmaps in mobile machinery. Nagoya-area precision equipment builders specify integrated motion systems bundling pumps with electronic controllers.
India
Tractor implement circuits and harvester drives prioritize unit cost over elevated pressure performance. BIS certification requirements and PLI scheme incentives shape sourcing patterns for farm equipment manufacturers. Gujarat and Maharashtra industrial corridors host distributor channels serving price-sensitive agricultural machinery production.
Global Hydraulic Gear Pump Market Competitive Environment
Player mix skews toward foundry-integrated European majors and North American diversified hydraulics conglomerates. Market structure concentrates specification influence among construction equipment OEMs with multi-year supply agreements. Two strategic archetypes dominate: vertically integrated manufacturers with captive casting capacity, and motion-control specialists bundling pumps with electronic systems. Competitive moves center on backward integration into precision housing production and strategic partnerships for hybrid drivetrain qualification.
Among Germany-based hydraulics specialists, Bosch Rexroth AG and Linde Hydraulics GmbH & Co. KG exemplify the foundry-integrated archetype with upstream control over casting and machining networks. Eaton Corporation and Parker Hannifin Corporation represent North American diversified players positioned across mobile hydraulics and integrated motion systems. Bucher Hydraulics and CASAPPA S.p.A. occupy positions within the European precision-tier segment serving noise-sensitive applications.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Eaton Corporation |
| Parker Hannifin Corporation |
| Bucher Hydraulics |
| KYB Corporation |
| CASAPPA S.p.A. |
| Linde Hydraulics GmbH & Co. KG |
| Kawasaki Heavy Industries Ltd. |
| Dynamatic Technologies |
| Others |
Value Chain & Pricing Dynamics
EPA Tier 4 Final and EU Stage V emissions frameworks simultaneously gate supplier qualification timelines and stratify price realization across certification tiers, compressing margins for non-compliant producers while rewarding foundry-integrated manufacturers with pricing power in premium specification windows.
Pricing Analysis
Fixed-displacement external gear pumps anchor economy-tier positioning for Chinese and Indian construction equipment fleets, while variable displacement configurations command premium pricing for European hybrid drivetrain prototypes requiring flow modulation capability. Three-tier pricing structure across premium, standard, and economy levels reflects volumetric efficiency ratings, ISO 4406 cleanliness compliance grades, and captive foundry integration status. Cost compression in external gear segments intensifies as Brazilian and Indian agricultural machinery manufacturers prioritize unit cost over pressure performance. Aftermarket rebuilders exhibit acute price sensitivity relative to OEM specification engineers who prioritize energy efficiency and noise performance thresholds.
Supply Chain Analysis
Germany, China, and the United States concentrate precision housing casting capacity and machining networks for hydraulic gear pump production. Aluminum alloy foundry output, precision gear steel, and REACH-compliant seal compounds constitute critical input dependencies. Single-source vulnerability concentrates in captive foundry capacity controlled by vertically integrated majors such as Bosch Rexroth AG and Eaton Corporation. Distribution runs through authorized distributor channels serving OEM procurement teams and aftermarket service networks, with direct supply agreements dominating fleet operator volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical actuation systems threaten fixed-displacement gear pump volumes in next-generation hybrid architectures, forcing incumbents to defend position through integrated motion system bundling and variable displacement qualification.
For Market Incumbents: Secure multi-year supply agreements with Japanese and Korean excavator builders operating joint ventures in China before GB standard evolution redirects sourcing patterns. Deepen backward integration into precision aluminum housing production to insulate margin structure from foundry capacity constraints. Prioritize CAN-enabled electronic controller integration to defend against electromechanical displacement control substitution in hybrid drivetrain prototypes. For New Entrants and Emerging Players: Anchor in Indian agricultural machinery distributor channels serving Gujarat and Maharashtra tractor implement manufacturers where price sensitivity exceeds specification rigor. Target Brazilian harvester drive applications with fixed-displacement external gear configurations that bypass captive foundry barriers through third-party casting partnerships. Pursue qualification partnerships with European aerial work platform OEMs seeking noise-reduced internal gear alternatives for indoor warehouse deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across variable displacement gear pump development programs requiring electronic control integration and hybrid drivetrain qualification. Long-term viability favors acquisition targets with demonstrated ISO 4406 compliance infrastructure and existing relationships with German precision manufacturing clusters. Monitor Chinese GB standard publication timelines as inflection indicators for joint venture sourcing redirection and domestic certification requirement escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive foundry capacity insulates Bosch Rexroth and Eaton from aluminum alloy supply constraints. |
| Variable Displacement Qualification | Flow modulation capability opens specification windows with European hybrid excavator OEMs. |
| Integrated Motion System Bundling | Proportional valve and CAN controller integration addresses OEM demand for simplified hydraulic architectures. |
| REACH-Compliant Seal Compound Reformulation | Alternative elastomer qualification maintains European market access under ECHA material restrictions. |
| Chinese GB Standard Certification Investment | Domestic certification alignment secures supply position with multinational joint ventures in Asia. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings from diversified hydraulics conglomerates, and ISO certification registries preceded structured interviews with OEM procurement directors, aftermarket distributor channel managers, foundry operations executives, and hydraulic system design engineers. Primary fieldwork across German precision manufacturing clusters, Yangtze River Delta assembly bases, and Midwest agricultural machinery corridors combined with secondary validation from ECHA REACH documentation and EPA Tier 4 Final compliance filings. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Analytical variance decomposes across product type, application, end user, and design type dimensions, with additional segmentation by regional regulatory cluster reflecting EU Stage V, EPA Tier 4 Final, and evolving Chinese GB standard frameworks. CAGRs derive from pressure rating evolution trajectories, electrification roadmap penetration assumptions, and foundry capacity expansion timelines throughout the forecast period. Hybrid drivetrain prototype volumes and energy recovery function adoption rates constitute critical industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure investment cycles and stable emissions regulatory frameworks; material deviation in aluminum alloy pricing or GB standard acceleration would warrant model refresh. Recalibration cycles align with material shifts in excavator fleet electrification roadmaps and Chinese domestic certification requirement publications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Industrial Aerators Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Global Leak Detection Solutions Market