
 Maraging Steel Market | 2026-2036
Maraging Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Maraging Steel Market Foresight
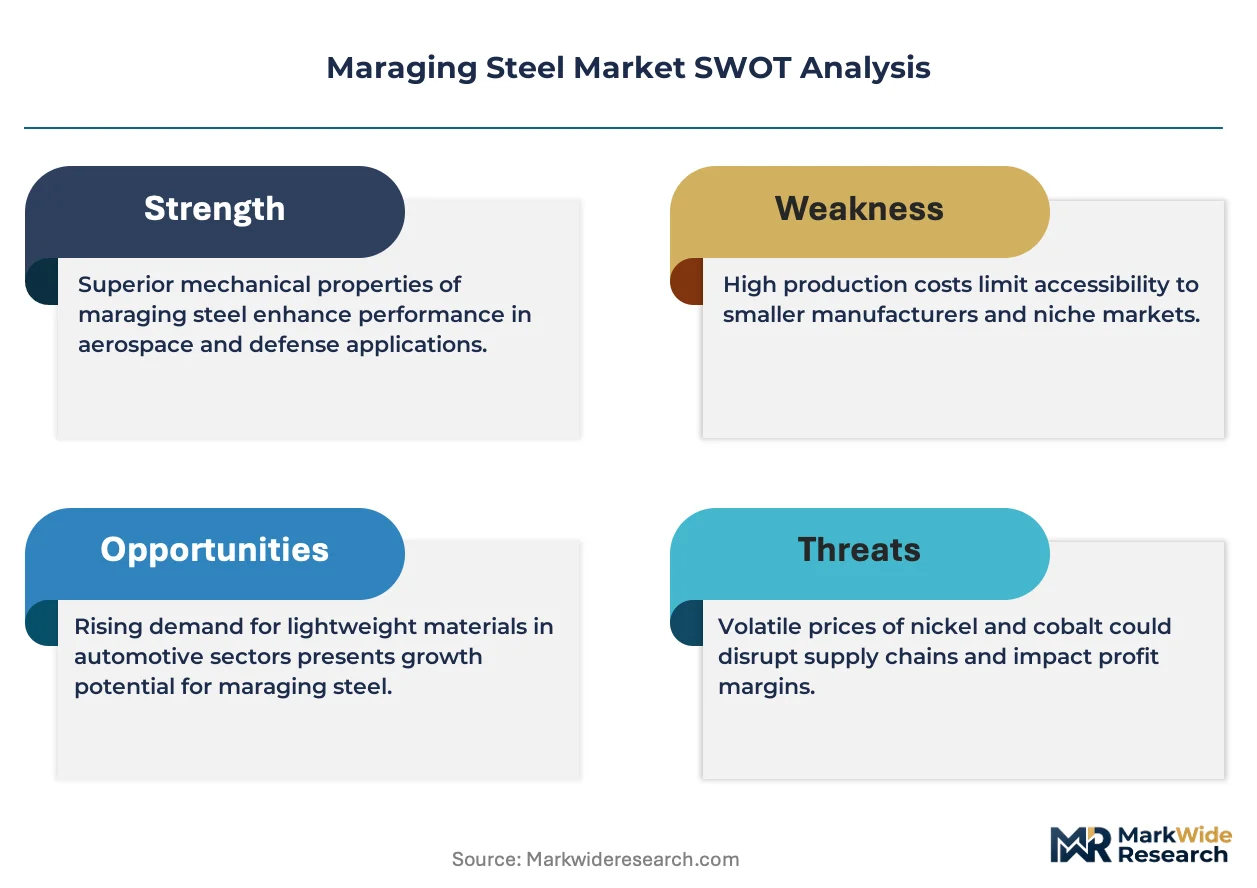
Project finance tied to defense procurement programs is tilting competitive access toward suppliers with long-term government contracts. Dongbei Special Steel Group leverages its integrated cobalt-nickel supply chain to control input costs for Maraging 350 grades. Voestalpine anchors European tooling demand through specialized bar and plate production in Austria. Carpenter Technology Corporation differentiates via vacuum induction melting capabilities that sustain premium positioning in aerospace-qualified material.
Maraging steel denotes a class of ultra-high-strength iron-nickel alloys hardened by intermetallic precipitates rather than carbon, typically containing 18% nickel with cobalt, molybdenum, and titanium additions, achieving yield strengths exceeding 2400 MPa after age-hardening. Aerospace applications dominate value consumption, with Maraging 350 commanding the highest margins in solid rocket motor casings where strength-to-weight ratios determine payload capacity. Tooling applications represent the fastest-growing segment as Maraging 250 bar stock displaces conventional die steels in high-pressure aluminum die-casting operations. Sheet and plate forms retain mature demand profiles in defense armor systems, while tube products occupy niche positions in high-pressure hydraulic systems for offshore equipment.
The U.S. Department of Commerce's Bureau of Industry and Security shapes export licensing requirements for maraging steel grades above 2400 MPa yield strength, restricting technology transfer to specific end-users. REACH compliance through ECHA mandates full material disclosure for cobalt content, elevating traceability costs for European tooling providers sourcing from non-EU mills. Japan's METI maintains JIS standards for aerospace-grade maraging steel that PMDA recognizes in medical device tooling applications. Stakeholders must monitor evolving dual-use export controls and alloy substitution research in additive manufacturing feedstocks that could displace wrought maraging products in select defense applications.
Market Dynamics
The Defense Production Act's domestic sourcing mandates are restructuring supply access, privileging mills with long-term government contracts while cobalt-nickel supply concentration in Central Africa amplifies input cost volatility.
Growth Catalysts
- Defense Procurement Mandates:The U.S. Defense Production Act prioritizes domestic specialty steel sourcing, redirecting aerospace and armor contracts toward qualified domestic mills.
- Die-Casting Tooling Conversion:European automotive suppliers are displacing conventional die steels with Maraging 250 bar stock for high-pressure aluminum casting operations.
- Solid Rocket Motor Demand:Aerospace OEMs are expanding orders for Maraging 350 grades in rocket motor casings where strength-to-weight ratios determine payload economics.
Market Restraints
- Cobalt Supply Concentration:Over 70% of global cobalt originates from Central African mining operations, exposing Maraging 350 producers to geopolitical supply disruptions.
- Export Licensing Friction:The U.S. Bureau of Industry and Security restricts technology transfer for grades above 2400 MPa yield strength, complicating international sales.
- Additive Manufacturing Substitution:Powder bed fusion and directed energy deposition processes using nickel superalloy feedstocks threaten wrought maraging demand in select defense applications.
Strategic Opportunities
- Medical Device Tooling:Japan's METI JIS standards for aerospace-grade maraging steel are gaining PMDA recognition for surgical instrument and implant tooling applications.
- Offshore Hydraulic Systems:High-pressure tube products for subsea equipment represent an underdeveloped segment with limited qualified suppliers.
- REACH Compliance Services:ECHA material disclosure mandates for cobalt content create revenue potential for European mills offering certified traceability documentation.
Industry Challenges
- Vacuum Induction Melting Expertise Gap:Aerospace-qualified material production requires specialized metallurgists with experience in ultra-low carbon melt practices.
- Age-Hardening Process Control:Precise temperature and time parameters for intermetallic precipitation demand capital-intensive furnace infrastructure and real-time monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maraging Steel Market |
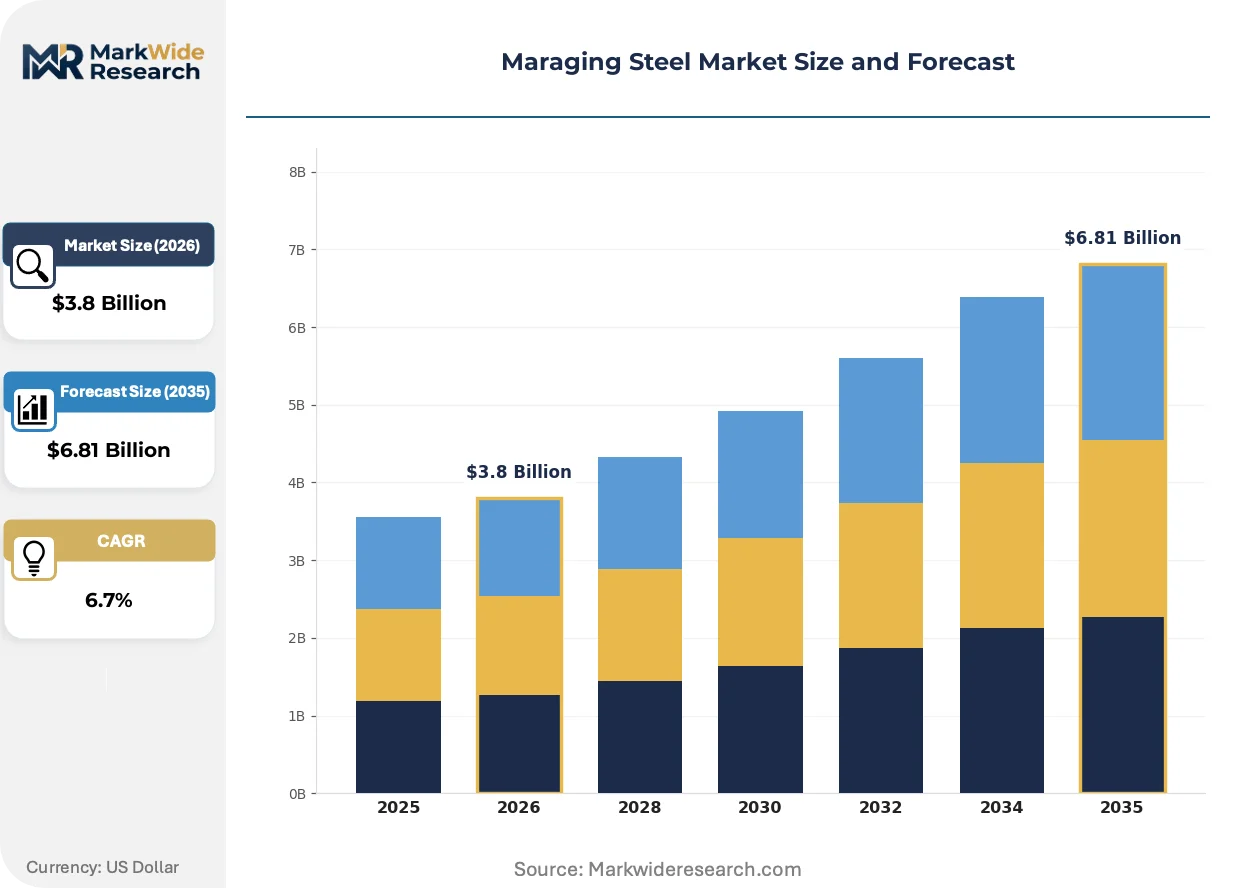
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maraging 250, Maraging 300, Maraging 350, Maraging 700 Application: Aerospace, Defense, Tooling, Automotive End User: Aerospace OEMs, Industrial Equipment Manufacturers, Tooling Providers, Defense Contractors Form: Sheet, Bar, Tube, Plate |
| Companies Covered | Dongbei Special Steel Group, Baosteel, Proterial, Aubert & Duval, Daido Steel, Universal Stainless, Nippon Koshuha Steel, Carpenter Technology Corporation, Voestalpine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maraging Steel Market Shifts & Advancements
Digital thread integration across the alloy supply chain is compressing certification timelines while regulatory disclosure requirements and procurement consolidation are reshaping competitive access.
Computational materials engineering platforms are virtualizing traditional trial-and-error alloy development cycles. Aerospace primes and specialty mills are adopting integrated computational materials engineering tools to predict precipitation kinetics and optimize heat treatment windows. This capability is virtualizing the historical reliance on extensive physical testing programs, reducing qualification timelines from years to months for new heat lot approvals.
REACH compliance through ECHA is mandating full material disclosure for cobalt content in European tooling applications. The regulation elevates traceability costs for non-EU mills while creating competitive advantage for integrated producers with captive cobalt-nickel supply chains. German tooling manufacturers serving automotive die-casting operations are now requiring certified supply chain documentation as a procurement prerequisite.
Long-term offtake agreements are displacing spot market purchasing in aerospace-qualified material. Tier-1 rocket motor casing suppliers are locking multi-year supply contracts directly with vacuum induction melting specialists, bypassing traditional distributor channels. This concentration is most visible in the U.S. defense industrial base, where the Defense Production Act incentives favor contract stability over price competition.
Maraging Steel Market Segmentation
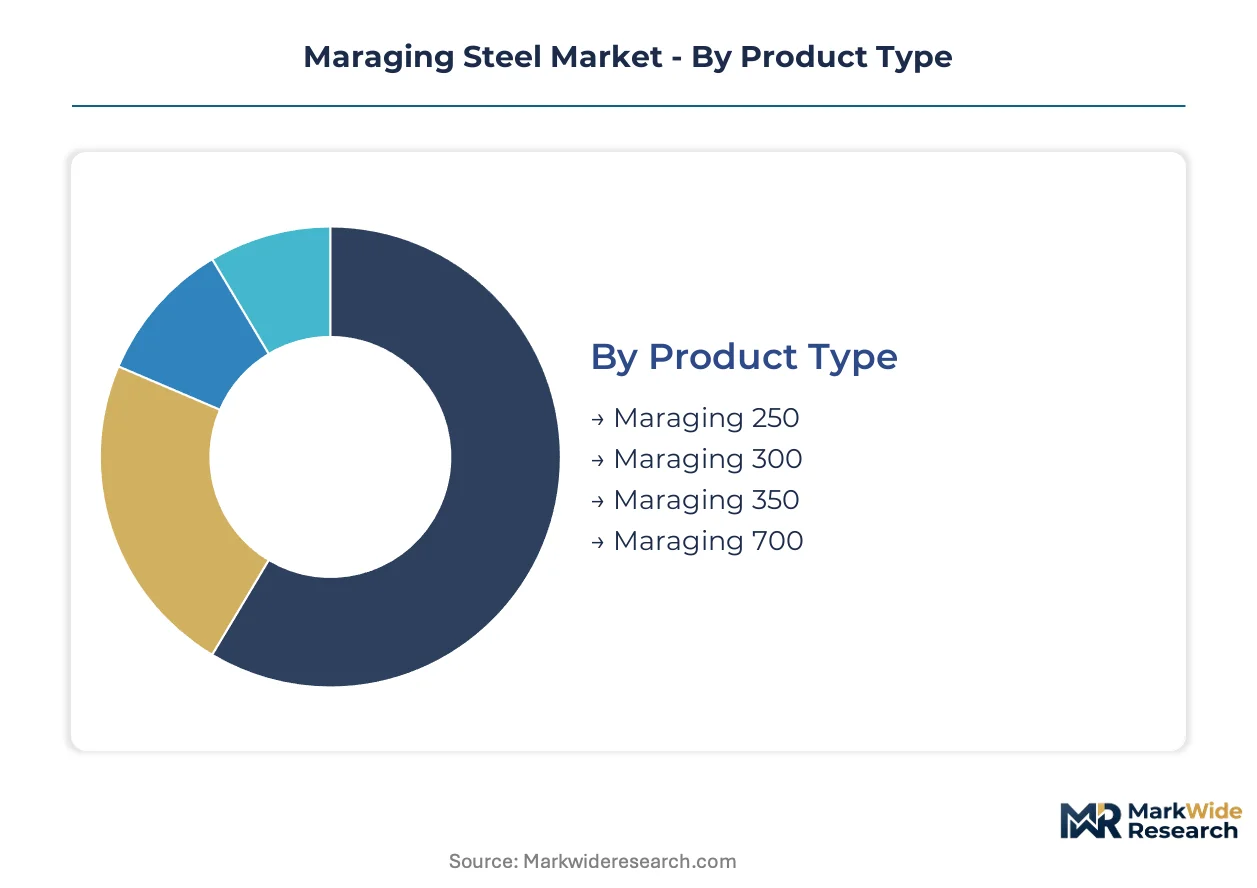
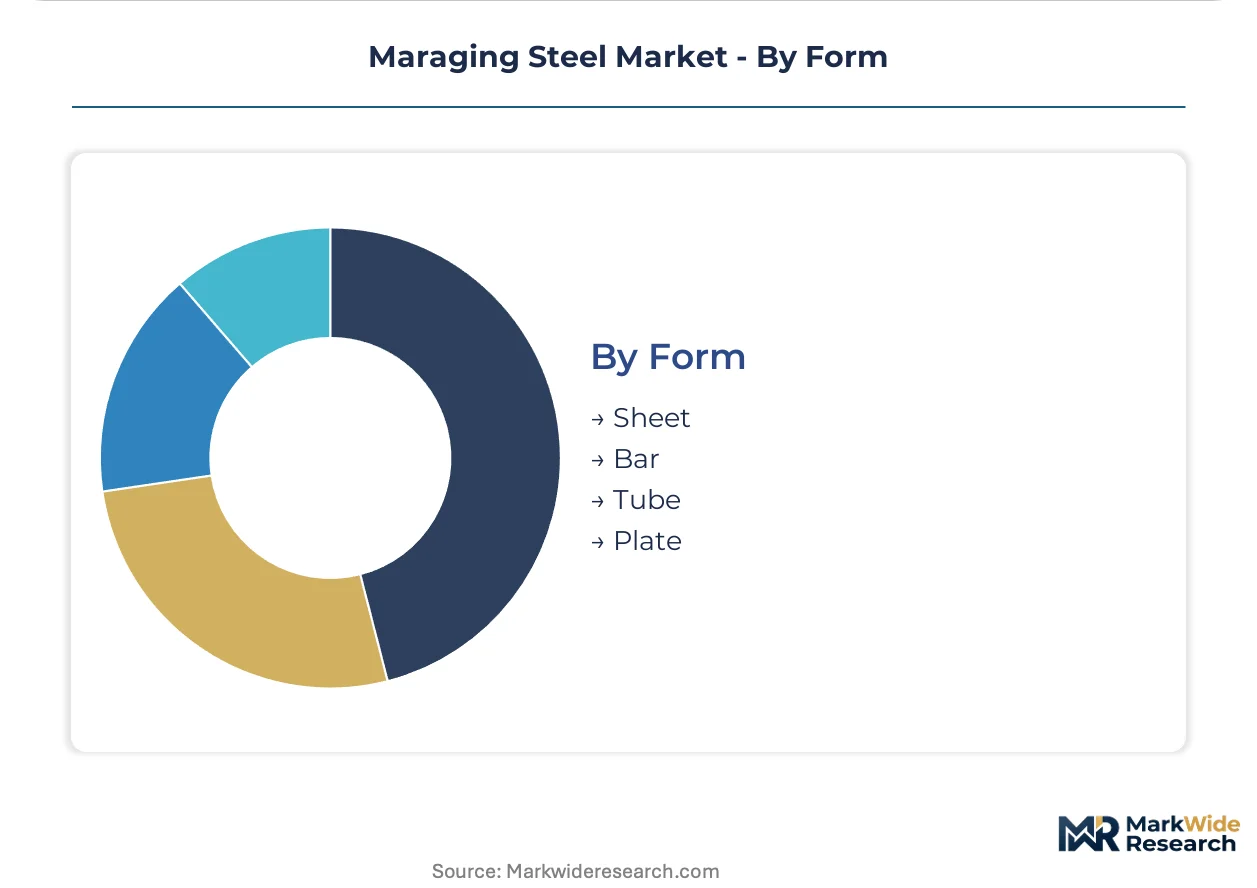
Maraging steel grades exhibit starkly different commercial cycles, with aerospace-qualified material requiring multi-year certification timelines while die-casting tooling converts within months. Understanding these velocity differentials across product grades, applications, and forms shapes procurement strategy and inventory positioning.
Product Type:
Cycle times vary dramatically across nickel-cobalt-molybdenum formulations, from rapid tooling qualification to decade-long aerospace certification programs.
- Maraging 250:The 18% nickel grade with reduced cobalt content achieves yield strengths of 1720 MPa after age-hardening. European automotive die-casting operations in Germany and Austria are displacing conventional H13 tool steels with Maraging 250 bar stock for high-pressure aluminum casting dies, driven by thermal fatigue resistance requirements.
- Maraging 350:Higher cobalt and titanium additions push yield strength to 2430 MPa, making this the premier grade for solid rocket motor casings where strength-to-weight ratios determine payload economics. U.S. defense procurement under the Defense Production Act is concentrating orders with domestic vacuum induction melting specialists.
- Maraging 300:Intermediate cobalt content delivers 2060 MPa yield strength for general aerospace structural components and landing gear applications.
- Maraging 700:Experimental ultra-high-strength formulation with specialized applications in defense armor systems requiring extreme hardness retention.
Maraging 250 anchors the volume base through tooling conversion while Maraging 350 gains share at the steepest rate on solid rocket motor demand.
Application:
Margin structures diverge sharply across end-use sectors, with defense-aerospace commanding certification premiums and automotive tooling competing on total cost of ownership.
- Aerospace:Solid rocket motor casings, landing gear components, and structural fasteners require vacuum arc remelted material with full traceability documentation. FAA certification protocols and prime contractor qualification programs sustain multi-year supply agreements.
- Tooling:High-pressure aluminum die-casting dies and plastic injection molds represent the fastest-expanding application as Maraging grades displace conventional die steels. German automotive suppliers are driving volume through tool life extension requirements.
- Defense:Armor plate and penetrator applications consume mature volumes with stable specifications governed by military standards.
- Automotive:Limited direct consumption; most automotive exposure flows through tooling providers serving Tier-1 casting operations.
Aerospace commands the highest absolute margins while tooling delivers the steepest volume expansion trajectory.
End User:
Procurement sophistication varies from integrated primes with metallurgical laboratories to distributors serving fragmented tooling shops.
- Aerospace OEMs:SpaceX, Blue Origin, and legacy primes like Northrop Grumman specify Maraging 350 for rocket motor casings with direct mill relationships.
- Tooling Providers:German die-casting tool manufacturers in Stuttgart and Munich cluster source Maraging 250 bar stock through specialized distributors.
- Defense Contractors:Tier-1 armor system integrators maintain long-term offtake agreements with qualified domestic mills.
- Industrial Equipment Manufacturers:Offshore hydraulic system builders represent an emerging niche for high-pressure tube products.
Aerospace OEMs anchor the value base while tooling providers expand most quickly through automotive supply chain conversion.
Form:
Processing complexity and scrap economics shape form-specific supply dynamics, with bar and plate dominating commercial flows.
- Bar:Round and rectangular bar stock in Maraging 250 and 300 grades serves die-casting tooling and aerospace fastener applications. Voestalpine's Austrian operations specialize in precision-ground bar for European automotive tooling.
- Plate:Thick plate products for armor systems and structural aerospace components require heavy forging capacity concentrated among integrated specialty steel producers.
- Sheet:Thin gauge material for aircraft skins and structural panels represents mature demand with limited growth.
- Tube:Seamless tubing for high-pressure hydraulic systems in offshore equipment occupies a niche with limited qualified suppliers.
Bar products anchor the volume base through tooling demand while tube formats gain share at the steepest rate in subsea applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in maraging steel tilt toward net importers with aerospace and defense industrial bases, while integrated producers in cobalt-rich supply chains capture re-export advantages. Trade frictions around dual-use export controls are redirecting procurement toward qualified domestic mills in consuming countries.
United States
Solid rocket motor casing demand from SpaceX and Blue Origin is concentrating orders for Maraging 350 grades. The Defense Production Act prioritizes domestic specialty steel sourcing, redirecting aerospace contracts toward qualified U.S. mills. Huntsville, Alabama and Los Angeles aerospace clusters anchor procurement for defense and commercial space applications.
Germany
Automotive die-casting tool manufacturers are displacing conventional die steels with Maraging 250 bar stock for high-pressure aluminum casting operations. REACH compliance through ECHA mandates full material disclosure for cobalt content, elevating traceability costs for tooling providers. Stuttgart and Munich industrial clusters source through specialized distributors serving the European automotive supply chain.
China
Dongbei Special Steel Group leverages integrated cobalt-nickel supply chains to control input costs for domestic aerospace and tooling applications. The country's national industrial standards regulator maintains GB standards for specialty steel grades that parallel aerospace qualification protocols. Shenyang and Dalian manufacturing bases concentrate vacuum induction melting capacity for defense and commercial aerospace programs.
Japan
METI JIS standards for aerospace-grade maraging steel are gaining PMDA recognition for surgical instrument and implant tooling applications. Medical device manufacturers in Osaka and Tokyo industrial corridors are qualifying Maraging 250 grades for precision tooling. The regulatory convergence between aerospace and medical standards is opening cross-sector procurement pathways.
Austria
Voestalpine anchors European tooling demand through specialized bar and plate production for die-casting and aerospace fastener applications. The country's alignment with EU REACH and dual-use export control frameworks positions Austrian mills as compliant suppliers for cross-border defense and automotive contracts. Linz and Vienna industrial zones concentrate precision-ground bar capacity for German automotive tooling supply chains.
Maraging Steel Market Competitive Landscape
On the supply side, the industry is consolidating around integrated producers with captive cobalt-nickel supply chains and vacuum induction melting specialists with aerospace qualifications. Three archetypes dominate: integrated mining-to-mill conglomerates controlling raw material costs, precision metallurgy specialists with aerospace certifications, and regional bar-and-plate processors serving tooling markets. Competitive moves center on long-term offtake agreements with defense primes and backward integration into cobalt sourcing.
Within the integrated producer tier, Dongbei Special Steel Group and Baosteel exemplify upstream control strategies. Carpenter Technology Corporation and Voestalpine occupy positions among vacuum induction melting specialists with aerospace-qualified material capabilities. Daido Steel represents the precision metallurgy archetype serving tooling and medical device applications. These named companies anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Dongbei Special Steel Group |
| Baosteel |
| Proterial |
| Aubert & Duval |
| Daido Steel |
| Universal Stainless |
| Nippon Koshuha Steel |
| Carpenter Technology Corporation |
| Voestalpine |
| Others |
Supply & Pricing Matrix
Undercapacity in European vacuum induction melting capacity is compressing lead times for aerospace-qualified Maraging 350 grades and elevating price premiums for certified domestic supply in the United States. This utilization asymmetry between regions is forcing buyers into long-term offtake commitments while suppliers with captive cobalt-nickel supply chains extract margin advantages from input cost stability.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with aerospace primes locking multi-year supply agreements directly with vacuum induction melting specialists. Price differentiation rests on certification grade—FAA-qualified material commands substantial premiums over commercial-grade tooling stock—and volume scale, with die-casting tooling providers competing on total cost of ownership. Cost compression in automotive tooling tiers is intensifying because European suppliers are displacing conventional H13 die steels with Maraging 250 bar stock. Tier-1 rocket motor casing suppliers exhibit the least price sensitivity due to Defense Production Act sourcing mandates, while fragmented German tooling shops face acute margin pressure.
Supply Chain Analysis
Tariff exposure between the United States and non-FTA cobalt suppliers dominates supply chain risk calculus for Maraging 350 producers. Geographic supply concentration centers on China, Austria, and Japan, with Dongbei Special Steel Group and Voestalpine anchoring regional capacity. Raw material dependencies draw from Central African cobalt mining operations, nickel laterite processing in Indonesia, and molybdenum concentrate from Chile. Single-source vulnerability in cobalt feedstock creates acute disruption exposure given the Defense Production Act's domestic sourcing mandates. Distribution runs through specialized distributors serving tooling markets and direct mill relationships for aerospace-qualified material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid rocket motor demand from commercial space launch providers is accelerating certification timelines for domestic vacuum induction melting capacity, creating a high-growth disruption as computational materials engineering compresses traditional alloy development cycles.
For Market Incumbents: Insulate aerospace-qualified material margins by deepening backward integration into cobalt-nickel supply chains and expanding vacuum arc remelting capacity in Huntsville, Alabama to capture Defense Production Act procurement flows. Powder bed fusion substitution in defense additive manufacturing represents the primary substitution threat requiring monitoring. For New Entrants and Emerging Players: Establish a beachhead in medical device tooling applications where Japan's PMDA recognition of METI JIS standards is opening cross-sector procurement pathways. Offshore hydraulic tube products for subsea equipment represent the most penetrable white-space segment with limited qualified suppliers. A go-to-market angle through REACH compliance documentation services for European tooling providers offers immediate revenue traction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum induction melting capacity expansions as aerospace certification requirements tighten. Long-term viability over a five-to-ten-year window favors acquisition targets with captive cobalt sourcing and established prime contractor relationships. The signal to watch is additive manufacturing qualification protocols for nickel superalloy feedstocks that could displace wrought maraging demand in select defense applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cobalt-Nickel Supply | Dongbei Special Steel Group's captive sourcing model controls input cost volatility for Maraging 350 grades. |
| Long-term Supply Agreement with Aerospace Primes | Direct mill relationships with SpaceX and Blue Origin bypass distributor channels and stabilize capacity utilization. |
| REACH Compliance Documentation Service | Voestalpine's certified traceability offerings capture procurement prerequisites from German automotive tooling suppliers. |
| Medical Device Tooling Qualification | PMDA recognition of METI JIS standards opens surgical instrument applications for Maraging 250 grades. |
| Computational Materials Engineering Platform | Virtualized precipitation kinetics modeling reduces aerospace heat lot qualification timelines from years to months. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with vacuum induction melting specialists, aerospace procurement executives at SpaceX and Northrop Grumman, German die-casting tool manufacturers in Stuttgart, and metallurgical laboratory directors at specialty steel mills. Secondary validation drew from U.S. Department of Commerce Bureau of Industry and Security export licensing databases, ECHA REACH compliance filings, Japan METI JIS standard publications, and SEC 10-K disclosures from listed specialty steel producers. Bottom-up volume builds across product grades, applications, and forms were triangulated against top-down aerospace and defense procurement budget allocations.
Calibration against historical capacity utilization rates and certified supplier registries shaped the analytical framework across the analysis window. Segmentation dimensions modeled include maraging steel grade tier, end-use application, geographic production cluster, and certification status. CAGRs were derived from regression analysis of disclosed order backlogs and procurement pipeline visibility. Industry-specific forecast inputs incorporated Defense Production Act incentive structures and European automotive die-casting conversion rates.
Stress conditions across cobalt supply disruption scenarios, additive manufacturing substitution velocities, and REACH regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding prime contractor qualification timelines and defense budget continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
Forgings Market