
 North America Green Steel Market | 2026-2036
North America Green Steel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Green Steel Market Analytics
Mill-direct and toll-processing channels in the Midwest is reconfiguring around carbon-accounted supply chains. Nucor Corporation leverages its electric arc furnace network to anchor low-carbon rebar and sheet production across the Southeastern US. Cleveland-Cliffs sustains integrated hydrogen pilot operations at its Toledo direct reduction facility while competing for automotive-grade flat-rolled contracts. Steel Dynamics controls a growing scrap-fed capacity base that positions the company for Scope 3 emissions compliance.
Green steel denotes iron and steel products manufactured with substantially reduced carbon dioxide emissions per ton, typically achieving less than one ton CO2 equivalent through hydrogen direct reduction, electric arc furnace processing with renewable power, or bioreduction pathways using biochar. These specifications serve automotive body-in-white panels, wind turbine towers, and structural beams where embodied carbon now factors into procurement scoring. Hydrogen direct reduction technology leads capital deployment as equipment suppliers and utilities align on electrolyzer-scale hydrogen supply, while scrap-based electric arc furnace output dominates current tonnage and holds mature margin pools in construction rebar. The automotive end-user segment absorbs premium-priced flat products as OEMs enforce supplier decarbonization timelines.
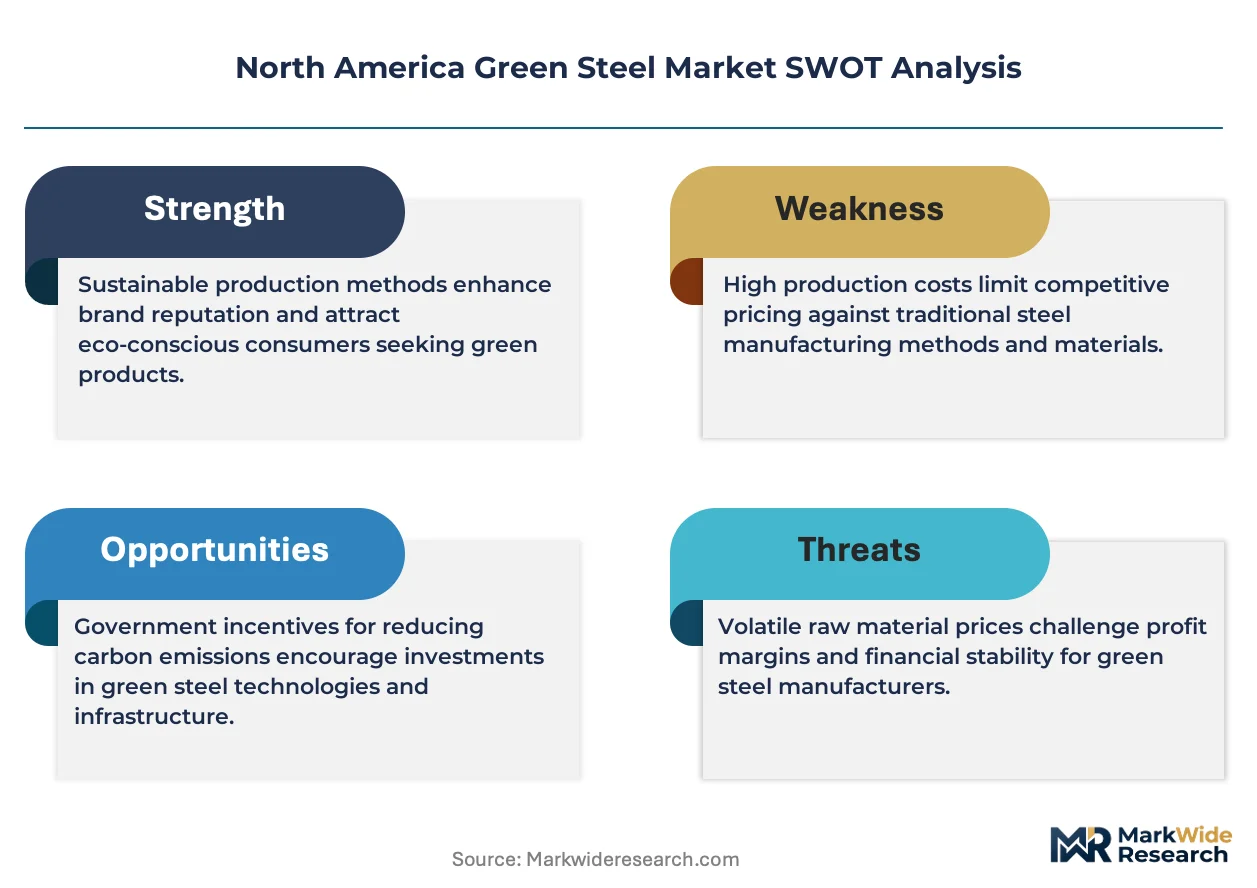
The US Environmental Protection Agency enforces greenhouse gas reporting under mandatory protocols that expose steel mill emissions to investor and customer scrutiny. The Inflation Reduction Act allocates production tax credits for clean hydrogen and advanced manufacturing that reshape project finance for greenfield steel investments. Buy Clean programs in California and New York embed environmental product declarations into public infrastructure procurement, effectively setting regional demand thresholds. Stakeholders must monitor state-level low-carbon procurement rules and hydrogen hub award outcomes to anticipate which production technologies secure offtake commitments.
Market Dynamics
The US Inflation Reduction Act's clean hydrogen production tax credits are redirecting capital flows toward hydrogen direct reduction facilities across the Great Lakes industrial corridor, compressing project finance timelines for near-zero-emission steel investments.
Growth Catalysts
- Automotive OEM decarbonization mandates:Michigan and Ontario assembly plants now require carbon-accounted flat steel in body-in-white panel contracts, creating pull-through demand for hydrogen-reduced sheet products.
- California Buy Clean procurement rules:Environmental product declaration thresholds in public infrastructure bids are forcing contractors to source low-carbon structural sections, embedding green steel specifications into bridge and transit projects.
- Hydrogen hub federal awards:Regional clean hydrogen clusters spanning Ohio, Pennsylvania, and New York are securing electrolyzer-scale supply commitments that anchor offtake agreements for direct reduction plants.
Market Restraints
- Renewable power cost volatility:Electric arc furnace and electrolyzer operations face margin compression from intermittent wind and solar pricing in Texas and Midwest ISO markets.
- Scrap supply concentration:Obsolete scrap collection networks concentrate in Southeastern US population corridors, creating logistics bottlenecks for Great Lakes-based green steel producers.
- Hydrogen storage and transport gaps:Pipeline infrastructure for industrial hydrogen remains underdeveloped between Gulf Coast production zones and Midwest steel mill demand centers.
Strategic Opportunities
- Canadian federal clean fuel regulations:Ottawa's carbon intensity standards for industrial feedstocks are creating premium pricing pools for hydrogen-reduced iron imports into Hamilton and Sault Ste. Marie mills.
- Wind tower fabricator demand:Domestic tower manufacturers in Texas and Colorado are specifying low-embodied-carbon plate for utility-scale turbine projects qualifying for IRA domestic content bonuses.
- Digital product passports:Blockchain-tracked carbon accounting systems are emerging as a channel innovation, allowing mill-direct sales to bypass traditional distributor markup layers.
Industry Challenges
- Electrolyzer technician shortage:Hydrogen direct reduction facilities face hiring bottlenecks for high-voltage electrolyzer maintenance crews, delaying commissioning timelines at greenfield sites.
- Scope 3 verification complexity:Automotive OEMs demand third-party audited carbon accounting across tier-two ore suppliers, creating compliance friction for integrated mills with international mining partnerships.
- Legacy blast furnace asset stranding:Integrated producers with conventional coke oven batteries face accelerated depreciation pressure as carbon border adjustments threaten export competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Green Steel Market |
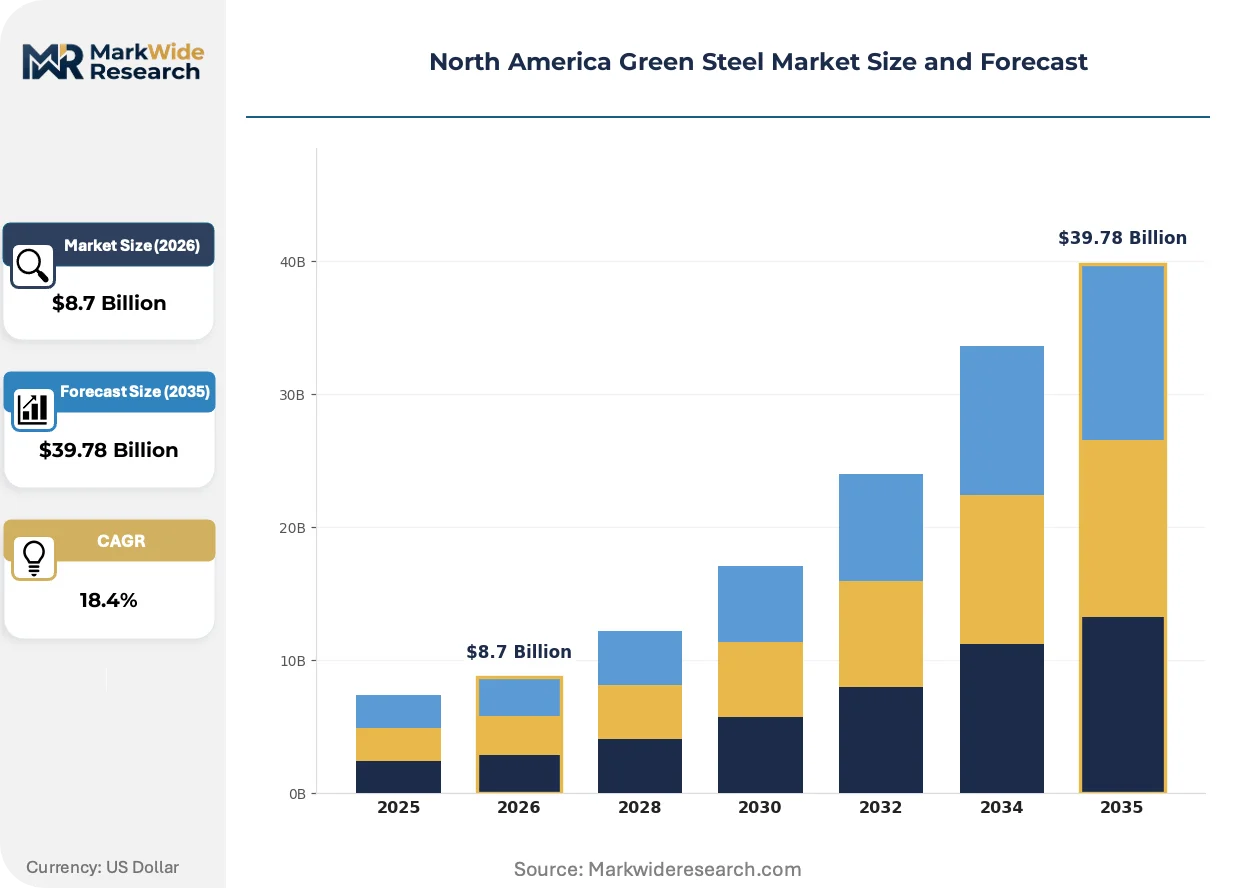
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydrogen Direct Reduction, Electric Arc Furnace, Bioreduction, Scrap-Based End User: Automotive, Construction, Energy, Appliances Manufacturing Stage: Primary Production, Secondary Production, Recycled Steel, Fabrication Application: Infrastructure, Transportation, Industrial Equipment, Consumer Goods |
| Companies Covered | Nucor Corporation, Cleveland-Cliffs, Steel Dynamics, United States Steel Corporation, Boston Metal, H2 Green Steel, ArcelorMittal, SSAB, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Green Steel Market Evolving Landscape
Digital twin and predictive maintenance platforms are virtualizing process control across North American steel mills, compressing energy intensity while enabling real-time carbon emissions tracking that satisfies automotive customer audit protocols.
Hydrogen direct reduction technology is virtualizing the traditional blast furnace value chain by replacing carbon-intensive coke with electrolyzer-produced hydrogen in iron ore reduction. Automotive stamping plants in Michigan and Ohio are specifying H2-DRI feedstock for exposed body panels at accelerating volumes. This virtualization is collapsing the capital cost gap between greenfield hydrogen-based plants and conventional integrated mill retrofits.
The US EPA's mandatory greenhouse gas reporting protocols now require facility-level emissions disclosure under standardized calculation methodologies. Steel producers face intensified investor scrutiny as Scope 1 and Scope 2 data become searchable in public databases. California and New York Buy Clean programs are embedding these disclosures into infrastructure procurement scoring, forcing bidders to document supply chain carbon intensity.
Automotive OEM supplier scorecards are elevating embodied carbon alongside price and delivery metrics in annual contract negotiations. Tier-one stamping suppliers to Detroit Three manufacturers are consolidating purchase orders with mills offering certified low-carbon flat products. This behavioral shift concentrates most visibly in the Windsor-to-Detroit corridor, where cross-border just-in-time delivery requirements intersect with Canadian federal clean fuel regulations.
North America Green Steel Market Segmentation
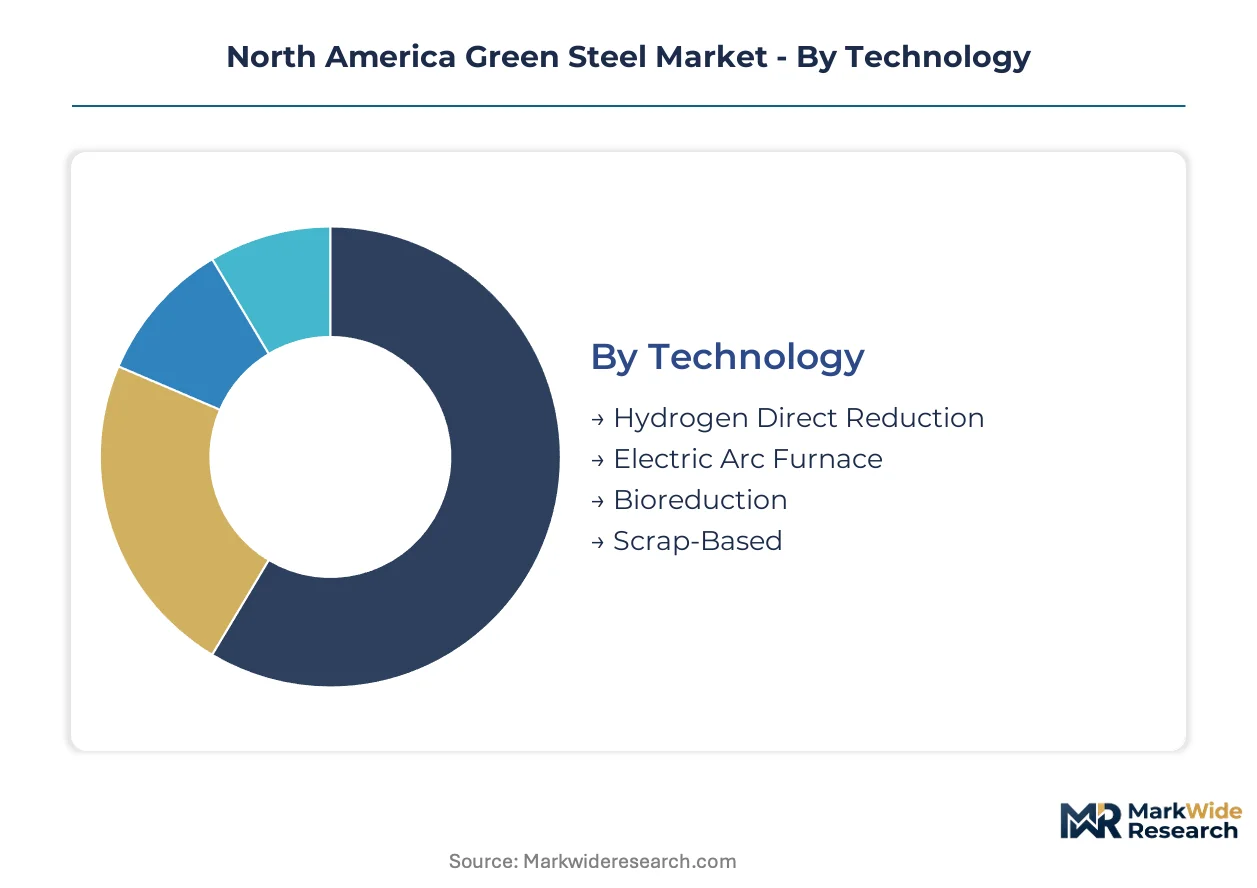
Green steel procurement patterns diverge sharply across production technologies and end-use specifications. Each segmentation dimension reveals distinct margin structures, compliance requirements, and capital deployment priorities that reshape supplier-customer contracting.
Technology:
Use-case spectrum spans near-zero-emission hydrogen reduction to mature scrap-fed processing, with each pathway commanding different premium structures and offtake security.
- Hydrogen Direct Reduction:Electrolyzer-produced hydrogen replaces coke in iron ore reduction, achieving sub-one-ton CO2 equivalent per ton of crude steel. Michigan and Ontario automotive stamping plants are specifying H2-DRI feedstock for exposed body panels, with hydrogen hub awards across Ohio and Pennsylvania anchoring supply commitments.
- Electric Arc Furnace:Scrap-fed electric melting using renewable grid power dominates current North American tonnage and holds mature margin pools in construction rebar. Texas and Midwest ISO markets expose operators to intermittent wind and solar pricing volatility that compresses processing margins.
- Bioreduction:Biochar-derived carbon substitutes metallurgical coal in reduction reactions, offering a transitional pathway for integrated mill retrofits. Pilot operations in the US Southeast are testing torrefied biomass feedstock consistency for commercial scale-up.
- Scrap-Based:Obsolete scrap collection networks concentrate in Southeastern US population corridors, creating logistics bottlenecks for Great Lakes-based producers seeking circular feedstock security.
The dominant share belongs to Electric Arc Furnace, while Hydrogen Direct Reduction is closing the gap fastest.
End User:
Cost tier differentiation separates premium-priced automotive contracts from volume-driven construction segments.
- Automotive:OEM decarbonization mandates in Michigan and Ontario assembly plants now require carbon-accounted flat steel in body-in-white panel contracts, creating pull-through demand for certified low-carbon sheet products with third-party audited Scope 3 accounting.
- Construction:California and New York Buy Clean programs embed environmental product declaration thresholds into public infrastructure bids, forcing contractors to source low-carbon structural sections for bridge and transit projects.
- Energy:Domestic wind tower manufacturers in Texas and Colorado specify low-embodied-carbon plate for utility-scale turbine projects qualifying for IRA domestic content bonuses.
- Appliances:White goods manufacturers prioritize cost-competitive cold-rolled coil with moderate carbon intensity reductions achievable through grid-mix optimization rather than process transformation.
Automotive commands the steepest premium tier, while Energy is expanding most quickly on IRA incentive alignment.
Manufacturing Stage:
Volume concentration flows toward secondary and recycled streams as primary greenfield investments face extended commissioning timelines.
- Primary Production:Greenfield hydrogen direct reduction facilities face hiring bottlenecks for high-voltage electrolyzer maintenance crews, delaying commissioning timelines at sites across the Great Lakes corridor.
- Secondary Production:Electric arc furnace remelting of direct-reduced iron or pig iron blends offers intermediate carbon intensity for automotive-grade flat-rolled contracts requiring near-zero-emission specifications.
- Recycled Steel:Scrap beneficiation and sorting investments are concentrating in Ohio and Indiana to supply furnace-ready feedstock with predictable chemistry and contaminant profiles.
- Fabrication:Downstream processors in the Windsor-to-Detroit corridor are integrating carbon accounting systems to satisfy cross-border just-in-time delivery requirements intersecting with Canadian federal clean fuel regulations.
Recycled Steel holds the largest volume position, while Primary Production is gaining share fastest on automotive OEM supplier scorecard enforcement.
Application:
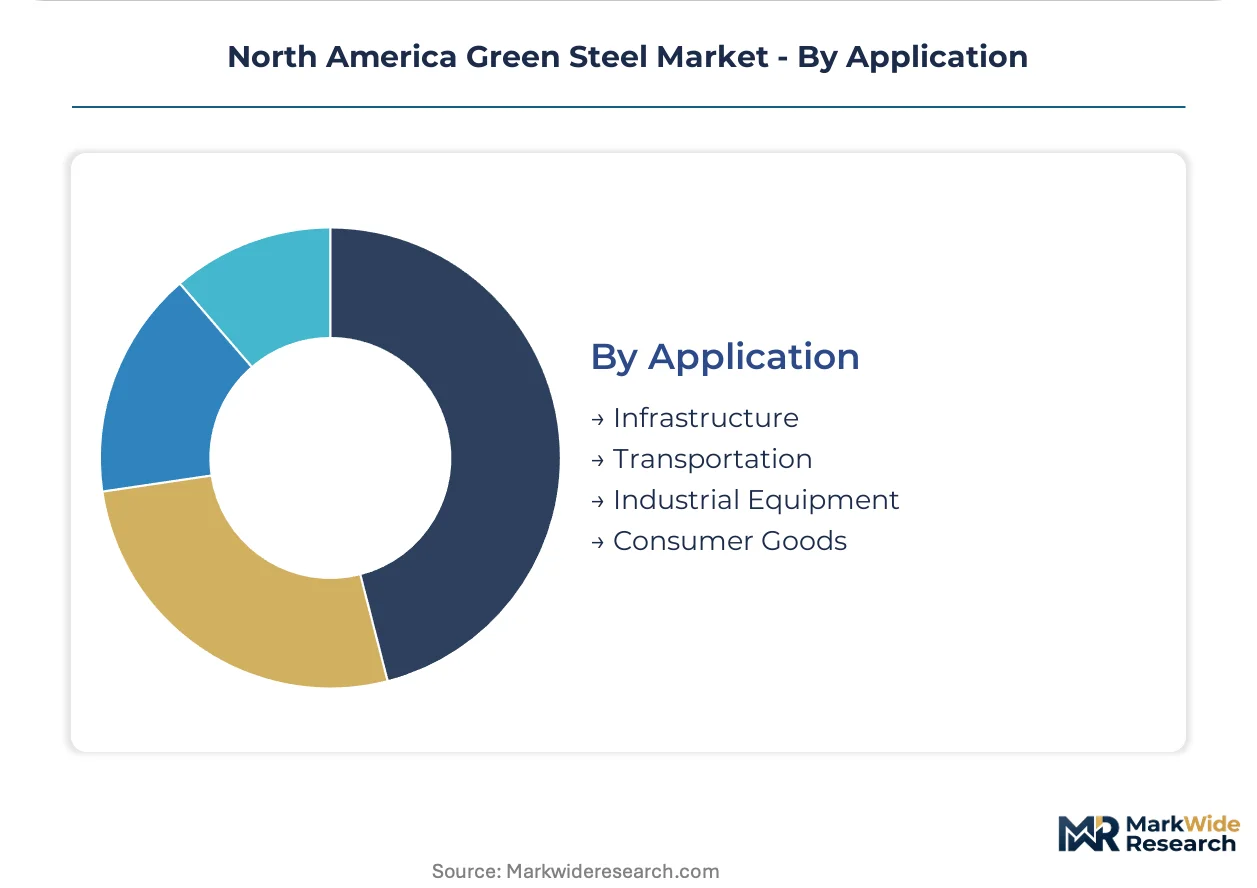
Customer type stratification separates specification-heavy infrastructure buyers from price-sensitive consumer goods manufacturers.
- Infrastructure:Public procurement scoring in California and New York embeds environmental product declarations into bridge and transit project bids, forcing documentation of supply chain carbon intensity through third-party verification.
- Transportation:Beyond automotive, rail car and shipbuilding fabricators are adopting low-carbon plate specifications as Scope 3 emissions disclosure requirements propagate through maritime and freight operator sustainability programs.
- Industrial Equipment:Agricultural and mining machinery producers balance durability requirements against moderate carbon reduction targets achievable through scrap-based electric arc furnace sourcing.
- Consumer Goods:Furniture and packaging steel buyers prioritize cost minimization over carbon intensity, sourcing from established electric arc furnace producers with baseline grid-mix emissions profiles.
Infrastructure captures the dominant procurement value, while Transportation is climbing the fastest on modal decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands pricing leverage through IRA production tax credits, while Canadian producers absorb carbon border adjustment exposure without matching federal incentive depth.
United States
Michigan and Ohio automotive stamping plants now require carbon-accounted flat steel in body-in-white contracts, pulling hydrogen-reduced sheet demand through the Great Lakes corridor. The EPA's mandatory greenhouse gas reporting protocols expose facility-level emissions to investor scrutiny, accelerating Scope 3 verification investments. Cleveland anchors integrated hydrogen pilot operations at Toledo direct reduction facilities competing for automotive-grade contracts.
Canada
Ottawa's clean fuel regulations create premium pricing pools for hydrogen-reduced iron imports into Hamilton and Sault Ste. Marie mills serving cross-border just-in-time delivery requirements. The Canadian federal carbon intensity standards for industrial feedstocks exceed US baseline stringency, embedding cost premiums into Ontario-produced structural sections. The Windsor-to-Detroit corridor concentrates mill-direct channel reconfiguration around carbon-accounted supply chains.
Mexico
Nuevo León and Bajío Region automotive assembly plants are integrating low-carbon steel specifications into supplier scorecards as export qualification requirements tighten. Mexico's national environmental regulator enforces industrial emissions disclosure without matching US IRA incentive scale, compressing margin recovery for greenfield investments. Monterrey-based fabricators face logistics bottlenecks sourcing scrap-fed feedstock from Southeastern US collection networks.
North America Green Steel Market Competitive Landscape
Integrated hydrogen-based producers and scrap-fed electric arc furnace operators split the market between premium automotive contracts and volume construction segments. The vendor base concentrates around three strategic archetypes: legacy integrated mills retrofitting direct reduction capacity, merchant scrap processors controlling circular feedstock security, and greenfield hydrogen ventures securing electrolyzer-scale offtake. Competitive moves center on hydrogen hub partnership formations and automotive OEM supplier certification races.
Among Great Lakes-based integrated producers, Cleveland-Cliffs and United States Steel Corporation exemplify the retrofit archetype, occupying positions between conventional blast furnace dependency and hydrogen direct reduction transition. Nucor Corporation anchors the scrap-fed merchant tier, representing scale advantages in electric arc furnace network density across the Southeastern US. These three companies illustrate the structural divergence between capital-intensive primary transformation and feedstock-secured secondary processing.
| Leading Market Players |
|---|
| Nucor Corporation |
| Cleveland-Cliffs |
| Steel Dynamics |
| United States Steel Corporation |
| Boston Metal |
| H2 Green Steel |
| ArcelorMittal |
| SSAB |
| POSCO |
| Others |
Value Network & Pricing Analysis
The Great Lakes industrial corridor stretching from Cleveland through Detroit to Hamilton concentrates hydrogen direct reduction capacity investments that translate into downstream pricing power for automotive-grade flat-rolled contracts. Michigan and Ontario stamping plants now absorb substantial premiums for carbon-accounted body-in-white panels, while construction segments in California and New York face compressed margins under Buy Clean procurement thresholds.
Pricing Analysis
The customization-premium spread between configured-to-order hydrogen-reduced sheet and standard electric arc furnace rebar widens as automotive OEM supplier scorecards embed third-party carbon accounting. Contract-based long-term offtake agreements dominate premium tier procurement, with price differentiation driven by certification level under ISO 14064 protocols and geographic delivery cost to just-in-time assembly corridors. Pricing pressure stems from renewable power cost volatility in Texas and Midwest ISO markets that compresses electric arc furnace processing margins. Construction contractors prove most price-sensitive, while automotive tier-one stamping suppliers accept substantial premiums for Scope 3 verified feedstock.
Supply Chain Analysis
Upstream feedstock security hinges on scrap collection networks concentrated in Southeastern US population corridors and hydrogen hub developments across Ohio, Pennsylvania, and New York. The supply chain draws from Canadian iron ore deposits, US Gulf Coast electrolyzer projects, and Mexican automotive assembly feedstock demand. Single-source vulnerability around high-voltage electrolyzer equipment creates commissioning delays at greenfield direct reduction facilities. Distribution runs through mill-direct channels reconfiguring around blockchain-tracked carbon passports that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a platform-economics inflection as hydrogen hub interoperability standards and digital product passport protocols reshape supplier-customer contracting. The emergence of electrolyzer-scale supply clusters creates ecosystem lock-in effects that favor early movers securing automotive OEM certification.
For Market Incumbents: Insulate core automotive contracts through backward integration into hydrogen production assets anchored by regional hub awards. Cleveland-Cliffs and Nucor Corporation exemplify defensive positioning through captive renewable power offtake and scrap collection network density. Legacy blast furnace operators face accelerated asset stranding as carbon border adjustments threaten export competitiveness, demanding rapid direct reduction retrofit commitments.
For New Entrants and Emerging Players: Mexico's Bajío Region automotive corridor presents underpenetration for low-carbon flat steel specifications as export qualification requirements tighten without matching IRA incentive scale. Wind tower fabrication in Texas and Colorado offers secondary white-space targeting through IRA domestic content bonus alignment. A go-to-market angle emphasizing third-party audited Scope 3 accounting bypasses incumbent certification queues.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors merchant hydrogen ventures with secured electrolyzer offtake and automotive OEM qualification timelines. Long-term viability centers on feedstock-secured secondary processors controlling circular scrap flows rather than capital-intensive primary transformation. The signal to watch is state-level low-carbon procurement rule expansion beyond California and New York into Illinois and Washington procurement codes.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Hub Partnership Formation | Ohio and Pennsylvania hub awards anchor electrolyzer-scale supply commitments for direct reduction plants. |
| Automotive OEM Supplier Certification | Detroit Three manufacturer scorecards elevate carbon accounting alongside price in annual contract negotiations. |
| Scrap Collection Network Expansion | Southeastern US corridor density controls circular feedstock security for electric arc furnace operators. |
| Digital Product Passport Implementation | Blockchain-tracked carbon accounting enables mill-direct sales bypassing traditional distributor markup layers. |
| Renewable Power Purchase Agreement | Texas and Midwest ISO market offtake hedges intermittent wind and solar pricing volatility exposure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA greenhouse gas reporting databases, hydrogen hub award announcements, and automotive OEM supplier disclosure filings. Primary interviews engaged steel mill procurement directors, hydrogen project developers, and Tier 1 automotive stamping supplier executives across Michigan, Ohio, and Ontario. Secondary validation drew from SEC 10-K filings, EIA power market data, and Canadian federal clean fuel regulation impact assessments. Bottom-up capacity modeling and top-down demand triangulation from automotive production forecasts and infrastructure procurement pipelines were cross-referenced.
Forecast inputs incorporate technology deployment curves for hydrogen direct reduction and electric arc furnace retrofits, segmented by production pathway, end-user vertical, and manufacturing stage. The analytical framework spans premium automotive contracts, volume construction segments, and emerging energy applications across the projection horizon. CAGRs were derived from capacity commissioning timelines, offtake agreement visibility, and regulatory incentive phase-in schedules. Key inputs include electrolyzer cost learning curves, renewable power price trajectories, and scrap supply elasticity estimates.
Practitioners should monitor hydrogen hub award execution delays, electrolyzer technician hiring bottlenecks, and carbon border adjustment implementation scope for early signals of forecast revision. Cross-checking against EPA mandatory reporting disclosures and state procurement rule dockets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Thulium Silicide Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Global Stainless Steel Forgings Market