
 Cobalt Alloy Powder Market | 2026-2036
Cobalt Alloy Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Alloy Powder Market Analysis
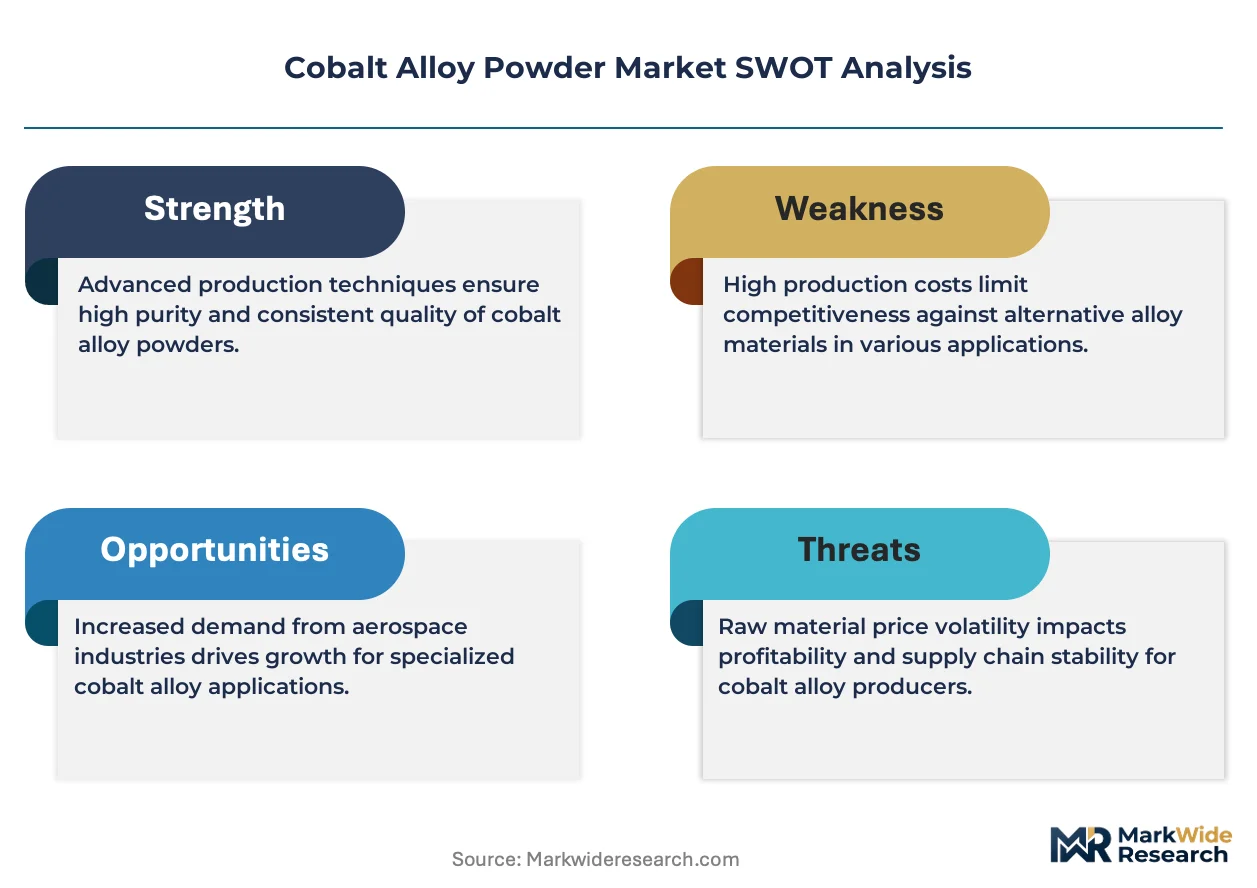
Aerospace-grade specification tiers is rotating demand toward higher-purity cobalt alloy powder for hot-section engine components. Sandvik AB leverages its gas atomization expertise to dominate premium powder supply for additive manufacturing repair cells. Carpenter Technology Corporation anchors North American specialty grade production through captive vacuum induction melting capacity.
Cobalt alloy powder denotes a family of cobalt-chromium-tungsten or cobalt-chromium-molybdenum compositions produced via gas atomization, water atomization, or mechanical alloying, typically specified for wear resistance, hot corrosion protection, and biocompatibility in service temperatures exceeding 800°C. Gas atomized powder commands the dominant value share due to superior spherical morphology and flowability for directed energy deposition processes. Water atomized powder occupies cost-sensitive automotive hardfacing segments where irregular particle shape suffices.
EMA, REACH, and EU F-Gas Regulation collectively constrain feedstock sourcing and mandate full supply chain disclosure for cobalt entering European aerospace and medical device channels. FDA and EPA requirements in the United States impose parallel purity and environmental handling standards on domestic powder conversion facilities. Stakeholders must monitor evolving conflict-mineral traceability rules and qualification timelines for novel alloy chemistries before committing capacity expansion decisions.
Market Dynamics
Gas atomization capacity scarcity is concentrating premium cobalt alloy powder supply among facilities with aerospace qualification, while REACH and EU F-Gas Regulation force feedstock traceability investments that reshape conversion economics.
Growth Catalysts
- Aerospace turbine blade repair:Hot-section engine component refurbishment drives specification upgrades toward higher-purity grades for directed energy deposition cells.
- REACH supply chain disclosure:Mandatory full traceability for cobalt entering European aerospace channels creates competitive moats for qualified converters.
- Additive manufacturing repair cells:On-site powder-fed deposition systems reduce downtime for aviation maintenance, repair, and overhaul operations.
Market Restraints
- Feedstock cost volatility:Cobalt metal price swings from Democratic Republic of Congo concentrate exposure compress conversion margins unpredictably.
- Gas atomization capacity concentration:Premium spherical powder supply clusters in Sweden and limited US sites, creating single-source vulnerability.
- Water atomization performance ceiling:Irregular particle morphology restricts water-atomized grades to automotive hardfacing, excluding aerospace qualification.
Strategic Opportunities
- Medical device biocompatibility:Cobalt-chromium-molybdenum compositions for orthopedic implants face unmet demand in aging population markets.
- EU Green Deal circular material flows:Recycled cobalt qualification pathways offer margin relief against virgin feedstock price pressure.
- Hybrid laser-arc deposition:Converging directed energy technologies enable thicker section repair with reduced powder consumption rates.
Industry Challenges
- AMS specification certification timelines:Aerospace Material Society qualification for novel alloy chemistries extends 18-36 months, freezing formulation innovation.
- Vacuum induction melting operator scarcity:Specialized metallurgical expertise for high-purity cobalt alloy production concentrates at retiring workforce demographics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Alloy Powder Market |
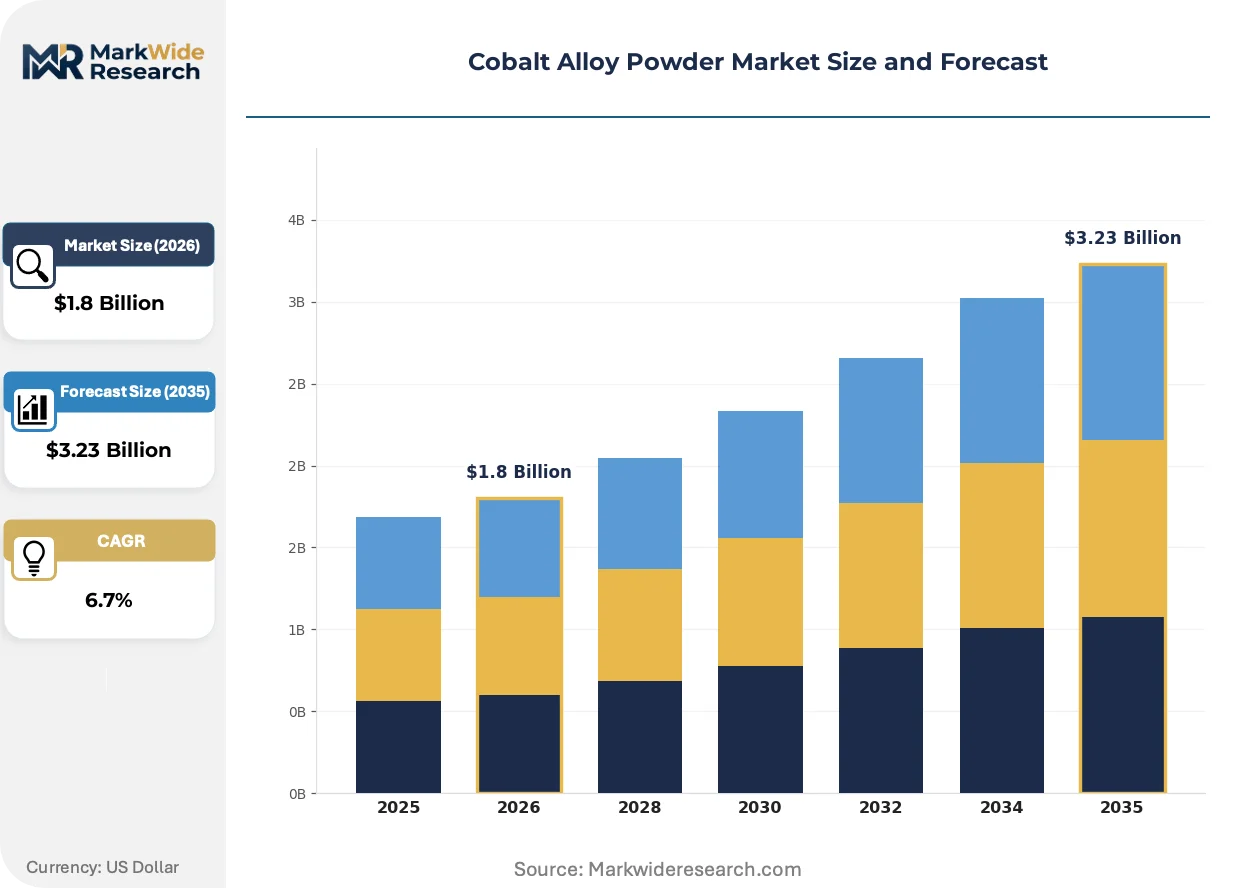
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Atomized Powder, Water Atomized Powder, Mechanical Alloyed Powder, Chemical Powder Grade: Commercial Grade, High Purity Grade, Specialty Grade, Aerospace Grade Application: Aerospace, Automotive, Medical, Energy End User: Manufacturers, Research Institutions, Defense Contractors, Maintenance Service Providers |
| Companies Covered | Sandvik AB, Carpenter Technology Corporation, Umicore, Höganäs AB, Kennametal Inc., Freeport Cobalt, ATI, Norilsk Nickel, Eramet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Alloy Powder Market Emerging Trajectories
Plasma rotating electrode process technology is bifurcating the premium powder tier, while regulatory disclosure mandates and procurement model compression reshape competitive positioning across the value chain.
Gas atomization is bifurcating cobalt alloy powder supply into aerospace-qualified spherical grades and industrial irregular fractions. Aviation maintenance, repair, and overhaul networks adopt qualified powder at accelerated rates for on-wing repair cells. The technology is bifurcating converter economics between premium qualification investments and commodity hardfacing retreat.
EU F-Gas Regulation and REACH collectively mandate full supply chain disclosure for cobalt entering European aerospace and medical device channels. Conversion facilities must deploy blockchain-traceable documentation from mine to powder lot. German precision manufacturing corridors face the steepest compliance cost escalation, accelerating backward integration into captive feedstock sourcing.
Aviation procurement is compressing supplier panels toward single-source powder agreements with integrated repair cell operators. Long-term offtake contracts displace spot market purchasing for qualified grades. This concentration is most visible in German turbine engine maintenance clusters and US Southwest aerospace corridors.
Cobalt Alloy Powder Market Segmentation
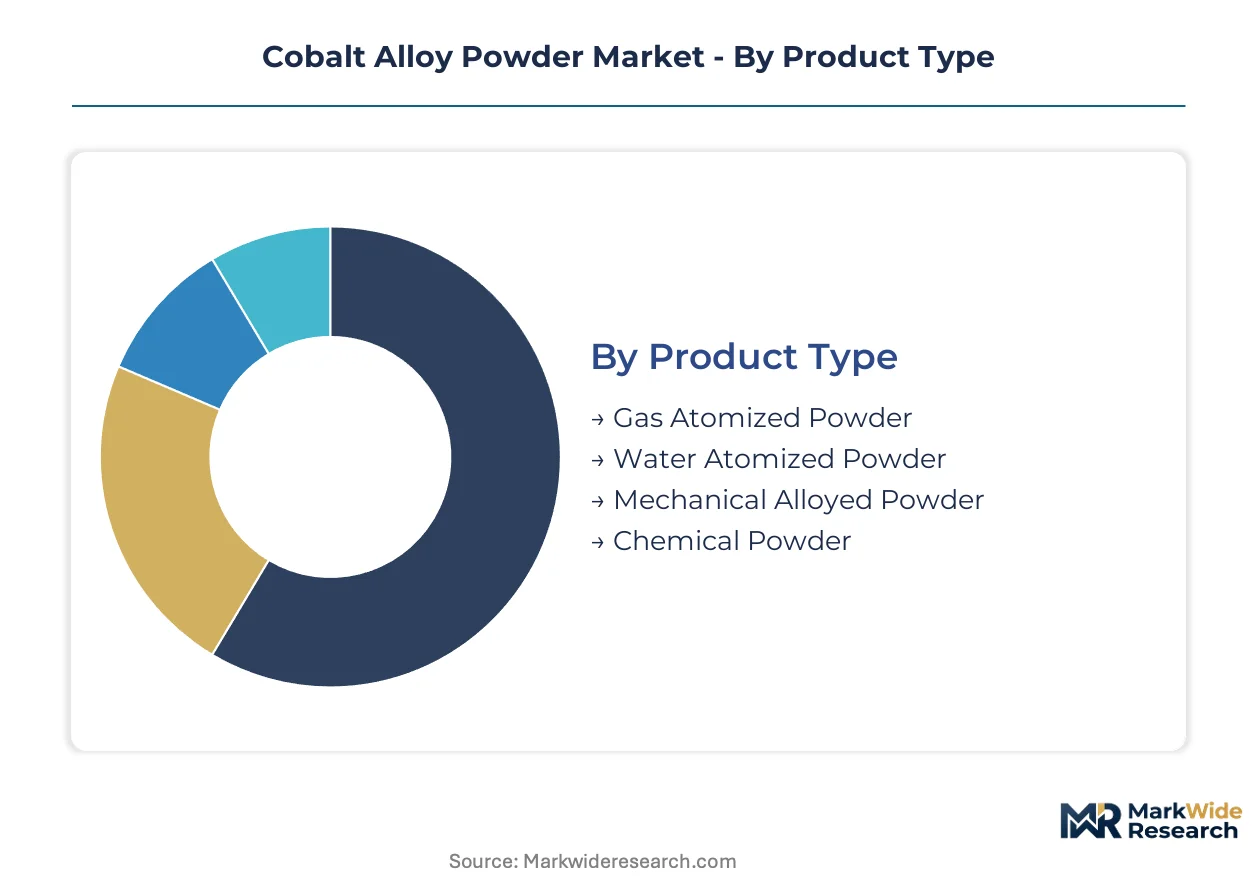
Cobalt alloy powder segmentation reveals stark margin stratification between qualification-intensive aerospace channels and cost-driven industrial applications. Powder morphology and purity tiers determine pricing power, while end-use qualification timelines lock customers into specific supply relationships.
Product Type:
Premium margin pools concentrate in spherical powder grades where gas atomization expertise creates defendable positions against commodity converters.
- Gas Atomized Powder:Spherical particle morphology delivers superior flowability for directed energy deposition in aviation repair cells. Demand clusters in Germany's precision manufacturing corridor and US Southwest aerospace maintenance networks, driven by on-site turbine blade refurbishment programs. REACH and EU F-Gas Regulation mandate full traceability for material entering these channels.
- Water Atomized Powder:Irregular particle shape serves automotive hardfacing applications where cost sensitivity outweighs flowability requirements. Demand concentrates in Detroit-area powertrain component remanufacturing and Ruhr Valley industrial clusters, constrained by performance ceilings that exclude aerospace qualification.
- Mechanical Alloyed Powder:Solid-state processing enables non-equilibrium compositions for specialized wear applications in mining equipment.
- Chemical Powder:Precipitation routes deliver ultrafine fractions for catalyst and battery precursor applications outside traditional alloy markets.
The dominant share belongs to Gas Atomized Powder, while Water Atomized Powder is closing the gap fastest through automotive remanufacturing volume expansion.
Grade:
Customer procurement patterns split sharply between qualified aerospace tiers and price-negotiated industrial specifications.
- Aerospace Grade:AMS-certified chemistries with full lot traceability command substantial premiums for hot-section engine component repair. Demand anchors in Rolls-Royce and GE Aviation supply chains, with qualification timelines extending 18-36 months for novel formulations. FAA and EASA dual-certification requirements concentrate supply among established converters.
- High Purity Grade:Reduced interstitial content serves medical implant applications where biocompatibility testing drives specification rigidity. FDA and EPA requirements impose parallel purity standards on domestic US conversion facilities, while European channels face MDR compliance burdens.
- Specialty Grade:Custom compositions address niche wear and corrosion environments in chemical processing equipment.
- Commercial Grade:Standard specifications dominate bulk hardfacing markets with minimal qualification overhead.
Aerospace Grade captures the steepest pricing tier, though High Purity Grade is expanding most quickly through orthopedic implant demand in aging population markets.
Application:
End-use concentration patterns reflect divergent technical requirements and procurement sophistication across industrial sectors.
- Aerospace:Hot-section turbine blade repair and additive manufacturing refurbishment drive specification intensity. German engine maintenance clusters and US Southwest aviation corridors adopt qualified powder through long-term offtake contracts displacing spot purchasing.
- Medical:Cobalt-chromium-molybdenum orthopedic implants require biocompatibility certification extending through device approval cycles. Demand concentrates in Warsaw, Indiana and Tuttlingen, Germany surgical instrument manufacturing zones.
- Automotive:Valve seat hardfacing and powertrain component remanufacturing absorb cost-optimized water-atomized grades.
- Energy:Oilfield drilling component cladding and nuclear valve facing require corrosion-resistant compositions.
Aerospace maintains volume leadership, while Medical is gaining share fastest through demographic-driven implant procedure growth.
End User:
Procurement authority distribution shapes converter sales strategies and technical service requirements.
- Manufacturers:OEM powder-bed fusion and directed energy deposition cells require qualified material with process-parameter matching. Automotive and aerospace tier-1 suppliers dominate volume offtake.
- Maintenance Service Providers:Aviation MRO networks and industrial repair shops drive spot demand for qualified grades with rapid lot certification.
- Defense Contractors:Military airframe and engine programs impose ITAR-controlled supply chains with restricted converter pools.
- Research Institutions:National laboratories and university additive manufacturing centers pilot novel alloy chemistries before commercial scale-up.
Manufacturers hold the dominant procurement position, while Maintenance Service Providers are climbing the fastest through distributed repair cell deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gas atomization capacity for aerospace-qualified cobalt alloy powder clusters in Sweden and select United States sites, while REACH and EU F-Gas Regulation reshape conversion economics across European supply chains. Demand geography follows precision manufacturing corridors and aviation maintenance clusters in Germany, the United States, Japan, China, and the United Kingdom.
United States
Aerospace maintenance, repair, and overhaul networks in the US Southwest drive qualified powder consumption for on-wing turbine blade refurbishment. FAA certification requirements and EPA environmental handling standards govern domestic conversion facilities. Carpenter Technology Corporation anchors specialty grade production through captive vacuum induction melting capacity in Pennsylvania and surrounding industrial zones.
Germany
Precision manufacturing corridors in Baden-Württemberg and Bavaria absorb premium spherical grades for additive manufacturing repair cells serving Rolls-Royce supply chains. ECHA REACH mandates and EU F-Gas Regulation impose full supply chain disclosure obligations on cobalt entering aerospace channels. Stuttgart and Munich industrial clusters face steepest compliance cost escalation, accelerating backward integration strategies.
Sweden
Sandvik AB leverages gas atomization expertise to dominate premium powder supply for European and North American aviation markets. The country's national chemical regulator enforces ECHA-aligned substance registration requirements on powder conversion operations. Sandviken and Stockholm-region facilities concentrate aerospace-qualified spherical grade capacity, creating single-source vulnerability for global supply chains.
Japan
Tokyo and Nagoya industrial corridors demand high-purity cobalt-chromium-molybdenum compositions for orthopedic implant manufacturing serving aging demographics. METI industrial standards and PMDA biocompatibility requirements parallel FDA rigidity for medical device materials. Osaka-based precision metallurgy clusters specialize in directed energy deposition parameter matching for domestic aviation tier-1 suppliers.
United Kingdom
Derby and Bristol aerospace corridors source qualified powder for Rolls-Royce turbine engine maintenance networks under dual FAA-EASA certification regimes. UK REACH retains substance registration obligations post-Brexit, maintaining disclosure parity with continental European channels. Midlands manufacturing zones face procurement compression toward single-source powder agreements with integrated repair cell operators.
Cobalt Alloy Powder Market Vendor Landscape
Concentration sits with gas atomization specialists holding aerospace qualification credentials, while water atomization players occupy cost-sensitive automotive hardfacing segments. The vendor base stratifies across three tiers: integrated powder-converter-repair cell operators, captive metallurgy divisions of aerospace OEMs, and independent commodity converters. Dominant competitive moves include capacity expansion in spherical grade atomization and strategic partnerships bridging powder supply to additive manufacturing equipment integration.
Within the integrated specialty tier, Sandvik AB and Carpenter Technology Corporation exemplify archetypes combining captive melting capacity with aerospace channel access. Höganäs AB occupies a position representing Scandinavian powder metallurgy consolidation. These three entities anchor competitive dynamics through differentiated qualification timelines and geographic proximity to German and US Southwest aviation clusters.
| Leading Market Players |
|---|
| Sandvik AB |
| Carpenter Technology Corporation |
| Umicore |
| Höganäs AB |
| Kennametal Inc. |
| Freeport Cobalt |
| ATI |
| Norilsk Nickel |
| Eramet |
| Others |
Supply Flow & Price Mechanics
Gas atomization capacity utilization above 85 percent in Swedish and Pennsylvania facilities creates scale economies that lock in price floors for aerospace-qualified spherical grades while marginalizing smaller converters. REACH compliance investments and EU F-Gas Regulation traceability mandates compound fixed cost burdens, compressing margin structures for non-qualified producers and accelerating consolidation toward integrated powder-converter-repair cell operators.
Pricing Analysis
REACH and EU F-Gas Regulation dictate the pricing tier structure across European aerospace and medical device channels, mandating full supply chain disclosure that separates qualified converters from commodity suppliers. Three-tier pricing structure across premium aerospace-qualified, standard industrial-grade, and economy hardfacing levels reflects certification intensity and lot traceability depth. Cost compression in water-atomized automotive segments is intensifying because Detroit-area powertrain remanufacturers negotiate volume contracts with irregular powder suppliers. Maintenance service providers exhibit highest price sensitivity for qualified grades, while OEM manufacturers accept substantial premiums for AMS-certified chemistries with guaranteed process-parameter matching.
Supply Chain Analysis
Sweden and the United States anchor spherical powder production for aviation repair cells, while Germany and Japan absorb premium grades through precision manufacturing corridors. Raw material supply draws from Democratic Republic of Congo concentrate, Finnish refined metal, and Australian laterite sources, with cobalt metal price volatility transmitting unpredictably through conversion economics. Single-source vulnerability concentrates in Sandviken-region gas atomization facilities serving global Rolls-Royce and GE Aviation supply chains. Distribution runs through long-term offtake contracts with integrated repair cell operators, displacing spot market purchasing for qualified aerospace grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across medical device biocompatibility tiers and recycled cobalt qualification pathways, as demographic-driven orthopedic implant demand and EU Green Deal circular material flows create niches underserved by incumbent aerospace-focused converters.
For Market Incumbents: Secure captive vacuum induction melting capacity expansions in Pennsylvania and Baden-Württemberg corridors to defend against emerging Asian gas atomization entrants targeting FAA-EASA dual-certification. Anchor long-term offtake contracts with aviation MRO networks before procurement compression completes its shift toward single-source powder agreements with integrated repair cell operators. For New Entrants and Emerging Players: Lead with recycled cobalt qualification pathways under EU Green Deal circular material frameworks, targeting margin relief positioning against virgin feedstock price pressure. Warsaw and Tuttlingen orthopedic implant manufacturing zones offer the most penetrable entry points, with FDA-MDR parallel biocompatibility certification as the critical go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors gas atomization specialists with aerospace qualification credentials and backward integration into captive feedstock sourcing. Long-term viability rests on converter pools capable of spanning 18-36 month AMS specification certification timelines without liquidity strain. Watch for Democratic Republic of Congo supply disruption signals as inflection indicators for recycled cobalt pathway valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Gas Atomization Capacity Expansion | Swedish and Pennsylvania facility additions lock in aerospace-qualified spherical grade supply dominance. |
| Backward Integration into Captive Feedstock | Finnish refined metal and Australian laterite sourcing insulates converters against DRC concentrate volatility. |
| Recycled Cobalt Qualification Pathway | EU Green Deal circular material flows offer margin relief positioning against virgin feedstock price pressure. |
| Long-term Offtake Contract with MRO Networks | Aviation maintenance procurement compression favors integrated powder-converter-repair cell operators. |
| AMS Specification Certification Investment | 18-36 month qualification timelines for novel alloy chemistries create competitive moats against commodity entrants. |
Methodological Framework
A spread of perspectives from gas atomization plant managers, aerospace tier-1 supplier procurement leads, orthopedic implant device executives, and aviation MRO network directors converged on the working assumptions. Primary interview insights combined with secondary validation from ECHA REACH substance registrations, FAA certification databases, SEC filings of specialty metallurgy companies, and customs trade data for cobalt powder movements. Bottom-up facility capacity modeling and top-down end-use demand estimation triangulated volume and value outputs.
Segmentation dimensions modeled include powder morphology tier, grade certification level, end-use application intensity, and geographic regulatory cluster across the analysis window. CAGRs derived from facility utilization trajectories, qualification timeline backlogs, and substitution elasticity parameters for directed energy deposition versus traditional weld repair. Industry-specific forecast inputs incorporated orthopedic implant procedure growth curves and aviation engine fleet refurbishment cycles.
The analysis sits within stated boundaries; outcomes outside sustained aerospace production rates, stable DRC concentrate supply, or unaltered REACH-MDR regulatory stringency would require recalibration. Forecasts reflect documented assumptions regarding gas atomization yield rates and medical device biocompatibility testing durations. Recalibration cycles align with material shifts in cobalt metal pricing, AMS specification revision schedules, and EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Nitinol Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Europe Ceramic Ball Bearings Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Chromium Carbide Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Asia-Pacific Metal Casting Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Global Braze Alloys Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Global High Performance Alloys Market