
 Global Cough Hypersensitivity Syndrome Treatment Market | 2026-2036
Global Cough Hypersensitivity Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cough Hypersensitivity Syndrome Treatment Market Foresight
Good Clinical Practice certification is collapsing as the baseline threshold for trial participation, forcing smaller developers toward contract research partnerships. Pfizer Inc. leverages its respiratory pipeline infrastructure to sustain Phase III programs across multiple continents. AstraZeneca PLC differentiates through biologics specialization in refractory cough indications. Bellus Health Inc. anchors its strategy on selective P2X3 antagonist development, navigating regulatory complexity with targeted investigator-initiated studies.
Cough hypersensitivity syndrome treatment encompasses pharmacological interventions targeting heightened afferent nerve sensitivity in the airways, typically involving P2X3 receptor antagonists, voltage-gated sodium channel modulators, and neurokinin-1 receptor blockers formulated for oral or inhaled delivery. These therapies aim to suppress pathological cough reflex amplification without sedating central nervous system depression. Neuromodulators command premium pricing due to mechanistic novelty and limited therapeutic alternatives for refractory patients. Inhaled corticosteroids retain volume leadership through established reimbursement in asthma-overlap populations, though margin pools are shifting toward combination therapy formats that bundle bronchodilator and antitussive mechanisms.
The FDA, EMA, and Japan's PMDA each enforce distinct evidentiary standards for chronic cough endpoints, with the FDA requiring validated objective cough frequency monitoring while EMA accepts patient-reported outcome instruments. This divergence compels sponsors to design parallel trial architectures or accept geographic licensing limitations. Stakeholders must monitor P2X3 class safety signals and corresponding label restrictions that could reshape prescriber confidence and payer willingness across major markets.
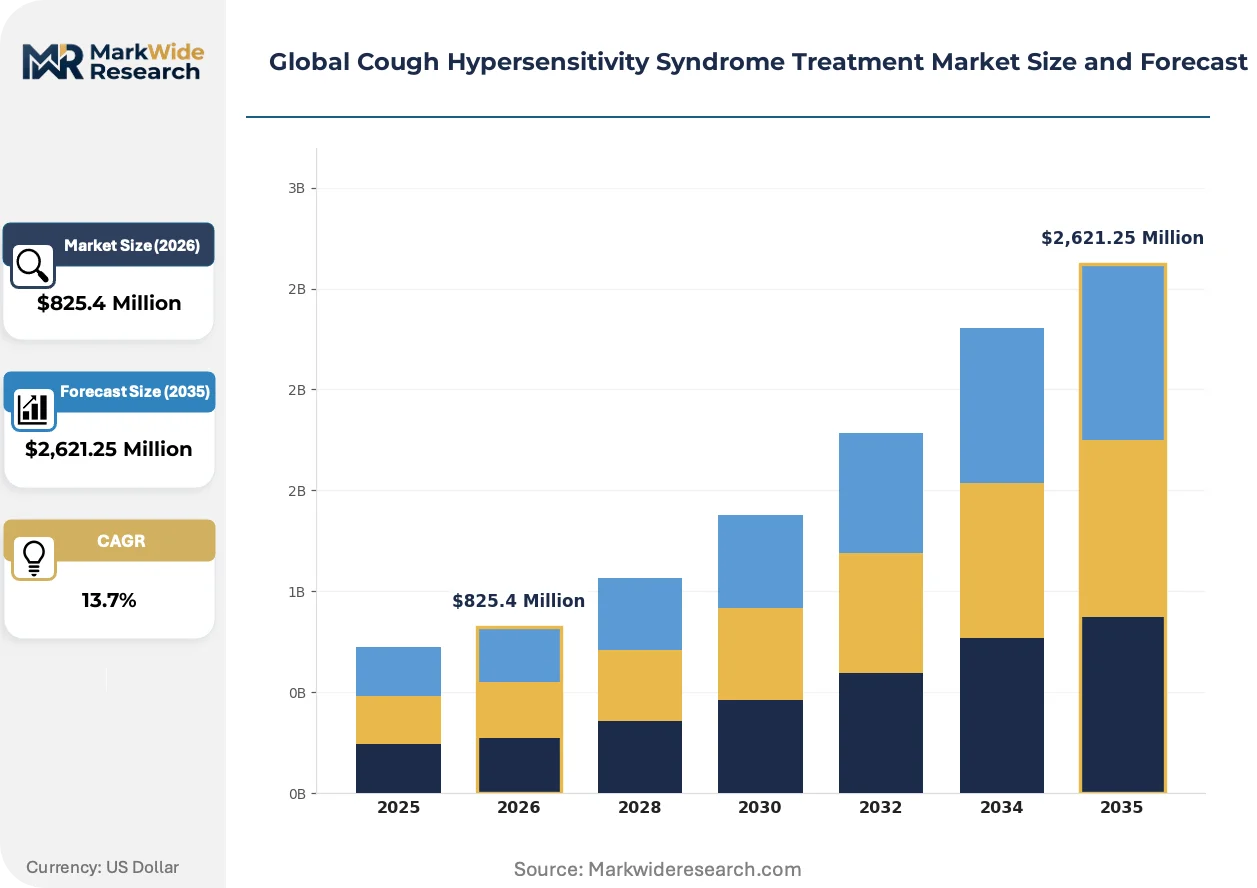
Market Dynamics
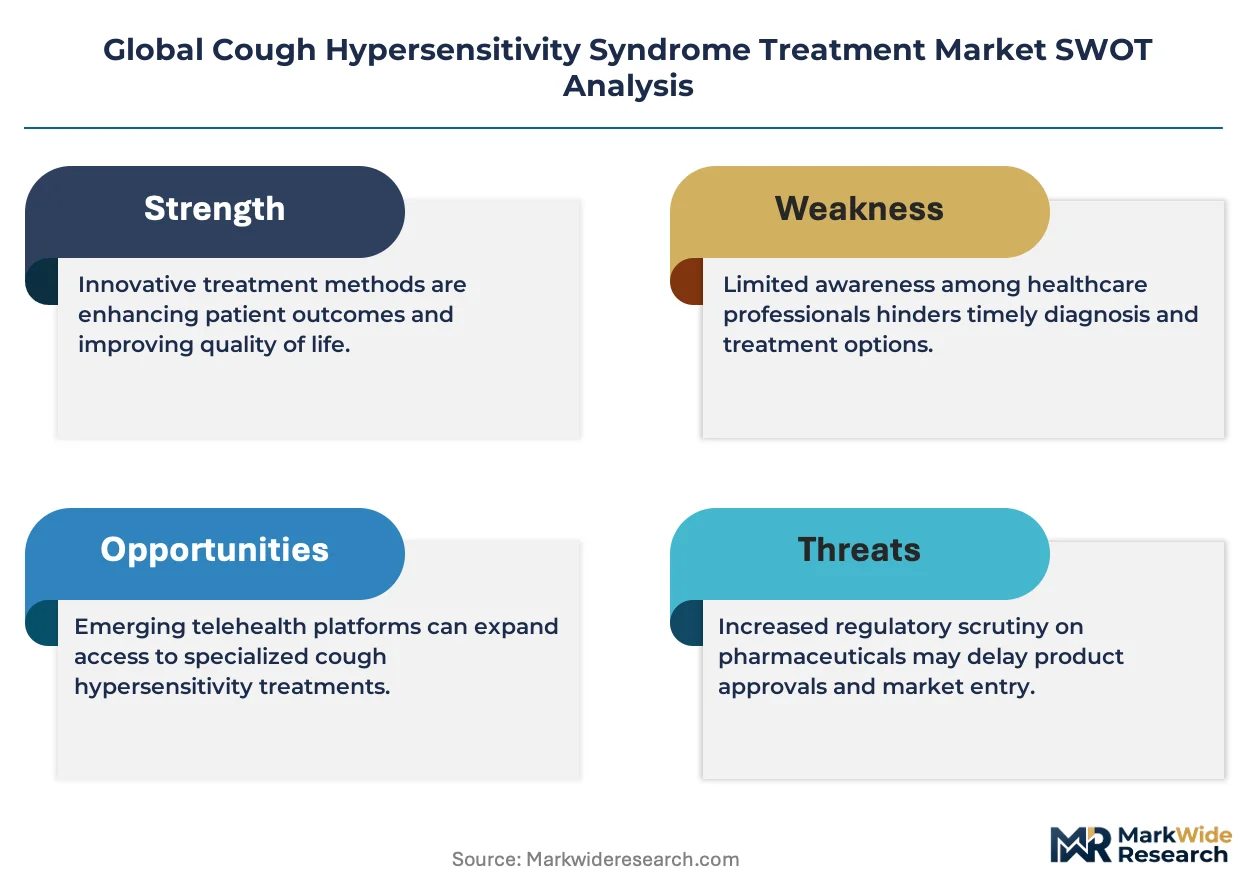
P2X3 receptor antagonist development is concentrating R&D investment toward selective peripheral nerve modulation, collapsing the historical reliance on centrally acting antitussives and forcing reformulation of clinical trial endpoints across major regulatory jurisdictions.
Growth Catalysts
- FDA orphan drug designation:Developers targeting refractory chronic cough gain tax credits and market exclusivity incentives, accelerating investment in mechanistically novel candidates.
- Pulmonology clinic networks:Specialized respiratory centers in Germany, the United Kingdom, and Japan are building dedicated cough clinics that streamline patient identification and protocol enrollment.
- Objective cough frequency monitoring:Validated acoustic digital biomarkers are replacing subjective symptom scales, improving signal detection in Phase IIb dose-ranging studies.
Market Restraints
- Taste disturbance liability:P2X3 antagonists carry class-wide dysgeusia signals that limit dose escalation and complicate placebo-controlled trial design.
- Specialized CRO concentration:Respiratory trial expertise clusters among three contract research organizations, creating capacity bottlenecks for mid-cap sponsors.
- Inhaled corticosteroid substitution:Established asthma-cough overlap protocols delay neuromodulator adoption in primary care settings where pulmonology referral rates remain low.
Strategic Opportunities
- Japan's PMDA Sakigake pathway:Priority review vouchers for innovative antitussives enable twelve-month accelerated approval timelines for qualifying sponsors.
- Pediatric refractory cough:Absence of approved therapies for adolescent populations creates first-mover advantage for developers completing juvenile toxicology programs.
- Combination inhaler formats:Bundling bronchodilator, corticosteroid, and antitussive mechanisms into single-device regimens addresses polypharmacy compliance in elderly comorbid populations.
Industry Challenges
- Cross-jurisdiction endpoint harmonization:FDA-mandated 24-hour objective cough counts conflict with EMA-accepted Leicester Cough Questionnaire scores, forcing parallel trial architectures or geographic licensing restrictions.
- Patient-reported outcome validation:Linguistic adaptation of cough-specific quality-of-life instruments for Korean, Mandarin, and Arabic-speaking populations delays multinational study initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cough Hypersensitivity Syndrome Treatment Market |
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $2,621.25 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antitussives, Neuromodulators, Inhaled Corticosteroids, Combination Therapy Application: Chronic Cough, Upper Respiratory Infection, Allergic Rhinitis, Gastroesophageal Reflux End User: Primary Care Providers, Pulmonologists, Allergy Specialists, Respiratory Therapy Centers Delivery Mode: Oral, Inhalation, Topical, Injectable |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, AstraZeneca PLC, Merck & Co., Inc., Novartis, Bayer AG, Boehringer Ingelheim GmbH, Bellus Health Inc., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cough Hypersensitivity Syndrome Treatment Market Shifts & Advancements
Digital biomarker integration is collapsing the latency between clinical measurement and regulatory submission, compressing development timelines while raising evidentiary standards for objective endpoint validation.
Selective P2X3 antagonists with optimized central nervous system penetration profiles are supplanting first-generation compounds that carried unacceptable taste disturbance burdens. Pulmonology clinics in the United States and Germany are adopting these refined candidates for refractory patient cohorts previously excluded from standard care pathways. The shift is compressing market opportunity for centrally acting codeine derivatives and accelerating prescriber education investments around peripheral nerve mechanism differentiation.
The EMA's updated guideline on clinical investigation of medicinal products for cough requires standardized objective monitoring alongside patient-reported outcomes, creating dual-endpoint burden for sponsors. Developers must now deploy ambulatory cough recorders validated against manual counts, increasing per-patient trial costs. European pulmonology centers are responding by consolidating into specialized cough research networks capable of managing complex protocol logistics.
Specialized cough clinics are displacing general respiratory practices as the primary referral channel for refractory patients seeking neuromodulator therapy. Hospital systems in the United Kingdom and Australia are unbundling cough diagnostics from broader asthma services, creating dedicated referral pathways that concentrate prescriber influence. This channel reconfiguration is most visible in urban tertiary centers where academic pulmonologists maintain active investigator-initiated study portfolios.
Global Cough Hypersensitivity Syndrome Treatment Market Segmentation
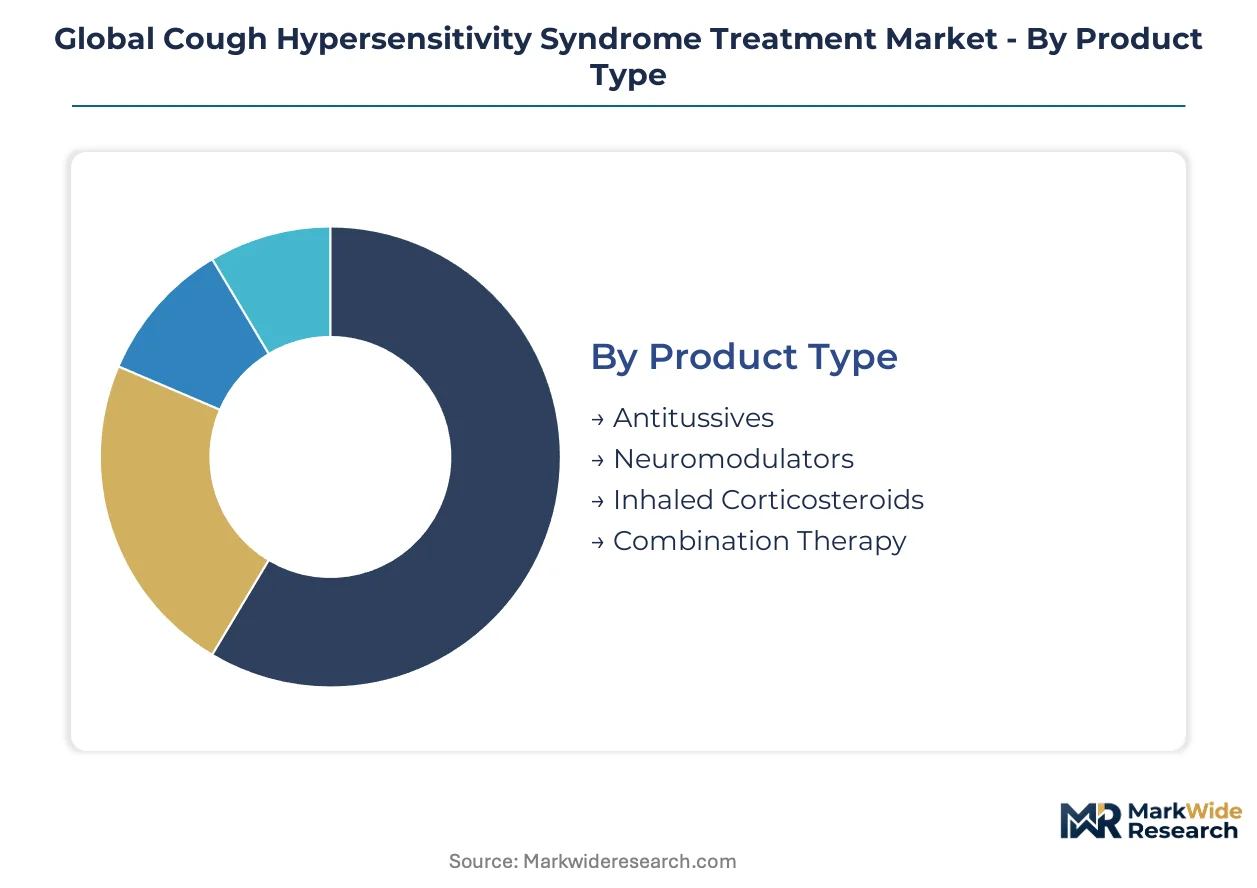
Treatment selection for cough hypersensitivity syndrome varies sharply across clinical settings, reimbursement tiers, and mechanism-of-action preferences. Segmentation reveals where pharmaceutical investment concentrates and which patient pathways resist neuromodulator penetration despite clinical evidence.
Product Type:
Margin pools cluster heavily toward mechanistically novel agents commanding premium pricing, while volume leadership remains anchored to established corticosteroid platforms with broad reimbursement.
- Neuromodulators:Peripheral nerve-targeting P2X3 antagonists and voltage-gated sodium channel modulators deliver differentiated efficacy in refractory populations. Demand concentrates in German and United Kingdom pulmonology clinics where specialized cough centers drive investigator-initiated adoption.
- Combination Therapy:Fixed-dose regimens bundling bronchodilator, corticosteroid, and antitussive mechanisms address polypharmacy compliance in elderly comorbid populations. United States hospital systems and Japanese respiratory networks are expanding formulary access for these streamlined delivery formats.
- Antitussives:Centrally acting agents including codeine derivatives retain residual volume in primary care settings with limited neuromodulator familiarity.
- Inhaled Corticosteroids:Established asthma-overlap protocols sustain volume leadership through broad payer coverage despite mechanistic limitations in pure cough hypersensitivity.
The dominant share belongs to Inhaled Corticosteroids, while Combination Therapy is closing the gap fastest.
Application:
Clinical trial design complexity and endpoint validation requirements vary substantially across indication type, directly shaping sponsor investment priorities.
- Chronic Cough:Persistent cough exceeding eight weeks represents the primary regulatory pathway for novel neuromodulator approval. FDA-mandated 24-hour objective cough frequency monitoring and EMA-accepted patient-reported outcomes create dual-endpoint burdens that concentrate trial activity in specialized United States and European respiratory centers.
- Gastroesophageal Reflux:Refractory cough linked to acid exposure constitutes a mechanistically distinct subpopulation with unmet need. Japanese PMDA Sakigake pathway incentives are accelerating development timelines for sponsors targeting this overlap indication.
- Upper Respiratory Infection:Acute post-viral cough hypersensitivity offers shorter trial windows but limited pricing power due to self-limiting disease course.
- Allergic Rhinitis:Seasonal exacerbations of cough reflex sensitivity attract antihistamine-antitussive combination development.
Chronic Cough commands the deepest development investment, with Gastroesophageal Reflux expanding most quickly as a target for mechanistic differentiation.
End User:
Prescriber influence over neuromodulator adoption depends on institutional access to objective cough monitoring infrastructure and specialist referral pathway density.
- Pulmonologists:Respiratory specialists in tertiary centers control access to P2X3 antagonist therapy through dedicated cough clinic protocols. German university hospitals and United Kingdom NHS foundation trusts are consolidating diagnostic and therapeutic services into streamlined referral networks.
- Respiratory Therapy Centers:Specialized facilities with ambulatory cough recording capabilities are displacing general respiratory practices as primary enrollment channels for Phase III trials. Australian hospital systems are replicating this unbundling model.
- Primary Care Providers:Gatekeeper physicians in under-resourced settings default to inhaled corticosteroid substitution due to limited neuromodulator familiarity.
- Allergy Specialists:Immunology-focused clinicians manage overlap populations with rhinitis-cough comorbidity through combination approaches.
Pulmonologists retain the strongest influence over high-value prescribing, while Respiratory Therapy Centers are gaining share fastest through trial infrastructure concentration.
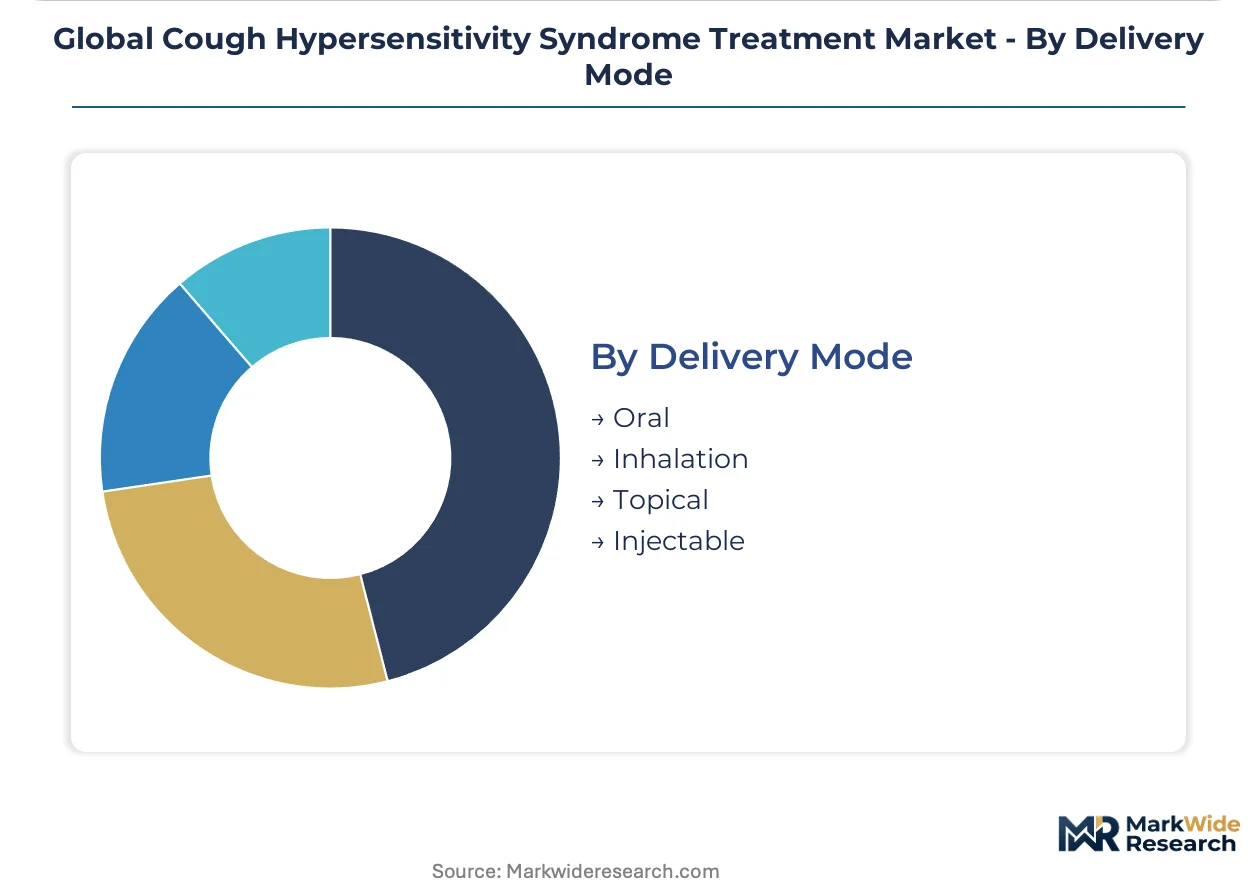
Delivery Mode:
Formulation strategy determines regulatory jurisdiction alignment and manufacturing partnership requirements across development programs.
- Oral:Systemic P2X3 antagonist delivery dominates late-stage pipelines due to patient compliance advantages and scalable production. Selective peripheral nerve modulation with optimized central nervous system penetration profiles is supplanting earlier compounds with taste disturbance liability.
- Inhalation:Localized airway delivery of corticosteroid-neuromodulator combinations targets rapid onset with reduced systemic exposure. European manufacturing clusters in Switzerland and Germany specialize in complex inhaler device assembly.
- Topical:Limited application for surface-acting agents in specific regional anesthesia protocols.
- Injectable:Hospital-administered formulations reserved for acute refractory episodes in controlled settings.
Oral formulations capture the largest development commitment, with Inhalation climbing fastest as device technology enables combination payload refinement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designation incentives and EMA's dual-endpoint requirements are reshaping where clinical development concentrates. Pulmonology clinic networks in specific countries now determine patient access to neuromodulator therapy.
United States
Specialized cough clinics in tertiary centers drive P2X3 antagonist adoption through investigator-initiated protocols. FDA mandates 24-hour objective cough frequency monitoring for chronic cough endpoints, forcing sponsors toward academic medical centers with ambulatory recording infrastructure. Boston and Durham respiratory research clusters host the densest Phase III trial activity.
Germany
University hospital networks in Munich and Heidelberg consolidate diagnostic and therapeutic services into streamlined referral pathways. EMA acceptance of patient-reported outcomes alongside objective measures reduces trial burden compared to US requirements. Baden-Württemberg's pharmaceutical manufacturing base supplies inhaler device components for combination therapy formats.
Japan
PMDA's Sakigake priority review pathway enables twelve-month accelerated approval timelines for innovative antitussives targeting refractory populations. Tokyo and Osaka academic centers concentrate juvenile toxicology programs for pediatric indication expansion. METI funding for respiratory digital biomarker validation supports acoustic cough monitoring standardization.
United Kingdom
NHS foundation trusts unbundle cough diagnostics from broader asthma services into dedicated referral channels. Leicester Cough Questionnaire validation studies originate from East Midlands respiratory research institutes. London hospital systems replicate German cough clinic models with centralized prescriber influence over neuromodulator access.
Australia
Hospital systems in Sydney and Melbourne adopt UK-style cough clinic unbundling to streamline neuromodulator prescribing. TGA alignment with EMA endpoint standards enables parallel trial participation with European sponsors. Specialized respiratory therapy centers with ambulatory recording capabilities displace general practices as primary enrollment channels.
Global Cough Hypersensitivity Syndrome Treatment Market Competitive Landscape
Player mix skews toward large-cap pharmaceutical incumbents with respiratory pipeline infrastructure and emerging biotech specialists targeting selective P2X3 modulation. Market structure concentrates development activity among entities with existing pulmonology commercialization capabilities and those with orphan drug designation experience. Strategic archetypes include mechanistic innovators pursuing peripheral nerve targets and incumbents defending corticosteroid volume through combination format extension. Dominant competitive moves encompass strategic partnerships for CRO capacity access and portfolio diversification into digital biomarker-enabled trial designs.
Within the large-cap incumbent tier, Pfizer Inc. and AstraZeneca PLC exemplify archetypes leveraging respiratory infrastructure for multi-continental Phase III execution. Bellus Health Inc. occupies a position representing selective P2X3 antagonist specialization with targeted investigator-initiated study strategies. These three entities collectively illustrate the competitive spectrum from scale-driven commercialization to mechanism-focused development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| AstraZeneca PLC |
| Merck & Co., Inc. |
| Novartis |
| Bayer AG |
| Boehringer Ingelheim GmbH |
| Bellus Health Inc. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply & Pricing Matrix
Oral P2X3 antagonist formulations displacing inhaled corticosteroid-first protocols are redrawing procurement geography toward Swiss and German manufacturing clusters while compressing margin structures for legacy nebulizer-dependent supply chains.
Pricing Analysis
Certification level (FDA orphan designation versus standard NDA pathway) creates the primary spread between neuromodulator price tiers. Three-tier pricing structure across premium, standard, and economy levels segments by mechanism novelty and reimbursement tier. Cost compression in the antitussive tier is intensifying because inhaled corticosteroid substitution protocols delay neuromodulator adoption. Primary care gatekeepers exhibit highest price sensitivity; tertiary pulmonology centers demonstrate lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for active pharmaceutical ingredient shipments. Supply concentrates in Switzerland, Germany, and India for P2X3 antagonist synthesis and inhaler device assembly. Manufacturing draws from specialized chemical intermediates, precision-milled device components, and validated acoustic monitoring hardware. Single-source vulnerability sits with concentrated CRO capacity for respiratory trial execution. Distribution runs through hospital system formularies and specialized cough clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as FDA orphan drug designation cycles refresh development incentives and pulmonology clinic investment waves crest across German and Japanese hospital systems.
For Market Incumbents: Shield corticosteroid volume positions through combination inhaler format extensions that bundle bronchodilator and antitussive mechanisms. Accelerate backward integration into precision device manufacturing to secure capacity access against CRO bottlenecks. Prioritize certification investment in FDA-validated objective cough frequency monitoring infrastructure. For New Entrants and Emerging Players: Lead with pediatric refractory cough indications where juvenile toxicology completion creates first-mover structural advantage. Target Japan's PMDA Sakigake pathway for twelve-month accelerated approval timelines. Deploy investigator-initiated study strategies in United Kingdom NHS foundation trusts to build prescriber influence before commercial infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed respiratory CRO specialists holding concentrated trial capacity in German and Australian cough clinic networks. Long-term viability hinges on P2X3 class safety signal resolution and corresponding label restriction scope across FDA and EMA jurisdictions. Watch taste disturbance liability thresholds as the inflection indicator for prescriber confidence and payer willingness.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Objective cough frequency monitoring deployment accelerates Phase III enrollment in Boston and Durham academic centers. |
| Regulatory Approval Pathway | Orphan drug designation secures tax credits and market exclusivity for refractory chronic cough indications. |
| Manufacturing Scale-Up | Swiss and German device assembly expansion supports combination inhaler format production for elderly comorbid populations. |
| Pipeline Diversification | Juvenile toxicology program investment opens pediatric refractory cough segments with zero approved competitors. |
| Strategic Partnership | Contract research organization alliances resolve capacity bottlenecks for mid-cap sponsors lacking respiratory trial expertise. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists inform qualitative assessments. Bottom-up patient-flow modeling and top-down epidemiological triangulation validate market sizing across the analysis window.
Segmentation dimensions modeled include treatment mechanism, dosage form, administration route, patient population severity tier, and regional regulatory cluster. CAGRs derive from epidemiological trend projection, adoption curve analysis, and pricing elasticity estimation. Forecast inputs incorporate pulmonology clinic network expansion rates and objective cough monitoring technology penetration curves.
The analysis sits within stated boundaries; outcomes outside continued orphan drug incentive stability and P2X3 receptor target validation would require recalibration. Forecasts reflect assumptions around regulatory endpoint harmonization progress and taste disturbance liability management. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market