
 Switzerland E-Bike Market | 2026-2036
Switzerland E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland E-Bike Market Analytics
Lithium-ion battery chemistry is consolidating around higher energy-density cell formats that reduce frame weight and extend range per charge. BMC Switzerland AG leverages its domestic engineering base to sustain premium positioning across performance segments. Canyon Bicycles GmbH anchors its competitive stance through direct-to-consumer channels that bypass traditional retail markups. myStromer AG differentiates via integrated Swiss manufacturing that controls quality from motor assembly through final testing.
An e-bike combines a conventional bicycle frame with an electric assist system comprising a rechargeable battery pack, hub or mid-drive motor, and pedal-torque sensor delivering supplemental power up to 25 km/h under European type-approval rules. City E-Bikes dominate unit volume as Swiss commuters replace short car trips with electrified cycling, while Mountain E-Bikes capture margin pools through advanced suspension integration and higher component specifications. Lithium-Ion batteries now define the technical baseline as nickel-metal hydride and lead acid configurations retreat to price-sensitive replacement segments.
Swissmedic oversees product safety compliance for electrical systems, while METI-aligned type-approval frameworks ensure harmonization with EU motor-assisted cycle directives that govern maximum assisted speed and power output. The Federal Roads Office (FEDRO) and cantonal transport authorities shape demand through cycling lane investments and parking infrastructure standards that privilege electrified mobility. Stakeholders must monitor evolving battery recycling mandates and potential power-threshold revisions that would reclassify speed-pedelec products under moped insurance and licensing requirements.
Market Dynamics
Battery chemistry migration toward high-nickel lithium-ion cell architectures is compressing frame weights and extending per-charge range, forcing incumbent suppliers to retool cell sourcing contracts and thermal management designs.
Growth Catalysts
- Swissmedic electrical safety mandates:Harmonized testing protocols for battery packs and motor controllers reduce certification friction for domestic manufacturers seeking cantonal procurement contracts.
- Zurich-Geneva corridor density:Population concentration along this transit axis generates predictable commuter demand for speed-pedelec configurations that replace regional rail segments.
- Mid-drive torque sensor integration:Advanced pedal-assist algorithms deliver smoother power modulation, attracting recreational cyclists upgrading from conventional mountain bikes.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress gross margins for battery pack assemblers unable to pass through costs in premium-positioned retail channels.
- East Asian cell concentration:Cylindrical and prismatic lithium-ion production clusters in South Korea and Japan create single-source dependency risks for Swiss frame integrators.
- 25 km/h type-approval ceiling:EU motor-assisted cycle directives cap assisted velocity, limiting product differentiation against internal-combustion mopeds in suburban commuter segments.
Strategic Opportunities
- Ticino and Graubünden alpine tourism:Mountain E-Bike rental fleets serving ski-resort summer operations remain underpenetrated relative to Zurich and Basel urban markets.
- FEDRO cycling infrastructure grants:Federal Roads Office funding for charging stations and secure parking creates pull-through demand for fleet operators and municipal bike-share programs.
- Cell-to-frame battery architectures:Direct integration of pouch cells into carbon fiber monocoques eliminates redundant housing mass, opening industrial design differentiation.
Industry Challenges
- Power electronics firmware certification:Swissmedic validation timelines for motor controller software updates extend product launch cycles and strain engineering bandwidth.
- After-sales service network scaling:Direct-to-consumer brands lack physical presence for warranty battery swaps, forcing partnerships with independent bicycle retailers that erode margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland E-Bike Market |
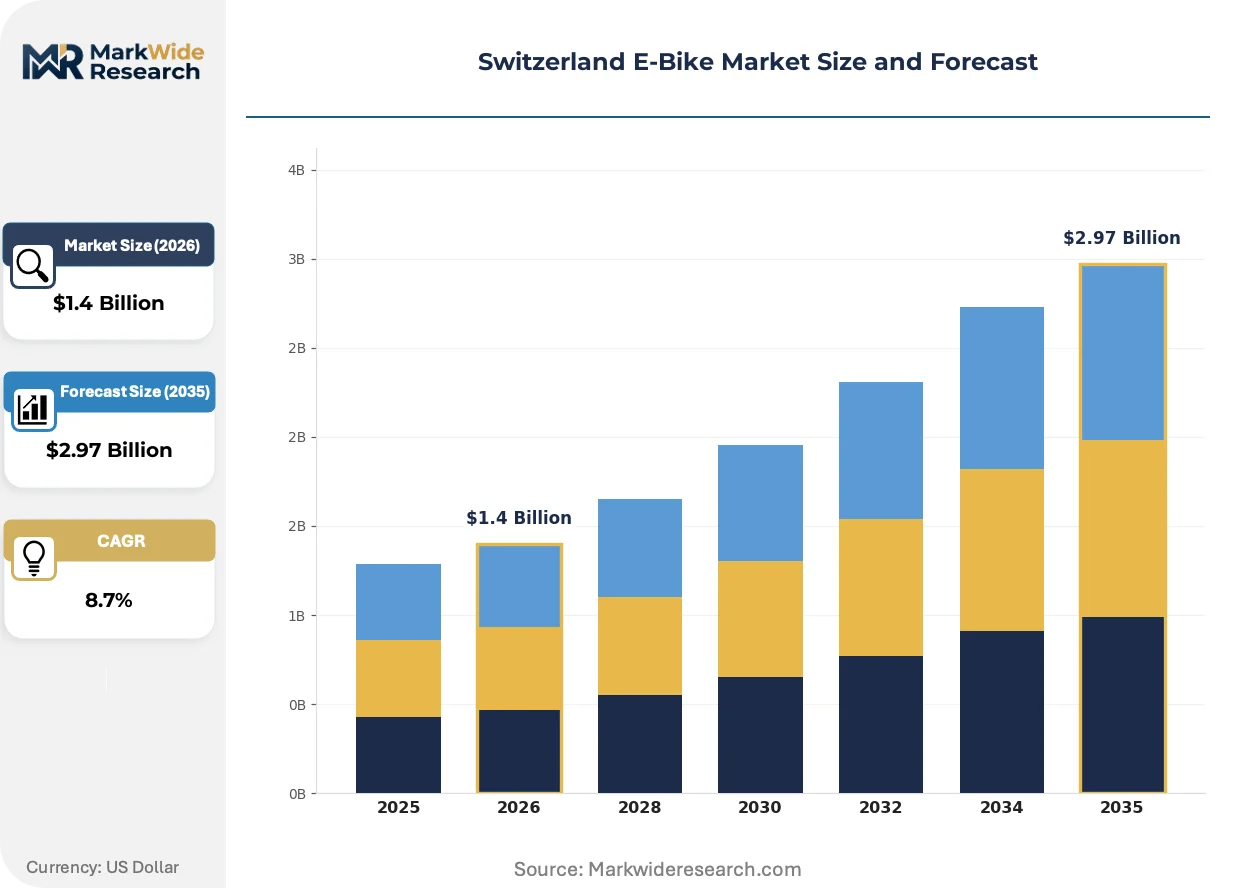
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Touring E-Bikes, Folding E-Bikes Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Others End User: Commuters, Enthusiasts, Rental Services, Delivery Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | MHW Bike-House GmbH (Cube Bikes), Canyon Bicycles GmbH, BMC Switzerland AG, Cresta Bikes, Maxon, Flyer AG, Swiss E-Mobility Group (SEMG), BiXs, myStromer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland E-Bike Market Evolving Landscape
Swiss E-Bike development is converging on three vectors: battery-pack integration depth, regulatory harmonization with neighboring EU frameworks, and channel restructuring that disintermediates traditional retail.
Silicon-anode lithium-ion chemistry is unifying energy density and cycle-life performance in premium battery packs. Zurich-based fleet operators are piloting these cells for daily-use cargo bikes. The technology is unifying previously separate product tiers—commuter and touring categories—into single-platform architectures with software-limited range configurations.
EU Battery Regulation due diligence requirements are reshaping supply chain documentation obligations for Swiss importers. Manufacturers must now trace cobalt and lithium origin through smelter-level disclosure. Mountain E-Bike assemblers sourcing cells from non-EU jurisdictions face compressed certification timelines ahead of 2027 enforcement thresholds.
Subscription-based fleet access is displacing outright ownership among Geneva corporate commuters. Employers contract directly with mobility providers for pooled bike allocations, bypassing retail showrooms. This pattern concentrates procurement volume with operators capable of centralized maintenance and battery rotation logistics.
Switzerland E-Bike Market Segmentation
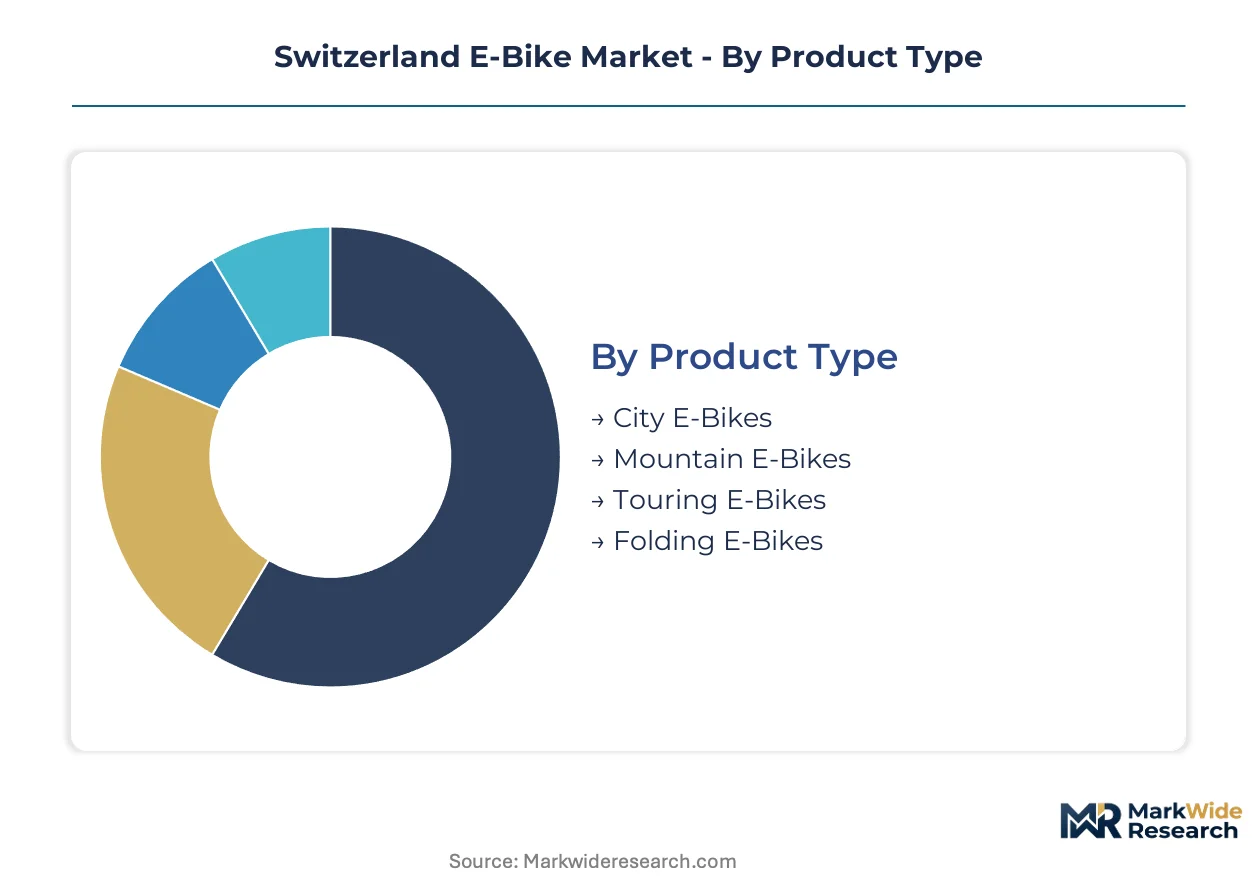
Segmentation in the Switzerland E-Bike Market reveals how infrastructure investment and buyer sophistication split demand across distinct performance tiers and channel preferences. Manufacturers must align battery chemistry, frame geometry, and service models to the specific constraints of each buyer cluster.
Product Type:
Urban density and terrain access separate buyers into four distinct use cases, each demanding specialized motor calibration and frame architecture.
- City E-Bikes:Step-through frames and integrated lighting dominate this segment, with hub-drive motors optimized for flat Zurich-Geneva corridor commutes. Swiss Federal Railways station parking expansions are accelerating replacement of short car trips with electrified cycling.
- Mountain E-Bikes:Mid-drive torque systems and full-suspension platforms define technical specifications. Ticino and Graubünden alpine tourism operators are expanding rental fleets to capture summer revenue gaps left by declining ski traffic.
- Touring E-Bikes:Extended-range battery configurations and pannier-compatible frame geometry serve multi-day route cyclists traversing Alpine passes.
- Folding E-Bikes:Compact hinge mechanisms and reduced wheel diameters address multimodal commuters combining S-Bahn segments with last-mile cycling.
Volume sits with City E-Bikes; growth tilts toward Mountain E-Bikes.
Battery Type:
Chemistry selection determines thermal performance, cycle longevity, and regulatory compliance burden across the product portfolio.
- Lithium-Ion:High-nickel cell architectures from South Korean suppliers now define the technical baseline. Swissmedic electrical safety mandates require harmonized testing protocols for these packs, favoring domestic assemblers with established certification relationships.
- Nickel-Metal Hydride:Lower energy density limits application to price-sensitive replacement markets and legacy fleet retrofits.
- Lead Acid:Heavy mass and short cycle life restrict deployment to entry-level cargo configurations and municipal bike-share programs prioritizing upfront cost over total ownership economics.
- Others:Solid-state prototypes and sodium-ion alternatives remain pre-commercial, with Zurich-based research consortia piloting next-generation cell formats.
Procurement concentrates on Lithium-Ion; substitution risk clusters in the Others category.
End User:
Ownership models and utilization intensity create divergent requirements for durability, service access, and fleet management software.
- Commuters:Daily utilization patterns demand sealed drivetrains and all-weather component specifications. Employer-sponsored mobility budgets in Geneva and Basel are consolidating procurement with operators offering centralized maintenance.
- Enthusiasts:Component upgrade compatibility and diagnostic transparency drive purchasing decisions. This segment tolerates premium pricing for Swiss-manufactured motor systems with proprietary torque sensor calibration.
- Rental Services:High-turnover operations prioritize modular battery swap architectures and GPS tracking integration.
- Delivery Services:Cargo-rated frames and dual-battery configurations support last-mile logistics operators replacing van fleets in Bern and Lausanne urban cores.
Revenue pools favor Commuters; margin expansion tracks Enthusiasts.
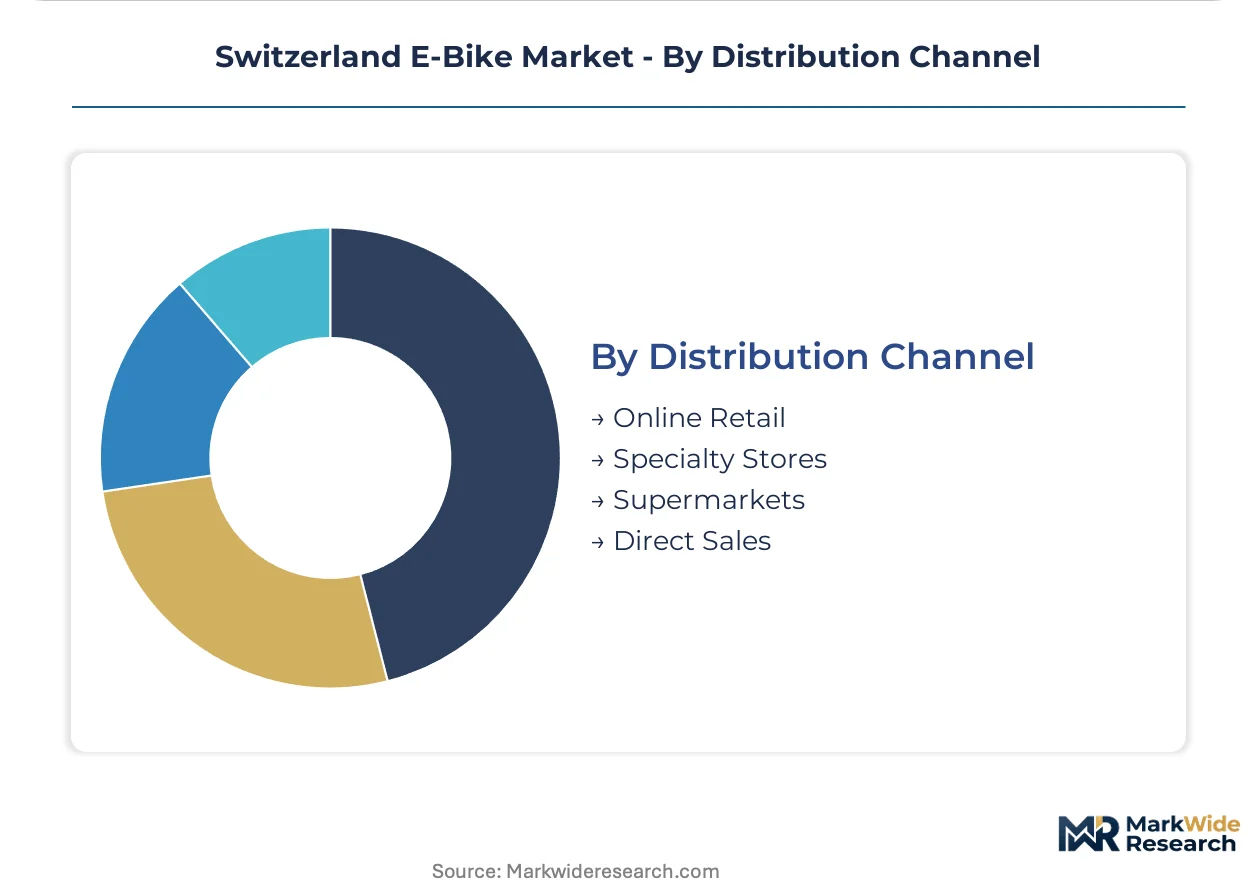
Distribution Channel:
Channel selection determines warranty service capability, margin retention, and customer acquisition cost structure.
- Online Retail:Direct-to-consumer platforms bypass traditional retail markups but strain after-sales service networks. Independent bicycle retailers in Zurich are negotiating partnership terms for warranty battery swaps.
- Specialty Stores:Technical consultation and test-ride availability sustain premium positioning. Cantonal cycling infrastructure grants often require procurement through certified local dealers.
- Supermarkets:Limited service support restricts this channel to entry-level hub-drive configurations with standardized component specifications.
- Direct Sales:Manufacturer-owned showrooms in high-traffic urban locations capture margin but require capital-intensive real estate commitments.
Transaction volume flows through Specialty Stores; channel margin capture favors Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss E-Bike demand clusters along the Zurich-Geneva corridor where population density intersects with Federal Roads Office cycling infrastructure grants. Cantonal transport authorities in Bern, Basel, and Ticino are expanding procurement programs that favor domestic frame assemblers.
German-speaking Switzerland
Zurich and Basel commuters drive volume for speed-pedelec configurations replacing regional rail segments. Swissmedic electrical safety mandates require harmonized testing protocols for battery packs, favoring domestic assemblers with established certification relationships. The Zurich metropolitan area hosts fleet operators piloting silicon-anode lithium-ion cells for daily-use cargo bikes.
Romandy
Geneva corporate mobility budgets are consolidating procurement with operators offering centralized maintenance and battery rotation logistics. Employer-sponsored subscription models bypass retail showrooms entirely. The Lake Geneva basin concentrates demand for touring E-Bikes serving multi-day Alpine route cyclists.
Ticino
Alpine tourism operators in Locarno and Lugano are expanding Mountain E-Bike rental fleets to capture summer revenue gaps left by declining ski traffic. Cantonal cycling infrastructure standards privilege electrified mobility through charging station investments. The region remains underpenetrated relative to northern urban markets.
Graubünden
Mountain resort municipalities in St. Moritz and Davos are deploying fleet access programs for seasonal visitors. Federal Roads Office funding for secure parking infrastructure creates pull-through demand for rental operators. The alpine terrain favors full-suspension platforms with mid-drive torque systems.
Central Switzerland
Lucerne and Zug commuters combine S-Bahn segments with folding E-Bike configurations for last-mile connectivity. Cantonal procurement contracts often require sourcing through certified local dealers, sustaining specialty store channel relevance. The region's multimodal transit integration shapes product specifications toward compact hinge mechanisms.
Switzerland E-Bike Market Competitive Landscape
Channel restructuring dominates the current landscape as direct-to-consumer platforms disintermediate traditional retail markups. The vendor base splits between premium domestic manufacturers with integrated Swiss production and volume-oriented importers sourcing East Asian cell architectures. Three strategic archetypes occupy distinct positions: engineering-led frame integrators controlling motor assembly through final testing, direct-to-consumer brands bypassing retail networks, and fleet operators consolidating employer-sponsored procurement. Competitive moves center on strategic partnerships with independent bicycle retailers for warranty service networks and portfolio diversification into subscription-based fleet access.
Among Swiss-based engineering specialists, BMC Switzerland AG and myStromer AG exemplify the integrated manufacturing archetype with domestic quality control from motor assembly through final testing. Canyon Bicycles GmbH occupies a position within the direct-to-consumer tier, leveraging German operational scale to sustain margin capture outside traditional retail channels. These three entities represent the competitive vectors reshaping procurement relationships across the Zurich-Geneva corridor.
| Leading Market Players |
|---|
| MHW Bike-House GmbH (Cube Bikes) |
| Canyon Bicycles GmbH |
| BMC Switzerland AG |
| Cresta Bikes |
| Maxon |
| Flyer AG |
| Swiss E-Mobility Group (SEMG) |
| BiXs |
| myStromer AG |
| Others |
Value Network & Pricing Analysis
EU Battery Regulation due diligence requirements gate qualified supply and premium-tier pricing access for Swiss E-Bike assemblers unable to trace cobalt and lithium origin through smelter-level disclosure. Manufacturers lacking documented supply chain transparency face exclusion from cantonal procurement contracts and compressed certification timelines ahead of enforcement thresholds.
Pricing Analysis
Volume concentrates in City E-Bike configurations where hub-drive motors and standardized battery packs compete on unit economics, while margin pools accrue to Mountain E-Bike platforms with mid-drive torque systems and full-suspension integration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—Swissmedic electrical safety validation commands pricing premiums for domestic assemblers with established testing relationships. Cost compression in entry-tier segments is intensifying because East Asian cell sourcing contracts expose frame integrators to lithium carbonate price volatility. Employer-sponsored commuters in Geneva and Basel exhibit lowest price sensitivity, while municipal bike-share programs and replacement battery buyers drive economy-tier volume.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from fleet operators and corporate mobility providers, while specialty store networks manage warranty service and test-ride fulfillment for individual purchasers. Cylindrical and prismatic lithium-ion cell production clusters in South Korea, Japan, and China feed Swiss frame integrators, creating single-source dependency risks for high-nickel cell architectures. Raw material procurement draws from lithium carbonate refineries, cobalt smelters, and rare earth magnet processors concentrated in East Asian jurisdictions. Tariff exposure on non-EU cell imports threatens margin structures for importers lacking preferential trade arrangements. Distribution runs through manufacturer-direct platforms, certified specialty retailers, and fleet operator partnerships with employer-sponsored procurement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Switzerland E-Bike Market represents a consolidation play as lithium carbonate price volatility and Swissmedic firmware certification timelines force capital-constrained assemblers toward exit or acquisition.
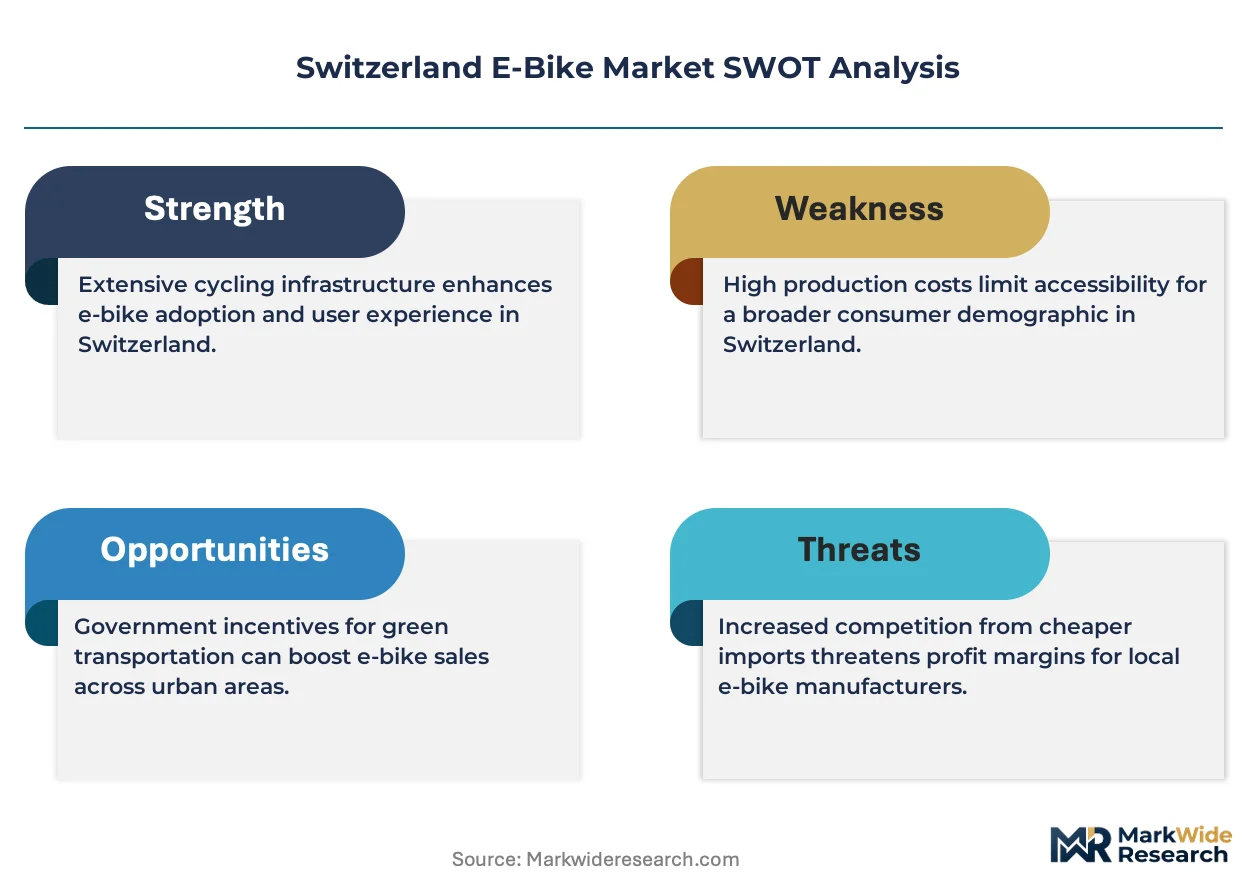
For Market Incumbents: Hedge against East Asian cell concentration by securing dual-source contracts with South Korean and Japanese suppliers, while deepening backward integration into motor controller firmware development to compress Swissmedic validation cycles. Battery pack assemblers facing margin erosion from direct-to-consumer brands should acquire independent bicycle retailer service networks to control warranty fulfillment infrastructure. For New Entrants and Emerging Players: The price-point gap between premium Swiss-manufactured speed-pedelecs and entry-level hub-drive imports creates white-space for mid-tier platforms with silicon-anode battery configurations and modular frame architectures. Ticino and Graubünden alpine tourism rental fleets remain underpenetrated relative to northern urban corridors, offering fleet operator partnerships as the most penetrable entry channel. Target employer-sponsored subscription models in Geneva and Basel with centralized maintenance and battery rotation logistics capabilities. For Investors and Strategic Acquirers: Swissmedic validation timeline extensions for motor controller software updates are the leading indicator that engineering bandwidth constraints will drive acquisition demand among direct-to-consumer brands unable to sustain in-house certification teams. Long-term viability over the next decade rests on vertical integration depth from cell sourcing through final assembly. Target acquisition archetypes include domestic frame integrators with established Swissmedic relationships and proprietary torque sensor calibration capabilities. Monitor FEDRO cycling infrastructure grant disbursement rates as the signal for fleet operator procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Assembly | Domestic pack manufacturing reduces East Asian sourcing dependency and accelerates Swissmedic certification timelines. |
| Direct-to-Consumer Platform Expansion | Channel restructuring bypasses specialty retail markups but requires parallel warranty service network investments. |
| Fleet Operator Partnership Development | Employer-sponsored subscription models in Geneva and Basel concentrate procurement volume with centralized maintenance providers. |
| Silicon-Anode Battery Technology Adoption | Next-generation cell chemistry unifies commuter and touring categories into single-platform architectures with software-limited range. |
| Alpine Tourism Rental Fleet Penetration | Ticino and Graubünden summer operations capture revenue gaps from declining ski traffic through Mountain E-Bike deployment. |
Research Methodology
Trade databases, Swiss Federal Railways procurement disclosures, and Swissmedic regulatory filings formed the secondary backbone for volume and value estimation. Primary interviews with frame assembly plant managers, cantonal transport authority procurement leads, independent bicycle retailer service heads, and fleet operator logistics directors validated demand assumptions and channel dynamics. Bottom-up unit shipment tallies triangulated against top-down consumer expenditure estimates across the Zurich-Geneva corridor and alpine tourism regions.
Historical trendline analysis of battery chemistry migration and cycling infrastructure investment patterns informed projection assumptions across the modeling period. Segmentation dimensions included product type, battery chemistry tier, end-user ownership model, and distribution channel structure. CAGRs derived from fitted growth curves incorporating Swissmedic certification timeline impacts, FEDRO grant disbursement trajectories, and lithium carbonate price volatility assumptions. Industry-specific forecast inputs encompassed speed-pedelec type-approval thresholds and EU Battery Regulation enforcement progression.
Inputs from cantonal transport authorities and fleet operator procurement departments were available through the study window; gaps in real-time lithium carbonate spot pricing and cell contract renewal terms introduce uncertainty bands around battery pack cost assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market