
 Europe E-Cargo Bike Market | 2026-2036
Europe E-Cargo Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Cargo Bike Market Foresight
Qualified cargo bike mechanics is bifurcating the European supply base into service-ready and service-constrained operators. Riese & Müller GmbH leverages its German engineering workforce to sustain premium manufacturing depth. Urban Arrow anchors Dutch design leadership through specialized front-loading architecture. Babboe competes on family-oriented utility positioning across Benelux retail channels.
Europe e-cargo bikes are electrically assisted human-powered vehicles engineered to haul commercial loads, typically incorporating mid-drive motors rated between 250 W and 850 W and reinforced chromoly or aluminum frames rated for 300 kg to 600 kg payloads. Their primary commercial purpose is substituting van-based urban delivery with zero-emission last-mile transport. Three-wheel cargo configurations are capturing disproportionate growth in logistics provider fleets due to superior stability under heavy loads. Li-ion battery systems dominate technical specifications across all weight classes, while lead-acid variants retreat to price-sensitive municipal tenders. Food delivery services represent the fastest-expanding end user segment as platform operators seek regulatory shelter from diesel restriction zones.
The EU Green Deal, CE marking requirements under the EU Machinery Directive, and national e-mobility subsidy schemes in Germany and France collectively shape product homologation and fleet procurement timelines. ECHA chemical safety protocols and REACH compliance further constrain battery supply chain sourcing for non-European cell manufacturers. Stakeholders must monitor the divergence between German KBA type-approval standards and emerging French national safety certifications as this regulatory fragmentation threatens cross-border fleet standardization.
Market Dynamics
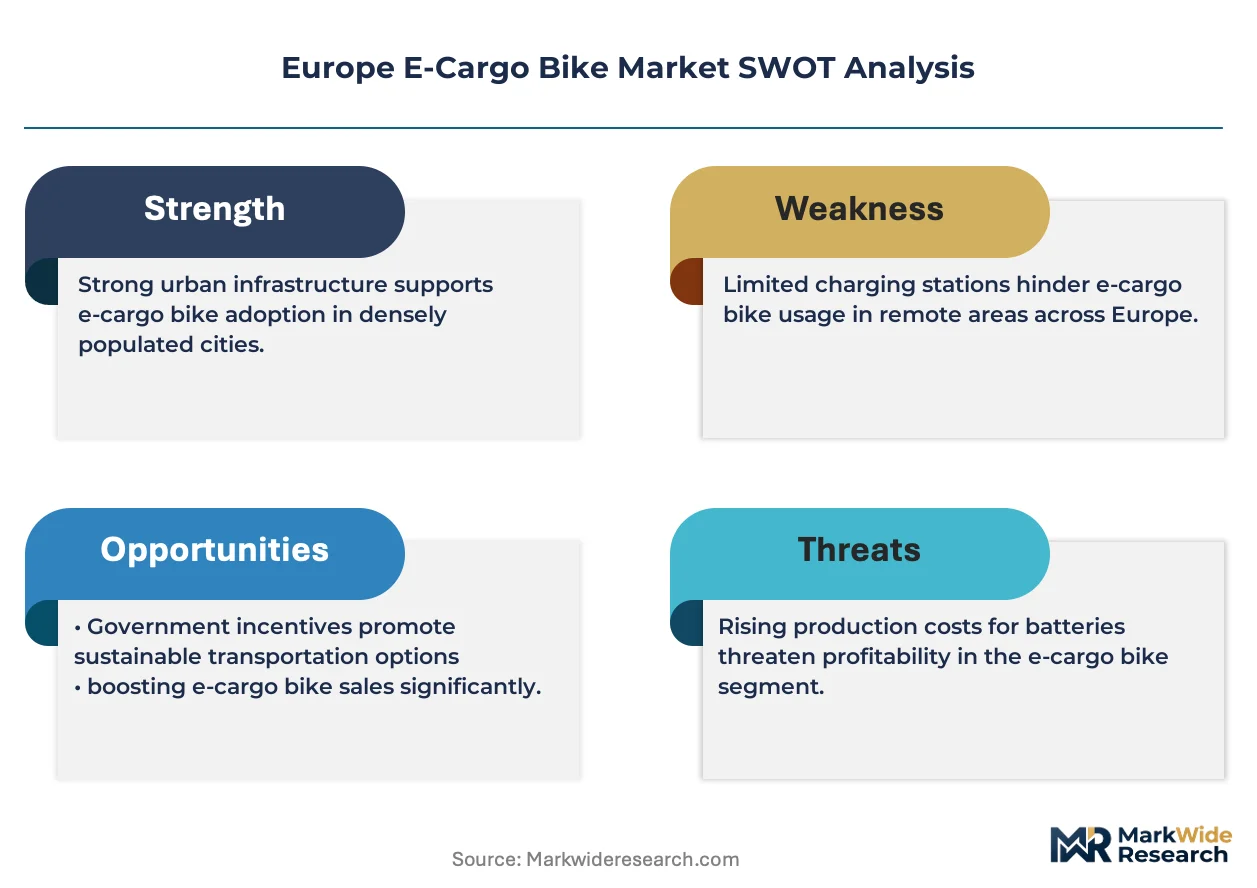
The EU Green Deal and F-Gas Regulation are compressing the operational lifespan of diesel delivery fleets across European urban centers, forcing logistics operators to accelerate zero-emission vehicle substitution timelines and reconfigure last-mile infrastructure around electrically assisted cargo platforms.
Growth Catalysts
- CE marking harmonization:The EU Machinery Directive streamlines cross-border fleet procurement for Dutch and German logistics networks, reducing homologation friction for three-wheel cargo variants rated above 250 W motor output.
- Last-mile logistics consolidation:Platform operators in food delivery and urban retail are expanding captive e-cargo bike fleets to secure regulatory shelter from municipal diesel restriction zones in Amsterdam, Berlin, and Paris.
- Li-ion battery cost curves:Cell chemistry improvements and localized European assembly capacity are extending vehicle range specifications while compressing total cost of ownership calculations for commercial operators.
Market Restraints
- Qualified mechanic scarcity:The bifurcation of service-ready versus service-constrained operators creates fleet downtime risk, particularly for mid-drive motor systems requiring specialized diagnostic equipment.
- Lead-acid battery legacy:Price-sensitive municipal tenders in Southern Europe continue specifying heavier battery chemistries, fragmenting procurement standards and complicating cross-border fleet standardization.
- Frame material volatility:Chromoly and 6061 aluminum supply concentration in East Asian smelters exposes European manufacturers to input cost swings and extended order-to-delivery cycles.
Strategic Opportunities
- French national subsidy expansion:The country's e-mobility incentive schemes are opening procurement channels for family-oriented utility models previously concentrated in Benelux retail networks.
- Front-loading architecture specialization:Dutch design leadership in low-center-of-gravity cargo platforms creates licensing potential for logistics providers seeking stability advantages in hilly Southern European topography.
- Battery swapping infrastructure:Platform operators are piloting hot-swappable Li-ion systems to eliminate charging downtime, creating aftermarket service revenue streams independent of vehicle sales.
Industry Challenges
- KBA type-approval divergence:German national safety certifications for motors above 250 W are misaligned with emerging French technical standards, forcing manufacturers to maintain dual homologation pathways.
- REACH compliance complexity:ECHA chemical safety protocols constrain non-European cell manufacturers from qualifying for municipal tenders, narrowing supplier bases and extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Cargo Bike Market |
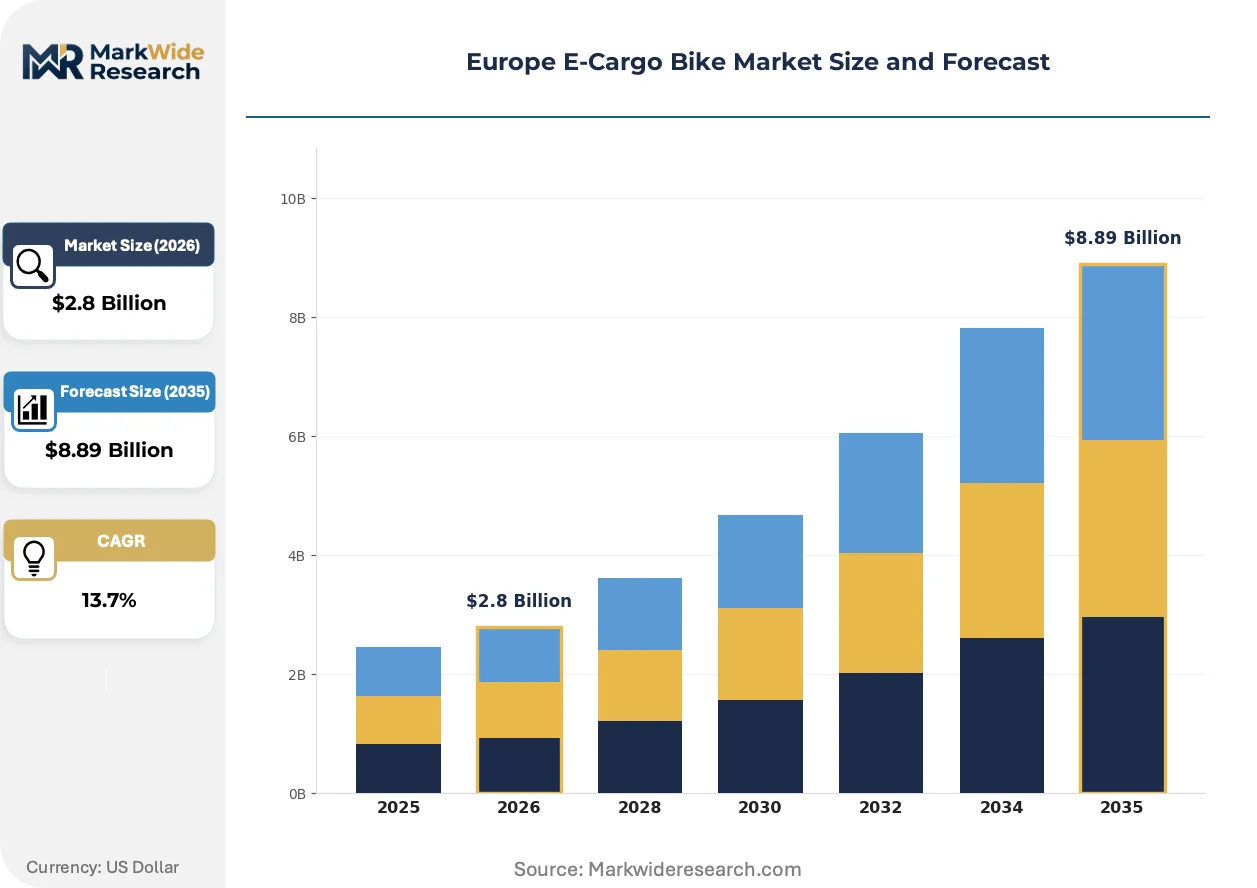
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheel Cargo, Three-Wheel Cargo, Electric Delivery, Load Carrier End User: Retailers, Logistics Providers, Food Delivery Services, Municipalities Battery Type: Li-ion, Lead-acid, NiMH, Others Weight Capacity: 300 kg, 400 kg, 500 kg, 600 kg |
| Companies Covered | Riese & Müller GmbH, Pon Holdings, Accell Group, Urban Arrow, Rad Power Bikes, Giant Manufacturing, Tern Bicycles, Babboe, Merida, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Cargo Bike Market Shifts & Advancements
Active reshaping in this market stems from the collision of regulatory phase-out mandates with supply-side technical specialization, producing divergent fleet procurement strategies between premium engineering-led operators and price-optimized municipal contractors.
Mid-drive motor systems rated between 250 W and 850 W are bifurcating the competitive landscape. German logistics networks and Dutch municipal fleets are adopting higher-torque variants for 300 kg to 600 kg payload ratings. This technology compression is squeezing hub-motor suppliers out of commercial-grade procurement channels while elevating service capability as a primary vendor selection criterion.
REACH and the EU Green Deal are tightening chemical safety and carbon intensity requirements across battery supply chains. European cell assembly localization is accelerating to satisfy ECHA protocols and reduce dependency on non-compliant foreign manufacturers. German and French fleet operators are now prioritizing EU-origin battery packs in tender specifications, reshaping procurement evaluation matrices.
Subscription-based fleet access is displacing outright purchase models among urban food delivery platforms. Operators in Amsterdam and Berlin are leasing vehicle-plus-service bundles that bundle maintenance, insurance, and battery replacement into per-kilometer pricing. This consumption-pattern shift transfers residual value risk to manufacturers while locking in multi-year revenue visibility.
Europe E-Cargo Bike Market Segmentation
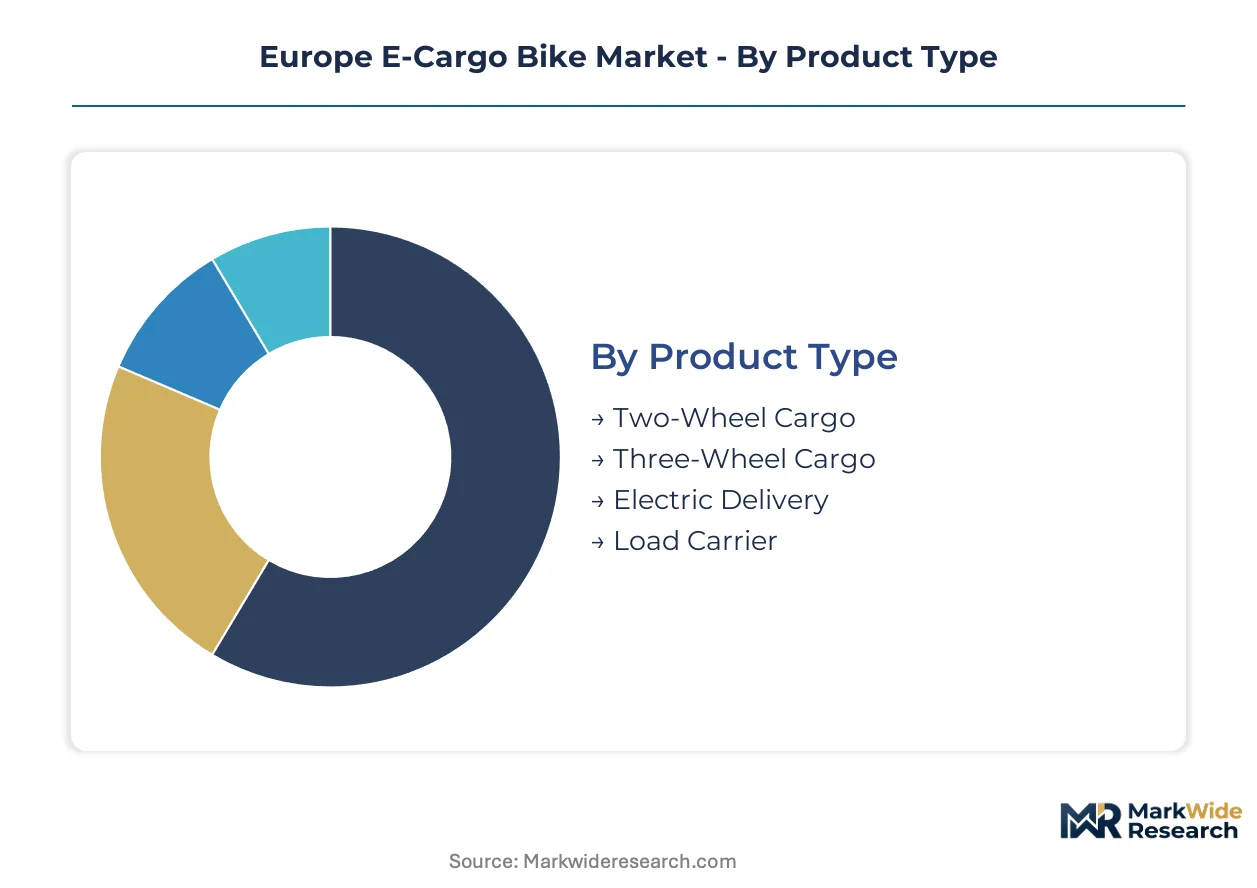
European e-cargo bike procurement diverges sharply between premium logistics networks seeking specialized engineering and price-optimized municipal tenders accepting heavier battery chemistries. Understanding these segment boundaries reveals where margin concentrates versus where volume flows.
Product Type:
Domestic Dutch and German manufacturers dominate three-wheel and front-loading architectures, while two-wheel variants face import competition from broader European assembly operations.
- Two-Wheel Cargo:Mid-drive motor systems rated 250 W to 500 W power compact urban delivery frames optimized for narrow European cycle infrastructure. German food delivery platforms in Berlin and Hamburg prioritize these configurations for maneuverability in dense historic centers where three-wheel turning radii prove restrictive.
- Three-Wheel Cargo:Reinforced chromoly frames with dual-front-wheel stability architectures handle 400 kg to 600 kg payloads across Dutch municipal procurement channels. Amsterdam and Rotterdam fleet operators specify these variants for their superior balance under uneven load distribution during last-mile parcel handoffs.
- Electric Delivery:Enclosed cargo compartments with weatherproofing specifications serve pharmaceutical and grocery logistics networks requiring temperature-protected transport across variable Central European climates.
- Load Carrier:Modular flatbed configurations accommodate custom container attachments for construction material and bulky retail freight moving through Belgian and French urban logistics corridors.
Three-wheel cargo commands the established base. The steepest expansion runs through electric delivery configurations.
End User:
Procurement authority concentrates with logistics providers holding multi-year fleet contracts, while municipalities fragment across national subsidy regimes.
- Retailers:Large-format grocery and home goods chains in France and Germany deploy captive e-cargo fleets to circumvent diesel restriction zones in Paris, Lyon, Munich, and Frankfurt city centers.
- Logistics Providers:National parcel carriers and regional courier networks across the Netherlands and Germany standardize on three-wheel platforms with 500 kg ratings for high-frequency stop-and-go delivery routes.
- Food Delivery Services:Platform operators in Amsterdam, Berlin, and Barcelona represent the segment gaining share fastest as regulatory shelter from municipal diesel bans becomes a competitive operational requirement.
- Municipalities:Urban procurement offices in Dutch provinces and German federal states specify price-optimized lead-acid configurations for internal maintenance and postal services.
Logistics providers anchor current fleet deployment. Food delivery services are climbing the fastest.
Battery Type:
REACH compliance and ECHA chemical safety protocols are compressing procurement options for non-European cell manufacturers.
- Li-ion:Nickel-manganese-cobalt and lithium-iron-phosphate chemistries dominate German and Dutch commercial fleet specifications. European cell assembly localization satisfies municipal tender requirements for supply chain traceability under EU Green Deal carbon intensity standards.
- Lead-acid:Heavier 48 V systems persist in Southern European municipal tenders where upfront capital constraints override total cost of ownership calculations.
- NiMH:Intermediate energy density chemistry occupies niche applications in temperature-extreme Nordic municipal operations.
- Others:Emerging solid-state prototypes and sodium-ion alternatives remain pre-commercial for cargo-rated payload applications.
Li-ion commands the established base. The steepest expansion runs through advanced lithium-iron-phosphate variants.
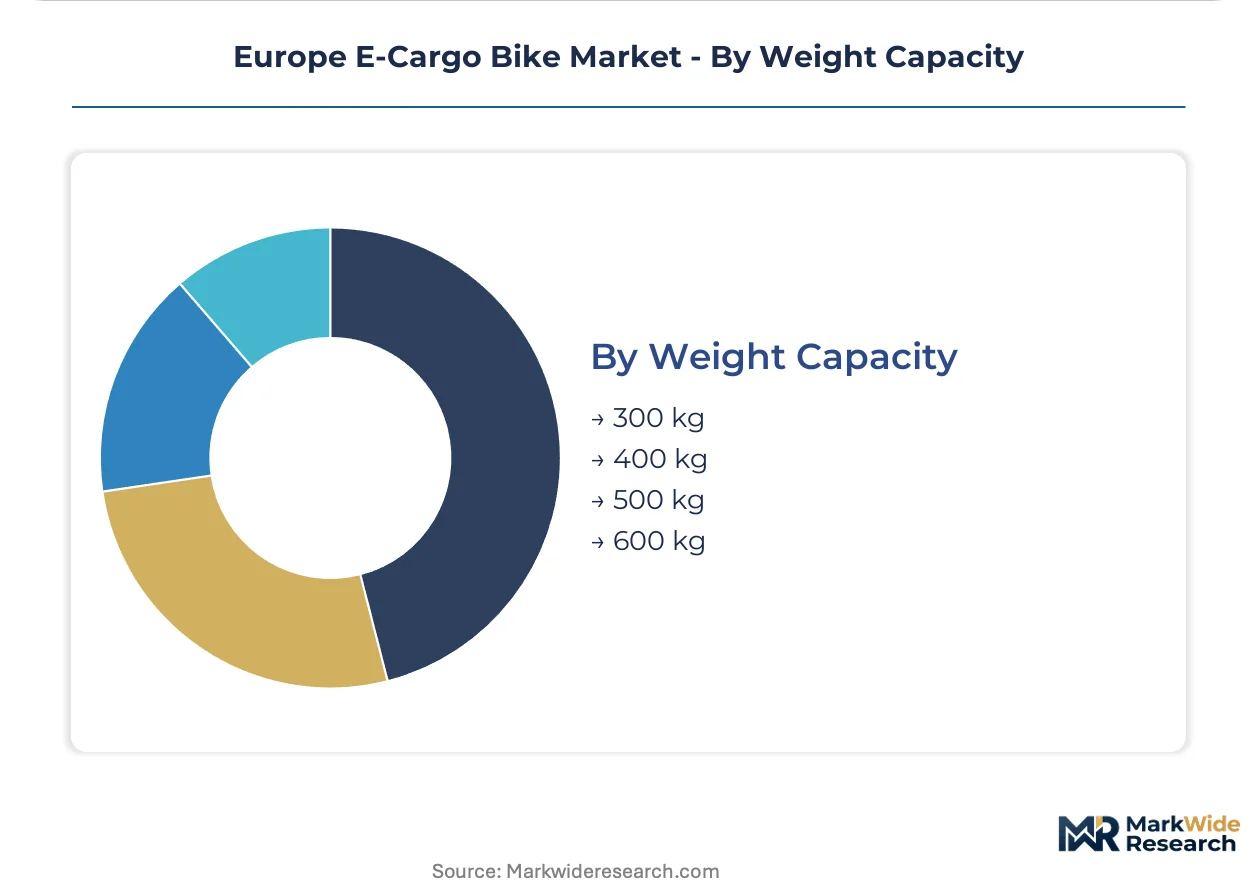
Weight Capacity:
German KBA type-approval standards for motors above 250 W favor heavier-rated frames, while French certification divergence complicates cross-border fleet standardization.
- 300 kg:Entry-level two-wheel configurations serve individual courier operators and small-format retail delivery in Belgian and Dutch urban cores.
- 400 kg:Mid-tier three-wheel platforms balance stability with infrastructure compatibility across German federal state procurement programs.
- 500 kg:Reinforced frame architectures with dual-battery systems support national logistics carrier operations through Amsterdam-Rotterdam-The Hague corridor density.
- 600 kg:Maximum-rated commercial platforms with hydraulic braking and reinforced suspension handle bulky freight consolidation for construction and industrial supply chains in French and German metropolitan zones.
400 kg and 500 kg ratings command the established base. The steepest expansion runs through 600 kg heavy-duty configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dutch municipal procurement channels while German logistics networks absorb premium engineering premiums. Southern European tenders trade specification depth for capital accessibility. Regional divergence in subsidy regimes and certification standards fragments fleet standardization across national boundaries.
Germany
Federal e-mobility subsidies and KBA type-approval standards for motors above 250 W drive fleet procurement in Berlin and Hamburg. The EU Green Deal accelerates diesel van phase-out timelines. North Rhine-Westphalia logistics corridors standardize on three-wheel platforms for high-frequency parcel consolidation.
Netherlands
Municipal procurement programs in Amsterdam and Rotterdam specify front-loading cargo architectures for urban freight density. CE marking harmonization under the EU Machinery Directive streamlines cross-border fleet deployment. Randstad metropolitan clusters anchor European design leadership in low-center-of-gravity platforms.
France
National e-mobility incentive schemes open procurement channels for family-oriented utility models. Emerging French safety certifications diverge from German KBA standards, complicating cross-border fleet integration. Paris and Lyon retail logistics networks deploy captive e-cargo fleets to circumvent municipal diesel restriction zones.
Belgium
Benelux retail channel concentration supports two-wheel configurations for narrow urban cycle infrastructure. REACH compliance requirements constrain battery supply chain sourcing to EU-origin cell manufacturers. Brussels and Antwerp food delivery platforms expand leased vehicle-plus-service bundles.
United Kingdom
London congestion charging exemptions and low-emission zone expansion drive logistics operator fleet conversion. Post-Brexit regulatory divergence from EU homologation standards extends vehicle qualification timelines. Southeast England last-mile consolidation hubs pilot battery swapping infrastructure for platform operators.
Europe E-Cargo Bike Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered competitive structure. Premium engineering specialists concentrate in German and Dutch manufacturing clusters, while scale-oriented assemblers compete on procurement efficiency and distribution reach. Three strategic archetypes dominate: vertically integrated European manufacturers, Asian contract assemblers, and platform-integrated fleet service providers. Competitive moves center on strategic partnerships with logistics operators and geographic licensing of specialized frame architectures.
Among German engineering-led fabricators, Riese & Müller GmbH and Urban Arrow occupy positions at opposite ends of the cargo architecture spectrum, with the former exemplifying premium manufacturing depth and the latter anchoring Dutch design leadership in front-loading platforms. Babboe sits within the family-oriented utility tier, competing across Benelux retail channels on accessible price positioning. These three entities collectively represent the geographic and technical specialization vectors that define European competitive boundaries.
| Leading Market Players |
|---|
| Riese & Müller GmbH |
| Pon Holdings |
| Accell Group |
| Urban Arrow |
| Rad Power Bikes |
| Giant Manufacturing |
| Tern Bicycles |
| Babboe |
| Merida |
| Others |
Supply & Pricing Matrix
Li-ion battery substitution for lead-acid chemistries is redrawing procurement geography toward EU-origin cell assembly while compressing total cost of ownership calculations for Dutch and German fleet operators. This chemistry migration simultaneously elevates REACH-compliant European manufacturers and erodes price competitiveness of non-compliant Asian suppliers.
Pricing Analysis
The customization-premium spread separates German-engineered configured-to-order platforms from Benelux standard-catalog family models. Three-tier pricing structure across premium engineering, standard commercial, and economy municipal levels tracks certification grade and after-sales service bundling. Cost compression in economy tiers intensifies because Southern European tenders prioritize upfront capital over lifecycle economics. Municipal procurement offices exhibit highest price sensitivity; logistics providers with multi-year fleet contracts absorb premium engineering margins.
Supply Chain Analysis
Germany and the Netherlands anchor frame fabrication and final assembly for premium three-wheel architectures. East Asian smelters supply chromoly and 6061 aluminum inputs that European fabricators draw from under extended order-to-delivery cycles. Single-source vulnerability concentrates in battery cell manufacturing where REACH compliance constrains non-European qualification. Distribution runs through captive fleet service providers in Amsterdam and Berlin alongside Benelux retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around KBA type-approval and CE marking constructs defensive moats for established European manufacturers, as compliance complexity elevates switching costs for fleet operators.
For Market Incumbents: Shield market position through backward integration into EU-origin battery pack assembly to satisfy ECHA traceability requirements. Deepen service capability investments around mid-drive motor diagnostics to exploit mechanic scarcity as a retention lever against Asian contract assemblers.
For New Entrants and Emerging Players: Anchor in French municipal subsidy expansion where emerging national safety certifications create temporary procurement shelter from German incumbents. Target family-oriented utility segments in Southern European price-sensitive tenders with lead-acid compatible platform architectures.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive battery supply and service networks. Long-term viability hinges on EU Green Deal enforcement durability. Watch battery swapping infrastructure pilot outcomes as inflection indicator for platform-operator business model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Harmonization | Streamlines cross-border fleet deployment for Dutch and German logistics networks under EU Machinery Directive. |
| Battery Supply Localization | EU-origin cell assembly satisfies REACH protocols and ECHA carbon intensity standards for municipal tenders. |
| Service Capability Expansion | Qualified mechanic networks reduce fleet downtime risk for mid-drive motor systems in commercial operations. |
| Front-Loading Architecture Licensing | Dutch design leadership transfers stability advantages to hilly Southern European topography applications. |
| Subscription Fleet Access | Vehicle-plus-service bundles transfer residual value risk while locking multi-year revenue visibility. |
Research Methodology
A standing panel of fleet procurement managers, cargo bike mechanics, municipal tender officers, and battery supply chain specialists provided ongoing calibration across primary interviews. Secondary validation drew from EU Machinery Directive documentation, ECHA REACH filings, KBA type-approval registers, and national e-mobility subsidy program disclosures. Bottom-up unit economics triangulated against top-down fleet deployment projections.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product architecture, payload rating, battery chemistry, and end-user procurement authority. CAGRs derived from logistic curve adoption patterns incorporating fleet replacement cycles and regulatory phase-out timelines. Forecast inputs encompassed diesel restriction zone expansion schedules and Li-ion cost curve trajectories.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable battery chemistry cost curves; material deviation would warrant model refresh. Recalibration cycles align with shifts in national subsidy regimes and REACH compliance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Malaysia Bicycle Market
Bikes and Motorcycles
Mountain Bike Suspension Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Cruiser Bikes Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Cargo Bike Market