
 Motorcycles Fuel Tank Market | 2026-2036
Motorcycles Fuel Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycles Fuel Tank Market Analysis
EU F-Gas Regulation is restructuring material compliance costs for European tank suppliers. JBM Group leverages integrated stamping and welding operations to sustain cost leadership across Indian OEM contracts. Lumax DK Jain Group anchors its position through dedicated two-wheeler fuel system specialization, while Goshi Giken Group competes on precision plastic blow-molding expertise serving Japanese motorcycle brands.
A motorcycle fuel tank is a sealed reservoir, typically fabricated from stamped steel, aluminum, or rotationally molded polyethylene, designed to store gasoline or alternative fuels while withstanding vibration, impact, and thermal cycling; it integrates venting systems, fuel pumps, and emission control interfaces to meet evaporative emissions standards. Steel tanks still dominate OEM supply chains for their crashworthiness and barrier properties, though plastic variants are gaining share in commuter segments where weight reduction drives fuel efficiency gains. Aftermarket installations occupy a fragmented margin pool shaped by customization trends and crash replacement cycles across aging vehicle parcs.
EPA evaporative emissions standards in the United States, EU F-Gas Regulation, and India's BIS automotive plastic certification collectively dictate material selection, permeation limits, and testing protocols that determine market access. Compliance complexity favors suppliers with in-house testing and multi-material process capabilities over pure-play metal stampers. Stakeholders must monitor regulatory divergence between major motorcycle-producing jurisdictions to anticipate retooling requirements and qualification timelines.
Market Dynamics
Adventure touring motorcycles are pulling demand for larger-capacity tanks across Southeast Asia, while India's BIS certification for automotive plastics tightens material standards and restructures supplier qualification timelines.
Growth Catalysts
- EU F-Gas Regulation:The regulation is restructuring material compliance costs for European tank suppliers, forcing investment in low-permeation barrier technologies and vapor recovery systems.
- Adventure touring segment:Long-distance riding motorcycles are driving demand for 20+ liter fuel tanks across Indonesia, Thailand, and Vietnam, expanding the addressable market for premium tank fabricators.
- Rotation molding:High-density polyethylene processing is gaining share in commuter segments where weight reduction directly improves fuel efficiency metrics.
Market Restraints
- Steel price volatility:Cold-rolled steel coil input costs create margin compression for stamped metal tank producers serving price-sensitive OEM contracts.
- Vietnam-Indonesia-Thailand concentration:Regional production clustering creates exposure to single-source supply disruptions and logistics bottlenecks during monsoon seasons.
- Permeation limits:EPA evaporative emissions standards impose technical barriers that plastic tank variants struggle to meet without multi-layer coextrusion, raising unit economics.
Strategic Opportunities
- India BIS certification gap:Domestic suppliers with in-house testing laboratories can capture share from importers facing extended qualification timelines under tightened automotive plastic standards.
- Alternative fuel compatibility:Ethanol-blend and flex-fuel motorcycle programs create demand for corrosion-resistant tank linings and modified venting architectures.
- Aftermarket customization:Direct-to-rider e-commerce channels are displacing traditional distributor networks for crash replacement and aesthetic upgrade volumes.
Industry Challenges
- Multi-material welding certification:Suppliers lack technicians qualified for aluminum-steel hybrid tank fabrication, constraining product portfolio expansion.
- Retooling capex cycles:Transitioning from metal stamping to plastic blow-molding requires 18-24 month payback periods that strain mid-tier fabricator balance sheets.
- Cross-jurisdiction testing duplication:Separate EPA, EU F-Gas, and BIS qualification protocols force redundant permeation and crash testing, extending time-to-revenue for new designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycles Fuel Tank Market |
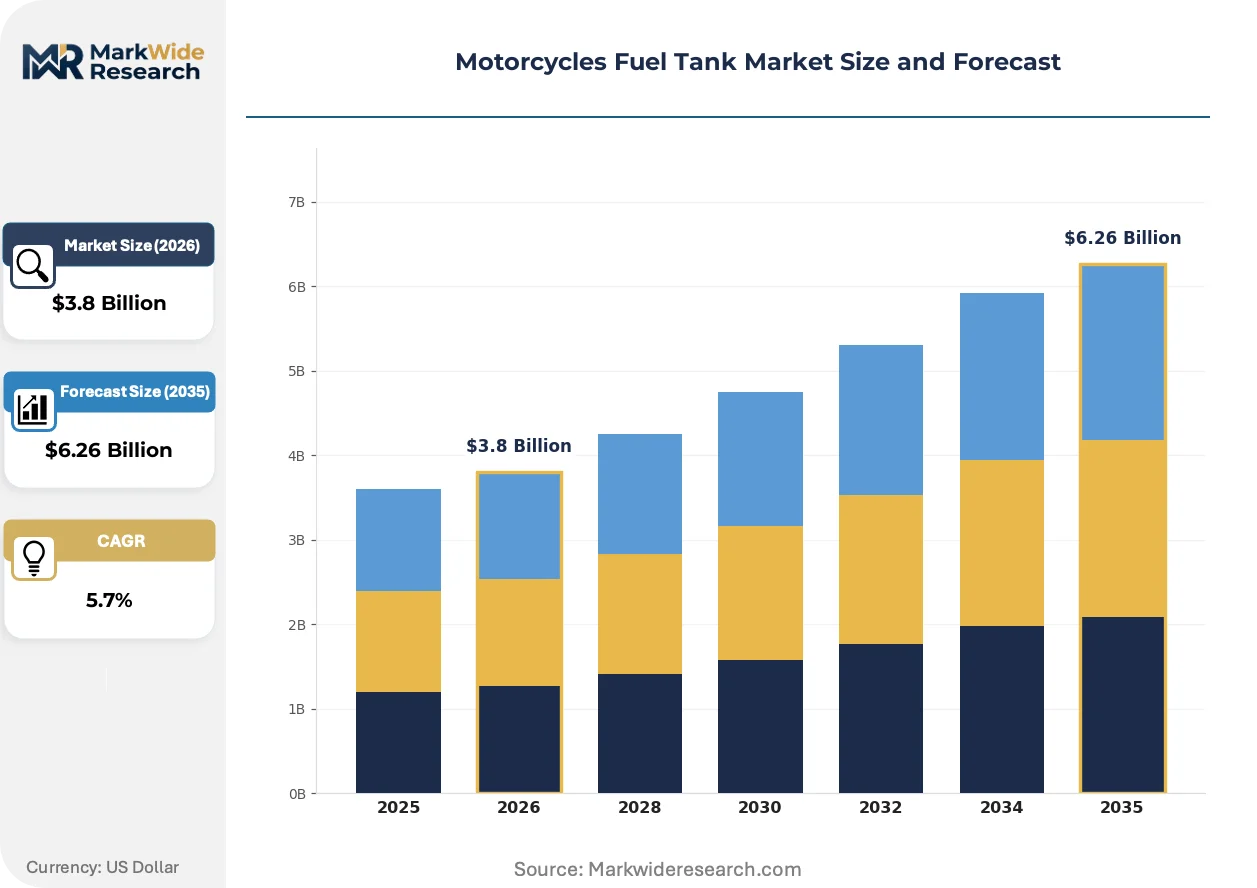
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Plastic, Composite Capacity: 5 Liters, 10 Liters, 15 Liters, 20 Liters Installation: OEM, Aftermarket, Custom, Replacement End User: Motorcyclists, Manufacturers, Custom Builders, Enthusiasts |
| Companies Covered | JBM Group, Lumax DK Jain Group, Goshi Giken Group, AG Industries, Wuxi Zhengda Enterprise, Linde-Wiemann GmbH, Magna International, Allied Industries, Metalcraft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycles Fuel Tank Market Emerging Trajectories
Material science advances and regulatory stringency are converging to reshape fabrication methods, with barrier-layer engineering and connected venting systems emerging as critical differentiators.
Multi-layer coextruded polyethylene is expanding into premium commuter segments previously dominated by stamped steel. Indian and Southeast Asian OEMs are specifying these tanks for 125-150cc models where weight targets now override legacy crashworthiness preferences. The technology is expanding into supplier portfolios as a hedge against steel price volatility and BIS plastic certification compliance costs.
EPA evaporative emissions standards are tightening permeation limits for unsealed fuel systems, forcing tank-integrated carbon canister architectures. US-market motorcycles now require sealed fuel caps, rollover valves, and pressure-vacuum relief systems that add component complexity. Small-displacement importers face the steepest compliance burden, with some exiting the market rather than absorbing redesign costs.
Buyer concentration at Southeast Asian OEMs is compressing supplier negotiation cycles and unbundling after-sales service contracts. Tier-one fabricators now face direct sourcing pressure from Vietnam's VMEP and Thailand's AAT assembly hubs, bypassing traditional trading company intermediaries. Indonesia's GAIKINDO member manufacturers are driving this shift most aggressively, consolidating vendor panels to capture procurement scale efficiencies.
Motorcycles Fuel Tank Market Segmentation
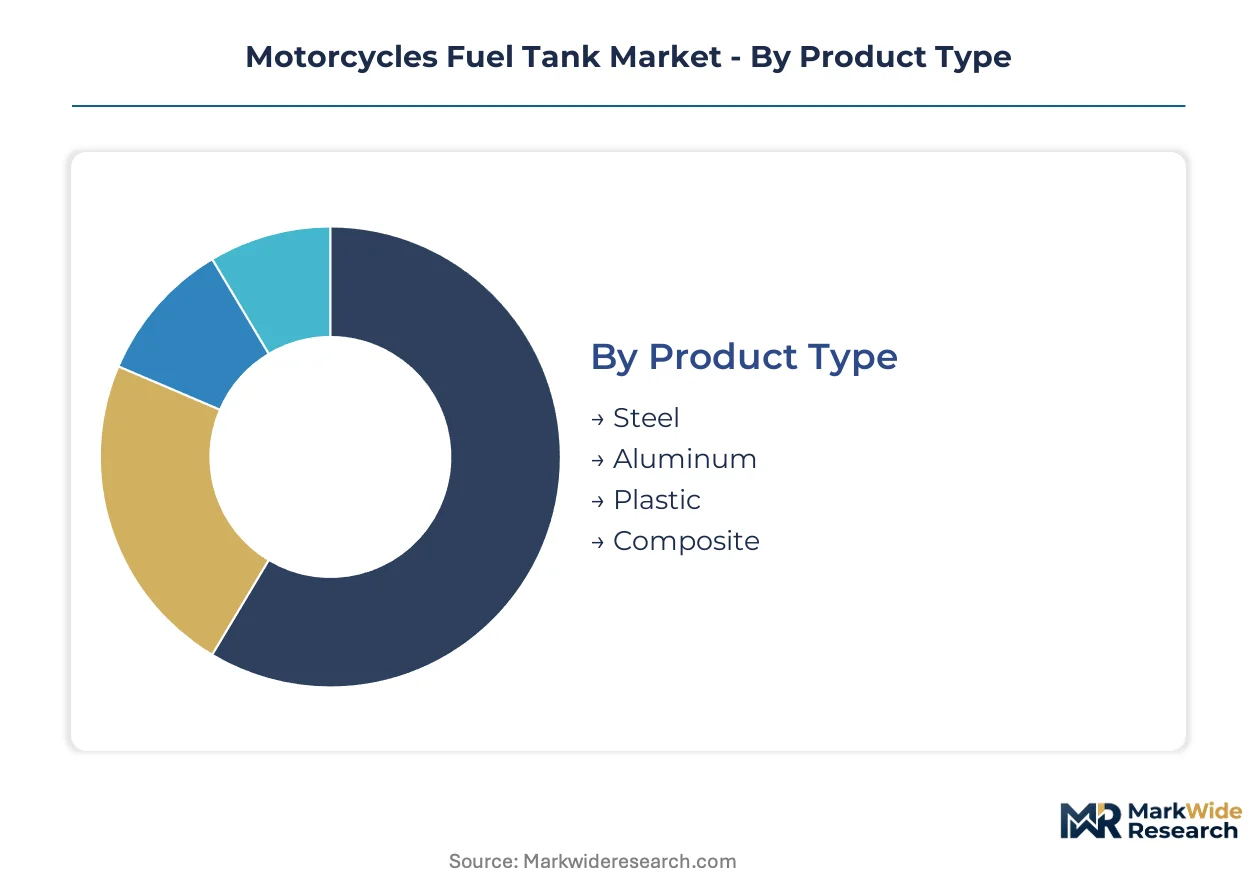
Motorcycle fuel tank segmentation reveals divergent certification burdens across materials and installation channels. Suppliers face distinct EPA, EU F-Gas, and BIS testing protocols depending on product type and target market access.
Product Type:
Steel and aluminum variants trigger crashworthiness and permeation testing under EPA and EU F-Gas frameworks, while plastic and composite tanks face heightened BIS scrutiny in India and multi-layer coextrusion requirements for US evaporative emissions compliance.
- Steel:Cold-rolled stamped construction dominates OEM supply chains for adventure touring and premium commuter segments. Crashworthiness certification under EPA standards sustains its position across Vietnamese and Thai assembly hubs despite weight penalties.
- Plastic:High-density polyethylene and multi-layer coextruded variants are gaining share in 125-150cc commuter models where BIS automotive plastic certification and weight reduction targets converge. Indonesian OEMs specify these tanks aggressively for fuel efficiency gains.
- Aluminum:Welded alloy construction serves racing and premium off-road applications requiring corrosion resistance and moderate weight savings.
- Composite:Fiber-reinforced polymer systems remain niche, constrained by permeation limits and repair complexity for mainstream motorcycle platforms.
Leading the category by volume: Steel. Growing fastest: Plastic.
Capacity:
Capacity selection directly correlates with motorcycle segment positioning and regional riding patterns across Southeast Asian markets.
- 20 Liters:Extended-range tanks anchor adventure touring motorcycles targeting Indonesia's trans-Java routes and Thailand's northern highway corridors. VMEP and AAT assembly hubs specify these for export-oriented premium models.
- 15 Liters:Mid-range capacity dominates 150-250cc commuter and light touring motorcycles across Vietnamese urban and intercity applications.
- 10 Liters:Compact tanks serve 110-125cc urban commuters where parking density and maneuverability override range requirements.
- 5 Liters:Minimalist capacity persists in electric conversion platforms and vintage restoration projects with limited commercial scale.
Dominant by production volume: 15 Liters. Expanding most quickly: 20 Liters.
Installation:
Installation channel determines margin structure and regulatory exposure, with OEM contracts demanding full certification portfolios while aftermarket channels navigate fragmented compliance territories.
- OEM:Factory-installed tanks require complete EPA, EU F-Gas, and BIS qualification, locking suppliers into long-term contracts with GAIKINDO member manufacturers and Indian two-wheeler producers.
- Aftermarket:Crash replacement and upgrade volumes flow through direct-to-rider e-commerce channels, bypassing traditional distributor networks across aging vehicle parcs.
- Custom:Fabrication for bespoke motorcycles and show bikes operates outside standard certification pathways, serving enthusiast segments with aesthetic and performance modifications.
- Replacement:Insurance-driven demand cycles align with regional accident rates and fleet age distributions, concentrated in high-density urban corridors.
Highest revenue concentration: OEM. Fastest channel shift: Aftermarket.
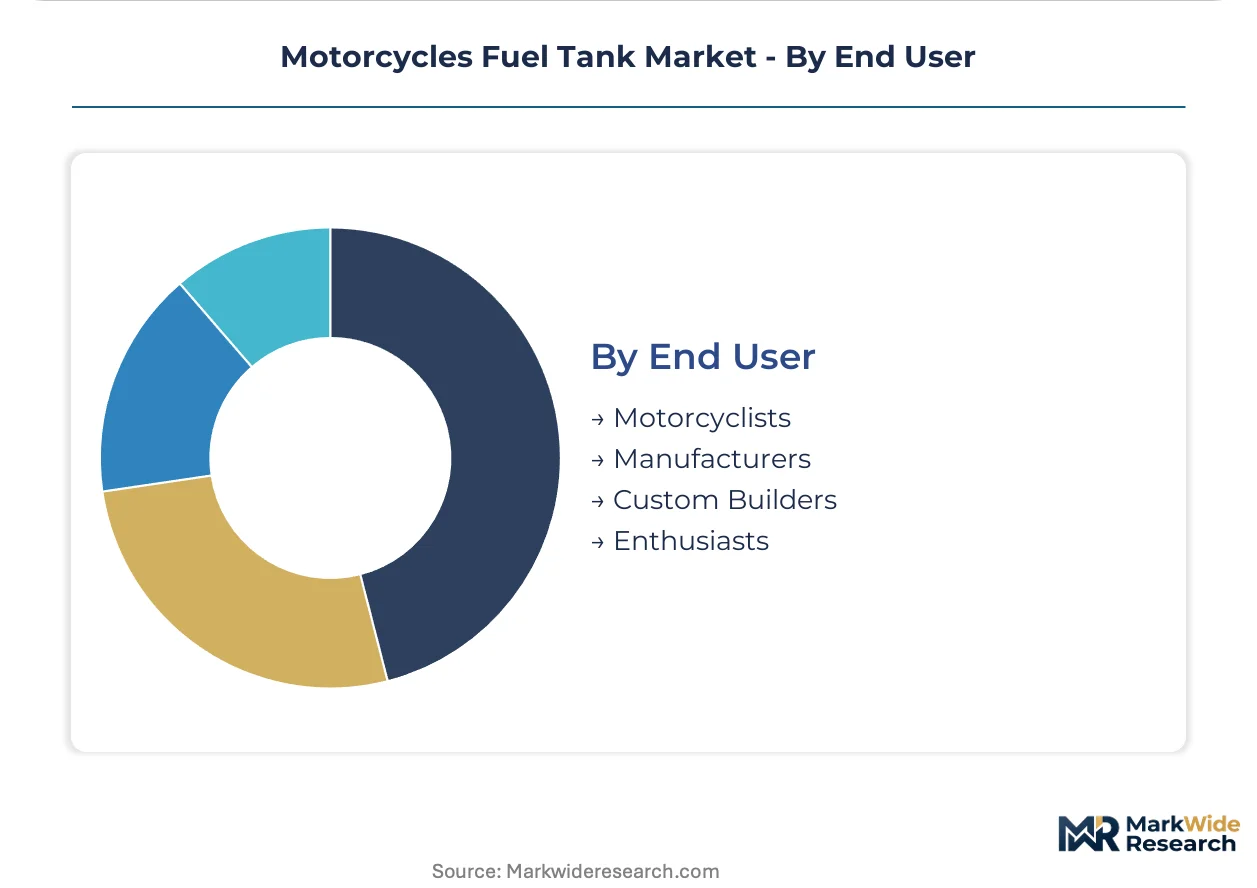
End User:
End user segmentation maps to distinct procurement behaviors and technical specification authority across the value chain.
- Manufacturers:OEM sourcing teams at Vietnam's VMEP, Thailand's AAT, and Indian integrated producers drive volume contracts with stringent qualification timelines and price-down schedules.
- Motorcyclists:Daily commuter riders prioritize fuel efficiency and durability in 125-150cc segments, accepting plastic tank trade-offs for weight reduction.
- Custom Builders:Specialist fabricators demand aluminum and composite materials for aesthetic differentiation and performance positioning in premium niche markets.
- Enthusiasts:Collector and touring communities sustain aftermarket demand for larger-capacity steel tanks and vintage-appropriate restoration components.
Controlling procurement volume: Manufacturers. Driving specification change: Motorcyclists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam, Indonesia, and Thailand concentrate motorcycle fuel tank production through tax incentives and duty-free component import regimes. These three countries now anchor Southeast Asian supply chains for both domestic assembly and export-oriented manufacturing.
Vietnam
VMEP assembly hubs in Vinh Phuc and Hanoi provinces drive demand for stamped steel tanks in 150-250cc commuter motorcycles. The Ministry of Industry and Trade enforces localization content rules that favor domestic metal fabricators over importers. Ha Noi-based suppliers now capture tier-one contracts previously held by Thai trading intermediaries.
Indonesia
GAIKINDO member manufacturers specify multi-layer plastic tanks aggressively for 125-150cc fuel efficiency programs. The Ministry of Industry's B20 biodiesel mandate requires corrosion-resistant tank linings compatible with higher ethanol blends. Surabaya and Bekasi industrial corridors concentrate blow-molding capacity serving both domestic and ASEAN export markets.
Thailand
AAT assembly facilities in Rayong and Chonburi provinces specify 20-liter adventure touring tanks for export-oriented premium models. The Board of Investment grants eight-year tax holidays for automotive component producers meeting advanced manufacturing criteria. Eastern Economic Corridor infrastructure investments reduce logistics costs for steel coil and polymer resin inputs.
India
BIS automotive plastic certification tightens qualification timelines for fuel tank importers while favoring domestic suppliers with in-house testing laboratories. The PLI scheme for auto components incentivizes capacity expansion in Gujarat and Tamil Nadu manufacturing clusters. Pune and Chennai now concentrate integrated stamping and welding operations serving Hero MotoCorp and Bajaj Auto contracts.
Japan
METI fuel efficiency standards push OEMs toward aluminum and composite tanks in 400cc+ premium segments. Domestic fabricators maintain precision welding expertise for racing and limited-production motorcycles. Hamamatsu and Osaka industrial zones sustain specialized supply chains for domestic brands and technology licensing to Southeast Asian joint ventures.
Motorcycles Fuel Tank Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct tier positions. The market structure separates into three layers: integrated automotive suppliers with multi-product portfolios, dedicated two-wheeler component fabricators, and regional metalworking specialists serving single geography contracts. Tier-one positions require simultaneous EPA, EU F-Gas, and BIS qualification capabilities that filter out mid-tier stampers. Competitive moves concentrate on backward integration into steel coil processing and captive supply of polymer resin compounds.
Among India-based fabricators, JBM Group and Lumax DK Jain Group exemplify the dedicated two-wheeler specialist archetype through concentrated fuel system expertise. Goshi Giken Group occupies a position within precision plastic processing for Japanese motorcycle brand supply chains. These three anchors demonstrate how geographic clustering and certification depth determine contract access across OEM vendor panels.
| Leading Market Players |
|---|
| JBM Group |
| Lumax DK Jain Group |
| Goshi Giken Group |
| AG Industries |
| Wuxi Zhengda Enterprise |
| Linde-Wiemann GmbH |
| Magna International |
| Allied Industries |
| Metalcraft |
| Others |
Supply Flow & Price Mechanics
VMEP and AAT assembly hubs in Vietnam and Thailand concentrate procurement volume for stamped steel and multi-layer plastic tanks, locking suppliers into contract-based long-term offtake agreements with annual price-down schedules. This buyer concentration forces tier-one fabricators to absorb cold-rolled steel coil volatility through hedging programs while passing polymer resin cost swings through index-linked clauses.
Pricing Analysis
Short lead-time premiums of 15-25% apply to crash replacement orders from direct-to-rider e-commerce channels, while spot inventory of standard 15-liter steel tanks trades at discounts to contract OEM pricing. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified multi-layer plastic from BIS-qualified domestic steel and uncertified gray-market imports. Cost compression in stamped metal segments is intensifying because Indian OEMs are unbundling after-sales service contracts. Price sensitivity peaks among 125-150cc commuter OEMs in Indonesia, while adventure touring manufacturers in Thailand accept premium positioning for 20-liter capacity tanks.
Supply Chain Analysis
Freight costs from Surabaya and Bekasi industrial corridors to VMEP assembly hubs in northern Vietnam run 12-18% above intra-Thailand movements, favoring Thai-based blow-molding capacity for Indonesian OEM contracts. Supply concentrates in Vietnam, Indonesia, and Thailand, with raw material dependencies on cold-rolled steel coil from Japanese mills, high-density polyethylene resin from Singaporean petrochemical complexes, and aluminum alloy from Chinese smelters. Single-source vulnerability permeates the steel coil tier, where Fukuyama and Kashima mill allocations determine Southeast Asian stamping capacity. Distribution runs through GAIKINDO-member manufacturer vendor panels, bypassing traditional trading company intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-material welding certification scarcity constrains supplier expansion, propping pricing power for qualified fabricators able to deliver aluminum-steel hybrid tanks. Capacity bottlenecks at in-house testing laboratories under India's tightened BIS standards extend qualification timelines and protect incumbent margins.
For Market Incumbents: Deepen backward integration into steel coil slitting and polymer resin compounding to defend against margin compression from Indonesian OEM price-down schedules. Capture tier-one contracts at Thailand's AAT facilities by investing in 20-liter tank welding automation before mid-tier stampers achieve aluminum certification. Lock in long-term resin supply agreements with Singaporean petrochemical producers to hedge against freight cost volatility across the Java Sea corridor. For New Entrants and Emerging Players: Aftermarket custom builders seeking corrosion-resistant linings for Indonesia's B20 biodiesel mandate represent the most penetrable buyer archetype outside OEM vendor panels. Target direct-to-rider e-commerce channels for 125-150cc plastic tank crash replacements, where BIS certification gaps delay Indian import competition. Pursue white-label supply partnerships with Vietnamese trading intermediaries disintermediated from VMEP contracts. For Investors and Strategic Acquirers: The window for entry favors mid-tier stampers with dormant aluminum welding capacity and existing EPA qualification portfolios. Long-term viability hinges on consolidation plays that aggregate BIS testing capabilities across Gujarat and Tamil Nadu manufacturing clusters. Watch for Indonesian Ministry of Industry biodiesel blend increases as the signal triggering accelerated corrosion-resistant lining retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Processing | JBM Group's captive slitting operations insulate margins from Nippon Steel spot price volatility. |
| Multi-Material Welding Certification Investment | Aluminum-steel hybrid tank capability unlocks AAT adventure touring contracts above 15-liter threshold. |
| In-House BIS Testing Laboratory Buildout | Domestic Indian suppliers compress qualification timelines against importers facing extended scrutiny. |
| Direct-to-Rider E-Commerce Channel Launch | Aftermarket customization demand bypasses traditional distributor networks across aging ASEAN vehicle parcs. |
| Corrosion-Resistant Lining Technology Licensing | B20 biodiesel compatibility creates pull-through from GAIKINDO member manufacturers seeking ethanol-blend tank solutions. |
Methodological Framework
Trade publications, customs databases, and OEM procurement disclosures formed the secondary backbone, cross-referenced against primary interviews with tier-one supplier procurement managers, BIS certification laboratory directors, and GAIKINDO member manufacturer platform engineers. Bottom-up tank production estimates from Vietnam's VMEP and Thailand's AAT facilities were triangulated against top-down motorcycle assembly forecasts across the analysis window.
Historical trendline analysis of steel coil input costs and polymer resin pricing informed margin compression modeling across stamped metal and blow-molded plastic segments. Segmentation dimensions included material type, capacity tier, installation channel, and regional regulatory cluster. CAGRs were derived from production volume trajectories at Indonesian, Vietnamese, and Thai assembly hubs, incorporating EPA evaporative emissions compliance costs and EU F-Gas barrier technology investments as forecast inputs.
Revisions become necessary when BIS automotive plastic certification timelines extend beyond current qualification windows or when Indonesian biodiesel blend mandates accelerate beyond tank lining retrofit capacity. Forecasts reflect assumptions about regional production concentration and regulatory harmonization that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Flying Bikes Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Accessories Market