
 Italy E-Bike Market | 2026-2036
Italy E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Italy E-Bike Market Foresight
Lithium iron phosphate is recalibrating battery economics across the Italy E-Bike Market by displacing conventional cobalt-dependent cells with safer, longer-cycle alternatives. Atala SpA leverages its domestic manufacturing footprint to control assembly costs and shorten lead times for Italian retailers. Fabbrica Italiana Velocipedi Edoardo Bianchi SpA anchors its positioning in premium urban mobility through heritage branding and dedicated city-bike R&D. Giant Manufacturing Co. Ltd. competes on scale by importing high-volume frames and localizing final motor-battery integration.
An e-bike integrates an electric motor, rechargeable battery pack, and pedal-assist controller into a bicycle frame, delivering supplemental propulsion up to regulated speed thresholds with torque sensors modulating power output against rider input. City E-Bikes dominate unit volume as Italian municipalities restrict car access in historic centers, while Cargo E-Bikes capture expanding margin pools from last-mile delivery fleets replacing diesel vans. Lithium-Ion batteries lead the power segment due to energy density advantages, though Lithium Polymer variants are gaining traction in folding designs where form-factor flexibility matters most.
Italy's Ministry of Infrastructure and Transport administers Ecobonus purchase incentives, while the European Union's Machinery Directive and CE marking requirements govern motor safety and electromagnetic compatibility standards for market access. The National Recovery and Resilience Plan channels infrastructure funds toward cycling lane expansion, directly conditioning where e-bike utility peaks. Stakeholders must monitor whether subsidy renewal timelines and evolving battery recycling mandates under EU battery regulations reshape total cost-of-ownership calculations for fleet buyers and individual consumers alike.
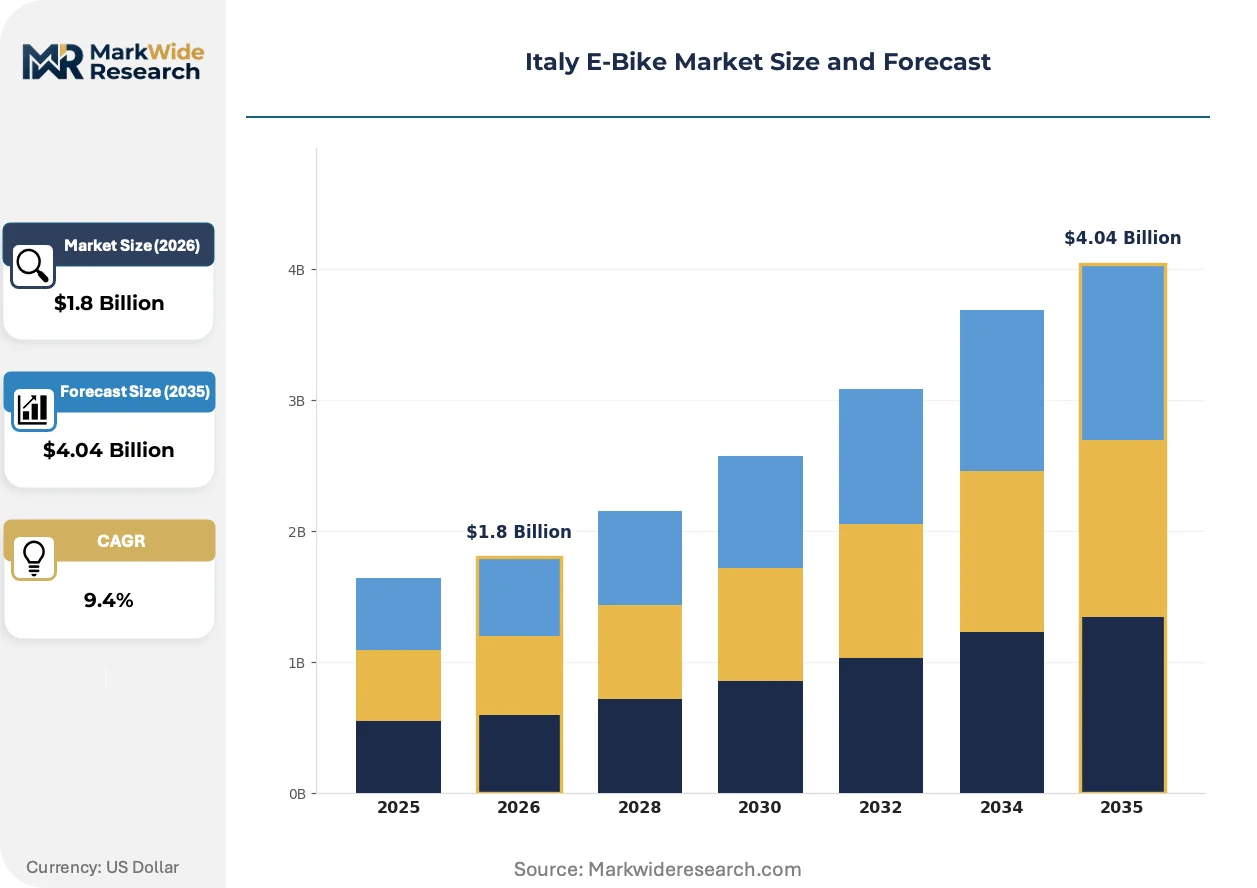
Market Dynamics
Italy's Ecobonus purchase incentive scheme is compressing household adoption timelines while lithium iron phosphate battery chemistry is displacing cobalt-dependent cells across domestic assembly lines. Municipal cycling infrastructure investments in northern industrial cities are conditioning where pedal-assisted mobility delivers maximum utility.
Growth Catalysts
- Ecobonus Incentive Framework:Italy's Ministry of Infrastructure and Transport subsidizes e-bike purchases up to defined thresholds, directly lowering consumer acquisition costs and accelerating replacement of conventional bicycles.
- Lithium Iron Phosphate Chemistry:Safer, longer-cycle battery alternatives are displacing conventional cobalt-dependent cells in domestic assembly, reducing thermal runaway risk and extending warranty periods for fleet operators.
- Milan and Rome Commuter Migration:Urban professionals in Italy's two largest metropolitan areas are shifting from public transit to pedal-assisted mobility as historic center car restrictions expand.
Market Restraints
- Lithium Price Volatility:Raw material input costs for battery cathodes fluctuate with global mining output, compressing assembler margins when contract pricing lags spot market movements.
- East Asian Motor Concentration:Hub motor and mid-drive system supply concentrates among Taiwanese and Chinese manufacturers, creating lead time vulnerability for Italian frame builders without captive motor production.
- CE Marking Compliance Friction:European Union Machinery Directive electromagnetic compatibility testing adds certification duration and third-party laboratory expense before market access.
Strategic Opportunities
- Southern Italy Underpenetration:Cycling lane density in Campania, Sicily, and Calabria lags northern regions, creating first-mover positioning for retailers establishing service networks ahead of infrastructure catch-up.
- Last-Mile Cargo Fleet Electrification:Diesel van replacement mandates in Italian urban delivery zones are opening margin pools for heavy-duty cargo e-bike configurations with extended range batteries.
- EU Battery Regulation Recycling Mandates:Extended producer responsibility frameworks for end-of-life battery collection are incentivizing domestic remanufacturing capabilities that reduce raw material import dependency.
Industry Challenges
- Battery Diagnostics Skill Shortage:Italian bicycle mechanics require retraining in lithium-ion cell balancing, battery management system firmware updates, and thermal management troubleshooting.
- Integration Complexity with Legacy Transit:Municipal bike-sharing operators face system architecture friction when retrofitting pedal-assisted units into existing dock-based infrastructure designed for mechanical bicycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy E-Bike Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Commuters, Tourists, Delivery Services, Recreational Users |
| Companies Covered | Atala SpA, Fabbrica Italiana Velocipedi Edoardo Bianchi SpA, Giant Manufacturing Co. Ltd., Merida Industry Co. Ltd., Trek Bicycle Corporation, Bottecchia Cicli Srl, Fantic Motor SpA, Askoll EVA SpA, Wayel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy E-Bike Market Shifts & Advancements
Smart torque-sensor calibration and connected fleet management platforms are reshaping how Italian operators extract value from pedal-assisted assets. Three developments merit particular attention.
Lithium iron phosphate chemistry is consolidating battery supply strategies across Italian assemblers. The technology delivers superior thermal stability and cycle life compared to nickel-manganese-cobalt alternatives. Fleet operators in Milan and Turin are specifying LFP configurations for high-utilization delivery applications. This chemistry shift is compressing total cost-of-ownership calculations for commercial buyers who amortize acquisition premiums over extended service intervals.
Italy's National Recovery and Resilience Plan channels infrastructure investment toward metropolitan cycling lane expansion. The framework conditions where e-bike utility peaks by connecting residential zones to commercial centers. Municipalities accessing these funds must meet design standards for lane separation and intersection signaling. Northern industrial cities with established procurement offices are capturing disproportionate allocation, widening the infrastructure gap with southern regions.
Subscription-based mobility service contracts are displacing outright purchase models among Milan corporate commuters. Employers bundle e-bike access with maintenance and insurance into monthly payroll deductions. This procurement evolution is restructuring retailer revenue toward recurring service relationships. The shift is most visible in Lombardy, where dense employer networks enable pooled fleet utilization across multiple worksites.
Italy E-Bike Market Segmentation
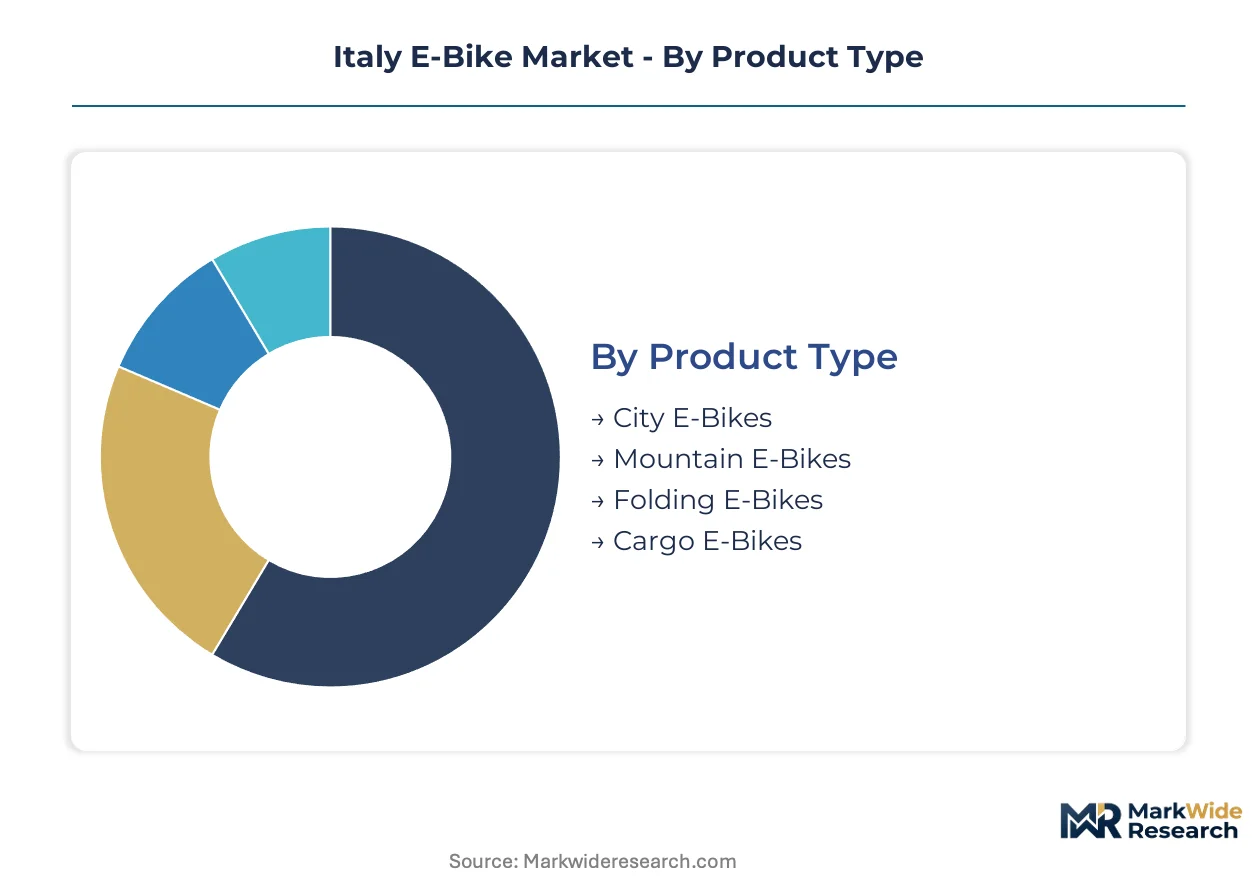
Segmentation reveals how Italian e-bike demand fragments across mobility use cases, powertrain configurations, and procurement channels. Each dimension carries distinct margin profiles and infrastructure dependencies that condition where manufacturers and retailers extract value.
Product Type:
Assembly capacity concentrates around frame architectures optimized for distinct terrain and payload requirements, with northern Italian manufacturers dominating urban-focused production.
- City E-Bikes:Step-through frames with integrated lighting and rack systems dominate Milan and Rome commuter procurement. Municipal car restrictions in historic centers concentrate replacement demand here, while Ecobonus subsidies compress payback periods for daily riders.
- Cargo E-Bikes:Extended wheelbase configurations with dual-battery options capture last-mile delivery fleet contracts in Turin and Bologna. Diesel van replacement mandates in urban low-emission zones accelerate commercial adoption despite premium pricing.
- Mountain E-Bikes:Full-suspension frames with high-torque mid-drive motors serve recreational demand in Alpine provinces.
- Folding E-Bikes:Compact hinge-frame designs with reduced battery capacity address multimodal commuters combining cycling with regional rail.
City E-Bikes absorb the bulk of installed capacity; Cargo E-Bikes is expanding most quickly.
Battery Type:
Cost tier stratification across cathode chemistries determines which cell technologies penetrate consumer versus fleet segments, with thermal stability and cycle life driving specification divergence.
- Lithium-Ion:Nickel-manganese-cobalt cylindrical cells deliver highest energy density for range-critical applications. Premium urban models specify these configurations where weight reduction justifies cathode cost premiums.
- Lithium Iron Phosphate:Prismatic LFP cells displace cobalt-dependent alternatives in commercial fleet procurement across Lombardy. Extended cycle life and reduced thermal runaway risk align with high-utilization delivery operator requirements.
- Lithium Polymer:Pouch-cell configurations enable irregular form factors for folding frame integration.
- Nickel-Metal Hydride:Legacy chemistry persists in entry-level replacements of conventional bicycles.
- Lead-Acid:Sealed lead-acid batteries occupy minimal share in price-sensitive secondary markets.
Lithium-Ion retains dominant share in consumer channels; Lithium Iron Phosphate climbs the fastest in commercial procurement.
Distribution Channel:
Customer type and service intensity requirements fragment procurement routes, with high-touch retail maintaining grip where technical consultation and maintenance bundling matter.
- Specialty Stores:Independent bicycle dealers in Milan, Turin, and Verona control premium positioning through test-ride facilities and subscription maintenance contracts. Corporate fleet procurement flows through these channels where specification consulting adds value.
- Online Retail:Direct-to-consumer platforms capture price-sensitive commuter demand with standardized urban configurations. Logistics networks enable rapid delivery to northern industrial cities where cycling infrastructure investment has preceded adoption.
- Direct Sales:Manufacturer-owned showrooms anchor brand experience in metropolitan flagship locations.
- Supermarkets:Mass retail captures impulse purchases in entry-level folding and city segments.
Specialty Stores command highest margin attachment; Online Retail gains share fastest in standardized commuter specifications.
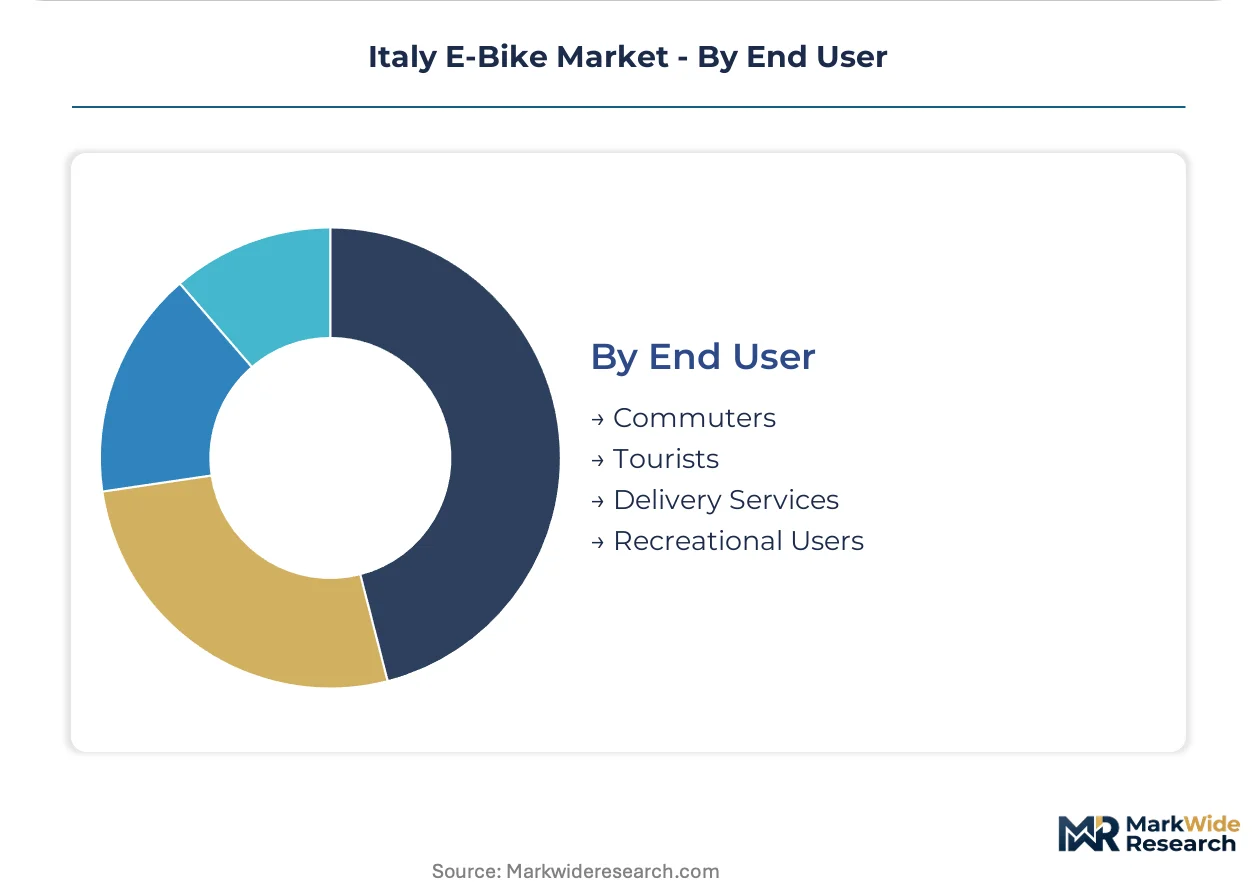
End User:
Application-driven usage patterns determine frame, motor, and battery configuration requirements, with commercial operators amortizing acquisition costs over higher utilization intensity than individual consumers.
- Commuters:Daily urban riders in Rome and Milan prioritize reliability and theft-deterrent features over performance specifications. Subscription service models from employers concentrate demand in Lombardy and Lazio metropolitan corridors.
- Delivery Services:Courier fleets in Bologna, Florence, and Genoa specify heavy-duty cargo configurations with swappable battery systems. Route optimization software integration and 24-hour service availability condition supplier selection.
- Tourists:Rental operators in Venice, Amalfi, and Tuscan wine regions deploy step-through city models with simplified controls.
- Recreational Users:Weekend riders in Alpine and Apennine regions demand full-suspension mountain configurations with extended range batteries.
Commuters represent the largest addressable base; Delivery Services shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's Ecobonus incentive zone concentrates Italian e-bike demand through subsidized fleet procurement and employer subscription programs. Northern industrial regions capture disproportionate infrastructure investment from Rome's National Recovery and Resilience Plan allocation.
Lombardy
Milan's corporate commuter migration drives subscription-based mobility contracts. The Ministry of Infrastructure and Transport administers Ecobonus purchase subsidies up to defined thresholds. Bergamo and Brescia assembly plants supply city e-bike configurations to metropolitan retailers.
Piedmont
Turin's last-mile delivery fleets replace diesel vans with heavy-duty cargo configurations. Municipal low-emission zone mandates accelerate commercial adoption despite premium acquisition costs. The Torino cycling corridor expansion connects peripheral residential zones to the central business district.
Veneto
Verona specialty retailers control premium positioning through test-ride facilities and maintenance bundling. The European Union Machinery Directive governs CE marking requirements for electromagnetic compatibility. Vicenza and Padua industrial clusters support component fabrication for domestic assemblers.
Emilia-Romagna
Bologna courier networks specify swappable battery systems for 24-hour route utilization. Regional cycling lane design standards align with National Recovery and Resilience Plan infrastructure criteria. Modena and Reggio Emilia frame builders source hub motors from Taiwanese suppliers.
Lazio
Rome's historic center car restrictions compress payback periods for daily commuter e-bike acquisition. The Ecobonus framework extends to metropolitan households replacing conventional bicycles. Fiumicino and Ostia coastal corridors attract recreational rental operators deploying step-through city models.
Italy E-Bike Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage Italian marques commanding premium positioning while East Asian fabricators compete on scale. The vendor base concentrates around three strategic archetypes: domestic heritage brands leveraging century-old cycling legacies, Taiwanese and Chinese volume manufacturers optimizing frame cost structures, and European mid-market specialists filling specification gaps. Competitive moves center on lithium iron phosphate battery chemistry transitions and subscription service model partnerships with corporate employers.
Within the domestic heritage tier, Atala SpA and Fabbrica Italiana Velocipedi Edoardo Bianchi SpA exemplify brand equity monetization through metropolitan flagship positioning. Among East Asian scale manufacturers, Giant Manufacturing Co. Ltd. occupies a position representing import-dependent assembly strategies. These three entities anchor the competitive spectrum from premium urban mobility to high-volume frame sourcing.
| Leading Market Players |
|---|
| Atala SpA |
| Fabbrica Italiana Velocipedi Edoardo Bianchi SpA |
| Giant Manufacturing Co. Ltd. |
| Merida Industry Co. Ltd. |
| Trek Bicycle Corporation |
| Bottecchia Cicli Srl |
| Fantic Motor SpA |
| Askoll EVA SpA |
| Wayel |
| Others |
Supply & Pricing Matrix
Lithium iron phosphate chemistry migration is compressing battery cost curves while concentrating cathode supply relationships among Chinese and South Korean cell producers serving Italian assemblers. This dual shift tightens margin structures for domestic frame builders who must absorb cell price volatility or pass through to fleet buyers.
Pricing Analysis
Volume concentrates in entry-level city configurations where Ecobonus subsidies mask price sensitivity, while margin pools concentrate in cargo and premium urban segments where service bundling commands attachment. Price differentiation stems from battery chemistry grade and after-sales maintenance contracts. Cost compression in the standard tier intensifies as East Asian frame imports undercut domestic assembly. Fleet operators in Milan and Turin exhibit lowest price sensitivity due to diesel van replacement mandates and total cost-of-ownership amortization.
Supply Chain Analysis
Hub motor supply rests on Taiwanese and Chinese manufacturers including Bafang and Shimano, with Italian frame builders lacking captive motor production. Lithium carbonate and refined cathode materials draw from Chinese chemical processors and Chilean-Argentinean brine operations. Single-source vulnerability concentrates in mid-drive system controllers and battery management system firmware. Distribution runs through specialty retail networks in northern industrial cities where technical consultation and maintenance bundling anchor channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where battery pack assembly and motor system sourcing represent the decisive upstream levers. Players who secure captive LFP cell relationships or backward-integrate into battery management system firmware will capture margin expansion.
For Market Incumbents: Lock in long-term LFP cell offtake agreements with Chinese and South Korean producers before capacity allocation tightens. Secure exclusive service network contracts in Lombardy and Piedmont to block emerging entrants from maintenance bundling. The threat of direct-to-consumer platforms undercutting specialty retail pricing makes channel control the priority defensive lever.
For New Entrants and Emerging Players: Enter via southern Italian regions where cycling infrastructure investment lags but Ecobonus eligibility extends. Campania and Sicily present white-space positioning ahead of National Recovery and Resilience Plan fund disbursement. Target cargo fleet procurement in secondary cities where incumbent service coverage remains thin, using 24-hour battery swap guarantees as the go-to-market wedge.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to East Asian volume manufacturers seeking European brand distribution. Long-term viability hinges on whether targets have secured battery chemistry transition capabilities and metropolitan retail footprint. Watch Ecobonus renewal timelines and EU Battery Regulation recycling mandate implementation as inflection signals for fleet buyer procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| LFP Battery Pack Integration | Captive cell sourcing from Chinese producers insulates Italian assemblers from cathode price volatility. |
| Corporate Subscription Partnership | Employer payroll deduction models in Lombardy restructure retailer revenue toward recurring service relationships. |
| Southern Retail Network Expansion | First-mover positioning in Campania and Sicily ahead of infrastructure catch-up captures underserved demand. |
| Cargo Fleet Service Contracting | 24-hour battery swap guarantees and route optimization software integration lock in Bologna and Florence delivery operators. |
| EU Battery Regulation Compliance Investment | Extended producer responsibility frameworks for end-of-life collection reduce raw material import dependency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Italy E-Bike Market analysis. Primary interviews with bicycle retailer owners, fleet procurement managers at delivery operators, and component sourcing leads at domestic assemblers combined with ANCMA industry statistics, Ministry of Infrastructure and Transport Ecobonus disbursement records, and EU Machinery Directive certification databases. Bottom-up unit shipment estimates triangulated against top-down value projections.
Segment-level modeling addressed product type, battery chemistry, distribution channel, and end-user application dimensions across the projection horizon. CAGRs derived from trend extrapolation of Ecobonus uptake curves, infrastructure investment schedules, and fleet electrification mandates. Industry-specific inputs included lithium carbonate spot price trajectories, cycling lane completion timelines, and employer subscription program adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium price spike scenarios or Ecobonus program suspension. Assumptions reflect current subsidy frameworks, battery chemistry transition timelines, and municipal low-emission zone enforcement intensity. Subsidy renewal delays, raw material export restrictions, and southern infrastructure funding shortfalls warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Electric Cargo Bikes Market
Bikes and Motorcycles
Used Bike Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market