
 Used Bike Market | 2026-2036
Used Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Used Bike Market Analysis
EPA emissions tier updates for motorcycles are recalibrating the cost-of-entry calculus for new internal-combustion inventory, pushing price-sensitive riders toward pre-owned alternatives. Buycycle leverages proprietary frame-scanning technology to certify structural integrity without physical inspection. Droom anchors its position through integrated financing and insurance products bundled at point of sale. eBay competes on geographic reach, sustaining liquidity across fragmented regional supply pools.
A used bike comprises a previously owned human-powered or motor-powered two-wheeled vehicle evaluated by frame material grade, drivetrain wear metrics, and service-history documentation, acquired for personal transportation or recreational propulsion. Standard bikes retain the largest volume share due to universal commuter applicability, while road bikes command premium resale multiples among enthusiast segments. Online marketplaces are capturing the fastest growth trajectory as condition-grading algorithms reduce information asymmetry between distant buyers and sellers.
FCC guidelines on connected-vehicle telemetry intersect with state-level lemon laws to shape warranty disclosure requirements for digitally listed used motorcycles. EPA enforcement of evaporative emissions testing for pre-owned gasoline-powered bikes in the United States, alongside EU REACH compliance for frame coating materials in European resale channels, creates divergent compliance burdens by geography. Stakeholders must monitor whether battery-health certification protocols for emerging electric two-wheeler resale migrate from voluntary OEM programs to binding federal standards.
Market Dynamics
Digital provenance verification is restructuring trust economics between distant buyers and sellers, compressing transaction friction that previously anchored used bike commerce to local inspection networks.
Growth Catalysts
- EPA Tier 5 motorcycle emissions standards:Rising compliance costs for new internal-combustion inventory redirect price-sensitive riders toward pre-owned alternatives with grandfathered certification status.
- Blockchain-based title registries:Distributed ledger systems in India and Southeast Asia eliminate odometer fraud and ownership dispute risks that historically suppressed peer-to-peer volume.
- Urban micromobility corridors:Dedicated bike lane expansions in São Paulo, Bogotá, and Jakarta convert car-dependent commuters to two-wheeler ownership, with used units capturing first-time buyer entry.
Market Restraints
- Lithium battery degradation uncertainty:Absence of standardized state-of-health testing protocols for used electric two-wheelers creates information asymmetry that suppresses resale premiums and liquidity.
- Regional supply fragmentation:Used motorcycle inventory concentrates in informal dealer networks across India's tier-two cities, limiting price discovery and financing access for distant buyers.
- EU REACH coating compliance:Frame refinishing requirements for resale in European channels impose documentation burdens that exclude small-scale refurbishers from formal market participation.
Strategic Opportunities
- Embedded insurance bundling:Point-of-sale warranty products for used motorcycles capture lifetime value beyond transaction margins, with Indian digital marketplaces piloting subscription-based coverage models.
- AI-driven condition grading:Computer vision systems analyzing frame geometry and component wear from smartphone imagery enable remote certification, unlocking cross-border trade between Latin America and North American buyers.
- Battery-swapping network integration:Used electric two-wheeler resale platforms in China and Taiwan are converging with Gogoro-style swap infrastructure, decoupling vehicle value from cell ownership.
Industry Challenges
- Certified mechanic scarcity:Diagnostic proficiency for electric drivetrain refurbishment lags behind internal-combustion expertise, constraining throughput at dedicated reconditioning facilities.
- Cross-jurisdiction title reconciliation:State-level lemon law variations in the United States create compliance fragmentation for national listing platforms attempting standardized disclosure frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Bike Market |
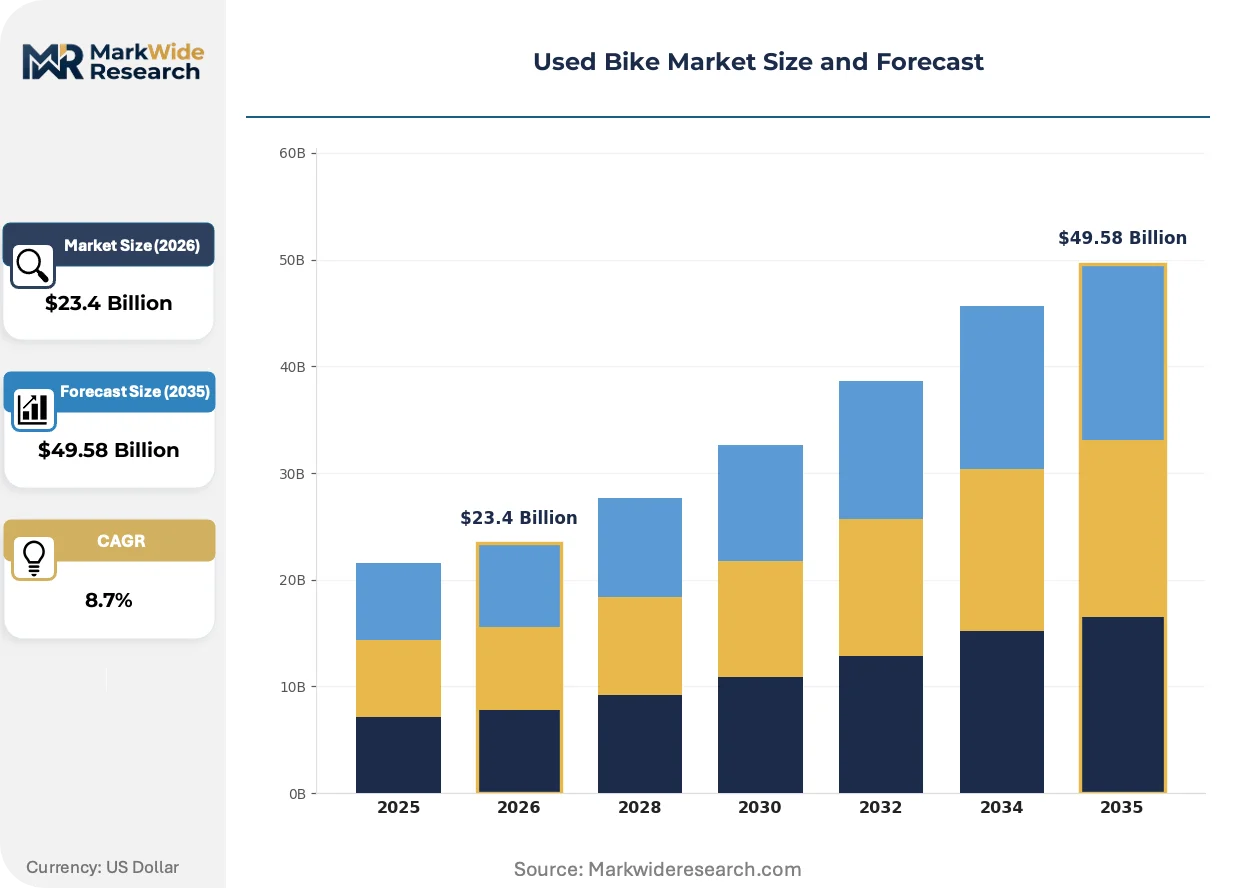
| Market Size in 2026 | $23.4 Billion |
| Market Size in 2035 | $49.58 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bikes, Mountain Bikes, Road Bikes, Hybrid Bikes Customer Type: First-time Buyers, Enthusiasts, Commuters, Casual Riders Distribution Channel: Online Marketplaces, Local Dealerships, Auctions, Classified Ads Condition: Refurbished, Like New, Good, Acceptable |
| Companies Covered | Buycycle, Yamaha Certified Pre-Owned, Droom, India Kawasaki Motors, Triumph Motorcycles, MotoHunt, eBay, Motorbikes 4 All, The Pro’s Closet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Bike Market Emerging Trajectories
Condition-certification automation is collapsing geographic barriers between buyers and sellers, while regulatory pressure on new vehicle emissions accelerates residual value capture in pre-owned channels.
Computer vision frame-scanning technology is modularizing structural integrity assessment across inspection workflows. Remote certification platforms deploy smartphone-based algorithms to detect crack propagation and fatigue stress without physical teardown. Urban marketplace operators in India and Brazil integrate these tools to enable sight-unseen transactions that previously required in-person verification.
EPA enforcement of evaporative emissions testing for pre-owned gasoline-powered motorcycles is tightening documentation requirements for US resale channels. State regulators in California and New York now mandate diagnostic port verification of catalytic converter integrity before title transfer. Digital listing platforms absorb compliance costs through integrated inspection partnerships, while informal sellers face delisting from major marketplaces.
Subscription-based ownership models are fragmenting traditional purchase cycles among younger urban demographics. Riders in European cities and East Asian metros increasingly treat two-wheelers as depreciating assets to rotate rather than long-term holdings, compressing holding periods and accelerating secondary market velocity. Fleet operators and peer-to-peer rental platforms capture off-lease inventory for refurbishment and resale.
Used Bike Market Segmentation
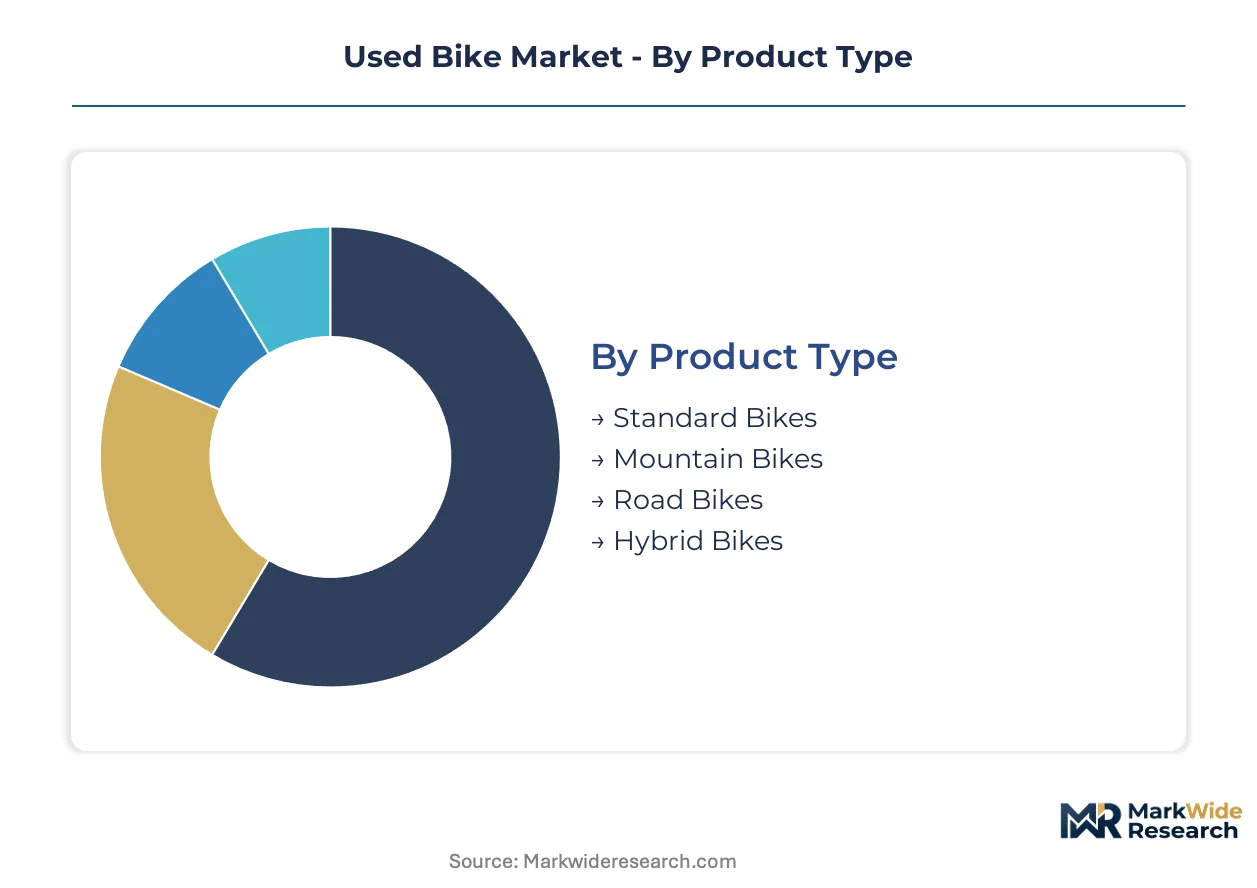
Segmentation in the used bike market determines pricing power, refurbishment economics, and channel selection. Capital deployment varies sharply across product categories and customer profiles, shaping where platforms concentrate inspection technology and inventory financing.
Product Type:
Capital intensity peaks with road bikes requiring precision drivetrain calibration and carbon fiber diagnostics, while standard bikes demand minimal reconditioning investment.
- Standard Bikes:Steel or aluminum frames with basic single-speed or multi-gear configurations dominate volume in Indian tier-two cities and Southeast Asian urban corridors. Demand concentrates among price-sensitive commuters in Jakarta and São Paulo where first-time buyers prioritize durability over performance specifications.
- Mountain Bikes:Suspension fork maintenance and disc brake servicing drive higher refurbishment costs than road or hybrid categories. Enthusiast segments in Colorado and British Columbia sustain premium resale multiples through trail-access proximity.
- Road Bikes:Carbon fiber layup inspection and groupset compatibility verification attract the highest per-unit capital allocation in reconditioning workflows.
- Hybrid Bikes:Versatile geometry suits European city bike lane expansions with moderate component complexity balancing commuter utility against maintenance burden.
Most installed capacity flows through Standard Bikes. Expansion is steepest in Road Bikes.
Customer Type:
Acquisition cost tolerance and financing eligibility diverge sharply across buyer sophistication levels, determining where platforms deploy credit underwriting versus cash-transaction optimization.
- First-time Buyers:Price ceilings below three hundred dollars concentrate demand in Indian and Brazilian digital marketplaces with integrated EMI products. Droom and similar platforms capture this segment through smartphone-first onboarding with minimal documentation requirements.
- Enthusiasts:Component-grade discrimination and frame material expertise justify premium inspection services including borescope analysis of carbon fiber tubes. North American and Western European buyers drive cross-border procurement through condition-certification platforms.
- Commuters:Reliability guarantees and theft-insurance bundling shape purchasing decisions in dense urban micromobility corridors.
- Casual Riders:Seasonal usage patterns and storage constraints favor rental-to-own conversion models over outright purchase.
First-time Buyers absorb the highest absolute volume. Enthusiasts generate the steepest margin expansion.
Distribution Channel:
Technology deployment intensity separates capital-light classified models from inspection-integrated marketplace infrastructure requiring sustained platform investment.
- Online Marketplaces:Computer vision grading algorithms and blockchain title verification demand substantial fixed-cost infrastructure. Buycycle and eBay sustain liquidity through geographic reach with proprietary frame-scanning certification reducing return rates.
- Local Dealerships:Physical inspection networks capture trust-sensitive buyers in India's informal tier-two dealer concentrations where financing access remains limited.
- Auctions:Fleet operator off-lease volume and insurance salvage titles concentrate in commercial buyer segments with refurbishment capabilities.
- Classified Ads:Minimal platform fees attract price-maximizing sellers accepting higher transaction friction and fraud exposure.
Inspection-integrated Online Marketplaces command the highest capital deployment per transaction. Auction volume is expanding most quickly through fleet electrification turnover.
Condition:
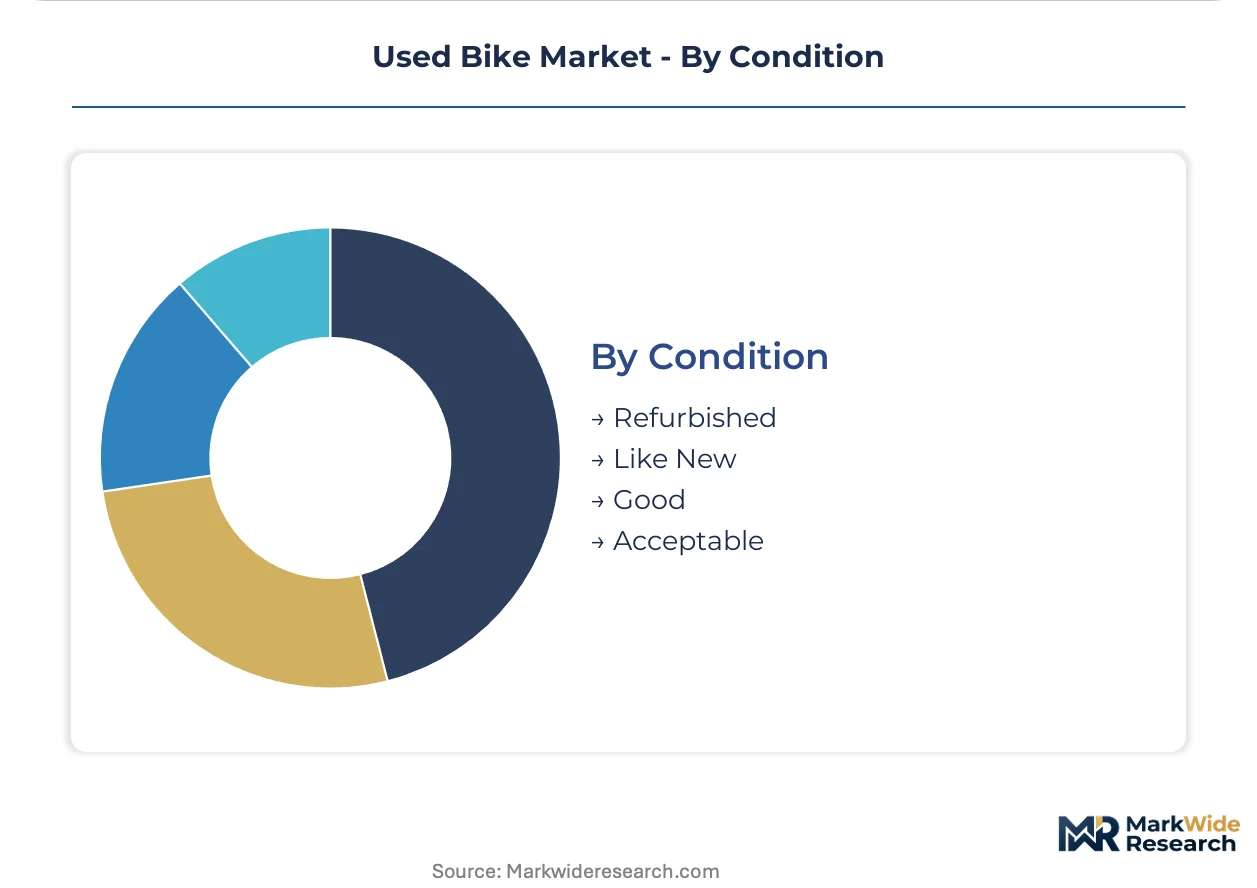
Refurbishment depth determines working capital cycles and technician allocation across reconditioning facilities.
- Refurbished:Complete drivetrain replacement, bearing overhaul, and frame realignment require the most intensive labor input with EPA evaporative emissions testing mandated for gasoline-powered motorcycle resale in California and New York.
- Like New:Cosmetic touch-up and component adjustment absorb minimal shop time with fastest inventory turnover in enthusiast segments.
- Good:Brake pad replacement and cable housing refresh represent standard reconditioning depth for commuter-targeted inventory.
- Acceptable:Functional verification without cosmetic investment suits extreme price-sensitive entry with highest return risk.
Good condition inventory absorbs the most working capital in aggregate. Refurbished units are gaining share fastest as EPA compliance documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The used bike market traces its modern commercial roots to post-war Europe, where surplus military bicycles and early motorcycle manufacturing created the first structured secondary markets for two-wheeled transport.
United States
California and New York regulators now mandate diagnostic port verification of catalytic converter integrity before title transfer for pre-owned gasoline-powered motorcycles. EPA enforcement of evaporative emissions testing tightens documentation requirements for US resale channels. Digital listing platforms absorb compliance costs through integrated inspection partnerships concentrated in Los Angeles and New York metro corridors.
Germany
KBA vehicle inspection protocols and EU REACH compliance for frame coating materials shape refurbishment economics in European resale channels. ECHA documentation burdens exclude small-scale refurbishers from formal market participation. Industrial reconditioning clusters around Stuttgart and Munich sustain precision drivetrain calibration capabilities for premium road bike segments.
India
Tier-two cities including Pune, Nagpur, and Coimbatore outpace metro growth for used two-wheeler sales as first-time buyers seek affordable mobility alternatives. BIS standards intersect with state-level RTO documentation requirements to shape ownership transfer workflows. Droom anchors digital marketplace penetration through integrated financing products bundled at point of sale.
China
MIIT dual carbon goals accelerate fleet electrification turnover, compressing holding periods for internal-combustion motorcycles and accelerating secondary market velocity. GB standards for battery-health certification remain voluntary, creating information asymmetry that suppresses electric two-wheeler resale premiums. Yangtze River Delta manufacturing clusters supply refurbishment components to domestic resale networks.
Brazil
Dedicated bike lane expansions in São Paulo convert car-dependent commuters to two-wheeler ownership, with used units capturing first-time buyer entry. ANVISA regulatory frameworks for vehicle safety certification intersect with state-level environmental standards. São Paulo's urban micromobility corridor concentrates marketplace liquidity through physical inspection networks serving trust-sensitive buyers.
Used Bike Market Vendor Landscape
The competitive structure tilts toward inspection-integrated marketplace operators over capital-light classified models. Platform density concentrates among digital-native entrants with proprietary certification infrastructure and legacy horizontal marketplaces with geographic reach advantages. Three archetypes dominate: technology-led condition-grading platforms, OEM-certified pre-owned programs, and horizontal e-commerce incumbents. Competitive moves center on embedded insurance bundling and cross-border trade enablement through remote certification tools.
Among technology-led marketplace operators, Buycycle exemplifies the frame-scanning certification archetype, while Droom anchors integrated financing penetration in high-growth emerging markets. eBay occupies a position as the horizontal incumbent sustaining liquidity across fragmented regional supply pools. OEM-certified programs including Yamaha Certified Pre-Owned represent manufacturer-backed provenance verification, capturing trust-sensitive segments through dealership network density.
| Leading Market Players |
|---|
| Buycycle |
| Yamaha Certified Pre-Owned |
| Droom |
| India Kawasaki Motors |
| Triumph Motorcycles |
| MotoHunt |
| eBay |
| Motorbikes 4 All |
| The Pro's Closet |
| Others |
Supply Flow & Price Mechanics
Captive inspection networks in India and Brazil anchor both supply security and pricing power for digital marketplace operators, as proprietary frame-scanning certification creates defensible margin positions against horizontal classified competitors. EPA emissions documentation requirements in California and New York tighten compliance costs that concentrate in refurbished inventory tiers, compressing returns for uncertified sellers while rewarding integrated platforms with inspection partnerships.
Pricing Analysis
Bundled financing-insurance products against unbundled cash transactions split the pricing architecture across buyer archetypes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion, with Droom's integrated EMI products capturing price-sensitive first-time buyers in Indian tier-two cities. Cost compression in refurbished gasoline-powered motorcycles is intensifying because EPA evaporative emissions testing mandates diagnostic port verification before title transfer. First-time buyers exhibit highest price sensitivity below three hundred dollar ceilings, while enthusiasts demonstrate lowest sensitivity through component-grade discrimination and cross-border procurement premiums.
Supply Chain Analysis
Reverse-logistics flows for frame realignment, drivetrain replacement, and battery-health recertification determine working capital cycles across reconditioning facilities. Manufacturing clusters in China, Taiwan, and Germany supply carbon fiber layup components and precision groupset hardware that refurbishment networks in India and Brazil draw from. Single-source vulnerability concentrates in lithium battery cell supply for emerging electric two-wheeler resale channels. Distribution runs through inspection-integrated online marketplaces in dense urban corridors, with informal dealer networks in Indian tier-two cities capturing trust-sensitive buyers outside digital penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
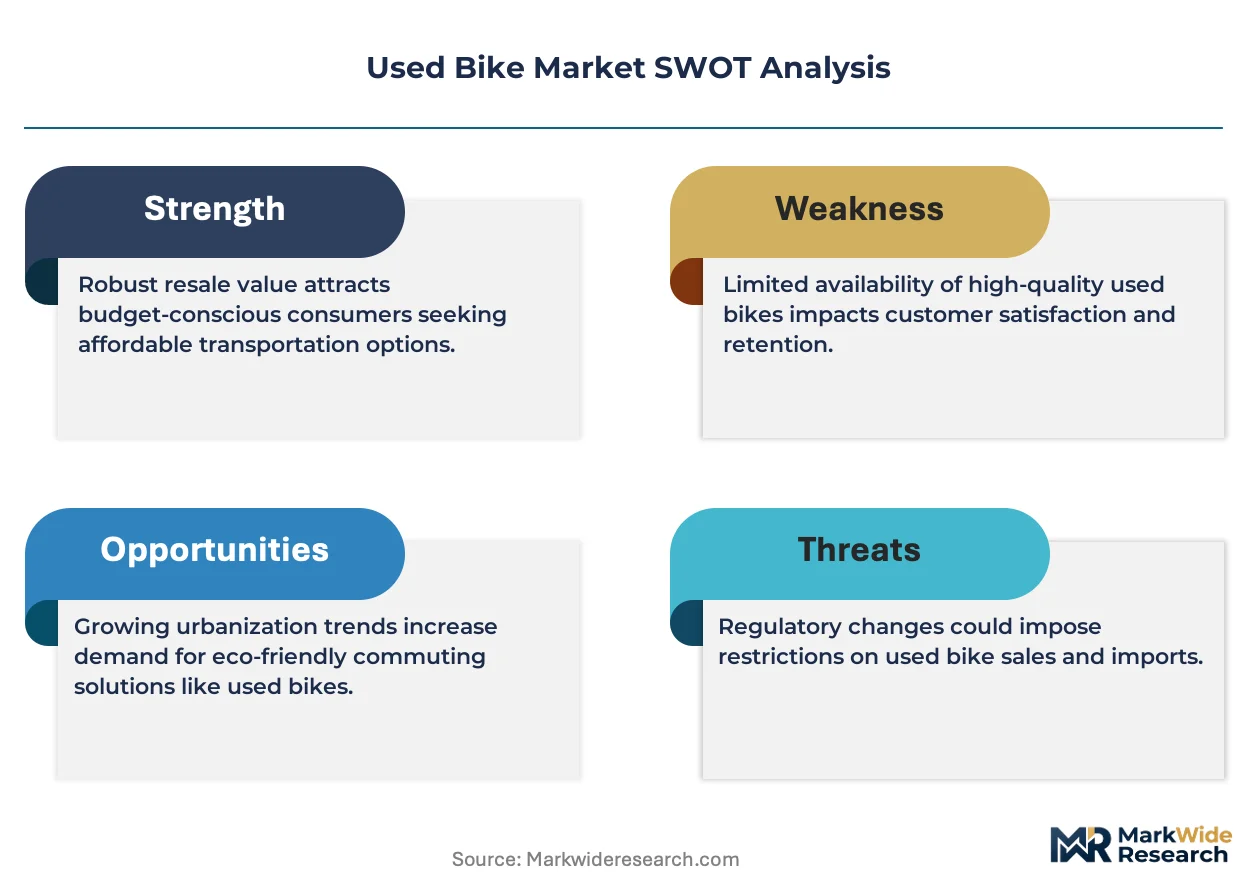
This market compounds regulatory pressure into demand acceleration, with EPA Tier 5 motorcycle emissions standards redirecting price-sensitive riders toward pre-owned alternatives with grandfathered certification status.
For Market Incumbents: Hedge against lithium battery degradation uncertainty by piloting standardized state-of-health testing protocols before binding federal standards emerge. Absorb compliance costs through integrated inspection partnerships in California and New York metro corridors, while defending margin position through proprietary frame-scanning certification that horizontal classified competitors cannot replicate.
For New Entrants and Emerging Players: First-time buyers in Indian tier-two cities represent the most penetrable white-space segment, as Pune, Nagpur, and Coimbatore outpace metro growth with limited financing access from incumbent platforms. Capture this segment through smartphone-first onboarding with minimal documentation requirements, converging with Gogoro-style battery-swapping infrastructure to decouple vehicle value from cell ownership.
For Investors and Strategic Acquirers: Roll-up economics work for technology-led condition-grading platforms because inspection-integrated marketplace operators command sustainable liquidity advantages over capital-light classified models across fragmented regional supply pools. Target acquisition archetypes include computer vision certification specialists and embedded insurance bundling pilots with proven subscription-based coverage models. Monitor whether battery-health certification protocols for electric two-wheeler resale migrate from voluntary OEM programs to binding federal standards as the inflection indicator for platform valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Condition Grading Deployment | Computer vision systems analyzing frame geometry from smartphone imagery unlock cross-border trade between Latin America and North American buyers. |
| Embedded Insurance Bundling | Point-of-sale warranty products capture lifetime value beyond transaction margins through subscription-based coverage models piloted by Indian digital marketplaces. |
| Battery-Swapping Network Integration | Used electric two-wheeler resale platforms in China and Taiwan converge with Gogoro-style swap infrastructure to decouple vehicle value from cell ownership. |
| Blockchain Title Registry Implementation | Distributed ledger systems in India and Southeast Asia eliminate odometer fraud risks that historically suppressed peer-to-peer volume expansion. |
| Certified Mechanic Training Programs | Diagnostic proficiency development for electric drivetrain refurbishment addresses throughput constraints at dedicated reconditioning facilities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with digital marketplace operators, refurbishment facility managers, OEM pre-owned program directors, and regulatory compliance officers with secondary validation. Secondary sources encompassed EPA enforcement disclosures, state-level lemon law variations, EU REACH documentation requirements, and BIS standard filings. Bottom-up transaction volume estimates across product categories, customer segments, and distribution channels triangulated against top-down macroeconomic indicators and mobility demand proxies.
Historical reference periods anchored the projection horizon through comparable-period growth rate analysis and structural breakpoint identification across regulatory milestone implementation. Segmentation dimensions modeled included product type, customer sophistication tier, distribution channel technology intensity, condition grade, and regional regulatory cluster. CAGRs derived from segment-level trajectory fitting and convergence analysis incorporated electric two-wheeler fleet turnover velocity and urban micromobility corridor expansion as industry-specific forecast inputs.
Underlying measurement precision varies by segment; online marketplace transaction data and OEM-certified program disclosures carry tighter precision than informal dealer network estimates. Forecasts reflect assumptions regarding regulatory enforcement continuity, battery-health standardization timelines, and inspection technology adoption curves. Practitioners should monitor EPA emissions tier updates, blockchain title registry deployment velocity, and certified mechanic training program scale for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market