
 Automotive Start-Stop System Market | 2026-2036
Automotive Start-Stop System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Start-Stop System Market Analysis
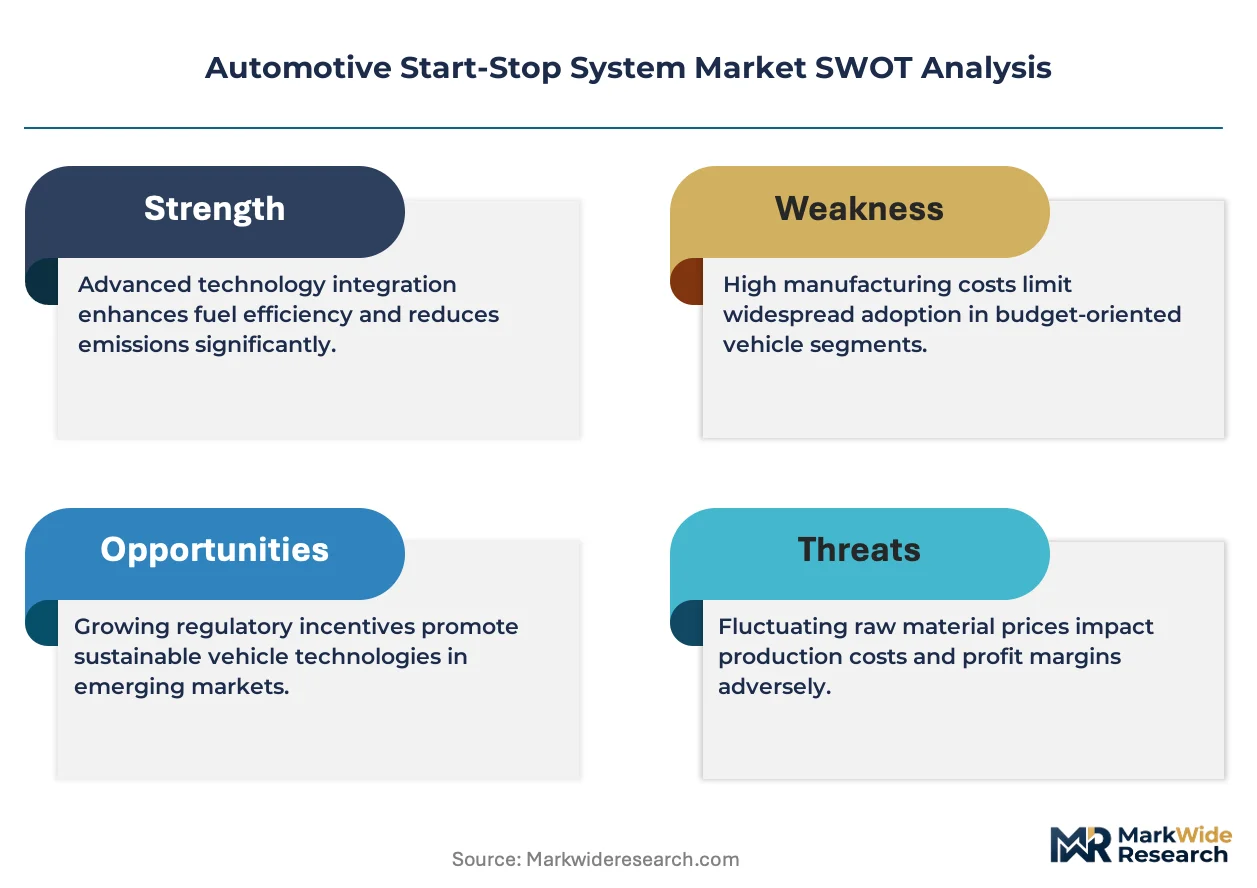
Fleet operators are bifurcating demand away from individual consumers as commercial vehicle electrification mandates intensify. Continental AG leverages its integrated powertrain portfolio to anchor European OEM supply chains. Robert Bosch GmbH sustains technology leadership through advanced battery management algorithms. Denso Corporation dominates Japanese and Southeast Asian factory-fitted installations with thermal-optimized system designs.
An automotive start-stop system automatically shuts down and restarts the internal combustion engine to eliminate idle fuel consumption, typically achieving restart times under 0.4 seconds through reinforced starter motors and enhanced control electronics. Its primary commercial purpose is to reduce urban cycle emissions and improve fleet fuel economy ratings without full hybridization costs. Lithium-ion battery configurations command the highest margin pools due to superior cycle life under frequent restart loads. Mild hybrid technology leads volume deployment as OEMs balance cost against regulatory credit accumulation. Factory-fitted installation maintains structural dominance over retro-fit channels because calibration complexity discourages aftermarket penetration.
The EPA enforces Corporate Average Fuel Economy standards that directly mandate idle-reduction technology adoption across US vehicle fleets. The European Union applies CO2 fleet emission limits through EEA implementation, while China's MIIT administers dual carbon goals that accelerate domestic start-stop integration. Stakeholders must monitor regulatory credit trading mechanics and battery chemistry certification pathways as compliance thresholds tighten and OEM sourcing decisions consolidate around proven system integrators.
Market Dynamics
OEM sourcing decisions now consolidate around proven system integrators as EPA Corporate Average Fuel Economy standards and EU CO2 fleet limits tighten simultaneously, compressing supplier qualification timelines and favoring integrated powertrain portfolios over component specialists.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:US passenger vehicle fleets face escalating idle-reduction mandates that factory-fitted start-stop systems satisfy without full hybridization costs, pulling demand through OEM supply chains.
- Enhanced battery management algorithms:Advanced control electronics achieve restart times under 0.4 seconds, eliminating driver perceptible lag and removing adoption friction in premium vehicle segments.
- China MIIT dual carbon goals:Domestic OEMs accelerate start-stop integration to meet national carbon neutrality targets, concentrating manufacturing capacity expansion in Shanghai and Guangzhou clusters.
Market Restraints
- Lithium-ion raw material volatility:Cobalt and nickel price swings compress margin pools on high-cycle-life battery configurations, forcing OEMs toward less durable lead-acid alternatives in cost-sensitive trims.
- Starter motor supply concentration:German and Japanese component specialists control reinforced starter manufacturing, creating single-source vulnerability for North American OEMs seeking dual qualification.
- Retro-fit channel technical barriers:Calibration complexity between engine control units and transmission modules blocks aftermarket penetration, locking revenue in factory-fitted channels.
Strategic Opportunities
- Commercial vehicle electrification mandates:Fleet operators in California and Germany face phase-out deadlines that mild hybrid start-stop architectures satisfy as bridge technologies before full electric transition.
- 48V belt-driven starter-generator convergence:Integration of start-stop with regenerative braking creates upsell potential in European C-segment vehicles seeking regulatory credit accumulation.
- India BIS fuel efficiency norms:Domestic passenger vehicle OEMs adopt start-stop as lowest-cost compliance path, opening white space for thermal-optimized system designs in high-ambient-temperature operating conditions.
Industry Challenges
- Power electronics integration complexity:Control module software must synchronize with transmission shift logic and HVAC load management, extending calibration cycles and delaying platform launches.
- ISO 26262 functional safety certification:ASIL-D requirements for restart reliability in traffic-critical scenarios demand specialized verification engineering talent that suppliers struggle to recruit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Start-Stop System Market |
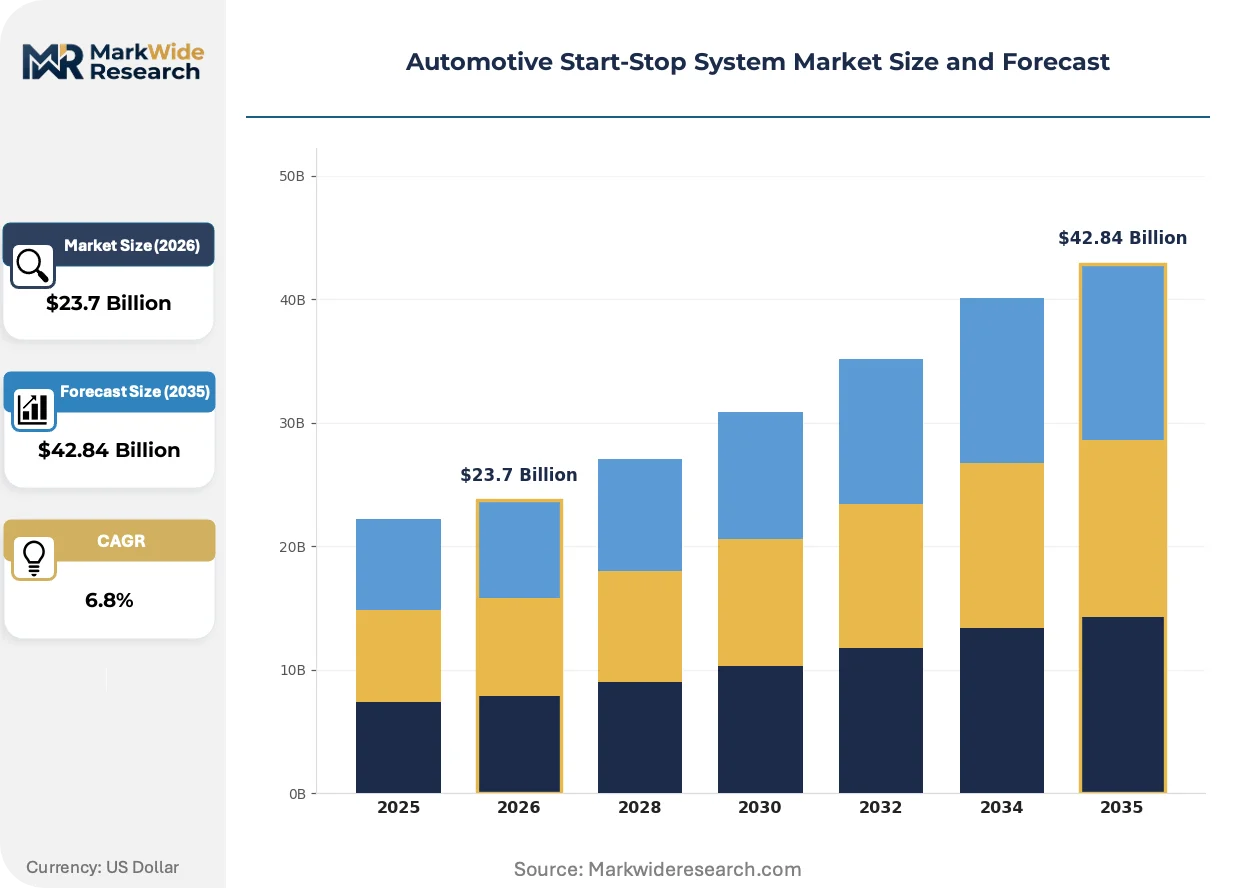
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
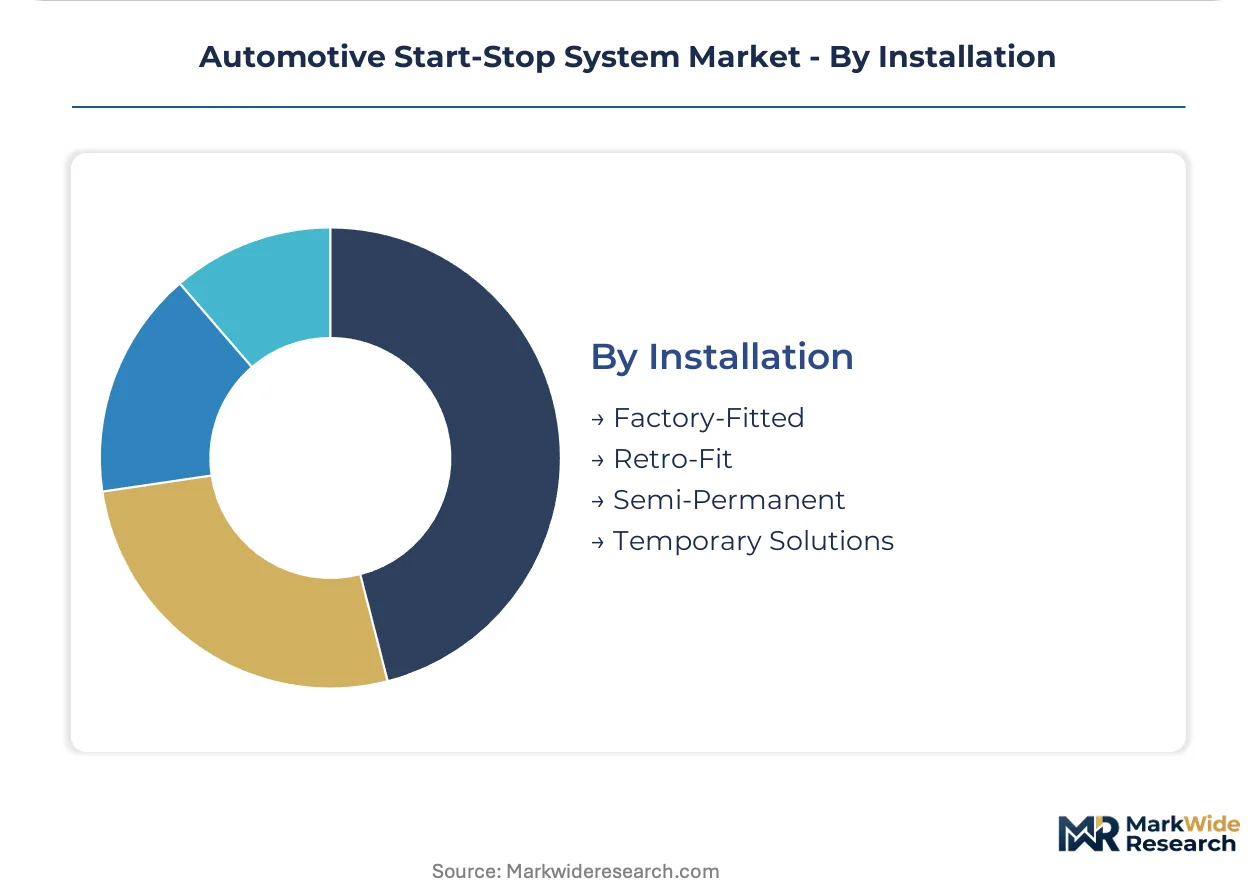
| Segmentation | Product Type: Lead-Acid Batteries, Lithium-Ion Batteries, Integrated Systems, Supercapacitors Technology: Micro Hybrid, Full Hybrid, Plug-in Hybrid, Mild Hybrid End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Installation: Factory-Fitted, Retro-Fit, Semi-Permanent, Temporary Solutions |
| Companies Covered | BorgWarner Inc., Hitachi Ltd, Continental AG, Johnson Controls Inc., Schaeffler Technologies AG & Co. KG, Denso Corporation, Valeo, ZF Friedrichshafen, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Start-Stop System Market Emerging Trajectories
Technology convergence between start-stop control electronics and mild hybrid powertrain management is compressing supplier tiers and reshaping competitive boundaries. Three developments dominate the current transformation window.
Silicon carbide power semiconductors are displacing traditional silicon MOSFETs in starter motor control modules. Tier-1 suppliers in Germany and Japan deploy these devices to reduce switching losses and shrink thermal management hardware. The shift enables higher restart duty cycles in urban traffic without increasing package size or cost.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant system redesigns that integrate start-stop with electric compressor control. European OEMs must coordinate engine shutdown logic with cabin cooling demand to maintain regulatory credit eligibility. This forces thermal system suppliers to share control architecture roadmaps previously held proprietary.
Fleet procurement departments now unbundle powertrain warranties from vehicle acquisition contracts, creating direct commercial relationships with start-stop system suppliers. Large rental and logistics operators in the United States negotiate service-level agreements based on restart reliability metrics rather than component replacement schedules. This shifts margin capture toward aftermarket predictive maintenance platforms and away from upfront hardware sales.
Automotive Start-Stop System Market Segmentation
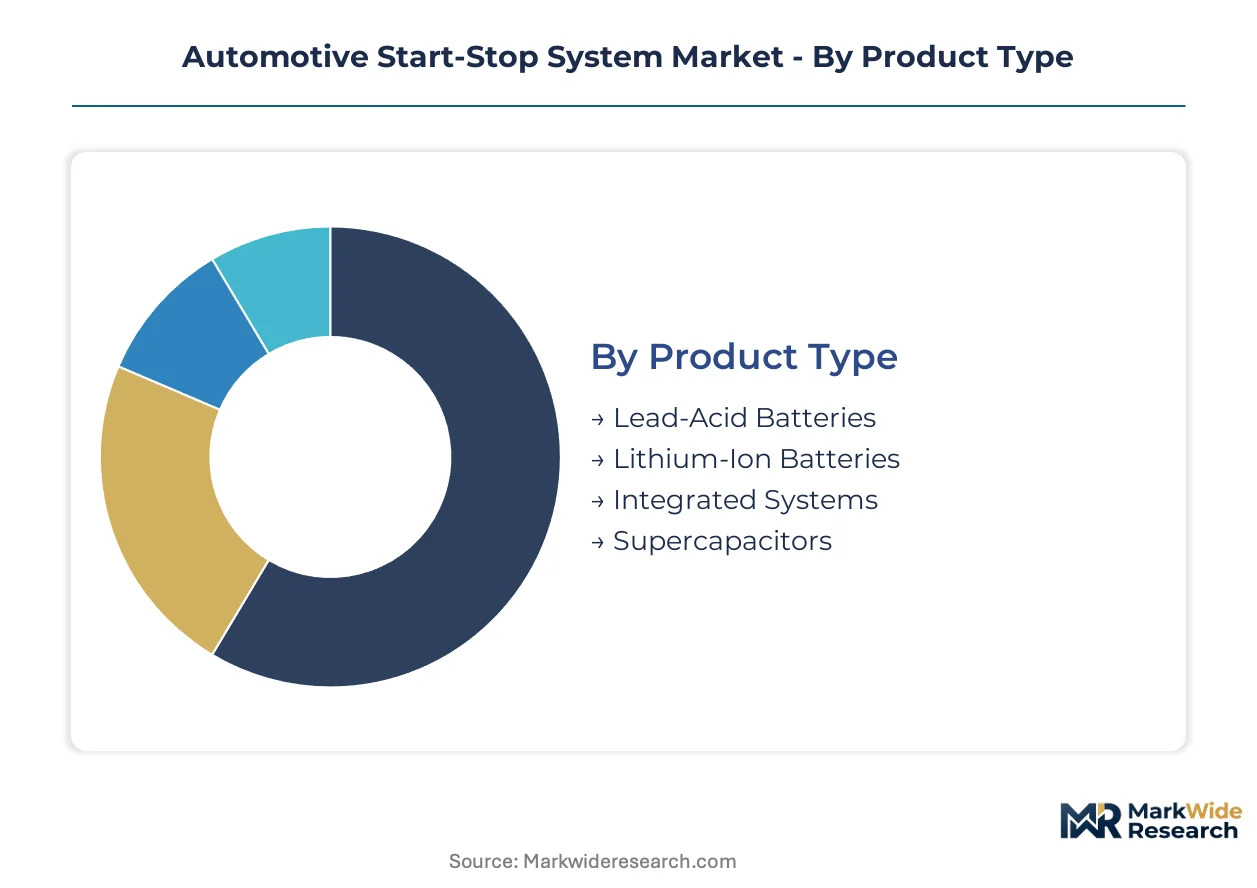
Segmentation in automotive start-stop systems reveals how margin capture diverges between battery chemistry tiers, powertrain integration levels, and channel structures. Understanding these splits exposes where OEM sourcing decisions consolidate and where aftermarket barriers persist.
Product Type:
Lithium-ion and integrated system configurations command the deepest margin pools due to cycle life demands and calibration complexity.
- Lithium-Ion Batteries:Superior cycle endurance under frequent restart loads supports premium vehicle segments. German and Japanese OEMs specify these for mild hybrid architectures where EPA fuel economy credits justify cost premiums.
- Integrated Systems:Combine battery, control module, and starter motor in pre-calibrated packages. Chinese OEMs in Shanghai and Guangzhou clusters favor these to compress supplier qualification timelines under MIIT dual carbon deadlines.
- Lead-Acid Batteries:Cost-sensitive trims in India's passenger vehicle market specify these as BIS fuel efficiency compliance paths.
- Supercapacitors:Niche deployment in commercial vehicle applications requiring extreme restart duty cycles.
Lithium-ion holds installed capacity. Integrated systems are rotating up the share rankings.
Technology:
Volume concentration sits with architectures that balance regulatory credit accumulation against hybridization cost.
- Mild Hybrid:48V belt-driven starter-generator architectures dominate European C-segment deployment. EU CO2 fleet limits pull demand as bridge technology before full electric transition.
- Micro Hybrid:Conventional 12V start-stop satisfies entry-level compliance in cost-constrained markets. Indian OEMs deploy these widely under BIS norms without additional powertrain redesign.
- Full Hybrid:Toyota and Honda proprietary systems largely bypass conventional start-stop supply chains.
- Plug-in Hybrid:Larger battery packs reduce start-stop system relevance as standalone revenue driver.
Mild hybrid captures regulatory-driven volume. Micro hybrid maintains broadest geographic penetration.
End User:
Procurement authority is shifting from individual consumers toward fleet operators with unbundled powertrain warranty demands.
- OEMs:Factory-fitted channel concentration creates direct relationships with Continental AG, Robert Bosch GmbH, and Denso Corporation. Calibration complexity locks revenue in this channel.
- Fleet Operators:California and Germany commercial electrification mandates accelerate mild hybrid adoption as compliance bridge. Large US rental and logistics operators now negotiate service-level agreements on restart reliability metrics.
- Aftermarket Providers:ECU-transmission calibration barriers block meaningful penetration.
- Individual Consumers:Price-sensitive demand concentrates in emerging market entry segments.
OEMs retain structural dominance. Fleet operators are gaining procurement leverage fastest.
Installation:
Channel economics favor permanent integration where software calibration protects margin.
- Factory-Fitted:Structural dominance reinforced by ISO 26262 ASIL-D functional safety requirements. Control module software must synchronize with transmission shift logic and HVAC load management.
- Retro-Fit:Technical barriers between engine control units and transmission modules prevent scalable aftermarket models.
- Semi-Permanent:Limited deployment in commercial vehicle trial programs.
- Temporary Solutions:Negligible commercial relevance in regulated markets.
Factory-fitted maintains channel control. Retro-fit faces persistent technical blockades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports integrated start-stop systems to US and Chinese OEMs, while Japanese component manufacturers supply reinforced starter motors to European assembly plants.
United States
EPA Corporate Average Fuel Economy standards drive factory-fitted adoption across Detroit Three lineups. The Inflation Reduction Act extends regulatory pressure through fleet electrification incentives. Michigan and Ohio manufacturing corridors concentrate starter motor and control module assembly capacity.
Germany
EU CO2 fleet emission limits pull demand for 48V mild hybrid architectures in C-segment vehicles. The KBA enforces type-approval standards that compress supplier qualification timelines. Stuttgart and Munich engineering clusters anchor Continental AG and Robert Bosch GmbH development centers.
China
MIIT dual carbon goals accelerate domestic OEM integration of start-stop as lowest-cost compliance path. National carbon neutrality targets phase down fleet emissions through 2035. Shanghai and Guangzhou production clusters concentrate lithium-ion battery pack manufacturing for integrated system exports.
Japan
METI fuel efficiency standards sustain technology investment in advanced battery management algorithms. JIS certification requirements protect domestic supply chain relationships. Aichi Prefecture manufacturing corridors concentrate Denso Corporation thermal-optimized system production for Southeast Asian markets.
India
BIS fuel efficiency norms mandate idle-reduction technology in entry-level passenger vehicles. Domestic OEMs specify lead-acid configurations as cost-sensitive compliance paths. Tamil Nadu and Maharashtra automotive clusters expand factory-fitted installation capacity for Maruti Suzuki and Hyundai Motor India.
Automotive Start-Stop System Market Vendor Landscape
Player mix skews toward diversified powertrain conglomerates with integrated portfolio breadth. Consolidation favors suppliers controlling battery management software, reinforced starter manufacturing, and thermal system calibration under single engineering umbrellas. Two strategic archetypes dominate: integrated system integrators bundling battery, control module, and starter in pre-calibrated packages; and component specialists defending position in high-cycle-life battery chemistries or silicon carbide power electronics. Competitive moves concentrate on M&A to acquire battery management algorithm capabilities and capacity expansion in Shanghai and Guangzhou corridors to serve MIIT compliance deadlines.
Within the integrated system tier, Continental AG, Robert Bosch GmbH, and Denso Corporation exemplify the powertrain conglomerate archetype. Continental AG anchors European OEM supply chains through factory-fitted pre-calibration packages. Robert Bosch GmbH occupies a position defined by control electronics sophistication. Denso Corporation represents thermal optimization specialization for high-ambient-temperature operating conditions in Southeast Asian markets.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Hitachi Ltd |
| Continental AG |
| Johnson Controls Inc. |
| Schaeffler Technologies AG & Co. KG |
| Denso Corporation |
| Valeo |
| ZF Friedrichshafen |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Ninety-day battery cell lead times from Shanghai and Guangzhou manufacturing clusters concentrate pricing leverage among integrated system suppliers serving EPA and MIIT compliance deadlines. OEMs face compressed negotiation windows as dual qualification timelines favor pre-calibrated packages over component sourcing.
Pricing Analysis
Next-generation 48V mild hybrid architectures command substantial premiums over legacy 12V micro hybrid configurations. Three-tier pricing structure across premium lithium-ion, standard integrated lead-acid, and economy standalone starter systems reflects battery chemistry durability and calibration complexity. Cost compression in lead-acid tiers is intensifying because cobalt and nickel volatility pushes OEMs toward shorter-cycle alternatives. Fleet operators demonstrate lowest price sensitivity due to unbundled warranty service-level agreements, while Indian entry-segment OEMs exhibit highest cost pressure under BIS norms.
Supply Chain Analysis
Strait of Malacca transit routes underpin lithium-ion cell delivery schedules to European assembly plants. German and Japanese component specialists anchor reinforced starter motor manufacturing, while Chinese producers dominate lithium-ion pack assembly. The supply chain draws from cobalt extraction in the Democratic Republic of Congo, nickel refining in Indonesia, and silicon carbide wafer production in Japan. Single-source vulnerability concentrates in German starter motor specialists serving North American OEMs. Distribution runs through Tier 1 supplier direct contracts with OEM platform engineering teams, bypassing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 26262 ASIL-D functional safety certification talent scarcity constrains supplier expansion as restart reliability requirements tighten. Engineering teams capable of synchronizing control modules with transmission shift logic command premium positioning.
For Market Incumbents: Fortify software-defined control module roadmaps against silicon carbide power electronics displacement from Japanese semiconductor specialists. Acquire battery management algorithm capabilities through targeted engineering hires in Stuttgart and Munich clusters. Expand captive lithium-ion cell capacity in Shanghai corridors to offset raw material volatility exposure. For New Entrants and Emerging Players: Differentiate on thermal-optimized system designs for high-ambient-temperature operating conditions in Indian and Southeast Asian markets. Target commercial vehicle fleet procurement departments in California and Germany seeking mild hybrid bridge technologies before full electrification mandates. Pursue direct service-level agreement structures with rental and logistics operators bypassing OEM channel control. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized power electronics divisions capable of ISO 26262 certification. Long-term viability hinges on software-defined vehicle integration trajectories rather than standalone hardware margins. Monitor EPA Corporate Average Fuel Economy standard tightening velocity as inflection indicator for factory-fitted demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cobalt and nickel offtake contracts with Indonesian refiners stabilize input costs for lithium-ion configurations. |
| Software-Defined Vehicle Investment | Control module architectures integrating start-stop with regenerative braking capture EU CO2 fleet limit credits. |
| Geographic Manufacturing Footprint | Shanghai and Guangzhou production clusters align with MIIT dual carbon compliance timelines for domestic OEMs. |
| Platform Standardization | Pre-calibrated integrated systems reduce OEM supplier qualification cycles under tightening EPA idle-reduction mandates. |
| Charging Infrastructure Partnership | 48V belt-driven starter-generator convergence with mild hybrid architectures creates bridge technology positioning before full electrification. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, EU EEA implementation directives, MIIT carbon neutrality policy documents, and vehicle production databases. Primary interviews engaged Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet operations managers across Germany, China, the United States, and Japan. Secondary validation incorporated IHS Markit registration data, customs trade records, and SEC filings from publicly traded powertrain suppliers. Bottom-up unit deployment estimates triangulated against top-down regulatory mandate compliance requirements.
Segmentation dimensions modeled span battery chemistry tier, propulsion architecture classification, vehicle class, OEM sourcing tier, and regional production cluster. CAGRs derive from regression analysis across historical installation volumes and projected regulatory threshold trajectories throughout the forecast period. Industry-specific inputs include EPA fuel economy credit trading mechanics, EU F-Gas Regulation phase-down schedules, and MIIT dual carbon goal implementation velocity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or battery chemistry certification pathway stability would require recalibration. Forecasts reflect documented assumptions regarding OEM sourcing consolidation patterns and raw material supply continuity. Practitioners should keep alternative scenarios live as EPA standard tightening schedules and EU CO2 fleet limit trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market
Automotive Safety and Security Systems
Airbag Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Air Brake System Market