
 Automotive Seat Belt System Market | 2026-2036
Automotive Seat Belt System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Belt System Market Analysis
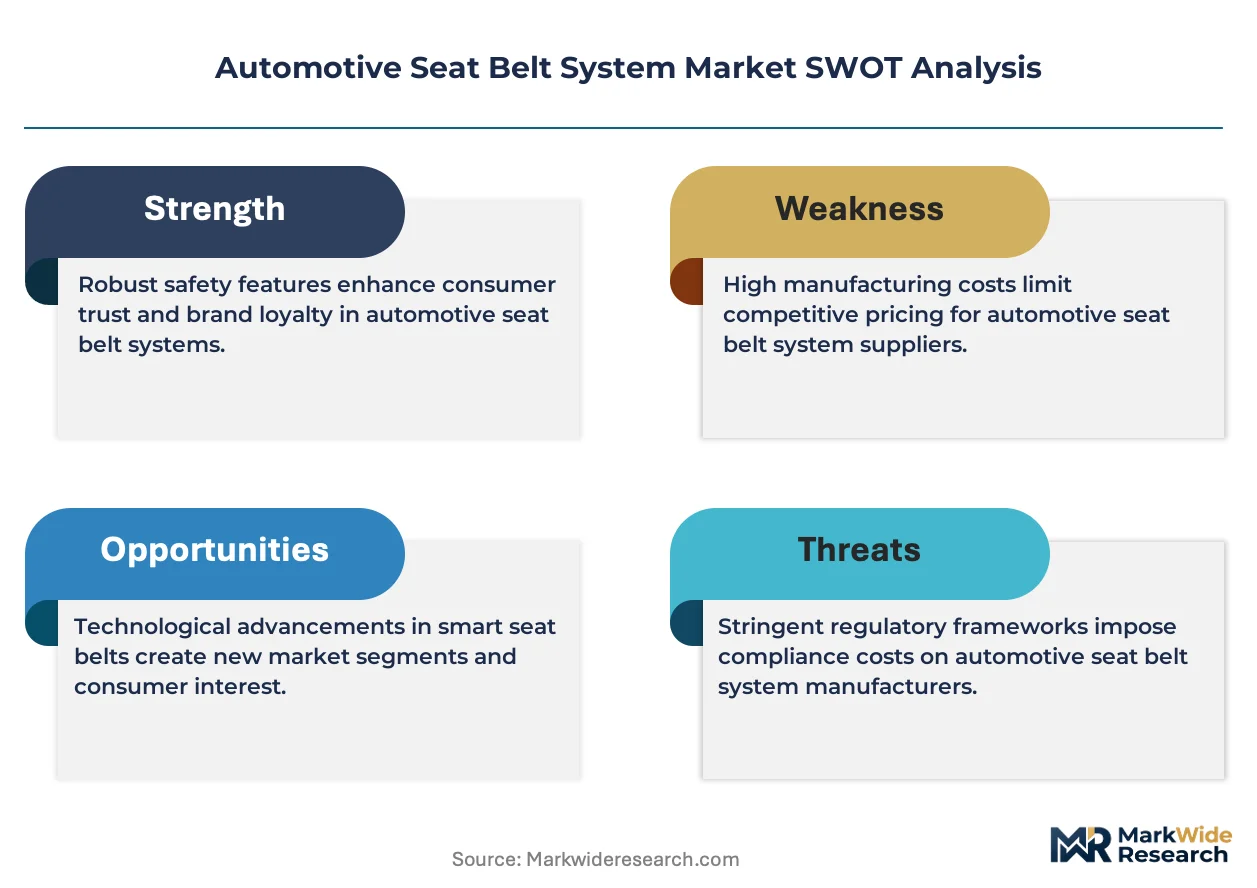
Electric vehicle platforms are restructuring how OEMs source seat belt systems, with dedicated EV architectures requiring integrated restraint modules rather than standalone components. Autoliv Inc. dominates retractable pretensioner supply for premium EV lineups. ZF Friedrichshafen AG anchors its position through load-limiter technology leadership in European assembly plants. Joyson Safety Systems leverages its China manufacturing base to supply domestic EV brands at scale.
An automotive seat belt system is an occupant restraint device comprising woven polyester webbing, a retractor mechanism with torsion bar or clutch-based load limiting, and anchorages engineered to withstand forces exceeding 10 kN during collision events; its primary function is to distribute deceleration loads across the pelvis and thorax while preventing occupant ejection. Three-point belts remain the volume backbone across passenger vehicle segments, though pretensioner-equipped variants command disproportionate margin pools in premium installations. Smart belt technology, integrating capacitive occupancy sensing and buckle-state telemetry, represents the fastest-growing technology dimension as OEMs pursue predictive crash preparation.
NHTSA's FMVSS 209 and 302 standards govern webbing flame resistance and breaking strength in the US market, while ECE R16 mandates dynamic testing protocols across European type approvals. China's GB 14166 standard, administered by SAMR, now requires load-limiter performance verification for all new passenger vehicle certifications. Stakeholders must monitor divergence between UN harmonized regulations and emerging market-specific test protocols when allocating R&D budgets across regional product lines.
Market Dynamics
Electric vehicle architectures are dissolving the boundary between seat belt systems and vehicle structure, forcing suppliers to engineer restraint modules as integrated safety nodes rather than discrete components. This platform-level integration is compressing supplier margins while elevating technical barriers to entry.
Growth Catalysts
- ECE R16 anchorage mandates:Europe's upgraded dynamic testing protocols are compelling OEMs to redesign mounting points, generating replacement demand for reinforced webbing and retractor assemblies.
- Capacitive occupancy sensing:Smart belt systems with buckle-state telemetry are penetrating premium EV lineups as predictive crash preparation becomes a competitive differentiator.
- China's five-star safety push:Domestic EV brands seeking C-NCAP top ratings are accelerating procurement of pretensioner-equipped variants with integrated load limiters.
Market Restraints
- High-tenacity polyester volatility:Raw material concentration among Asian petrochemical suppliers exposes tier-one manufacturers to input cost swings without pass-through mechanisms.
- Retractor mechanism complexity:Torsion bar and clutch-based load limiters require precision metal forming capabilities that concentrate among a limited supplier base in Germany and Japan.
- Homologation fragmentation:Divergence between UN harmonized regulations and China's GB 14166 standard forces redundant testing cycles, inflating R&D overhead.
Strategic Opportunities
- India's PLI scheme for auto components:Localized manufacturing incentives for advanced safety systems create greenfield capacity opportunities for restraint module assembly.
- Aftermarket smart retrofit kits:Telemetry-enabled buckle sensors are opening a channel for upgrade installations in aging vehicle parcs across Southeast Asia.
- Biomechanical simulation convergence:Partnerships between webbing manufacturers and crash-test dummy producers are enabling virtual certification pathways that compress development timelines.
Industry Challenges
- Multi-physics simulation talent scarcity:Finite element modeling expertise combining textile mechanics with occupant kinematics remains concentrated among a narrow specialist pool.
- Legacy platform integration friction:ICE-derived vehicle architectures resist the wiring harness and sensor placement requirements of predictive restraint systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Belt System Market |
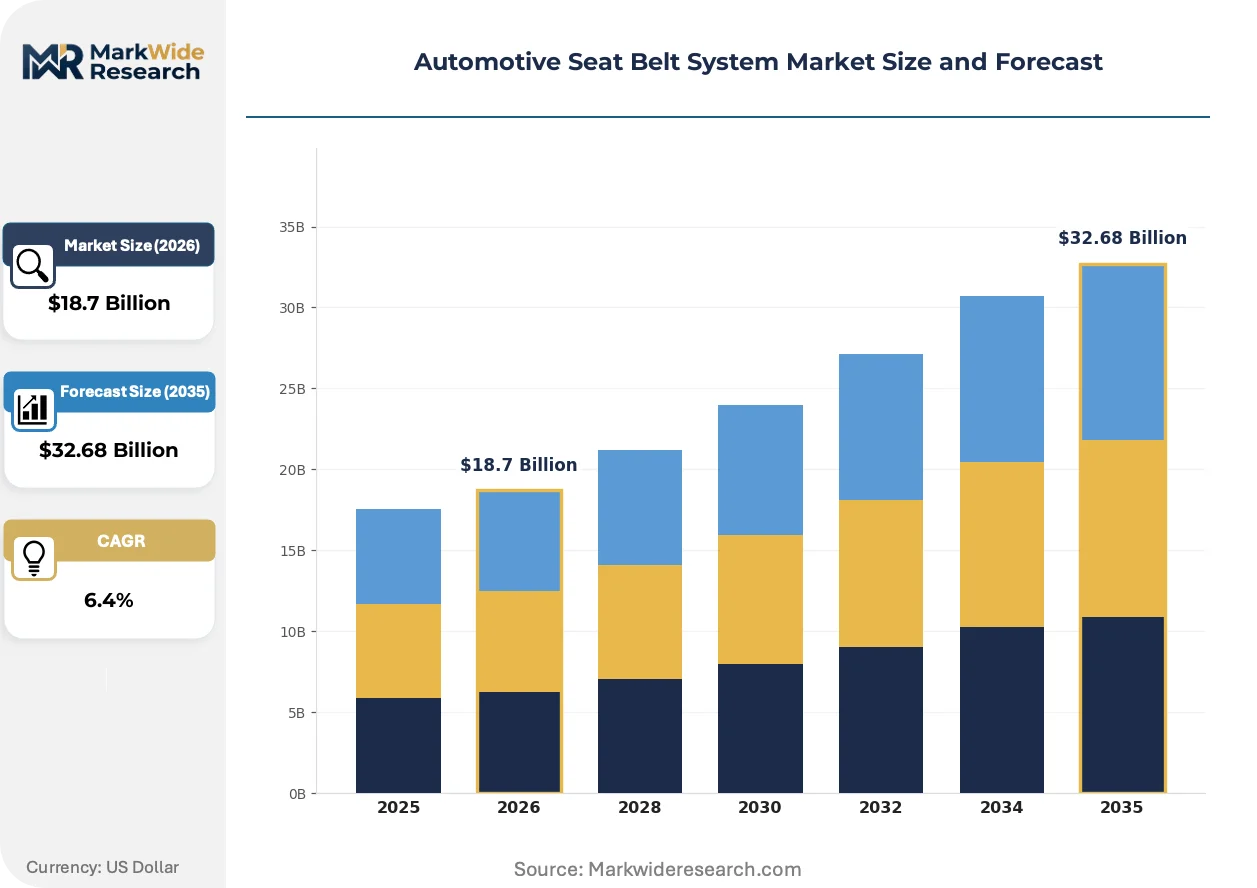
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3-Point Belts, 5-Point Harness, Lap Belts, Booster Seats Technology: Retractor Mechanism, Load Limiter, Pretensioner, Smart Belt End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Installation: Front Seats, Rear Seats, Seatbelts with Airbags, Commercial Vehicles |
| Companies Covered | Autoliv Inc., ZF Friedrichshafen AG, Joyson Safety Systems, Continental AG, Hyundai Mobis Co., Ltd., Robert Bosch GmbH, Toyoda Gosei Co., Ltd., Denso Corporation, Tokai Rika Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Belt System Market Emerging Trajectories
Seat belt technology is migrating from passive restraint toward active safety nodes that communicate with vehicle-wide crash prediction networks. This transformation is redrawing competitive boundaries between traditional suppliers and electronics integrators.
Webbing-integrated force sensors are converging with vehicle-to-vehicle communication protocols to enable pre-tensioning milliseconds before physical impact. Premium EV platforms in Germany and South Korea are adopting these systems at accelerated cadences. The technology is converging with centralized computing architectures, eliminating standalone ECUs and compressing the addressable market for discrete restraint controllers.
NHTSA's pending updates to FMVSS 209 are tightening flame resistance thresholds for polyester webbing used in electric vehicle battery-proximate seating positions. The rulemaking is forcing reformulation of polymer additives across US-bound production lines. Suppliers serving Detroit Three OEMs are responding by qualifying alternative halogen-free treatments ahead of enforcement.
Fleet operators are unbundling safety system procurement from full-vehicle contracts, establishing direct supplier relationships for standardized restraint modules across multi-brand parcs. Rental and ride-hail aggregators are driving this disintermediation, seeking volume pricing and unified telemetry interfaces. The shift is most visible in California and Texas, where large fleet holders are consolidating specification authority away from individual OEM negotiations.
Automotive Seat Belt System Market Segmentation
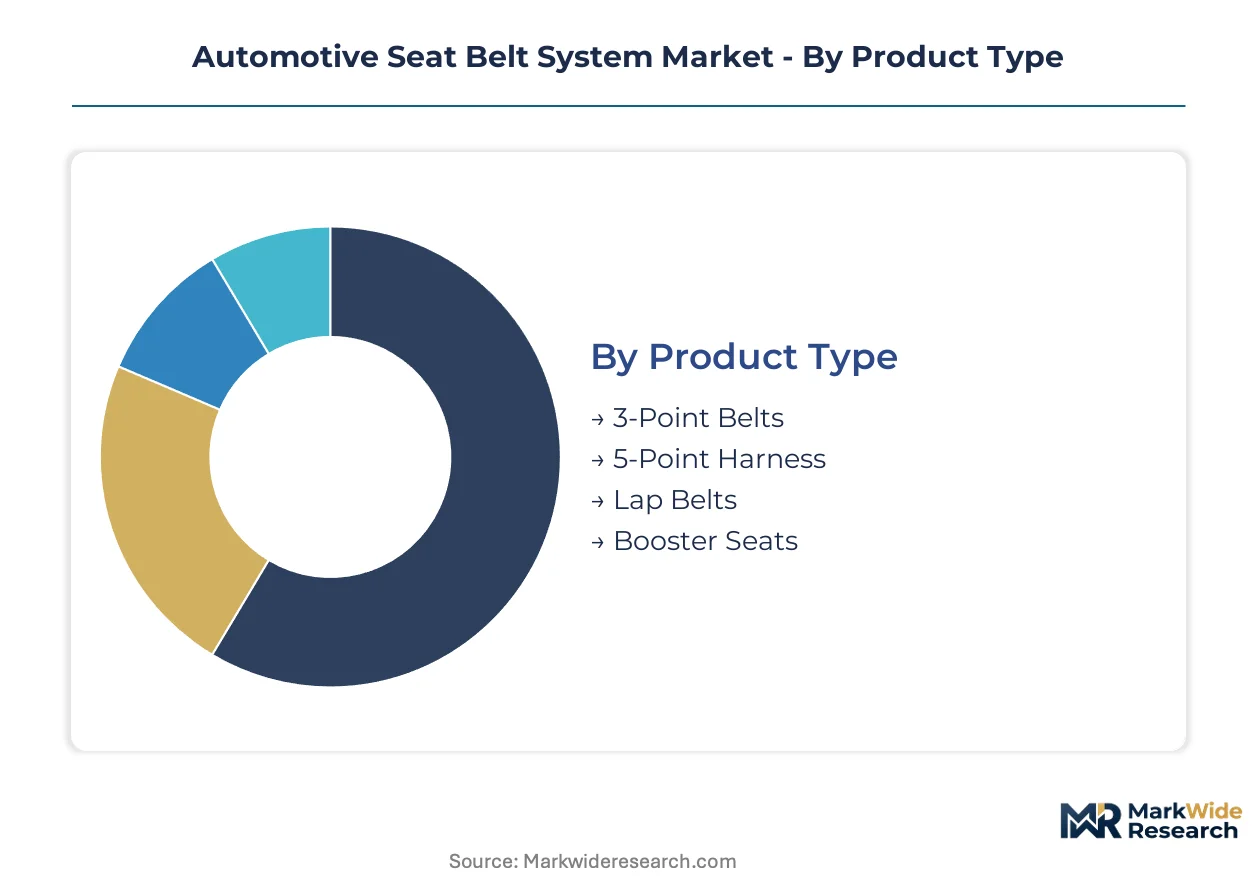
Seat belt system procurement splits across divergent certification pathways, with ECE R16 anchorage mandates applying unevenly across product configurations. Technology tiers separate volume production from margin-intensive premium installations, while end-user channels dictate warranty liability and telemetry integration requirements.
Product Type:
ECE R16 and NHTSA FMVSS 209 impose distinct webbing strength and anchorage test protocols on each configuration, with three-point variants facing streamlined homologation compared to harness systems.
- 3-Point Belts:Polyester webbing with retractor-integrated load limiting dominates passenger vehicle installations across China and Germany. C-NCAP five-star requirements are accelerating pretensioner penetration in domestic Chinese EV lineups.
- 5-Point Harness:Motorsport-derived restraint systems with camlock or latch-link buckle mechanisms serve child safety seats and performance vehicle niches. FMVSS 213 child restraint mandates in the US sustain specialized procurement volumes despite limited vehicle fitment.
- Lap Belts:Two-point configurations persist in commercial vehicle rear seating and certain agricultural equipment categories. SAMR's GB 14166 load-limiter requirements now extend to these installations, eliminating grandfathered exemptions.
- Booster Seats:Belt-positioning devices with rigid lower anchor attachments interface with vehicle LATCH systems. European ECE R44 and R129 regulations govern dynamic testing for this accessory category separately from primary restraint systems.
Three-point belts sit at the top of the volume ranking, with smart belt-enabled variants climbing the fastest.
Technology:
Cost tiering separates commodity retractor mechanisms from electromechanical pretensioner modules, with smart belt systems commanding 3-4x unit pricing against baseline configurations.
- Retractor Mechanism:Emergency locking retractors with vehicle-sensitive or webbing-sensitive spool control constitute the volume foundation. German and Japanese metal-forming specialists concentrate precision torsion bar production for this segment.
- Load Limiter:Torsion bar and clutch-based force-limiting devices reduce thoracic injury risk during high-severity collisions. European assembly plants specify these for driver positions under ECE R16's upgraded dynamic testing protocols.
- Pretensioner:Pyrotechnic or electromechanical spool-tensioning systems remove slack milliseconds before impact. South Korean EV platforms are adopting these at accelerated rates for C-NCAP scoring optimization.
- Smart Belt:Capacitive occupancy sensing and buckle-state telemetry integrate restraint systems with predictive crash networks. California fleet operators are unbundling these modules from OEM contracts for unified parc management.
Retractor mechanisms anchor volume procurement, while smart belt technology is gaining share fastest among premium EV architectures.
End User:
Application-specific requirements fragment procurement authority, with vehicle assemblers and tier-1 suppliers negotiating divergent warranty and telemetry terms.
- OEMs:Brand-holding manufacturers specify restraint systems through platform engineering teams, integrating modules with vehicle electrical architectures. Direct procurement concentrates among Detroit Three, German premium groups, and Chinese state-owned vehicle enterprises.
- Aftermarket:Replacement webbing and retractor assemblies serve collision repair channels and safety upgrade installations. Southeast Asian aging vehicle parcs are driving demand for telemetry-enabled retrofit kits.
- Tier-1 Suppliers:Autoliv, ZF, and Joyson Safety Systems manufacture restraint modules for OEM assembly line fitment. These entities bear homologation liability and manage sub-tier webbing and metal component sourcing.
- Vehicle Assemblers:Contract manufacturers without captive engineering capabilities rely on tier-1 specification packages. This channel is expanding in India's PLI-supported auto component corridors.
OEMs command the largest procurement volumes, with aftermarket channels expanding most quickly through fleet disintermediation trends.
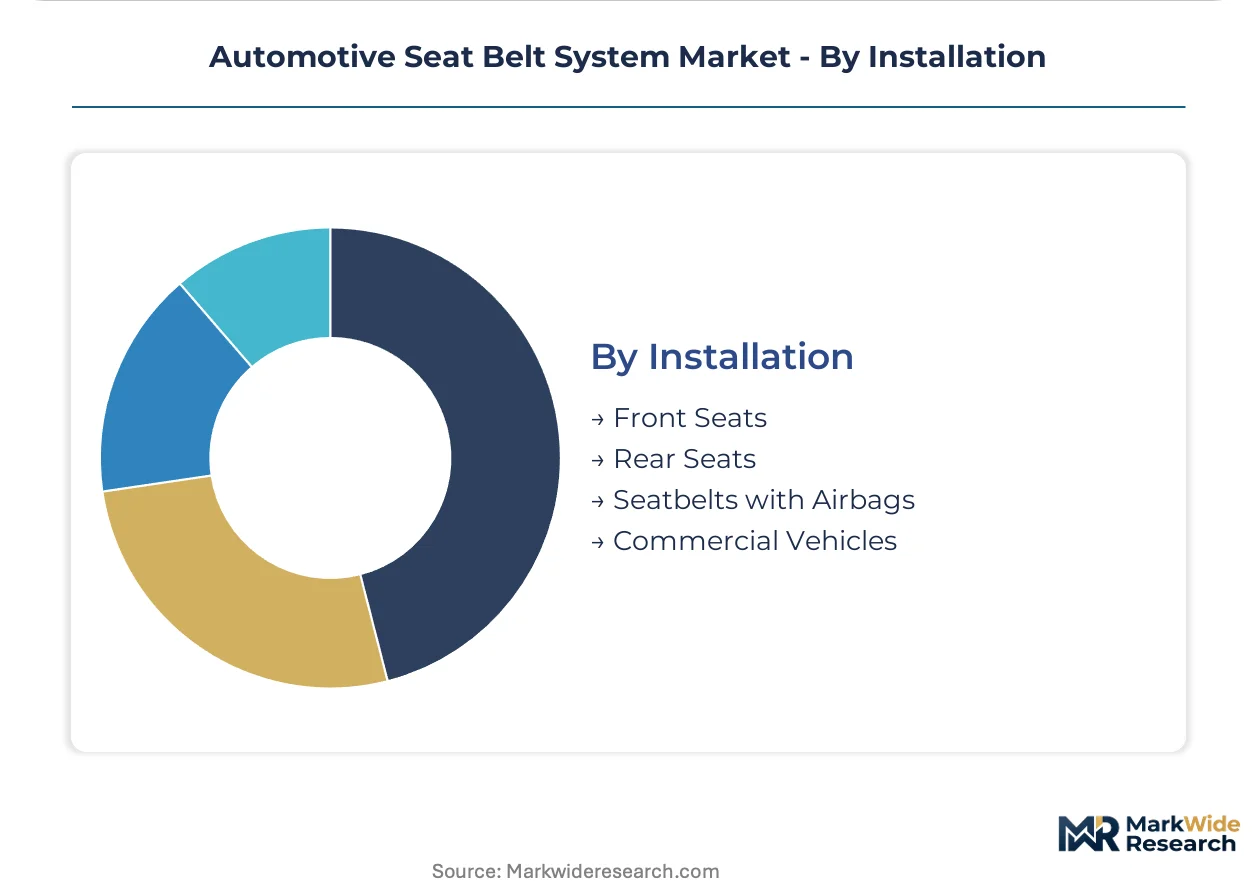
Installation:
Geography within vehicle cabins determines sensor placement complexity and wiring harness routing, with front positions absorbing predictive restraint technology first.
- Front Seats:Driver and passenger positions integrate pretensioners, load limiters, and buckle switches as standard equipment. NHTSA's pending FMVSS 209 updates are tightening flame resistance for battery-proximate seating in US-bound EVs.
- Rear Seats:Outboard positions increasingly match front-seat specification for C-NCAP and Euro NCAP scoring, while center positions often retain simpler retractor-only configurations.
- Seatbelts with Airbags:Inflatable restraint systems integrated into webbing or buckle assemblies serve luxury vehicle lineups. These require dual homologation under ECE R16 and airbag-specific UN regulations.
- Commercial Vehicles:Heavy-duty trucks and buses specify high-durability webbing with reinforced anchorages for occupant masses exceeding passenger car norms. India's commercial vehicle safety mandates are accelerating load-limiter adoption in this segment.
Front seats retain the highest technology penetration, with rear outboard positions showing the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is driving manufacturing relocation as suppliers seek jurisdictions with streamlined homologation pathways and lower compliance costs. China's GB 14166 load-limiter mandates and India's PLI incentives are pulling assembly capacity away from European facilities burdened by ECE R16's dynamic testing overhead. This geographic redistribution is reshaping procurement networks for tier-one restraint module suppliers.
China
Domestic EV brands pursuing C-NCAP five-star ratings are accelerating pretensioner-equipped variant procurement. SAMR's GB 14166 standard now requires load-limiter performance verification for all new passenger vehicle certifications. Shanghai and Guangdong province assembly corridors concentrate Joyson Safety Systems manufacturing capacity for BYD and NIO lineups.
Germany
Premium OEM engineering teams specify integrated restraint modules with predictive crash preparation capabilities. KBA enforces ECE R16 anchorage mandates with upgraded dynamic testing protocols that compel mounting point redesigns. Stuttgart and Wolfsburg automotive clusters host ZF Friedrichshafen AG precision metal-forming operations for torsion bar production.
United States
NHTSA's pending FMVSS 209 updates are tightening flame resistance thresholds for battery-proximate seating positions in EVs. Detroit Three OEMs are qualifying alternative halogen-free polymer treatments ahead of enforcement. Michigan and Ohio assembly corridors concentrate Autoliv Inc. supply relationships for F-150 Lightning and Silverado EV programs.
India
Commercial vehicle safety mandates are accelerating load-limiter adoption in heavy-duty truck and bus segments. The PLI scheme for auto components creates localized manufacturing incentives for advanced restraint system assembly. Tamil Nadu and Maharashtra auto component corridors are attracting greenfield capacity for tier-one module production.
South Korea
Hyundai Motor Group and Kia EV platforms are adopting electromechanical pretensioners at accelerated rates for C-NCAP scoring optimization. MFDS-aligned vehicle safety regulations support harmonized testing with UN protocols. Gyeonggi-do and Busan-Ulsan manufacturing belts concentrate Hyundai Mobis Co., Ltd. capacity for integrated safety node production.
Automotive Seat Belt System Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers establish dedicated EV architecture lines alongside legacy ICE-derived platforms. The market structure consolidates around three global tier-one manufacturers with captive metal-forming capabilities, supplemented by regional specialists serving domestic OEMs. Two strategic archetypes define competitive positioning: integrated safety node architects and precision component specialists. Geographic expansion into India's PLI corridors and technology licensing partnerships for smart belt telemetry represent the dominant competitive moves.
Within the integrated safety node tier, Autoliv Inc., ZF Friedrichshafen AG, and Joyson Safety Systems exemplify contrasting geographic anchoring strategies. Autoliv Inc. occupies a position aligned with Detroit Three and German premium OEM supply relationships. ZF Friedrichshafen AG represents European engineering-intensive positioning through load-limiter technology concentration. Joyson Safety Systems exemplifies China-centric scale manufacturing for domestic EV brand procurement. These three entities collectively illustrate how tier-one suppliers are navigating platform-level integration pressures while defending specification authority against electronics integrators entering the predictive restraint domain.
| Leading Market Players |
|---|
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Joyson Safety Systems |
| Continental AG |
| Hyundai Mobis Co., Ltd. |
| Robert Bosch GmbH |
| Toyoda Gosei Co., Ltd. |
| Denso Corporation |
| Tokai Rika Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned precision metal-forming specialists in Germany and Japan anchor torsion bar production for load limiters, concentrating supply-side pricing power while compressing margins for tier-one assemblers lacking captive forging capabilities. This ownership structure reinforces long-term contracting discipline with OEMs, insulating input costs from spot volatility in high-tenacity polyester feedstocks.
Pricing Analysis
Direct-to-OEM contract pricing dominates procurement, with three-tier pricing structure across premium, standard, and economy levels separating smart belt modules from retractor-only configurations. Price differentiation hinges on ECE R16 certification grade and volume scale, with China's domestic EV brands showing highest price sensitivity due to C-NCAP scoring-driven specification tradeoffs. Cost compression in standard-tier retractor mechanisms is intensifying because of raw material concentration among Asian petrochemical suppliers.
Supply Chain Analysis
Refurbishment flows for collision-damaged retractor assemblies remain underdeveloped, creating stranded inventory in aftermarket channels across Southeast Asia. Manufacturing concentrates in China, Germany, and South Korea, with precision metal forming for torsion bars drawing from captive facilities in Stuttgart and Wolfsburg automotive clusters. Single-source vulnerability in high-tenacity polyester webbing feeds from Asian petrochemical suppliers. Distribution runs through tier-one module suppliers rather than direct OEM relationships for vehicle assembler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with fleet operators unbundling procurement from full-vehicle contracts and tilting demand toward telemetry-integrated premium specifications.
For Market Incumbents: Anticipate margin compression from electronics integrators entering predictive restraint domains by deepening backward integration into precision metal forming and securing exclusive platform engineering relationships with German premium OEMs. Capacity addition in India's PLI-supported corridors defends specification authority against emerging regional assemblers.
For New Entrants and Emerging Players: GB 14166 in China opens a window for localized load-limiter assembly serving BYD and NIO supply chains, with aftermarket smart retrofit kits for aging vehicle parcs across Southeast Asia representing the most penetrable white-space target. A direct fleet-operator go-to-market angle bypasses entrenched OEM procurement gatekeepers.
For Investors and Strategic Acquirers: Tier-one automotive electronics suppliers are the most active acquirer in this space, seeking restraint module capabilities to complete integrated safety node portfolios. Over the long-term viability window, target acquisition candidates include precision metal-forming specialists with ECE R16 certification infrastructure and existing relationships with Stuttgart engineering clusters. Monitor NHTSA FMVSS 209 enforcement timing as inflection indicator for halogen-free webbing reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | EV-dedicated architectures from Hyundai and Kia consolidate restraint module specifications across vehicle lineups. |
| Backward Integration | Autoliv's captive torsion bar production insulates margin pressure from German and Japanese metal-forming specialists. |
| Geographic Manufacturing Footprint | Joyson Safety Systems' Shanghai and Guangdong capacity captures C-NCAP-driven procurement from domestic Chinese EV brands. |
| Software-Defined Vehicle Investment | Predictive crash preparation networks eliminate standalone ECUs and compress addressable market for discrete restraint controllers. |
| Long-term Supply Agreement | Fleet operators in California and Texas consolidate specification authority through direct tier-one relationships for unified parc management. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down tier-one supplier capacity tracking forms the analytical core. Primary interviews with OEM platform engineers, tier-one procurement directors, aftermarket distributors, and dealership operations specialists combined with secondary validation from NHTSA rulemaking dockets, ECE R16 type approval databases, vehicle production registries, and SAMR GB standard filings. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of pretensioner penetration rates and load-limiter adoption curves informs the projection framework across the analysis window. Segmentation dimensions include propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional regulatory cluster. CAGRs derive from fitted adoption curves rather than extrapolated historical growth. Industry-specific forecast inputs encompass C-NCAP scoring methodology revisions and ECE R16 dynamic testing protocol updates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory harmonization failures between UN protocols and China's GB 14166 standard. Practitioners should monitor NHTSA FMVSS 209 enforcement timing and India's PLI scheme disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Europe Adaptive Steering Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Driver Attention Alert Systems Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Lane Departure Warning (LDW) Market
Automotive Safety and Security Systems
Air Brake System Market