
 India Two Wheeler Market | 2026-2036
India Two Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
India Two Wheeler Market Outlook
BIS certification under AIS-156 for electric two-wheelers is bifurcating the competitive landscape between legacy internal combustion manufacturers and new energy entrants. Hero MotoCorp leverages its sprawling rural dealership network to sustain volume leadership across the 100cc to 150cc motorcycle segment. Ola Electric competes aggressively on software-defined vehicle architecture, while Bajaj Auto anchors its position through deep backward integration into component manufacturing at its Pune and Aurangabad facilities.
Two-wheelers encompass motorized vehicles with engine displacements ranging from sub-50cc mopeds to 350cc-plus performance motorcycles, serving India's last-mile mobility needs across dense urban corridors and poorly connected rural roads. The scooter category dominates urban female workforce participation and short-haul family transport, while the 100cc to 150cc motorcycle segment retains structural importance in agrarian economies where load-carrying durability and fuel efficiency determine purchase decisions. Electric bike volumes are accelerating fastest among fleet operators and delivery services, though economy-price internal combustion models still capture the deepest margin pools through spare parts and servicing ecosystems.
BIS enforces AIS-140 telematics and battery safety standards that shape product development timelines, while the Ministry of Road Transport and Highways administers FAME-II subsidy eligibility criteria that directly alter effective consumer pricing. CEA guidelines on battery swapping infrastructure and state-level EV policies from Maharashtra and Gujarat further fragment the regulatory terrain. Stakeholders must monitor how PLI scheme disbursement timelines intersect with tightening local content requirements to determine manufacturing location and technology partnership strategies.
Market Dynamics
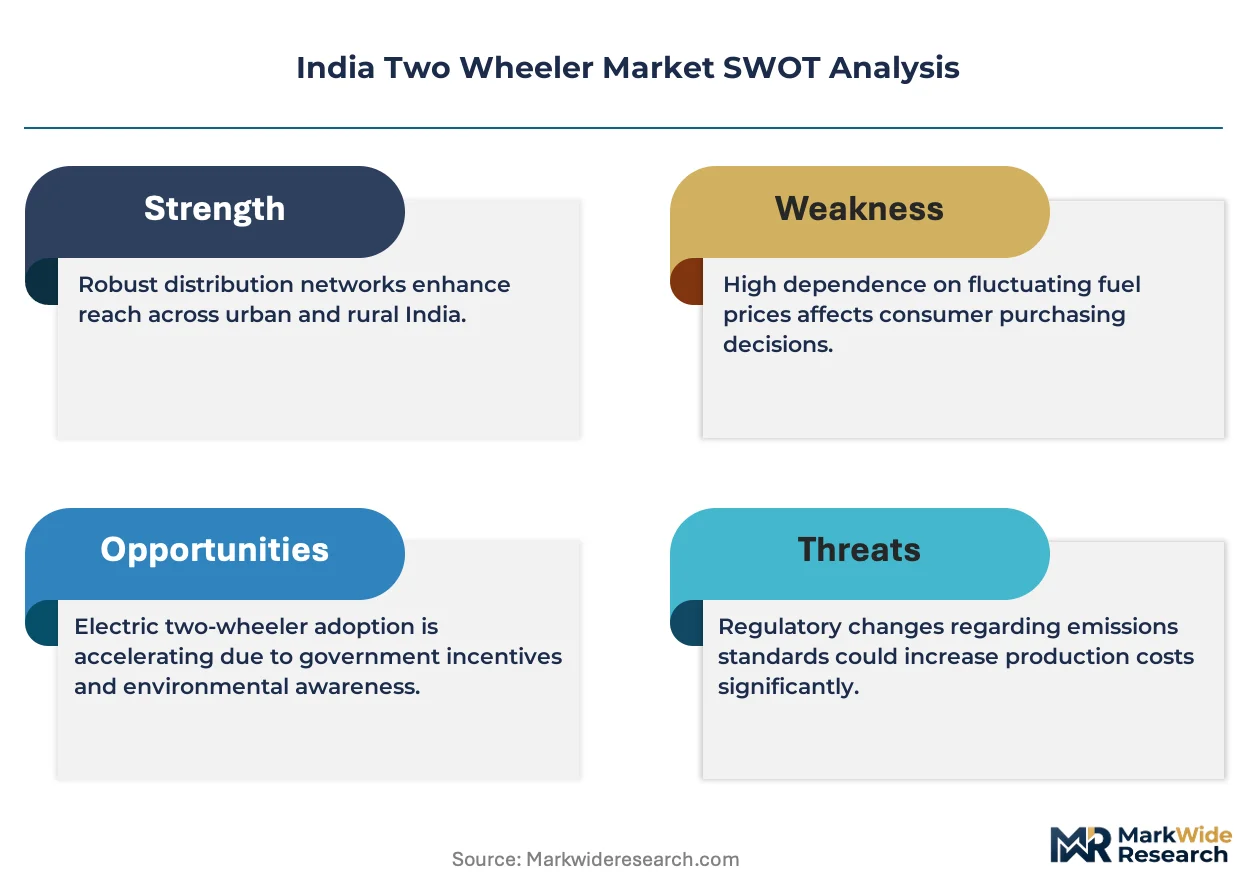
BS6 Phase II emission norms are forcing a fundamental recalibration of engine architecture across India's two-wheeler manufacturing base, compressing development timelines while elevating compliance costs for legacy internal combustion platforms.
Growth Catalysts
- FAME-II subsidy framework:Central government incentives reduce effective consumer pricing for electric two-wheelers, accelerating fleet operator adoption in urban logistics corridors.
- Rural replacement cycles:Agrarian economies in Maharashtra and Gujarat are upgrading aging 100cc motorcycles as emission compliance tightens resale viability of pre-BS6 inventory.
- Battery swapping infrastructure:CEA guidelines enabling standardized interchange stations are reducing range anxiety among delivery service operators in dense metropolitan zones.
Market Restraints
- Lithium-ion import dependence:Cell manufacturing concentration in East Asian supply chains exposes assemblers to currency volatility and shipping cost surges.
- AIS-156 certification timelines:BIS testing protocols for electric two-wheelers extend product launch windows by four to six months versus internal combustion equivalents.
- Petrol price elasticity:Sustained fossil fuel subsidies in neighboring economies sustain parallel grey market imports of non-compliant vehicles across porous border zones.
Strategic Opportunities
- Tamil Nadu production clustering:State EV policy incentives and port proximity are attracting component suppliers to co-locate with original equipment manufacturers.
- Software-defined vehicle architecture:Over-the-air update capability enables recurring revenue streams through feature unlocking and predictive maintenance subscriptions.
- Last-mile fleet electrification:E-commerce delivery aggregators are consolidating procurement volumes to negotiate preferential pricing and dedicated service networks.
Industry Challenges
- Power electronics talent scarcity:Motor controller and battery management system design expertise concentrates in Bengaluru and Hyderabad, creating wage inflation for tier-2 manufacturers.
- Dealer network retraining:Legacy internal combustion service infrastructure requires capital-intensive tooling upgrades to handle high-voltage diagnostics and thermal runaway protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Two Wheeler Market |
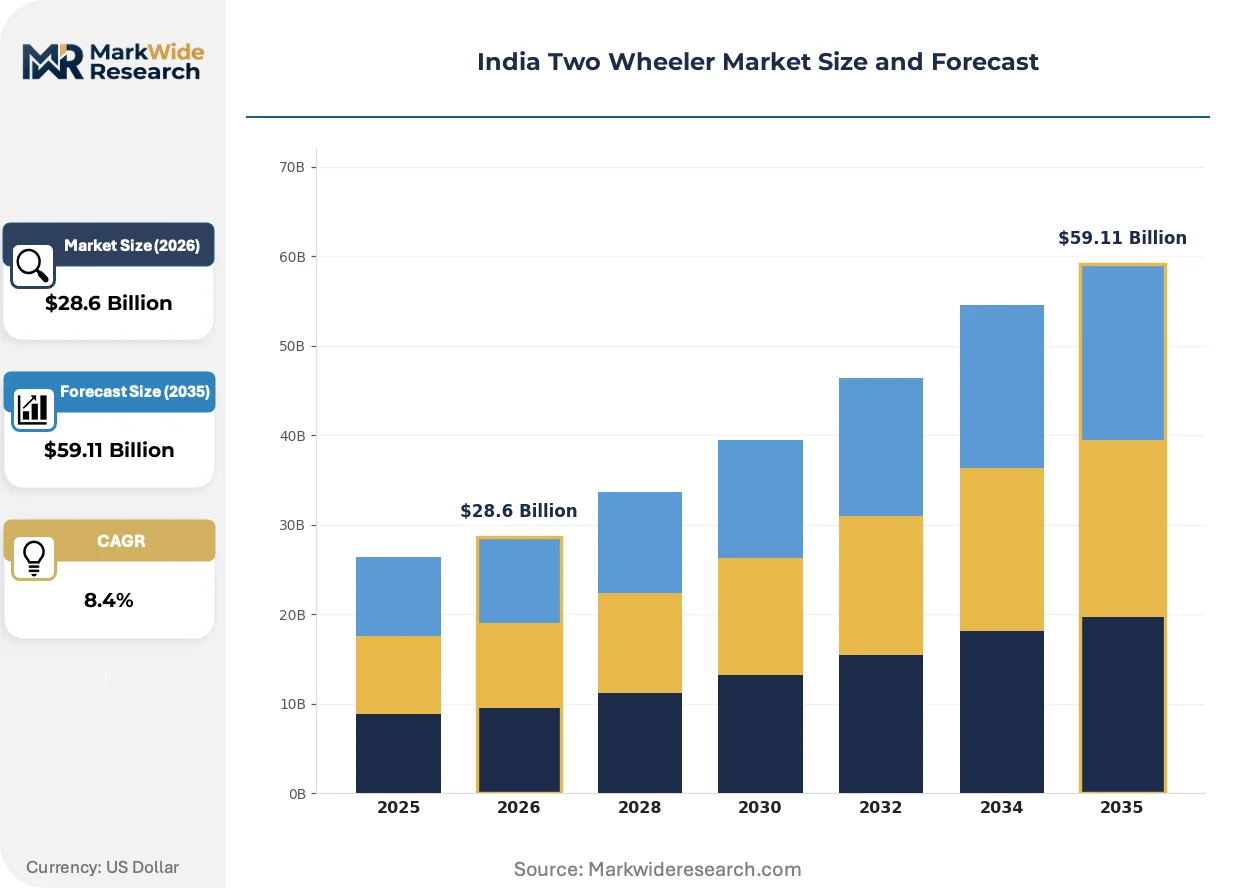
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Motorcycle, Scooter, Moped, Electric Bike Engine Capacity: Below 100cc, 100cc to 150cc, 150cc to 250cc, Above 250cc End User: Individual Users, Fleet Operators, Commercial Users, Delivery Services Price Segment: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Bajaj Auto, Suzuki Motor, Hero MotoCorp, Ather Energy, India Yamaha Motor, Honda Motorcycle and Scooter India, Royal Enfield, Ola Electric, TVS Motor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Two Wheeler Market Strategic Shifts
Powertrain electrification is fragmenting competitive advantage away from mechanical engineering toward software integration and thermal management, rewarding players with captive battery chemistry partnerships.
Silicon carbide MOSFETs in motor controllers are decomposing the traditional cost-performance tradeoff in electric two-wheeler drivetrains. Tier-1 suppliers in Pune and Chennai are qualifying these wide-bandgap semiconductors for 125cc-equivalent platforms. The technology is decomposing incumbent advantages in internal combustion refinement by enabling comparable acceleration response at lower bill-of-materials cost.
BIS enforcement of AIS-140 telematics mandates is mandating GPS-enabled connectivity modules across all electric two-wheeler categories. Manufacturers must integrate cellular modems and cloud architecture into entry-price segments previously optimized for hardware minimization. The regulation compresses margin structures most severely for economy-focused assemblers lacking in-house firmware development teams.
Aggregator-led procurement consolidation is concentrating demand among fleet operators who negotiate multi-year service contracts bundling vehicles, charging infrastructure, and predictive maintenance. Traditional dealership networks face disintermediation as direct enterprise sales channels capture high-volume accounts. This pattern is most pronounced in Bengaluru and Mumbai where delivery platform density supports dedicated swapping station networks.
India Two Wheeler Market Segmentation
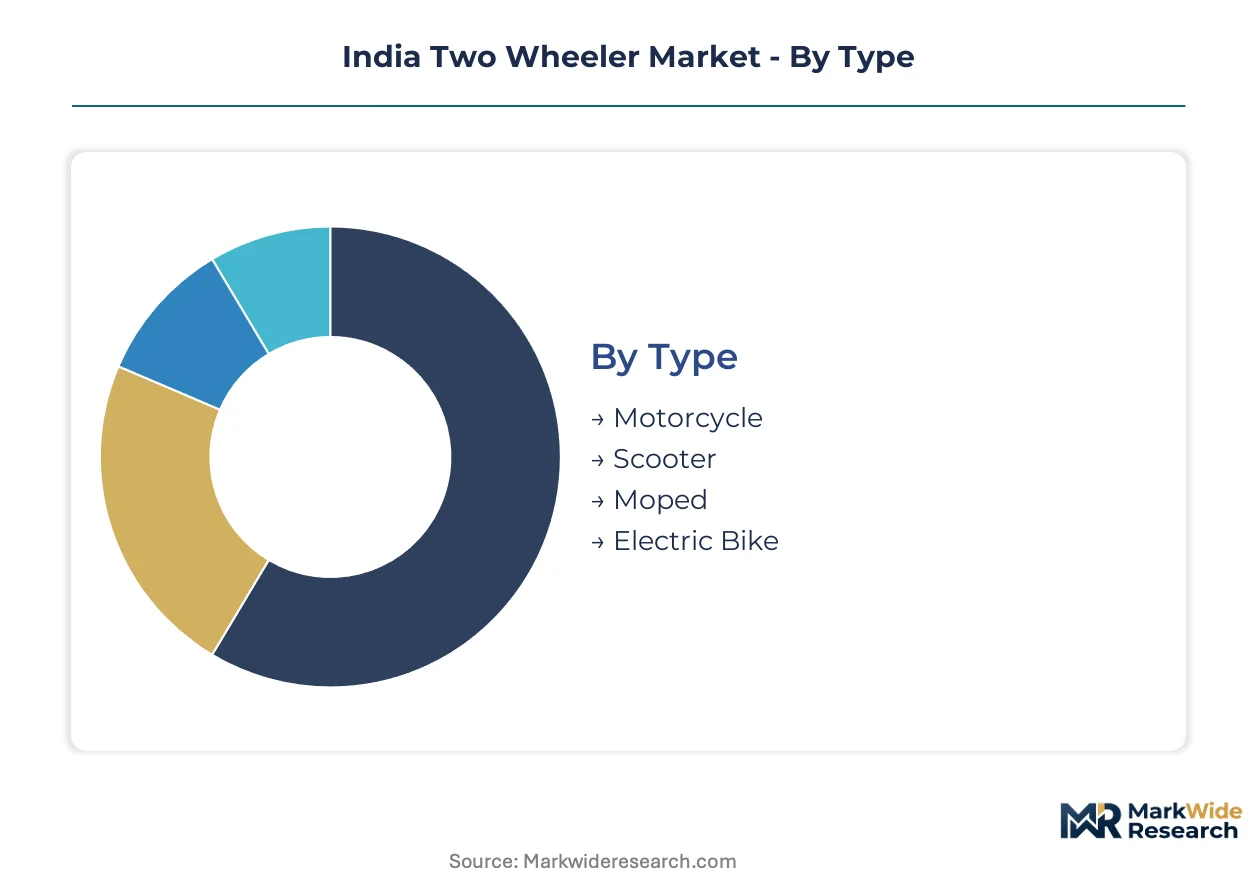
Segmentation in India's two-wheeler market exposes divergent vulnerability to electrification and emission compliance costs. Manufacturers must calibrate platform strategies across displacement tiers and ownership models that face radically different substitution economics.
Type:
Electric drivetrains exert asymmetric substitution pressure across vehicle architectures, with urban-centric formats facing earlier displacement than load-optimized rural platforms.
- Motorcycle:Frame structures prioritize load-bearing durability and fuel efficiency for agrarian and semi-urban applications. Demand concentrates in Maharashtra's sugar belt and Gujarat's cotton-growing districts where 100cc to 150cc models serve dual-purpose transport and cargo hauling.
- Scooter:Step-through architecture with under-seat storage dominates female workforce participation in Bengaluru, Mumbai, and Delhi-NCR urban corridors. Battery swapping compatibility is becoming a decisive procurement criterion for delivery fleet operators consolidating volumes.
- Moped:Sub-50cc platforms with bicycle-derived pedals retain niche penetration in tier-3 towns and peri-urban zones with licensing exemptions.
- Electric Bike:Lithium-ion powered two-wheelers with hub or mid-drive motors are accelerating fastest among logistics aggregators and last-mile delivery services in dense metropolitan zones.
Motorcycle retains volume leadership; Electric Bike holds the steepest expansion curve.
Engine Capacity:
Cost tier stratification determines compliance burden distribution, with smaller displacement segments absorbing proportionally heavier BS6 Phase II engineering overhead relative to sticker price.
- Below 100cc:Entry commuter motorcycles and mopeds with single-cylinder air-cooled engines face severe margin compression from catalytic converter and fuel injection mandates. Rural replacement demand in Uttar Pradesh and Bihar sustains volumes despite shrinking profitability.
- 100cc to 150cc:The structural heartland of Indian motorcycling combines tractable power output with service network ubiquity. Hero MotoCorp and Bajaj Auto anchor production at Chakan, Pune, and Manesar facilities serving this displacement band.
- 150cc to 250cc:Performance-oriented commuters and entry sport bikes target urban male demographics with higher disposable income and brand consciousness.
- Above 250cc:Premium motorcycles with liquid cooling and multi-cylinder configurations serve enthusiast segments concentrated in Mumbai, Delhi, and Bengaluru.
100cc to 150cc dominates unit economics; Below 100cc faces the steepest margin erosion from regulatory compliance.
End User:
Procurement centralization intensity separates fragmented individual ownership from consolidated fleet purchasing with divergent service and financing requirements.
- Individual Users:Owner-operated vehicles purchased through dealer networks with two-wheeler financing from NBFCs and banking subsidiaries. Maharashtra and Gujarat account for disproportionate individual ownership penetration relative to national population share.
- Fleet Operators:Asset-light logistics platforms and mobility aggregators procuring standardized vehicle pools with integrated charging or swapping infrastructure. Tamil Nadu's EV policy incentives are attracting fleet operator headquarters and deployment concentration.
- Commercial Users:Small business proprietors utilizing two-wheelers for goods transport, passenger ferrying, or mobile vending operations across tier-2 and tier-3 urban centers.
- Delivery Services:E-commerce and quick-commerce last-mile specialists with high-utilization, high-depreciation asset models demanding predictive maintenance and rapid battery interchange.
Individual Users retain absolute volume; Fleet Operators are climbing the fastest on electrification-driven procurement consolidation.
Price Segment:
Margin structure and regulatory exposure diverge sharply across pricing tiers, with economy segments subsidizing compliance costs through spare parts ecosystems while premium tiers absorb upfront technology investment.
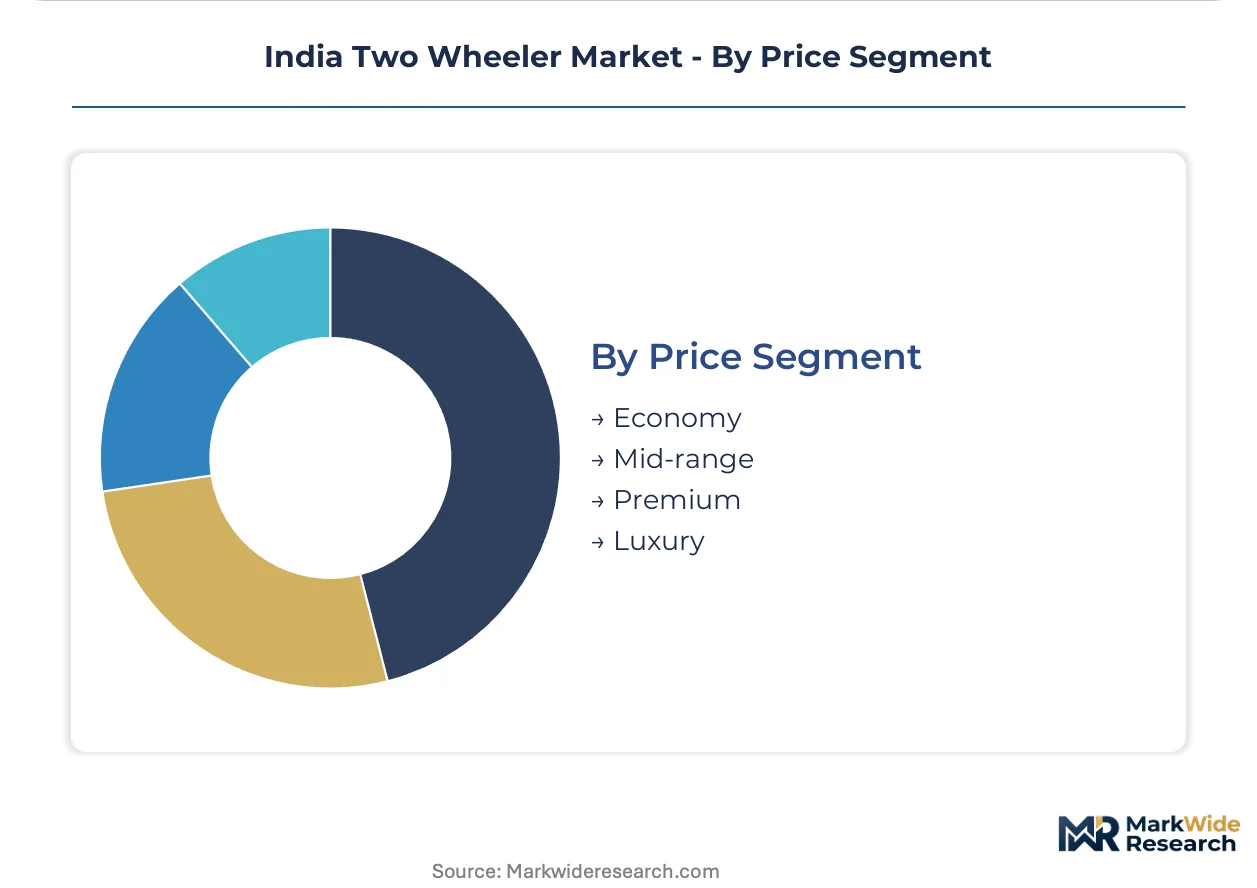
- Economy:Sub-70,000 INR entry motorcycles and scooters optimized for hardware minimization and service accessibility. Hero MotoCorp's Splendor and HF Deluxe platforms define this tier with deepest rural penetration.
- Mid-range:70,000 to 150,000 INR vehicles balancing feature content with affordability, capturing urban commuter upgrade cycles and semi-urban first-time buyers.
- Premium:150,000 to 300,000 INR motorcycles and scooters with differentiated styling, connected features, and enhanced performance positioning.
- Luxury:Above 300,000 INR imported or locally assembled performance and lifestyle motorcycles with limited volume but disproportionate brand halo effects.
Economy retains volume leadership; Premium holds the steepest expansion curve on feature upgrade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level EV policies and PLI scheme disbursements are redistributing manufacturing investment across India's automotive corridors. Sub-regional concentration reflects divergent infrastructure readiness and incentive arbitrage.
Maharashtra
Chakan and Pune host the densest internal combustion engine manufacturing clusters. The state EV policy offers capital subsidies for battery pack assembly facilities. Aurangabad's industrial belt is attracting power electronics suppliers to co-locate with legacy motorcycle producers.
Gujarat
Ahmedabad-Vadodara corridor concentrates two-wheeler exports through Mundra port access. The state's single-window clearance mechanism compresses project commissioning timelines. Sanand's automotive zone is repurposing vacant passenger vehicle capacity for electric scooter assembly.
Tamil Nadu
Hosur and Sriperumbudur anchor electric two-wheeler production with dedicated EV parks. The state's advanced chemistry cell PLI allocation is securing cathode active material suppliers. Chennai's component ecosystem is pivoting from four-wheeler ancillaries to two-wheeler motor and controller manufacturing.
Karnataka
Bengaluru's software talent density enables battery management system firmware development. The state's EV policy mandates 100 percent renewable energy for manufacturing incentives. Whitefield's electronics manufacturing cluster is qualifying silicon carbide semiconductor packaging for motor controllers.
Haryana
Manesar's industrial belt sustains Hero MotoCorp's integrated engine and transmission production. The state's freight corridor connectivity supports just-in-time component logistics to North Indian markets. Gurugram's startup ecosystem is incubating battery swapping technology ventures.
India Two Wheeler Market Competitive Environment
Listed leaders compete with private specialists across capital access and technology agility. The market exhibits a three-tier structure: integrated conglomerates with captive component supply, pure-play electric entrants with software differentiation, and regional assemblers serving price-sensitive rural segments. Strategic archetypes include backward-integrated engine manufacturers, asset-light platform aggregators, and swapping-infrastructure operators. Dominant competitive moves center on dealer network expansion for service capture and battery chemistry partnerships for cell cost reduction.
Within the integrated conglomerate tier, Hero MotoCorp and Bajaj Auto occupy positions defined by rural distribution depth and engine manufacturing heritage. Among electric pure-plays, Ather Energy exemplifies the software-defined vehicle archetype with over-the-air capability. Ola Electric sits within the platform-aggregator model, leveraging direct-to-consumer channels to bypass traditional dealership structures. These three anchors represent divergent bets on electrification timing and customer acquisition economics.
| Leading Market Players |
|---|
| Bajaj Auto |
| Suzuki Motor |
| Hero MotoCorp |
| Ather Energy |
| India Yamaha Motor |
| Honda Motorcycle and Scooter India |
| Royal Enfield |
| Ola Electric |
| TVS Motor |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Chakan and Pune engine plants shapes margin floors across the 100cc to 150cc segment, concentrating pricing power with Hero MotoCorp and Bajaj Auto while compressing tier-2 assemblers. Scale economies in internal combustion manufacturing anchor price resistance against electric substitution, though lithium-ion import dependence erodes this advantage in premium tiers.
Pricing Analysis
Certification level under AIS-156 and BS6 Phase II compliance creates the primary spread between economy and premium tiers. Three-tier pricing structure across premium, standard, and economy levels captures 300,000-plus INR performance motorcycles, 70,000 to 150,000 INR mid-range commuters, and sub-70,000 INR rural workhorses. Price differentiation stems from connected feature bundling and after-sales service network depth. Cost compression in the below-100cc segment intensifies because catalytic converter mandates absorb disproportionate sticker price share. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership optimization, while individual rural buyers in Uttar Pradesh and Bihar remain most responsive to upfront payment thresholds.
Supply Chain Analysis
Nhava Sheva port congestion and Red Sea transit volatility expose lithium cell importers to inventory cost surges. Manufacturing concentrates in China, South Korea, and Japan for cathode active materials, while India anchors final assembly and power electronics packaging. The supply chain draws from East Asian cell production, domestic aluminum die-casting at Hosur, and Gujarat-based forging operations for chassis components. Single-source vulnerability concentrates in NCM battery chemistry procurement from Chinese suppliers. Distribution runs through Hero MotoCorp's 6,000-plus rural touchpoints and Ola Electric's direct-to-consumer platform, with fleet sales bypassing traditional dealership structures entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery swapping interoperability is collapsing the traditional vehicle-ownership model into a platform-access economy, rewarding players who control charging infrastructure rather than manufacturing assets alone.
For Market Incumbents: Shield dealer network relevance by retrofitting 3,000-plus service points with high-voltage diagnostics capability before electric volumes cross critical mass. Anchor backward integration into motor controller production at Pune facilities to defend margin position against silicon carbide commoditization. Prioritize certification investment under AIS-156 to maintain access to FAME-II subsidy channels as eligibility tightens. For New Entrants and Emerging Players: Anchor in Tamil Nadu's EV policy jurisdiction to capture PLI scheme disbursements and port-proximity logistics savings. Target fleet operator procurement consolidation in Bengaluru and Mumbai where delivery platform density supports dedicated swapping station economics. Pursue software-defined vehicle architecture with over-the-air revenue streams as the primary go-to-market angle against hardware-centric incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among swapping-infrastructure operators and predictive maintenance platform providers, suggesting superior cash-flow quality versus pure manufacturing exposure. Acquisition targets should demonstrate captive battery chemistry partnerships or firmware development teams in Bengaluru and Hyderabad. Monitor BIS enforcement timelines for AIS-140 telematics mandates as the inflection signal for connectivity-module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode material contracts with Korean suppliers secure FAME-II local content compliance. |
| Software-Defined Vehicle Investment | Over-the-air capability enables subscription revenue from feature unlocking and thermal management updates. |
| Charging Infrastructure Partnership | CEA-guided swapping station networks reduce fleet operator range anxiety in dense metropolitan zones. |
| Geographic Manufacturing Footprint | Tamil Nadu EV park clustering attracts power electronics suppliers to co-locate with final assembly. |
| Platform Standardization | Common battery pack architectures across scooter and motorcycle formats amortize R&D across higher volumes. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, dealership operations heads, and fleet aggregator logistics directors anchored the qualitative base. Primary interviews with BIS certification specialists and CEA policy implementation officers cross-validated regulatory trajectory assumptions. Secondary sources included SIAM production databases, Ministry of Road Transport registration statistics, DGFT import-export records, and state EV policy notification documents. Bottom-up vehicle segment sizing triangulated against top-down macroeconomic elasticity models.
Sensitivity analysis tested forecast robustness across FAME-II subsidy continuation scenarios, lithium price volatility bands, and BS6 Phase II enforcement intensity variations. The projection framework modeled displacement tier, propulsion architecture, end-user ownership model, and regional production cluster as core segmentation dimensions. CAGRs were derived from regression against historical replacement cycle patterns and urbanization-driven fleet adoption curves. Industry-specific inputs incorporated PLI scheme disbursement timelines and state-level EV incentive arbitrage effects.
Decision-makers should treat outputs as directional under stable subsidy policy and stable lithium supply chain assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as BIS certification timelines and battery swapping standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
China Motorcycle ADAS Market