
 Motorcycle Advanced Rider Assistance System Market | 2026-2036
Motorcycle Advanced Rider Assistance System Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Advanced Rider Assistance System Market Foresight
Subscription-based over-the-air feature activation is hardening as the dominant commercial model in motorcycle ARAS, shifting revenue from one-time hardware sales to recurring software revenue pools. Robert Bosch GmbH leverages its tier-1 automotive sensor heritage to anchor integrated radar-camera fusion stacks for European OEMs. Continental AG sustains deep manufacturing scale in micromobility perception systems, while ZF Friedrichshafen AG competes through specialized motorcycle-specific adaptive cruise control modules that occupy a narrow but defensible technical niche.
Motorcycle Advanced Rider Assistance System denotes an integrated electronic safety architecture comprising millimeter-wave radar, CMOS image sensors, inertial measurement units, and edge-computing control modules designed to detect road hazards, monitor rider intent, and autonomously intervene through braking, throttle, or steering assist. Collision avoidance technology leads current OEM fitment programs due to its direct insurance premium reduction value, while lane keeping assist represents the fastest-expanding segment as electric motorcycle platforms with ride-by-wire architectures enable smoother electromechanical steering intervention. Camera components capture disproportionate margin pools because image sensor resolution and thermal management specifications drive unit economics more sharply than commodity radar transceivers.
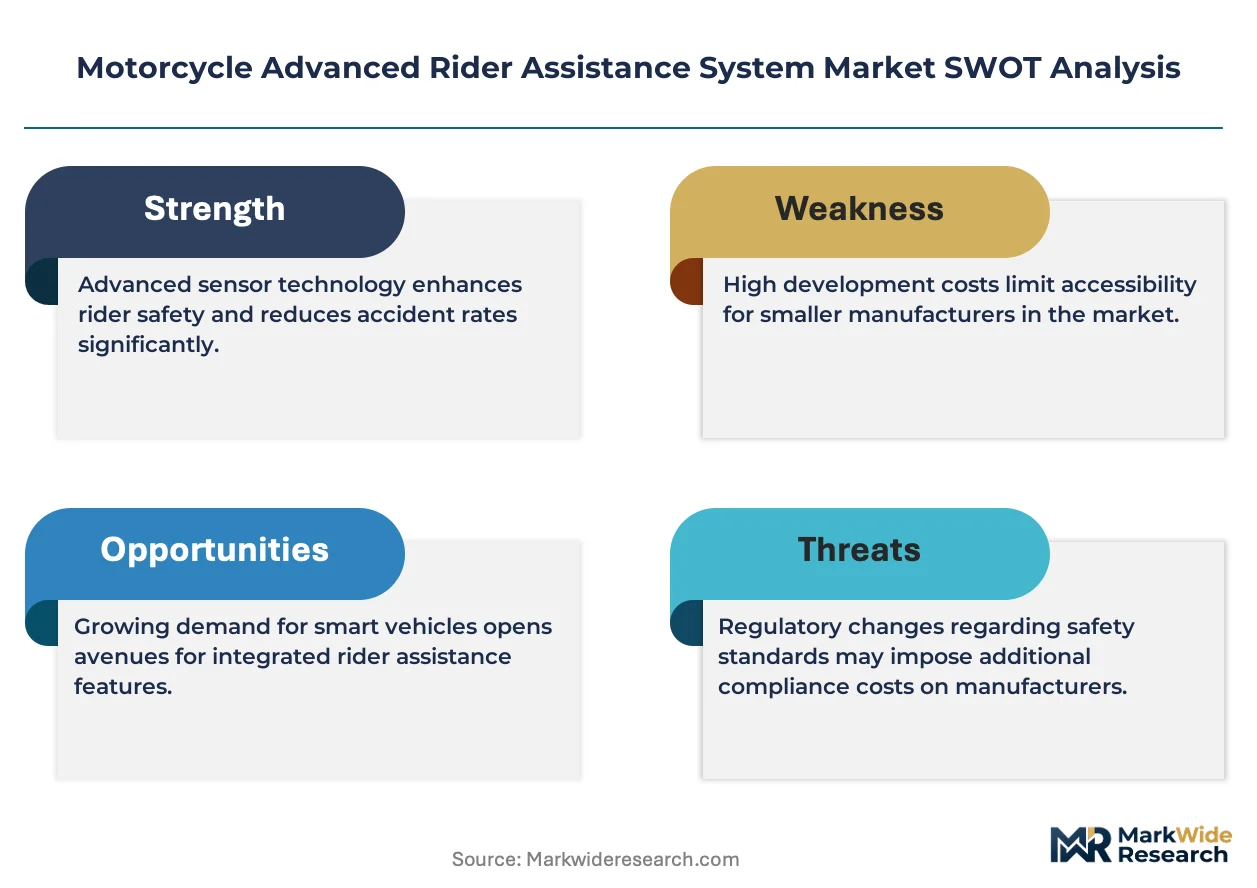
NHTSA in the United States, the EU's General Safety Regulation framework, and Japan's METI vehicle type approval standards collectively mandate escalating autonomous emergency braking and blind-spot detection requirements for new motorcycle registrations. These regulatory trajectories force OEMs to pre-integrate ARAS hardware at the factory rather than rely on aftermarket fitment, compressing supplier qualification timelines and elevating barriers for non-certified component vendors. Stakeholders must monitor whether software liability frameworks evolve faster than hardware homologation cycles, as this divergence will determine which tier-1 suppliers can capture recurring revenue from feature-upgradable platforms versus those locked into fixed-specification production contracts.
Market Dynamics
Factory-fit sensor pre-integration is compressing supplier qualification timelines as Euro 5+ and NHTSA mandates force OEMs to abandon aftermarket retrofit strategies in favor of embedded ARAS architectures.
Growth Catalysts
- Euro 5+ emissions and safety mandates:European regulators now require autonomous emergency braking and blind-spot detection for new motorcycle registrations, eliminating homologation shortcuts for non-compliant suppliers.
- Electric motorcycle ride-by-wire architectures:EV powertrain platforms from Zero Motorcycles and Energica enable smoother electromechanical steering intervention, accelerating lane keeping assist deployment.
- Insurance premium reduction programs:German and Japanese underwriters now discount collision avoidance-equipped motorcycles by 8-15%, creating direct consumer price elasticity for ARAS fitment.
Market Restraints
- CMOS image sensor cost volatility:Thermal management specifications for motorcycle-grade cameras require automotive-tier silicon, exposing BOMs to foundry capacity constraints in Taiwan and South Korea.
- Radar transceiver supply concentration:77GHz MMIC fabrication concentrates among three European and US semiconductor foundries, creating single-source vulnerability for tier-2 module assemblers.
- Software liability framework fragmentation:No harmonized international standard governs fault attribution when AI-driven collision avoidance systems misclassify road debris, chilling OEM deployment timelines.
Strategic Opportunities
- India's premium motorcycle segment:Royal Enfield and Bajaj Auto are localizing 650cc+ platforms with export-grade safety content, creating first-mover advantage for ARAS suppliers qualifying under BIS and CDSCO parallel tracks.
- Subscription-based over-the-air activation:BMW Motorrad and KTM are piloting feature-unlocking models that convert one-time hardware sales into recurring software revenue pools.
- Lidar-radar fusion for urban mobility:Solid-state lidar cost curves are converging with millimeter-wave radar, enabling 360-degree perception for lane-splitting scenarios in dense European traffic.
Industry Challenges
- Edge AI firmware certification timelines:UN ECE R79 and R157 homologation cycles for steering and braking intervention systems now exceed 18 months, compressing model-year integration windows.
- Sensor calibration skill scarcity:Multi-modal fusion architectures require technicians trained in both radar signal processing and computer vision pipelines, a combination rare in traditional motorcycle service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Advanced Rider Assistance System Market |
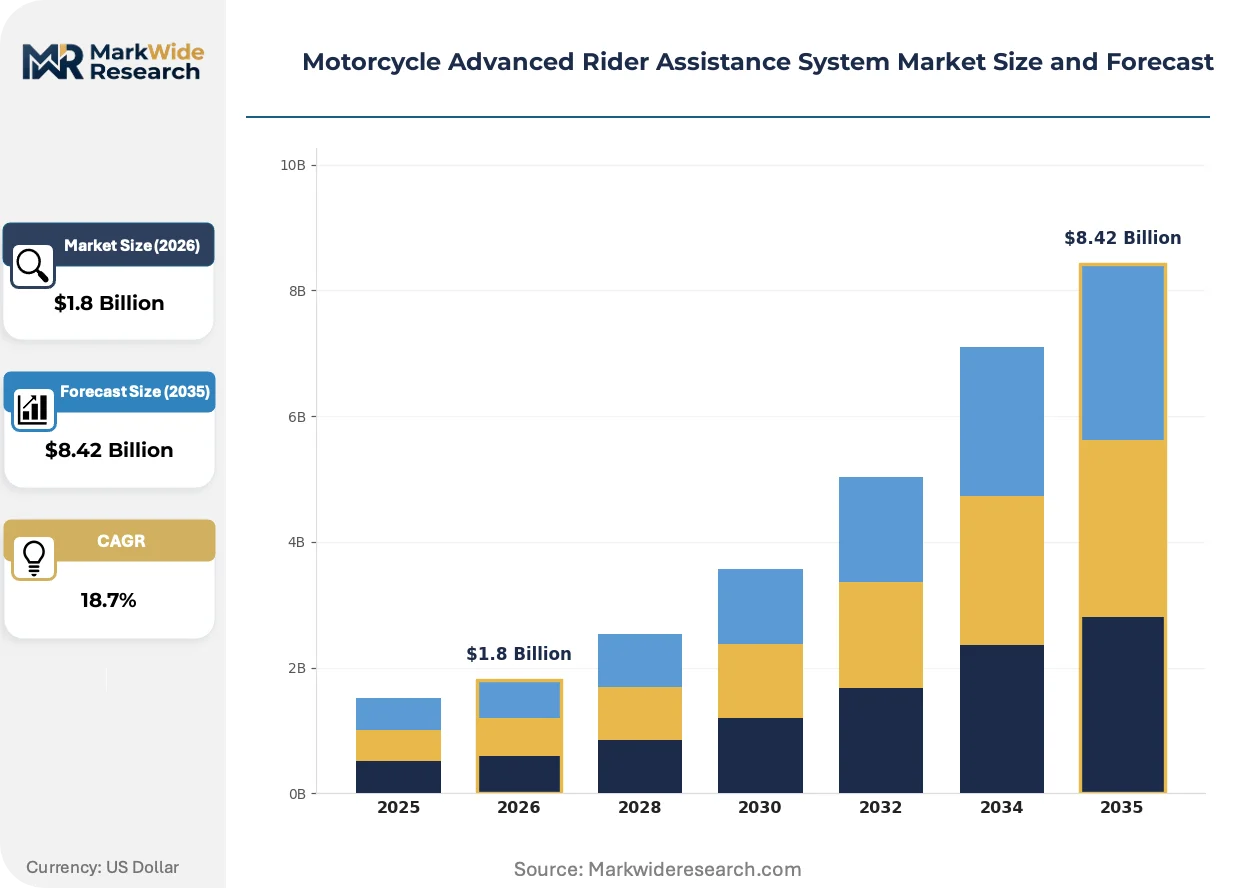
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Adaptive Cruise Control, Collision Avoidance, Lane Keeping Assist, Traction Control Component: Cameras, Sensors, Control Units, Displays End User: Riders, OEMs, Fleet Operators, Training Institutions Application: Safety Enhancements, Navigation Assistance, Performance Tuning, Maintenance Alerts |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, BMW Motorrad, Ducati Motor Holding, Honda Motor Co., Yamaha Motor Co., Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Advanced Rider Assistance System Market Shifts & Advancements
Software-defined rider assistance platforms are redirecting R&D investment from fixed-function hardware stacks toward updatable perception algorithms, collapsing the traditional tier-1 supplier value chain into vertically integrated OEM control.
Millimeter-wave radar is converging with solid-state lidar in next-generation perception stacks. Premium European OEMs now specify fused 77GHz and 905nm architectures for adaptive cruise control in heavy traffic. This convergence is compressing the addressable market for single-modality radar specialists while elevating margin capture for sensor fusion software vendors.
The EU's General Safety Regulation framework now mandates blind-spot detection and advanced emergency braking for all new motorcycle types from 2026. This industrial consequence forces factory-fit pre-integration rather than aftermarket retrofit, accelerating consolidation among homologated tier-1 suppliers. German OEMs are responding by locking in multi-year sensor fusion contracts with incumbent automotive suppliers.
Fleet procurement by motorcycle taxi operators is displacing individual retail as the dominant demand channel for ARAS-equipped vehicles in Southeast Asian urban corridors. Grab and Gojek now specify collision avoidance as mandatory for high-mileage fleet additions. This channel shift concentrates volume among white-label platform suppliers in Indonesia and Vietnam.
Motorcycle Advanced Rider Assistance System Market Segmentation
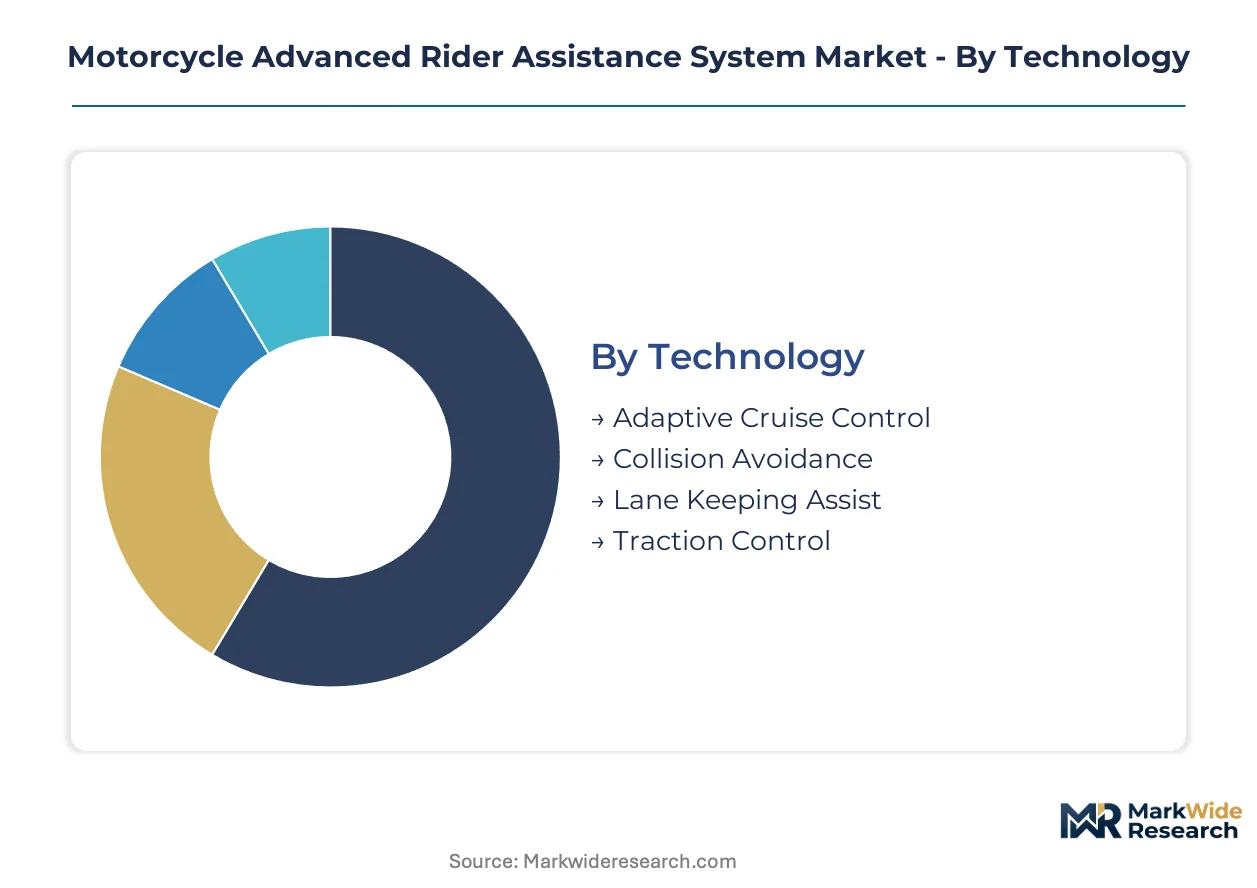
Segmentation in motorcycle ARAS reveals how technical complexity and regulatory pressure concentrate value across discrete hardware and software layers. Suppliers must calibrate portfolio depth against homologation timelines that vary sharply by technology type and end-use channel.
Technology:
Supply concentration in radar fusion stacks and AI perception software is redirecting tier-1 R&D budgets toward integrated platforms rather than discrete function modules.
- Adaptive Cruise Control:Combines 77GHz radar with vehicle-to-vehicle distance algorithms. German OEMs now mandate this for touring motorcycles sold domestically, driven by KBA type-approval requirements and fleet procurement specifications from long-distance courier services.
- Collision Avoidance:Integrates millimeter-wave radar and CMOS image sensors for autonomous emergency braking. Demand clusters in Japan where METI safety mandates and insurance premium reductions create direct consumer price elasticity for factory-fit systems.
- Lane Keeping Assist:Electromechanical steering intervention enabled by ride-by-wire architectures. Electric motorcycle platforms from California and Italian manufacturers accelerate deployment.
- Traction Control:Wheel-slip mitigation through throttle modulation and ABS integration. Standard fitment on premium sportbikes from Bavarian and Austrian OEMs.
Collision Avoidance absorbs the bulk of installed capacity; Lane Keeping Assist is expanding most quickly.
Component:
Cost tier differentiation in semiconductor sourcing is fragmenting supplier margins, with automotive-grade silicon commanding premium positioning against industrial-tier alternatives.
- Cameras:CMOS image sensors with thermal management specifications for vibration and weather exposure. Resolution requirements above 2MP concentrate demand among Taiwanese and South Korean foundry customers.
- Sensors:Millimeter-wave radar transceivers and inertial measurement units. 77GHz MMIC fabrication concentrates among three European and US semiconductor foundries, creating single-source vulnerability.
- Control Units:Edge-computing modules running sensor fusion algorithms. German tier-1 suppliers anchor integrated stacks for European OEM homologation programs.
- Displays:TFT and OLED instrument clusters relaying ARAS alerts to riders. Motorcycle-grade specifications demand wider temperature operating ranges than automotive equivalents.
Cameras capture disproportionate margin pools; Control Units are climbing the fastest as software-defined architectures displace fixed-function hardware.
End User:
Customer type is reshaping procurement patterns, with fleet operators displacing individual retail as the dominant volume channel in high-density urban corridors.
- Riders:Individual consumers purchasing factory-fit ARAS through OEM dealerships. German and Japanese underwriters discount collision avoidance-equipped motorcycles, creating purchase incentives.
- OEMs:Motorcycle manufacturers integrating ARAS at the factory to satisfy Euro 5+ and NHTSA mandates. Pre-integration compresses supplier qualification timelines and elevates barriers for non-certified vendors.
- Fleet Operators:Motorcycle taxi and delivery services specifying ARAS as mandatory for high-mileage vehicle additions. Grab and Gojek procurement concentrates volume among Indonesian and Vietnamese platform suppliers.
- Training Institutions:Rider safety schools deploying ARAS-equipped motorcycles for curriculum demonstration. Limited volume but high visibility for technology validation.
OEMs absorb the bulk of installed capacity; Fleet Operators are gaining share fastest as urban mobility platforms scale.
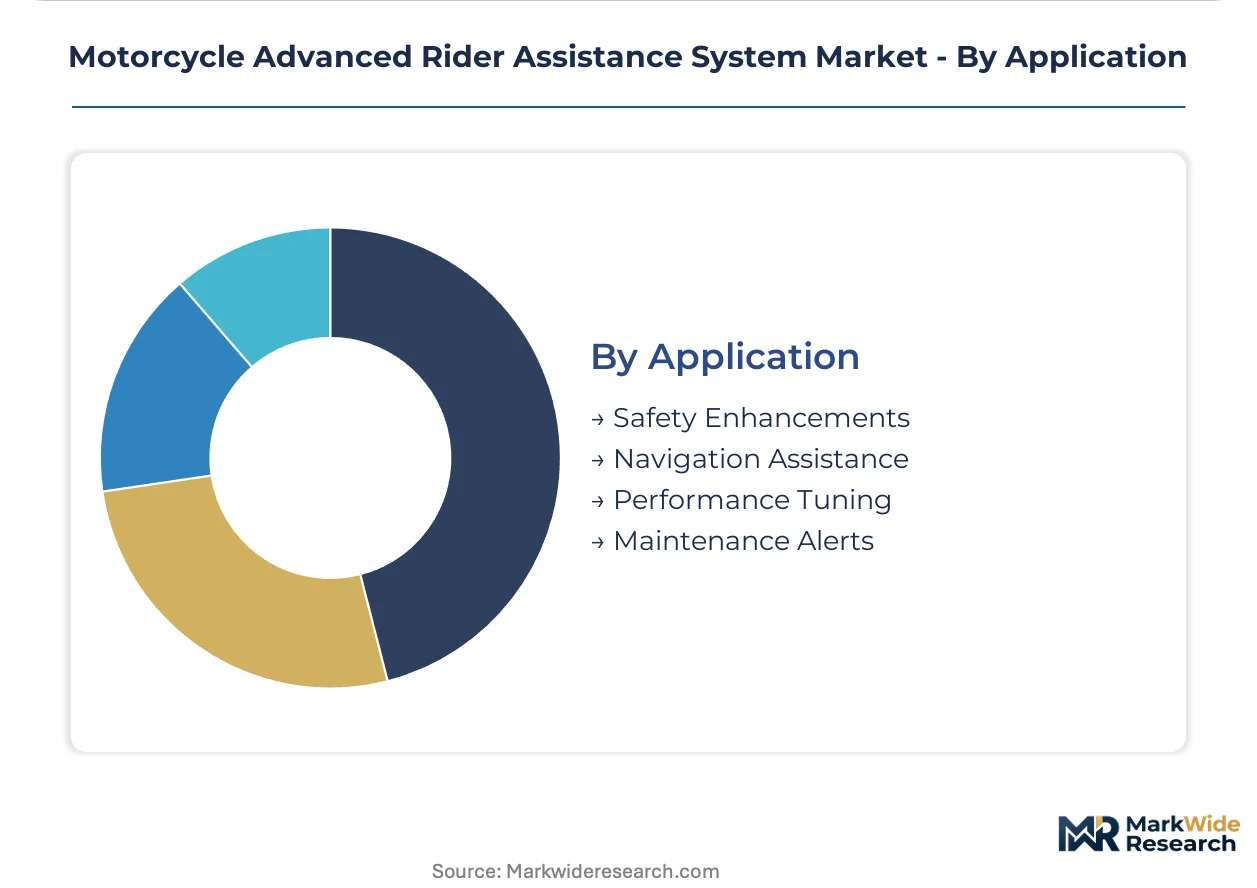
Application:
Application maturity varies sharply, with safety functions commanding near-universal fitment while predictive maintenance remains nascent.
- Safety Enhancements:Autonomous emergency braking, blind-spot detection, and collision warning systems. Regulatory mandates in the EU, US, and Japan force baseline fitment across all premium motorcycle registrations.
- Navigation Assistance:ARAS-integrated turn-by-turn guidance with hazard alerts. Demand concentrates in touring motorcycles from German and Japanese OEMs.
- Performance Tuning:Real-time suspension and powertrain adjustment based on road condition sensing. Track-day enthusiasts and sportbike segments drive adoption.
- Maintenance Alerts:Predictive diagnostics for brake wear, tire pressure, and component fatigue. Subscription-based over-the-air activation models piloted by Bavarian and Austrian OEMs.
Safety Enhancements absorb the bulk of installed capacity; Maintenance Alerts are expanding most quickly as software revenue models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European ARAS engineering density, housing Robert Bosch GmbH's radar fusion development centers alongside KBA certification laboratories that validate autonomous emergency braking systems for factory-fit deployment.
Germany
KBA type-approval requirements and fleet procurement from long-distance courier services drive adaptive cruise control demand. The EU General Safety Regulation mandates blind-spot detection from 2026. Baden-Württemberg's automotive corridor concentrates radar-camera integration facilities serving BMW Motorrad and KTM.
United States
NHTSA safety mandates and insurance premium reduction programs create direct consumer price elasticity for collision avoidance systems. The federal regulator now requires escalating autonomous emergency braking standards for new motorcycle registrations. California's electric motorcycle manufacturers leverage ride-by-wire architectures to accelerate lane keeping assist deployment.
Japan
METI vehicle type approval standards and underwriter discount programs of 8-15% for ARAS-equipped motorcycles shape procurement patterns. The ministry's safety mandates force OEMs to pre-integrate perception hardware at the factory. Tokyo-Yokohama's precision electronics cluster supplies CMOS image sensors with thermal management specifications for vibration-exposed motorcycle applications.
India
Royal Enfield and Bajaj Auto are localizing 650cc+ platforms with export-grade safety content, creating qualification opportunities under BIS and CDSCO parallel tracks. The country's national standards body and pharmaceutical regulator oversee parallel homologation pathways. Maharashtra's Pune-Nashik automotive corridor hosts emerging tier-2 module assembly for radar transceiver integration.
Indonesia
Grab and Gojek fleet procurement now specifies collision avoidance as mandatory for high-mileage motorcycle taxi additions. The country's national transport regulator enforces urban mobility safety standards for commercial operators. Jakarta's platform economy concentrates volume among white-label ARAS suppliers serving Southeast Asian mobility corridors.
Motorcycle Advanced Rider Assistance System Market Competitive Landscape
Capital-heavy semiconductor foundries compete with asset-light perception software designers for margin capture in motorcycle ARAS. The supplier base consolidates around three European tier-1 automotive incumbents with homologation track records, while Asian electronics conglomerates and specialized motorcycle OEMs occupy secondary tiers. Two strategic archetypes dominate: integrated sensor fusion stack providers and electric motorcycle-native platform developers. Competitive moves center on multi-year sensor fusion contract lock-ins and subscription-based over-the-air feature activation pilots.
Among German-based tier-1 suppliers, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG occupy positions representing the integrated stack archetype. Bosch leverages automotive radar heritage for European OEM programs. Continental sustains manufacturing scale in micromobility perception. ZF competes through specialized adaptive cruise control modules. Japanese conglomerates Denso Corporation, Honda Motor Co., and Yamaha Motor Co. exemplify the vertically integrated OEM tier, while BMW Motorrad and Ducati Motor Holding represent premium motorcycle manufacturers developing proprietary rider assistance platforms.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| BMW Motorrad |
| Ducati Motor Holding |
| Honda Motor Co. |
| Yamaha Motor Co. |
| Garmin Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap sensor module assemblers in Taiwan and South Korea exercise outsized pricing discipline over CMOS image sensor procurement, translating foundry capacity constraints into tiered margin capture across European and Japanese OEM supply contracts.
Pricing Analysis
Value-based pricing anchored to insurance premium reduction outcomes dominates collision avoidance system contracts, with German underwriters discounting ARAS-equipped motorcycles by 8-15% and creating direct consumer willingness-to-pay elasticity. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade silicon from industrial-tier alternatives and uncertified commodity components. Cost compression in camera modules is intensifying because thermal management specifications for motorcycle-grade applications require scarce foundry capacity. Fleet operators in Southeast Asia exhibit highest price sensitivity, while premium European OEMs absorb premium-tier positioning with minimal volume negotiation.
Supply Chain Analysis
Single-source vulnerability sits with 77GHz MMIC fabrication concentrated among three European and US semiconductor foundries, exposing tier-2 module assemblers to allocation risk during capacity crunches. Taiwan, South Korea, and Germany anchor CMOS image sensor and radar transceiver supply, with raw material dependencies spanning automotive-grade silicon wafers, precision optics, and vibration-hardened packaging substrates. Tariff exposure on semiconductor imports from East Asian fabrication hubs threatens cost stability for European module integrators. Distribution runs through homologated tier-1 supplier direct contracts to OEM platform engineering teams, bypassing traditional aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as Euro 5+ homologation timelines and 18-month UN ECE certification cycles force non-certified component vendors into acquisition or exit.
For Market Incumbents: Hedge against software liability framework fragmentation by diversifying R&D investment across multiple regulatory jurisdictions rather than single-market certification depth. Lock in multi-year sensor fusion contracts with Bavarian and Austrian OEMs before tier-2 Asian electronics conglomerates achieve KBA type-approval status. Prioritize backward integration into edge AI firmware development to capture recurring subscription revenue pools and displace fixed-specification hardware margins. For New Entrants and Emerging Players: Launch via white-label platform supply to Grab and Gojek fleet procurement specifications in Indonesia and Vietnam, where homologation barriers remain lower than European or Japanese OEM direct qualification. Target India's 650cc+ premium motorcycle localization programs under BIS and CDSCO parallel tracks as the most penetrable geography. Pursue lidar-radar fusion development for urban lane-splitting scenarios as a differentiated technical entry point against established radar-only incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized motorcycle-specific adaptive cruise control module developers with existing UN ECE R79 homologation track records in Baden-Württemberg's automotive corridor. Long-term viability across the next decade hinges on software-defined architecture transition capability rather than fixed-function hardware scale. Monitor NHTSA autonomous emergency braking mandate acceleration as the critical inflection signal for US market timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Stack Integration | Combines radar-camera-lidar perception into unified platforms for European OEM homologation. |
| Subscription-Based Feature Activation | Converts one-time hardware sales into recurring software revenue for BMW Motorrad and KTM pilots. |
| Electric Motorcycle Platform Partnership | Leverages ride-by-wire architectures from Zero Motorcycles for lane keeping assist deployment. |
| Regulatory Certification Fast-Track | Compresses UN ECE R79 and R157 homologation timelines below 18-month standard cycles. |
| Fleet Operator Direct Procurement | Captures high-volume channel shift through Grab and Gojek mandatory collision avoidance specifications. |
Research Methodology
Independent corroboration across tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distribution heads underwrites the qualitative findings on sensor fusion architecture preferences. Primary interviews with KBA certification laboratory technical leads, NHTSA regulatory affairs specialists, and fleet procurement managers at Southeast Asian mobility platforms combined with secondary validation from UN ECE homologation databases, vehicle production registries, and semiconductor foundry capacity disclosures. Bottom-up component demand modeling and top-down OEM fitment rate analysis triangulate volume estimates.
Rate-of-change decomposition across the projection horizon segments volume by technology type, component tier, end-user channel, and application maturity. Modeled dimensions include adaptive cruise control, collision avoidance, lane keeping assist, and traction control functions; cameras, sensors, control units, and displays; riders, OEMs, fleet operators, and training institutions; and safety enhancements, navigation assistance, performance tuning, and maintenance alerts. CAGRs derive from fitted adoption curves against regulatory mandate phase-in schedules and insurance premium reduction program expansion trajectories. Electric motorcycle ride-by-wire penetration rates and solid-state lidar cost convergence curves inform technology transition timing.
Regulatory mandate delay, semiconductor foundry capacity rationing, and software liability precedent uncertainty are the dominant revision risks that could compress or extend adoption timelines. Forecasts reflect documented assumptions on homologation cycle duration, OEM pre-integration commitment levels, and fleet operator procurement specification evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Spain E-Bike Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Fuel Cell Bikes Market