
 Europe Motorcycle ADAS Market | 2026-2036
Europe Motorcycle ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Motorcycle ADAS Market Analytics
EU General Safety Regulation (GSR 2019/2144) is realigning the cost-of-entry calculus for motorcycle OEMs by mandating advanced emergency braking and intelligent speed assistance systems. Robert Bosch GmbH leverages its radar portfolio to anchor Tier 1 supply relationships across German and Italian manufacturing clusters. Continental AG differentiates through integrated sensor fusion architectures that combine camera and radar inputs for urban collision scenarios. PIERER Mobility AG sustains in-house ADAS development for KTM and Husqvarna platforms, controlling a vertically integrated pipeline from prototype to production.
Europe Motorcycle ADAS encompasses electronic rider assistance systems engineered around millimeter-wave radar, stereoscopic cameras, and ultrasonic arrays operating at 24 GHz and 77-81 GHz bands, designed to mitigate single-vehicle crashes and multi-party collisions in variable European road conditions. Collision avoidance systems dominate current OEM fitment programs due to their direct alignment with GSR homologation requirements, while blind spot detection represents the fastest-growing product category as lane-splitting legality in France and Belgium creates distinctive rider safety needs. Camera systems capture disproportionate R&D investment because they enable multi-function platforms combining lane departure warning with traffic sign recognition, whereas radar systems retain structural importance for all-weather reliability across Nordic climates.
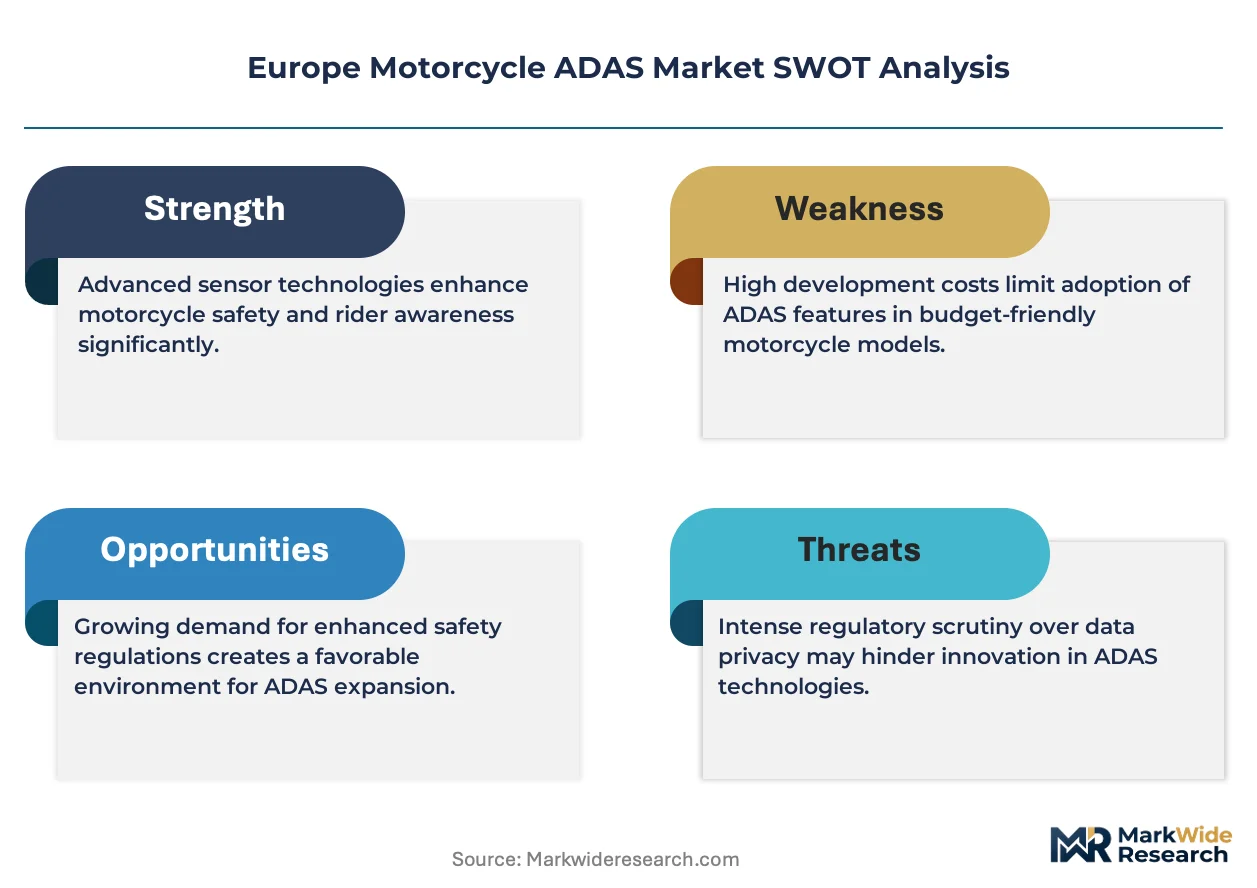
EMA's vehicle type-approval framework, ECE R157 for automatic lane-keeping, and the EU AI Act's risk classification for autonomous decision-making collectively shape product development timelines and liability structures for ADAS suppliers. The European Commission's periodic GSR enforcement reviews force continuous algorithmic recalibration to maintain homologation validity. Stakeholders must monitor the interplay between national motorcycle type-approval authorities and Brussels-level harmonization timelines, as divergence in implementation speed across member states fragments addressable market windows.
Market Dynamics
EU General Safety Regulation (GSR 2019/2144) is compressing OEM development cycles by mandating advanced emergency braking and intelligent speed assistance as baseline homologation requirements, forcing Tier 1 suppliers to accelerate radar-camera fusion architectures ahead of 2026 compliance deadlines.
Growth Catalysts
- GSR 2019/2144 Mandates:The EU's General Safety Regulation legally requires advanced rider assistance systems on all new motorcycle types, creating non-discretionary demand for collision avoidance and blind spot detection modules across European OEM fitment programs.
- Lane-Splitting Legality:France and Belgium permit motorcycle lane-filtering in dense urban corridors, generating distinctive safety requirements that accelerate blind spot detection adoption among fleet operators managing high-mileage delivery platforms.
- Millimeter-Wave Radar Maturation:77-81 GHz sensor platforms achieve cost parity with legacy 24 GHz systems while delivering superior angular resolution for urban collision scenarios, enabling multi-function ADAS architectures without proportional bill-of-materials expansion.
Market Restraints
- Semiconductor Supply Concentration:Radar-specific MMIC fabrication concentrates among a limited supplier base in Taiwan and South Korea, exposing European Tier 1s to allocation volatility during automotive demand surges.
- Sensor Calibration Complexity:Stereoscopic camera systems require precise factory alignment that degrades with handlebar vibration and fork compression, creating warranty exposure and service network training burdens.
- Homologation Timeline Friction:Divergent implementation speeds between Germany's KBA and France's ANSM for GSR secondary requirements fragment addressable market windows and force redundant certification investments.
Strategic Opportunities
- Poland and Czech Republic Manufacturing:Greenfield production facilities in Central European corridors offer labor cost arbitrage and proximity to expanding Eastern European motorcycle markets with nascent ADAS penetration.
- AI Act Risk Classification Alignment:Early compliance with the EU AI Act's autonomous decision-making frameworks positions suppliers for liability advantages as algorithmic rider assistance migrates toward higher automation levels.
- Radar-Camera Fusion Convergence:Integrated sensor architectures that combine 77 GHz radar with stereoscopic vision enable single-module platforms serving multiple GSR mandates, reducing OEM integration complexity and supplier SKU proliferation.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineering for ISO 26262-compliant automotive software remains concentrated among experienced practitioners, constraining development velocity for mid-tier suppliers.
- ECE R157 Adaptation Burden:Motorcycle-specific interpretation of automatic lane-keeping homologation standards requires extensive track testing and algorithmic recalibration, extending certification timelines beyond passenger car equivalents.
- Legacy Platform Integration:Retrofit compatibility with existing CAN bus architectures and power distribution systems complicates ADAS module design for model-year carryover motorcycles with limited electrical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Motorcycle ADAS Market |
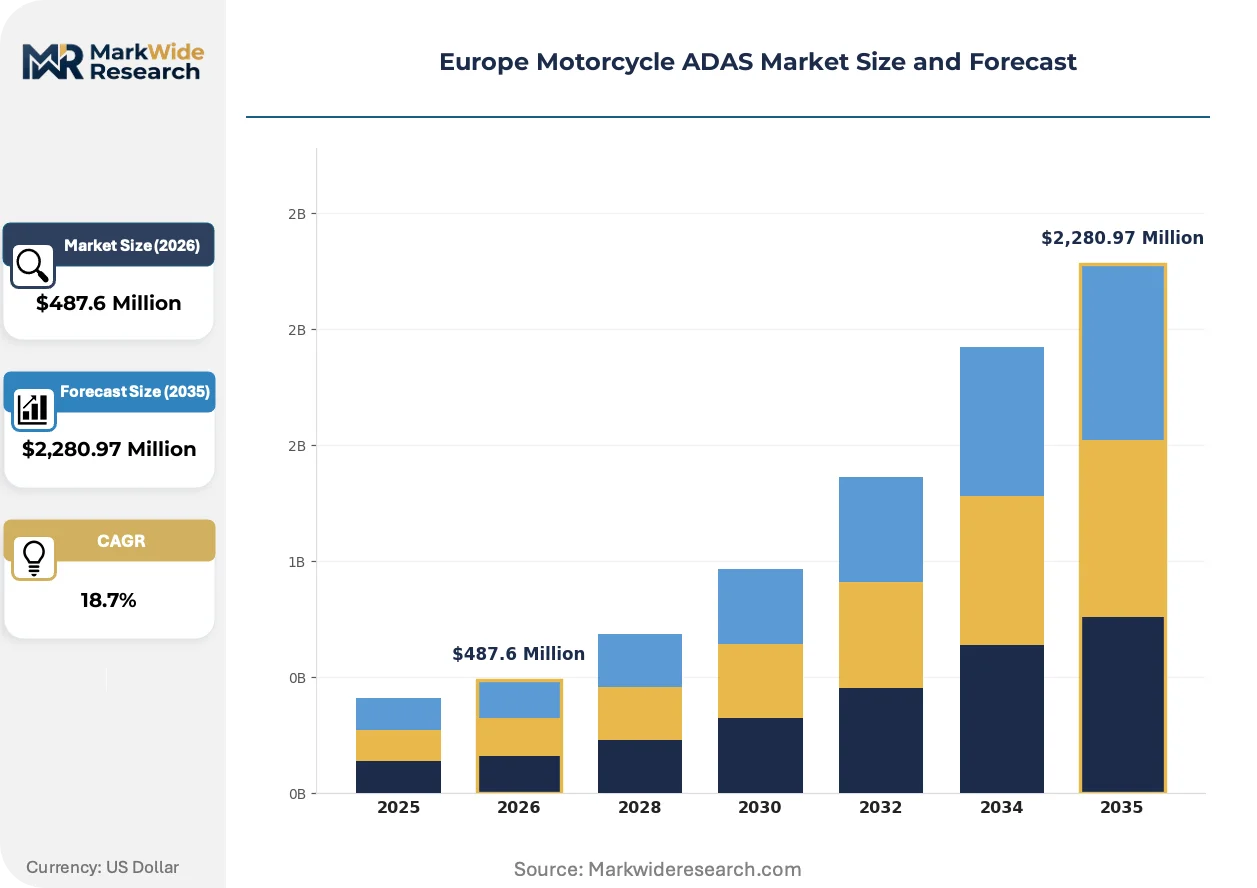
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,280.97 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Lane Departure Warning, Collision Avoidance, Blind Spot Detection Technology: Radar Systems, Camera Systems, LiDAR Systems, Ultrasonic Sensors End User: Riders, Fleet Operators, Motorcycle Manufacturers, Dealerships Installation: Aftermarket, OEM, Retrofit, Custom Fit |
| Companies Covered | Bayerische Motoren Werke AG, PIERER Mobility AG, Robert Bosch GmbH, BMW Motorrad, Honda Motor Co., Continental AG, Ducati Motor Holding, Hitachi Ltd., ZF Friedrichshafen AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Motorcycle ADAS Market Evolving Landscape
Algorithmic sensor fusion is displacing discrete single-safety-function modules as the dominant technical architecture, while procurement patterns favor vertically integrated subsystem suppliers capable of delivering homologation-ready platforms.
Millimeter-wave radar is consolidating its position as the foundational sensing layer for European motorcycle ADAS, with 77-81 GHz front-end modules now standard fitment for collision avoidance and adaptive cruise control functions. German and Italian OEMs specify these platforms across premium and mid-tier model ranges, compressing development timelines for camera-only alternatives. Tier 1 suppliers with captive radar portfolios capture disproportionate sourcing volume as multi-sensor fusion architectures become the default design pattern.
EMA's vehicle type-approval framework is tightening algorithmic transparency requirements through periodic GSR enforcement reviews, forcing continuous recalibration of automatic emergency braking decision thresholds. Suppliers must maintain version-controlled software documentation and validation datasets to preserve homologation validity across model-year updates. Nordic markets with extended winter operating conditions drive the most stringent all-weather performance specifications, influencing baseline radar sensitivity requirements for pan-European platforms.
Fleet procurement is fragmenting traditional OEM-direct sourcing relationships as large motorcycle taxi and delivery operators in Paris and Berlin establish direct technical collaboration with Tier 1 ADAS developers. These operators specify custom blind spot detection parameters and data logging requirements that diverge from retail consumer configurations. France's lane-splitting corridors generate the most distinctive sensor coverage specifications, with urban fleet managers prioritizing rear-quarter detection over highway-oriented adaptive cruise functionality.
Europe Motorcycle ADAS Market Segmentation
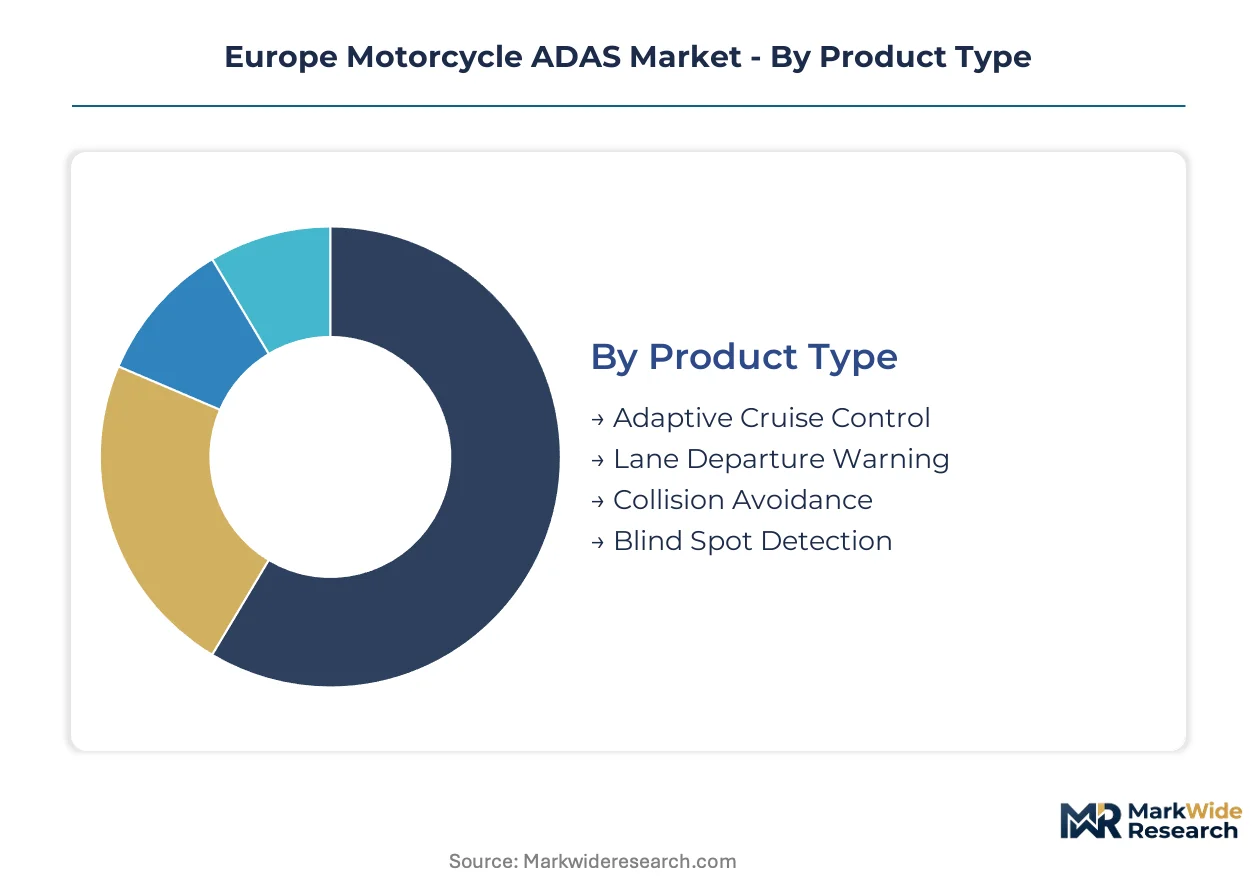
Segmentation in Europe Motorcycle ADAS tracks how regulatory mandates cascade through distinct product architectures and customer configurations. Each dimension carries different EMA type-approval burdens and GSR compliance timelines that reshape supplier priorities.
Product Type:
Collision avoidance and blind spot detection carry the heaviest ECE R157 adaptation requirements, while lane departure warning faces lighter algorithmic transparency thresholds under periodic GSR enforcement reviews.
- Collision Avoidance:Front-facing radar-camera fusion platforms process real-time trajectory data to trigger automatic emergency braking. German fleet operators in Munich-Stuttgart corridor specify these systems for premium touring motorcycles, driven by KBA homologation deadlines that compress OEM fitment schedules.
- Blind Spot Detection:Rear-quarter 77 GHz radar modules monitor adjacent vehicle proximity during lane-filtering maneuvers. French delivery platforms in Paris specify wider detection angles than retail configurations, responding to ANSM interpretations of urban collision risk.
- Adaptive Cruise Control:Long-range radar maintains following distances on high-speed corridors. Nordic markets demand enhanced all-weather reliability specifications.
- Lane Departure Warning:Camera-based edge detection triggers haptic handlebar alerts. Lower certification burden accelerates mid-tier motorcycle adoption.
Leading the category by volume: Collision Avoidance. Expanding most quickly: Blind Spot Detection.
Technology:
Cost tiers separate established 77-81 GHz radar from emerging LiDAR platforms, with camera systems occupying the mid-market integration sweet spot for multi-function architectures.
- Radar Systems:Millimeter-wave front-end modules at 77-81 GHz deliver superior angular resolution for urban collision scenarios. German and Italian OEM procurement concentrates here, leveraging established Tier 1 supply relationships for GSR-compliant homologation packages.
- Camera Systems:Stereoscopic vision enables lane departure warning and traffic sign recognition from single hardware suites. R&D investment concentrates in Stuttgart engineering clusters seeking multi-function platform economics.
- Ultrasonic Sensors:Short-range parking assistance and low-speed obstacle detection. Limited motorcycle application due to wind noise interference at highway speeds.
- LiDAR Systems:Emerging solid-state architectures for future autonomous decision-making frameworks. EU AI Act risk classification delays commercial deployment timelines.
Dominating procurement volume: Radar Systems. Gaining share fastest: Camera Systems.
End User:
Customer type determines specification divergence, with fleet procurement bypassing traditional OEM channels to negotiate direct Tier 1 collaboration on custom sensor coverage parameters.
- Fleet Operators:Large motorcycle taxi and delivery managers in Paris and Berlin establish technical collaboration directly with ADAS developers. These operators mandate data logging capabilities and rear-quarter detection priorities that diverge from retail specifications.
- Motorcycle Manufacturers:BMW Motorrad and PIERER Mobility AG anchor in-house development pipelines, controlling vertically integrated prototype-to-production workflows for KTM and Husqvarna platforms.
- Riders:Individual consumers respond to GSR-mandated baseline fitment with limited configuration choice. Premium segment seeks upgradeable modular architectures.
- Dealerships:Service network training burdens concentrate around sensor calibration complexity for stereoscopic camera alignment degradation.
Commanding volume leadership: Motorcycle Manufacturers. Steepest expansion trajectory: Fleet Operators.
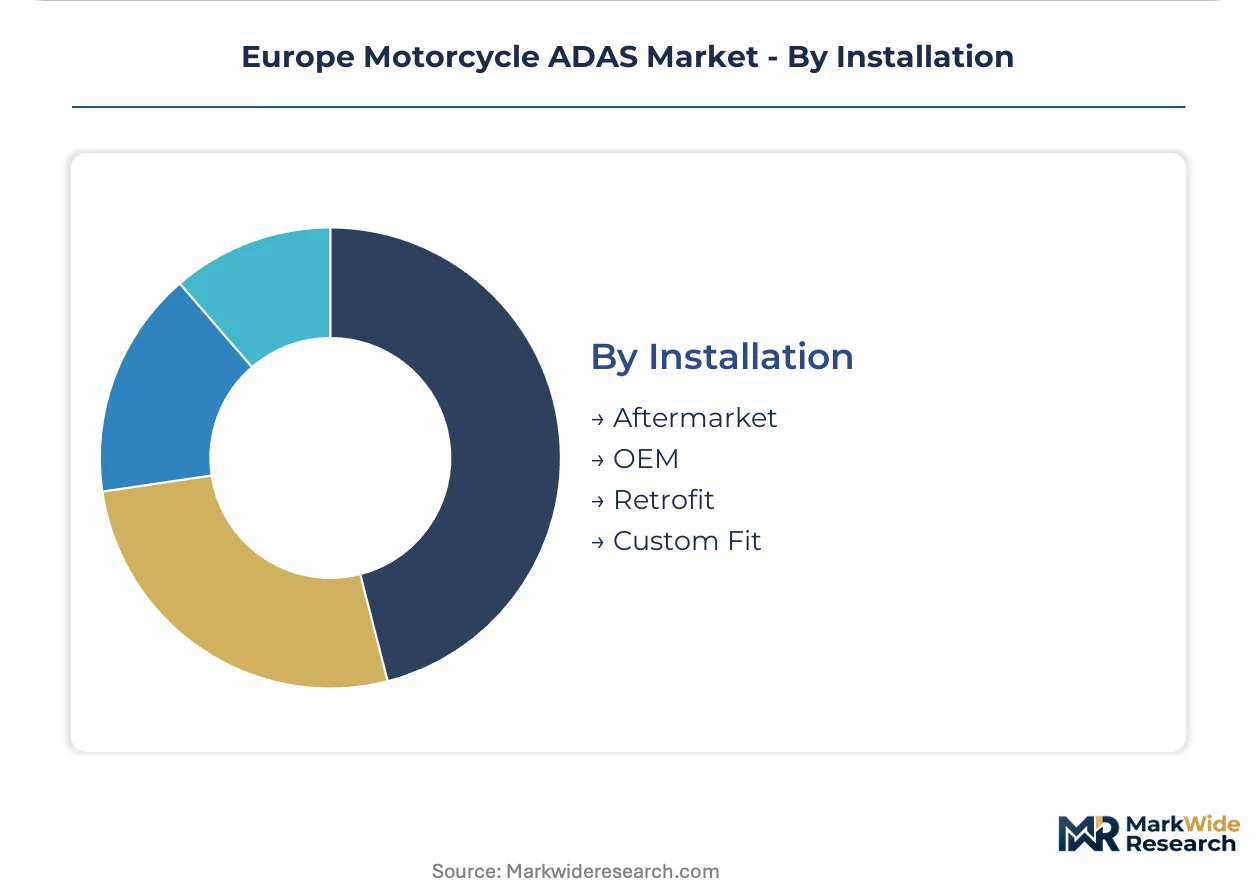
Installation:
Supply concentration in OEM channels contrasts with aftermarket fragmentation, where retrofit compatibility with legacy CAN bus architectures creates distinct engineering constraints.
- OEM:Factory-integrated radar-camera fusion architectures meet GSR 2019/2144 mandates through homologation-ready platforms. Robert Bosch GmbH and Continental AG capture disproportionate sourcing volume here.
- Aftermarket:Discrete module sales face warranty exposure from handlebar vibration and fork compression effects on camera alignment. Service network training requirements constrain growth velocity.
- Retrofit:Legacy platform integration demands compatibility with existing power distribution systems. Limited electrical capacity in model-year carryover motorcycles narrows addressable applications.
- Custom Fit:Niche specialist installations for racing and touring modifications. Minimal regulatory oversight outside EMA framework.
Holding volume dominance: OEM. Climbing fastest: Aftermarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg and Bavaria automotive corridors concentrate ADAS engineering talent through specialized R&D tax incentives and proximity to Tier 1 supplier clusters. France's Île-de-France region anchors fleet operator procurement for lane-splitting safety systems. Italy's Emilia-Romagna and Lombardy manufacturing belts sustain premium motorcycle production with integrated sensor platforms.
Germany
BMW Motorrad and PIERER Mobility AG drive collision avoidance procurement from Munich to Stuttgart. KBA homologation deadlines compress OEM development cycles for GSR 2019/2144 compliance. Engineering clusters in Ingolstadt and Ulm anchor radar-camera fusion R&D for multi-sensor architectures.
France
Paris-based delivery fleets specify custom blind spot detection angles for dense urban lane-filtering corridors. ANSM interpretations of secondary GSR requirements diverge from German implementation timelines. Lyon and Grenoble engineering centers develop algorithmic transparency documentation for periodic enforcement reviews.
Italy
Ducati Motor Holding and premium OEMs in Bologna-Modena corridor integrate 77 GHz radar for adaptive cruise control on touring platforms. EMA type-approval frameworks for ECE R157 lane-keeping standards concentrate certification activity in Milan-Turin engineering networks. Camera-system R&D investment flows to Stuttgart-adjacent Italian satellite offices.
United Kingdom
London motorcycle taxi operators pilot data-logging ADAS configurations diverging from retail consumer specifications. DVSA alignment with EU GSR mandates remains contingent on post-Brexit regulatory convergence negotiations. Midlands manufacturing heritage sustains niche aftermarket calibration service networks.
Poland
Greenfield Tier 1 production facilities near Wrocław and Poznań exploit labor cost arbitrage for radar module assembly. Expanding Eastern European motorcycle markets with nascent ADAS penetration attract supplier logistics investment. Warsaw technical universities feed embedded software talent into ISO 26262 functional safety pipelines.
Europe Motorcycle ADAS Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across sensor fusion architectures and homologation service bundles. Market structure tilts toward consolidated Tier 1 supply relationships with captive radar portfolios, though mid-tier camera specialists retain niche positioning. Three archetypes dominate: vertically integrated motorcycle OEMs controlling prototype-to-production pipelines, diversified automotive suppliers leveraging passenger-car technology transfer, and focused ADAS module specialists concentrating on algorithmic calibration. Competitive moves center on strategic partnerships for semiconductor allocation security and geographic expansion into Central European manufacturing corridors.
Within the diversified automotive supplier tier, Robert Bosch GmbH and Continental AG exemplify scale-driven radar-camera fusion platform providers. Among motorcycle OEMs with captive ADAS development, Bayerische Motoren Werke AG and PIERER Mobility AG occupy positions controlling vertically integrated supply from sensor specification to vehicle homologation. ZF Friedrichshafen AG represents the chassis-systems conglomerate archetype extending into rider assistance modules through acquisition-led portfolio expansion.
| Leading Market Players |
|---|
| Bayerische Motoren Werke AG |
| PIERER Mobility AG |
| Robert Bosch GmbH |
| BMW Motorrad |
| Honda Motor Co. |
| Continental AG |
| Ducati Motor Holding |
| Hitachi Ltd. |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
EU Green Deal sustainability mandates gate qualified Tier 1 supplier status and premium-tier pricing access for motorcycle ADAS modules, compressing margin structures for non-compliant component sources while rewarding radar-camera fusion architectures with validated carbon footprints. German OEM procurement teams now weight embodied emissions in supplier scorecards, reshaping contract terms across the Munich-Stuttgart corridor.
Pricing Analysis
Short lead-time premiums of 15-20 percent apply to 77-81 GHz radar modules with sub-12-week delivery windows, while spot inventory of legacy 24 GHz sensors trades at distressed levels. Three-tier pricing structure across premium, standard, and economy levels separates GSR-homologated fusion platforms from single-sensor alternatives and uncertified aftermarket modules. Cost compression in mid-tier camera systems is intensifying because Taiwanese MMIC allocation volatility forces European Tier 1s to absorb buffer stock carrying costs. Fleet operators in Paris exhibit highest price sensitivity due to volume procurement leverage, while premium OEMs in Bavaria prioritize homologation speed over unit economics.
Supply Chain Analysis
Freight cost inflation on Asia-Europe semiconductor lanes has elevated landed costs for radar front-end modules by double-digit percentages since 2022, compressing Tier 1 gross margins unless passed through to OEM customers. Millimeter-wave radar fabrication concentrates in Taiwan and South Korea, with secondary sensor assembly in Germany and Poland. European ADAS supply chains draw from silicon wafer suppliers in Japan, specialized automotive-grade capacitors from Malaysia, and precision optics from Germany. Single-source vulnerability around TSMC's automotive radar MMIC allocation exposes Continental AG and Robert Bosch GmbH to demand surge disruptions. Distribution runs through captive OEM supply agreements rather than merchant channels, with direct technical collaboration replacing traditional tiered procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive radar portfolio control determines Tier 1 survival, with upstream semiconductor allocation security now the decisive competitive lever.
For Market Incumbents: Deploy strategic partnerships with Taiwanese foundries to secure 77-81 GHz MMIC allocation priority ahead of automotive demand surges. Acquire Central European calibration service networks to control aftermarket sensor alignment revenue streams. Emerging LiDAR specialists threaten radar-dominant architectures through EU AI Act autonomous decision-making frameworks, requiring algorithmic transparency investments to preserve homologation validity. For New Entrants and Emerging Players: Fleet operator technical collaboration teams offer the most penetrable channel, bypassing OEM-direct procurement relationships that Robert Bosch GmbH and Continental AG have captured. Target blind spot detection customization for Paris lane-splitting corridors where ANSM interpretations create specification gaps. White-space exists in aftermarket retrofit modules compatible with legacy CAN bus architectures, particularly for KTM and Husqvarna platforms with limited electrical capacity. For Investors and Strategic Acquirers: ANSM-KBA homologation timeline divergence is the leading indicator that regulatory arbitrage opportunities will concentrate value in multi-certification-capable suppliers. Mid-tier camera specialists with ISO 26262 functional safety engineering pipelines represent prime acquisition targets as algorithmic sensor fusion displaces discrete modules. Watch for Tier 1 consolidation moves in Poland and Czech Republic manufacturing corridors as labor cost arbitrage attracts greenfield investment.| Strategic Initiative | Industry Significance |
|---|---|
| Radar-Camera Fusion Platform Standardization | Single-module architectures reduce OEM integration burden and compress supplier SKU proliferation across GSR mandates. |
| Central European Manufacturing Footprint Expansion | Greenfield facilities near Wrocław exploit labor arbitrage and proximity to expanding Eastern European motorcycle markets. |
| EU AI Act Risk Classification Compliance | Early algorithmic transparency documentation positions suppliers for liability advantages as automation levels advance. |
| Fleet Operator Direct Collaboration | Paris and Berlin delivery platforms specify custom sensor coverage parameters diverging from retail configurations. |
| Semiconductor Allocation Security Partnership | Taiwanese foundry relationships anchor Tier 1 supply continuity during automotive demand surges. |
Research Methodology
Multi-period observation of GSR enforcement review timelines, EMA type-approval issuance patterns, and fleet procurement contract values anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, KBA homologation engineers, Paris fleet operations managers, and Stuttgart-adjacent R&D directors. Secondary validation drew from EMA vehicle registration databases, EU official journal regulatory filings, IHS Markit motorcycle production data, and SEC 10-K disclosures from diversified automotive suppliers. Bottom-up sensor unit shipment estimates triangulated against top-down OEM fitment program values.
Input-output matrices modeled technology adoption curves, regulatory compliance deadlines, and regional manufacturing cost structures across the projection horizon. Segmentation dimensions included product architecture, sensing modality, customer type, and installation channel, with additional granularity on national type-approval authority interpretation variance. CAGRs derived from logistic diffusion curves fitted to historical fitment rates and policy-mandated floor penetration assumptions. Industry-specific inputs encompassed ECE R157 motorcycle adaptation timelines and Nordic all-weather performance specification stringency.
Several conditions sit outside the modeled scope, including potential GSR implementation delays in select member states, breakthrough solid-state LiDAR cost reductions, and semiconductor fabrication capacity expansions beyond announced foundry roadmaps. Forecasts reflect assumptions around regulatory harmonization persistence and OEM development cycle compression rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market