
 Automotive Chain Sprockets Market | 2026-2036
Automotive Chain Sprockets Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Chain Sprockets Market Analysis
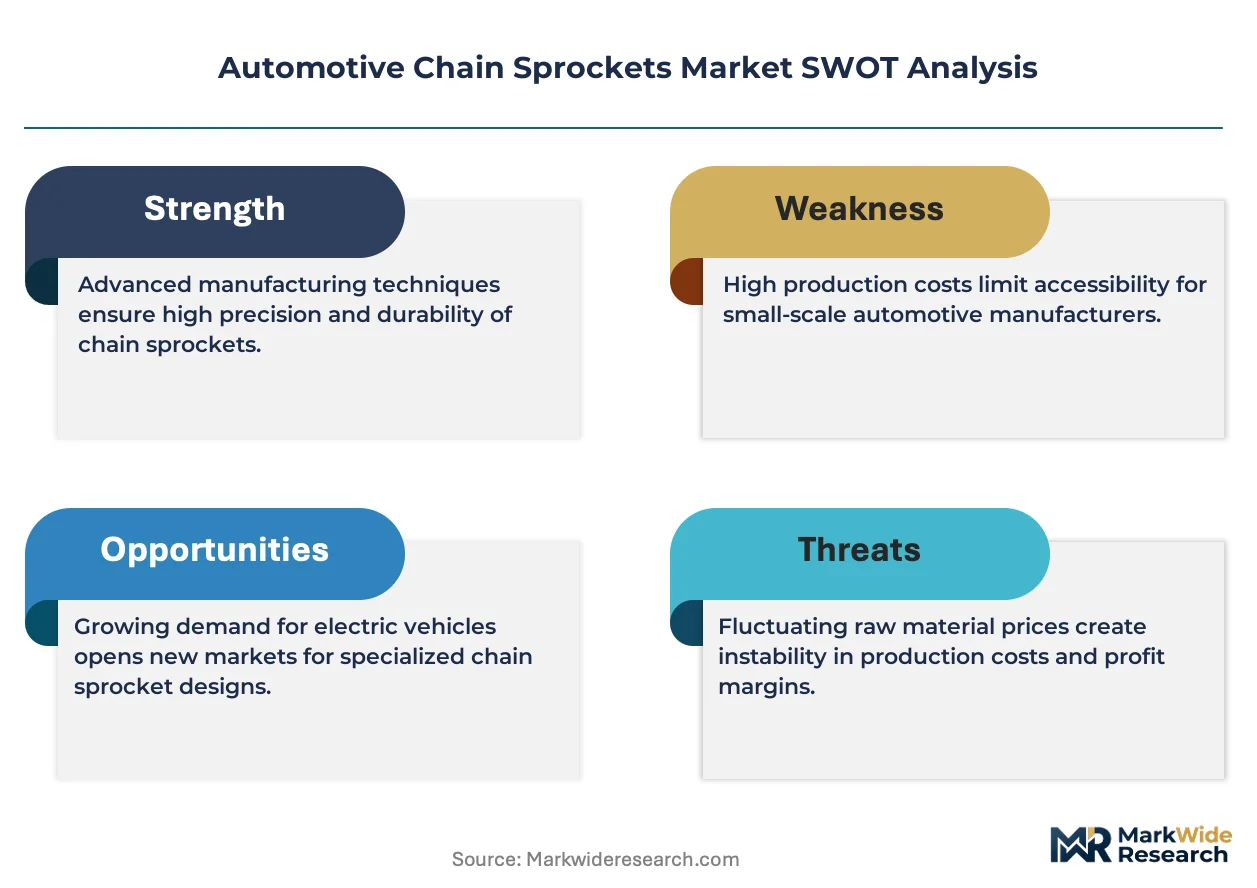
Single-source supply contracts for precision-machined sprockets is decoupling from long-term OEM agreements as vehicle assemblers diversify vendor bases to mitigate disruption risk. Renold PLC leverages its British manufacturing heritage to sustain high-torque roller sprocket output for commercial vehicle programs. Tsubakimoto Chain Co. anchors Asian supply networks through integrated heat-treatment facilities. SKF Group competes on material science, extending hardened steel formulations that reduce chain wear in start-stop hybrid systems.
Automotive chain sprockets are toothed wheels engineered to mesh with roller or silent chains, typically manufactured from case-hardened steel or sintered powder metal with pitch tolerances under 0.05 millimeters to ensure synchronous power transmission in engine timing and driveline applications. Their primary purpose is converting rotational motion into linear chain movement while maintaining constant velocity ratios under variable load conditions. Roller sprockets dominate OEM volumes due to proven durability in internal combustion architectures, though silent chain sprockets are capturing margin pools as noise regulations tighten. Steel retains absolute volume leadership, yet aluminum and composite variants are expanding fastest where mass reduction targets override unit cost premiums in electric vehicle platforms.
EPA emissions benchmarks and NHTSA fuel economy standards in the United States compel sprocket suppliers to validate friction losses across complete timing systems, while REACH substance restrictions in Europe limit certain surface coatings and lubricant chemistries used in finishing processes. China's MIIT enforces GB standards for mechanical component reliability that foreign suppliers must certify before qualifying for domestic OEM contracts. Stakeholders must monitor how divergent regional efficiency protocols fragment testing requirements and determine whether localized tooling investments or cross-certified product platforms offer superior capital efficiency.
Market Dynamics
The automotive chain sprockets sector is experiencing a fundamental recalibration as electric vehicle powertrain architectures displace conventional timing systems, forcing suppliers to engineer lighter, quieter components for reduced-load e-motor applications while maintaining precision tolerances.
Growth Catalysts
- China's MIIT dual carbon mandates:Stringent efficiency targets under the national carbon-neutrality framework are accelerating OEM demand for optimized driveline components that reduce mechanical losses.
- Aluminum alloy adoption:Mass-critical EV platforms are specifying forged aluminum sprockets to achieve rotational inertia reduction without sacrificing tooth hardness.
- Germany's precision engineering cluster:Concentrated OEM engineering centers in Baden-Württemberg and Bavaria are generating specification upgrades that propagate through global supply chains.
Market Restraints
- Alloy steel price volatility:Case-hardening grade steel input costs fluctuate with scrap metal and energy pricing, compressing margin predictability for mid-volume manufacturers.
- Heat-treatment capacity concentration:Specialized carburizing furnace networks cluster in East Asian industrial zones, creating geographic chokepoints for Western suppliers.
- Silent chain technical ceiling:Polymer-inverted tooth designs face durability thresholds above 15,000 RPM that limit deployment in high-performance hybrid applications.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentive structures are attracting sprocket tooling investments to serve domestic two-wheeler and emerging EV assembly.
- Integrated sensor mounting:Smart sprocket designs with embedded position sensing are converging with vehicle telemetry architectures for predictive maintenance revenue streams.
- Direct-to-fleet aftermarket channels:Commercial vehicle operators are bypassing traditional distribution tiers through digital procurement platforms for replacement timing sets.
Industry Challenges
- Metallurgical talent scarcity:Case-hardening process engineering expertise is retiring faster than vocational programs replenish qualified furnace operators.
- Multi-standard certification burden:Suppliers must simultaneously validate to EPA friction protocols, REACH coating restrictions, and China's GB mechanical reliability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chain Sprockets Market |
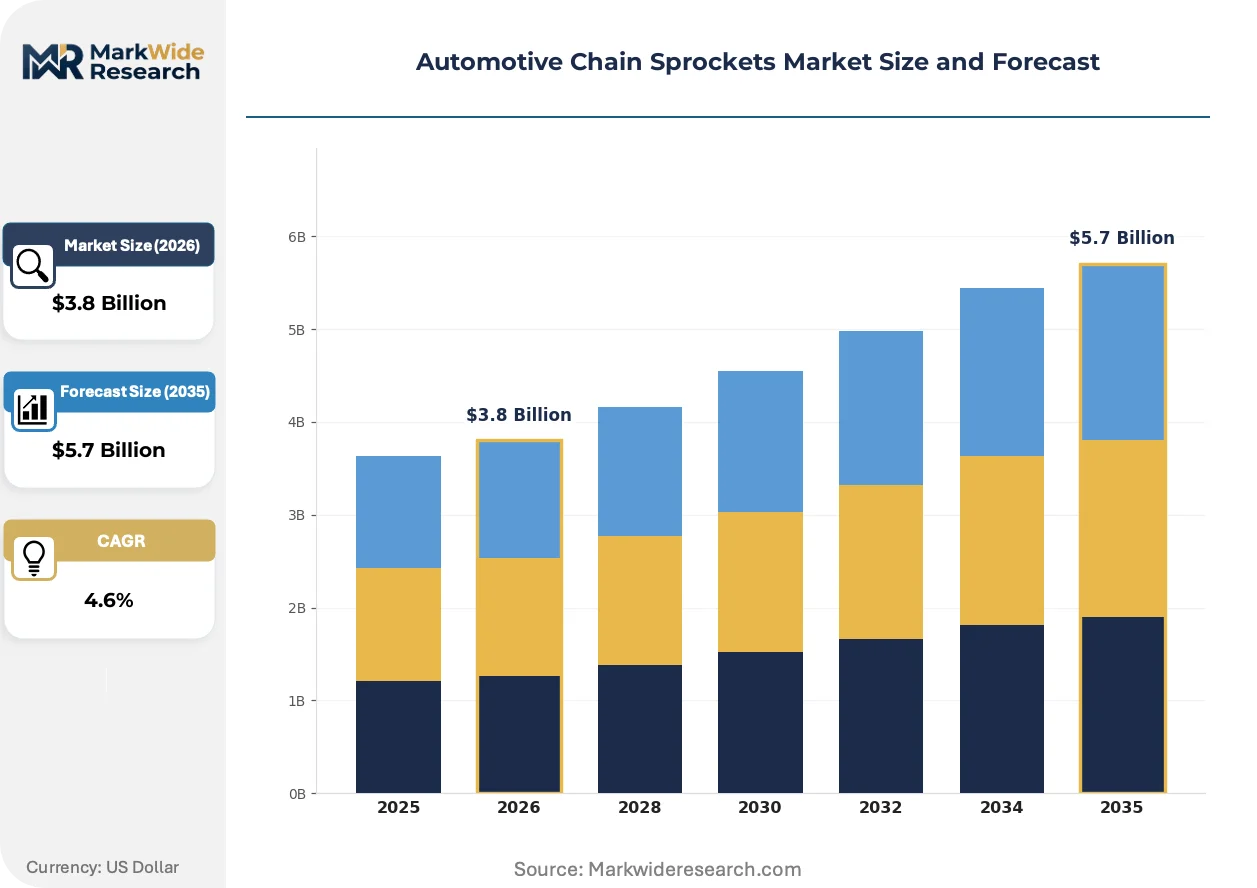
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Sprockets, Leaf Sprockets, Silent Chain Sprockets, Specialty Sprockets Material: Steel, Aluminum, Plastic, Composite End User: Original Equipment Manufacturers, Aftermarket Suppliers, Vehicle Assemblers, Maintenance Providers Size: Standard, Miniature, Heavy Duty, Customized |
| Companies Covered | SKF Group, Rexnord Corporation, Renold PLC, Tsubakimoto Chain Co., NSK Ltd., INA, Gates Corporation, Dayco Products LLC, The Timken Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chain Sprockets Market Emerging Trajectories
Material science advances and regulatory pressure on driveline efficiency are converging to transform how sprockets are specified, manufactured, and integrated into next-generation powertrains across combustion, hybrid, and electric architectures.
Powder metallurgy is consolidating as the dominant near-net-shape production method for complex tooth profiles in high-volume passenger vehicle programs. Tier-one suppliers are adopting warm compaction presses capable of achieving 7.2 g/cm³ density in sintered steel, reducing machining operations by sixty percent versus forged blanks. This process compression is consolidating supplier tiers as captive powder operations displace independent machining houses.
REACH substance restrictions on hexavalent chromium surface coatings are compelling conversion to trivalent alternatives or thin-film DLC deposition across European supply chains. Finishers must requalify corrosion resistance to OEM salt-spray specifications while maintaining identical friction coefficients. German and Czech stamping operations are most affected, accelerating in-house PVD coating investments to preserve qualification status.
Modular platform procurement is fragmenting long-term supply agreements as vehicle assemblers adopt competitive dual-sourcing for timing system components. Tier-one buyers are unbundling sprocket orders from complete chain kit contracts, creating entry points for specialized manufacturers. This pattern is most visible in South Korean and Japanese OEM purchasing departments, where supplier rotation clauses now mandate technology refresh cycles every four years.
Automotive Chain Sprockets Market Segmentation
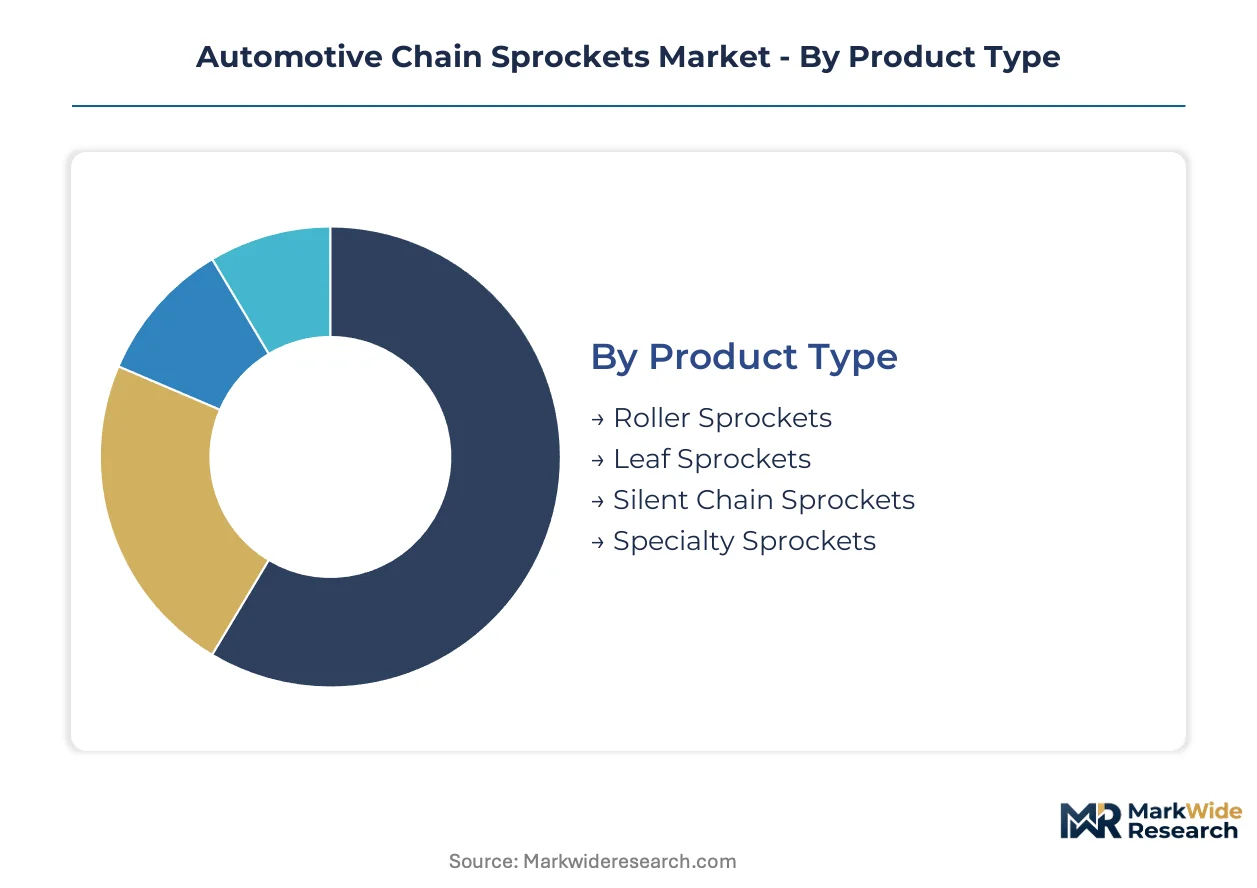
Sprocket procurement patterns diverge sharply between high-volume standardized platforms and low-volume precision-engineered applications. Specification requirements from Germany's automotive engineering centers propagate globally, fragmenting supplier qualification criteria across product tiers.
Product Type:
Customization intensity spans from mass-produced roller designs to application-specific silent chain variants requiring acoustic engineering collaboration.
- Roller Sprockets:Toothed wheels meshing with roller chains through hardened steel teeth with pitch tolerances under 0.05 millimeters. Demand concentrates in commercial vehicle timing systems across China's heavy-duty truck assembly plants, where durability specifications override unit cost considerations under MIIT reliability mandates.
- Silent Chain Sprockets:Inverted-tooth profiles engineered for noise reduction in passenger vehicle engine timing applications. Orders from Germany's precision engineering cluster in Baden-Württemberg are tightening supplier lead times as OEMs specify sub-60 decibel operation for hybrid powertrains.
- Leaf Sprockets:Plate-style designs for conveyor and auxiliary drive applications with lower rotational speed requirements.
- Specialty Sprockets:Custom-engineered profiles for racing, industrial conversion, and prototype vehicle programs.
Most installed capacity flows through Roller Sprockets. Expansion is steepest in Silent Chain Sprockets.
Material:
Cost tier stratification separates commodity steel grades from premium aluminum and composite formulations.
- Steel:Case-hardened and through-hardened grades dominate internal combustion architectures with proven fatigue resistance. India's PLI scheme for auto components is attracting carbon steel forging investments to serve domestic two-wheeler demand.
- Aluminum:Forged and cast alloys specified for rotational inertia reduction in electric vehicle platforms. Mass-critical EV architectures in South Korea and Japan are accepting unit cost premiums for 40% mass reduction versus steel equivalents.
- Plastic:Glass-reinforced polymers for low-load auxiliary drives and tensioner applications.
- Composite:Carbon fiber and hybrid matrices emerging in motorsport and premium EV prototyping.
Steel retains absolute volume leadership. Aluminum gains share fastest in OEM electric platforms.
End User:
Customer type determines contract structure, with captive OEM supply contrasting fragmented aftermarket procurement.
- Original Equipment Manufacturers:Direct specification authority for powertrain timing systems with multi-year platform contracts. Germany's Volkswagen Group and BMW engineering centers validate friction losses across complete systems under EPA protocols.
- Vehicle Assemblers:Contract manufacturers and joint-venture operations integrating sprockets into complete chain kits. Chinese OEMs under MIIT dual carbon mandates are qualifying suppliers to GB mechanical reliability standards.
- Aftermarket Suppliers:Replacement timing set distributors serving independent repair networks.
- Maintenance Providers:Fleet operators and commercial vehicle service chains procuring direct-to-operator.
Platform procurement concentrates with Original Equipment Manufacturers. Digital procurement expansion is steepest among Maintenance Providers.
Size:
Volume scale separates high-unit miniature applications from heavy-duty mining and construction equipment.
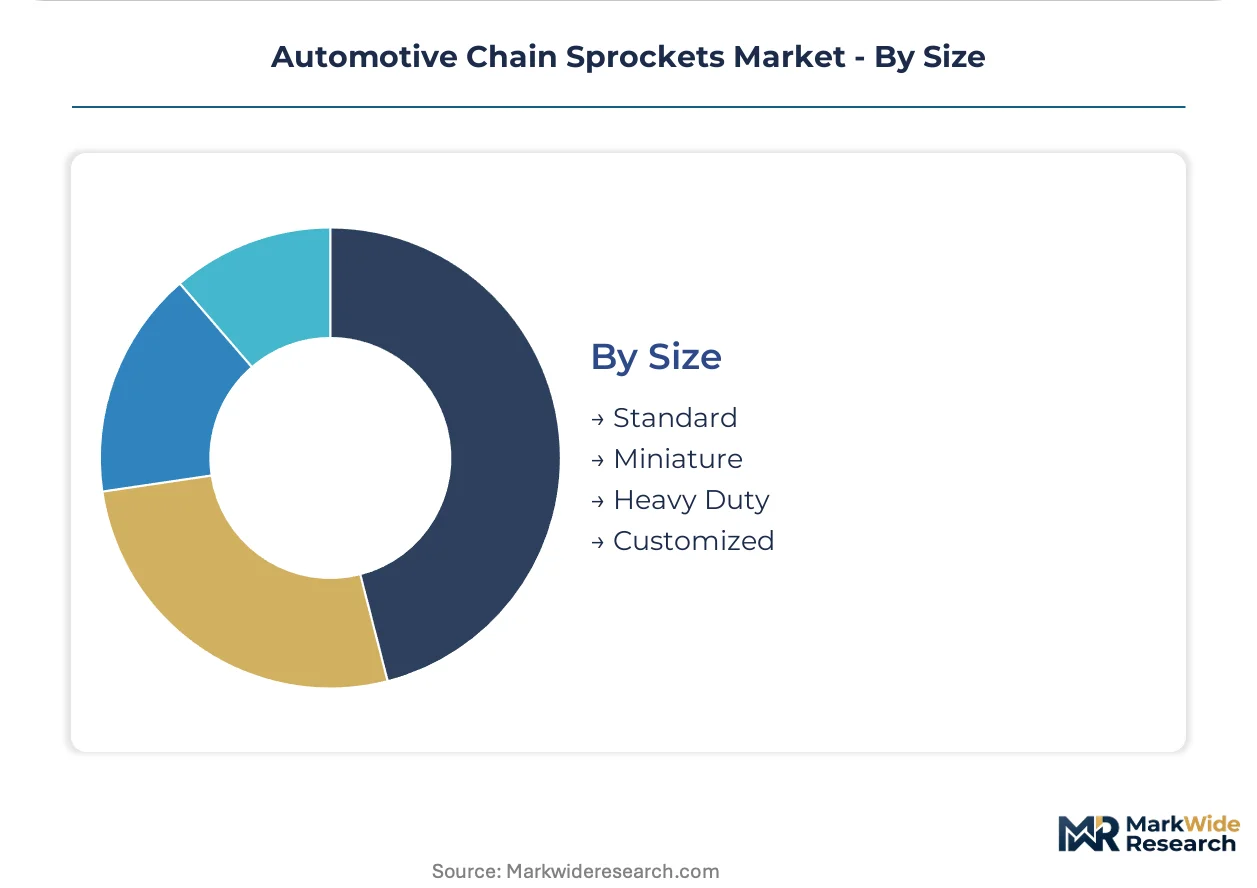
- Standard:Pitch dimensions conforming to ISO 606 and ANSI B29.1 for passenger and light commercial vehicles. Global OEM platform strategies favor interchangeability across assembly plants in Germany, China, and the United States.
- Heavy Duty:Enlarged tooth profiles and thicker hub sections for commercial vehicle and off-highway applications. Mining equipment manufacturers in Australia specify case-hardening depths exceeding 1.2 millimeters for abrasive operating environments.
- Miniature:Sub-6.35 millimeter pitch for motorcycle and small engine applications.
- Customized:Non-standard pitch, bore, and tooth count for prototype and retrofit programs.
Standard sizes absorb most production throughput. Customized specifications expand most quickly in EV prototype engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering cluster generates specification upgrades that propagate through global automotive supply chains, while China's MIIT dual carbon mandates reshape supplier qualification criteria across multiple continents.
Germany
Volkswagen Group and BMW engineering centers in Bavaria validate friction losses across complete timing systems under EPA protocols. REACH substance restrictions on hexavalent chromium coatings compel conversion to trivalent alternatives across German stamping operations. Stuttgart-based engineering teams specify sub-60 decibel silent chain sprockets for hybrid powertrains, tightening supplier lead times throughout the precision manufacturing corridor.
China
Domestic heavy-duty truck assembly plants under MIIT reliability mandates prioritize durability specifications over unit cost considerations. GB standards for mechanical component reliability require foreign suppliers to certify before qualifying for domestic OEM contracts. Yangtze River Delta manufacturing zones concentrate heat-treatment furnace networks, creating geographic chokepoints for Western suppliers seeking capacity access.
United States
EPA emissions benchmarks and NHTSA fuel economy standards compel sprocket suppliers to validate friction losses across complete timing systems. Detroit-area engineering centers specify case-hardened steel formulations for start-stop hybrid architectures. Midwestern automotive belt procurement teams are unbundling sprocket orders from complete chain kit contracts, fragmenting long-term supply agreements.
Japan
South Korean and Japanese OEM purchasing departments now mandate supplier rotation clauses with technology refresh cycles every four years. METI efficiency guidelines accelerate specification of forged aluminum sprockets for mass-critical EV platforms. Nagoya-based engineering clusters drive demand for powder metallurgy warm compaction presses capable of achieving 7.2 g/cm³ density in sintered steel.
India
Production-linked incentive structures under the PLI scheme attract sprocket tooling investments to serve domestic two-wheeler and emerging EV assembly. Carbon steel forging investments concentrate in Tamil Nadu and Gujarat to serve expanding commercial vehicle production. BIS certification requirements for automotive components create entry barriers for unqualified foreign suppliers.
Automotive Chain Sprockets Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue aluminum alloy formulations and integrated sensor mounting for electric vehicle platforms. The vendor base stratifies across three maturity levels: legacy European and Japanese manufacturers with captive heat-treatment networks, mid-scale regional specialists serving domestic OEM programs, and technology-focused entrants targeting smart sprocket architectures. Competitive positioning depends on metallurgical process control, geographic proximity to carburizing furnace clusters, and multi-standard certification capabilities. Primary competitive moves include backward integration into powder metallurgy operations and strategic partnerships with PVD coating specialists to preserve REACH qualification status.
Among European-anchored manufacturers, Renold PLC and SKF Group exemplify distinct archetype positions within the competitive structure. Renold PLC represents heritage-driven British manufacturing continuity in high-torque roller sprocket output. SKF Group occupies a material science-focused position extending hardened steel formulations. Tsubakimoto Chain Co. anchors Asian supply network integration through proximity to concentrated heat-treatment infrastructure. These three entities collectively illustrate how geographic origin and manufacturing heritage shape viable competitive strategies without converging on identical capability portfolios.
| Leading Market Players |
|---|
| SKF Group |
| Rexnord Corporation |
| Renold PLC |
| Tsubakimoto Chain Co. |
| NSK Ltd. |
| INA |
| Gates Corporation |
| Dayco Products LLC |
| The Timken Company |
| Others |
Supply Flow & Price Mechanics
Case-hardening grade steel input costs flow from scrap metal and energy markets through mid-volume manufacturers into three-tier pricing structures across premium, standard, and economy levels, with alloy price volatility compressing margin predictability for suppliers serving China's heavy-duty truck assembly plants under MIIT reliability mandates.
Pricing Analysis
Input-cost pass-through from alloy steel and energy pricing dominates contract structures, with case-hardening grade fluctuations compressing margins for mid-volume manufacturers while premium tiers capture value through REACH-compliant coating investments and GB certification status. Price differentiation separates OEM direct specification contracts from aftermarket replacement sets, with volume scale and certification level as primary drivers. Pricing pressure stems from unbundling of sprocket orders from complete chain kit contracts in Midwestern automotive procurement. Aftermarket distributors exhibit highest price sensitivity; OEM platform engineering centers demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with heat-treatment furnace networks concentrated in China's Yangtze River Delta and East Asian industrial zones, creating geographic chokepoints for Western suppliers seeking carburizing capacity. Raw material dependencies center on scrap metal pricing, energy inputs for furnace operations, and specialized case-hardening grade steel formulations. Supply chain risk manifests as tariff exposure on coated finished goods entering European markets under REACH substance restrictions. Distribution runs through Tier 1 supplier consolidation into OEM platform contracts, with aftermarket channels fragmenting through direct-to-fleet digital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive chain sprockets offer margin expansion through powder metallurgy process compression reducing machining operations, while aluminum alloy premiums for EV rotational inertia reduction shift volume toward higher-value tiers.
For Market Incumbents: Anchor competitive position through backward integration into warm compaction powder metallurgy operations and in-house PVD coating investments to preserve REACH qualification status against emerging coating specialists. Defend against unbundling pressure from OEM procurement teams by embedding sensor-mounting capabilities for predictive maintenance revenue streams. Prioritize heat-treatment capacity access in East Asian furnace clusters to mitigate geographic chokepoint risk. For New Entrants and Emerging Players: India's PLI scheme for auto components opens a window for carbon steel forging investments serving domestic two-wheeler demand and emerging EV assembly in Tamil Nadu and Gujarat. Target aluminum alloy formulations for South Korean and Japanese OEM mass-critical EV platforms accepting unit cost premiums for rotational inertia reduction. Pursue direct-to-fleet aftermarket channels through digital procurement platforms bypassing traditional distribution tiers for commercial vehicle replacement timing sets. For Investors and Strategic Acquirers: Consolidation pressure builds where metallurgical talent scarcity outpaces vocational program replenishment of qualified furnace operators and case-hardening process engineers. Long-term viability favors acquisition targets with captive heat-treatment networks and multi-standard certification capabilities spanning EPA friction protocols, REACH coating restrictions, and China's GB mechanical reliability standards. Watch for inflection where OEM dual-sourcing mandates accelerate technology refresh cycle frequency beyond four-year intervals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Metallurgy | Warm compaction presses achieving 7.2 g/cm³ density reduce machining operations by sixty percent versus forged blanks. |
| In-House PVD Coating Investment | German and Czech stamping operations preserve REACH qualification status against hexavalent chromium coating restrictions. |
| Aluminum Alloy Formulation Development | Forged aluminum sprockets capture EV platform demand for forty percent mass reduction versus steel equivalents. |
| Integrated Sensor Mounting Capabilities | Smart sprocket designs with embedded position sensing converge with vehicle telemetry architectures for predictive maintenance. |
| Heat-Treatment Capacity Expansion | Proximity to Yangtze River Delta furnace networks mitigates geographic chokepoint risk for Western suppliers. |
Methodological Framework
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and heat-treatment furnace operators grounded qualitative insights in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed component manufacturers, and MIIT GB standard documentation. Bottom-up and top-down triangulation cross-checked volume assumptions against OEM platform-level content-per-vehicle estimates and regional production cluster outputs.
Segmentation outputs across product type, material formulation, end-user category, and size tier fed into analytical frameworks spanning the projection horizon. CAGRs were derived from regression analysis against vehicle production forecasts, powertrain architecture mix shifts, and regulatory efficiency mandate timelines. Industry-specific inputs included EV platform mass reduction targets, REACH substance restriction implementation schedules, and India's PLI scheme incentive structures.
Revisions become necessary when alloy steel price volatility exceeds historical bands, when heat-treatment capacity concentration triggers supply disruption, or when OEM dual-sourcing mandates accelerate technology refresh cycles. Forecasts reflect assumptions about powertrain electrification pace, regulatory harmonization across EPA, REACH, and GB protocols, and vocational program output of qualified metallurgical talent. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Africa Two-Wheeler Market