
 Bike Taxi Market | 2026-2036
Bike Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Taxi Market Analysis
India is reshaping competitive dynamics through aggressive fleet expansion and driver onboarding programs across Mumbai, Bangalore, and Delhi. Uber Technologies Inc. leverages its integrated mobility stack to cross-sell bike taxi rides within its super-app ecosystem. Grab Holdings Ltd. anchors Southeast Asian operations with hyperlocal payment integration and driver incentive structures. PT GoTo Gojek Tokopedia Tbk dominates Indonesian urban corridors through its dual-platform merchant and mobility network.
A bike taxi constitutes a two-wheeled motorized or pedal-powered vehicle operated by a licensed driver for short-distance passenger transport, typically covering 2-10 kilometer trips with 100-150cc engine displacement or electric equivalents rated below 4 kW. The service addresses congestion-induced delays in dense urban cores where four-wheeled alternatives face parking scarcity and traffic saturation. Ride-hailing commands the largest transaction volume due to spontaneous demand patterns and minimal pre-booking friction. Shared rides represent the fastest-expanding format as platforms optimize per-trip economics through route-pooling algorithms. Subscription plans concentrate margin pools among daily commuters seeking fare predictability.
FCC guidelines govern GPS navigation accuracy and communication device certification for US-based fleet operators, while India's BIS mandates helmet and vehicle safety standards for commercial two-wheeler deployment. The EU Green Deal's urban mobility directives push municipalities to integrate bike taxis into low-emission zone frameworks. Stakeholders must monitor how ride-hailing labor classification rulings reshape cost structures and platform liability exposure.
Market Dynamics
Urban congestion and last-mile connectivity gaps are forcing municipalities to formally integrate bike taxis into licensed transport frameworks, with India's BIS standards and GPS mandates rewriting operational compliance requirements.
Growth Catalysts
- India's BIS helmet and vehicle safety mandates:Commercial two-wheeler certification requirements legitimize fleet operations and unlock insurance coverage for drivers and passengers.
- Jakarta-Ho Chi Minh City-Bangkok corridor density:Megacity traffic saturation creates structural demand for sub-10 kilometer trips where four-wheeled alternatives face parking scarcity.
- Route-pooling algorithms:Shared-ride optimization compresses per-trip costs while maintaining driver earnings, expanding addressable commuter segments.
Market Restraints
- Driver classification rulings:Labor reclassification pressures in multiple jurisdictions threaten platform cost structures and liability exposure.
- Petrol-electric cost volatility:Fuel price swings and battery supply concentration in East Asian manufacturing squeeze fleet operator margins unpredictably.
- Helmet compliance friction:Passenger safety equipment mandates create enforcement complexity and trip-abandonment risk at scale.
Strategic Opportunities
- EU Green Deal low-emission zone integration:Municipal bike taxi carve-outs in European urban cores create preferential access lanes and parking privileges.
- Subscription commuter plans:Daily rider lock-in models concentrate predictable revenue pools and reduce customer acquisition costs.
- Hyperlocal payment-wallet convergence:Embedded financial services deepen platform stickiness and capture transaction economics beyond ride fees.
Industry Challenges
- Real-time GPS telemetry integration:FCC-certified device deployment and backend fleet management systems require sustained capital investment and technical expertise.
- Multi-jurisdiction licensing harmonization:Fragmented municipal permit regimes create operational complexity for cross-city platform expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Taxi Market |
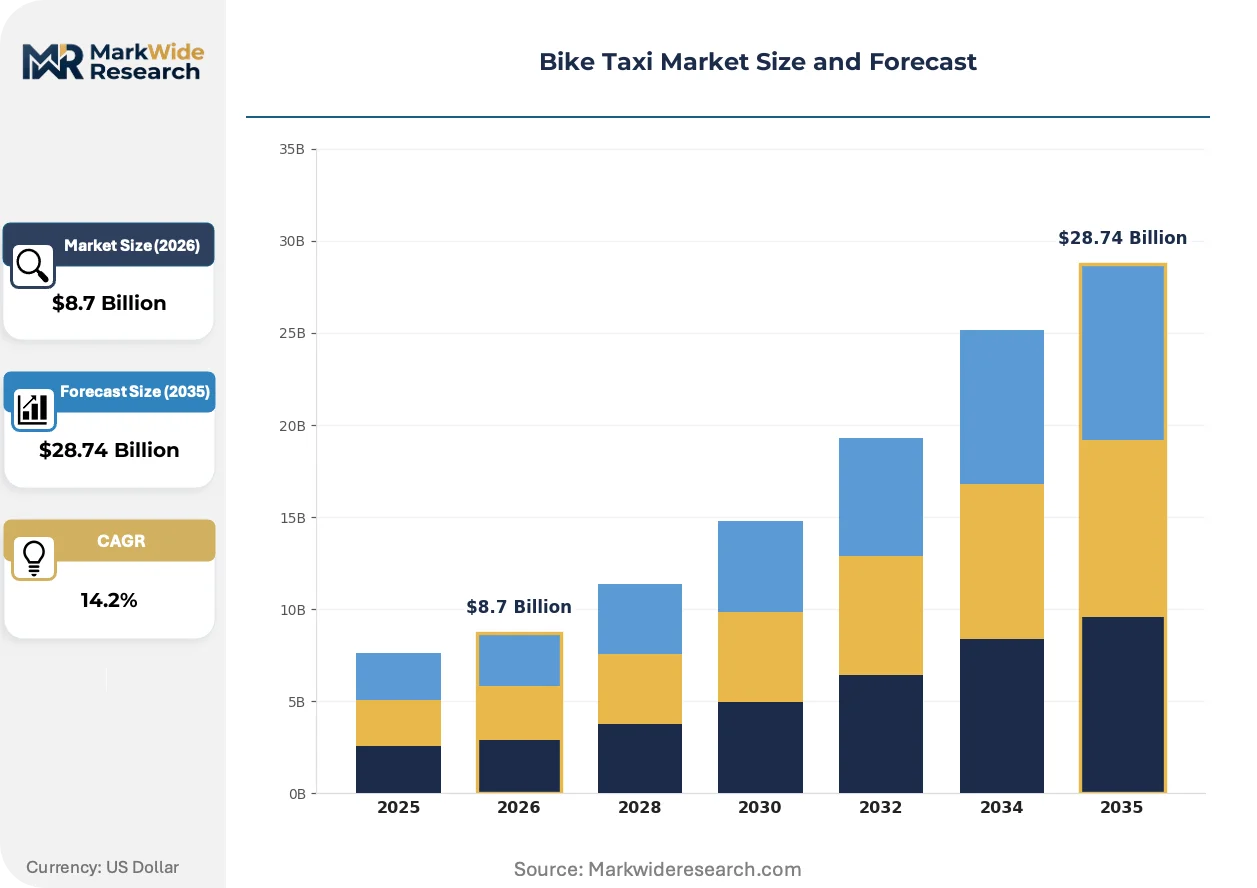
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Scheduled Rides, Shared Rides, On-Demand Services Customer Type: Daily Commuters, Tourists, Students, Business Travelers Technology: Mobile Apps, GPS Navigation, Cashless Payments, Tracking Systems Pricing Model: Fixed Fare, Surge Pricing, Subscription Plans, Hourly Rates |
| Companies Covered | Roppen Transportation Services, inDriver NA Inc., Uber Technologies Inc., MAX BIKES SDN BHD, Ryde Technologies Pte. Ltd., Grab Holdings Ltd., Bolt Technology OU, LA Taximoto, PT GoTo Gojek Tokopedia Tbk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Taxi Market Emerging Trajectories
Platform economics and regulatory formalization are converging to professionalize a historically informal sector, with technology stack investments separating scalable operators from fragmented local competitors.
AI-powered demand forecasting is virtualizing fleet deployment decisions. Predictive algorithms analyze traffic patterns, weather data, and event calendars to pre-position drivers before demand spikes materialize. Southeast Asian platforms are adopting these systems fastest, compressing passenger wait times from minutes to seconds while maximizing driver utilization rates.
India's BIS commercial two-wheeler safety standards are mandating structural vehicle modifications and helmet quality thresholds. Fleet operators must now certify vehicles through designated testing facilities, creating compliance backlogs that favor well-capitalized platforms with dedicated certification teams. The mandate disproportionately impacts electric bike taxi deployments, where battery thermal management systems face additional scrutiny.
Corporate commuter contracts are displacing individual ride-hailing as the preferred procurement channel for daily mobility. Employers in Bangalore and Mumbai are negotiating bulk subscription packages for staff transportation, unbundling the traditional platform-consumer relationship. This shift concentrates volume among fewer decision-makers and introduces annual contract cycles with negotiated service-level agreements.
Bike Taxi Market Segmentation
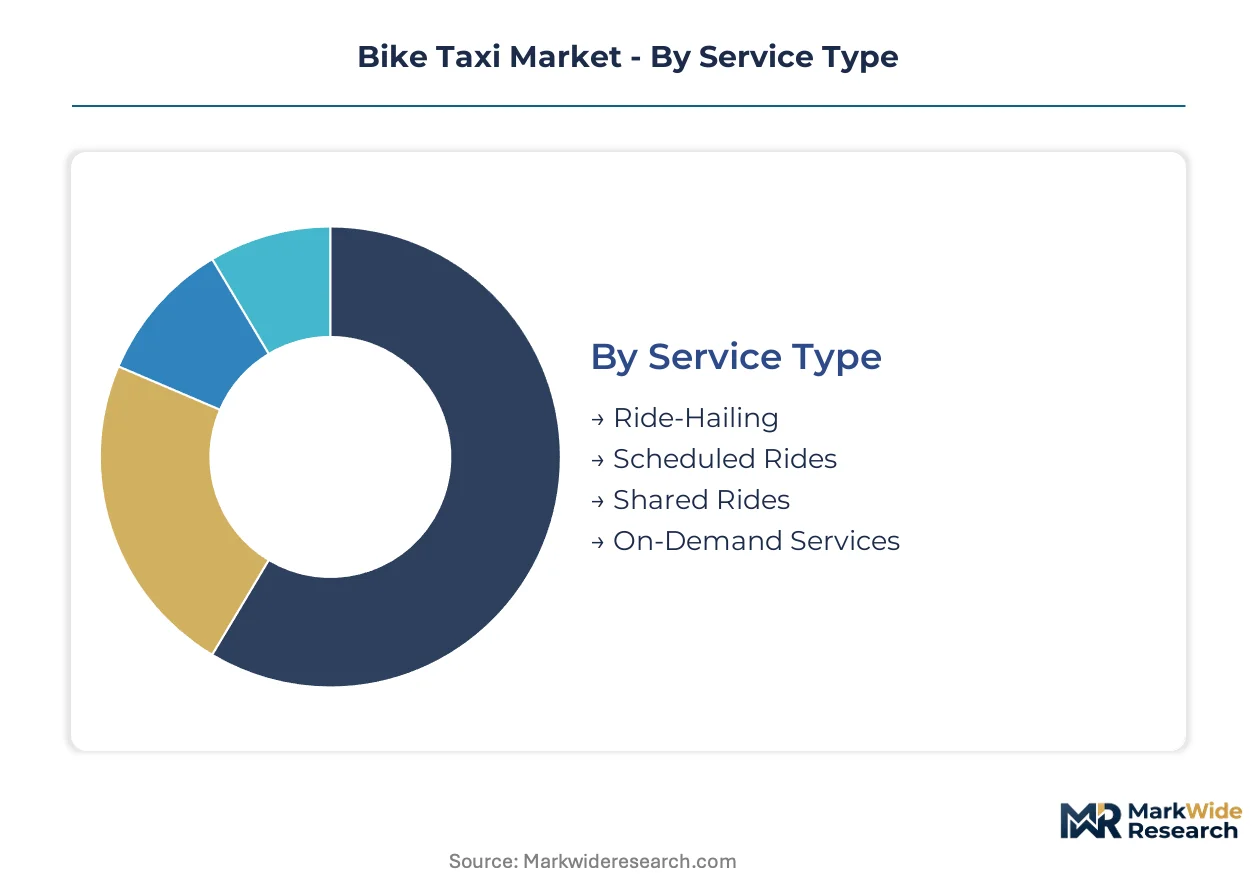
Segmentation in the bike taxi market reveals how platform economics and commuter behavior intersect across service formats, customer profiles, and payment architectures. Each dimension carries distinct operational requirements and margin structures that shape competitive positioning.
Service Type:
Cost tier differentiation separates spontaneous demand from planned mobility, with each format commanding distinct driver utilization rates and platform commission structures.
- Ride-Hailing:Spontaneous trip requests via mobile platforms dominate transaction volume in Jakarta, Ho Chi Minh City, and Bangkok. Minimal pre-booking friction captures impulse demand during peak congestion windows.
- Shared Rides:Route-pooling algorithms optimize per-trip economics through passenger consolidation. This format is gaining share fastest among price-sensitive commuters in dense Southeast Asian corridors where traffic saturation extends trip durations.
- Scheduled Rides:Pre-booked trips with guaranteed pickup times serve airport transfers and recurring appointments. Higher reliability premiums attract business travelers seeking predictability.
- On-Demand Services:Immediate dispatch without app intermediation persists in informal markets. Regulatory pressure and insurance mandates are compressing this segment's addressable base.
Ride-hailing holds installed capacity. Shared rides is rotating up the share rankings.
Customer Type:
Application context determines trip frequency, route predictability, and price elasticity across commuter archetypes.
- Daily Commuters:Recurring peak-hour travelers between residential clusters and commercial districts in Mumbai, Bangalore, and Delhi generate the highest lifetime value. Subscription plans and corporate contracts concentrate this volume.
- Tourists:Short-duration visitors prioritize convenience over cost, accepting premium fares for hotel-to-attraction links. Seasonal demand spikes strain fleet availability in heritage corridors.
- Students:Price-sensitive, high-frequency travelers between campuses and transit hubs. Discounted off-peak pricing and semester passes lock in predictable volume.
- Business Travelers:Expense-account mobility with strict punctuality requirements. Corporate procurement channels and receipt integration dominate this thin-margin, high-service tier.
Daily commuters anchor revenue concentration. Students show the steepest expansion trajectory in emerging platform markets.
Technology:
Customer interaction layers and backend infrastructure define operational scalability and regulatory compliance thresholds.
- Mobile Apps:Primary booking interfaces with integrated fare estimation, driver tracking, and rating systems. Platform stickiness depends on UI responsiveness and localization depth.
- GPS Navigation:FCC-certified devices in US fleets and India's mandated tracking systems enable real-time route optimization and safety monitoring. Backend telemetry integration requires sustained capital investment.
- Cashless Payments:Wallet integration and embedded financial services deepen transaction economics beyond ride fees. Hyperlocal payment convergence drives platform loyalty in Southeast Asian markets.
- Tracking Systems:Fleet management dashboards and driver behavior analytics support insurance underwriting and regulatory reporting. BIS compliance in India mandates specific device certification standards.
Mobile apps command user interface investment. GPS navigation is rotating up the compliance priority rankings.
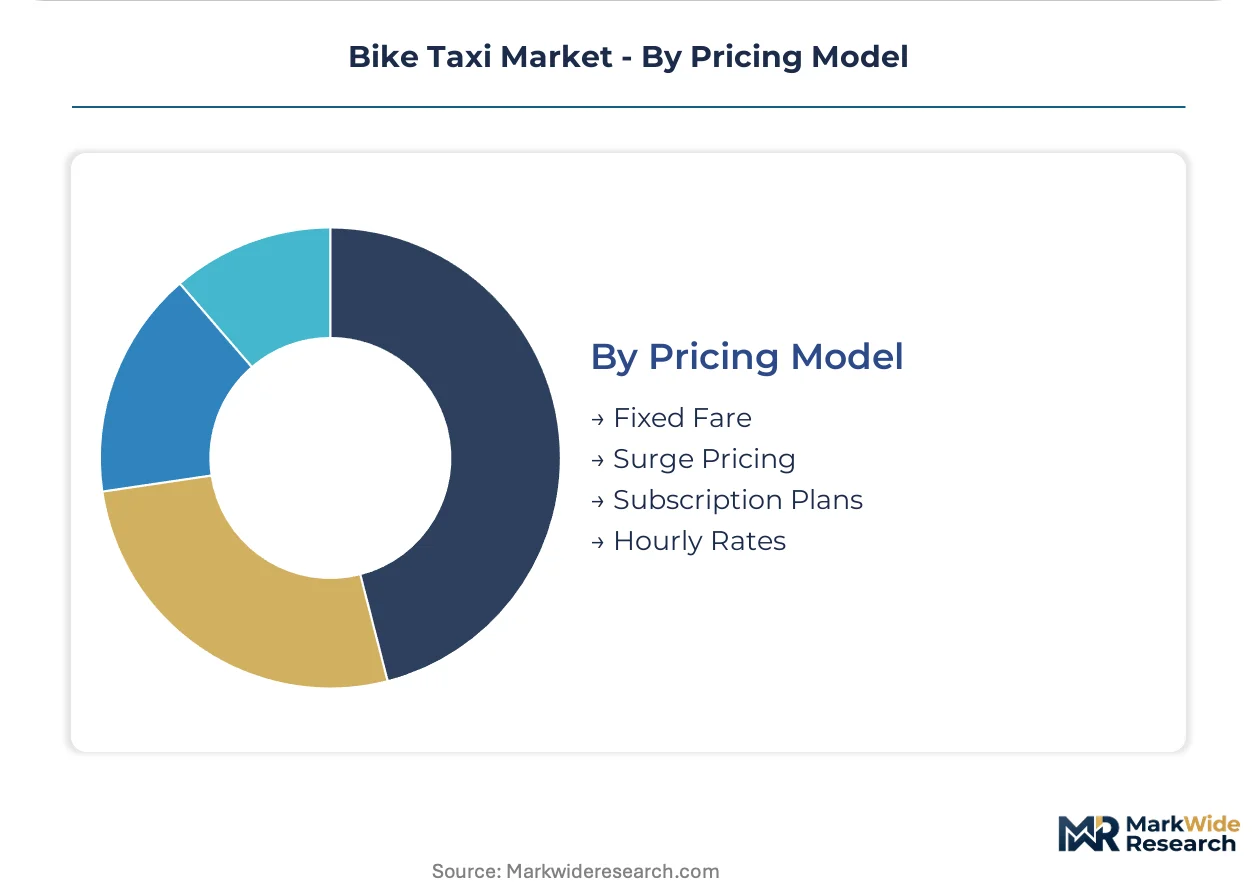
Pricing Model:
Revenue architecture choices balance demand elasticity, driver earnings stability, and platform margin capture.
- Fixed Fare:Pre-trip price certainty eliminates passenger surprise and supports corporate budgeting. Route-distance algorithms must account for traffic variability to protect driver margins.
- Surge Pricing:Dynamic multiplier mechanics balance supply-demand mismatches during peak windows. Regulatory scrutiny in multiple jurisdictions threatens deployment flexibility.
- Subscription Plans:Daily commuter lock-in models concentrate predictable revenue pools and reduce customer acquisition costs. Bangalore and Mumbai employers are negotiating bulk packages for staff transportation.
- Hourly Rates:Time-based billing for multi-stop itineraries and waiting periods. Niche application in business traveler segments with complex mobility requirements.
Fixed fare holds installed capacity. Subscription plans is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS mandates in India anchor regulatory formalization for commercial two-wheeler operations. Fleet certification requirements and GPS tracking obligations are rewriting compliance thresholds across high-density urban corridors.
India
Daily commuter volume between Mumbai, Bangalore, and Delhi generates concentrated demand for sub-10 kilometer trips. BIS helmet and vehicle safety standards mandate structural modifications and designated testing facility certification. Fleet operators in Maharashtra and Karnataka face compliance backlogs that favor platforms with dedicated certification teams.
Indonesia
Jakarta's traffic saturation creates structural demand for congestion-bypassing mobility options. The national transport ministry has integrated bike taxis into licensed commercial frameworks with insurance mandates. PT GoTo Gojek Tokopedia Tbk dominates urban corridors through dual-platform merchant and mobility network density.
Vietnam
Ho Chi Minh City's narrow street grids and parking scarcity push commuters toward two-wheeled alternatives. Local regulations require commercial driver licensing and vehicle registration for fleet operations. Platform operators concentrate driver onboarding in District 1 and District 7 commercial zones.
Thailand
Bangkok's chronic congestion extends four-wheeled trip durations beyond commuter tolerance thresholds. The transport ministry has formalized bike taxi licensing categories with mandatory GPS tracking provisions. Fleet deployment clusters along BTS and MRT transit corridors for last-mile connectivity capture.
United States
Urban last-mile gaps in Los Angeles and Miami create niche demand for two-wheeled mobility services. FCC guidelines govern GPS navigation accuracy and communication device certification for fleet operators. LA Taximoto occupies a position in the California corridor with regulatory-compliant commercial operations.
Bike Taxi Market Vendor Landscape
Capability concentration sits with technology-integrated platforms; scale advantage sits with established ride-hailing incumbents. The market structures around three tiers: global mobility super-apps with cross-selling ecosystems, regional specialists with hyperlocal payment integration, and emerging platforms with fleet-heavy operational models. Dominant competitive moves include strategic partnerships with municipal transit authorities and portfolio diversification into subscription commuter plans.
Within the super-app tier, Uber Technologies Inc. and Grab Holdings Ltd. exemplify cross-platform mobility integration. PT GoTo Gojek Tokopedia Tbk anchors the Southeast Asian specialist position with merchant-mobility network density. Bolt Technology OU and inDriver NA Inc. occupy challenger positions with driver-centric incentive structures and geographic expansion vectors.
| Leading Market Players |
|---|
| Roppen Transportation Services |
| inDriver NA Inc. |
| Uber Technologies Inc. |
| MAX BIKES SDN BHD |
| Ryde Technologies Pte. Ltd. |
| Grab Holdings Ltd. |
| Bolt Technology OU |
| LA Taximoto |
| PT GoTo Gojek Tokopedia Tbk |
| Others |
Supply Flow & Price Mechanics
Fleet undercapacity in India's BIS certification pipeline concentrates pricing power among platforms with dedicated compliance teams, while driver onboarding bottlenecks compress margins for capital-constrained operators. This utilization asymmetry forces a bifurcation between subscription-anchored incumbents and transactional competitors exposed to surge-pricing volatility.
Pricing Analysis
Price spreads between Jakarta and Bangkok reflect divergent regulatory enforcement intensity and fuel subsidy regimes. Three-tier pricing structure across premium, standard, and economy levels segments commuters by reliability requirements and booking flexibility. Price differentiation rests on BIS certification status and GPS telemetry integration depth. Cost compression in the economy tier is intensifying because driver supply expansion outpaces demand growth in saturated corridors. Students exhibit highest price sensitivity; corporate contract negotiators show lowest.
Supply Chain Analysis
Contract manufacturing for GPS tracking hardware concentrates in Taiwan and mainland China, with FCC-certified device assembly anchored in Mexico for North American fleet operators. Battery cell production draws from South Korea and Japan for thermal-managed electric two-wheeler deployments. Raw material dependencies span lithium carbonate, rare-earth magnets for motors, and ABS-grade polymers for helmet shells. Single-source vulnerability in semiconductor-based telematics chips threatens fleet scaling timelines. Distribution runs through platform-controlled driver onboarding centers and third-party vehicle retrofit workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
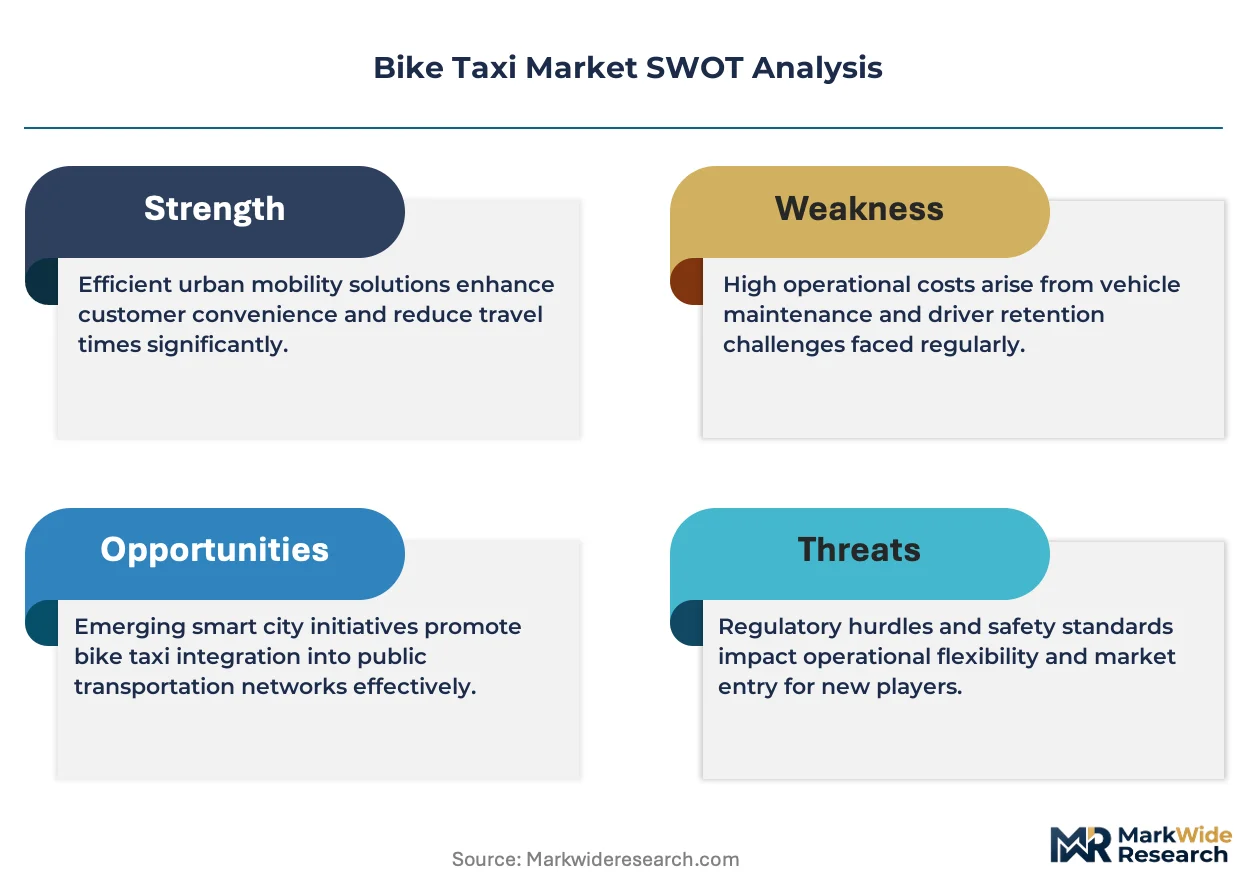
This market rewards regulatory entrenchment as the primary defensive moat. BIS certification backlogs and municipal licensing fragmentation create structural barriers that compound with scale.
For Market Incumbents: Insulate market position by accelerating backward integration into BIS-designated testing facilities and captive driver training academies. Lock in corporate commuter contracts with annual service-level agreements before emerging platforms achieve certification parity. The threat of labor reclassification rulings demands pre-emptive insurance structure redesign. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's District 7 and Ho Chi Minh City periphery corridors where incumbent density remains thin. Target student segments with semester-pass pricing and campus-partnership distribution. A go-to-market angle anchored in electric vehicle-only positioning exploits BIS thermal-management scrutiny gaps affecting petrol fleet conversions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GPS telemetry and certification infrastructure. Long-term viability favors platforms with municipal transit authority partnerships and subscription revenue concentration. Acquisition target archetype: regional specialists with hyperlocal payment-wallet integration and unexploited corporate sales channels. Monitor BIS certification queue clearance rates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Plan Expansion | Corporate commuter contracts in Bangalore and Mumbai concentrate predictable revenue pools. |
| BIS Certification Investment | Dedicated testing facility access unlocks insurance coverage and fleet scaling permissions. |
| Hyperlocal Payment Integration | Embedded wallet services capture transaction economics beyond ride fees in Jakarta. |
| Electric Fleet Transition | Battery thermal management compliance creates differentiation under India's safety mandates. |
| Municipal Transit Partnership | Last-mile connectivity carve-outs along BTS and MRT corridors secure preferential access lanes. |
Methodological Framework
A standing panel of fleet operations directors, driver onboarding managers, municipal transport regulators, and corporate mobility procurement officers provided ongoing calibration across the study period. Primary interviews with platform executives and secondary validation against BIS certification databases, Indonesia's transport ministry licensing records, and Vietnam's commercial driver registration systems anchored supply-side estimates. Bottom-up driver capacity modeling and top-down urban commuter flow analysis enabled triangulation.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning service format, customer archetype, propulsion technology, and regional regulatory cluster. CAGRs derived from historical fleet deployment trajectories and commuter adoption elasticity curves. Forecast inputs incorporated BIS mandate implementation timelines and EU Green Deal low-emission zone expansion schedules.
Stress conditions across fuel price volatility, battery supply concentration, and labor classification rulings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and platform technology investment continuity. Quarterly review of certification queue lengths and corporate contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Used Bike Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Motorcycle Rider Assistance System Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Three Wheeled Motorcycle Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market