
 Motorcycle Chain Market | 2026-2036
Motorcycle Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Chain Market Foresight
Multi-source procurement among Japanese OEMs is rebalancing toward qualified regional foundries as shipping volatility persists. Daido Kogyo Co., Ltd. (D.I.D) anchors premium O-ring and X-ring output through captive heat-treatment facilities in Japan. RK Japan competes on racing-derived specifications that transfer to street applications. Qingdao Choho Industrial Co., Ltd leverages coastal steel access to dominate standard-chain exports across Asia.
A motorcycle chain is a roller chain transmitting engine power to the rear wheel, typically constructed from alloy steel with pin diameters between 5.5 mm and 10 mm and subjected to carbonitriding for wear resistance. Its primary function is to sustain tensile loads exceeding 3,000 kgf while maintaining efficiency across variable RPM ranges. O-ring chains command margin pools in touring and cruiser segments where longevity justifies premium positioning. X-ring variants lead sport bike applications as reduced friction translates to measurable horsepower retention. Steel remains the overwhelming material choice; titanium occupies a narrow enthusiast niche where weight reduction overrides cost sensitivity.
Japan's METI enforces JIS standards on fatigue life and corrosion resistance that effectively gate non-compliant imports. India's BIS certification mandates minimum tensile strength ratings for chains sold through domestic OEM channels. REACH compliance in Europe restricts certain surface-treatment chemistries, elevating cost for suppliers serving multiple regulatory zones. Stakeholders must calibrate alloy formulations and testing protocols against diverging national standards rather than pursuing single-platform certification.
Market Dynamics
Sealed-ring chain technology is bifurcating procurement patterns as Southeast Asian sport bike ownership accelerates replacement cycles toward premium O-ring and X-ring specifications, compressing standard-chain margins while elevating heat-treatment capacity constraints.
Growth Catalysts
- India's BIS tensile mandates:Domestic OEM certification requirements concentrate demand on qualified suppliers, reinforcing captive foundry relationships with commuter motorcycle producers.
- Carbonitriding process advances:Extended fatigue life from refined surface-hardening protocols is extending replacement intervals for touring segments, locking in aftermarket loyalty.
- Southeast Asia sport bike proliferation:Rising disposable income in Indonesia, Vietnam, and Thailand is displacing standard-chain fitment with X-ring specifications in 250cc-plus displacement categories.
Market Restraints
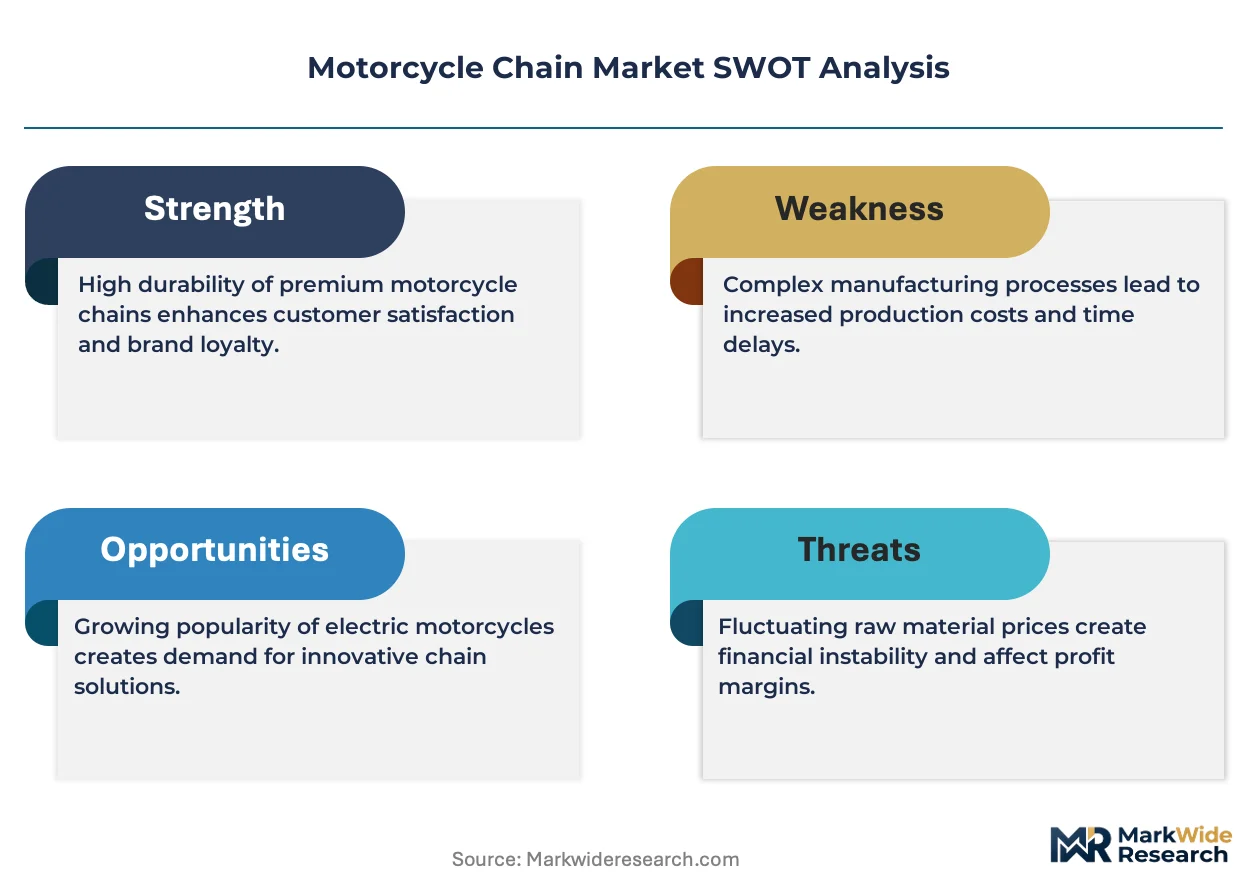
- Alloy steel input volatility:Scrap metal and ferroalloy price swings transmit directly to foundry cost structures, compressing margin predictability for heat-treatment-intensive producers.
- Japan METI carbon-neutrality pressure:Cleaner steel production mandates are elevating capital intensity for JIS-compliant domestic foundries, gating capacity expansion.
- Belt-drive substitution in electric motorcycles:Maintenance-free synchronous belt systems are displacing chain final-drive in urban electric two-wheeler architectures, narrowing addressable volume in emerging powertrain categories.
Strategic Opportunities
- Indonesia underpenetrated premium aftermarket:Archipelago geography and informal service networks create whitespace for branded sealed-ring distribution through consolidated parts retailers.
- EU REACH surface-treatment compliance:Restricted chemistries elevate cost for multi-zone suppliers, creating competitive moat for European-certified specialists serving touring and cruiser segments.
- Digital parts-catalog integration:QR-code-linked fitment databases are converging with mobile-first purchasing behavior, enabling direct-to-workshop channels that bypass traditional distributor tiers.
Industry Challenges
- Heat-treatment technician scarcity:Captive furnace operation and atmosphere control expertise is concentrating among aging workforces in Japanese and German supplier bases, constraining quality replication.
- JIS-BIS-REACH multi-certification timelines:Diverging fatigue-test protocols and corrosion-resistance standards force parallel validation runs, extending product launch cycles for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Chain Market |
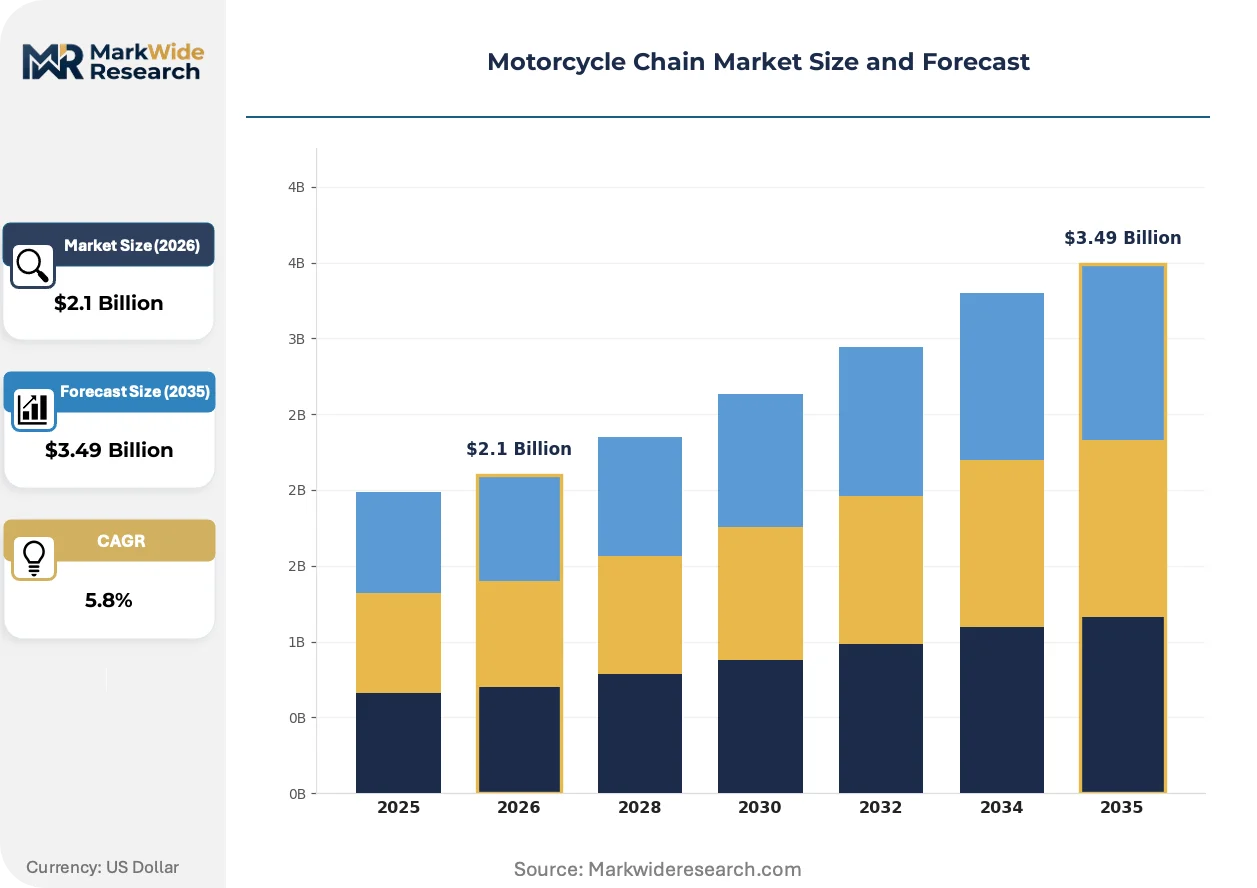
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chains, O-ring Chains, X-ring Chains, Heavy-Duty Chains Application: Sport Bikes, Cruiser Bikes, Touring Bikes, Dirt Bikes Material: Steel, Aluminum, Titanium, Composite End User: OEMs, Aftermarket Suppliers, Enthusiasts, Distributors |
| Companies Covered | Daido Kogyo Co., Ltd. (D.I.D), RK Japan, Tsubakimoto Chain Co., Renthal Ltd, Regina Catene Calibrate S.p.A, KMC, Qingdao Choho Industrial Co., Ltd, Rockman Industries, Enuma Chain Mfg. Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Chain Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are restructuring competitive differentiation around surface-engineering capabilities rather than scale economies alone, compressing standard-chain supplier margins while elevating premium-tier value capture.
Self-lubricating sintered bushing technology is converging with sealed-ring architectures to eliminate external lubrication intervals, extending service life beyond 20,000 kilometers in commuter applications. OEMs in India and Brazil are specifying this hybrid construction for 125-150cc volume models, compressing aftermarket replacement revenue while locking in initial-fitment supplier relationships.
Japan's METI carbon-neutrality roadmap is forcing foundry emission retrofits that elevate clean-steel premiums by mid-single-digit percentages, transmitting through captive heat-treatment facilities. European touring-bike assemblers are absorbing these input costs through sealed-ring specification upgrades, while standard-chain exporters from coastal Chinese foundries face margin compression from dual-zone compliance overhead.
Workshop-level procurement is fragmenting toward mobile-platform ordering with same-day fulfillment guarantees, displacing traditional multi-tier distributor stocking in urban Indonesian and Vietnamese markets. Consolidated parts retailers are capturing this channel shift through captive app-based fitment tools, compressing independent distributor relevance in high-frequency replacement geographies.
Motorcycle Chain Market Segmentation
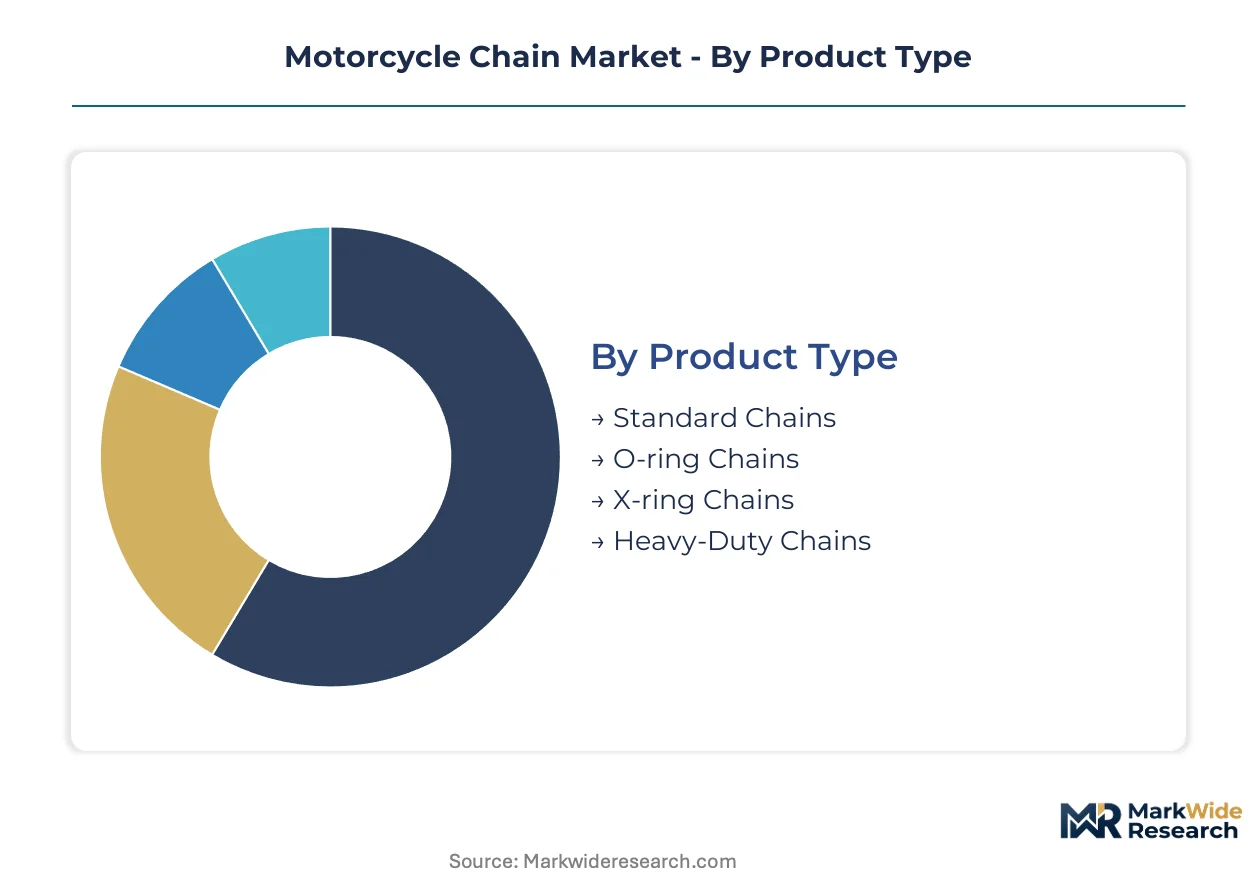
Replacement cycle timing and upgrade economics govern how motorcycle chain demand fragments across product tiers. Segmentation reveals where margin pools concentrate versus where volume commoditization erodes supplier returns.
Product Type:
Upgrade trajectories from standard to sealed-ring specifications are compressing replacement frequency while elevating per-unit revenue capture for heat-treatment-capable foundries.
- Standard Chains:Non-sealed roller chains constructed from through-hardened carbon steel with exposed pin-bushing interfaces requiring frequent lubrication. Demand concentrates in India's 100-125cc commuter segment where BIS tensile mandates enforce minimum specifications but price sensitivity blocks premium migration; foundry relationships with Hero MotoCorp and Bajaj Auto lock in volume placements despite thin margins.
- O-ring Chains:Elastomer-sealed variants with nitrile or Viton rings retaining factory lubrication between pin and bushing, extending service intervals to 8,000-12,000 kilometers. Touring and cruiser applications in Germany and the United States absorb elevated pricing where longevity justifies premium positioning; ECHA REACH compliance on surface treatments elevates cost for multi-zone suppliers, creating moats for European-certified specialists.
- X-ring Chains:X-cross-section seals reduce friction surface area versus O-ring designs, translating to measurable horsepower retention in high-RPM applications.
- Heavy-Duty Chains:Oversized pin and plate constructions rated for continuous loads exceeding 5,000 kgf in displacement categories above 800cc.
Volume placements concentrate in Standard Chains; the faster expansion belongs to X-ring Chains.
Application:
Displacement category and riding intensity separate customers by replacement frequency and specification willingness-to-pay.
- Sport Bikes:High-RPM architectures demanding X-ring or racing-derived specifications with sub-2% elongation tolerance over 5,000 kilometers. Indonesia, Vietnam, and Thailand show accelerating displacement migration toward 250cc-plus categories where reduced friction translates to competitive lap times; informal service networks create whitespace for branded sealed-ring distribution through consolidated parts retailers.
- Cruiser Bikes:Low-RPM, high-torque final-drive systems prioritizing tensile strength over friction reduction. North American and European touring segments absorb premium O-ring positioning where aesthetic chrome plating and extended warranty terms support margin capture; carbonitriding process advances from Japanese suppliers extend fatigue life beyond 20,000 kilometers, locking in aftermarket loyalty.
- Touring Bikes:Long-distance applications combining load capacity with weather resistance.
- Dirt Bikes:Off-road architectures exposed to abrasive contaminants and shock loading.
Replacement frequency peaks in Dirt Bikes; margin stability concentrates in Cruiser Bikes.
Material:
Alloy formulation directly determines heat-treatment response and fatigue life certification under diverging national standards.
- Steel:Alloy formulations dominate across all displacement categories, with 8620 and 4140 grades subjected to carbonitriding for case hardness exceeding 60 HRC. India's BIS certification mandates minimum tensile strength ratings that effectively gate non-compliant imports; scrap metal and ferroalloy price swings transmit directly to foundry cost structures, compressing margin predictability.
- Titanium:Ti-6Al-4V occupies a narrow enthusiast niche where weight reduction overrides cost sensitivity in racing applications.
- Aluminum:Limited to decorative components and non-structural applications due to insufficient tensile performance.
- Composite:Experimental fiber-reinforced polymers under evaluation for electric motorcycle belt-drive substitution scenarios.
Cost-performance optimization centers on Steel; Titanium captures niche premium positioning.
End User:
Channel structure and procurement authority separate captive OEM relationships from fragmented aftermarket access.
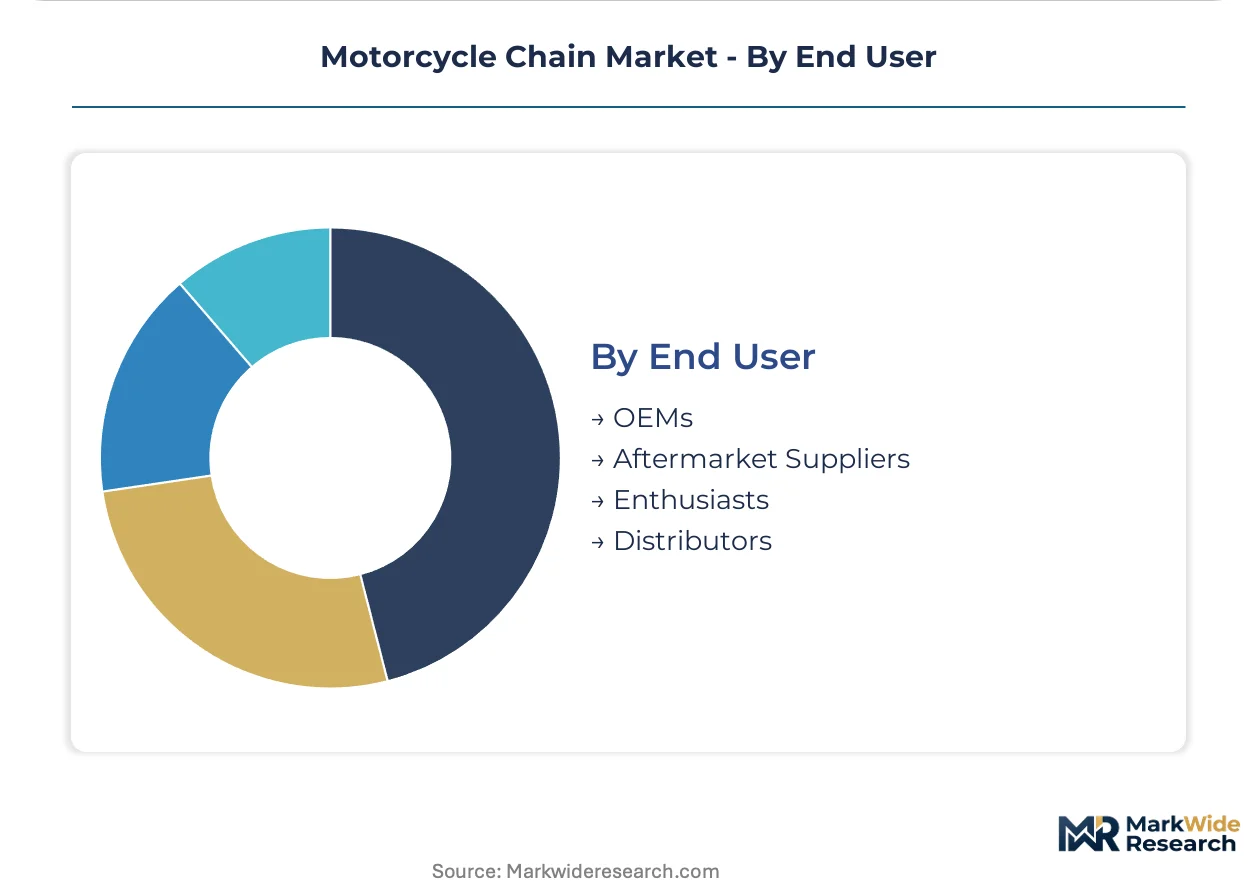
- OEMs:Volume motorcycle assemblers specifying initial-fitment chains with multi-year supply agreements and captive heat-treatment audit requirements. Japanese OEMs are rebalancing procurement toward qualified regional foundries as shipping volatility persists; Daido Kogyo anchors premium O-ring and X-ring output through captive facilities.
- Aftermarket Suppliers:Independent distributors and consolidated parts retailers serving replacement demand. Workshop-level procurement is fragmenting toward mobile-platform ordering with same-day fulfillment guarantees in Indonesian and Vietnamese urban markets; QR-code-linked fitment databases enable direct-to-workshop channels that bypass traditional distributor tiers.
- Enthusiasts:Direct purchasers prioritizing racing-derived specifications and brand heritage.
- Distributors:Multi-tier intermediaries facing compression from digital catalog integration and captive app-based fitment tools.
Contract security concentrates with OEMs; channel disruption reshapes Aftermarket Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates replacement-cycle volume as commuter motorcycle ownership sustains elevated aftermarket turnover. Southeast Asian markets are displacing standard-chain fitment with sealed-ring specifications as sport bike displacement categories expand. Diverging national certification standards reshape procurement geography.
India
Commuter motorcycle volumes exceeding 15 million units annually sustain the world's largest replacement-chain aftermarket. BIS tensile-strength mandates gate non-compliant imports, reinforcing captive foundry relationships with Hero MotoCorp and Bajaj Auto. Manufacturing clusters in Pune and Manesar concentrate heat-treatment capacity serving domestic OEM channels.
Japan
Carbon-neutrality roadmaps from METI are elevating clean-steel production costs for JIS-compliant domestic foundries. Premium O-ring and X-ring specifications anchor export competitiveness to European and North American touring segments. Kanto and Chubu industrial corridors retain captive heat-treatment expertise amid aging-technician scarcity.
Indonesia
Archipelago geography and informal service networks create whitespace for branded sealed-ring distribution as 250cc-plus sport bike ownership accelerates. National standardization agency SNI requirements on fatigue testing parallel BIS protocols, favoring pre-qualified suppliers. Jababeka and MM2100 industrial zones near Jakarta concentrate aftermarket parts consolidation.
Germany
EU REACH restrictions on surface-treatment chemistries elevate compliance costs for multi-zone suppliers serving touring and cruiser segments. ECHA enforcement creates competitive moats for European-certified specialists. Baden-Württemberg and Bavaria host premium aftermarket distributors specifying extended-warranty O-ring fitments.
Vietnam
Workshop-level procurement is fragmenting toward mobile-platform ordering with same-day fulfillment guarantees in Ho Chi Minh City and Hanoi. Rising disposable income displaces standard-chain fitment in 150cc-plus categories. Northern industrial provinces concentrate steel-forging capacity serving regional export demand.
Motorcycle Chain Market Competitive Landscape
Capacity expansion dominates the current landscape as heat-treatment-intensive producers scale carbonitriding furnace networks. The vendor base separates into three tiers: Japanese specialists with captive Japanese facilities, Chinese coastal exporters leveraging raw material access, and European-certified niche suppliers. Strategic archetypes include premium sealed-ring specialists, scale-driven standard-chain exporters, and vertically integrated OEM captive suppliers. Competitive moves center on regional foundry qualification for multi-source procurement and digital catalog integration bypassing traditional distributor tiers.
Among Japanese specialists, Daido Kogyo Co., Ltd. (D.I.D) and RK Japan exemplify the premium-tier archetype with heat-treatment capabilities concentrated domestically. Tsubakimoto Chain Co. occupies a position bridging industrial and motorcycle applications. Qingdao Choho Industrial Co., Ltd represents the scale-driven coastal export model. These three anchors illustrate how geographic origin and captive facility ownership stratify competitive positioning across certification-intensive markets.
| Leading Market Players |
|---|
| Daido Kogyo Co., Ltd. (D.I.D) |
| RK Japan |
| Tsubakimoto Chain Co. |
| Renthal Ltd |
| Regina Catene Calibrate S.p.A |
| KMC |
| Qingdao Choho Industrial Co., Ltd |
| Rockman Industries |
| Enuma Chain Mfg. Co., Ltd. |
| Others |
Supply & Pricing Matrix
Heat-treatment technician scarcity in Japan and Germany widens pricing-tier spreads between premium sealed-ring chains and commodity standard chains, as labor-cost differentials transmit through captive furnace operation and atmosphere control expertise.
Pricing Analysis
Warranty bundling separates premium-tier positioning from unbundled aftermarket transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and heat-treatment depth. Pricing pressure stems from alloy steel input volatility compressing margin predictability for carbonitriding-intensive producers. Commuter segments in India exhibit highest price sensitivity, while European touring buyers absorb elevated O-ring positioning where extended warranty terms justify premium capture.
Supply Chain Analysis
Container freight rate volatility and archipelago logistics in Indonesia reshape procurement economics for aftermarket distributors. Raw material sourcing draws from Japanese specialty steel mills, Chinese coastal foundries, and Indian domestic alloy suppliers. Supply chain risk centers on JIS-BIS-REACH multi-certification timelines forcing parallel validation runs. Distribution runs through consolidated parts retailers capturing mobile-platform ordering shifts in Southeast Asian urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH surface-treatment restrictions and diverging national fatigue-test protocols erect barrier-to-entry moats for European-certified specialists and Japanese JIS-compliant incumbents.
For Market Incumbents: Lock in captive heat-treatment capacity expansion in qualified regional foundries as shipping volatility persists. Deepen backward integration into specialty steel sourcing to buffer alloy input volatility. Defend against belt-drive substitution in electric motorcycle architectures by accelerating self-lubricating sintered bushing development for 125-150cc volume fitments. For New Entrants and Emerging Players: Launch via direct-to-workshop digital channels bypassing traditional distributor tiers in Indonesian and Vietnamese urban markets. Target underpenetrated premium aftermarket whitespace in Indonesia's archipelago geography where informal service networks fragment incumbent control. Prioritize SNI fatigue-test pre-qualification to access displacement migration toward 250cc-plus sport bike categories. For Investors and Strategic Acquirers: Re-rating potential sits with European-certified niche specialists given ECHA enforcement elevating compliance costs for multi-zone suppliers. Long-term viability favors heat-treatment-capable foundries with captive technical workforce development programs. Watch Indonesia's national standardization agency SNI adoption pace as inflection indicator for sealed-ring specification penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Facility Expansion | Carbonitriding furnace networks in Japan and India lock in JIS and BIS certification compliance for premium O-ring and X-ring output. |
| Regional Foundry Qualification | Multi-source procurement rebalancing toward qualified Southeast Asian foundries reduces shipping volatility exposure for Japanese OEMs. |
| Digital Parts-Catalog Integration | QR-code-linked fitment databases converge with mobile-first purchasing behavior in Indonesian and Vietnamese workshop channels. |
| Self-Lubricating Sintered Bushing Development | Hybrid construction eliminates external lubrication intervals, extending service life beyond 20,000 kilometers in Indian commuter applications. |
| EU REACH Surface-Treatment Compliance Investment | Restricted chemistries elevate cost for multi-zone suppliers, creating competitive moat for European-certified specialists serving touring segments. |
Research Methodology
Independent corroboration across heat-treatment facility audits, OEM procurement director interviews, and aftermarket distributor operational reviews underwrites the qualitative findings. Primary fieldwork engaged plant managers at Japanese and Indian carbonitriding facilities, procurement leads at Hero MotoCorp and Bajaj Auto, channel partners in Jakarta and Ho Chi Minh City, and technical R&D directors at sealed-ring specialists. Secondary validation drew from METI JIS standard filings, BIS tensile-strength certification records, ECHA REACH restriction updates, and customs trade data on alloy steel imports. Bottom-up volume modeling triangulated against top-down market sizing across product tiers.
Rate-of-change decomposition across the analysis window segments expansion by product type, application displacement category, material grade, and end-user channel structure. CAGRs derive from replacement-cycle timing analysis, upgrade economics modeling, and sport bike displacement migration patterns in Southeast Asia. Forecast inputs incorporate BIS tensile mandate enforcement trajectories, METI carbon-neutrality retrofit timelines, and belt-drive substitution rates in electric two-wheeler architectures.
Alloy steel price volatility, regulatory certification timeline extensions, and technician workforce attrition are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on displacement category growth and sealed-ring specification penetration. Stakeholders should weight assumptions against their own operating context and captive certification status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Trike Market
Bikes and Motorcycles
Ride on Bikes Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
LAMEA Motorcycle ADAS Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Motorsport Components Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market