
 Motion Control Software in Robotics Market | 2026-2036
Motion Control Software in Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Control Software in Robotics Market Outlook
Buyer concentration among automotive OEMs is restructuring procurement patterns for motion control software as tier-one suppliers consolidate their vendor rosters. ABB leverages its integrated hardware-software stack to dominate European automotive lines. FANUC Corporation anchors its position through captive servo systems and proprietary controller architectures. Yaskawa Electric Corporation competes aggressively in Asian manufacturing hubs with high-speed trajectory optimization.
Motion control software in robotics encompasses algorithms and firmware that govern position, velocity, and torque in electromechanical systems, typically executing closed-loop updates at 1-10 kHz to maintain sub-millimeter path accuracy in multi-axis configurations. Its primary purpose is to translate high-level task commands into real-time motor signals that synchronize manipulator joints, mobile platforms, or process tooling. Software Platforms currently capture the highest margin pools as vendors bundle AI-driven path planning with predictive maintenance analytics. Servo Control leads in revenue share due to its ubiquity in precision manufacturing, while Distributed Control Systems represent the fastest-expanding technology segment as edge-computing architectures decentralize processing across factory floors.
The EU AI Act and Machinery Directive impose conformity requirements on autonomous robotic systems deployed in European manufacturing facilities. The FDA regulates surgical and diagnostic robotic platforms in the United States through premarket clearance pathways that validate motion control safety. Japan's METI promotes next-generation robotics through JIS standards that harmonize interoperability benchmarks. Stakeholders must monitor how divergent regional certification timelines affect product release cycles and localization costs.
Market Dynamics
Automotive OEM procurement consolidation is compressing vendor ecosystems for motion control software, forcing suppliers to deliver integrated hardware-software stacks or exit tier-one supplier rosters entirely. This concentration dynamic favors incumbents with captive servo architectures and penalizes point-solution vendors lacking full-stack capabilities.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers must retrofit existing robotic lines with transparent motion control algorithms, generating replacement demand for software platforms that document decision pathways in real-time.
- High-speed trajectory optimization:Asian electronics manufacturers deploy sub-millisecond path planning to maintain throughput on compact assembly floors where space constraints limit robot arm reach.
- Germany's industrial clustering:Stuttgart and Munich manufacturing corridors concentrate demand for precision motion systems, creating localized scale effects that accelerate vendor specialization in automotive-grade control firmware.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependencies on Chinese processing facilities expose servo motor costs to geopolitical supply disruptions and export quota volatility.
- Real-time kernel licensing costs:Proprietary RTOS platforms for 1-10 kHz closed-loop control carry per-unit royalties that inflate software stack economics for mid-volume robot OEMs.
- Functional safety certification friction:IEC 61508 and ISO 13849 compliance timelines for autonomous robotic systems extend 18-24 months, delaying product commercialization and freezing R&D amortization.
Strategic Opportunities
- India's PLI scheme for robotics:Production-linked incentives for advanced manufacturing equipment create localized assembly demand where motion control software vendors can establish captive development centers.
- Edge-computing decentralization:Distributed control architectures that process servo loops at factory-floor nodes rather than centralized PLCs open white space for software vendors with lightweight runtime environments.
- Medical robotics FDA pathway:Surgical platform premarket clearance requirements for motion control safety create premium pricing tiers for vendors with validated fault-tolerant firmware architectures.
Industry Challenges
- Embedded control systems engineering scarcity:The talent pool for hard real-time programming in C and assembly for DSP architectures remains shallow, inflating compensation costs and extending hiring cycles.
- Legacy fieldbus integration complexity:EtherCAT and PROFINET migration from proprietary serial protocols requires middleware layers that degrade deterministic performance and expand validation scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Control Software in Robotics Market |
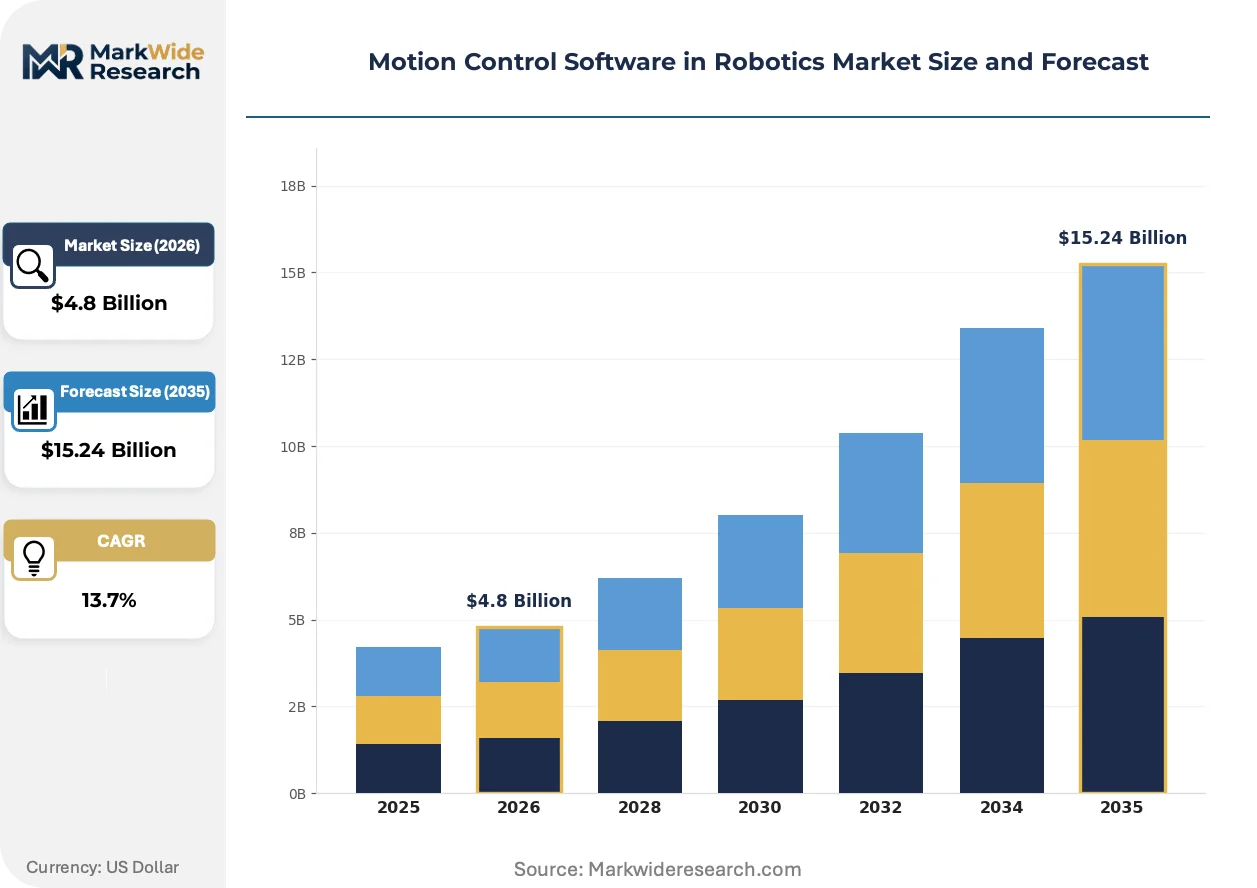
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Controllers, Motion Controllers, Drive Technology, Software Platforms End User: Manufacturing, Aerospace, Automotive, Healthcare Technology: Servo Control, Stepper Control, PID Control, Distributed Control Systems Application: Industrial Automation, Robotics Research, Process Automation, Autonomous Vehicles |
| Companies Covered | ABB, FANUC Corporation, Yaskawa Electric Corporation, KUKA AG, Omron Corporation, Teradyne, Yamaha Motor, Denso Corporation, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Control Software in Robotics Market Strategic Shifts
Model-based control architectures are displacing hand-tuned PID loops across precision manufacturing, compressing commissioning timelines while demanding new competencies in physics simulation and system identification.
Physics-informed neural networks for motion control are consolidating algorithm development around differentiable simulation frameworks that train policies in virtual environments before hardware deployment. Automotive battery assembly lines adopt these methods to reduce physical commissioning cycles from months to weeks. The technology is consolidating competitive advantage around vendors with in-house multibody dynamics expertise rather than traditional control theory backgrounds.
The EU Machinery Directive's updated conformity assessment procedures for collaborative robots now mandate validated human-robot interaction limits with documented force-torque thresholds. German automotive suppliers face the steepest compliance costs as they retrofit existing lines for power-and-force limiting functionality. Tier-one integrators respond by pre-certifying complete robot-controller-software bundles to accelerate end-user deployment timelines.
Automotive OEMs now unbundle motion control software licensing from hardware procurement, separating perpetual controller purchases from subscription-based algorithm updates and predictive maintenance analytics. This shift disrupts traditional capital-equipment distributors who lack recurring revenue infrastructure. The transformation is most visible in Germany, where Stuttgart-based manufacturers pilot usage-based pricing for trajectory optimization modules tied to actual production volume.
Motion Control Software in Robotics Market Segmentation
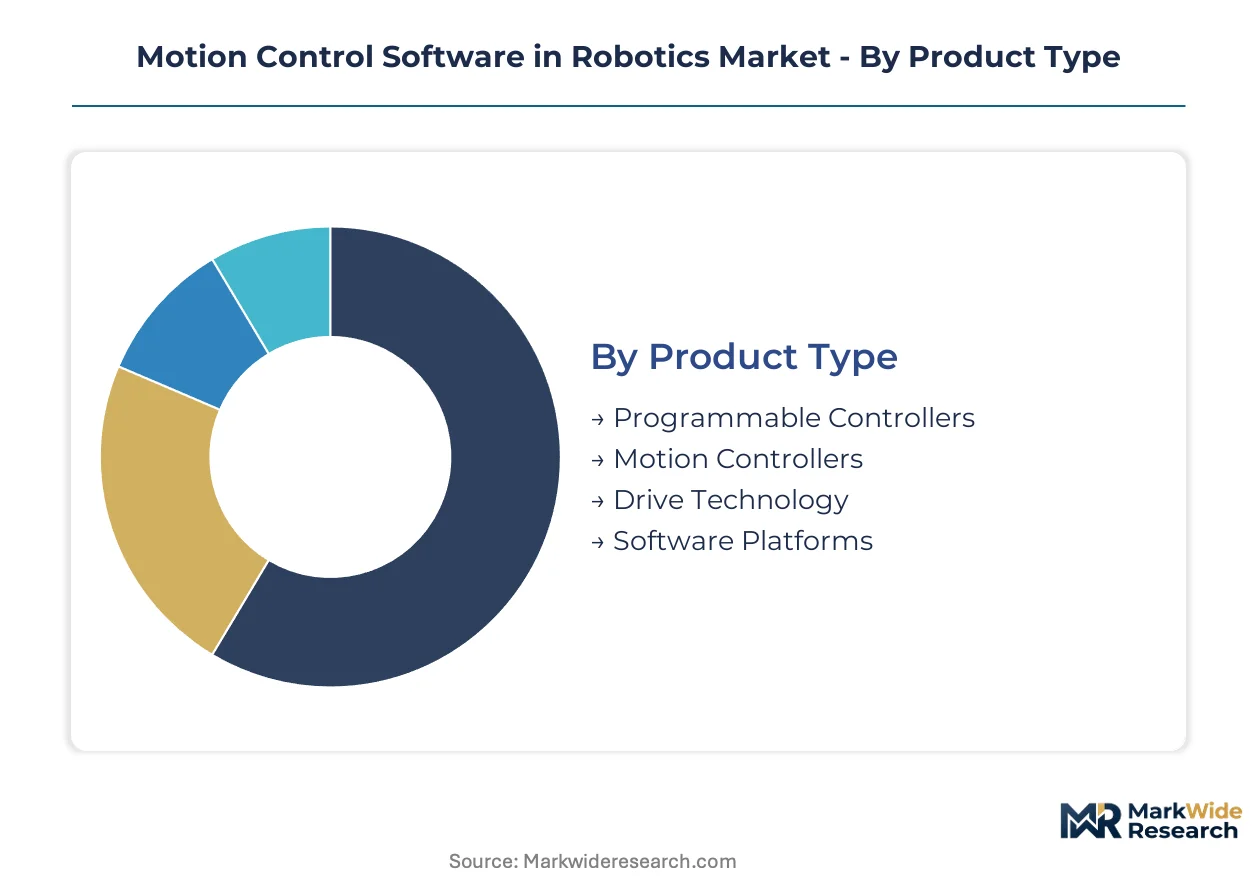
Motion control software segmentation reveals how certification burdens, application complexity, and hardware integration requirements reshape procurement decisions across robotics verticals. Each dimension carries distinct regulatory weight and margin implications for vendors positioning across automotive lines, surgical platforms, and factory-floor deployments.
Product Type:
Software Platforms require EU AI Act algorithmic transparency documentation and IEC 61508 functional safety certification, while Drive Technology faces Machinery Directive conformity assessments for integrated servo-motor combinations.
- Software Platforms:Bundled AI-driven path planning with predictive maintenance analytics command premium pricing tiers. Automotive OEMs in Stuttgart and Munich corridors concentrate procurement here for trajectory optimization modules with usage-based licensing.
- Motion Controllers:Real-time firmware executing 1-10 kHz closed-loop updates for multi-axis synchronization. Demand clusters in German automotive lines where ABB and FANUC anchor integrated hardware-software stacks.
- Programmable Controllers:General-purpose automation logic with motion control extensions.
- Drive Technology:Integrated servo amplifiers and motor control electronics.
Leading the category by volume: Motion Controllers. Growing fastest: Software Platforms.
End User:
Automotive procurement consolidation favors vendors delivering full-stack solutions, while Healthcare demands FDA premarket clearance for surgical motion control safety.
- Automotive:Robotic assembly lines require sub-millimeter path accuracy for battery module placement and powertrain assembly. German OEMs unbundle software licensing from hardware, shifting toward subscription-based algorithm updates.
- Healthcare:Surgical and diagnostic platforms face FDA validation requirements for fault-tolerant firmware architectures. Premium pricing tiers reward vendors with validated motion control safety documentation.
- Manufacturing:Electronics and general industrial automation.
- Aerospace:Precision component machining and assembly applications.
Highest certification burden: Healthcare. Steepest procurement consolidation: Automotive.
Technology:
Cost tiers separate proprietary RTOS-based solutions from open-standards architectures, with Distributed Control Systems carrying edge-computing infrastructure premiums.
- Servo Control:Closed-loop position-velocity-torque algorithms for precision electromechanical systems. Revenue concentration in manufacturing floors where EtherCAT and PROFINET migration demands middleware validation.
- Distributed Control Systems:Edge-computing architectures decentralizing servo loops across factory nodes. Asian electronics manufacturers deploy these for sub-millisecond path planning on compact assembly floors.
- Stepper Control:Open-loop positioning for lower-precision material handling.
- PID Control:Traditional feedback loops displaced by model-based architectures.
Widest deployment: Servo Control. Steepest expansion trajectory: Distributed Control Systems.
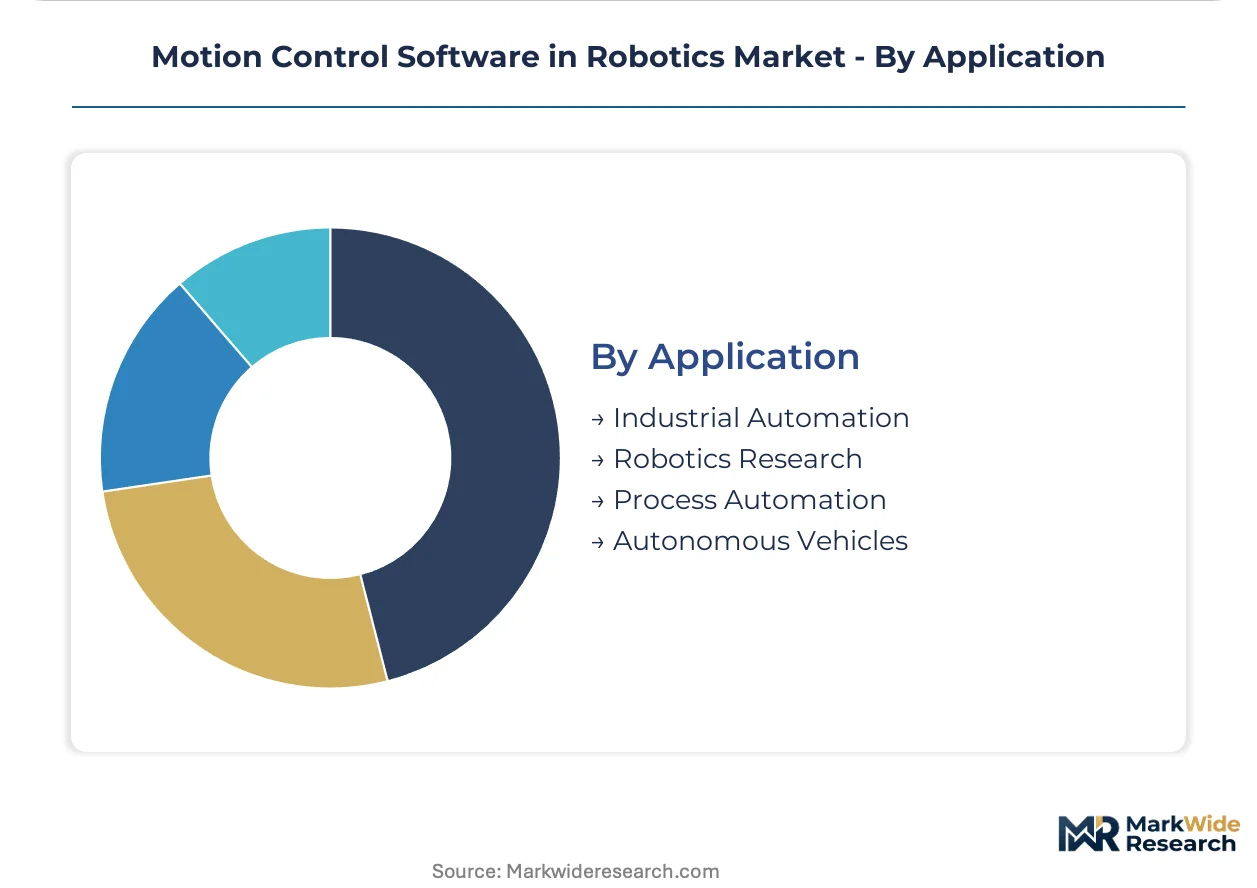
Application:
Application maturity determines whether customers accept standardized control firmware or demand customized commissioning with physics-informed neural network training.
- Industrial Automation:Mature demand with established IEC 61508 compliance pathways. Model-based control architectures displace hand-tuned PID loops, compressing commissioning timelines.
- Autonomous Vehicles:Emerging segment with NHTSA safety validation requirements for motion planning algorithms. Development concentrates in physics-informed neural networks trained in virtual environments.
- Robotics Research:Academic and R&D laboratory deployments.
- Process Automation:Continuous manufacturing with synchronized multi-axis control.
Deepest vendor specialization: Industrial Automation. Fastest algorithmic innovation: Autonomous Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for motion control software concentrates in automotive manufacturing corridors where precision assembly requirements intersect with tightening algorithmic transparency mandates. Germany's industrial clusters currently drive the highest per-facility software spend, while Asian electronics hubs accelerate deployment of decentralized control architectures.
Germany
Automotive OEM procurement consolidation and Machinery Directive retrofit mandates power demand across Stuttgart and Munich manufacturing belts. The EU AI Act imposes conformity requirements on autonomous robotic systems deployed in European facilities. Stuttgart-based manufacturers pilot usage-based pricing for trajectory optimization modules tied to actual battery module production volume.
United States
FDA-regulated surgical robotics and NHTSA autonomous vehicle validation create dual demand streams for fault-tolerant firmware architectures. The FDA premarket clearance pathway for diagnostic and surgical platforms mandates documented motion control safety. Detroit-area automotive suppliers unbundle software licensing from hardware procurement, shifting toward subscription-based algorithm updates.
China
Electronics contract manufacturers deploy sub-millisecond path planning on compact assembly floors where space constraints limit robot arm reach. MIIT promotes next-generation robotics through GB standards that harmonize interoperability benchmarks. Shenzhen and Dongguan manufacturing hubs concentrate demand for high-speed trajectory optimization in consumer electronics assembly.
Japan
Captive servo system architectures and proprietary controller designs anchor domestic vendor positions in precision manufacturing. METI promotes next-generation robotics through JIS standards that establish interoperability benchmarks. Nagoya and Osaka industrial corridors concentrate demand for automotive-grade control firmware in powertrain assembly applications.
India
Production-linked incentives for advanced manufacturing equipment create localized assembly demand for motion control platforms. The PLI scheme for robotics establishes captive development opportunities for software vendors with lightweight runtime environments. Gujarat and Maharashtra manufacturing clusters attract tier-one suppliers establishing regional engineering centers.
Motion Control Software in Robotics Market Competitive Environment
European producers anchor one tier; Asian specialists hold differentiated positions in high-speed trajectory optimization. The vendor ecosystem compresses as automotive OEM procurement consolidation forces suppliers to deliver integrated hardware-software stacks or exit tier-one rosters entirely. Three archetypes dominate: integrated stack providers with captive servo architectures, point-solution vendors with specialized path planning algorithms, and edge-computing platform developers. Competitive moves concentrate on strategic partnerships for RTOS licensing and geographic expansion into PLI-subsidized manufacturing corridors.
Within the integrated stack tier, ABB and FANUC Corporation exemplify vendors leveraging captive hardware-software combinations to dominate automotive line deployments. Yaskawa Electric Corporation occupies a position among Asian specialists competing aggressively in electronics manufacturing hubs. These three anchors represent how geographic origin and organizational structure map to competitive positioning in a market where full-stack capabilities increasingly determine procurement outcomes.
| Leading Market Players |
|---|
| ABB |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| KUKA AG |
| Omron Corporation |
| Teradyne |
| Yamaha Motor |
| Denso Corporation |
| Rockwell Automation |
| Others |
Value Chain & Pricing Dynamics
The EU AI Act's algorithmic transparency mandates gate qualified supply access and premium-tier pricing for motion control software vendors serving European automotive manufacturers. Compliance documentation requirements separate certified firmware providers from uncertified competitors, concentrating margin capture among vendors with pre-validated safety architectures.
Pricing Analysis
High-volume motion controller hardware generates thin margins while software platforms and subscription-based algorithm updates capture expanded profitability pools. Pricing stratifies across AI-enabled trajectory optimization tiers, IEC 61508 certification grades, and predictive maintenance bundling. Cost compression in standard servo control firmware intensifies as Chinese vendors enter mid-market segments with royalty-free RTOS alternatives. Tier-one automotive OEMs exhibit lowest price sensitivity for safety-critical battery assembly applications, while contract electronics manufacturers in Asia prioritize per-unit licensing minimization.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for motion control hardware fulfillment, with software delivery increasingly shifting to cloud-based license management. Neodymium and dysprosium processing concentrates in Chinese facilities, creating raw material dependencies for servo motor production. Single-source vulnerability in rare earth magnet supply exposes motor costs to export quota volatility. Distribution runs through captive OEM procurement portals and tier-one system integrator channels rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Motion control software is becoming a vertical-integration race where captive servo architectures and proprietary controller firmware determine procurement survival. Players are pursuing backward integration into real-time kernel development to escape per-unit royalty burdens.
For Market Incumbents: Anticipate margin erosion from open-source RTOS alternatives by deepening in-house production of safety-certified firmware stacks and accelerating IEC 61508 pre-certification for complete robot-controller bundles. Channel control through direct OEM procurement portals limits exposure to distributor disintermediation. For New Entrants and Emerging Players: Cloud-native deployment platforms offer the most penetrable entry vector for mid-volume robot OEMs seeking lightweight runtime environments without legacy fieldbus integration burdens. Target India's PLI-subsidized manufacturing corridors with localized engineering centers and usage-based pricing models calibrated to actual production volume. For Investors and Strategic Acquirers: FDA premarket clearance submissions for surgical motion control platforms are the leading indicator that premium pricing tiers will sustain across the medical robotics vertical. Acquisition candidates with validated fault-tolerant architectures and existing FDA documentation command defensive positioning value as compliance timelines extend.| Strategic Initiative | Industry Significance |
|---|---|
| RTOS Licensing Partnership | Reduces per-unit royalty exposure for mid-volume robot OEMs deploying EtherCAT architectures. |
| FDA Premarket Clearance Pathway | Unlocks premium pricing tiers for surgical platforms with validated motion control safety documentation. |
| Edge-Computing Platform Launch | Captures distributed control demand from Asian electronics manufacturers with sub-millisecond path planning requirements. |
| EU AI Act Compliance Certification | Accelerates German automotive procurement decisions through pre-validated algorithmic transparency documentation. |
| India PLI Corridor Expansion | Establishes captive development presence in Gujarat and Maharashtra manufacturing clusters. |
Study Parameters
Independent corroboration across motion control firmware engineering leads, automotive OEM procurement officers, and tier-one system integrator technical directors underwrites the qualitative findings in this analysis. Primary interviews with embedded control systems specialists, robotics platform architects, and factory automation consultants combined with secondary validation from IEC standards documentation, FDA 510(k) filings, EU Machinery Directive conformity assessment records, and SEC 10-K disclosures from publicly traded automation vendors. Bottom-up demand modeling across software platform, motion controller, and drive technology segments triangulated against top-down automotive production capacity forecasts.
Comparable-period anchoring to historical servo control deployment cycles and software licensing transitions structured the projection horizon. The analytical framework modeled segmentation across product type, end-user vertical, technology architecture, and application maturity, with regional regulatory cluster treated as an additional dimension. CAGRs derived from installed base growth rates, replacement demand coefficients, and unbundled software penetration assumptions. Physics-informed neural network adoption curves and edge-computing infrastructure deployment timelines served as industry-specific forecast inputs.
The model holds under stable rare earth magnet supply conditions and sustained EU AI Act enforcement timelines; deviation in Chinese export quota policy or Machinery Directive retrofit acceleration would shift replacement demand patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Marine Robots Market