
 Robotic Process Automation in Legal Services Market | 2026-2036
Robotic Process Automation in Legal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Process Automation in Legal Services Market Insights
Multi-source procurement of automation tools is restructuring how legal departments build technology stacks. UiPath leverages its partner ecosystem to extend platform reach into mid-sized law firms. Automation Anywhere anchors its position through cloud-native architectures that reduce IT overhead for corporate legal teams. IBM differentiates by embedding Watson capabilities into governance-heavy compliance workflows.
Robotic Process Automation in Legal Services deploys software bots to execute repetitive legal tasks such as document extraction, contract clause comparison, and regulatory filing preparation, typically operating through rule-based scripts with optional AI augmentation for unstructured data interpretation. The primary commercial purpose centers on compressing cycle times for due diligence, discovery, and contract management while reducing human error rates in high-volume document processing. Document automation leads solution type adoption because contract generation and review consume disproportionate associate hours across firms of all sizes. Cloud-based deployment is expanding fastest among end user categories as corporate legal departments prioritize scalable subscription models over capital-intensive on-premise installations.
The EU AI Act and the American Bar Association's evolving ethics guidelines on technology competence shape vendor product roadmaps and client procurement criteria across both jurisdictions. GDPR data processing requirements constrain how RPA tools handle client matter information in European deployments, pushing suppliers toward enhanced encryption and regional data residency architectures. Stakeholders must monitor how emerging AI liability frameworks redefine the boundary between attorney oversight and automated legal output.
Market Dynamics
The EU AI Act's risk-based classification system for automated legal decision-making is forcing vendors to re-engineer certification pathways and client legal departments to restructure oversight protocols for bot-generated outputs.
Growth Catalysts
- EU AI Act compliance mandates:High-risk system requirements create mandatory upgrade cycles for legacy automation tools, accelerating replacement demand across European corporate legal departments.
- Cloud-native architecture maturation:Containerized deployment models reduce IT infrastructure burdens for mid-sized law firms previously priced out of enterprise RPA platforms.
- GDPR Article 25 data protection by design:Technical and organizational measures requirements push legal automation vendors toward embedded privacy controls that differentiate compliant offerings.
Market Restraints
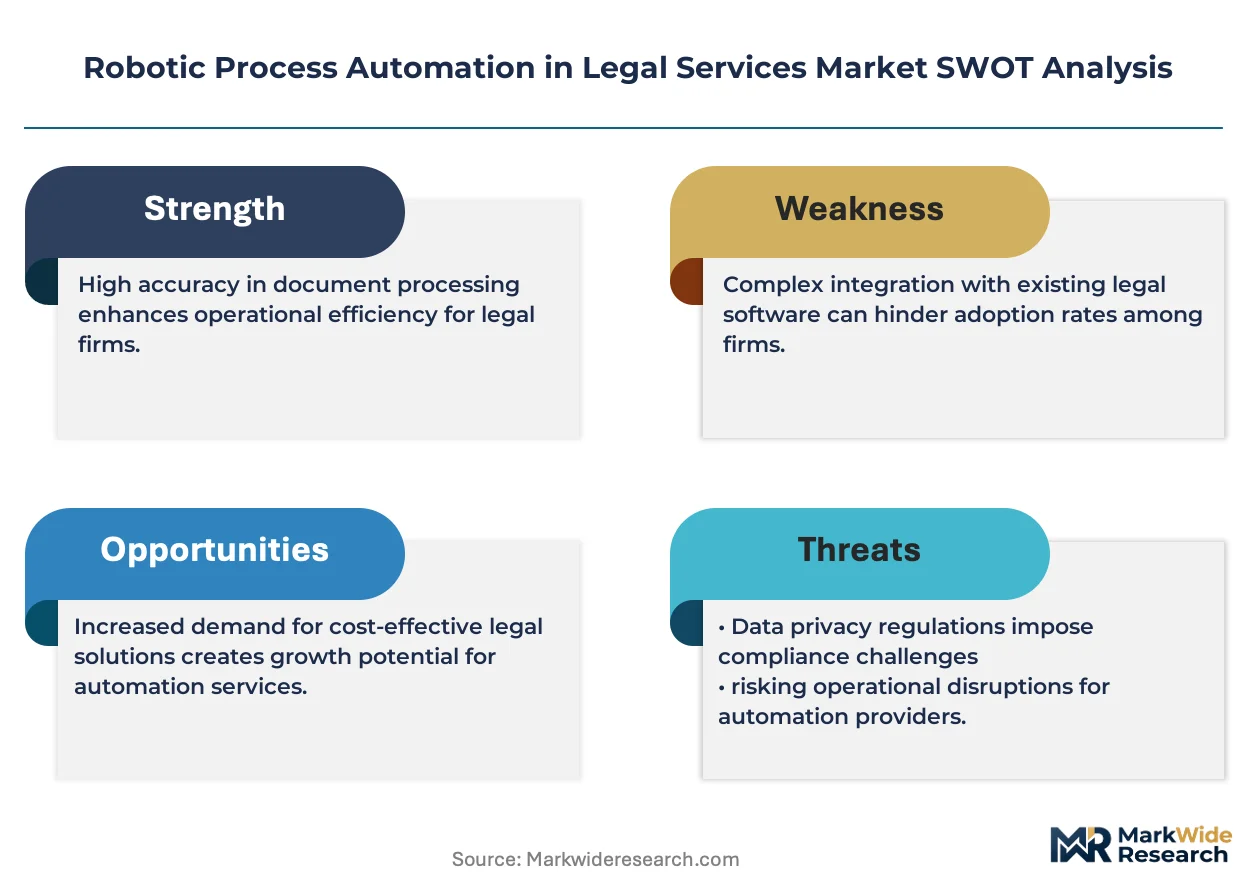
- Attorney-client privilege erosion risks:Automated document processing in multi-tenant cloud environments creates jurisdictional uncertainty over confidentiality protections under US state bar rules.
- Large language model inference costs:AI-augmented clause extraction consumes compute resources at rates that compress margins for fixed-fee managed service contracts.
- European data residency requirements:GDPR localization mandates fragment vendor architectures, raising operational complexity for US-headquartered platform providers serving EU legal departments.
Strategic Opportunities
- India legal process outsourcing integration:Hybrid human-bot workflows combining Mumbai and Bangalore contract review centers with automated extraction tools offer cost arbitrage for US litigation discovery.
- Regulatory technology convergence:Merging RPA with continuous compliance monitoring creates subscription revenue streams from financial services legal teams managing SEC and FINRA filing obligations.
- Small law firm penetration:Pre-configured document automation templates for residential real estate and estate planning open volume markets below current enterprise-focused pricing floors.
Industry Challenges
- Technology competence ethics rules:American Bar Association Model Rule 1.1 commentary creates malpractice exposure for attorneys delegating judgment to inadequately supervised automation systems.
- Legacy practice management system integration:Proprietary data formats in established legal software require expensive custom API development for seamless bot workflow deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Process Automation in Legal Services Market |
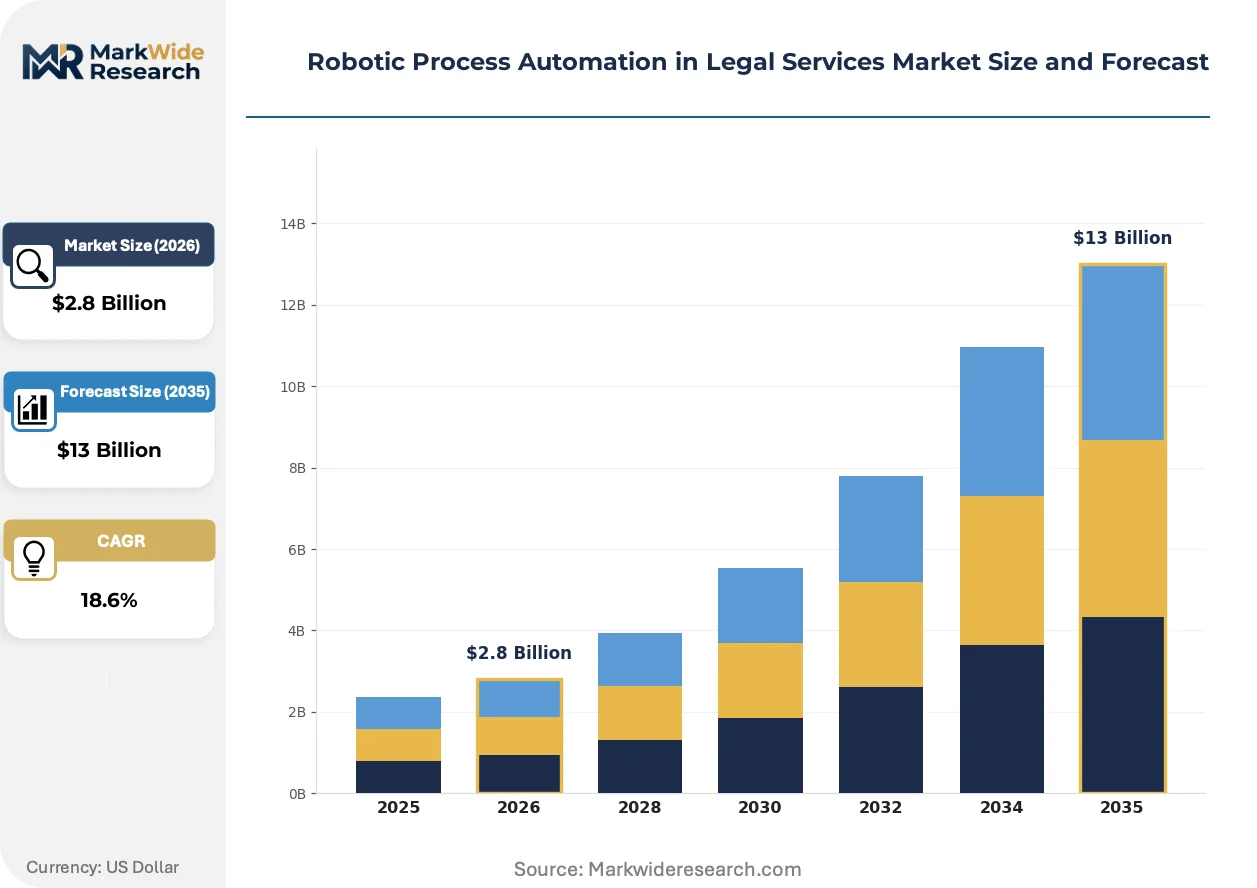
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Document Automation, Workflow Management, Compliance Tracking, Case Management End User Type: Law Firms, Corporate Legal Departments, Legal Process Outsourcing, Government Agencies Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS Technology: Artificial Intelligence, Machine Learning, Natural Language Processing, Optical Character Recognition |
| Companies Covered | UiPath, Automation Anywhere, Blue Prism, IBM, Microsoft, Pegasystems, NICE, Tungsten Automation, Appian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Process Automation in Legal Services Market Trends and Innovations
Legal automation architectures are fragmenting from monolithic platforms into composable toolchains, with buyers assembling best-of-breed components rather than accepting vendor-locked suites.
Intelligent document processing is modularizing around specialized microservices for entity extraction, sentiment analysis, and obligation mapping. Corporate legal departments at Fortune 500 manufacturers are piloting API-first architectures that swap components without platform migration. This modularization is compressing vendor switching costs and fragmenting market share concentration.
The EU AI Act's conformity assessment procedures for high-risk legal decision systems are restructuring product development roadmaps. Vendors must now embed technical documentation, human oversight interfaces, and accuracy testing protocols before market entry. US-based automation suppliers serving European multinational legal departments are establishing Brussels compliance offices to navigate notified body relationships.
General counsel procurement patterns are rotating toward outcome-based engagement models that tie vendor compensation to measured cycle time reduction. Alternative legal service providers and managed legal service arms of Big Four firms are capturing this spend by guaranteeing document throughput rates. This shift is most visible in London and New York financial services legal operations, where CLOs face pressure to demonstrate operational efficiency to CFOs.
Robotic Process Automation in Legal Services Market Segmentation
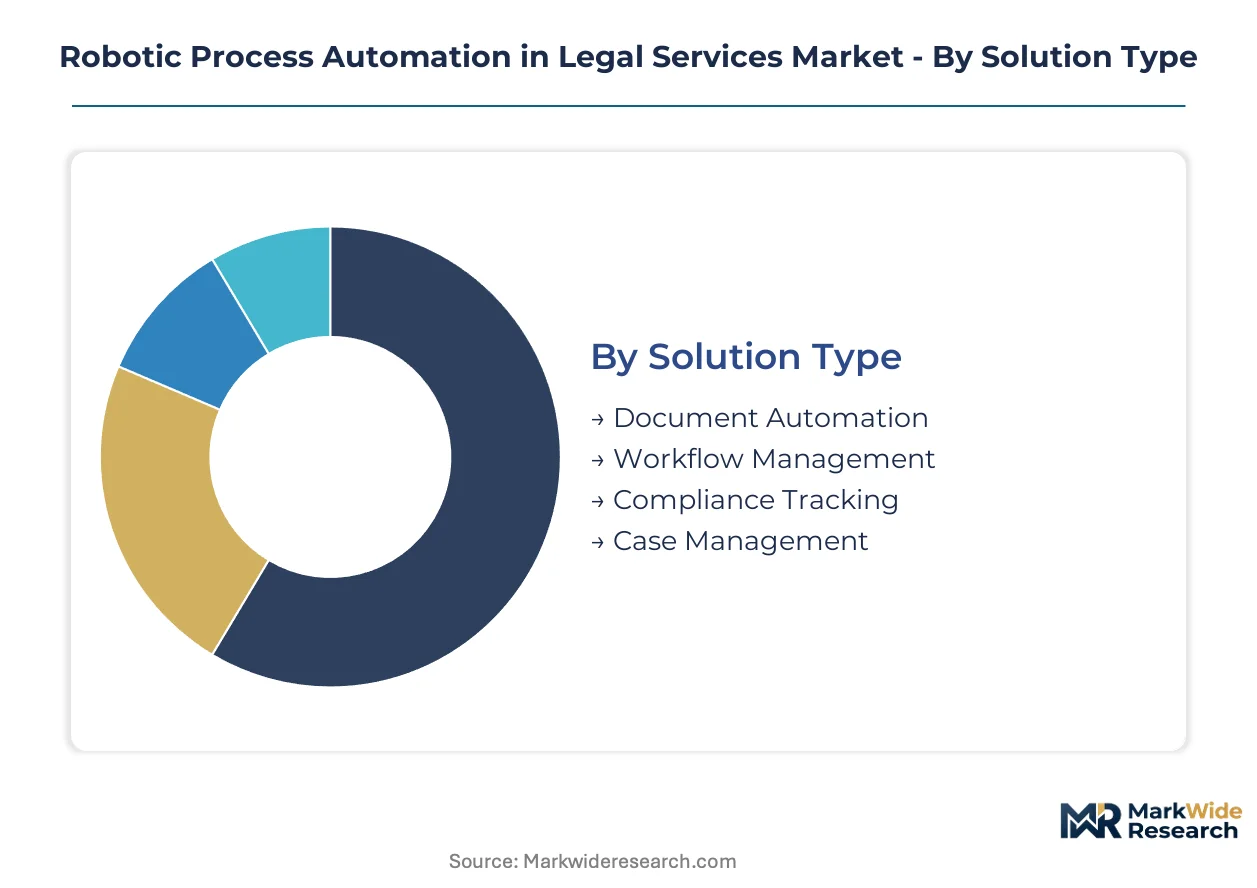
Legal automation procurement patterns diverge sharply across buyer sophistication, compliance exposure, and IT infrastructure maturity. Understanding these fault lines clarifies why vendor pricing and deployment architectures vary by segment despite overlapping functional capabilities.
Solution Type:
Buyer investment priority separates routine document generation from governance-intensive monitoring systems.
- Document Automation:Rule-based engines generate contracts, NDAs, and discovery filings from templated clauses with variable insertion. Corporate legal departments at Fortune 500 manufacturers in the United States deploy these tools to compress contract turnaround from weeks to hours under CFO pressure for operational efficiency metrics.
- Compliance Tracking:Continuous monitoring bots scan regulatory databases and flag filing deadlines across jurisdictions. Financial services legal teams in London and New York subscribe to these solutions for SEC and FINRA obligation management, where missed deadlines trigger enforcement exposure.
- Workflow Management:Orchestration layers route tasks between attorneys, paralegals, and external counsel with escalation protocols.
- Case Management:Matter-centric databases integrate deadlines, billing, and document repositories for litigation lifecycle tracking.
Document automation leads volumes today; compliance tracking is gaining share fastest.
End User Type:
Procurement authority and budget cycles reshape how automation vendors structure sales engagement and pricing tiers.
- Corporate Legal Departments:In-house teams at multinational manufacturers and technology companies purchase cloud-native platforms through enterprise software procurement channels. These buyers demand API connectivity to existing ERP systems and outcome-based pricing tied to measured cycle time reduction.
- Law Firms:Partnership governance slows technology adoption despite associate hour pressures, with Am Law 200 firms piloting bots for due diligence while mid-sized practices lag. GDPR Article 25 constraints complicate European firm deployments.
- Legal Process Outsourcing:Indian contract review centers in Mumbai and Bangalore integrate extraction bots with human attorney review for US litigation discovery cost arbitrage.
- Government Agencies:Public sector procurement rules and civil service union considerations constrain automation rollout velocity.
Corporate legal departments anchor current spending; legal process outsourcing is expanding most quickly.
Deployment Model:
Infrastructure control preferences and data residency mandates fragment vendor architecture roadmaps.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure and enable rapid scaling for mid-sized law firms previously priced out of enterprise platforms. GDPR localization requirements force US-headquartered vendors to establish EU data residency zones.
- Hybrid:Sensitive matter data remains on-premise while compute-intensive AI processing shifts to cloud inference engines. German corporate legal departments favor this architecture under BDSG federal data protection constraints.
- On-Premise:Legacy installations persist at defense contractors and government legal offices with classified information handling requirements.
- SaaS:Subscription delivery models with pre-configured legal templates reduce implementation timelines for standardized practice areas.
Cloud-based deployments dominate new bookings; hybrid architectures are climbing the fastest among regulated industries.
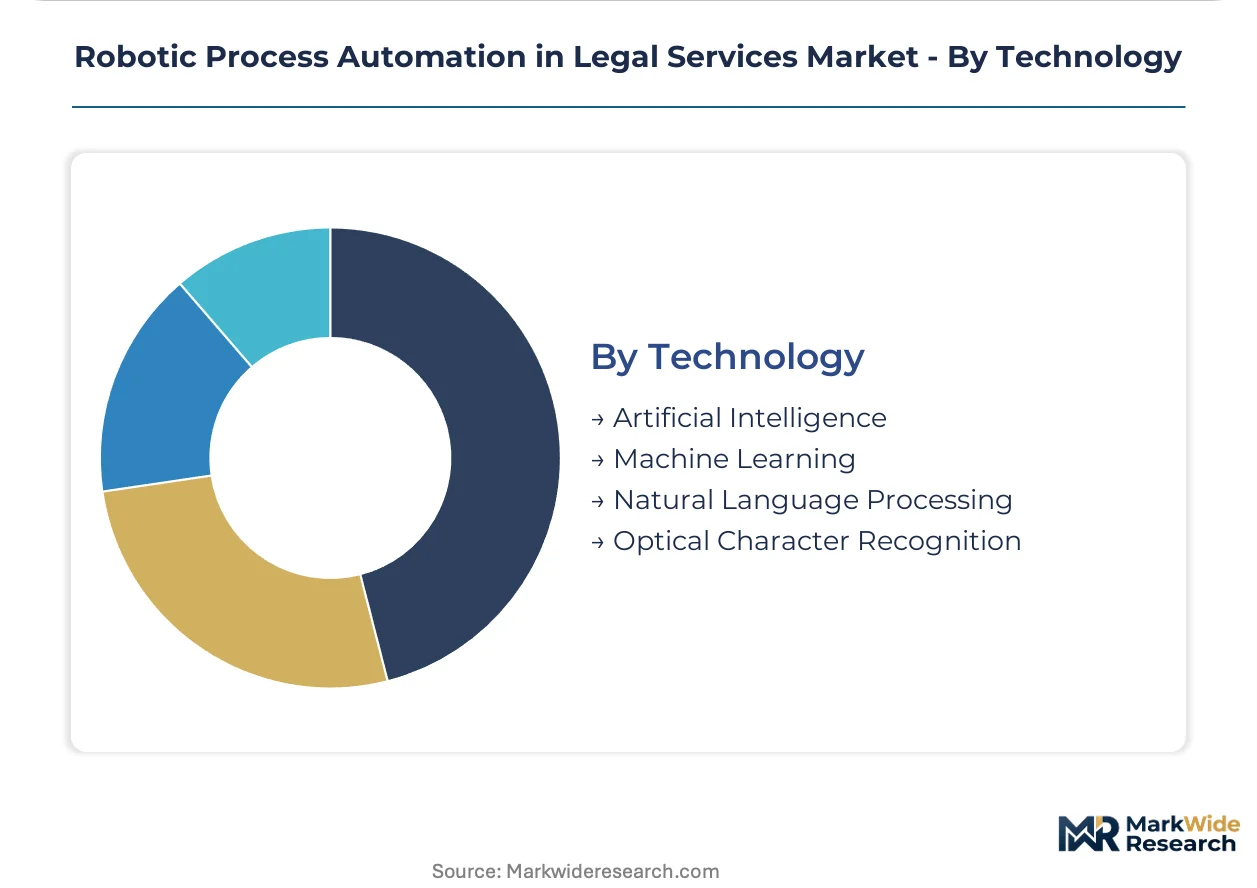
Technology:
Capability sophistication separates rule-based automation from AI-augmented interpretation of unstructured legal text.
- Natural Language Processing:Transformer models extract entities, obligations, and risk indicators from contracts and discovery documents without rigid template dependencies. These tools face EU AI Act high-risk system classification when deployed for automated legal decision support.
- Artificial Intelligence:Broad capability layer enabling predictive analytics for litigation outcome probability and spend forecasting.
- Machine Learning:Supervised classification systems improve extraction accuracy through attorney feedback loops on training data.
- Optical Character Recognition:Legacy digitization technology converting scanned filings and handwritten notes to machine-readable formats.
Natural language processing commands premium pricing; machine learning adoption is deepening fastest through embedded feedback mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate legal departments in New York and London drive automation procurement for contract lifecycle management and regulatory compliance monitoring.
United States
Fortune 500 manufacturers and financial services firms in Manhattan and Chicago purchase cloud-native RPA platforms through enterprise software channels. SEC disclosure requirements and FINRA filing obligations push legal operations teams toward automated compliance tracking. The Greater Boston cluster hosts alternative legal service providers integrating extraction bots with human attorney review for litigation discovery cost reduction.
United Kingdom
Magic Circle firms and in-house teams at multinational banks in the City of London deploy document automation to compress turnaround times for cross-border transactions. The Solicitors Regulation Authority's technology competence guidance shapes vendor selection criteria for ethical compliance. Manchester and Birmingham legal operations centers pilot hybrid human-bot workflows for high-volume contract review.
Germany
Industrial conglomerates in Munich and Frankfurt favor hybrid deployment architectures under BDSG federal data protection constraints. The EU AI Act's conformity assessment procedures force re-engineering of automated legal decision systems before market entry. Berlin hosts emerging legal tech vendors establishing Brussels compliance offices for notified body relationships.
India
Legal process outsourcing centers in Mumbai and Bangalore integrate extraction bots with human attorney review for US litigation discovery cost arbitrage. The country's national technology regulator promotes data localization requirements that shape vendor cloud architecture decisions. Hyderabad and Pune emerge as secondary hubs for contract automation service delivery to North American corporate clients.
France
Paris-based banking and insurance legal departments subscribe to continuous monitoring solutions for AMF and ACPR filing obligation management. CNIL guidance on automated decision-making constrains how RPA tools handle client matter information in French deployments. The Lyon legal tech cluster develops specialized microservices for entity extraction and obligation mapping.
Robotic Process Automation in Legal Services Market Competitive Landscape
Global majors compete with regional champions across platform architecture and compliance specialization, producing a tiered structure where scale-driven vendors anchor enterprise accounts while niche players capture mid-market segments. Pure-play automation vendors, diversified technology conglomerates, and legal-specific software houses constitute three dominant archetypes. Consolidation through strategic acquisitions and cloud-native platform development represent the primary competitive vectors reshaping vendor positioning.
Within the pure-play tier, UiPath and Automation Anywhere exemplify platform-centric strategies targeting cross-industry deployment with legal vertical specialization. IBM occupies a position among diversified technology providers embedding governance capabilities into compliance-heavy workflows. These three anchors demonstrate how vendor origin—automation-native versus enterprise software heritage—shapes product roadmap priorities for legal department procurement.
| Leading Market Players |
|---|
| UiPath |
| Automation Anywhere |
| Blue Prism |
| IBM |
| Microsoft |
| Pegasystems |
| NICE |
| Tungsten Automation |
| Appian |
| Others |
Pricing and Supply Chain Analysis
Outcome-based procurement from corporate legal departments at Fortune 500 manufacturers is compressing vendor margins and forcing platform providers toward consumption-based SaaS models that sacrifice upfront revenue for recurring contract lock-in.
Pricing Analysis
Compute infrastructure costs from GPU-intensive NLP inference pass through to client subscription tiers, with vendors absorbing margin compression on fixed-fee managed service contracts. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-compliant high-risk system deployments from basic document automation. Pricing pressure stems from alternative legal service providers guaranteeing throughput rates below traditional vendor pricing floors. Mid-sized law firms exhibit highest price sensitivity, while corporate legal departments at financial services firms prioritize compliance certification over cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from multinational corporate legal departments, while value-added resellers serve mid-market law firms requiring implementation support. Cloud infrastructure concentrates in the United States, Ireland, and Germany to satisfy GDPR data residency mandates. Platform development draws from specialized labor pools in India for engineering talent and the United Kingdom for legal domain expertise. Single-source vulnerability runs through hyperscaler cloud dependencies, where AWS, Azure, or GCP outages cascade to client matter processing. Distribution runs through partner ecosystems that extend platform reach without direct sales overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where general counsel procurement patterns rotate toward certified EU AI Act compliance and outcome-based engagement models that reward measured cycle time reduction over feature breadth.
For Market Incumbents: Lock in enterprise accounts through embedded compliance documentation and human oversight interfaces mandated by Brussels conformity assessment procedures. Deepen vertical integration into specialized NLP microservices for entity extraction rather than licensing third-party transformer models. Defend against alternative legal service providers by guaranteeing document throughput rates that match Big Four managed legal service arms. For New Entrants and Emerging Players: Launch via pre-configured document automation templates for residential real estate and estate planning that bypass enterprise sales cycles. Target small law firms below current pricing floors with SaaS delivery models that reduce implementation timelines. Penetrate through API-first architectures that swap components without platform migration, capturing corporate legal departments piloting modular toolchains. For Investors and Strategic Acquirers: Asymmetric upside sits with legal-specific software houses possessing EU AI Act certification pathways and established notified body relationships. Long-term viability favors vendors embedding governance capabilities into compliance-heavy workflows rather than pure-play automation platforms facing commoditization. Watch CLO procurement authority consolidation under CFO pressure as the inflection indicator for outcome-based pricing adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Pathway | Brussels conformity assessment unlocks high-risk system deployment for European multinational legal departments. |
| Cloud-Native Architecture Migration | Containerized deployment reduces IT infrastructure burdens for mid-sized law firms previously priced out. |
| API-First Platform Development | Modular microservices enable Fortune 500 manufacturers to swap components without vendor lock-in. |
| Hybrid Human-Bot Workflow Integration | Mumbai and Bangalore contract review centers combine with extraction bots for US litigation discovery cost arbitrage. |
| Outcome-Based Engagement Models | Vendor compensation tied to measured cycle time reduction captures CLO procurement spend in London and New York. |
Research Methodology
Direct dialogue with legal operations directors, compliance officers at financial services firms, procurement leads at alternative legal service providers, and platform engineers at automation vendors grounds the analysis in practitioner constraints. Secondary validation draws from SEC filings of publicly traded legal tech vendors, EU AI Act implementation guidance from Brussels regulatory databases, American Bar Association ethics opinions on technology competence, and GDPR Article 25 technical documentation requirements. Bottom-up deployment estimates triangulate against top-down corporate legal department IT spending benchmarks.
Segmented outputs across solution type, end user category, deployment model, and technology sophistication layer feed into the analytical framework. Natural language processing adoption curves, cloud-native migration timelines, and EU AI Act compliance upgrade cycles inform the projection dynamics. CAGRs derive from fitted growth trajectories adjusted for regulatory mandate acceleration and buyer consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU AI Act enforcement escalation or hyperscaler cloud pricing volatility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
North America Data Center Robotics Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market