
 Marine Robots Market | 2026-2036
Marine Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Robots Market Insights
ISO 13628-8 qualification for subsea production control systems is unwinding the competitive landscape for tethered and untethered marine robot suppliers. Kongsberg leverages its integrated sonar and navigation stack to dominate hydrographic survey contracts across Nordic waters. Teledyne Marine anchors North American demand through its dense distributor network for acoustic sensor modules. Saab competes aggressively on defense surveillance tenders, where national security procurement rules favor domestic sourcing.
Marine robots encompass autonomous and remotely operated platforms engineered for underwater and surface operations, typically rated for depths from 300 meters to full oceanic trench capability using pressure-resistant titanium or ceramic-composite hulls, with primary purpose spanning seabed mapping, infrastructure inspection, and environmental data collection. Autonomous Underwater Vehicles capture the fastest-expanding application share as battery energy density improvements enable multi-day unsupervised missions. Remotely Operated Vehicles retain the largest installed base, though margin pools are shifting toward AI-Based Control architectures that reduce operator headcount per mission. Surface Autonomous Robots are maturing rapidly in port security and coastal patrol roles where GPS Navigation and optical imaging convergence lowers per-unit system cost.
The International Maritime Organization, national defense departments, and ISO technical committees collectively shape product standards, certification timelines, and market access for marine robot deployments in commercial and sovereign waters. ECA Group and Oceaneering International navigate this compliance architecture through dedicated regulatory affairs teams that pre-qualify platforms for client-specific tender requirements. Stakeholders must monitor how emerging seabed mining regulations and exclusive economic zone sovereignty claims reshape permissible operating areas and sensor disclosure mandates.
Market Dynamics
ISO 13628-8 qualification requirements for subsea production control systems are forcing rapid platform upgrades across offshore energy fleets, compressing replacement cycles for tethered inspection systems and redirecting procurement budgets toward AI-augmented autonomous architectures.
Growth Catalysts
- North Sea infrastructure aging:Norwegian operators face mandatory inspection intervals for subsea pipelines and wellheads, sustaining replacement demand for pressure-rated robotic platforms.
- REACH compliance for seabed sensors:European chemical disclosure mandates accelerate sensor module upgrades, favoring suppliers with pre-certified component libraries.
- Lithium-sulfur battery chemistry:Improved energy density enables AUV missions exceeding 72 hours unsupervised, expanding addressable survey contracts.
Market Restraints
- Titanium hull plate supply:Russian and Chinese smelter concentration creates input cost volatility for deep-rated pressure vessel manufacturers.
- Acoustic positioning component scarcity:Ultra-short baseline transducer production concentrates in three Nordic facilities, exposing procurement timelines.
- Substitution by satellite bathymetry:Lidar-equipped orbital platforms capture shallow-water mapping contracts previously held by surface autonomous robots.
Strategic Opportunities
- Japan's Exclusive Economic Zone expansion:Revised sovereignty claims around Okinotorishima create demand for persistent underwater surveillance platforms.
- EU Green Deal seabed carbon monitoring:Mandated environmental baseline surveys for offshore wind installations require benthic sensor networks.
- Optical-acoustic sensor fusion:Converging camera and sonar data streams enable real-time classification without surface tether bandwidth constraints.
Industry Challenges
- Subsea robotics engineering talent:Pressure-hull welding and underwater navigation algorithm development face acute skill shortages in Atlantic Canada and Scotland.
- ISO/IEC 80001-1 certification timelines:Medical-device-grade software validation requirements for autonomous decision systems extend product launch schedules by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Robots Market |
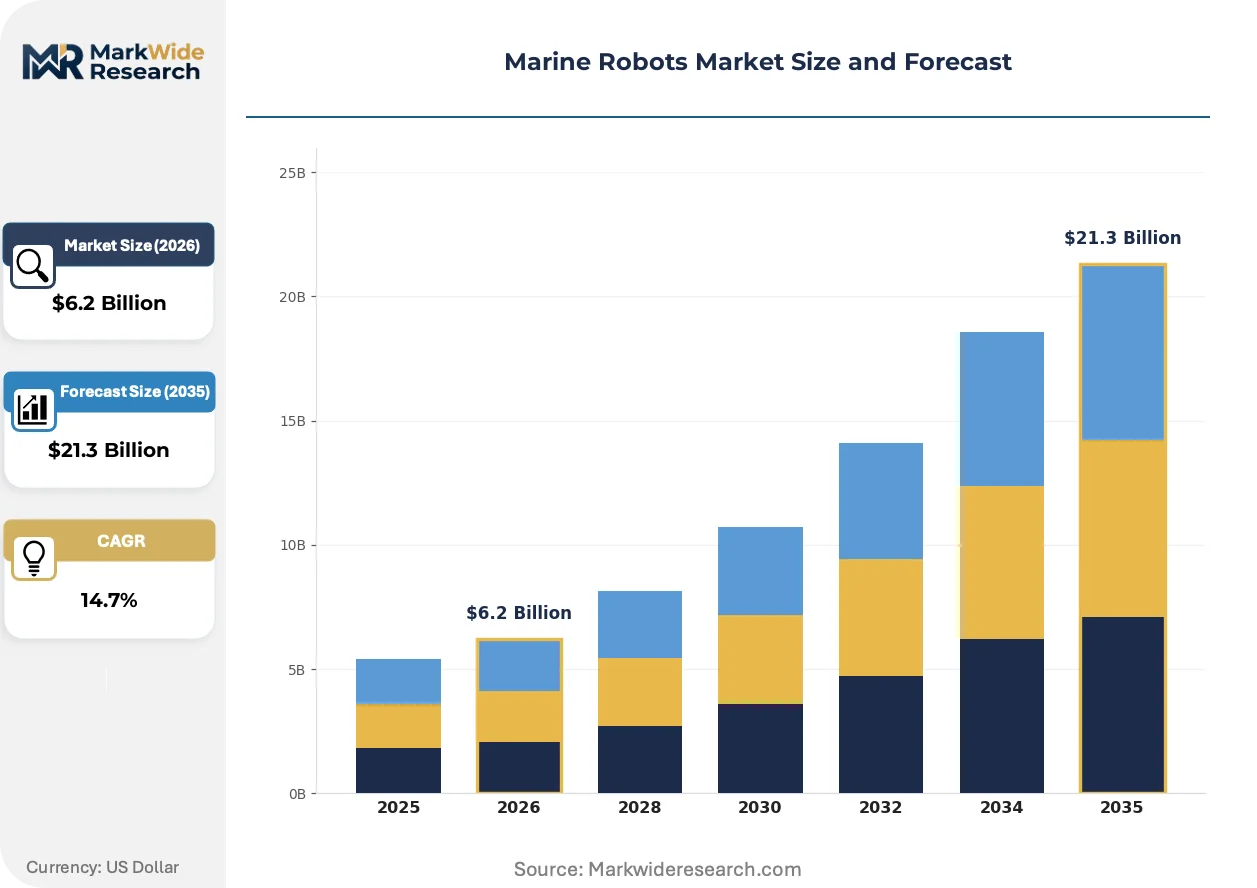
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $21.3 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Underwater Vehicles, Remotely Operated Vehicles, Hybrid Underwater Vehicles, Surface Autonomous Robots Technology: Sonar, Lidar, Optical Imaging, Acoustic Sensors, GPS Navigation, AI-Based Control Application: Oceanographic Research, Offshore Platform Inspection, Environmental Monitoring, Defense Surveillance, Archaeological Exploration End User: Marine Research Institutes, Energy Exploration Firms, Environmental Agencies, Defense Departments |
| Companies Covered | Oceaneering International, Atlas Elektronik, ECA Group, Saab, Kongsberg, Fugro, Deep Ocean Engineering, Teledyne Marine, Ocean Infinity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Robots Market Trends and Innovations
Solid-state sensor architectures and edge-computing payloads are compressing platform size while expanding mission autonomy, enabling deployment from smaller vessels and reducing per-survey logistics costs.
Synthetic aperture sonar processing hardware is miniaturizing from rack-mounted systems to palm-sized modules. Offshore wind farm operators in the North Sea are adopting these compact units for cable burial monitoring surveys. The technology is miniaturizing inspection-class AUV form factors, allowing launch from 15-meter workboats rather than dedicated survey vessels.
The EU AI Act's high-risk system classification for autonomous maritime platforms imposes algorithmic transparency requirements on navigation decision stacks. European AUV suppliers must now document training data provenance and failure-mode probabilities. Deep-rated inspection systems face the steepest compliance burden, with Nordic yards accelerating documentation investments to maintain certification validity.
Charter-based survey contracting is displacing equipment ownership among mid-sized offshore energy contractors. Brazilian pre-salt field developers now specify deliverables—seabed terrain models, anomaly reports—rather than platform specifications in tender documents. This model concentrates in the Campos Basin, where Petrobras-led consortiums prioritize operational expenditure flexibility over capital deployment.
Marine Robots Market Segmentation
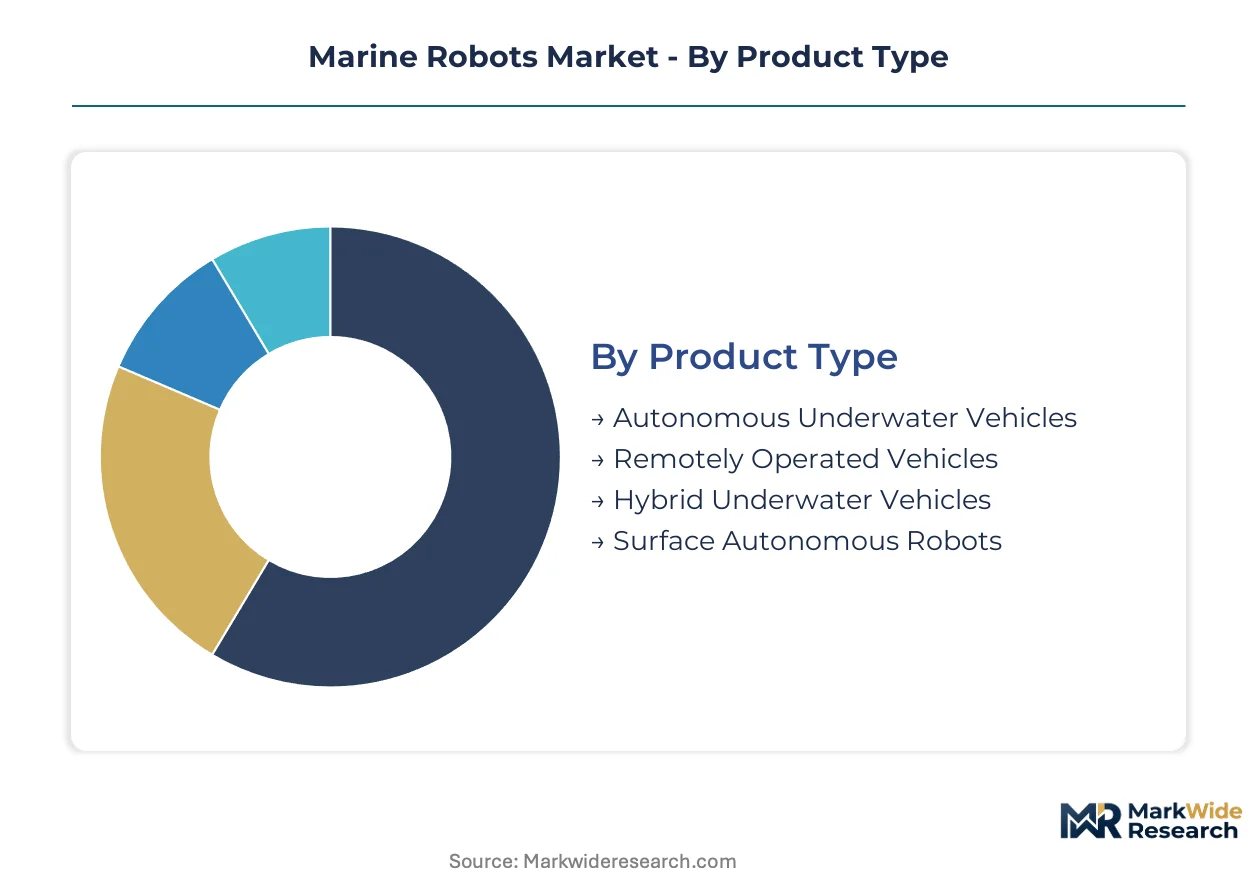
Marine robot procurement patterns diverge sharply across product architectures and operational depths, with tethered systems dominating established energy infrastructure markets while untethered platforms capture frontier applications requiring extended endurance.
Product Type:
Autonomous Underwater Vehicles concentrate demand in Norway and Brazil where pre-salt and North Sea operators specify unsupervised seabed survey capabilities; Remotely Operated Vehicles anchor procurement in mature markets with dense installed base maintenance requirements.
- Autonomous Underwater Vehicles:Battery-powered untethered platforms rated for 300-meter to full ocean depth operations using pressure-resistant hull architectures. Norwegian operators under Equinor procurement frameworks specify these for subsea pipeline inspection intervals mandated by national petroleum regulators. Lithium-sulfur chemistry improvements now enable missions exceeding 72 hours without surface recovery.
- Remotely Operated Vehicles:Tethered platforms maintaining real-time operator control through umbilical power and data links. North Sea energy contractors retain these for wellhead intervention tasks where human-in-the-loop decision authority remains non-negotiable under ISO 13628-8 qualification protocols. Tether bandwidth constraints limit sensor payload integration compared to autonomous alternatives.
- Hybrid Underwater Vehicles:Dual-mode architectures switching between tethered precision operations and untethered transit modes. Japanese defense procurement around Okinotorishima sovereignty monitoring drives specialized demand for these transitional platforms.
- Surface Autonomous Robots:GPS-navigated platforms operating at air-sea interface for port security and coastal patrol missions. Port authorities in Rotterdam and Singapore deploy these for vessel traffic monitoring where reduced draft requirements enable harbor access.
Remotely Operated Vehicles hold the largest share; momentum sits with Autonomous Underwater Vehicles.
Technology:
Sensor modality selection tracks mission depth and data resolution requirements, with acoustic systems dominating deep-rated applications and optical methods capturing shallow-water inspection contracts.
- Sonar:Acoustic ranging and imaging systems including multibeam echosounders and synthetic aperture configurations. Nordic hydrographic survey contractors specify Kongsberg integrated sonar stacks for seabed mapping deliverables under national maritime authority contracts. Solid-state miniaturization now enables palm-sized modules replacing rack-mounted heritage systems.
- Acoustic Sensors:Ultra-short baseline and long-baseline positioning transducers for subsea navigation and vehicle tracking. Three Nordic manufacturing facilities concentrate global production, exposing procurement timelines to geographic supply risk. Brazilian pre-salt field developers face extended lead times for these components in charter-based survey contracting models.
- Lidar:Laser-based optical ranging systems for high-resolution shallow-water bathymetry. Satellite lidar platforms are displacing surface autonomous robots in certain coastal mapping applications.
- Optical Imaging:Camera systems for visual inspection and real-time anomaly classification. EU AI Act algorithmic transparency requirements now impose documentation burdens on navigation decision stacks using these sensors.
- GPS Navigation:Satellite positioning for surface and near-surface operations. Convergence with optical imaging is lowering per-unit system costs for coastal patrol platforms.
- AI-Based Control:Autonomous decision architectures reducing operator headcount per mission. ISO/IEC 80001-1 medical-device-grade software validation extends product launch schedules by 14-18 months for these systems.
Sonar and Acoustic Sensors together dominate installed base; AI-Based Control is climbing the fastest as margin pools shift toward reduced-crew mission architectures.
Application:
End-use concentration reflects regulatory enforcement intensity and infrastructure replacement cycles, with energy sector procurement outpacing research and environmental monitoring in absolute spending.
- Offshore Platform Inspection:Subsea infrastructure assessment for pipelines, wellheads, and production control systems. North Sea operators face mandatory inspection intervals under Norwegian Petroleum Safety Authority directives, sustaining replacement demand for pressure-rated robotic platforms. ISO 13628-8 qualification requirements are compressing replacement cycles for tethered systems.
- Defense Surveillance:Sovereign underwater domain awareness and exclusive economic zone monitoring. Japan's revised sovereignty claims around Okinotorishima are creating demand for persistent surveillance platforms. National security procurement rules in multiple jurisdictions favor domestic sourcing for these applications.
- Oceanographic Research:Academic and government-funded seabed mapping and water column studies. Marine research institutes in Atlantic Canada and Scotland face acute engineering talent shortages for pressure-hull welding and navigation algorithm development.
- Environmental Monitoring:Benthic sensor networks for carbon sequestration baseline assessment and pollution tracking. EU Green Deal mandates for offshore wind installations are driving seabed carbon monitoring requirements.
- Archaeological Exploration:Non-invasive survey of submerged cultural heritage sites. Mediterranean and Baltic Sea projects specify these platforms for shipwreck documentation under UNESCO convention protocols.
Offshore Platform Inspection captures the largest revenue pool; Defense Surveillance is expanding most quickly on sovereignty claim tensions.
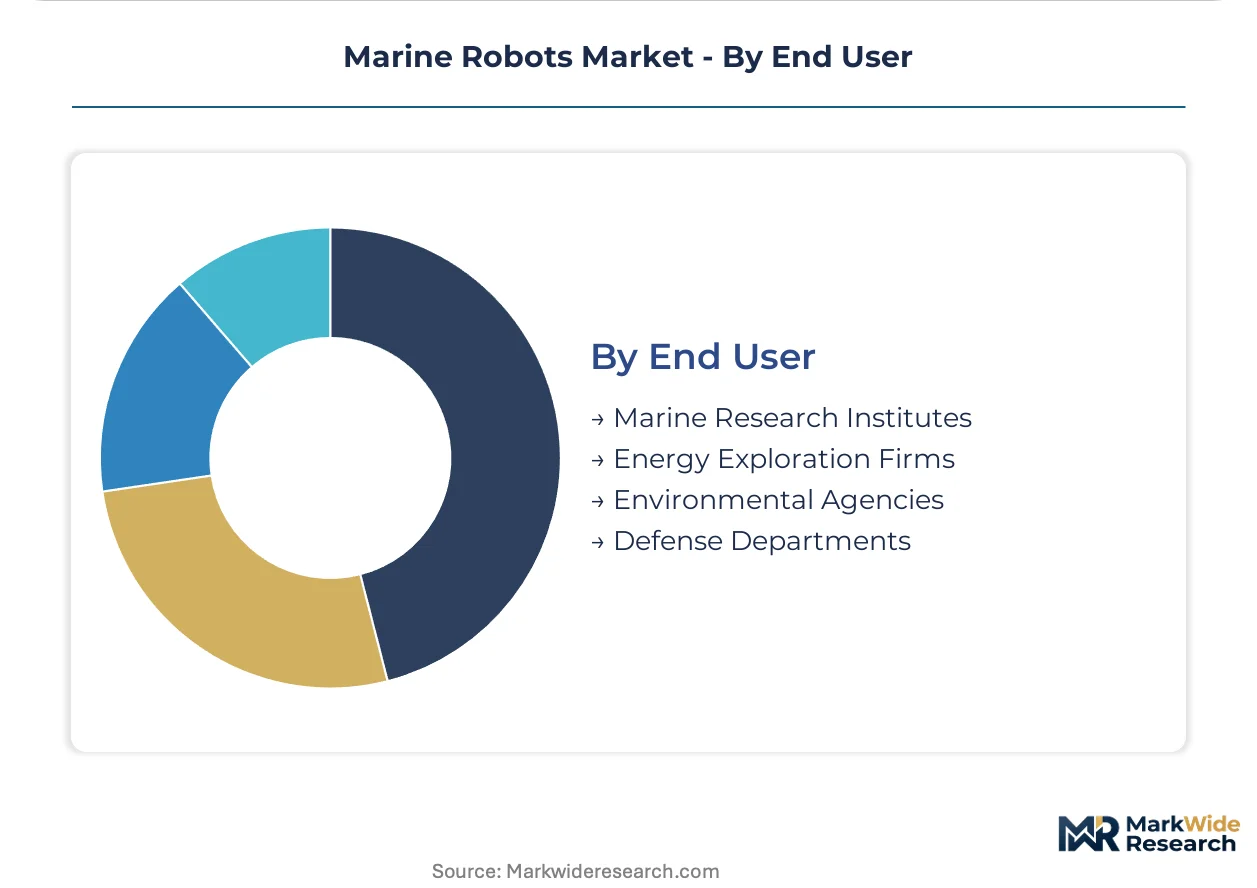
End User:
Customer procurement models are bifurcating between capital-intensive platform ownership and operational expenditure-based charter contracting, with mid-sized contractors leading the shift toward deliverables-specified tenders.
- Energy Exploration Firms:Oil and gas operators and offshore wind developers specifying robotic survey capabilities. Brazilian pre-salt consortiums now contract for seabed terrain models and anomaly reports rather than platform specifications, prioritizing opex flexibility. Petrobras-led tenders in the Campos Basin exemplify this model displacement.
- Marine Research Institutes:Academic and governmental oceanographic organizations funding basic and applied seabed science. REACH compliance for seabed sensors is accelerating sensor module upgrades among European institutions.
- Defense Departments:National military and coast guard organizations procuring surveillance and mine countermeasures platforms. Saab competes aggressively in this segment where domestic sourcing rules apply.
- Environmental Agencies:Regulatory bodies and conservation organizations monitoring marine protected areas and pollution incidents. These users favor standardized sensor disclosure protocols compatible with international data sharing frameworks.
Energy Exploration Firms command the largest procurement volumes; Environmental Agencies are gaining share fastest on EU Green Deal implementation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal seabed carbon monitoring mandates and ISO 13628-8 qualification protocols are redirecting procurement budgets toward AI-augmented autonomous architectures across sovereign waters. National petroleum regulators in North Sea jurisdictions compress inspection intervals for aging subsea infrastructure. Exclusive economic zone sovereignty claims in the Western Pacific generate defense surveillance demand.
Norway
Equinor procurement frameworks specify autonomous underwater vehicles for subsea pipeline inspection intervals mandated by the Norwegian Petroleum Safety Authority. REACH compliance for seabed sensors accelerates module upgrades among North Sea operators. Bergen and Stavanger harbor the world's largest fleet concentration of inspection-class marine robots serving pre-salt and mature field assets.
Brazil
Petrobras-led consortiums in the Campos Basin prioritize operational expenditure flexibility through charter-based survey contracting rather than platform ownership. ANVISA-equivalent offshore safety protocols govern subsea production control system qualifications. Rio de Janeiro anchors pre-salt field development robotics demand as Brazilian contractors specify deliverables-specified tenders for seabed terrain models.
Japan
Revised sovereignty claims around Okinotorishima create demand for persistent underwater surveillance platforms under METI defense procurement frameworks. National security procurement rules favor domestic sourcing for exclusive economic zone monitoring missions. Yokohama and Kobe shipyards specialize in hybrid underwater vehicle architectures switching between tethered precision and untethered transit modes.
United States
Gulf of Mexico offshore platform operators face compressed replacement cycles for tethered inspection systems under Bureau of Safety and Environmental Enforcement directives. FAA coordination requirements govern surface autonomous robot deployments in coastal patrol roles. Houston energy contractors anchor North American demand through dense distributor networks for acoustic sensor modules.
United Kingdom
North Sea decommissioning liabilities and aging infrastructure sustain replacement demand for pressure-rated robotic platforms under Health and Safety Executive offshore regulations. EU AI Act algorithmic transparency requirements impose documentation burdens on navigation decision stacks deployed from Aberdeen and Great Yarmouth. Scottish yards accelerate investments to maintain certification validity for deep-rated inspection systems.
Marine Robots Market Competitive Landscape
Player mix skews toward integrated sonar and navigation stack specialists alongside defense-focused domestic suppliers. Market structure concentrates around Nordic hydrographic survey contractors and North American acoustic sensor distributors. Three archetypes dominate: integrated platform OEMs with captive sensor production, defense contractors leveraging national security procurement preferences, and charter-based survey service providers displacing equipment ownership. Competitive moves center on regulatory pre-qualification investments and synthetic aperture sonar miniaturization partnerships.
Among Nordic integrated platform specialists, Kongsberg occupies a position exemplifying the sonar-navigation convergence archetype, while Saab sits within the defense surveillance tier where domestic sourcing rules apply. Teledyne Marine anchors North American demand representation through acoustic module distribution density. These three entities collectively illustrate how geographic specialization and regulatory alignment shape competitive positioning without requiring uniform scale or vertical scope.
| Leading Market Players |
|---|
| Oceaneering International |
| Atlas Elektronik |
| ECA Group |
| Saab |
| Kongsberg |
| Fugro |
| Deep Ocean Engineering |
| Teledyne Marine |
| Ocean Infinity |
| Others |
Pricing and Supply Chain Analysis
Ninety-day acoustic positioning component lead times expose procurement timelines to Nordic manufacturing concentration, concentrating pricing power among hull plate suppliers while forcing charter-based contractors toward operational expenditure models that buffer input cost volatility.
Pricing Analysis
Certification level under ISO 13628-8 and EU AI Act algorithmic transparency protocols creates the primary spread between premium autonomous architectures and standard tethered systems. Three-tier pricing structure across deep-rated inspection platforms, mid-depth survey units, and shallow-water observation craft tracks pressure-hull material grade and sensor payload density. Cost compression in standard ROV tiers intensifies as Brazilian pre-salt charter contracting prioritizes deliverables over platform ownership. Environmental agencies exhibit highest price sensitivity due to grant-funded procurement constraints; defense departments show lowest sensitivity under national security exemption frameworks.
Supply Chain Analysis
Strategic stockpiling of titanium hull plate dominates over just-in-time preferences given Russian and Chinese smelter concentration and Norwegian Petroleum Safety Authority inspection interval mandates. Manufacturing draws from Norway, the United Kingdom, and Japan for pressure-rated vessel fabrication; acoustic transducer production rests on three Nordic facilities. Single-source vulnerability in ultra-short baseline positioning modules exposes procurement timelines to geographic concentration. Distribution runs through Equinor procurement frameworks and Petrobras-led consortium tender processes toward end-use deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent marine robot suppliers face substitution pressure from satellite lidar bathymetry capturing shallow-water mapping contracts previously held by surface autonomous platforms, requiring defensive repositioning around unsupervised endurance capabilities.
For Market Incumbents: Compound certification investments under ISO/IEC 80001-1 medical-device-grade software validation to extend product launch timelines ahead of emerging entrants lacking regulatory affairs infrastructure. Deepen backward integration into lithium-sulfur battery chemistry partnerships to secure energy density advantages against satellite bathymetry substitution in extended-duration survey contracts. For New Entrants and Emerging Players: Differentiate on optical-acoustic sensor fusion architectures that enable real-time classification without surface tether bandwidth constraints, targeting Japan's Okinotorishima sovereignty monitoring tenders where hybrid underwater vehicle specifications favor transitional platform specialists. Penetrate EU Green Deal seabed carbon monitoring mandates for offshore wind installations through benthic sensor network deliverables. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractors with dormant commercial marine robotics divisions and mid-sized survey service providers consolidating charter-based contracting models in the Campos Basin. Long-term viability centers on regulatory pre-qualification moats and synthetic aperture sonar miniaturization capabilities. Watch for lithium-sulfur battery chemistry cost curves crossing threshold viability for 72-hour unsupervised missions as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Qualification Investment | ISO 13628-8 and EU AI Act compliance compresses replacement cycles for tethered systems toward autonomous architectures. |
| Synthetic Aperture Sonar Miniaturization | Palm-sized modules enable launch from 15-meter workboats rather than dedicated survey vessels in North Sea wind farm contracts. |
| Charter-Based Survey Contracting | Petrobras-led consortiums in Brazil specify seabed terrain deliverables over platform ownership for operational expenditure flexibility. |
| Lithium-Sulfur Battery Integration | Improved energy density extends AUV missions beyond 72 hours unsupervised, expanding addressable survey contract scope. |
| Optical-Acoustic Sensor Fusion | Converging data streams enable real-time classification without surface tether bandwidth constraints in deep-rated inspection. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with subsea robotics engineering directors, offshore energy procurement leads at Equinor and Petrobras consortiums, defense surveillance program managers under METI frameworks, and charter-based survey contracting officers in the Campos Basin. Secondary validation drew from Norwegian Petroleum Safety Authority inspection interval directives, ISO 13628-8 qualification protocols, EU AI Act algorithmic transparency requirements, and Bureau of Safety and Environmental Enforcement offshore platform regulations. Bottom-up platform deployment tallies triangulated against top-down energy sector capital expenditure flows.
Across the analysis window, the forecasting framework modeled product type segmentation across autonomous underwater vehicles, remotely operated vehicles, hybrid architectures, and surface autonomous robots; technology segmentation spanning sonar, acoustic sensors, lidar, optical imaging, GPS navigation, and AI-based control; and application segmentation covering offshore platform inspection, defense surveillance, oceanographic research, environmental monitoring, and archaeological exploration. CAGRs were derived from replacement cycle compression under ISO qualification mandates and sovereignty claim-driven defense procurement intensification.
The analysis sits within stated boundaries; outcomes outside sustained Norwegian North Sea inspection interval enforcement, Brazilian pre-salt field development continuity, and Western Pacific exclusive economic zone sovereignty claim trajectories would require recalibration. Forecasts reflect assumptions regarding lithium-sulfur battery chemistry maturation, titanium hull plate supply diversification, and acoustic positioning component manufacturing geographic dispersion. Revision becomes warranted when satellite lidar bathymetry resolution thresholds cross competitive displacement thresholds for shallow-water surface autonomous robot contracts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Servo Gripper Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Healthcare Robots Market