
 Global Automated Guided Vehicle (AGV) Software Market | 2026-2036
Global Automated Guided Vehicle (AGV) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Guided Vehicle (AGV) Software Market Foresight
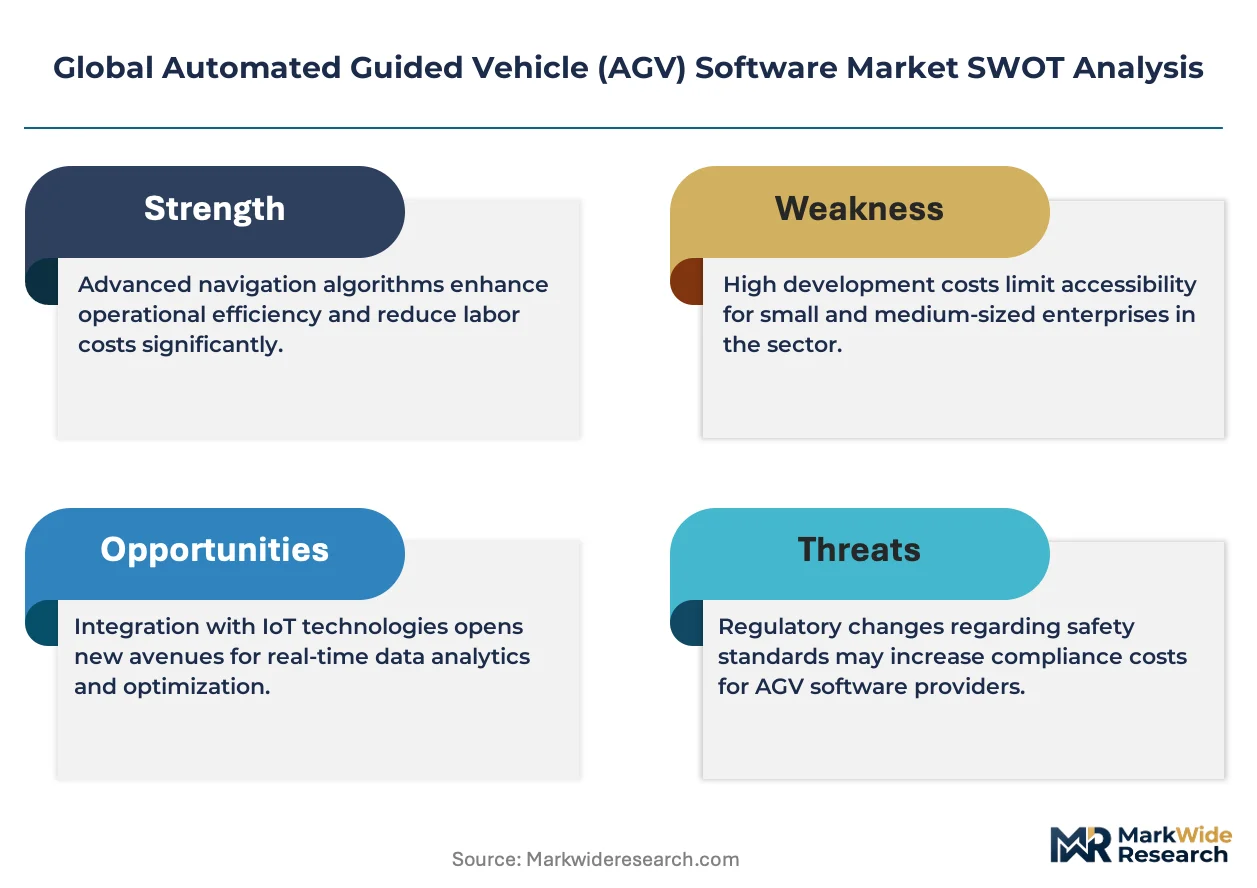
Project finance and equipment-leasing structures is narrowing the capital barrier for mid-sized logistics operators seeking AGV software subscriptions. Swisslog Holding AG leverages its parent company's warehouse automation installed base to bundle software with hardware service contracts. Dematic sustains competitive intensity through deep integration with its own material handling equipment portfolio. GreyOrange anchors its position in retail fulfillment by specializing in AI-driven fleet orchestration for variable SKU environments.
Automated Guided Vehicle (AGV) Software comprises embedded navigation algorithms, fleet coordination middleware, and safety compliance modules that process real-time sensor data through LiDAR, vision, or magnetic tape inputs to direct unmanned vehicles along predefined or dynamically optimized paths. The primary purpose is to synchronize vehicle movement with warehouse management systems and manufacturing execution systems, eliminating human intervention in repetitive transport tasks. Cloud-based deployment is capturing the fastest expansion as operators prioritize remote diagnostics and elastic compute scaling over capital-intensive on-premises infrastructure. Fleet management solutions command the deepest margin pools because recurring software licenses for multi-vehicle coordination generate stickier revenue than single-vehicle navigation licenses. Warehouse automation remains the dominant application segment, though pharmaceutical distribution is emerging as a high-specification niche requiring validated software under strict traceability protocols.
The EU Machinery Directive and CE marking requirements enforced by national regulators in Germany and France mandate functional safety certification for AGV control systems, elevating compliance costs for software vendors seeking European market access. The U.S. Occupational Safety and Health Administration interprets existing industrial truck standards to cover autonomous vehicle operations, creating enforcement uncertainty that shapes product liability coverage and safety feature prioritization. China's Ministry of Industry and Information Technology issues GB standards for industrial robot software interoperability, influencing how foreign navigation platforms adapt for domestic manufacturing ecosystems. Stakeholders must monitor whether emerging AI liability frameworks in the European Union and United States will reclassify autonomous decision-making algorithms as regulated products rather than traditional software tools.
Market Dynamics
Fleet orchestration middleware is consolidating control authority away from vehicle-level navigation stacks as warehouse operators demand centralized command over heterogeneous equipment fleets spanning multiple OEM hardware generations.
Growth Catalysts
- EU Machinery Directive compliance mandates:Functional safety certification requirements in Germany and France force facility upgrades, accelerating replacement of legacy tape-guided systems with certified software-controlled fleets.
- Pharmaceutical cold-chain validation:Temperature-sensitive distribution networks require AGV software with full audit trails and electronic batch records, creating specification premiums in validated environments.
- Cloud-native architecture migration:Elastic compute scaling enables mid-sized 3PLs to access enterprise-grade fleet coordination without on-premises infrastructure investments.
Market Restraints
- LiDAR sensor supply concentration:Sourcing dependency on Chinese and German optical component manufacturers creates lead-time volatility for navigation hardware-software bundles.
- CE marking certification timelines:European notified body backlogs extend functional safety validation cycles to 14-18 months, delaying revenue recognition for new platform releases.
- Magnetic tape infrastructure substitution:Existing warehouse operators with sunk capital in physical guidance systems face switching costs that slow pure-software navigation adoption.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for domestic manufacturing are driving greenfield distribution center construction with native AGV software specifications.
- 5G-Edge convergence:Ultra-reliable low-latency communication enables real-time fleet re-routing without warehouse Wi-Fi infrastructure overhaul.
- US OSHA clarification pathway:Pending interpretive guidance on autonomous industrial truck standards creates first-mover advantage for vendors with pre-validated safety architectures.
Industry Challenges
- Safety-certified software engineering talent scarcity:IEC 61508 competency requirements outpace vocational training pipeline output in all major manufacturing economies.
- WMS integration complexity:Proprietary data exchange protocols force custom middleware development for each major warehouse management system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Guided Vehicle (AGV) Software Market |
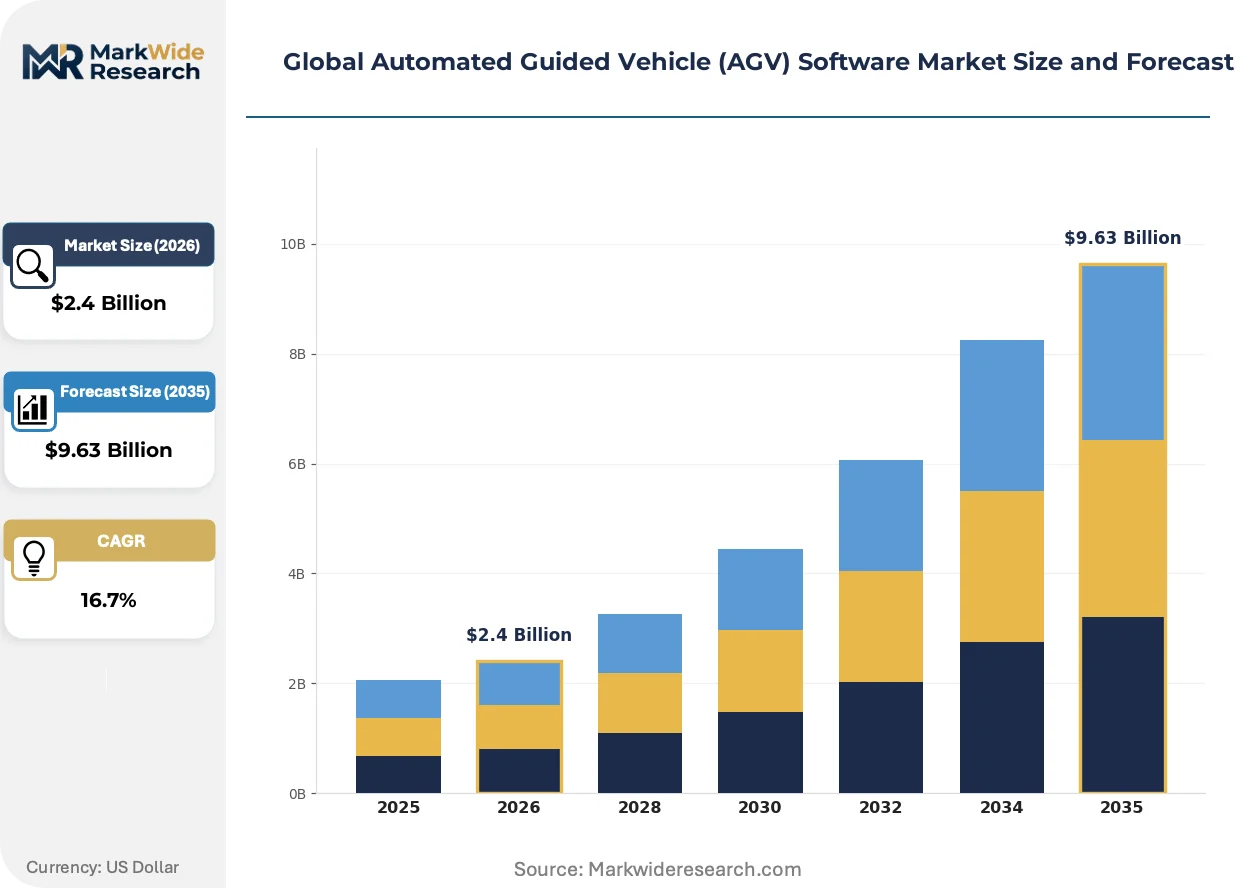
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $9.63 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Navigation, Fleet Management, Safety & Security, Maintenance, Analytics Application: Warehouse Automation, Retail Fulfillment, Airport Logistics, Manufacturing Lines, Pharmaceutical Distribution End User: E-Commerce Companies, Third-Party Logistics Providers, Automotive Tier-1 Suppliers, Food & Beverage Processors, Chemical Production Facilities |
| Companies Covered | Navitec, Swisslog Holding AG, BlueBotics, Clearpath Robotics, Seegrid Corporation, IncubedIt, Dematic, GreyOrange, Kollmorgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Guided Vehicle (AGV) Software Market Shifts & Advancements
Digital twin simulation is compressing deployment risk for AGV fleet rollouts by enabling virtual commissioning before physical infrastructure modifications. Vendors are racing to embed predictive maintenance algorithms that reduce unplanned downtime below 2% annualized.
Simulation-based deployment validation is virtualizing the traditional pilot-phase timeline. Major e-commerce fulfillment operators in the United States now mandate virtual commissioning for any fleet exceeding 50 vehicles, compressing go-live schedules from 9 months to 14 weeks. This capability is virtualizing capital allocation decisions by allowing software configuration optimization before concrete floor cutting or rack repositioning.
REACH chemical restrictions on battery electrolytes are accelerating solid-state power system development for AGV platforms. The European Chemicals Agency's 2024 substance evaluation roadmap limits conventional lithium-ion chemistries in indoor logistics environments. German automotive suppliers are responding with sodium-ion and solid-state alternatives that require redesigned battery management software stacks.
Subscription-based fleet management licenses are displacing perpetual software purchases among third-party logistics operators. Tier-1 retail fulfillment contracts in China now specify software-as-a-service pricing with uptime guarantees rather than capital expenditure line items. This preference is most visible in Yangtze River Delta distribution clusters where facility lease terms average 5-7 years versus 15-year ownership horizons in North American markets.
Global Automated Guided Vehicle (AGV) Software Market Segmentation
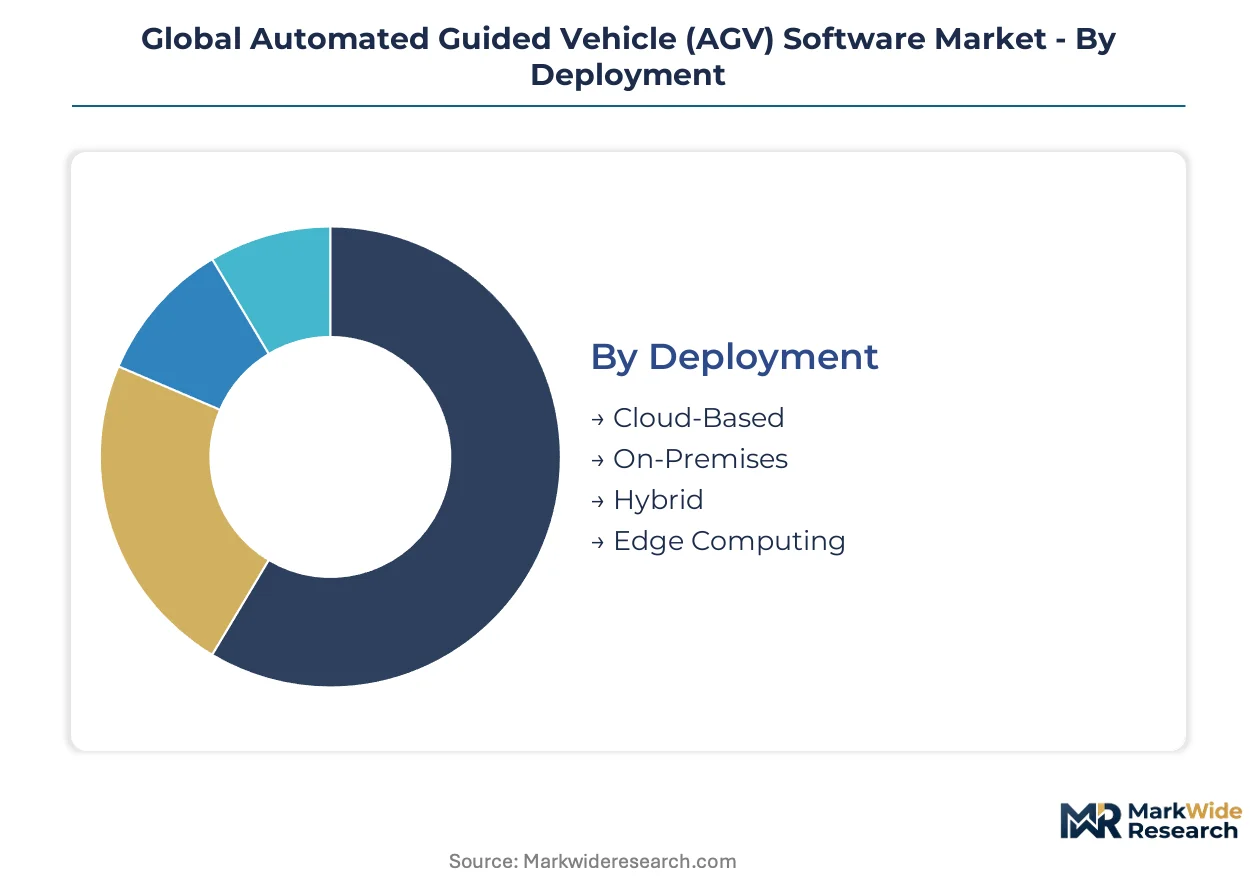
AGV software purchasing patterns diverge sharply between capital-intensive on-premises deployments favored by automotive manufacturers and subscription-driven cloud models adopted by e-commerce fulfillment networks. The segmentation reveals how regulatory complexity, fleet heterogeneity, and integration depth reshape vendor pricing architectures across deployment modes and solution tiers.
Deployment:
The use-case spectrum spans from single-facility manufacturers requiring air-gapped control systems to multi-site 3PL networks demanding elastic compute scaling across distributed warehouses.
- Cloud-Based:Software hosted on third-party infrastructure enables remote diagnostics and over-the-air navigation algorithm updates without facility-level server maintenance. Third-party logistics providers in the Yangtze River Delta specify cloud-native deployments to align software costs with 5-7 year facility lease terms rather than 15-year capital depreciation schedules.
- On-Premises:Local server installations maintain complete data sovereignty and sub-millisecond latency for safety-critical vehicle control loops. German automotive tier-1 suppliers mandate on-premises stacks to satisfy internal IT security protocols and functional safety certification requirements under the EU Machinery Directive.
- Hybrid:Split architectures process real-time navigation locally while pushing fleet analytics to cloud environments for cross-site optimization.
- Edge Computing:Containerized software deployed on warehouse edge nodes reduces bandwidth dependencies for vision-based obstacle detection.
The dominant share belongs to Cloud-Based deployments, while Edge Computing is closing the gap fastest as 5G-ULTRA networks reduce infrastructure overhaul requirements.
Solution Type:
Margin concentration follows recurring revenue intensity, with multi-vehicle coordination commanding premium pricing over single-vehicle navigation licenses.
- Navigation:Embedded algorithms process LiDAR, vision, or magnetic inputs to generate real-time path plans and obstacle avoidance trajectories. Magnetic tape-guided navigation retains installed base in legacy European manufacturing facilities where physical infrastructure substitution costs delay pure-software upgrades.
- Fleet Management:Centralized middleware orchestrates heterogeneous vehicle fleets across multiple OEM hardware generations and coordinates handoffs with warehouse management systems. E-commerce fulfillment centers in Germany deploy fleet management suites to synchronize AGV movements with automated storage and retrieval systems under EU machinery safety directives.
- Safety & Security:Functional safety modules enforce emergency stop protocols and personnel detection thresholds certified to IEC 61508 standards.
- Maintenance:Predictive algorithms monitor motor vibration patterns and battery degradation to schedule component replacement before unplanned failures.
- Analytics:Fleet performance dashboards track vehicle utilization rates, path efficiency metrics, and energy consumption patterns for continuous optimization.
Fleet Management captures the deepest recurring revenue pools, while Analytics is expanding most quickly as operators virtualize capital allocation through simulation-based deployment validation.
Application:
Specification intensity escalates from standard warehouse throughput optimization to validated cold-chain environments requiring full electronic batch record traceability.
- Warehouse Automation:Software coordinates goods-to-person picking, inbound putaway, and outbound staging across high-density storage configurations. China's Ministry of Industry and Information Technology GB standards influence how foreign navigation platforms adapt for domestic warehouse automation ecosystems.
- Retail Fulfillment:Variable SKU environments demand AI-driven fleet orchestration capable of dynamic path re-routing during promotional surge periods. GreyOrange anchors its competitive position in this segment through specialized fulfillment algorithms.
- Airport Logistics:Baggage handling systems require software capable of operating across expansive terminal footprints with mixed pedestrian and vehicle traffic.
- Manufacturing Lines:Just-in-time component delivery to assembly stations mandates precise timing synchronization with production schedules.
- Pharmaceutical Distribution:Temperature-sensitive networks require validated software with full audit trails under FDA and EMA good distribution practice guidelines.
Warehouse Automation maintains the largest installed base, though Pharmaceutical Distribution is climbing the fastest as cold-chain validation requirements harden.
End User:
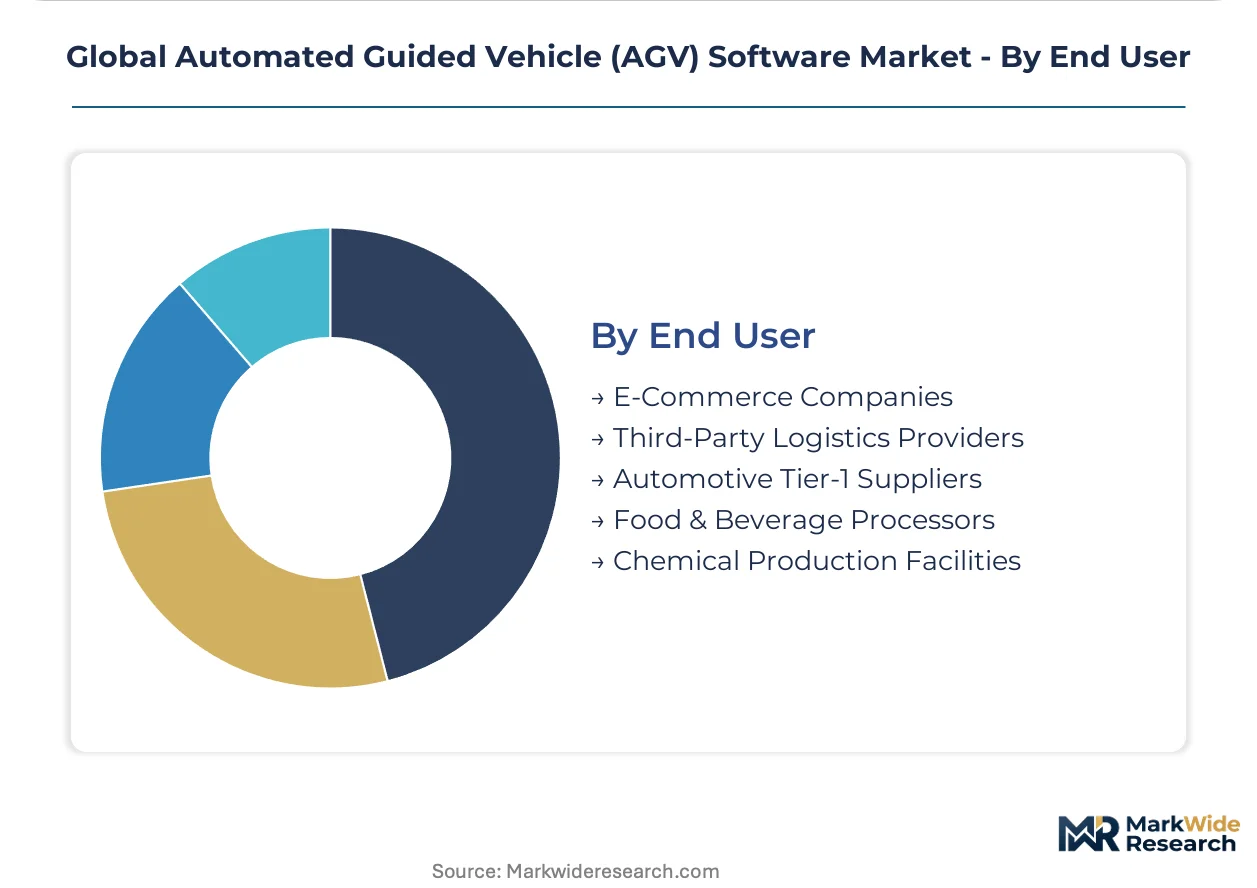
Procurement authority concentrates with operators managing facility networks large enough to amortize integration costs across multiple sites.
- E-Commerce Companies:Direct operators of fulfillment infrastructure prioritize cloud elasticity to match software capacity with seasonal demand volatility. United States-based e-commerce operators now mandate virtual commissioning for fleets exceeding 50 vehicles.
- Third-Party Logistics Providers:Multi-tenant facility operators require software capable of segregating client data and optimizing shared vehicle pools across competing brand requirements. Swisslog Holding AG bundles software with hardware service contracts to capture 3PL procurement decisions.
- Automotive Tier-1 Suppliers:Sequenced parts delivery to assembly plants demands millisecond-precision timing and zero-defect navigation reliability.
- Food & Beverage Processors:Hygienic design requirements and allergen segregation protocols shape software safety zone configurations.
- Chemical Production Facilities:Hazardous material transport mandates explosion-proof vehicle certifications and emergency response algorithms.
Third-Party Logistics Providers command the dominant procurement volume, while E-Commerce Companies are gaining share fastest as direct fulfillment infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software licensing flows track hardware deployment patterns, with Germany and China running structural trade surpluses in AGV control systems while the United States and India remain net importers of fleet orchestration platforms.
United States
E-commerce fulfillment operators mandate virtual commissioning for fleets exceeding 50 vehicles, compressing deployment timelines from nine months to fourteen weeks. OSHA's pending interpretive guidance on autonomous industrial truck standards creates enforcement uncertainty that shapes vendor liability coverage decisions. The Greater Boston cluster anchors development of cloud-native navigation algorithms serving North American distribution networks.
Germany
Automotive tier-1 suppliers mandate on-premises software stacks to satisfy internal IT security protocols and EU Machinery Directive functional safety requirements. KBA enforcement of CE marking timelines extends validation cycles to 14-18 months, delaying revenue recognition for new platform releases. The Stuttgart industrial corridor concentrates procurement for validated pharmaceutical distribution software requiring full electronic batch record traceability.
China
MIIT GB standards for industrial robot software interoperability force foreign navigation platforms to adapt data exchange protocols for domestic manufacturing ecosystems. Yangtze River Delta distribution clusters specify software-as-a-service pricing with uptime guarantees rather than capital expenditure line items. Shenzhen-based system integrators bundle edge computing deployments with 5G-ULTRA network infrastructure for real-time fleet re-routing.
India
PLI scheme incentives for domestic manufacturing drive greenfield distribution center construction with native AGV software specifications. CDSCO alignment with FDA good distribution practice guidelines shapes cold-chain validation requirements for pharmaceutical logistics operators. Maharashtra's Mumbai-Pune industrial belt anchors deployment of subscription-based fleet management licenses among third-party logistics providers.
Japan
METI industrial robot safety standards elevate software engineering competency requirements for IEC 61508 certification in precision assembly applications. Kansai region automotive suppliers prioritize millisecond-precision timing synchronization for just-in-time component delivery to assembly plants. Osaka-based integrators specialize in hybrid deployment architectures processing real-time navigation locally while pushing fleet analytics to cloud environments.
Global Automated Guided Vehicle (AGV) Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: warehouse automation incumbents bundling software with hardware service contracts, pure-play navigation specialists licensing embedded algorithms across OEM platforms, and cloud-native fleet orchestration providers capturing mid-sized 3PL procurement. Dominant competitive moves include backward integration into safety-certified software engineering talent pools and geographic expansion through notified body certification in European markets.
Within the bundled-solutions tier, Swisslog Holding AG and Dematic exemplify warehouse automation incumbents leveraging parent-company installed bases to capture multi-year service contracts. Among pure-play navigation specialists, BlueBotics and Seegrid Corporation occupy positions emphasizing hardware-agnostic software licensing across heterogeneous vehicle fleets. GreyOrange anchors the AI-driven fulfillment segment with specialized orchestration algorithms for variable SKU environments.
| Leading Market Players |
|---|
| Navitec |
| Swisslog Holding AG |
| BlueBotics |
| Clearpath Robotics |
| Seegrid Corporation |
| IncubedIt |
| Dematic |
| GreyOrange |
| Kollmorgen |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into AGV software pricing architectures, compressing margins for European system integrators while amplifying price differentiation between cloud-native SaaS tiers and on-premises perpetual licenses. Supply concentration in German optical component manufacturing and Chinese edge-compute hardware creates asymmetric cost pass-through dynamics that favor vendors with captive navigation algorithm development.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with premium tiers capturing functional safety certification under IEC 61508 and economy tiers serving magnetic tape-guided retrofits. Price differentiation rests on certification grade and after-sales service bundling, with CE-marked navigation stacks commanding substantial premiums over uncertified alternatives. Cost compression in the mid-market tier is intensifying as subscription-based fleet management licenses displace perpetual purchases among third-party logistics operators. E-commerce fulfillment centers exhibit the lowest price sensitivity due to uptime guarantee requirements, while small automotive tier-2 suppliers remain highly cost-conscious.
Supply Chain Analysis
Export control restrictions on LiDAR sensor technology and machine vision processors limit component flows from Chinese and German manufacturers to foreign navigation platform developers. Geographic supply concentration centers on China for edge-compute hardware, Germany for optical sensing components, and Taiwan for semiconductor fabrication. Raw material dependencies draw from rare earth magnet supply for drive systems, lithium-ion cell chemistry for power management, and precision optical glass for vision systems. Single-source vulnerability in LiDAR emitter arrays creates procurement risk for vendors lacking dual-qualified suppliers. Distribution runs through system integrator channels that bundle software with hardware service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AGV software penetration sits in early-cycle expansion as pharmaceutical cold-chain validation requirements and EU Machinery Directive compliance mandates accelerate replacement of legacy tape-guided systems. Cloud-native architecture migration among mid-sized third-party logistics operators extends addressable market reach beyond capital-intensive automotive incumbents.
For Market Incumbents: Build certification moats through accelerated IEC 61508 competency investment and notified body relationship deepening in German and French markets. Backward integration into safety-certified software engineering talent pools defends against pure-play navigation specialists eroding margin in hardware-agnostic licensing. Capacity addition in Stuttgart and Munich industrial corridors captures automotive tier-1 supplier procurement concentrated under EU Machinery Directive requirements. For New Entrants and Emerging Players: Mid-market third-party logistics providers in India's Maharashtra industrial belt represent the most penetrable entry point, with PLI scheme incentives driving greenfield distribution center construction lacking legacy infrastructure lock-in. Pharmaceutical distribution software in validated cold-chain environments offers specification-premium capture with lower competitive density than saturated warehouse automation. A direct SaaS sales motion with uptime-guaranteed pricing aligns with Yangtze River Delta facility lease terms averaging five to seven years. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native fleet orchestration providers with demonstrated 5G-edge convergence capabilities and recurring revenue intensity above single-vehicle navigation licensing. Long-term viability over the next decade rests on software engineering talent scarcity arbitrage and regulatory certification barrier maintenance. The signal to watch is OSHA interpretive guidance clarity on autonomous industrial truck standards, which would trigger accelerated capital deployment toward pre-validated safety architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep WMS integration with SAP and Oracle systems captures enterprise procurement decisions. |
| Acquisition of Specialist Firm | Navigation algorithm developers with IEC 61508 certification accelerate European market access. |
| Geographic Expansion | Notified body certification in Germany and France unlocks pharmaceutical distribution opportunities. |
| Product Launch | Digital twin simulation capabilities compress deployment timelines for e-commerce fulfillment operators. |
| Strategic Partnership | 5G-ULTRA network infrastructure alliances enable real-time fleet re-routing without facility overhaul. |
Research Methodology
Cross-validation between primary interviews with warehouse automation directors, fleet operations managers, system integration specialists, and regulatory compliance officers and secondary validation anchors the qualitative findings. Primary fieldwork draws from facility tours in German automotive corridors, Yangtze River Delta distribution clusters, and Maharashtra industrial belt greenfield sites. Secondary sources include EU Machinery Directive implementation guidance from German KBA and French notified bodies, MIIT GB standard documentation, OSHA interpretive guidance dockets, SEC filings from warehouse automation incumbents, and customs data on LiDAR sensor trade flows. Bottom-up triangulation across deployment mode, solution type, application vertical, and end-user segment converges with top-down macroeconomic overlay analysis.
Calibration against historical adoption curves in warehouse management systems and manufacturing execution platforms shapes the analytical framework across the projection horizon. Segmentation dimensions modeled span deployment architecture, fleet scale tier, integration complexity level, vertical regulatory intensity, and regional certification pathway. CAGRs derive from elasticity-adjusted penetration modeling against capital expenditure cycles and facility construction pipelines. Industry-specific forecast inputs include pharmaceutical cold-chain validation requirement timelines and 5G infrastructure deployment schedules in target logistics corridors.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles, facility lease term structures, or semiconductor availability would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline adherence and technology substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Nanorobotics Market