
 Motherboard Market | 2026-2036
Motherboard Market Size, Share, and Industry Trends Forecast 2026-2036
Motherboard Market Outlook
PCI-SIG compliance certification is redrawing competitive boundaries for high-speed signal integrity. ASUS leverages in-house PCB fabrication to sustain premium positioning in enthusiast segments. Supermicro anchors North American server motherboard supply through direct-to-datacenter channel control. Gigabyte Technology differentiates via thermal design specialization for compact workstation builds.
A motherboard is a printed circuit board that houses the CPU socket, memory slots, expansion buses, and chipset interconnect, typically fabricated from FR-4 laminate with 8-14 copper layers and impedance-controlled traces for gigahertz signaling. It serves as the central nervous system of computing devices, coordinating power delivery and data exchange between processors, storage, and peripherals. ATX form factor retains volume leadership in desktop builds, while Mini ITX commands premium pricing in compact gaming and embedded applications where space constraints dominate design tradeoffs. PCI Express connectivity tiers now function as a de facto segmentation mechanism, with PCIe 5.0-enabled boards capturing margin pools from workstation and AI inference server buyers.
FCC electromagnetic compatibility rules in the United States and CE marking requirements under EU RoHS and REACH constrain material selection and trace routing for products sold across both jurisdictions. China's GB standards and NMPA-aligned quality supervision further condition market access for imported boards and locally manufactured alternatives. Taiwan's BSMI safety certification adds another compliance layer for production originating from the island's dominant ODM ecosystem. Stakeholders must weigh certification lag against interface generation transitions when committing to platform roadmaps.
Market Dynamics
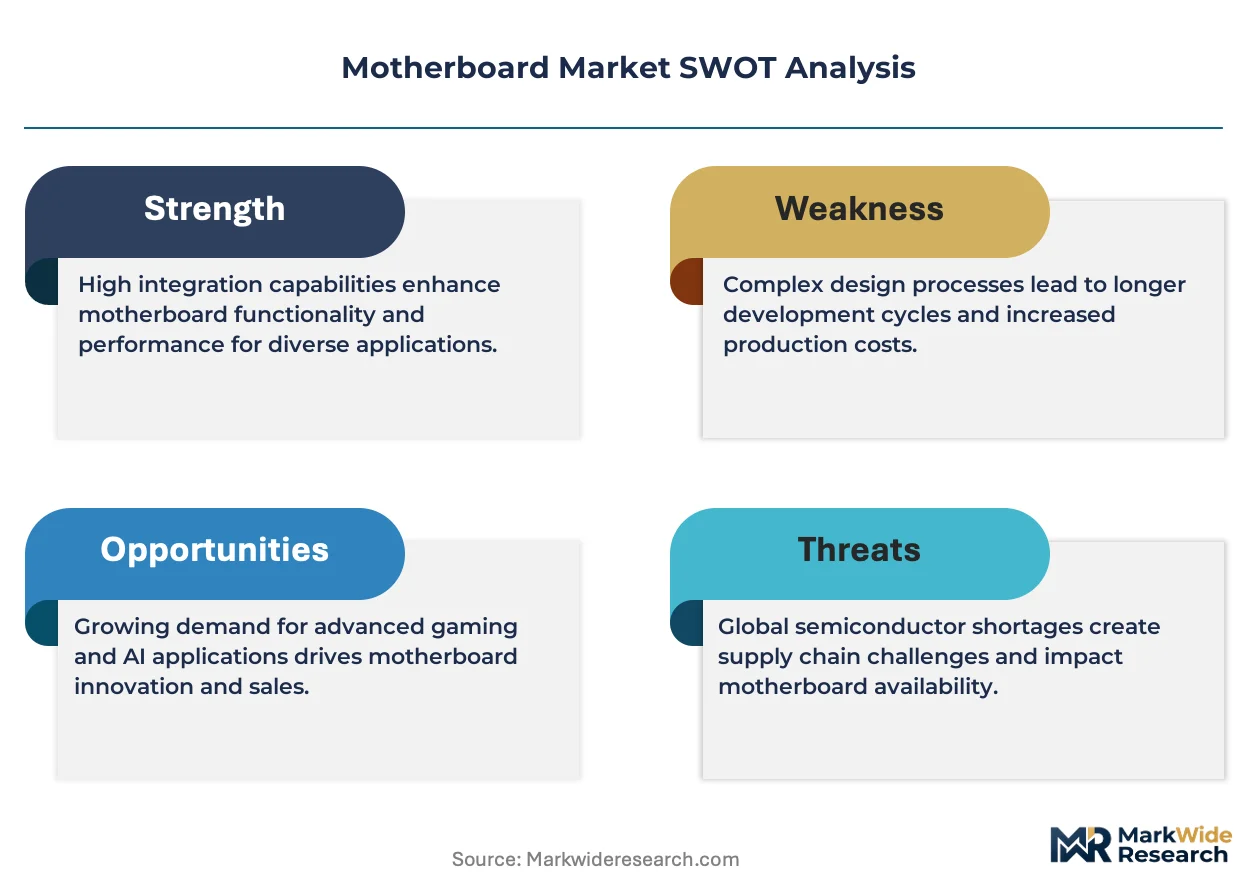
PCIe 5.0 interface migration is compressing refresh cycles across enterprise infrastructure, forcing simultaneous retooling of signal integrity engineering, thermal management, and power delivery architectures. This single technical inflection is redrawing competitive boundaries between established ODMs and specialized high-speed PCB fabricators.
Growth Catalysts
- Data center buildouts:Hyperscale operators in the United States and Germany are expanding server motherboard procurement for AI inference clusters, driving demand for multi-socket designs with enhanced VRM thermal headroom.
- REACH material compliance:EU RoHS and REACH constraints on halogenated flame retardants are accelerating FR-4 laminate substitution with higher-grade epoxy systems that support gigahertz signaling.
- Hsinchu cluster concentration:Taiwan's science park ecosystem anchors ODM engineering resources, creating captive access to advanced PCB fabrication for PCIe 5.0-compliant designs.
Market Restraints
- Copper and resin input volatility:FR-4 laminate pricing fluctuates with copper cathode and epoxy resin feedstock markets, compressing margin predictability for mid-tier board fabricators.
- Single-region ODM dependency:Concentration of high-layer-count PCB production in Taiwan's Hsinchu-Taoyuan corridor exposes supply continuity risk from seismic or geopolitical disruption.
- Signal integrity ceiling:Current organic substrate materials face fundamental limitations at PCIe 6.0 speeds, requiring costly transitions to glass-core or embedded bridge technologies.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and testing are attracting motherboard ODMs to establish captive PCB facilities in Gujarat and Tamil Nadu.
- Edge AI server form factors:Compact E-ATX and proprietary short-depth designs for telco edge cabinets represent underpenetrated volume pools outside traditional hyperscale procurement.
- MIIT domestic substitution:China's GB standards and NMPA-aligned quality supervision are creating procurement preference for locally certified boards in government and SOE server deployments.
Industry Challenges
- High-speed signal integrity engineering scarcity:Talent capable of PCIe 5.0+ channel simulation and equalization tuning commands premium compensation, constraining ODM expansion velocity.
- BSMI certification lag:Taiwan's safety certification timeline for revised power delivery architectures delays platform launches by 8-14 weeks against competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motherboard Market |
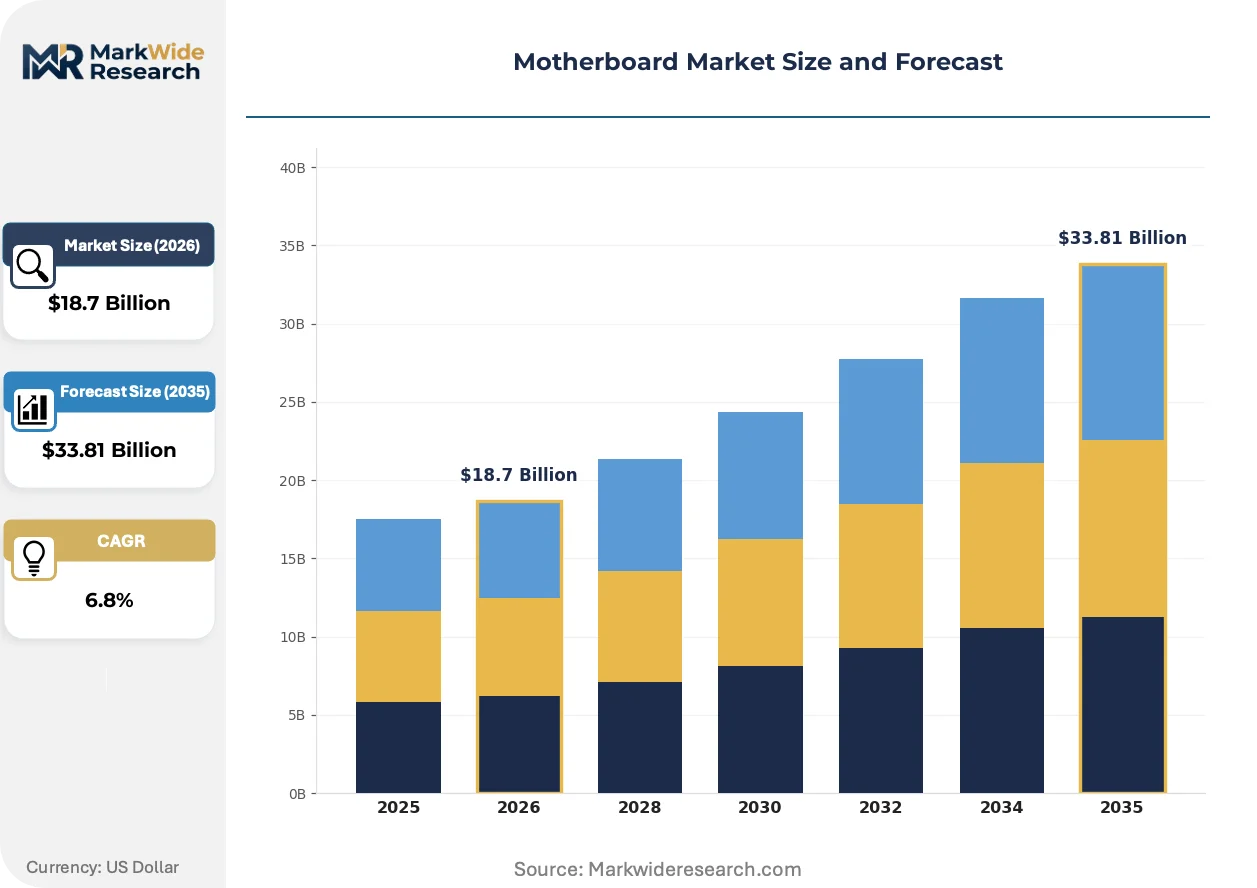
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATX, Micro ATX, Mini ITX, E-ATX Connectivity Type: USB, HDMI, PCI Express, SATA Form Factor: Standard, Custom, Compact, Modular Target User: Gamers, Professionals, General Users, Developers |
| Companies Covered | ASUS, MSI, Gigabyte Technology, ASRock, Supermicro, Intel, Advantech, Biostar, Colorful, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motherboard Market Strategic Shifts
Power delivery architectures are undergoing fundamental restructuring as processor TDP envelopes expand beyond 350W. Thermal and electrical design constraints are converging, forcing motherboard layouts to prioritize VRM cooling over traditional expansion slot density.
Chiplet-based processor packaging is decomposing the monolithic motherboard into distributed substrate assemblies. AMD and Intel's disaggregated die strategies require more complex routing between CPU tiles and memory controllers. Server OEMs are adopting these platforms faster than desktop builders, compressing the design validation cycle from 18 months to 11 months. This shift is decomposing the traditional single-board value proposition into modular power and I/O subsystems.
EU F-Gas Regulation phase-down schedules are accelerating hydrocarbon and CO2-based cooling system adoption in European data centers. This regulatory pressure is forcing motherboard vendors to certify designs for wider ambient temperature ranges and condensing environments. German and French server deployments are most affected, with ODMs now pre-qualifying boards for 40°C inlet conditions versus historical 35°C standards.
Direct-to-datacenter channel contracts are displacing traditional distribution for enterprise server motherboards. Supermicro and direct-attach ODMs are capturing procurement relationships previously mediated by broadline distributors. North American hyperscale buyers are leading this transition, with Taiwan-based ODMs establishing dedicated account engineering teams in Ashburn and Phoenix to bypass distributor margin layers.
Motherboard Market Segmentation
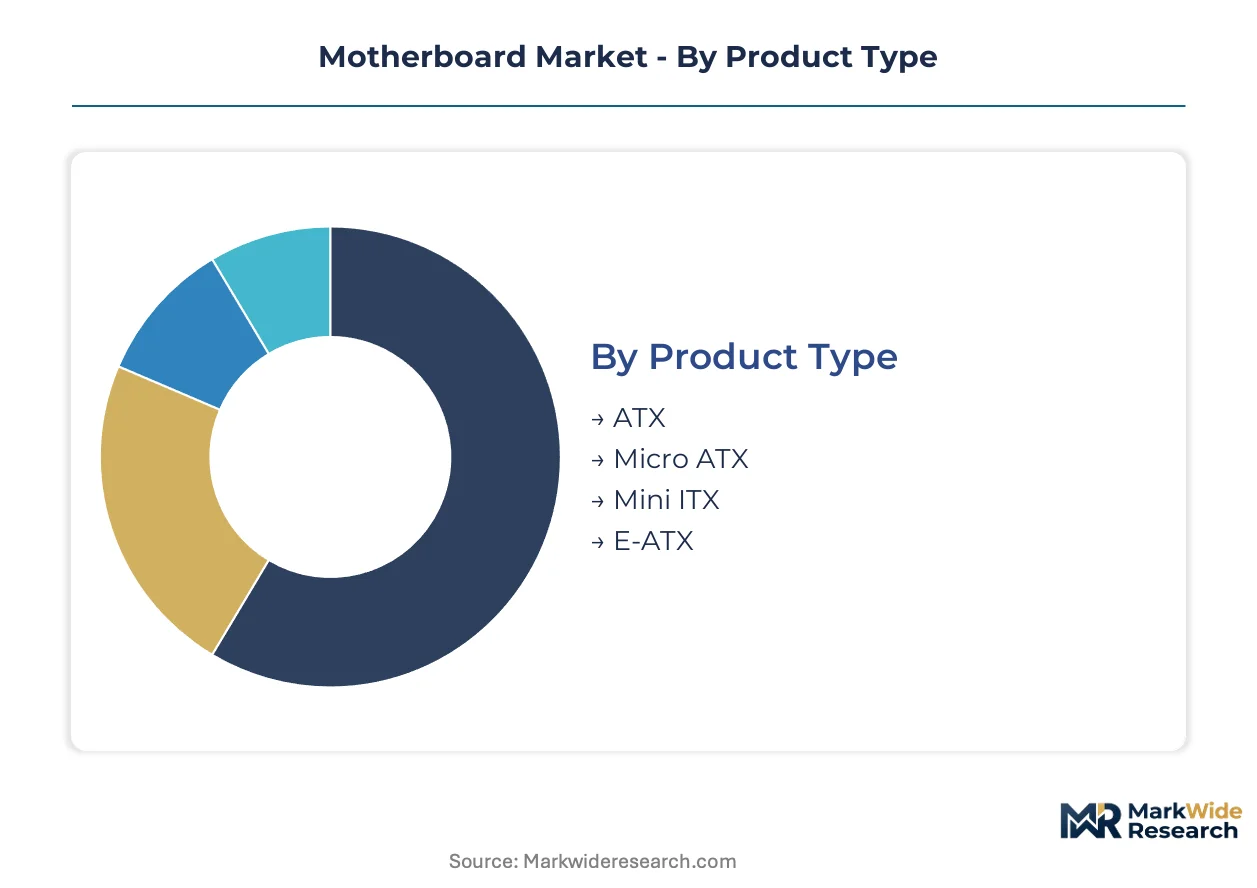
Motherboard segmentation reveals how technical specifications translate into procurement channels. Signal integrity requirements and thermal envelopes determine whether boards flow through distributor networks or direct-to-datacenter contracts.
Product Type:
Channel mix varies sharply by board dimensions, with larger form factors commanding direct enterprise procurement while compact designs move through retail and system integrator channels.
- ATX:The 305mm x 244mm specification accommodates four memory slots and multiple expansion buses. Data center operators in the United States and Germany specify ATX variants for AI inference clusters, prioritizing VRM thermal headroom over slot density. Direct-to-datacenter contracts displace traditional distribution for this segment.
- Mini ITX:The 170mm x 170mm footprint demands layered PCB routing and specialized thermal solutions. Premium pricing prevails in compact gaming builds and embedded applications where space constraints dominate design tradeoffs in Taiwan's Hsinchu cluster output.
- Micro ATX:Mid-tower desktop builds favor this 244mm x 244mm specification for cost-optimized consumer procurement.
- E-ATX:Extended dimensions serve workstation and server applications requiring additional memory channels and expansion slots.
ATX dominates installed base. Mini ITX is where expansion concentrates.
Connectivity Type:
Interface generation functions as a de facto cost tier, with premium signal integrity certification separating enterprise procurement from volume consumer channels.
- PCI Express:PCIe 5.0-enabled boards capture margin pools from workstation and AI inference server buyers. Hyperscale operators specify PCIe 5.0 for bandwidth-intensive workloads, forcing simultaneous retooling of signal integrity engineering and power delivery architectures. FCC electromagnetic compatibility rules constrain trace routing for US-bound shipments.
- USB:USB4 and Thunderbolt integration commands premium positioning in professional workstation builds. Content creators and software developers in Germany and France prioritize high-speed peripheral connectivity, driving specification requirements for external storage and capture devices.
- HDMI:Display output standards segment boards by integrated versus discrete graphics use cases.
- SATA:Legacy storage connectivity persists in cost-sensitive enterprise refresh cycles and archival server deployments.
PCI Express commands revenue concentration. USB is climbing the fastest as peripheral bandwidth demands escalate.
Form Factor:
Physical configuration determines supply chain configuration, with custom and modular designs requiring captive engineering relationships versus standard volume production.
- Standard:ATX and Micro ATX reference designs flow through high-volume ODM channels with minimal customization. Taiwan's Hsinchu-Taoyuan corridor anchors production for this segment, exposing supply continuity risk from seismic or geopolitical disruption.
- Compact:Mini ITX and proprietary small-form-factor specifications demand specialized thermal design and layered PCB fabrication. Edge AI server deployments in telco cabinets drive specification requirements for short-depth designs.
- Custom:Hyperscale operators specify proprietary layouts for optimized thermal and power delivery in dedicated facilities.
- Modular:Disaggregated power and I/O subsystems serve chiplet-based processor packaging requirements.
Standard form factors dominate volume shipments. Compact designs are gaining share fastest in edge infrastructure.
Target User:
End-use segmentation separates enthusiast retail channels from professional procurement systems and enterprise direct contracts.
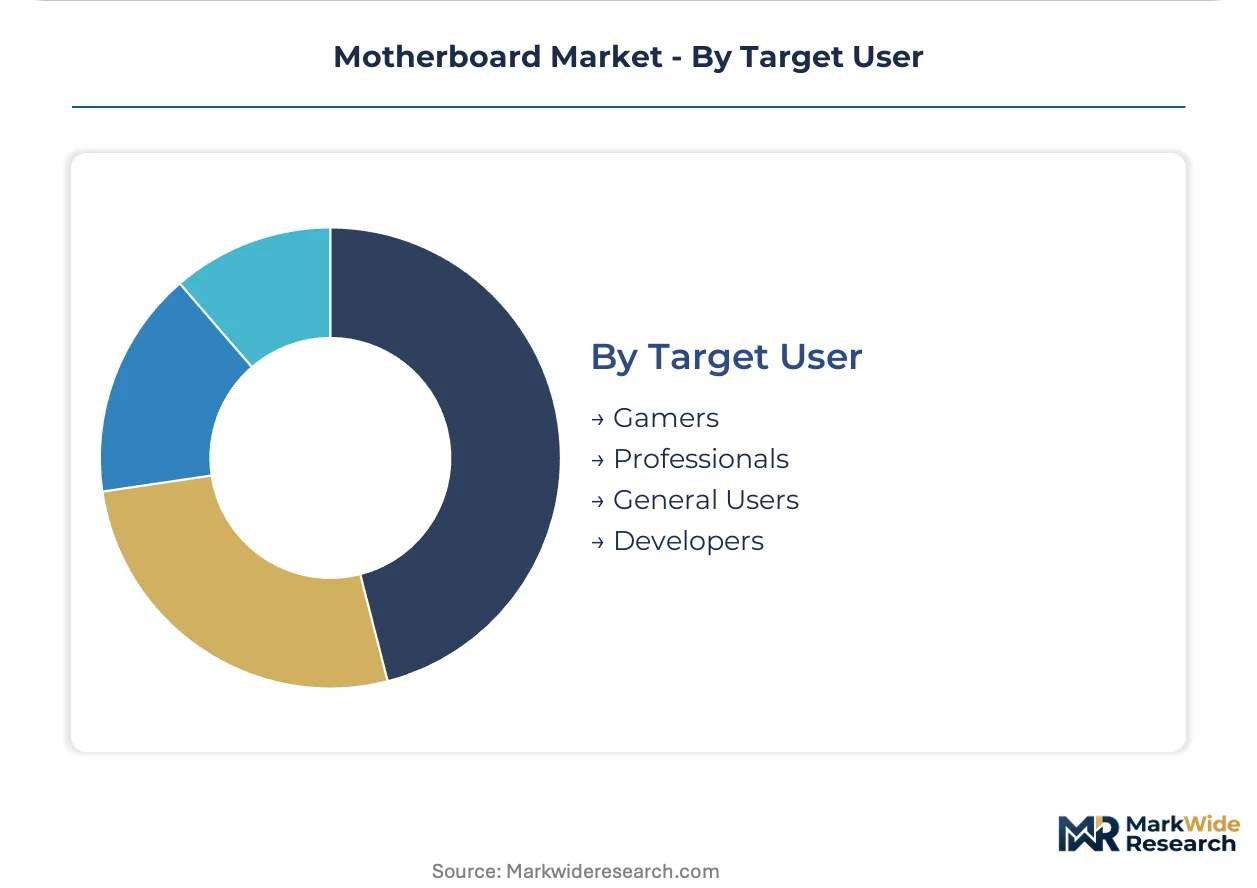
- Professionals:Workstation builders prioritize certified stability and extended validation cycles. Software developers and media production houses in the United States specify boards with enhanced VRM cooling and error-correcting memory support, driving premium-mid-economy pricing differentiation across certification tiers.
- Gamers:RGB integration and overclocking headroom command retail premium positioning. Enthusiast segments in Taiwan and South Korea drive demand for specialized thermal solutions and aesthetic customization.
- General Users:Cost-optimized consumer builds move through broadline distributor networks with minimal specification differentiation.
- Developers:Prototyping and embedded system requirements favor compact form factors with expansion flexibility.
General users dominate unit volume. Professionals represent the steepest expansion trajectory as workstation procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and MIIT domestic substitution mandates in China are redrawing motherboard procurement geography. Data center buildouts in Germany and hyperscale expansion in the United States are concentrating demand in specific industrial corridors. Taiwan's Hsinchu cluster retains fabrication dominance while supply chain diversification accelerates.
United States
Hyperscale operators in Ashburn and Phoenix are expanding server motherboard procurement for AI inference clusters. FCC electromagnetic compatibility rules constrain trace routing and material selection for domestic-bound shipments. The Pacific Northwest anchors direct-to-datacenter channel engineering teams established by Taiwan-based ODMs.
Germany
EU F-Gas Regulation phase-down schedules are accelerating motherboard certification for wider ambient temperature ranges in Frankfurt and Berlin data centers. REACH constraints on halogenated flame retardants mandate FR-4 laminate substitution with higher-grade epoxy systems. Bavaria hosts workstation procurement relationships prioritizing certified stability and extended validation cycles.
China
MIIT domestic substitution policies are creating procurement preference for locally certified boards in government and SOE server deployments. GB standards and NMPA-aligned quality supervision condition market access for imported alternatives. The Yangtze River Delta concentrates motherboard assembly and testing facilities serving domestic hyperscale buyers.
Taiwan
BSMI safety certification timelines delay platform launches by 8-14 weeks against competitive windows. Hsinchu Science Park anchors ODM engineering resources with captive access to advanced PCB fabrication for PCIe 5.0-compliant designs. The Hsinchu-Taoyuan corridor exposes supply continuity risk from seismic or geopolitical disruption.
India
PLI scheme incentives for semiconductor assembly and testing are attracting motherboard ODMs to establish captive PCB facilities. Gujarat and Tamil Nadu host emerging fabrication capacity targeting export markets and domestic server procurement. The country's national electronics regulator is aligning certification timelines with international standards to accelerate market entry.
Motherboard Market Competitive Environment
Player mix skews toward vertically integrated ODMs with captive PCB fabrication and specialized server-focused fabricators with direct-to-datacenter channel control. The competitive structure separates premium-tier vendors with in-house signal integrity engineering from mid-tier assemblers dependent on third-party laminate supply. Two strategic archetypes dominate: Taiwan-based ODMs leveraging Hsinchu cluster concentration and North American server specialists anchoring hyperscale procurement relationships. M&A activity targets high-speed PCB fabricators with PCIe 5.0 certification capabilities, while capacity expansion concentrates in India and Vietnam to diversify single-region dependency.
Within the premium-tier enthusiast segment, ASUS exemplifies vertical integration through in-house PCB fabrication sustaining positioning in high-margin builds. Supermicro occupies a distinct position anchoring North American server motherboard supply through direct channel relationships with hyperscale operators. Among Taiwan-based ODMs, Gigabyte Technology and ASRock represent alternative competitive vectors through thermal design specialization and cost-optimized volume production respectively.
| Leading Market Players |
|---|
| ASUS |
| MSI |
| Gigabyte Technology |
| ASRock |
| Supermicro |
| Intel |
| Advantech |
| Biostar |
| Colorful |
| Others |
Value Chain & Pricing Dynamics
High-layer-count PCB fabrication in Taiwan's Hsinchu-Taoyuan corridor generates scale economies that compress unit costs for PCIe 5.0-compliant designs while simultaneously elevating price floors for mid-tier competitors lacking captive laminate supply. This concentration dynamic forces pricing discipline through supply-side control rather than demand elasticity alone.
Pricing Analysis
Certification level creates the primary spread between premium and volume tiers, with BSMI safety validation and FCC electromagnetic compatibility compliance commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by signal integrity grade and thermal design sophistication. Cost compression in the economy tier is intensifying because ODMs in Taiwan and Vietnam compete for volume contracts with thinning margin buffers. Hyperscale data center operators exhibit the lowest price sensitivity, prioritizing VRM thermal headroom and direct channel relationships over unit cost.
Supply Chain Analysis
Taiwan and China anchor high-layer-count PCB fabrication and motherboard assembly respectively, with South Korea supplying advanced memory controllers and VRM components. Raw material dependencies center on copper cathode, epoxy resin feedstocks, and halogen-free FR-4 laminates compliant with REACH constraints. Single-source vulnerability from seismic exposure in the Hsinchu corridor threatens supply continuity for PCIe 5.0-grade substrate production. Distribution runs through direct-to-datacenter contracts for enterprise server boards and broadline distributor networks for consumer retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across edge AI server form factors and regional manufacturing incentives creates viable entry points outside incumbent-dominated hyperscale procurement. Chiplet-based processor packaging decomposes traditional motherboard value into modular subsystems, generating specialist niches.
For Market Incumbents: Fortify captive PCB fabrication capacity in India and Vietnam to dilute single-region dependency while accelerating BSMI pre-certification investments to compress platform launch windows. Emerging ODMs in Gujarat threaten volume positioning unless incumbents establish localized engineering presence ahead of PLI scheme maturation.
For New Entrants and Emerging Players: Anchor in compact E-ATX and proprietary short-depth designs for telco edge cabinets, where underpenetrated volume pools exist outside traditional hyperscale procurement relationships. India's domestic server buildouts represent the most penetrable geography, with certification alignment to BIS standards enabling direct SOE and government procurement access.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized high-speed PCB fabricators with PCIe 5.0 signal integrity certification and established relationships with Taiwan-based ODMs. Long-term viability hinges on capability depth in glass-core substrate transitions required for PCIe 6.0 speeds. Watch for MIIT domestic substitution acceleration in China as the inflection indicator for regional supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| PCIe 5.0 Certification Investment | BSMI and FCC pre-validation compresses platform launch cycles against competitive windows. |
| India Captive Facility Establishment | PLI scheme incentives in Gujarat and Tamil Nadu diversify supply beyond Hsinchu corridor exposure. |
| Direct-to-Datacenter Channel Expansion | Bypassing distributor margin layers captures hyperscale procurement relationships in Ashburn and Phoenix. |
| Glass-Core Substrate R&D Partnership | Early positioning for PCIe 6.0 signal integrity requirements offsets organic substrate limitations. |
| Edge AI Form Factor Specialization | Telco cabinet specifications for short-depth designs access underpenetrated infrastructure deployment pools. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and customs trade data, with input from ODM engineering directors, data center procurement officers, and PCB fabrication specialists. Bottom-up triangulation across motherboard unit shipments and top-down validation against semiconductor substrate consumption patterns ensure cross-verified outputs.
Segmentation dimensions modeled include form factor specification, PCI Express generation tier, target user archetype, and regional regulatory cluster across the analysis window. CAGRs derive from installed base turnover assumptions tied to interface migration cycles and thermal design envelope expansion. Forecast inputs incorporate FR-4 laminate pricing volatility and ODM capacity utilization rates in Taiwan and emerging India facilities.
Material uncertainties — copper and resin feedstock volatility, geopolitical disruption in the Taiwan Strait, and PCIe 6.0 material transition timelines — sit outside the modeled envelope. Recalibration cycles align with material shifts in interface generation adoption and regional manufacturing incentive maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Charger Market
Electronic Components
Film Capacitor Market
Electronic Components
Encoder Market
Electronic Components
Battery Holders Market
Electronic Components
USB Retimer Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Display Port Adapters Market
Electronic Components
Microspeaker Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Audio DSP Market
Electronic Components
North America USB Retimer Market
Electronic Components
Electromechanical Timers Market
Electronic Components
Semiconductor Micro Components Market
Electronic Components
Global Industrial Media Converters Market