
 Nonanoic Acid Market | 2026-2036
Nonanoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Nonanoic Acid Market Analytics
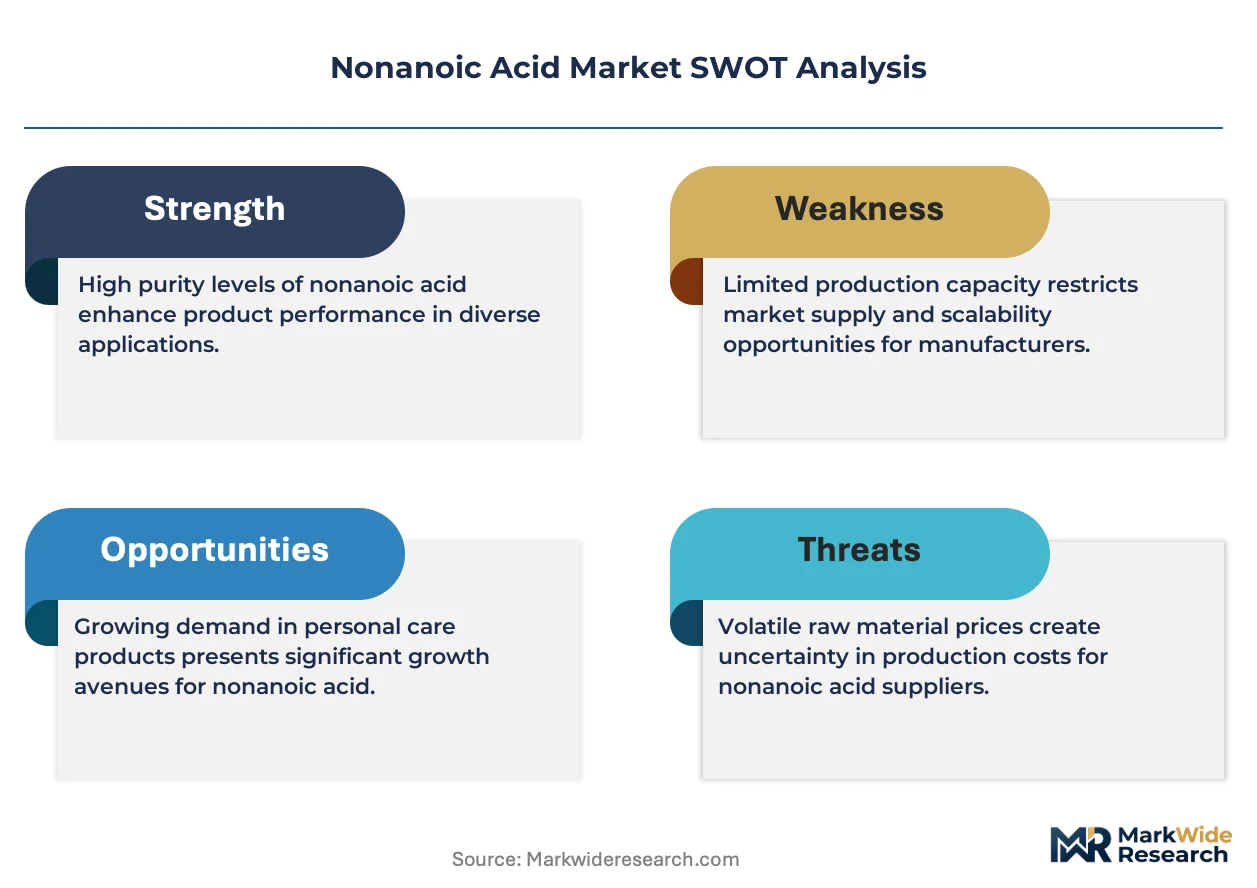
REACH compliance is broadening the cost-of-entry calculus for nonanoic acid producers serving European industrial buyers. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply chains for pelargonic acid derivatives. OQ Chemicals GmbH anchors its position through Oxo alcohol backward integration into C9 feedstock streams. Evonik Industries AG differentiates via high-purity grades targeting pharmaceutical and cosmetic precursor applications.
Nonanoic acid, also called pelargonic acid, is a saturated nine-carbon carboxylic acid with molecular formula C9H18O2, typically produced through ozonolysis of oleic acid or fermentation of renewable feedstocks, and serves primarily as a chemical intermediate for synthetic lubricants, surfactants, and agrochemical formulations. Industrial grade material dominates volume flows into lubricant and solvent applications where cost efficiency outweighs purity premiums. Pharmaceutical grade segments command elevated margins through CDMO partnerships and active pharmaceutical ingredient precursor contracts. Food grade supply channels face tightening specifications from EFSA and national food safety authorities across Western Europe.
EMA pharmaceutical standards, EPA chemical substance regulations, and REACH authorization requirements collectively shape product specifications and market access conditions for nonanoic acid manufacturers. ECHA substance evaluation processes are extending compliance timelines for novel bio-based production pathways, creating competitive differentiation between petrochemical and renewable routes. Stakeholders must monitor regulatory divergence between EU hazard classification updates and EPA TSCA Section 5 review thresholds to align capacity investments with the stricter emerging framework.
Market Dynamics
REACH authorization requirements and EFSA purity specifications are compressing supplier margins while concentrating volume among integrated chemical producers with captive ozonolysis capacity. Specialty lubricant formulators now demand documented renewable feedstock percentages, forcing process reconfiguration across the C9 carboxylic acid value chain.
Growth Catalysts
- Synthetic Ester Demand:Wind turbine gearbox manufacturers are specifying high-performance lubricants requiring nonanoic acid-derived esters for extreme pressure tolerance.
- REACH Compliance Thresholds:Tighter ECHA purity mandates are disqualifying spot-market suppliers and locking in long-term contracts with certified producers.
- Germany's Industrial Corridor:Cologne-Düsseldorf chemical clustering creates dense buyer networks with integrated logistics infrastructure.
Market Restraints
- Oleic Acid Feedstock Volatility:Vegetable oil price swings directly compress ozonolysis route economics without hedgeable alternatives.
- Azelaic Acid Substitution:C9-C9 dicarboxylic acid competitors capture surfactant applications where chain length flexibility outweighs monobasic acid performance.
- European Supply Concentration:Ludwigshafen and Marl sites control disproportionate EU volume, creating single-point vulnerability.
Strategic Opportunities
- Pharmaceutical CDMO Partnerships:High-purity grades for active pharmaceutical ingredient precursors command 3-4x industrial grade margins.
- Fermentation Route Scale-Up:Engineered yeast platforms using renewable feedstocks bypass petrochemical oleic acid dependency entirely.
- EU Green Deal Incentives:Bio-based production pathways qualify for preferential financing under circular economy transition frameworks.
Industry Challenges
- ECHA Substance Evaluation Timelines:Novel bio-based production routes face 18-24 month regulatory validation delays before market access.
- Analytical Method Harmonization:Divergent EPA TSCA Section 5 and REACH data requirements force duplicate testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonanoic Acid Market |
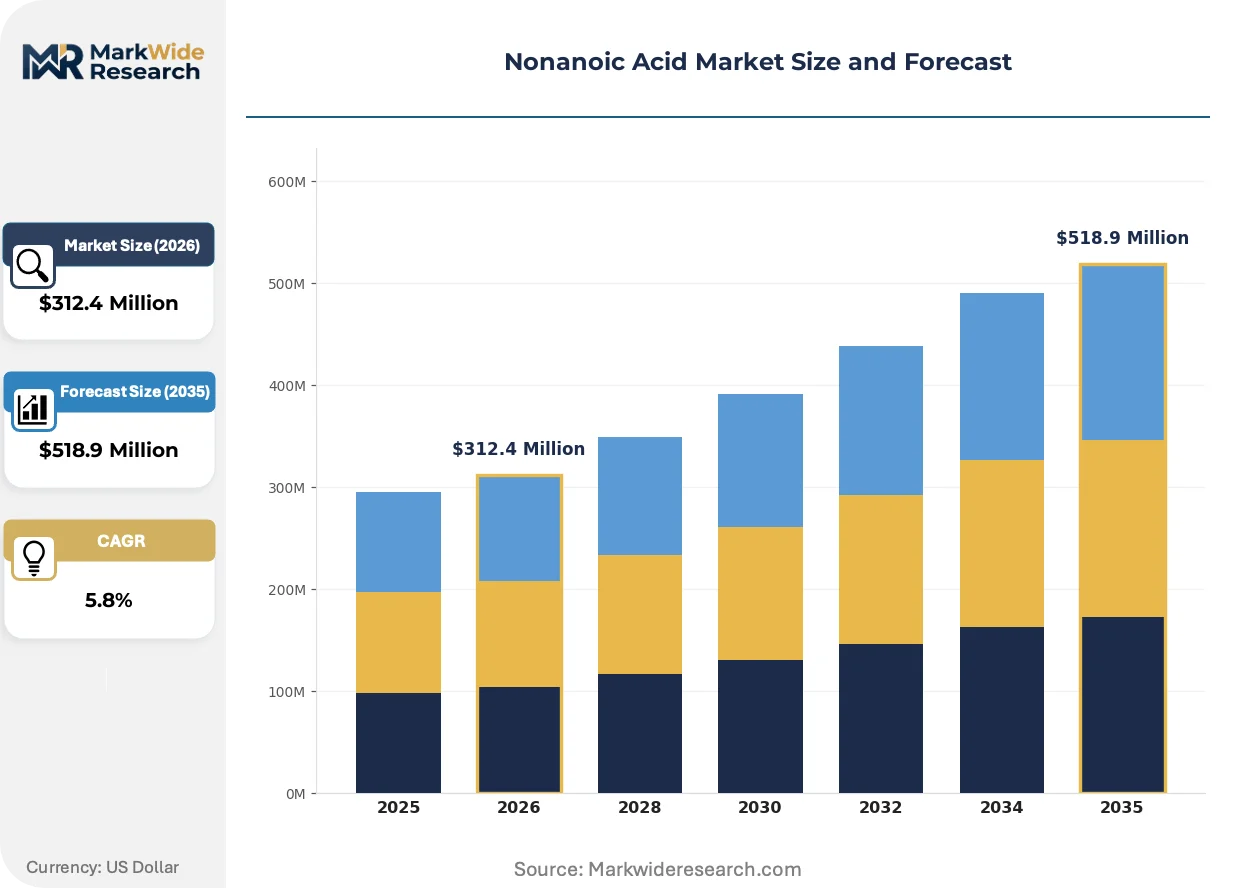
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Cosmetic Grade, Pharmaceutical Grade Application: Surfactants, Lubricants, Solvents, Additives End User: Manufacturing, Personal Care, Food processing, Pharmaceuticals Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | BASF SE, OQ Chemicals GmbH, KH Neochem Co. Ltd., Emery Oleochemicals, Evonik Industries AG, Corteva Agriscience, Albaugh Holdings, Nufarm Limited, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonanoic Acid Market Evolving Landscape
Fermentation-based production routes are disrupting the traditional oleochemical value chain, while regulatory divergence between EPA and ECHA frameworks is fragmenting compliance strategies. Buyer procurement patterns are simultaneously consolidating toward integrated suppliers and demanding granular sustainability documentation.
Biocatalytic conversion of renewable feedstocks is expanding into commercial-scale nonanoic acid production. Specialty chemical producers in the Netherlands and Belgium are piloting engineered yeast strains with C9 specificity. This platform is expanding into markets previously locked to petrochemical ozonolysis by offering mass-balance certified supply chains.
REACH authorization requirements for C9 carboxylic acid derivatives are tightening substance evaluation protocols. ECHA's extended compliance timelines for novel production pathways create competitive moats for early bio-based entrants. German industrial buyers are responding by locking in multi-year contracts with producers demonstrating pre-registered dossier completion.
Consolidated procurement by synthetic lubricant formulators is displacing spot-market purchasing. Major blenders now require documented renewable content percentages and cradle-to-gate carbon footprints. This pattern is most visible in Germany's Ruhr industrial basin, where wind energy sector demand concentrates buying power among three dominant gearbox manufacturers.
Nonanoic Acid Market Segmentation
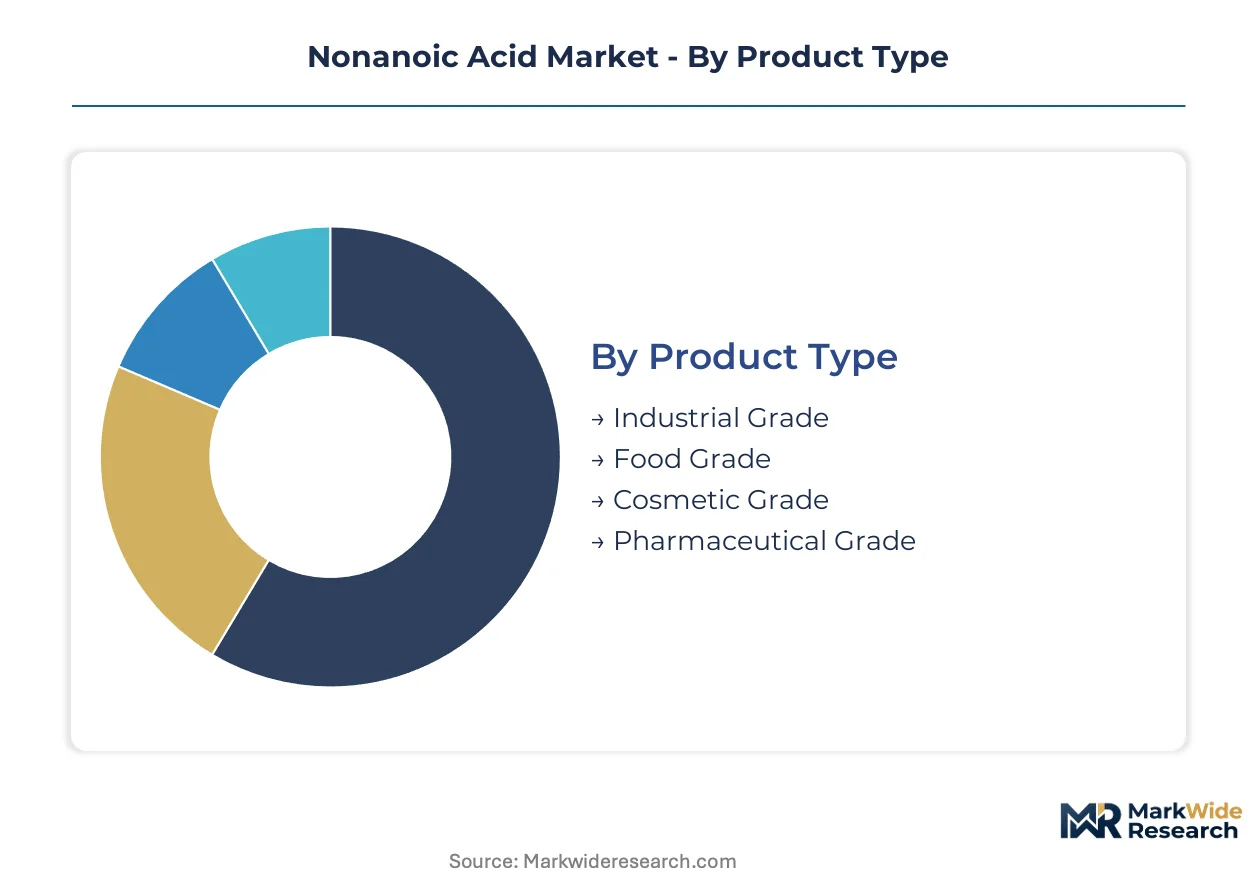
Nonanoic acid buyers exhibit sharply divergent technical requirements across purity grades, with pharmaceutical and cosmetic formulators imposing specification thresholds that industrial lubricant manufacturers disregard entirely. Segmentation reveals how certification tiers create pricing stratification that concentrates margin capture among integrated producers with multi-grade production flexibility.
Product Type:
Cost tiers separate buyers who accept technical-grade variability from those requiring batch-certified purity documentation.
- Industrial Grade:Material with 85-95% purity and higher residual oleic acid content serves synthetic ester production for wind turbine lubricants and metalworking fluids. German gearbox manufacturers in the Ruhr basin absorb the majority of EU industrial grade volume, prioritizing cost efficiency over pharmaceutical-tier specifications.
- Pharmaceutical Grade:≥99.5% purity with full impurity profiling meets EMA standards for active pharmaceutical ingredient precursors. CDMO partnerships in Switzerland and the Netherlands lock in multi-year supply contracts at 3-4x industrial grade pricing, with REACH dossier completion serving as the critical supplier qualification gate.
- Food Grade:EFSA-compliant material with strictly controlled heavy metal limits and documented chain-of-custody enters flavoring agent and food additive applications.
- Cosmetic Grade:Refined C9 acid meeting ISO 16128 natural origin criteria supplies ester formulations for European premium skincare brands.
Volume sits with Industrial Grade; growth tilts toward Pharmaceutical Grade.
Application:
End-use performance requirements dictate whether buyers source through spot markets or captive supply agreements.
- Lubricants:Synthetic ester base stocks for wind turbine gearboxes and aviation turbine oils demand nonanoic acid with controlled viscosity indices and oxidative stability. Cologne-Düsseldorf chemical corridor buyers consolidate procurement through three dominant blenders, forcing suppliers to demonstrate renewable feedstock percentages.
- Surfactants:C9-derived anionic and non-ionic surfactants for industrial cleaning and personal care formulations compete directly with azelaic acid alternatives. REACH authorization for specific surfactant derivatives has compressed the supplier base to producers with pre-registered ECHA dossiers.
- Solvents:High-boiling-point C9 acid esters serve precision cleaning applications in electronics manufacturing.
- Additives:Corrosion inhibitors and plasticizer components for polymer compounding absorb lower-purity material streams.
Revenue concentrates in Lubricants; steepest expansion trajectory belongs to Surfactants as bio-based feedstock certification penetrates personal care supply chains.
End User:
Regulatory exposure and batch traceability requirements fragment procurement patterns across customer categories.
- Pharmaceuticals:API precursor manufacturers impose ICH Q3D elemental impurity limits and demand certificate-of-analysis documentation for every lot. Swissmedic and EMA inspections drive supplier consolidation toward integrated chemical producers with dedicated pharmaceutical-grade production lines.
- Manufacturing:Synthetic lubricant blenders and industrial chemical processors purchase through annual contracts with volume-tier pricing, accepting broader specification ranges in exchange for supply security.
- Personal Care:Cosmetic formulators in France and Germany require mass-balance certification and cradle-to-gate carbon footprints under EU Green Deal procurement guidelines.
- Food Processing:Flavor and fragrance compounders navigate tightening EFSA specifications on processing aid residuals.
Margin capture favors Pharmaceuticals; volume expansion tracks Manufacturing.
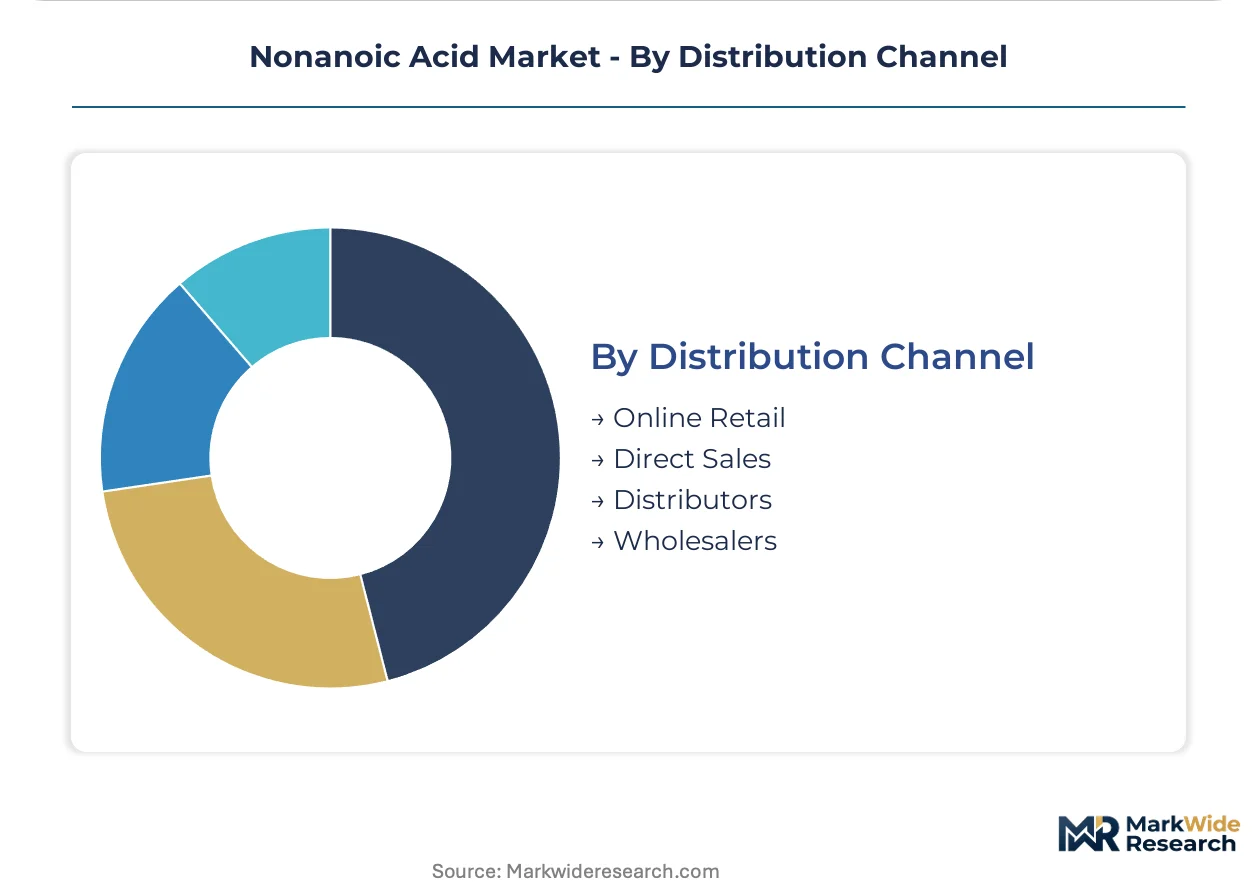
Distribution Channel:
Supply chain configuration determines whether buyers access technical support and certification documentation.
- Direct Sales:Integrated producers including BASF SE and OQ Chemicals GmbH serve German industrial corridor buyers through dedicated account management, embedding regulatory compliance support and long-term contract structures.
- Distributors:Pan-European chemical distributors including Brenntag and Univar Solutions hold inventory positions for mid-tier manufacturers requiring shorter lead times and smaller lot sizes.
- Online Retail:E-commerce platforms serve research institutions and small-scale formulators with catalog-grade material and standard certificates of analysis.
- Wholesalers:Regional bulk handlers aggregate demand from smaller industrial processors in secondary manufacturing locations.
Procurement gravity centers on Direct Sales; channel diversification accelerates through Distributors serving mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial buyers concentrate nearly half of European nonanoic acid procurement through the Cologne-Düsseldorf chemical corridor. This demand clustering shapes supplier location decisions and logistics infrastructure investments across the continent.
Germany
Wind turbine gearbox manufacturers in the Ruhr basin drive synthetic ester demand for extreme-pressure lubricants. REACH authorization requirements under ECHA tighten purity thresholds for chemical intermediates entering the EU market. The Ludwigshafen-Marl production axis hosts integrated ozonolysis capacity serving captive derivative manufacturing.
Netherlands
Rotterdam port logistics enable efficient C9 feedstock importation for oleochemical processors. The EU Green Deal circular economy transition frameworks provide preferential financing terms for bio-based production pathway investments. Biocatalytic fermentation pilots near Eindhoven are scaling engineered yeast platforms with C9 specificity.
Switzerland
Pharmaceutical CDMO partnerships lock in multi-year supply contracts for high-purity API precursors. Swissmedic inspections drive supplier consolidation toward producers with dedicated pharmaceutical-grade production lines. Basel's life sciences cluster concentrates formulation demand for EMA-compliant chemical intermediates.
Belgium
Specialty surfactant formulators in the Antwerp-Ghent industrial zone compete for C9-derived anionic and non-ionic variants. EFSA specifications on processing aid residuals tighten food-grade supply channel requirements. Mass-balance certification capabilities are expanding to serve personal care brand procurement guidelines.
France
Premium skincare brands in the Île-de-France region require ISO 16128 natural origin criteria for cosmetic-grade C9 acid. ANSM oversight of cosmetic ingredient safety extends compliance documentation burdens upstream to chemical suppliers. The Paris-Saclay research corridor hosts pilot programs for renewable feedstock fermentation scale-up.
Nonanoic Acid Market Competitive Landscape
German producers anchor the integrated tier; Asian specialists hold positions in fermentation-based supply. The supplier base compresses around three strategic archetypes: petrochemical majors with captive ozonolysis infrastructure, bio-based specialists leveraging renewable feedstock platforms, and agrochemical conglomerates with backward integration into C9 value chains. Competitive positioning hardens through multi-year contract lock-ins with certified producers and capacity expansion into pharmaceutical-grade production lines.
Within the integrated chemical tier, BASF SE and OQ Chemicals GmbH exemplify producers with Ludwigshafen and Marl site advantages. Evonik Industries AG represents the high-purity specialist archetype targeting pharmaceutical and cosmetic precursor applications. KH Neochem Co. Ltd. anchors the Asia-based fermentation pathway contingent.
| Leading Market Players |
|---|
| BASF SE |
| OQ Chemicals GmbH |
| KH Neochem Co. Ltd. |
| Emery Oleochemicals |
| Evonik Industries AG |
| Corteva Agriscience |
| Albaugh Holdings |
| Nufarm Limited |
| Croda International Plc |
| Others |
Value Network & Pricing Analysis
Integrated petrochemical majors with captive ozonolysis infrastructure anchor supply-side discipline across the European nonanoic acid value chain, translating backward integration into pricing power that spot-market suppliers cannot replicate. This ownership pattern concentrates margin capture among Ludwigshafen and Marl site operators while compressing returns for merchant producers dependent on volatile oleic acid feedstock procurement.
Pricing Analysis
Premium pricing for compressed lead times separates procurement tiers across the nonanoic acid market. Three-tier pricing structure across pharmaceutical, industrial, and technical grades reflects certification burden and batch documentation depth. Cost compression in industrial-grade segments is intensifying because German gearbox manufacturers now mandate renewable feedstock percentages without accepting price premiums. Pharmaceutical buyers show least price sensitivity due to CDMO contract structures and regulatory switching costs.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp handle bulk C9 acid flows before final-mile delivery to Cologne-Düsseldorf corridor buyers. Supply concentrates in Germany, the Netherlands, and Belgium as oleochemical processing hubs. Feedstock dependency on vegetable oil oleic acid and petrochemical C9 streams creates exposure to agricultural commodity volatility. Single-source vulnerability runs through Ludwigshafen-Marl production axis concentration. Distribution runs through integrated producer direct sales and pan-European chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonanoic acid market functions as a vertical-integration race where upstream control over ozonolysis capacity or fermentation feedstock platforms determines sustainable margin capture. Players lacking captive C9 supply chains face structural disadvantage against integrated German producers.
For Market Incumbents: Anticipate fermentation-based entrants disrupting oleochemical cost curves by securing multi-year contracts with wind turbine gearbox manufacturers before bio-based supply scales. Lock in pharmaceutical CDMO partnerships to defend against high-purity specialists. Prioritize REACH dossier completion for novel production pathways to extend regulatory moats.
For New Entrants and Emerging Players: Enter via biocatalytic fermentation platforms targeting cosmetic-grade supply chains where ISO 16128 natural origin certification commands premium positioning. White-space exists in food-grade channels facing tightening EFSA specifications that incumbent industrial producers avoid. Pursue mass-balance certification partnerships with personal care brands seeking cradle-to-gate carbon documentation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fermentation specialists in the Netherlands with scalable yeast platforms but constrained working capital. Long-term viability hinges on regulatory validation timelines shortening for bio-based pathways. Watch ECHA substance evaluation acceleration as the inflection signal for platform competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C9 Feedstock | OQ Chemicals GmbH anchors margin control through Oxo alcohol captive supply chains. |
| Fermentation Route Scale-Up | Engineered yeast platforms bypass oleic acid price volatility for renewable C9 production. |
| Pharmaceutical Grade Capacity Addition | Evonik Industries AG captures 3-4x industrial margins via EMA-compliant production lines. |
| Long-term Supply Agreement | German gearbox manufacturers lock in synthetic ester volumes with REACH-certified producers. |
| Green Manufacturing Transition | EU Green Deal financing accelerates bio-based pathway investments in Rotterdam corridor. |
Research Methodology
Independent corroboration across plant managers at ozonolysis facilities, procurement leads at synthetic lubricant blenders, distribution channel partners in the Benelux region, and technical R&D directors at fermentation pilots underwrites the qualitative findings. Secondary validation draws from ECHA substance registration databases, Cefic chemical industry reports, customs trade data for C9 carboxylic acid flows, and SEC filings from listed chemical producers. Bottom-up volume modeling triangulates against top-down market sizing from trade association aggregates.
Rate-of-change decomposition across the analysis window separates volume growth from price mix effects and grade-tier shifts. Segmentation dimensions include purity grade, end-use application, production route origin, and regional demand cluster. CAGRs derive from regression analysis against historical industrial production indices and lubricant formulation trends. Forecast inputs incorporate REACH authorization timeline probabilities and renewable feedstock cost curve projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA regulatory delay scenarios or vegetable oil price spike conditions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Whitening Ingredients Market
Chemicals
Global Thiophene Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Etching Chemicals Market
Chemicals
Malonic Acid Market
Chemicals
South Korea Methanol Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Ethanolamine Market
Chemicals
Cumene Market
Chemicals
China Inorganic Iodide Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Tromethamine Market
Chemicals
Methanol to Gasoline Market
Chemicals
Middle East Construction Chemicals Market