
 Asia-Pacific Fluorosilicic Acid Market | 2026-2036
Asia-Pacific Fluorosilicic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fluorosilicic Acid Market Insights
Multi-source procurement among phosphate fertilizer complexes is pivoting toward captive acid recovery from fluorine tail gas streams. Hubei Xingfa Group leverages its integrated phosphate-fluorine chemical chain to dominate domestic supply in central China. Gujarat State Fertilizers & Chemicals Ltd. anchors western Indian demand through dedicated captive units serving regional water utilities. Stella Chemifa Corporation competes on ultra-high-purity grades for Japanese electronics fabs, differentiating through stringent impurity controls.
Fluorosilicic acid, H2SiF6, is an aqueous solution typically containing 20-30% active acid by weight, produced as a byproduct from phosphate rock processing or synthetic hydrofluoric acid routes; it functions primarily as a fluorine source for water fluoridation, metal surface treatment, and fluorochemical synthesis. Liquid formulations occupy the dominant volume position due to compatibility with bulk municipal dosing infrastructure, though concentrate grades command superior unit economics by reducing freight burden across Australia's dispersed treatment networks. Electronics applications represent the fastest-expanding margin pool, as semiconductor fabs in South Korea and Taiwan specify sub-ppm impurity thresholds that only specialized refiners satisfy.
China's MEE enforces fluorine-containing wastewater discharge limits that compel on-site acid recovery or third-party purification, while India's BIS certification requirements for drinking water chemicals restrict import channels to qualified suppliers. Japan's METI chemical management frameworks classify fluorosilicic acid under controlled substance protocols, shaping cross-border trade documentation and storage standards. Stakeholders must monitor evolving fluorine recovery mandates and electronics-grade purity specifications as the primary determinants of competitive positioning.
Market Dynamics
China's dual carbon goals and MEE wastewater discharge rules are forcing phosphate fertilizer complexes to recover fluorosilicic acid from fluorine tail gas streams rather than vent or landfill, transforming captive supply economics across eastern China's chemical corridor.
Growth Catalysts
- Water fluoridation mandates:Southeast Asian public health agencies are tightening drinking water safety standards, compelling municipal utilities to expand fluoridation infrastructure and acid procurement volumes.
- Electronics-grade purity specifications:Semiconductor fabs in South Korea and Taiwan now specify sub-ppm impurity thresholds, creating premium demand pools that only specialized refiners can access.
- Higher-purity industrial requirements:China's stricter wastewater discharge rules under MEE are pushing industrial users toward higher-purity fluorosilicic acid grades for compliant process chemistry.
Market Restraints
- Phosphate rock input volatility:Fluorosilicic acid supply remains tethered to phosphate fertilizer production cycles, creating volume instability when phosphate demand fluctuates.
- Captive supply concentration:Eastern China's chemical manufacturing corridor dominates regional offtake through integrated phosphate-fluorine complexes, limiting third-party merchant market depth.
- Fluorine recovery cost barriers:On-site acid recovery from fluorine tail gas streams demands significant capital investment in scrubbing and purification equipment.
Strategic Opportunities
- Underpenetrated Australian treatment networks:Concentrate grades command superior unit economics by reducing freight burden across Australia's dispersed municipal water infrastructure.
- India's BIS certification channel:India's BIS certification requirements for drinking water chemicals restrict import channels, creating qualified-supplier premiums for domestic and approved foreign producers.
- Fluorochemical synthesis expansion:Synthetic hydrofluoric acid routes are converging with fluorosilicic acid recovery pathways, enabling integrated fluorochemical producers to diversify feedstock sources.
Industry Challenges
- Electronics-grade purification capex:Achieving sub-ppm impurity thresholds for semiconductor applications requires multi-stage distillation and ion-exchange systems with extended payback periods.
- Cross-border documentation complexity:Japan's METI controlled substance protocols classify fluorosilicic acid under strict chemical management frameworks, complicating storage, transport, and trade documentation.
- Legacy dosing infrastructure incompatibility:Many Southeast Asian municipal utilities operate bulk liquid dosing systems that cannot accommodate higher-concentration formulations without retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fluorosilicic Acid Market |
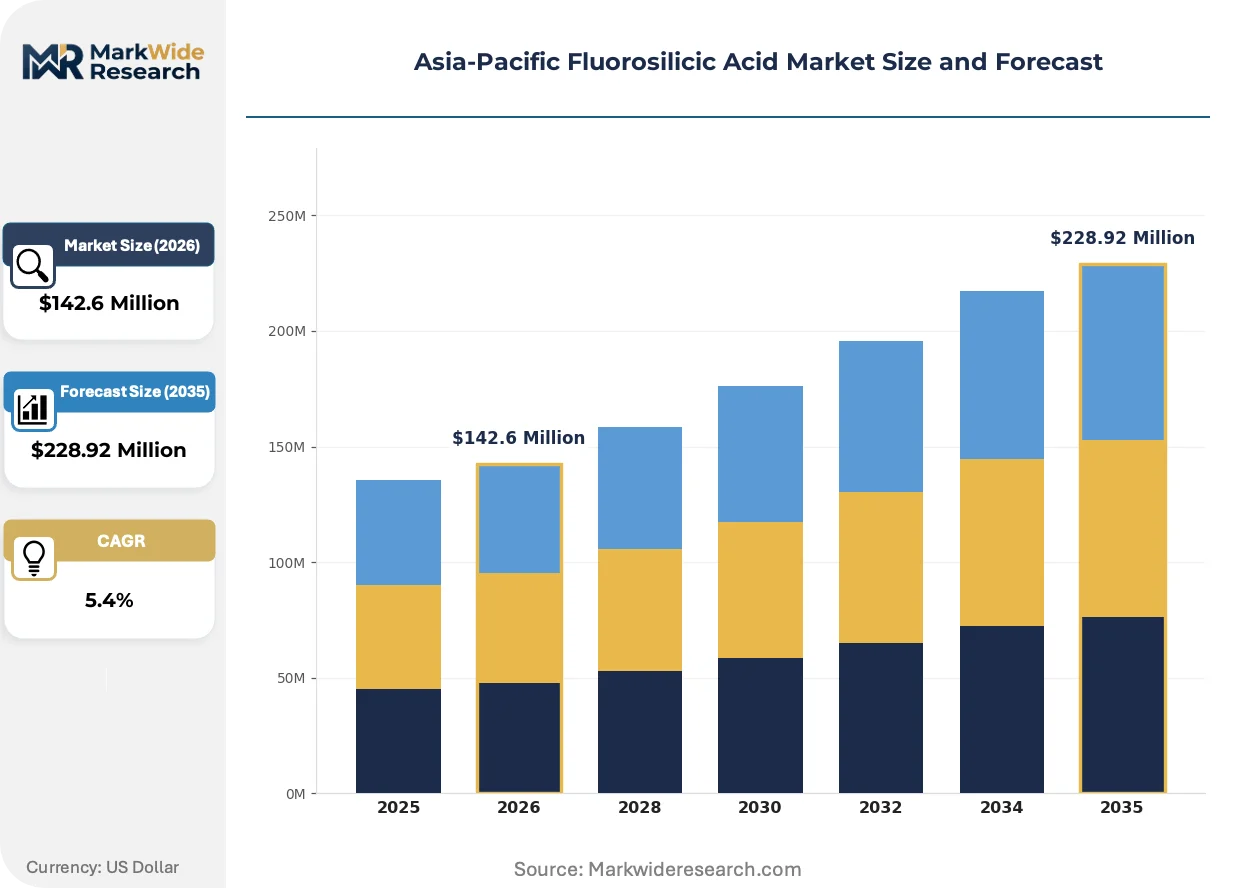
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $228.92 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Concentrate Application: Water Treatment, Chemical Manufacturing, Agriculture, Electronics End User: Municipalities, Industrial Users, Agricultural Sector, Electronics Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retailers, Others |
| Companies Covered | Hubei Xingfa Group, Foshan Nanhai Shuangfu Chemical Co., Xingxiang Yellow River Fine Chemical Industry Co. Ltd., Fengyuan Group, Jayfluoride Private Limited, Gujarat State Fertilizers & Chemicals Ltd., Stella Chemifa Corporation, Solvay, Honeywell International Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fluorosilicic Acid Market Trends and Innovations
Technology convergence between fluorine recovery systems and electronics-grade purification is reshaping competitive capabilities, while regulatory tightening around wastewater discharge and chemical management is accelerating process investments across the region.
Membrane-based fluorine recovery technology is converging with traditional wet-scrubbing systems in phosphate fertilizer complexes, enabling simultaneous acid capture and impurity rejection. Hubei Xingfa Group and similar integrated operators are deploying hybrid recovery trains to serve both captive fertilizer needs and merchant electronics-grade markets. This technology convergence is compressing the cost gap between recovered and synthetic acid sources.
China's MEE enforcement of fluorine-containing wastewater discharge limits is compelling on-site acid recovery or third-party purification across eastern industrial zones. Phosphate complexes now face penalties for unrecovered fluorine emissions, redirecting capital toward closed-loop scrubbing infrastructure. Smaller facilities without recovery capability are contracting with centralized purification services, fragmenting the traditional captive supply model.
Long-term offtake agreements are displacing spot procurement among Australian municipal water utilities seeking supply security across dispersed treatment networks. Bulk concentrate contracts with dedicated logistics providers are replacing fragmented multi-source purchasing, concentrating vendor relationships around established importers with storage and distribution infrastructure. Western Australia's isolated utilities are pioneering this contract structure to mitigate freight cost volatility.
Asia-Pacific Fluorosilicic Acid Market Segmentation
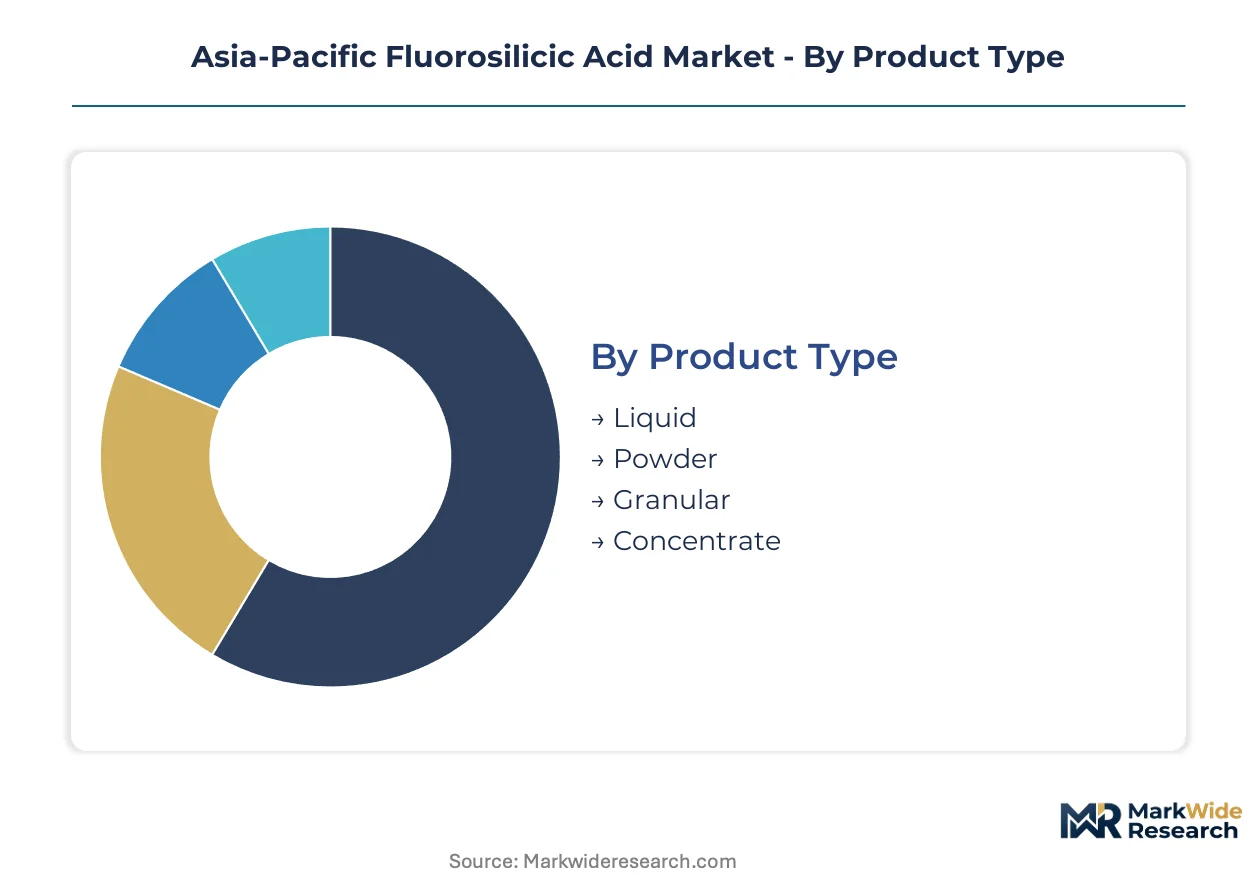
Segmentation in the Asia-Pacific fluorosilicic acid market reveals divergent capital requirements and margin structures across product forms and customer bases. Understanding these divisions exposes where purification investments concentrate and which channels resist commoditization.
Product Type:
Liquid and concentrate formulations demand the heaviest upfront investment in corrosion-resistant storage infrastructure and specialized bulk transport fleets.
- Liquid:Aqueous solutions containing 20-30% active H2SiF6 by weight, compatible with existing municipal dosing infrastructure across Southeast Asian utilities. Demand concentrates in Thailand and Vietnam where bulk fluoridation programs are expanding under tightened public health mandates, though freight costs penalize remote Australian networks.
- Concentrate:Higher active acid content reducing transport volumes, requiring dilution systems at point of use. Western Australian municipal utilities specify concentrate grades to offset freight burden across dispersed treatment networks, with procurement shifting toward long-term offtake agreements.
- Powder:Dehydrated solid requiring sealed packaging and humidity-controlled logistics; niche applications in remote industrial sites lacking liquid handling infrastructure.
- Granular:Free-flowing solid form for specialized agricultural and limited water treatment applications; constrained by higher unit costs versus liquid alternatives.
Liquid absorbs the bulk of installed capacity; concentrate is expanding most quickly.
Application:
Margin structures stratify sharply between commoditized bulk uses and purity-dependent specialty segments.
- Water Treatment:Municipal fluoridation programs across Southeast Asia drive volume demand, with procurement governed by drinking water safety mandates from public health agencies. Thailand's provincial water authorities are expanding acid dosing capacity fastest.
- Electronics:Semiconductor fabrication in South Korea and Taiwan specifies sub-ppm impurity thresholds, creating premium demand pools accessible only to specialized refiners with multi-stage purification systems. This segment commands the steepest expansion trajectory.
- Chemical Manufacturing:Feedstock for fluorochemical synthesis, primarily captive consumption within integrated phosphate-fluorine complexes across eastern China's chemical corridor.
- Agriculture:Minor fluorine source for specialized fertilizer formulations; volume constrained by substitution with cheaper fluoride compounds.
Water treatment absorbs the bulk of installed capacity; electronics is expanding most quickly.
End User:
Procurement sophistication and contract structures vary dramatically across buyer categories.
- Municipalities:Public water utilities operating under fluoridation mandates, with Australian networks pioneering multi-year concentrate supply agreements to mitigate freight volatility.
- Industrial Users:Process chemistry applications in metal treatment and chemical synthesis, with China's MEE discharge rules pushing users toward higher-purity grades requiring compliant on-site recovery or third-party purification.
- Electronics Manufacturers:Semiconductor fabs in South Korea and Taiwan imposing stringent qualification protocols that lock in approved suppliers for extended periods.
- Agricultural Sector:Dispersed demand from specialty fertilizer blenders with limited volume concentration and price-sensitive procurement.
Municipalities absorb the bulk of installed capacity; electronics manufacturers are expanding most quickly.
Distribution Channel:
Channel economics reflect the tension between bulk logistics efficiency and technical service requirements.
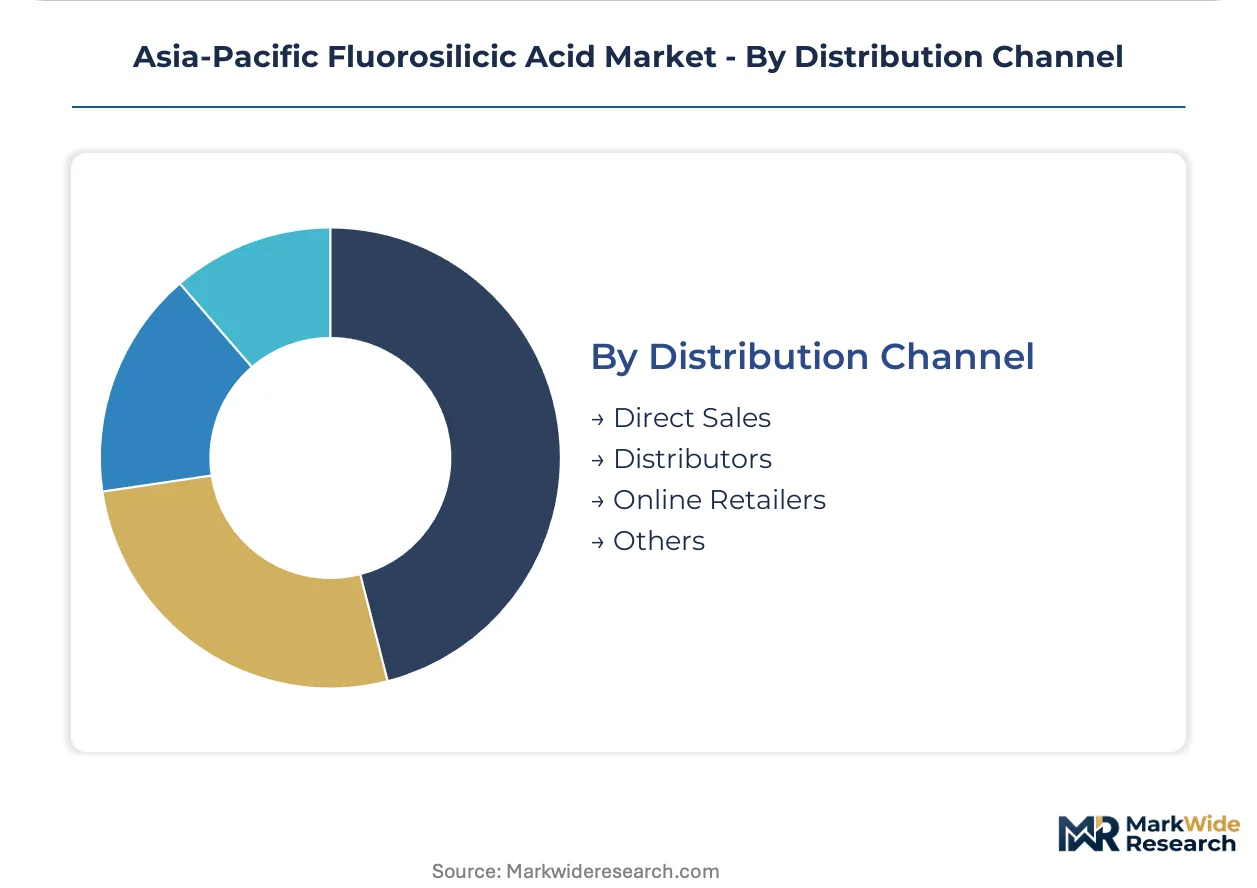
- Direct Sales:Producer-to-user relationships dominating concentrate and electronics-grade transactions, with Hubei Xingfa Group and similar integrated operators serving captive and qualified merchant accounts directly.
- Distributors:Regional intermediaries with storage infrastructure critical for liquid supply across Australia's dispersed municipal networks and Southeast Asian provincial utilities.
- Online Retailers:Limited to small-volume laboratory and specialty agricultural grades; constrained by hazardous materials shipping regulations.
- Others:Contract logistics providers and purification service operators handling centralized acid recovery for smaller facilities lacking on-site capability.
Direct sales absorb the bulk of installed capacity; distributors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in eastern China's phosphate fertilizer corridor, where captive acid recovery from fluorine tail gas streams supplies integrated fluorochemical complexes. Municipal water fluoridation programs across Southeast Asia and electronics-grade specifications in Northeast Asia create divergent demand pools with distinct procurement requirements.
China
Phosphate fertilizer complexes in Hubei and Guizhou provinces anchor domestic supply through captive fluorine recovery systems. MEE wastewater discharge rules enforce fluorine-containing effluent limits, compelling on-site acid recovery or third-party purification contracts. The Yangtze River Delta chemical manufacturing corridor dominates regional offtake, with integrated producers serving both captive fertilizer needs and merchant electronics-grade markets.
India
Gujarat State Fertilizers & Chemicals Ltd. anchors western Indian demand through dedicated captive units serving regional water utilities. BIS certification requirements for drinking water chemicals restrict import channels to qualified suppliers, creating domestic producer premiums. Maharashtra and Gujarat industrial clusters concentrate procurement from approved domestic and foreign producers with certified supply chains.
Japan
Semiconductor fabrication facilities in Kyushu and the Kanto region specify ultra-high-purity grades with sub-ppm impurity thresholds. METI chemical management frameworks classify fluorosilicic acid under controlled substance protocols, shaping cross-border trade documentation and storage standards. Stella Chemifa Corporation competes on stringent impurity controls for electronics applications.
South Korea
Memory and logic chip fabs in the Seoul Capital Area and Busan-Ulsan corridor drive premium demand for electronics-grade fluorosilicic acid. MFDS chemical safety regulations govern industrial chemical handling and import documentation for semiconductor process chemistry. Domestic refiners and qualified foreign suppliers compete through extended qualification protocols that lock in approved vendor relationships.
Australia
Western Australian municipal utilities specify concentrate grades to offset freight burden across dispersed treatment networks. Long-term offtake agreements with dedicated logistics providers are displacing fragmented multi-source purchasing. The country's national pharmaceutical regulator, the TGA, oversees chemical safety standards for drinking water treatment chemicals.
Asia-Pacific Fluorosilicic Acid Market Competitive Landscape
Capacity expansion dominates the current landscape as phosphate fertilizer complexes retrofit fluorine recovery trains to capture merchant acid volumes. The vendor base stratifies between integrated phosphate-fluorine producers with captive supply advantages and specialized refiners serving premium electronics segments. Three archetypes define competitive positioning: integrated phosphate complexes with backward control over fluorine feedstock, regional water chemical specialists with distribution infrastructure, and ultra-high-purity refiners with multi-stage purification capability. Geographic expansion into underpenetrated municipal markets and portfolio diversification into electronics-grade specifications represent the dominant competitive moves.
Among Chinese integrated producers, Hubei Xingfa Group and Foshan Nanhai Shuangfu Chemical Co. exemplify the phosphate-complex archetype with captive fluorine recovery and merchant market participation. Gujarat State Fertilizers & Chemicals Ltd. occupies a position within the regional specialist tier, anchoring Indian demand through BIS-certified supply to water utilities. Stella Chemifa Corporation represents the ultra-high-purity refiner archetype, serving Japanese and Korean semiconductor fabs with stringent impurity specifications.
| Leading Market Players |
|---|
| Hubei Xingfa Group |
| Foshan Nanhai Shuangfu Chemical Co. |
| Xingxiang Yellow River Fine Chemical Industry Co. Ltd. |
| Fengyuan Group |
| Jayfluoride Private Limited |
| Gujarat State Fertilizers & Chemicals Ltd. |
| Stella Chemifa Corporation |
| Solvay |
| Honeywell International Inc. |
| Others |
Pricing and Supply Chain Analysis
Electronics-grade purity certification creates a three-tier pricing structure across premium, standard, and economy levels that simultaneously stratifies procurement channels and concentrates supply chain investment in purification infrastructure. China's MEE discharge enforcement and India's BIS certification requirements enforce divergent cost structures, with compliant integrated producers capturing margin premiums while merchant traders face qualification barriers.
Pricing Analysis
Volume-margins split sharply between commodity liquid grades and ultra-high-purity electronics specifications. Contract-based long-term offtake dominates municipal procurement in Australia and Southeast Asia, while spot transactions persist for industrial chemical manufacturing feedstock. Price differentiation rests on impurity thresholds and certification status — BIS-approved suppliers command premiums in India, and sub-ppm grades attract semiconductor fab premiums in South Korea. Cost compression in standard-grade liquid supply is intensifying because phosphate fertilizer complexes are expanding captive recovery capacity. Municipal utilities remain most price-sensitive due to budget-constrained public procurement, while electronics manufacturers exhibit lowest sensitivity given qualification-locked supplier relationships.
Supply Chain Analysis
Direct-to-municipality channels handle bulk fluoridation demand across Thailand and Vietnam, with distributor networks critical for Australia's dispersed treatment infrastructure. Geographic supply concentrates in China, India, and Japan — China's eastern chemical corridor anchors phosphate-derived acid output, India's Gujarat cluster serves BIS-certified water utilities, and Japan's Kyushu fabs drive electronics-grade refinement. Raw material dependencies center on phosphate rock quality, fluorine tail gas capture efficiency, and synthetic hydrofluoric acid feedstock availability. Single-source vulnerability from integrated phosphate-fluorine complexes creates structural risk when fertilizer production cycles fluctuate. Distribution runs through regional chemical distributors with corrosion-resistant storage fleets for liquid grades, and direct sales relationships for concentrate and electronics specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific fluorosilicic acid markets function as a cost-of-compliance arena where China's MEE wastewater discharge rules erect capital-intensive barriers that favor incumbent integrated producers with recovery infrastructure already deployed.
For Market Incumbents: Deepen captive fluorine recovery integration to defend against merchant market fragmentation as smaller phosphate facilities contract with centralized purification services. Expand electronics-grade capacity in the Yangtze River Delta to capture semiconductor fab qualification windows before competitor refiners achieve sub-ppm certification. Channel control through long-term offtake agreements with Australian utilities locks out rival importers. For New Entrants and Emerging Players: Western Australian municipal utilities operating isolated treatment networks represent the most penetrable buyer archetype given their shift toward concentrate grades and dissatisfaction with freight cost volatility. Target qualification as a BIS-certified supplier for Indian water utilities where import channel restrictions create qualified-supplier premiums. Joint venture structures with established logistics providers overcome storage infrastructure barriers. For Investors and Strategic Acquirers: Re-rating potential sits with ultra-high-purity refiners given South Korean and Taiwanese semiconductor fab expansion and sub-ppm specification tightening. Long-term viability over a multi-year horizon favors acquisition targets with demonstrated qualification protocols and existing METI documentation compliance for Japanese market access. Watch for MEE enforcement intensity in China's Hubei and Guizhou provinces as an inflection indicator for captive supply economics versus merchant market depth.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorine Recovery | Phosphate fertilizer complexes capture merchant acid volumes under MEE discharge enforcement. |
| Electronics-Grade Purification Investment | Multi-stage distillation systems unlock sub-ppm qualification with South Korean semiconductor fabs. |
| Long-Term Supply Agreement | Concentrate contracts with Western Australian utilities mitigate freight cost volatility exposure. |
| BIS Certification Pathway | Approved supplier status creates import channel premiums in India's municipal water sector. |
| Joint Venture with Logistics Provider | Corrosion-resistant storage infrastructure overcomes distribution barriers in Southeast Asian utilities. |
Research Methodology
Independent corroboration across plant managers at phosphate fertilizer complexes, procurement leads at municipal water utilities, and technical R&D directors at semiconductor fabs underwrites the qualitative findings. Primary interviews with distribution channel partners and regulatory affairs specialists at fluorochemical producers combined with secondary validation from customs/trade data, MEE discharge compliance records, BIS certification registries, and SEC 10-K filings of listed chemical producers. Bottom-up acid production estimates triangulated against top-down fluoridation program expansion projections.
Rate-of-change decomposition across grade tier, end-use industry, and regional production hub dimensions structures the analytical framework. CAGRs derive from segment-level volume trajectories weighted by purity-premium realization patterns. Modeling incorporates phosphate fertilizer production cycle correlation, fluorine recovery technology diffusion curves, and electronics-grade qualification timeline assumptions across the analysis window.
Revisions become necessary when MEE enforcement intensity shifts, semiconductor fab qualification protocols tighten beyond current sub-ppm thresholds, or phosphate rock supply disruptions alter captive acid economics. Forecasts reflect documented assumptions regarding technology convergence timelines and regulatory implementation schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Acetic Anhydride Market
Chemicals
Etching Chemicals Market
Chemicals
Zinc Chemicals Market
Chemicals
Global Amines Market
Chemicals
Triethylenediamine Market
Chemicals
US Methanol Market
Chemicals
Chemical Distribution Market
Chemicals
Potassium Permanganate Market
Chemicals
Allyl Chloride Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Fluorine Derivatives Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Menadione Market