
 Global Engineered Fluids Market | 2026-2036
Global Engineered Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Engineered Fluids Market Foresight
The EU F-Gas Regulation is recalibrating procurement criteria across European electronics cooling and aerospace equipment supply chains. Daikin Industries leverages its fluoropolymer synthesis expertise to sustain positions in next-generation dielectric fluid formulations. Solvay anchors European supply through backward integration into specialty fluorochemical precursors. 3M Company navigates the transition by specializing in PFAS-free alternatives for semiconductor thermal management applications.
Engineered fluids are precisely formulated synthetic or semi-synthetic liquids engineered for thermal stability, chemical inertness, and dielectric performance across extreme operating temperatures, typically synthesized from perfluoropolyethers, fluorinated amines, or advanced ester bases. Their primary commercial purpose centers on precision thermal management, lubrication, and insulation in environments where conventional hydrocarbon fluids degrade or conduct electricity. Heat transfer fluids dominate value capture due to irreplaceable roles in semiconductor etching equipment and data center immersion cooling, while bio-based formulations represent the fastest-expanding technology segment as sustainability mandates harden procurement specifications. Specialty fluids concentrate margin pools through customized formulations for aerospace radar systems and medical imaging equipment.
EPA oversight of PFAS discharge under the Clean Water Act, REACH restrictions on perfluorinated substances administered by ECHA, and Japan's METI chemical substance management framework are collectively tightening formulation standards and market access requirements. These regulatory architectures force reformulation investments, elevate compliance costs for legacy product lines, and create structural advantage for producers with advanced synthetic capabilities. Stakeholders must monitor the trajectory of PFAS restriction scope expansions and pre-position supply agreements for qualified next-generation thermal management chemistries before qualification timelines extend beyond procurement planning horizons.
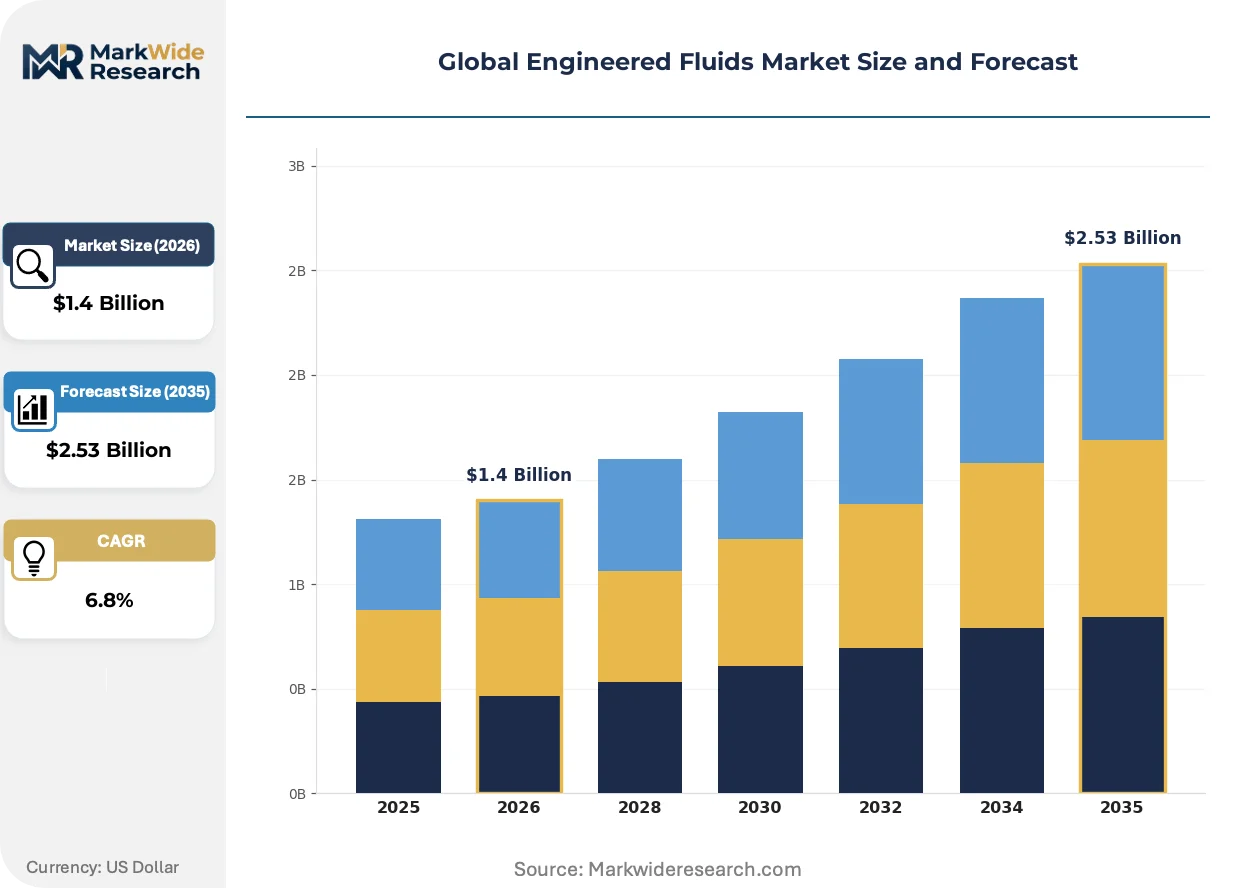
Market Dynamics
The EU F-Gas Regulation is forcing immediate reformulation across European thermal management supply chains while semiconductor fabs in Taiwan and South Korea scale dielectric fluid procurement for sub-3nm node production. This regulatory-demand tension is compressing qualification timelines and concentrating procurement power among synthetic chemistry specialists.
Growth Catalysts
- Advanced node semiconductor manufacturing:Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding dielectric heat transfer fluid volumes for extreme ultraviolet lithography thermal control. Etching equipment manufacturers specify fluoropolyether formulations for plasma chamber temperature stability.
- REACH restrictions on perfluorinated substances:ECHA's evolving candidate list is redirecting European electronics cooling procurement toward hydrofluoroether alternatives. Industrial buyers are pre-qualifying next-generation synthetic chemistries ahead of anticipated substance bans.
- Data center immersion cooling deployment:Hyperscale operators in Singapore and Ireland are piloting single-phase engineered fluids for direct-to-chip thermal management. Rack-density requirements above 50kW per cabinet are rendering air cooling insufficient.
Market Restraints
- Fluorochemical feedstock concentration:China controls 60-70% of global fluorspar mining and hydrofluoric acid refining. Western formulators face supply security risks from export licensing unpredictability and freight cost volatility.
- PFAS contamination liability exposure:EPA enforcement under the Clean Water Act is elevating environmental remediation costs for legacy perfluorocarbon users. Site contamination findings trigger Superfund liability chains affecting equipment manufacturers.
- Reformulation capex intensity:Developing F-Gas-compliant alternatives requires 18-36 month qualification cycles with semiconductor OEMs. Smaller formulators lack balance sheet capacity to sustain dual legacy-next-generation product lines.
Strategic Opportunities
- Bio-based ester formulations:Synthetic biology platforms in California and the Netherlands are yielding heat transfer fluids from engineered lipid precursors. These candidates bypass PFAS regulatory scope while matching dielectric strength specifications.
- Medical imaging equipment thermal management:MRI magnet cryocoolers and CT detector arrays require ultra-pure fluorinated fluids with sub-ppm moisture specifications. Equipment OEMs in Germany and Japan are consolidating supplier bases around qualified specialty fluid houses.
- India's PLI scheme for electronics manufacturing:Semiconductor assembly and test facilities in Gujarat and Karnataka are establishing first-time engineered fluid supply relationships. Domestic formulators are partnering with Taiwanese chemical distributors to capture import substitution incentives.
Industry Challenges
- Fluoropolymer synthesis talent scarcity:Experienced process chemists capable of tuning molecular weight distributions in perfluoropolyether production are concentrated at a handful of Japanese and Belgian producers. University pipeline output in fluorine chemistry has contracted over two decades.
- Multi-jurisdiction compliance complexity:Simultaneous adherence to EPA TSCA Section 5, ECHA REACH registration, and METI chemical substance notification creates documentation burdens. Formulators must maintain separate substance identity dossiers for chemically identical products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Engineered Fluids Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Lubricants, Heat Transfer Fluids, Cutting Fluids, Dielectric Fluids, Specialty Fluids Technology: Water-Based, Oil-Based, Synthetic, Semi-Synthetic, Bio-Based, Nanofluid Application: Metalworking, Power Generation, Aerospace Equipment, Marine Engineering, Electronics Cooling, Mining Operations End User Industry: Manufacturing Plants, Energy Producers, Aircraft Manufacturers, Shipbuilding Facilities, Electronics Assemblers, Mineral Processing |
| Companies Covered | 3M Company, Daikin Industries, The Chemours Company, Solvay, Halocarbon Products Corporation, Halopolymer Kirovo-Chepetsk, AGC Chemicals Americas, F2 Chemicals, Nye Lubricants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Engineered Fluids Market Shifts & Advancements
Reformulation chemistry is absorbing the bulk of R&D investment as F-Gas phase-down deadlines approach and semiconductor thermal budgets tighten. Three parallel developments are compressing product development cycles and reshaping competitive positioning.
Two-phase immersion cooling systems are absorbing capital deployment from hyperscale cloud operators seeking to eliminate mechanical refrigeration. Microsoft and Google data centers in the Netherlands and Singapore have operationalized fluoroketone-based baths for artificial intelligence training clusters. The technology is absorbing market share from traditional chilled water infrastructure by enabling power usage effectiveness ratios below 1.1.
Japan's METI chemical substance management framework is accelerating disclosure requirements for perfluorinated substance imports used in semiconductor manufacturing. The regulation forces importers to submit annual tonnage reports and hazard assessments to prefectural authorities. Electronics chemical distributors are absorbing compliance costs by consolidating supplier panels to pre-qualified domestic formulators with established METI registration histories.
Long-term supply agreements are displacing spot purchasing for high-purity heat transfer fluids as buyers seek price predictability through qualification cycle volatility. Semiconductor foundries in Taiwan are contracting directly with fluoropolyether producers for three-to-five year volumes with indexed pricing. The shift is absorbing working capital from smaller formulators unable to finance inventory positions against extended payment terms.
Global Engineered Fluids Market Segmentation
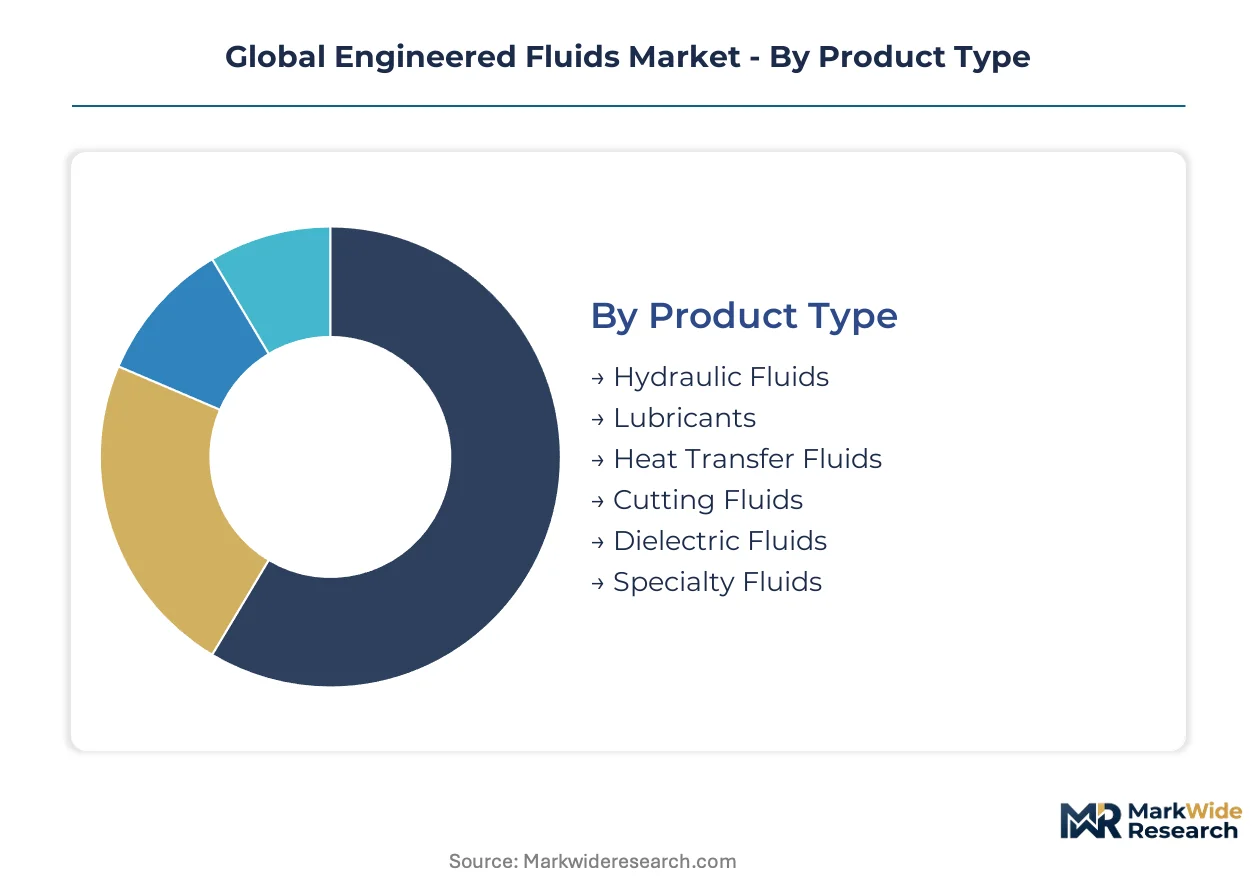
Engineered fluid procurement patterns diverge sharply across product categories, with semiconductor thermal management specifications driving premium formulation requirements while industrial maintenance applications prioritize cost efficiency. Understanding these segment boundaries clarifies where reformulation investments yield highest returns.
Product Type:
Upgrade cycles for thermal management equipment are compressing replacement timelines, forcing end-users to requalify fluid specifications against evolving temperature and purity standards.
- Heat Transfer Fluids:Formulated from perfluoropolyethers or advanced synthetic esters for extreme thermal stability across -90°C to 290°C operating ranges. Taiwan Semiconductor Manufacturing and Samsung Foundry specify these for EUV lithography temperature control, with dielectric strength requirements above 40 kV/mm preventing electrical discharge in high-voltage environments.
- Dielectric Fluids:Electrically insulating formulations with sub-ppm moisture content and high dielectric constants for direct contact with energized components. Data center immersion cooling pilots in Singapore and Ireland are absorbing fluoroketone-based variants for AI training clusters, where rack densities exceed 50kW per cabinet.
- Hydraulic Fluids:Precision lubricants for aerospace actuation systems and industrial machinery.
- Lubricants:Low-friction formulations for vacuum and cleanroom manufacturing environments.
- Cutting Fluids:Metalworking coolants with extreme pressure additives for precision machining.
- Specialty Fluids:Custom formulations for MRI cryocoolers and radar thermal management.
Volume placements concentrate in heat transfer fluids; the faster expansion belongs to dielectric fluids.
Technology:
Cost tiers separate mature hydrocarbon formulations from premium synthetic alternatives, with regulatory compliance costs widening the price spread between legacy and next-generation chemistries.
- Synthetic:Molecularly engineered perfluoropolyethers and hydrofluoroethers with precisely tuned viscosity indices and thermal decomposition thresholds. ECHA REACH restrictions on perfluorinated substances are redirecting European electronics cooling procurement toward lower-GWP hydrofluoroether alternatives, compressing qualification timelines.
- Bio-Based:Heat transfer fluids derived from engineered lipid precursors through synthetic biology platforms in California and the Netherlands. These candidates bypass PFAS regulatory scope while matching dielectric strength specifications for semiconductor thermal management.
- Water-Based:Emulsion formulations for metalworking and general industrial cooling.
- Oil-Based:Mineral and vegetable oil formulations for legacy industrial equipment.
- Semi-Synthetic:Blended formulations balancing performance and cost for mid-tier applications.
- Nanofluid:Colloidal suspensions of nanoparticles for enhanced thermal conductivity.
Procurement volumes cluster in synthetic formulations; bio-based alternatives are climbing the fastest as sustainability mandates harden.
Application:
Application-specific thermal budgets dictate formulation selection, with semiconductor and aerospace specifications commanding 10-20x price premiums over general industrial grades.
- Electronics Cooling:Single-phase and two-phase immersion systems for data centers and semiconductor fabrication. Hyperscale operators in Singapore and Ireland are piloting engineered fluid baths for direct-to-chip thermal management, targeting power usage effectiveness ratios below 1.1.
- Aerospace Equipment:Radar thermal management and avionics cooling with military-grade purity specifications. Equipment OEMs in Germany and Japan are consolidating supplier bases around qualified specialty fluid houses with established METI registration histories.
- Metalworking:Precision machining coolants for automotive and aerospace component production.
- Power Generation:Transformer and reactor cooling fluids for grid infrastructure.
- Marine Engineering:Corrosion-resistant formulations for offshore equipment thermal management.
- Mining Operations:Heavy-duty hydraulic and gear lubricants for extraction equipment.
Electronics cooling dominates value capture; aerospace equipment applications show the steepest expansion trajectory.
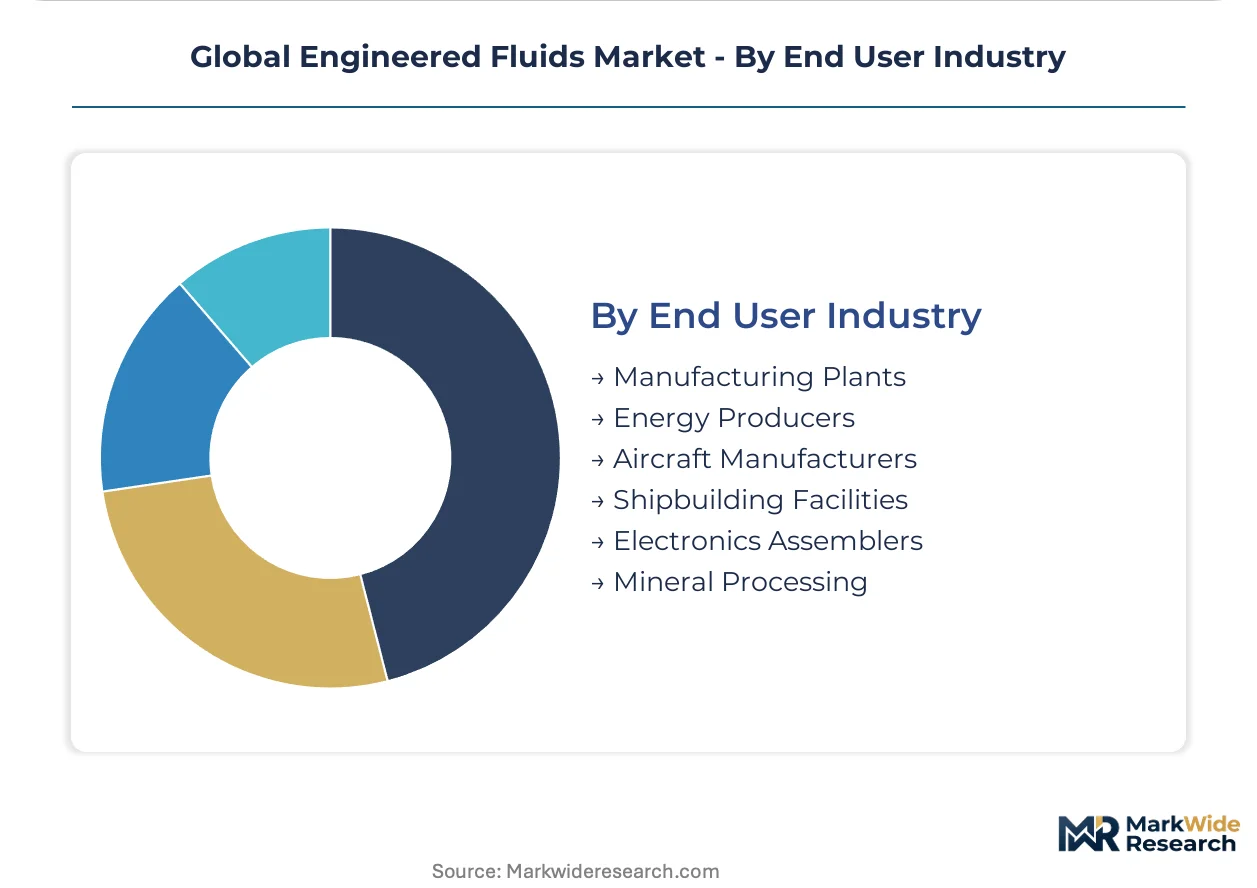
End User Industry:
Customer concentration varies by vertical, with semiconductor foundries consolidating procurement around qualified suppliers while fragmented manufacturing bases sustain multiple competing formulators.
- Electronics Assemblers:Semiconductor fabrication facilities and contract manufacturers with zero-defect purity requirements. Foundries in Taiwan are contracting directly with fluoropolyether producers for three-to-five year volumes with indexed pricing, displacing spot purchasing.
- Aircraft Manufacturers:OEMs and tier-one suppliers specifying MIL-PRF or equivalent certified fluids. Long-term supply agreements are absorbing working capital from smaller formulators unable to finance inventory positions against extended payment terms.
- Manufacturing Plants:General industrial users with standardized maintenance fluid specifications.
- Energy Producers:Utilities and independent power producers for transformer and turbine cooling.
- Shipbuilding Facilities:Naval and commercial vessel constructors with marine-grade corrosion requirements.
- Mineral Processing:Extraction and refining operations with extreme pressure lubrication needs.
Electronics assemblers anchor procurement volumes; aircraft manufacturers are gaining share fastest in premium formulation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors global engineered fluid procurement volumes through Taiwan Semiconductor Manufacturing's advanced node expansion. The concentration of EUV lithography equipment in this corridor generates concentrated demand for dielectric heat transfer fluids with sub-ppb purity specifications.
United States
Hyperscale data center operators in Northern Virginia and Phoenix are piloting two-phase immersion cooling systems for AI training clusters. EPA enforcement under the Clean Water Act is elevating PFAS contamination liability exposure for legacy perfluorocarbon users. Microsoft and Google facilities in the Netherlands and Singapore have operationalized fluoroketone-based baths, though domestic qualification cycles lag by 12-18 months.
China
Domestic fluorspar mining and hydrofluoric acid refining concentration supplies 60-70% of global feedstock for fluoropolyether synthesis. The Ministry of Ecology and Environment is tightening discharge permits for perfluorinated substance manufacturing. Semiconductor fabrication investments in the Yangtze River Delta are absorbing imported dielectric fluids while local formulators develop qualification relationships.
Germany
ECHA REACH restrictions on perfluorinated substances are redirecting electronics cooling procurement toward hydrofluoroether alternatives. The EU F-Gas Regulation is compressing reformulation timelines for industrial thermal management applications. Equipment OEMs in Bavaria are consolidating supplier bases around qualified specialty fluid houses with established substance registration histories.
Japan
METI chemical substance management framework is accelerating disclosure requirements for perfluorinated substance imports used in semiconductor manufacturing. Electronics chemical distributors are absorbing compliance costs by consolidating supplier panels to pre-qualified domestic formulators. Kyushu-based foundries are contracting directly with fluoropolyether producers for multi-year volumes with indexed pricing.
South Korea
Samsung Foundry and SK Hynix are scaling dielectric fluid procurement for sub-3nm node production at Pyeongtaek and Icheon complexes. The Ministry of Trade, Industry and Energy is monitoring chemical substance supply security for strategic industries. Domestic formulators are partnering with Japanese fluoropolymer specialists to secure precursor supply agreements.
Global Engineered Fluids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and qualification depth. The vendor base stratifies into synthetic chemistry specialists with backward integration into fluorochemical precursors, regional formulators serving industrial maintenance applications, and emerging bio-based alternatives developers. Three archetypes dominate: integrated fluoropolymer producers, specialty fluid houses with semiconductor OEM relationships, and synthetic biology platforms engineering lipid-derived heat transfer candidates. Competitive dynamics center on qualification cycle acceleration and long-term supply agreement capture.
Among integrated fluoropolymer producers, 3M Company, Daikin Industries, and Solvay occupy positions spanning dielectric fluid formulation and precursor supply. These entities exemplify the premium-tier archetype through captive fluorochemical synthesis capabilities and established semiconductor foundry relationships. Daikin Industries represents Japanese fluoropolymer expertise concentration, while Solvay anchors European supply architecture. 3M Company sits within the transition-focused tier, navigating PFAS regulatory scope through alternative chemistry development. Smaller specialists including Halocarbon Products Corporation and F2 Chemicals represent the qualified-niche archetype, serving medical imaging and aerospace applications with customized ultra-pure formulations.
| Leading Market Players |
|---|
| 3M Company |
| Daikin Industries |
| The Chemours Company |
| Solvay |
| Halocarbon Products Corporation |
| Halopolymer Kirovo-Chepetsk |
| AGC Chemicals Americas |
| F2 Chemicals |
| Nye Lubricants |
| Others |
Supply & Pricing Matrix
Semiconductor foundry consolidation around three-to-five year indexed contracts is forcing formulators to absorb working capital costs and restructure pricing around volume-commitment tiers rather than spot-market premiums. This procurement shift elevates balance-sheet barriers for smaller competitors while rewarding integrated producers with captive precursor supply.
Pricing Analysis
Yield-guarantee pricing anchors value capture in semiconductor thermal management, where fluid purity directly correlates with EUV lithography uptime. Pricing stratifies across premium, standard, and economy tiers based on dielectric strength certification and moisture-content specifications. Cost compression in standard-grade hydrofluoroethers is intensifying because REACH-compliant reformulation investments are amortizing across thinner volume bases. Electronics assemblers exhibit lowest price sensitivity due to zero-defect requirements, while general industrial buyers prioritize per-liter cost over performance specifications.
Supply Chain Analysis
Fluoropolymer synthesis talent scarcity in Japan and Belgium is constraining capacity expansion for perfluoropolyether producers despite foundry demand acceleration. Feedstock supply draws from Chinese fluorspar mining, German hydrofluoric acid refining, and Belgian fluorochemical precursor synthesis. Single-source vulnerability runs through concentrated hydrofluoric acid refining capacity subject to export licensing unpredictability. Distribution runs through qualified chemical distributors with established semiconductor OEM relationships and METI registration histories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a cost-of-compliance moat, elevating capital requirements for reformulation investments that filter out undercapitalized competitors and consolidate margin pools among qualified synthetic chemistry specialists.
For Market Incumbents: Anchor qualification cycle acceleration through direct semiconductor foundry partnerships, locking in three-to-five year indexed contracts before bio-based alternatives achieve dielectric strength parity. Prioritize backward integration into specialty fluorochemical precursors to offset Chinese hydrofluoric acid supply security risks. Defend against synthetic biology platforms by accelerating PFAS-free formulation timelines and pre-empting ECHA substance bans. For New Entrants and Emerging Players: Enter via India's PLI scheme for electronics manufacturing, where semiconductor assembly and test facilities in Gujarat and Karnataka are establishing first-time engineered fluid supply relationships without incumbent qualification entrenchment. Target medical imaging equipment thermal management, where MRI cryocooler specifications demand ultra-pure formulations that command 10-20x industrial-grade premiums. Pursue joint development agreements with German equipment OEMs consolidating supplier bases around qualified specialty fluid houses. For Investors and Strategic Acquirers: The window for entry favors synthetic biology platforms with engineered lipid-derived heat transfer candidates that bypass PFAS regulatory scope while matching dielectric specifications. Long-term viability centers on qualification depth with semiconductor foundries and METI registration histories that cannot be replicated through capital deployment alone. Monitor ECHA candidate list expansions as the inflection signal for accelerated procurement shifts toward hydrofluoroether alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorochemical Precursors | Solvay and Daikin Industries secure supply security against Chinese export licensing volatility. |
| Long-term Supply Agreement with Foundries | Taiwan Semiconductor Manufacturing contracts directly with fluoropolyether producers for indexed volume commitments. |
| PFAS-Free Formulation Development | 3M Company navigates EPA enforcement and ECHA restrictions through alternative chemistry platforms. |
| Joint Venture with Synthetic Biology Platforms | California and Netherlands bio-based developers bypass regulatory scope while matching dielectric strength. |
| Capacity Expansion in India | Domestic formulators capture PLI scheme incentives through partnerships with Taiwanese chemical distributors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fluoropolymer synthesis directors, semiconductor foundry procurement leads, specialty chemical distributors, and ECHA regulatory affairs specialists. SEC 10-K disclosures, Cefic sector reports, and METI chemical substance notification databases provided validation layers. Bottom-up volume estimates triangulated against top-down market sizing across synthetic, bio-based, and semi-synthetic technology tiers.
Segment-level granularity modeled product type, technology platform, application thermal budget, and end-user industry concentration across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns and regulatory phase-down timelines. Forecast inputs incorporated EU F-Gas Regulation compliance deadlines, semiconductor node transition schedules, and data center rack-density thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated PFAS restriction scope expansions or Chinese fluorspar export licensing disruptions. Forecasts reflect documented assumptions regarding qualification cycle durations and reformulation investment trajectories. Material deviation in ECHA candidate list timing or EPA enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
China Automotive Engine Oils Market
Lubricants
Vietnam Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Global Grease Cartridges Market
Lubricants
Angola Lubricants Market
Lubricants
ASEAN Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Global Grease Market
Lubricants
United Kingdom Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market