
 Firearm Lubricants Market | 2026-2036
Firearm Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Firearm Lubricants Market Analysis
Synthetic base-stock chemistry is rewriting how firearm lubricants withstand thermal breakdown during rapid-fire cycles. Lucas Oil Products leverages its racing-oil R&D pipeline to transfer extreme-pressure additive knowledge into gun-care formulations. WD-40 Company competes through mass-market channel density, while Ballistol sustains a century-old brand anchored in plant-derived formulations favored by European competitive shooters.
Firearm lubricants are specialty functional fluids engineered to reduce friction between moving metal parts, typically operating across temperature ranges from sub-zero to over 400°F while resisting carbon fouling and moisture intrusion. Their primary purpose is to prevent wear-induced malfunctions in precision mechanical assemblies subject to high cyclic stress. Synthetic formulations command premium positioning due to extended service intervals and broader temperature stability, while biodegradable variants attract institutional buyers facing environmental compliance mandates. Grease products dominate precision bolt-action maintenance, whereas spray packaging captures rapid field-application demand from law enforcement and military end users.
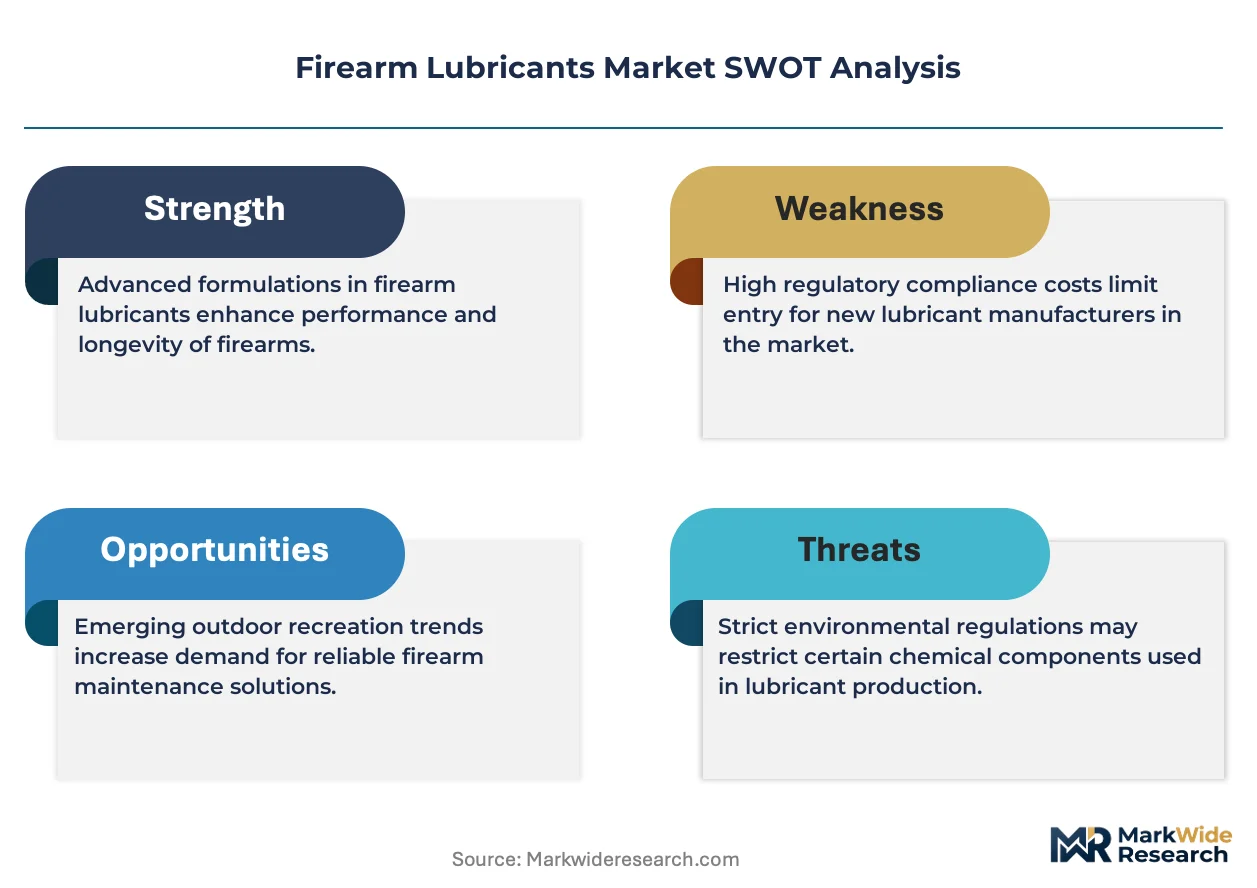
The EPA regulates volatile organic compound content in aerosol firearm lubricants, compelling reformulation of traditional mineral-oil sprays. OSHA workplace exposure limits influence packaging design and labeling for commercial armorer operations. Forward-looking stakeholders must monitor how state-level lead-abatement rules and federal procurement sustainability clauses reshape specification requirements for institutional buyers.
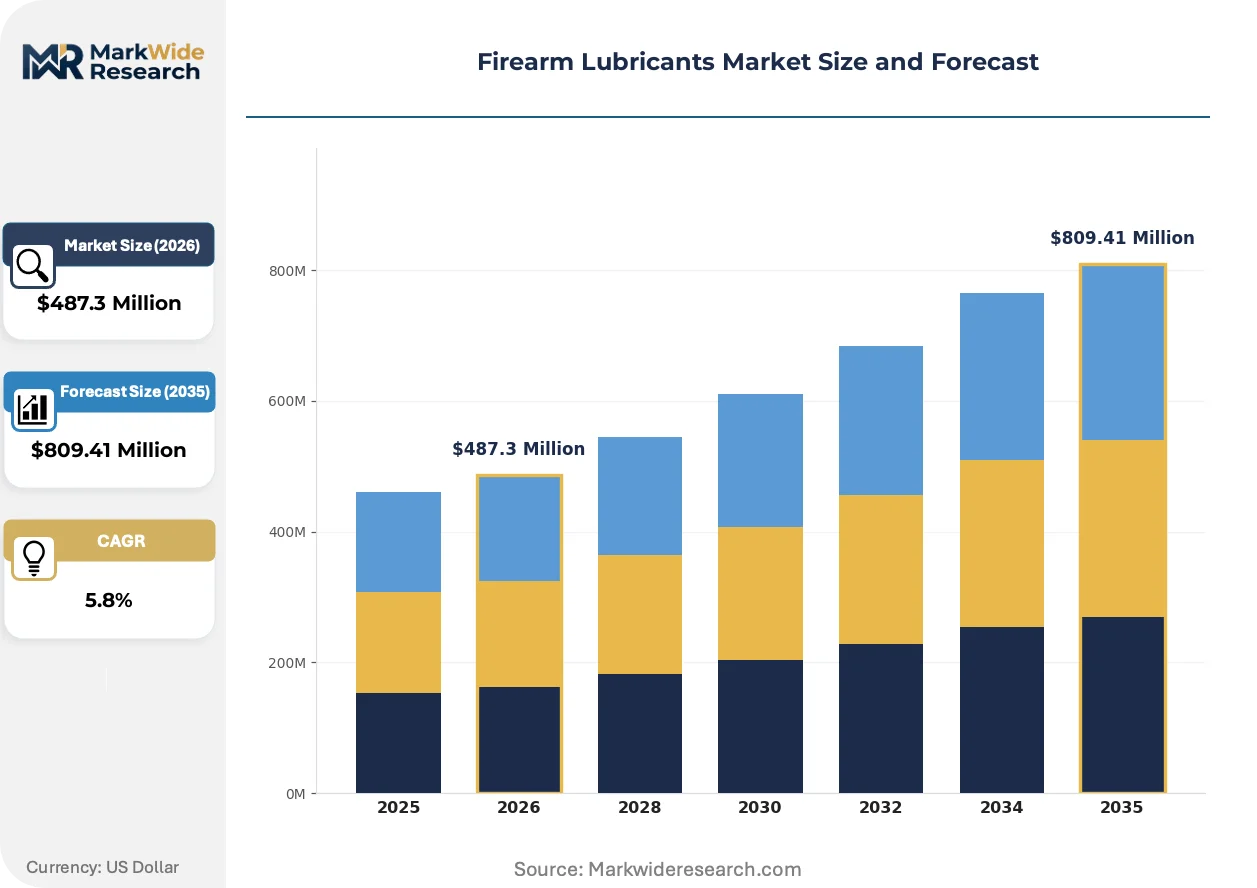
Market Dynamics
Synthetic base-stock chemistry and EPA VOC emission mandates are forcing simultaneous reformulation across aerosol and liquid product lines, compressing development cycles while opening premium positioning for biodegradable alternatives.
Growth Catalysts
- REACH compliance deadlines:European competitive shooters are migrating toward plant-derived formulations ahead of 2025 registration requirements, expanding addressable demand for biodegradable SKUs.
- High-volume training infrastructure:American Southwest competitive shooting clubs and law enforcement academies are consolidating lubricant procurement through multi-year supply agreements.
- Synthetic ester technology:Extended service intervals from polyol ester base stocks are displacing mineral-oil maintenance schedules in precision bolt-action applications.
Market Restraints
- Base oil supply concentration:Polyalphaolefin and ester feedstock production clusters in the US Gulf Coast and northwestern Europe create geographic vulnerability to hurricane and refinery outage disruptions.
- Technical performance ceiling:Biodegradable formulations face shear-stability limitations above 350°F in sustained rapid-fire conditions, constraining military and tactical adoption.
- OSHA workplace exposure thresholds:Aerosol packaging reformulation costs for commercial armorer operations compress margin structures on mass-market spray products.
Strategic Opportunities
- Brazilian civilian shooting expansion:Club-level competitive pistol disciplines in São Paulo and Rio de Janeiro states are creating first-mover advantage for spray-format field application products.
- EU Green Deal procurement clauses:Institutional buyers across German federal police and defense procurement are mandating biodegradable lubricant specifications in tender documents.
- Direct-to-consumer subscription models:Competitive shooters in Texas and Arizona are adopting automated replenishment for high-consumption cleaning and lubrication kits.
Industry Challenges
- Tribochemistry expertise scarcity:Formulation chemists with simultaneous firearms mechanism knowledge and extreme-pressure additive experience command premium compensation, constraining R&D scaling.
- Multi-jurisdiction labeling complexity:California Proposition 65 warnings, EPA VOC disclosures, and EU CLP hazard classifications require parallel packaging runs, inflating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firearm Lubricants Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grease, Oil, Gel, Spray Application: Handguns, Rifles, Shotguns, Airsoft Formulation: Mineral Oil, Synthetic, Biodegradable, Teflon Packaging Type: Containers, Tubes, Aerosols, Bulk |
| Companies Covered | Ballistol, WD-40 Company, Lucas Oil Products, Amsoil Inc., FrogLube Products, Clenzoil, Remington, G96 Products Inc., Break-Free (Safariland Group), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firearm Lubricants Market Emerging Trajectories
Formulation science is converging with digital supply chain tools and sustainability mandates to compress product development timelines while fragmenting traditional channel structures.
Smart packaging with embedded RFID temperature loggers is digitizing cold-chain integrity verification for synthetic lubricants shipped to desert training facilities. Law enforcement procurement offices in Nevada and Arizona are piloting these tracked shipments to validate thermal exposure during transit. The data stream is digitizing supplier quality audits, compressing the window for dispute resolution and warranty claims.
EPA's evolving volatile organic compound standards for consumer products are forcing aerosol manufacturers toward compressed air propellant systems and bag-on-valve packaging architectures. The industrial consequence is capital-intensive retooling of filling lines and reformulation of viscosity modifiers to maintain spray performance without hydrocarbon propellants. Aerosol-format firearm lubricants sold through mass retail channels in the United States face the steepest compliance timeline, with several suppliers accelerating biodegradable liquid alternatives to bypass aerosol classification entirely.
Competitive shooters are consolidating purchasing through specialty e-commerce platforms that bundle lubricants with match-grade ammunition and cleaning tools. Traditional brick-and-mortar sporting goods distributors in the American Southwest are losing share to these curated subscription boxes that guarantee lot consistency for precision rifle competitors. This behavioral shift is most pronounced among PRS (Precision Rifle Series) participants in Texas, where annual round counts exceed 10,000 and lubricant consumption tracks ammunition volume linearly.
Firearm Lubricants Market Segmentation
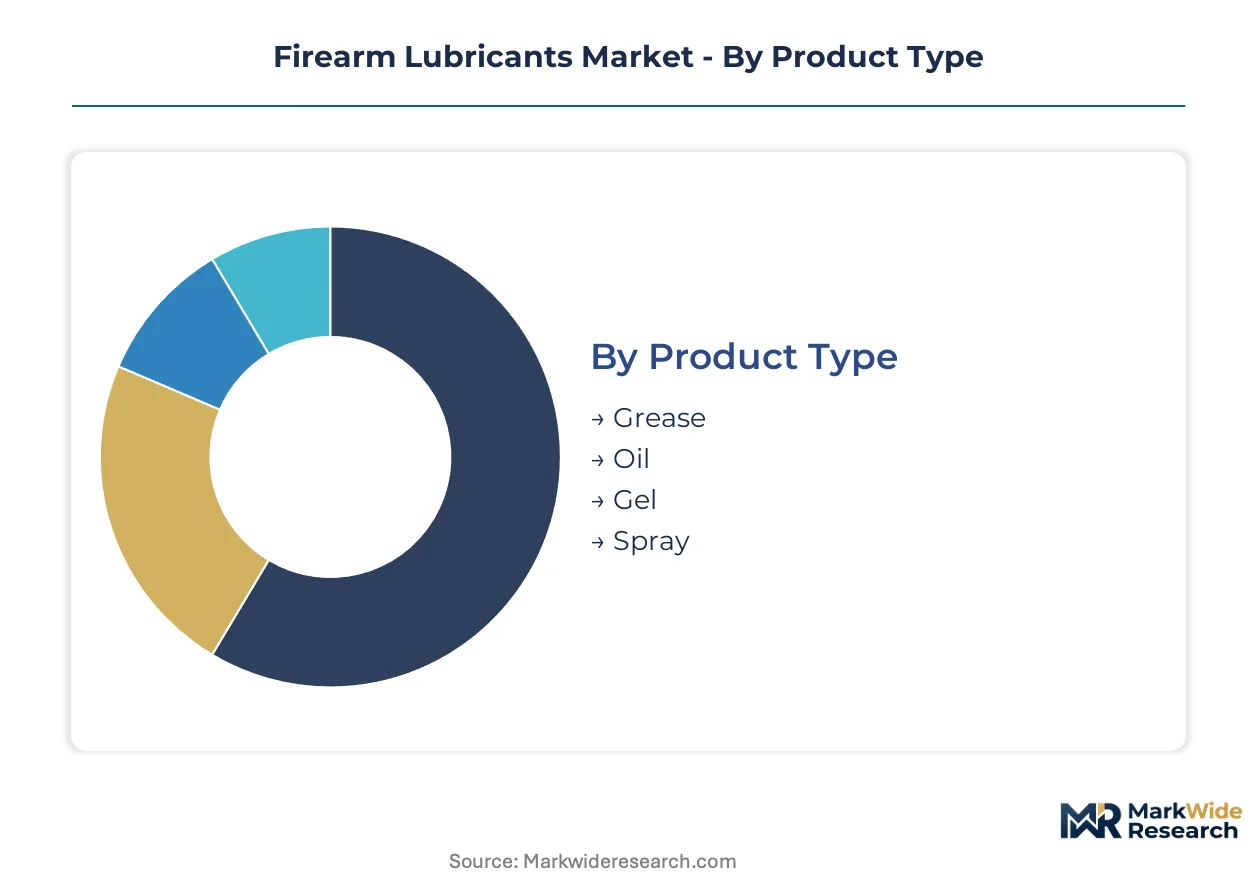
Firearm lubricant purchasing patterns diverge sharply between precision competitive shooters demanding laboratory-grade consistency and high-volume training facilities optimizing per-round maintenance economics. Segmentation reveals how formulation chemistry, application method, and packaging format each command distinct margin structures and renewal cadences across civilian, law enforcement, and institutional end uses.
Product Type:
After-sales-service intensity varies dramatically by product viscosity, with grease applications requiring detailed armorer training and spray formats demanding minimal technical support but higher replenishment frequency.
- Grease:High-viscosity lithium-complex or calcium-sulfonate thickeners suspend extreme-pressure additives for bolt-lug engagement surfaces and sear mechanisms. Precision rifle competitors in Texas and Arizona specify NLGI Grade 2 greases for 1,000-yard consistency, where friction coefficient stability directly impacts shot-to-shot repeatability.
- Oil:Low-viscosity synthetic ester or polyalphaolefin base stocks penetrate tight clearances in semi-automatic actions. German competitive pistol shooters favor drip-bottle dispensing for controlled application volume, reflecting European preference for precision over speed in maintenance routines.
- Gel:Thixotropic silicone or polymer-thickened formulations cling to vertical surfaces without migration. Brazilian shooting clubs in São Paulo state are adopting gel formats for humid climate storage protection.
- Spray:Aerosol or compressed-air propellant systems deliver atomized lubricant to inaccessible trigger group components. Law enforcement armorer operations in Nevada and Arizona specify spray formats for sub-60-second field application protocols.
Grease holds the largest share; momentum sits with spray formats as high-volume training infrastructure expands.
Application:
Cost tier differentiation separates match-grade precision maintenance from volume-driven consumable economics across firearm categories.
- Handguns:Compact slide-to-frame interfaces and sear mechanisms demand lubricants with boundary friction modification for rapid cycling. Brazilian competitive pistol disciplines in Rio de Janeiro state are driving biodegradable formulation trials ahead of ANVISA environmental registration requirements.
- Rifles:Bolt-action precision applications require thermal stability across 40°F to 400°F operational windows. Polyol ester synthetics are displacing mineral-oil schedules in PRS competitor maintenance kits.
- Shotguns:High-recoil pump and semi-automatic actions subject lubricant films to mechanical shear rates exceeding 10,000 per second. Clay target facilities in Arizona specify extended-service synthetic formulations for 50,000-round annual consumption patterns.
- Airsoft:Polymer-compatible lubricants with dielectric properties protect electric trigger contacts and gas blowback seals. European recreational shooting centers are standardizing plant-derived formulations for indoor range air quality compliance.
Rifles command premium pricing tiers; handguns represent the steepest expansion trajectory as Brazilian civilian participation accelerates.
Formulation:
Customer type stratification separates institutional buyers facing procurement sustainability mandates from individual enthusiasts prioritizing performance metrics.
- Mineral Oil:Refined petroleum distillates with sulfur-phosphorus extreme-pressure additive packages dominate legacy maintenance protocols. Price-sensitive bulk procurement at Southwest US law enforcement academies sustains residual demand despite synthetic displacement.
- Synthetic:Engineered polyalphaolefin, ester, or alkylated naphthalene base stocks deliver oxidative stability and low-temperature fluidity. German federal police tender documents now specify synthetic formulations for cold-weather operational reliability.
- Biodegradable:Plant-derived esters and vegetable oil base stocks meet EPA and REACH environmental compliance thresholds. EU Green Deal procurement clauses are mandating biodegradable specifications for institutional buyers across German defense and police supply chains.
- Teflon:Polytetrafluoroethylene solid-film lubricants provide dry-film friction reduction without oil contamination of shooting gloves or bench surfaces. Competitive precision rifle shooters favor Teflon-impregnated formulations for clean-handling maintenance between stages.
Synthetic formulations hold the largest share; biodegradable alternatives are climbing the fastest as regulatory deadlines approach.
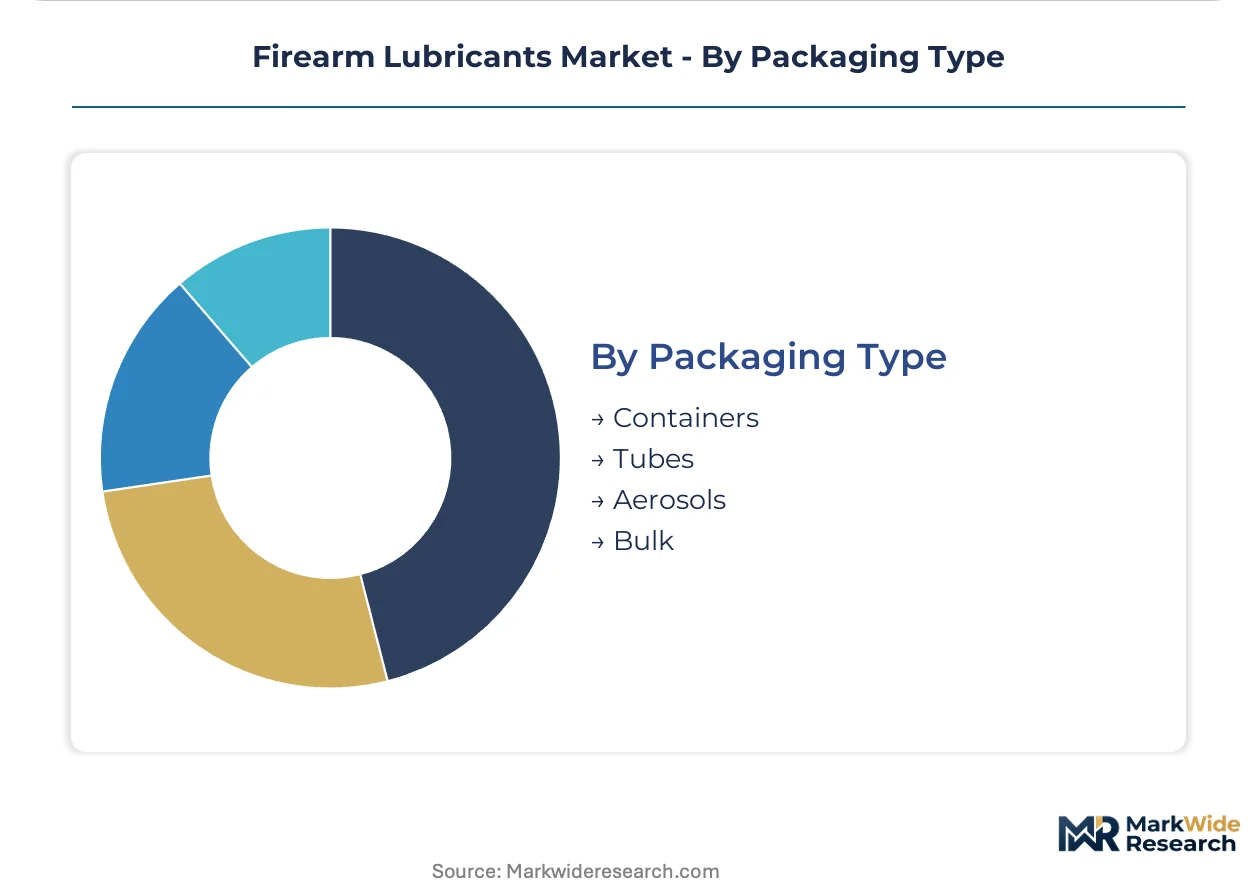
Packaging Type:
Supply concentration in aerosol propellant systems and bulk chemical handling infrastructure shapes regional availability and procurement channel selection.
- Containers:HDPE or glass bottles with precision dispensing caps serve benchrest maintenance routines. German competitive shooters prefer graduated 50ml containers for travel-kit portability.
- Tubes:Collapsible aluminum or laminate squeeze tubes deliver grease to specific friction points without waste. Precision bolt-action maintenance in Texas PRS competitions favors tube formats for controlled grease bead placement.
- Aerosols:Hydrocarbon or compressed-air propellant systems with bag-on-valve architectures face EPA VOC compliance retooling. Mass-market sporting goods channels in the United States are accelerating liquid alternatives to bypass aerosol classification complexity.
- Bulk:55-gallon drums or intermediate bulk containers supply high-volume training facilities with automated dispensing systems. Arizona and Nevada law enforcement academies consolidate procurement through multi-year bulk supply agreements.
Aerosols retain volume leadership; bulk packaging is gaining share fastest as institutional procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German synthetic lubricant exports supply American Southwest training facilities and Brazilian competitive shooting clubs, establishing a transatlantic trade corridor anchored by REACH-compliant formulation expertise.
United States
High-volume training infrastructure in Arizona and Nevada drives bulk procurement consolidation through multi-year supply agreements. EPA VOC emission standards for aerosol consumer products compel manufacturers toward compressed-air propellant systems and bag-on-valve packaging architectures. Texas precision rifle competitors in the PRS circuit consume lubricants linearly with ammunition volumes exceeding 10,000 rounds annually.
Germany
Federal police and defense procurement offices mandate biodegradable lubricant specifications in tender documents ahead of EU Green Deal implementation deadlines. ECHA REACH registration requirements accelerate plant-derived formulation adoption among competitive pistol shooters. Bavarian shooting sports clubs anchor European demand for laboratory-grade consistency in precision maintenance protocols.
Brazil
Civilian competitive pistol disciplines expand across São Paulo and Rio de Janeiro states, creating first-mover opportunity for spray-format field application products. ANVISA environmental registration requirements prompt biodegradable formulation trials ahead of regulatory deadlines. Club-level infrastructure investments concentrate procurement volume in southeastern metropolitan corridors.
United Kingdom
Precision rifle competitors prioritize synthetic ester formulations for thermal stability across variable climate conditions. HSE workplace exposure regulations influence commercial armorer operation packaging and labeling requirements. Scottish and English shooting grounds consolidate lubricant purchasing through specialty e-commerce platforms bundling match-grade maintenance kits.
Canada
Law enforcement and civilian competitive shooters demand low-temperature fluidity from synthetic base stocks for operational reliability across prairie and northern climate zones. Health Canada and PMRA regulate chemical product classifications affecting import and distribution channel structures. Ontario and Alberta shooting sports facilities drive regional procurement concentration through institutional supply agreements.
Firearm Lubricants Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market sporting goods distribution networks face erosion from curated subscription platforms and direct-to-consumer replenishment models. Three archetypes dominate: racing-oil technology transfer specialists, century-old plant-derived formulation heritage brands, and mass-market aerosol channel density operators. Competitive moves concentrate on aerosol packaging retooling for EPA compliance and synthetic base-stock R&D pipeline acceleration.
Within the heritage-formulation tier, Ballistol anchors European competitive shooter preference through plant-derived chemistry expertise. WD-40 Company exemplifies mass-market channel density with aerosol distribution ubiquity across North American retail networks. Lucas Oil Products represents racing-oil technology transfer, leveraging extreme-pressure additive knowledge from motorsport R&D into gun-care applications.
| Leading Market Players |
|---|
| Ballistol |
| WD-40 Company |
| Lucas Oil Products |
| Amsoil Inc. |
| FrogLube Products |
| Clenzoil |
| Remington |
| G96 Products Inc. |
| Break-Free (Safariland Group) |
| Others |
Supply Flow & Price Mechanics
The US Gulf Coast polyalphaolefin cluster anchors base-stock availability for synthetic firearm lubricant manufacturers, with hurricane-season outage risk translating directly into quarterly pricing volatility for downstream formulators serving Arizona and Nevada training facilities.
Pricing Analysis
Cost-plus contracts with polyalphaolefin feedstock indexation dominate procurement between base-oil suppliers and lubricant formulators. Three-tier pricing structure across premium synthetic, standard mineral-oil, and economy biodegradable levels separates laboratory-grade consistency from bulk training-facility supply. Pricing pressure stems from EPA-mandated aerosol reformulation capital requirements compressing margin structures on mass-market spray products. High-volume institutional buyers in the American Southwest exhibit lowest price sensitivity, while individual competitive shooters in Brazil demonstrate highest elasticity.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Lubrizol and Infineum holding specialized ester-blending assets for extreme-pressure additive incorporation. Base-oil production draws from the US Gulf Coast, northwestern Europe, and South Korean synthetic facilities. Polyalphaolefin and ester feedstock dependencies create vulnerability to refinery outage disruptions. Distribution runs through mass-market sporting goods retail, specialty e-commerce subscription platforms, and direct institutional procurement channels serving law enforcement academies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across formulation chemistry, packaging format, and geographic compliance creates niche entry points for specialists. The shift from brick-and-mortar sporting goods to curated e-commerce subscription platforms fragments channel control and opens white-space for direct-to-consumer positioning.
For Market Incumbents: Insulate aerosol revenue streams through accelerated bag-on-valve packaging retooling ahead of EPA compliance deadlines. Secure backward integration into synthetic ester base-stock supply through captive offtake agreements with US Gulf Coast producers. Channel erosion from specialty e-commerce platforms bundling lubricants with match-grade ammunition represents the primary threat to mass-market positioning. For New Entrants and Emerging Players: Establish a beachhead in Brazilian competitive pistol clubs ahead of ANVISA biodegradable registration requirements. Target German federal police procurement tenders specifying EU Green Deal-compliant formulations as the most penetrable institutional segment. Direct-to-consumer subscription models with automated replenishment for high-consumption competitive shooters offer the clearest go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors synthetic base-stock specialists with racing-oil R&D transfer capabilities over mineral-oil heritage brands facing reformulation headwinds. Long-term viability rests on formulation chemistry IP and regulatory compliance infrastructure rather than channel density. Watch biodegradable specification mandates in EU and Brazilian tender documents as the signal indicating acceleration timing for plant-derived formulation acquisitions.| Strategic Initiative | Industry Significance |
|---|---|
| Aerosol Packaging Retooling | EPA VOC compliance deadlines force capital-intensive bag-on-valve architecture adoption. |
| Synthetic Ester R&D Pipeline | Extended service intervals from polyol ester technology displace mineral-oil maintenance schedules. |
| Biodegradable Formulation Certification | EU Green Deal procurement clauses mandate plant-derived specifications in German defense tenders. |
| Direct-to-Consumer Subscription Launch | Texas PRS competitors adopt automated replenishment for 10,000-plus annual round counts. |
| Brazilian Market Entry Partnership | São Paulo and Rio de Janeiro club infrastructure investments concentrate southeastern demand. |
Methodological Framework
Initial hypotheses were tested against primary input from lubricant formulators, commercial armorer operations, competitive shooting club procurement officers, and EPA regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with synthetic base-stock procurement leads at formulators and distribution channel partners at specialty e-commerce platforms. Secondary sources included EPA VOC emission standard filings, ECHA REACH registration databases, customs trade data for polyalphaolefin imports, and SEC 10-K disclosures from lubricant manufacturers. Bottom-up demand modeling from end-use segments was triangulated against top-down supply-side capacity assessments.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by grease, oil, gel, and spray formats alongside formulation chemistry tiers and packaging architectures. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators and regulatory compliance timelines. Forecast inputs included high-volume training facility procurement consolidation patterns in Arizona and Nevada, Brazilian civilian shooting sports participation trajectories, and biodegradable specification adoption curves in German institutional tenders.
Sensitivities concentrate around EPA VOC standard enforcement timing, hurricane-season disruption frequency in the US Gulf Coast base-oil cluster, and EU Green Deal procurement clause implementation pace. Forecasts embed assumptions regarding synthetic ester technology adoption rates and e-commerce channel migration velocity among competitive shooters. Quarterly review of ANVISA registration progress, German federal police tender specifications, and Arizona law enforcement academy procurement awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Lubrication Systems Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Argentina Lubricants Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
Yarn Lubricant Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Chile Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
China Automotive Engine Oils Market