
 Histamine H2-Receptor Antagonists Market | 2026-2036
Histamine H2-Receptor Antagonists Market Size, Share, and Industry Trends Forecast 2026-2036
Histamine H2-Receptor Antagonists Market Insights
Proton pump inhibitors are restructuring competitive economics within acid suppression therapy as clinicians substitute away from H2-antagonist first-line protocols. Pfizer Inc. leverages its injectable famotidine franchise to sustain hospital formulary presence. Teva Pharmaceutical Industries Ltd. anchors the generic oral segment with broad pharmacy distribution. Dr. Reddy's Laboratories Ltd. competes on cost-optimized cimetidine production for emerging market tenders.
Histamine H2-receptor antagonists are competitive reversible inhibitors of histamine at the parietal cell H2 receptor, reducing gastric acid secretion through blockade of the cAMP-dependent proton pump pathway; famotidine achieves peak plasma concentration within one to three hours with a bioavailability of 40 to 45 percent, serving primary indications in gastroesophageal reflux disease and peptic ulcer healing. The oral delivery mode dominates prescription volumes across retail pharmacies, while intravenous formulations command premium positioning in acute care settings where rapid acid suppression proves clinically necessary. Application demand clusters in gastroesophageal reflux disease management as the most prevalent indication, with peptic ulcer disease representing a stable maintenance segment and Zollinger-Ellison syndrome occupying a narrow specialty niche.
FDA bioequivalence standards and EMA quality guidelines govern generic substitution pathways, shaping manufacturer investment in therapeutic equivalence studies and formulation stability programs. The US Pharmacopeia and International Council for Harmonisation stability protocols dictate shelf-life claims and storage condition labeling that directly influence distribution logistics and inventory carrying costs. Stakeholders must monitor evolving pharmacovigilance requirements for long-term H2-antagonist safety profiles while calibrating portfolio exposure against biosimilar proton pump inhibitor competition.
Market Dynamics
FDA withdrawal of ranitidine products in 2019 triggered a wholesale formulary restructuring across hospital systems, forcing rapid substitution toward famotidine and cimetidine protocols while proton pump inhibitors captured displaced first-line prescriptions.
Growth Catalysts
- Aging demographics:Expanding geriatric populations in Japan, Germany, and the US sustain chronic acid suppression therapy volumes. Hospital discharge protocols increasingly incorporate H2-antagonists for stress ulcer prophylaxis.
- EMA quality guidelines:Stringent bioequivalence standards for generic substitution create defensible market positions for manufacturers with validated therapeutic equivalence data. This regulatory clarity stabilizes procurement decisions.
- Injectable formulations:Intravenous famotidine commands premium positioning in acute care settings where rapid acid suppression proves clinically necessary, sustaining margin structures despite oral commoditization.
Market Restraints
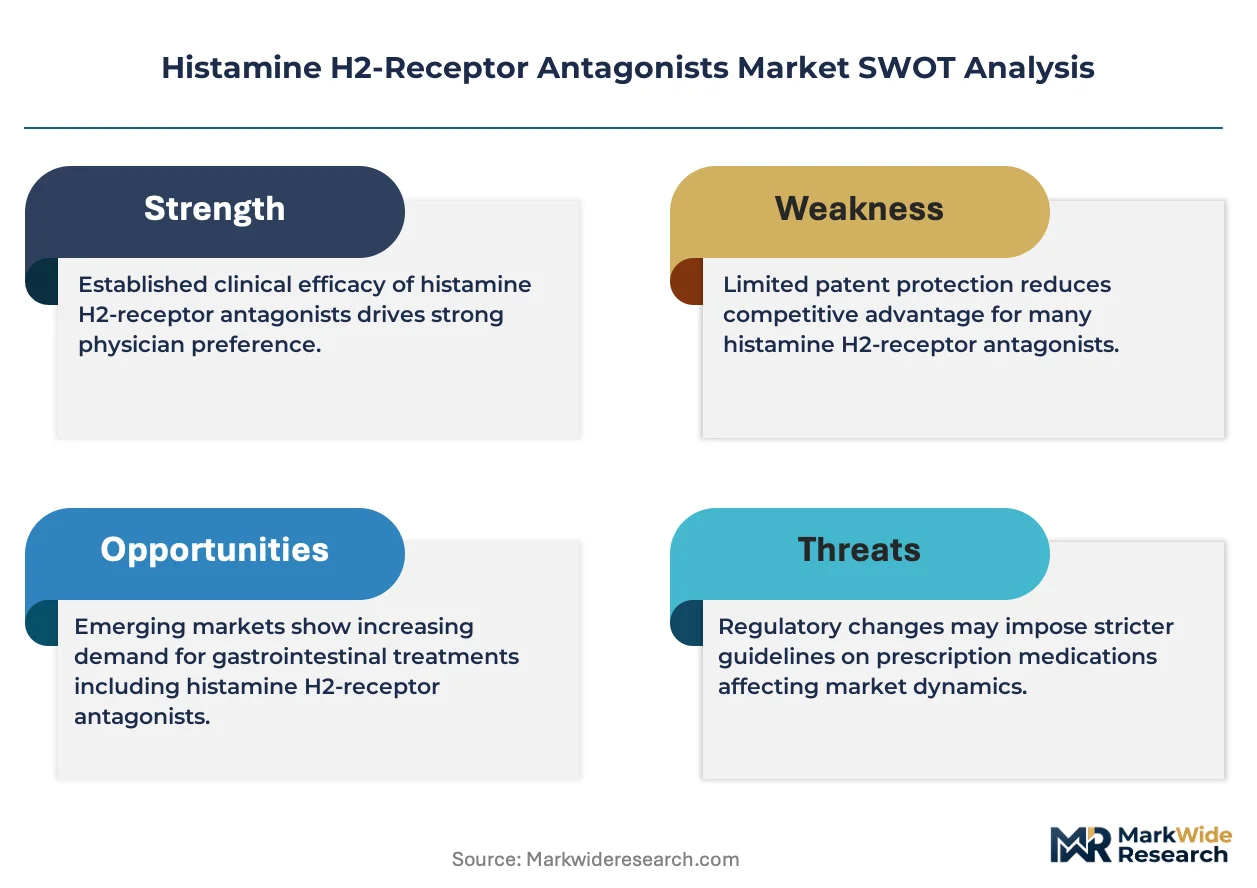
- Proton pump inhibitor substitution:PPIs deliver superior acid suppression efficacy, displacing H2-antagonists from first-line gastroesophageal reflux disease protocols across US and European prescribing guidelines.
- API supply concentration:Active pharmaceutical ingredient production clusters in China and India, exposing formulators to geopolitical friction and customs delays that compress inventory flexibility.
- Reimbursement compression:Medicare and commercial payers apply step-therapy requirements that mandate PPI trial before H2-antagonist coverage, restricting addressable prescription volumes.
Strategic Opportunities
- Pediatric indication expansion:Unmet need exists for weight-optimized famotidine dosing in neonatal intensive care units, where off-label use currently dominates.
- Biosimilar PPI convergence:Patent expirations for esomeprazole and omeprazole biosimilars create pricing pressure that may restore H2-antagonist cost-competitiveness in maintenance therapy segments.
- Direct-to-hospital distribution:Bypassing wholesale distributors through 340B program participation captures margin otherwise lost to pharmacy benefit manager rebates.
Industry Challenges
- Analytical method transfer:Migration from ranitidine to famotidine production lines requires revalidation of dissolution testing and impurity profiling protocols, extending regulatory filing timelines.
- Stability program costs:ICH Q1A(R2) long-term and accelerated stability studies demand 24-36 month commitment before shelf-life claims receive FDA approval, tying up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histamine H2-Receptor Antagonists Market |
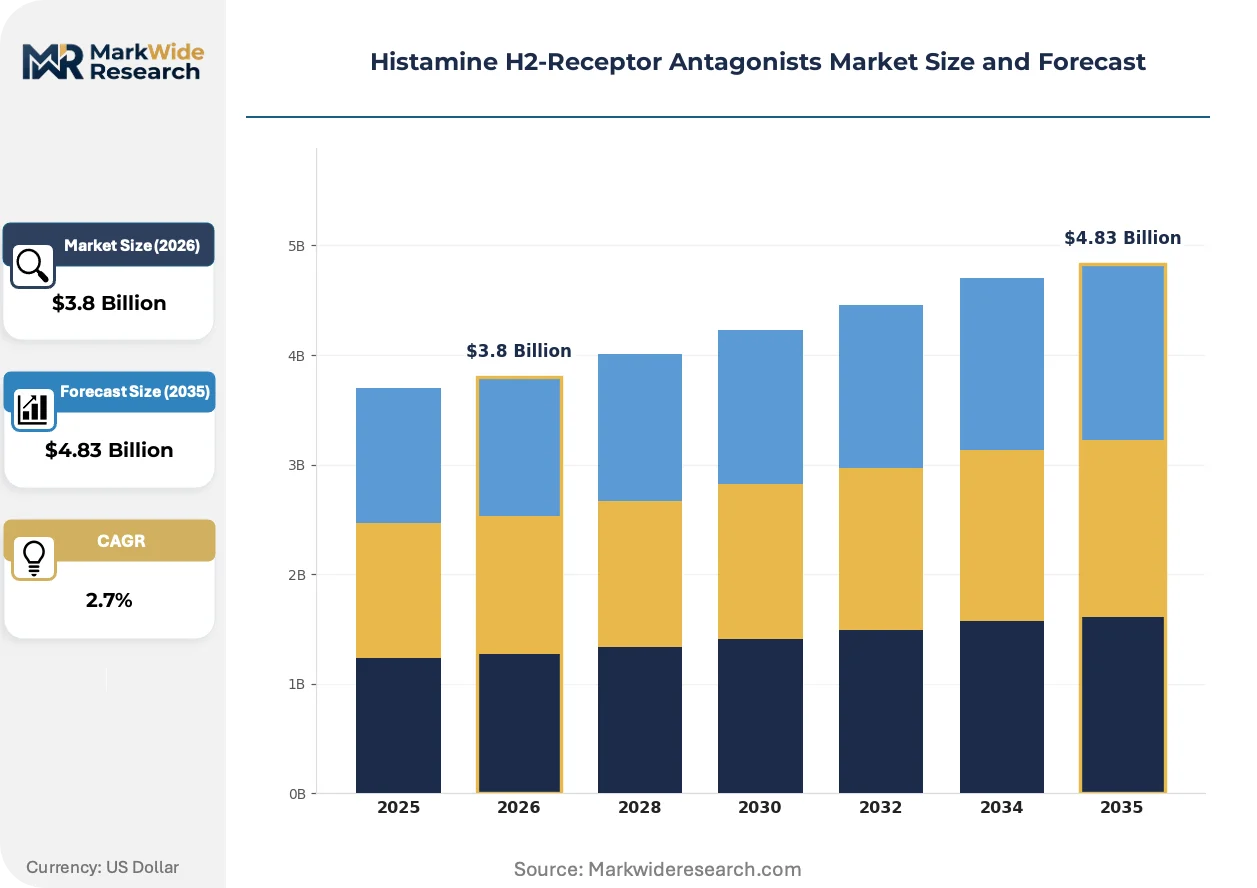
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ranitidine, Famotidine, Nizatidine, Cimetidine Delivery Mode: Oral, Injectable, Rectal, Intravenous End User: Hospitals, Clinics, Home Healthcare, Pharmacies Application: Gastroesophageal Reflux Disease, Peptic Ulcer Disease, Zollinger-Ellison Syndrome, Dyspepsia |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc., AstraZeneca plc, Johnson & Johnson, Boehringer Ingelheim GmbH, Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histamine H2-Receptor Antagonists Market Trends and Innovations
Formulation science and distribution logistics are converging to reshape competitive positioning within acid suppression therapy, with manufacturers prioritizing supply chain resilience and dosage-form differentiation over molecule innovation.
Orally disintegrating tablet technology is absorbing demand from traditional swallowable formulations, particularly among geriatric patients and those with dysphagia complications. Long-term care facilities in Japan and US nursing homes are adopting these dosage forms at accelerating rates. This absorption pattern is compressing standard tablet volumes while creating formulation patent opportunities for first-movers.
REACH authorization requirements for nitrosamine impurity testing have forced European manufacturers to implement enhanced analytical protocols for all histamine antagonist batches. Industrial consequence includes elevated quality control overhead and extended release timelines. Oral solid dosage producers serving EMA-regulated markets are responding by consolidating testing partnerships with specialized contract laboratories.
Hospital procurement departments are consolidating therapeutic category management under centralized pharmacy and therapeutics committees, displacing individual physician prescribing autonomy. Group purchasing organizations are capturing formulary gatekeeper roles previously held by clinical departments. This concentration is most visible in US health systems exceeding 500 beds, where standardized protocols now govern over eighty percent of acid suppression therapy selection.
Histamine H2-Receptor Antagonists Market Segmentation
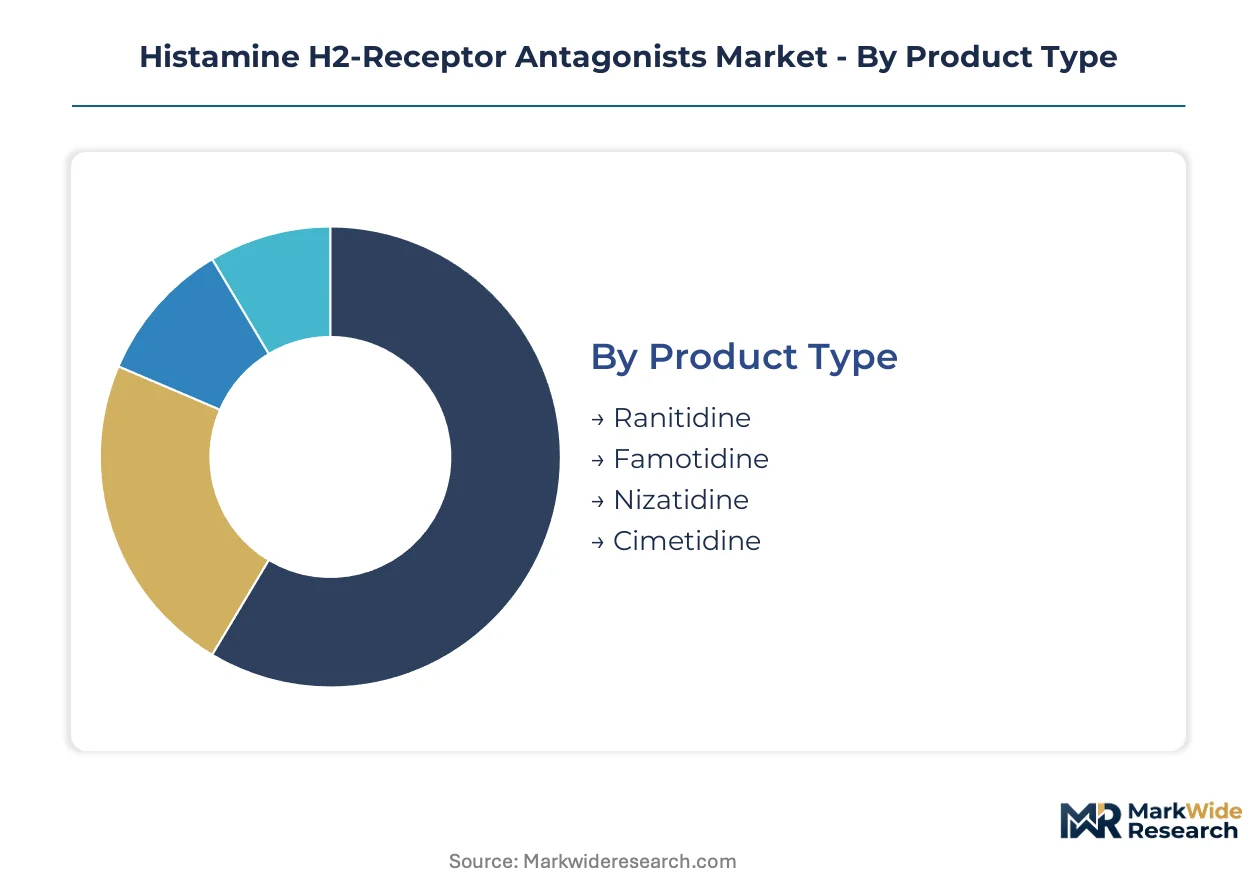
Segmentation in the histamine H2-receptor antagonists market reveals how FDA regulatory actions, clinical protocol hierarchies, and distribution channel economics partition commercial opportunity. Understanding these divides enables manufacturers to align formulation investment with reimbursement pathways and procurement concentration points.
Product Type:
Famotidine commands premium hospital pricing while cimetidine anchors cost-sensitive tender markets; ranitidine's regulatory withdrawal has permanently altered volume distribution across this category.
- Famotidine:A potent, long-acting H2-antagonist with minimal drug interaction liability. Hospital procurement in the US and Japan concentrates demand for injectable famotidine in intensive care stress ulcer prophylaxis, where its superior safety profile versus cimetidine justifies formulary inclusion despite higher acquisition cost.
- Cimetidine:The first-generation H2-antagonist with significant cytochrome P450 inhibition. Emerging market tenders in India and Brazil absorb volume for uncomplicated peptic ulcer maintenance, though its interaction burden limits adoption in polypharmacy geriatric populations.
- Ranitidine:Former volume leader withdrawn from US and European markets following FDA and EMA nitrosamine contamination findings. Remaining production serves limited markets with alternative regulatory standards.
- Nizatidine:A second-generation agent with bioavailability exceeding 90 percent. Prescription volumes cluster in North American retail pharmacy maintenance therapy where once-daily dosing improves adherence metrics.
Mature deployment sits with cimetidine in emerging market oral segments. Newer deployment is concentrated in famotidine injectable formulations for acute care protocols.
Delivery Mode:
Oral solid dosage forms generate prescription volume through retail pharmacy channels, while parenteral routes capture margin in institutional settings where rapid onset determines clinical utility.
- Oral:Tablets and capsules dominate outpatient GERD management. The US retail pharmacy channel processes the majority of famotidine and cimetidine oral prescriptions, with Medicare Part D reimbursement structures favoring generic substitution.
- Injectable:Intramuscular formulations serve perioperative acid suppression in ambulatory surgical centers. Japan's aging surgical population sustains demand where oral intake is contraincicated.
- Intravenous:Hospital critical care units in Germany and the US deploy IV famotidine for stress ulcer prophylaxis in mechanically ventilated patients, commanding price multiples over oral equivalents.
- Rectal:Limited to pediatric and dysphagic patient populations where enteral access is compromised. Compounding pharmacies in the US manufacture these formulations on a per-prescription basis.
Volume concentration follows oral tablets. Margin expansion is accelerating in intravenous presentations.
End User:
Institutional procurement departments increasingly consolidate purchasing authority, displacing individual prescriber discretion with protocol-driven formulary compliance.
- Hospitals:Integrated delivery networks exceeding 500 beds standardize acid suppression therapy selection through pharmacy and therapeutics committees. Injectable famotidine dominates perioperative and ICU protocols.
- Clinics:Outpatient gastroenterology practices in the US prescribe oral famotidine for step-down therapy following PPI failure or intolerance, with 340B program participation influencing sourcing decisions.
- Home Healthcare:Long-term care facilities in Japan administer orally disintegrating tablets to dysphagic geriatric residents, absorbing demand from standard tablet presentations.
- Pharmacies:Retail chains in Germany and the US process high-volume generic cimetidine and famotidine prescriptions, with substitution laws mandating bioequivalent interchange at the point of dispensing.
Established demand patterns center on hospital procurement. Emerging growth is visible in home healthcare channel expansion.
Application:
Clinical indication severity determines reimbursement tiering and prescribing hierarchy, with GERD maintenance offering volume and Zollinger-Ellison syndrome providing specialty pricing power.
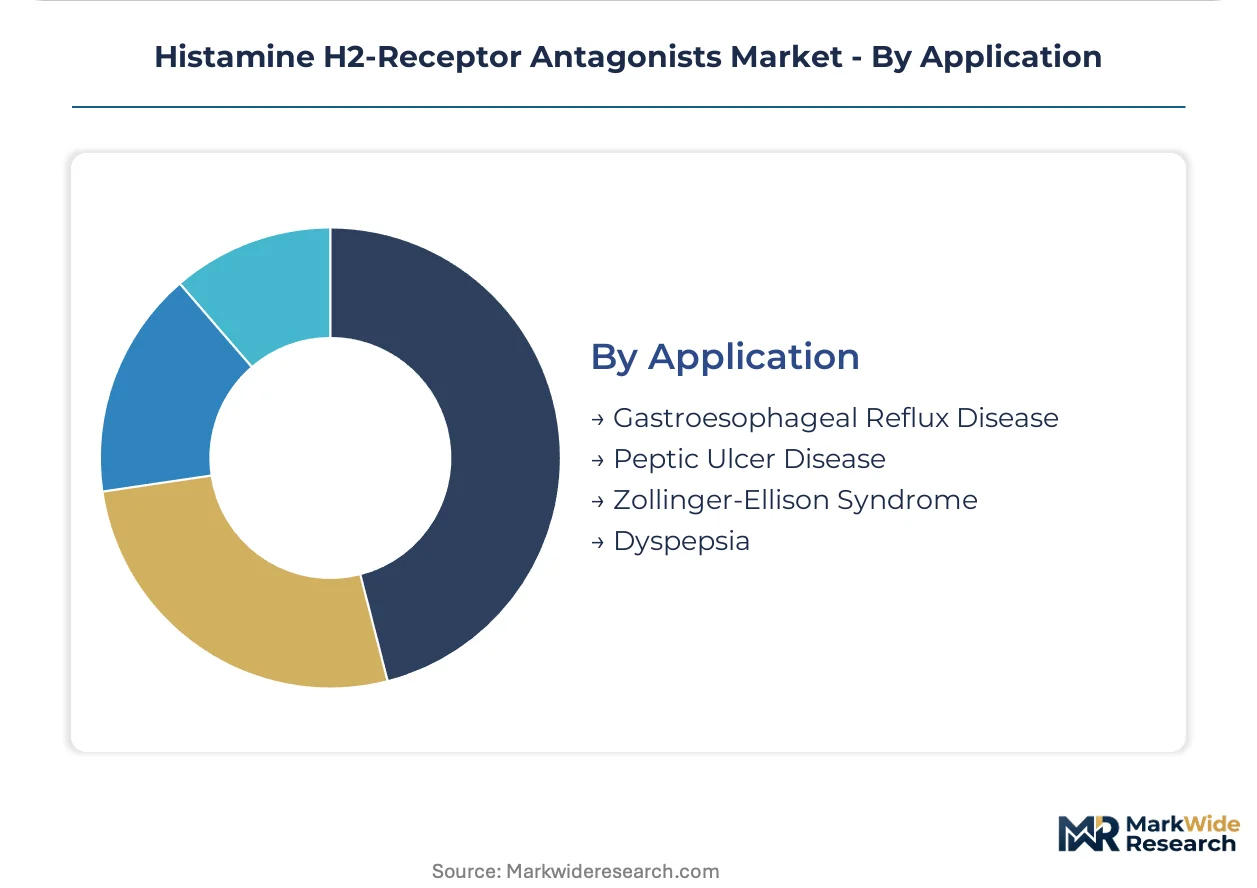
- Gastroesophageal Reflux Disease:The most prevalent indication drives prescription volume across all geographies. US and European guidelines relegate H2-antagonists to second-line status behind PPIs, compressing first-line opportunity.
- Peptic Ulcer Disease:Maintenance therapy following H. pylori eradication sustains stable demand. Japan's aging population generates consistent prescription renewal for gastric ulcer healing.
- Zollinger-Ellison Syndrome:A rare gastrin-secreting tumor indication requiring high-dose continuous acid suppression. Specialty oncology centers in the US and Germany prescribe famotidine at multiples of standard dosing.
- Dyspepsia:Functional upper gastrointestinal symptoms without organic pathology. Over-the-counter famotidine captures self-directed consumer demand in US and Japanese pharmacy retail.
Standardized protocols govern GERD management. Niche expansion concentrates in Zollinger-Ellison syndrome specialty care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and Japan concentrate demand for injectable famotidine formulations. Aging demographics across these markets sustain prescription volumes for peptic ulcer disease management and stress ulcer prophylaxis protocols.
United States
Medicare Part D reimbursement structures favor generic substitution at retail pharmacies, compressing branded oral famotidine margins. FDA bioequivalence standards govern therapeutic interchange decisions by pharmacy benefit managers. Hospital systems exceeding 500 beds in the Northeast and Midwest standardize acid suppression therapy through centralized pharmacy and therapeutics committees.
Germany
Germany's statutory health insurance funds apply reference pricing to H2-antagonist categories, intensifying cost competition among generic manufacturers. EMA quality guidelines and nitrosamine impurity testing requirements under REACH authorization elevate quality control overhead for oral solid dosage producers. The Rhine-Ruhr metropolitan region hosts concentrated pharmaceutical distribution infrastructure serving hospital procurement networks.
Japan
Japan's geriatric population drives sustained demand for orally disintegrating tablet formulations in long-term care facilities. PMDA pharmacovigilance requirements monitor long-term H2-antagonist safety profiles in polypharmacy elderly patients. The Kanto region surrounding Tokyo anchors hospital procurement concentration for intravenous famotidine in perioperative and intensive care protocols.
India
India's domestic market absorbs cost-optimized cimetidine production for uncomplicated peptic ulcer maintenance through government tender programs. CDSCO manufacturing facility inspections enforce ICH Q1A(R2) stability protocol compliance for export-oriented formulation facilities. The Mumbai-Pune pharmaceutical cluster concentrates active pharmaceutical ingredient production and contract formulation services for emerging market supply.
Brazil
Brazil's unified health system procurement channels distribute generic H2-antagonists through public pharmacy networks. ANVISA bioequivalence certification requirements create regulatory barriers for imported generic substitution. The São Paulo metropolitan area concentrates private hospital demand for injectable famotidine in surgical and critical care settings.
Histamine H2-Receptor Antagonists Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement favoring established injectable suppliers while retail pharmacy channels commoditize oral presentations. The market structure consolidates around three strategic tiers: research-intensive originators with hospital formulary relationships, high-volume generic manufacturers with broad distribution reach, and emerging market specialists competing on cost-optimized production. Dominant competitive moves include portfolio diversification into orally disintegrating tablet formats and geographic expansion through 340B program participation to bypass wholesale distribution.
Among research-intensive originators, Pfizer Inc. and AstraZeneca plc occupy positions anchored by hospital procurement relationships and therapeutic category expertise. Teva Pharmaceutical Industries Ltd. exemplifies the high-volume generic archetype with broad pharmacy distribution networks. Dr. Reddy's Laboratories Ltd. represents emerging market specialists competing on cost-optimized cimetidine production for tender-based procurement channels.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc. |
| AstraZeneca plc |
| Johnson & Johnson |
| Boehringer Ingelheim GmbH |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| Others |
Pricing and Supply Chain Analysis
API synthesis specialists in the Mumbai-Pune pharmaceutical cluster anchor production economics, with labor-cost differentials between Indian contract manufacturers and Western formulators driving spreads between economy-tier oral generics and premium-priced injectable presentations.
Pricing Analysis
Volume concentrates in oral tablet commoditization while margin expansion accelerates in intravenous famotidine. Three-tier pricing structure across premium injectable, standard oral prescription, and economy generic oral levels separates hospital formulary positioning from retail pharmacy substitution. Cost compression in the oral segment intensifies because Medicare Part D step-therapy mandates and pharmacy benefit manager rebate structures compress acquisition prices. Retail pharmacy chains exhibit highest price sensitivity, while hospital procurement departments prioritize supply assurance and clinical protocol compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from hospital group purchasing organizations and EMA-regulated manufacturers mandate multi-supplier qualification for famotidine active pharmaceutical ingredient, mitigating single-source vulnerability. API production draws from India, China, and limited European specialty chemical facilities. Key inputs include imidazole ring precursors, sulfur-containing coupling reagents, and high-purity solvents for crystallization. Tariff exposure on Chinese chemical intermediates creates inventory flexibility constraints. Distribution runs through wholesale distributors serving retail pharmacy networks, with direct-to-hospital 340B program participation capturing margin otherwise lost to pharmacy benefit manager rebates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as proton pump inhibitors displace H2-antagonists from first-line gastroesophageal reflux disease protocols, forcing incumbents to defend positioning in maintenance therapy and acute care niches where rapid acid suppression remains clinically necessary.
For Market Incumbents: Lock in hospital formulary presence through injectable famotidine supply agreements with integrated delivery networks exceeding 500 beds, while securing 340B program participation to bypass wholesale distribution margin compression. Defend against proton pump inhibitor substitution by emphasizing stress ulcer prophylaxis protocols in mechanically ventilated patient populations where H2-antagonist safety profiles retain clinical preference. Prioritize certification investment in FDA bioequivalence data packages to maintain generic substitution eligibility under pharmacy benefit manager formularies. For New Entrants and Emerging Players: Capture pediatric indication expansion opportunities in neonatal intensive care units, where weight-optimized famotidine dosing protocols remain underdeveloped and off-label use currently dominates clinical practice. Target home healthcare channel growth in Japan's long-term care facilities, where orally disintegrating tablet demand accelerates for dysphagic geriatric populations. Pursue go-to-market angles through specialized contract manufacturing organizations with established EMA quality guideline compliance and nitrosamine impurity testing capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with emerging market specialists possessing validated therapeutic equivalence data and cost-optimized cimetidine production infrastructure, given biosimilar proton pump inhibitor pricing pressure that may restore H2-antagonist cost-competitiveness in maintenance therapy segments. Long-term viability hinges on portfolio diversification into dosage-form differentiation rather than molecule innovation, with acquisition targets screening for formulation patent positions in orally disintegrating tablet technology. Monitor FDA pharmacovigilance requirements for long-term H2-antagonist safety profiles as the signal indicating regulatory burden shifts that could advantage established players with validated post-market surveillance infrastructure. Deviation in proton pump inhibitor biosimilar pricing trajectories or ranitidine regulatory reinstatement pathways would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Orally Disintegrating Tablet Development | Captures demand from Japan's geriatric long-term care facilities where dysphagia complications dominate. |
| Injectable Formulation Scale-Up | Secures hospital formulary presence in US and German intensive care stress ulcer prophylaxis protocols. |
| 340B Program Participation | Bypasses pharmacy benefit manager rebates through direct-to-hospital distribution channel capture. |
| Pediatric Indication Expansion | Addresses unmet need in neonatal intensive care units where off-label famotidine use currently prevails. |
| EMA Quality Guideline Compliance Investment | Enables European market access under REACH authorization nitrosamine impurity testing requirements. |
Research Methodology
Independent corroboration across hospital procurement managers, regulatory affairs leads at generic manufacturers, formulary directors at integrated delivery networks, and pharmacy benefit manager rebate contract specialists underwrites the qualitative findings. Primary interviews with drug development executives and payer access specialists combined with secondary validation from FDA bioequivalence filings, EMA quality guideline submissions, ClinicalTrials.gov protocol registrations, and CMS Medicare Part D reimbursement data establish demand-side parameters. Bottom-up prescription volume modeling and top-down therapeutic category expenditure analysis triangulate market size estimates.
Comparable-period anchoring to historical ranitidine withdrawal dynamics and subsequent famotidine substitution patterns structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and application indication, with regional regulatory cluster differentiation capturing FDA, EMA, PMDA, and CDSCO jurisdiction-specific pathway constraints. CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions reflecting reimbursement compression trends. Forecast inputs incorporate API supply concentration risk factors and proton pump inhibitor substitution elasticity coefficients.
The model holds under stable regulatory enforcement of bioequivalence standards and continued proton pump inhibitor first-line guideline positioning; deviation in FDA pharmacovigilance safety signal emergence or biosimilar pricing disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market