
 Quinoa Protein Market | 2026-2036
Quinoa Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Quinoa Protein Market Analytics
Bolivian and Peruvian altiplano farming cooperatives is restructuring seed-to-protein supply chains to meet industrial buyer specifications. Andean Naturals Inc leverages long-standing relationships with high-altitude growers to secure organic-certified raw material. Equinom competes through computational breeding platforms that optimize protein content and amino acid profiles. CK Ingredients anchors its position by controlling extraction and spray-drying infrastructure near coastal export hubs.
Quinoa protein denotes the isolated or concentrated protein fraction extracted from Chenopodium quinoa seeds, typically yielding protein contents between 50% and 90% depending on processing intensity, with a complete essential amino acid profile including notable lysine concentrations. Its primary commercial purpose centers on fortifying plant-based foods, sports nutrition formulations, and clean-label beverage systems where allergen-free positioning matters. Protein isolates command the deepest margin pools due to purity premiums and technical formulation requirements in dairy alternatives. The dietary supplements application segment registers the fastest trajectory as consumers shift toward single-source plant proteins with full amino acid disclosure. Powder form dominates current volume flows, though bar formats are gaining traction in convenience-oriented channels.
FDA GRAS self-determination and USDA organic certification govern U.S. market access, while the EU Green Deal's Farm to Fork strategy tightens sustainability documentation for imported protein ingredients. Peru's national agricultural regulator, SENASA, enforces phytosanitary standards that directly shape export eligibility for quinoa protein derivatives. Stakeholders must monitor evolving amino acid fortification claims regulation and carbon border adjustment mechanisms as these frameworks reshape procurement criteria.
Market Dynamics
The EU Green Deal's carbon accounting mandates are compressing procurement timelines for plant-based meat manufacturers sourcing Andean protein isolates. Industrial buyers now require documented supply chain emissions data before contract execution.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding sustainability documentation requirements for imported protein ingredients are accelerating certified organic quinoa protein uptake among European food manufacturers seeking compliance certainty.
- Plant-based meat formulation:German and Dutch manufacturers are expanding quinoa protein inclusion rates to meet texture and amino acid targets without soy or wheat allergens.
- Altiplano cooperative infrastructure:Peruvian and Bolivian farming collectives are consolidating seed cleaning and pre-processing capacity to meet industrial buyer volume and traceability specifications.
Market Restraints
- Quinoa seed price volatility:Climate variability in the Altiplano region creates input cost instability that propagates through protein isolate pricing.
- Single-origin supply concentration:Over 80% of organic quinoa protein feedstock originates from high-altitude Andean plateaus, creating geographic risk exposure.
- Technical protein functionality gaps:Quinoa protein exhibits lower gelation strength than soy isolates, limiting application in certain dairy alternative formats.
Strategic Opportunities
- Sports nutrition powder expansion:Single-source plant protein powders with complete amino acid disclosure are capturing share from blended formulations in North American direct-to-consumer channels.
- Beverage system fortification:Clean-label beverage developers are testing quinoa protein for its neutral flavor profile and suspension stability in RTD applications.
- Carbon border adjustment positioning:Early compliance with EU carbon border documentation creates preferential procurement status for Andean suppliers with verified low-emission cultivation.
Industry Challenges
- Organic certification timeline compression:SENASA phytosanitary approvals and USDA organic audits create 14-18 month qualification periods that strain working capital for new entrants.
- Spray-drying capacity scarcity:Limited extraction and drying infrastructure near coastal export hubs concentrates processing leverage among incumbent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quinoa Protein Market |
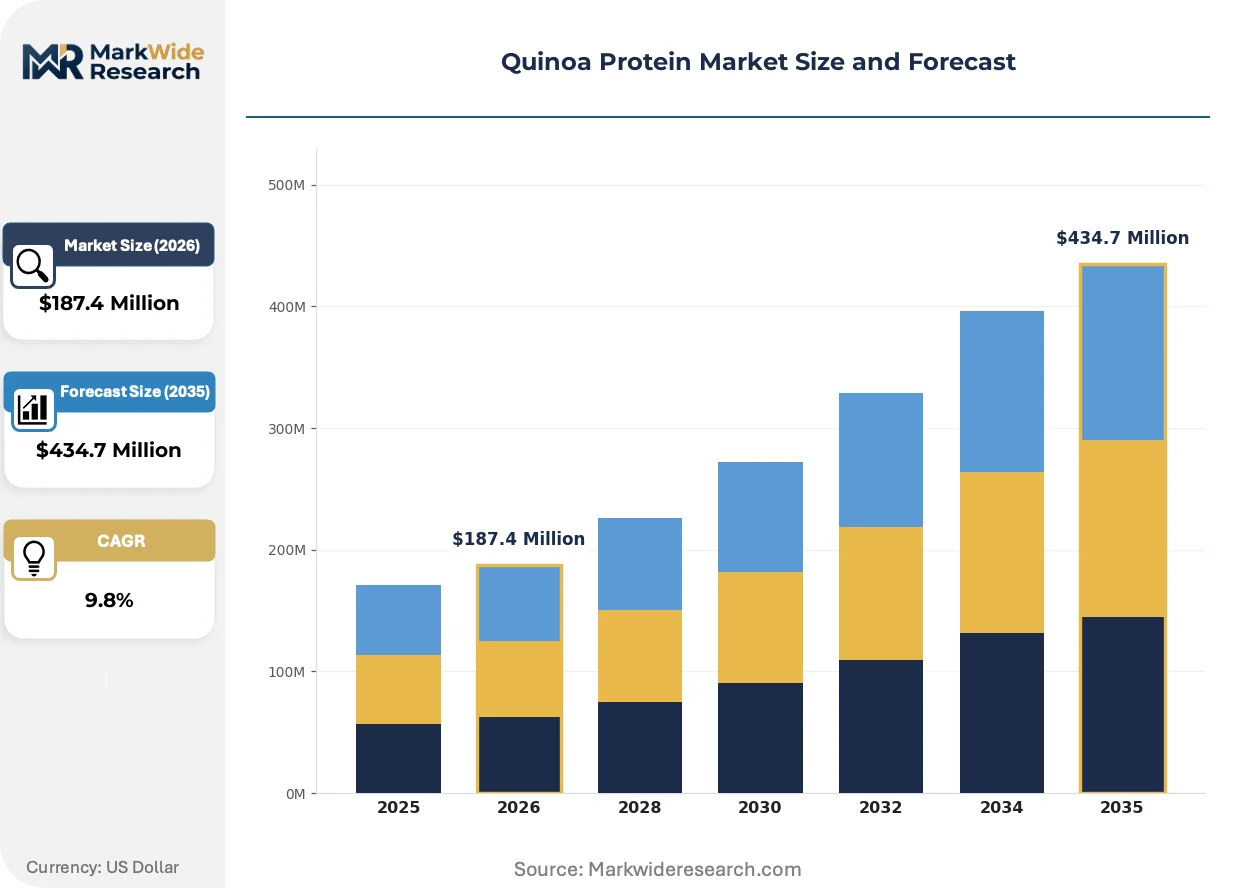
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Isolates, Protein Concentrates, Textured Protein, Protein Flour Application: Food & Beverages, Dietary Supplements, Nutraceuticals, Animal Feed Form: Powder, Liquid, Granules, Bars Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Andean Naturals Inc, Equinom, YT Biochem, Organic Meets Good (OMG), BI Nutraceuticals, CK Ingredients, Active Concepts LLC, Northern Quinoa Production Corporation, Avena Foods Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quinoa Protein Market Evolving Landscape
Computational breeding platforms and precision fermentation are converging to reshape protein quality specifications and supply security expectations across plant-based ingredient procurement.
Enzymatic protein extraction is absorbing capital allocation from traditional aqueous methods as manufacturers seek higher yields and preserved amino acid integrity. European isolates producers are retrofitting extraction lines to accommodate enzyme-assisted processing at commercial scale. This technology is absorbing margin pressure from energy-intensive thermal separation while enabling cleaner label positioning.
REACH chemical registration requirements and the EU Green Deal's carbon border adjustment mechanism are tightening documentation burdens for imported protein derivatives. Food manufacturers must now verify cultivation emissions and processing chemical inputs through certified third-party audits. German and Dutch plant-based meat producers are most exposed, accelerating supplier consolidation toward vertically integrated Andean operators with pre-validated compliance packages.
Direct contracting between food manufacturers and Altiplano cooperatives is displacing spot-market purchasing through commodity traders. Large European buyers are establishing multi-year offtake agreements with named Peruvian farming collectives to secure organic-certified volumes. This pattern is most visible in German procurement offices, where sustainability officers now negotiate directly with SENASA-registered cooperative federations rather than intermediaries.
Quinoa Protein Market Segmentation
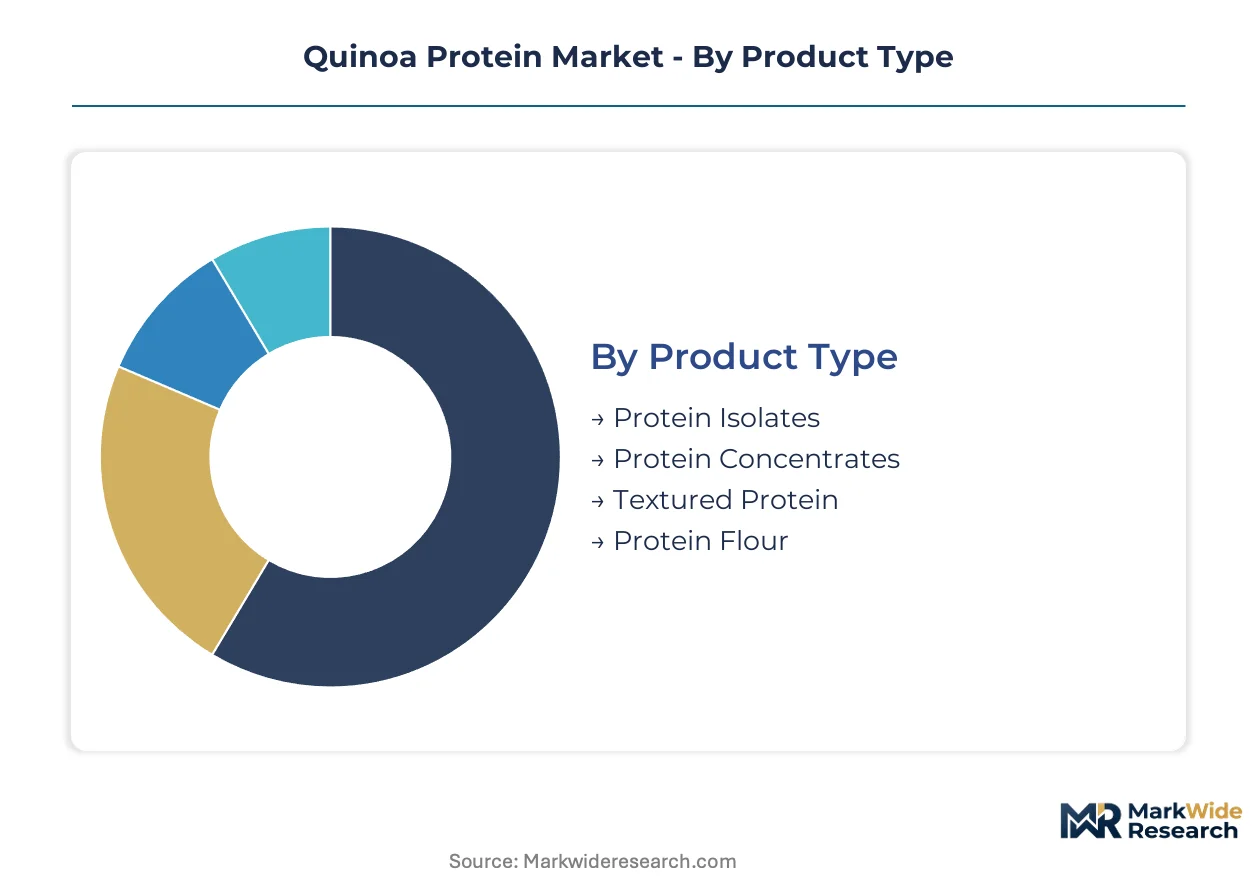
Quinoa protein's commercial value crystallizes through purity gradients and formulation requirements. Manufacturers calibrate procurement across four distinct dimensions, each mapping to specific margin pools and technical specifications.
Product Type:
Volume flows concentrate in mid-purity concentrates, while premium extraction yields anchor profitability for isolate specialists.
- Protein Isolates:These refined fractions achieve protein contents between 80% and 90% through intensive aqueous or enzymatic extraction. German plant-based meat manufacturers specify isolates for amino acid fortification in clean-label formulations. The EU Green Deal's carbon documentation requirements favor suppliers with verified low-emission Altiplano cultivation.
- Protein Concentrates:Concentrates deliver 50% to 70% protein content through less intensive processing, capturing the largest volume share in cost-sensitive applications. Peruvian cooperatives direct concentrate output toward animal feed compounders and emerging economy food fortification programs.
- Textured Protein:Extruded formats provide structural integrity for meat analog applications, with Dutch manufacturers testing quinoa-based textures for allergen-free positioning.
- Protein Flour:Whole-seed milled products retain fiber and lipid fractions, serving gluten-free bakery developers seeking complete nutritional profiles.
Mature deployment sits with Protein Concentrates. Newer deployment is concentrated in Protein Isolates.
Application:
End-use segmentation tracks the divergence between industrial formulation scale and direct-to-consumer premium positioning.
- Dietary Supplements:Single-source plant protein powders with complete amino acid disclosure are displacing blended formulations in North American direct-to-consumer channels. Sports nutrition brands specify quinoa isolates for lysine fortification and allergen-free claims.
- Food & Beverages:Clean-label beverage developers test quinoa protein for neutral flavor and suspension stability in RTD applications. Peruvian export infrastructure concentrates supply toward European dairy alternative manufacturers.
- Nutraceuticals:Functional food positioning leverages quinoa's complete protein status for aging population nutrition products in Japanese and South Korean markets.
- Animal Feed:Pet food manufacturers incorporate quinoa concentrates for premium positioning in grain-free formulations, though price volatility constrains volume scaling.
Food & Beverages commands the deepest procurement volumes. Dietary Supplements climbs the fastest.
Form:
Physical format selection determines logistics economics and formulation integration complexity.
- Powder:Spray-dried formats dominate current volume flows, enabling precise dosing in industrial batching and consumer scoop-based applications. Coastal Peruvian drying infrastructure concentrates processing leverage among incumbent operators.
- Bars:Convenience-oriented formats gain traction in European sports nutrition retail, with German manufacturers testing quinoa protein inclusion for texture and binding properties.
- Liquid:Ready-to-drink suspensions require advanced stabilization systems, limiting deployment to beverage specialists with homogenization capabilities.
- Granules:Intermediate moisture formats serve specific meat analog extrusion requirements, though application scope remains narrower than powder alternatives.
Powder formats anchor current supply contracts. Bar formats are gaining share fastest.
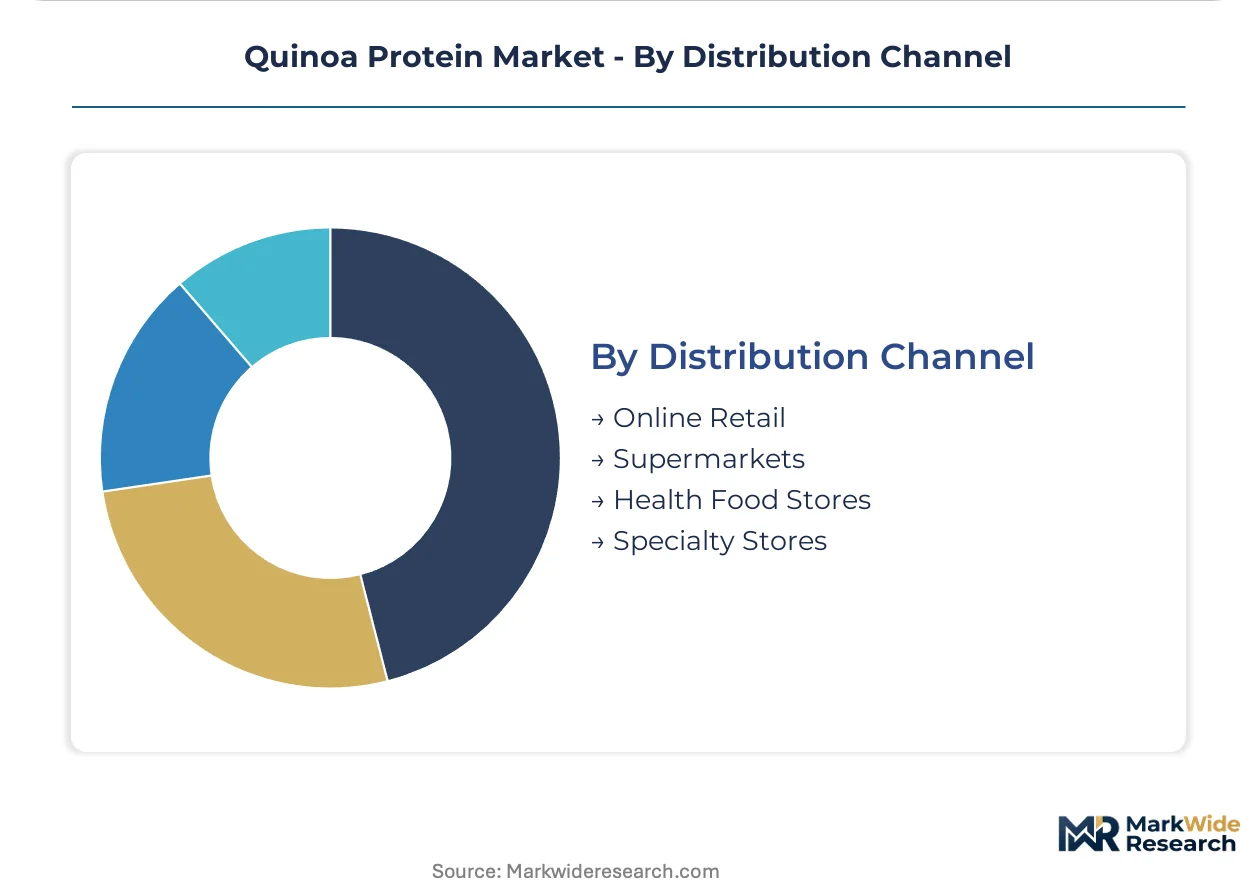
Distribution Channel:
Channel structure reflects the tension between traceability requirements and procurement efficiency.
- Online Retail:Direct-to-consumer platforms enable single-source protein storytelling and subscription-based replenishment. North American sports nutrition brands leverage Amazon and specialized fitness commerce for quinoa isolate distribution.
- Health Food Stores:Specialty retail provides education-intensive positioning for organic-certified products, with Peruvian cooperative brands securing shelf space through sustainability narrative differentiation.
- Supermarkets:Mass retail penetration remains limited by price positioning relative to soy and pea alternatives, though German REWE and EDEKA chains test quinoa protein in private-label ranges.
- Specialty Stores:Professional nutrition outlets and fitness centers serve high-loyalty consumer segments with technical product guidance.
Health Food Stores represent established premium positioning. Online Retail expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's Altiplano region anchors quinoa protein feedstock supply, with smallholder cooperatives supplying premium organic grades to industrial buyers. German plant-based meat manufacturers are scaling quinoa protein purchases as EU carbon accounting tightens. Processing infrastructure concentrates near coastal export hubs to minimize logistics friction.
Germany
REWE and EDEKA chains test quinoa protein in private-label plant-based meat ranges. The EU Green Deal's Farm to Fork strategy binds German manufacturers to documented sustainability credentials for imported protein ingredients. Berlin procurement offices negotiate directly with SENASA-registered Peruvian cooperatives, bypassing commodity traders.
United States
FDA GRAS self-determination governs market access for quinoa protein isolates entering sports nutrition formulations. Amazon and specialized fitness commerce platforms enable North American brands to distribute single-source protein powders with subscription-based replenishment. California clean-label beverage developers test quinoa protein for neutral flavor and suspension stability in RTD applications.
Peru
SENASA enforces phytosanitary standards that directly shape export eligibility for quinoa protein derivatives. The national agricultural regulator's organic certification audits create 14-18 month qualification periods that strain working capital for new entrants. Arequipa and coastal export hubs concentrate spray-drying infrastructure among incumbent operators with validated compliance packages.
Netherlands
Dutch plant-based meat manufacturers expand quinoa protein inclusion rates to meet texture targets without soy or wheat allergens. REACH chemical registration requirements tighten documentation burdens for imported protein derivatives. Rotterdam logistics clusters serve as distribution nodes for Andean isolates entering European formulation facilities.
Japan
METI standards and aging population nutrition programs drive functional food positioning for quinoa's complete protein status. Japanese nutraceutical developers leverage lysine fortification claims in senior nutrition products. Osaka formulation clusters import Peruvian organic-certified isolates for premium positioning in health food retail channels.
Quinoa Protein Market Competitive Landscape
Global majors compete with regional champions across extraction infrastructure and cooperative sourcing relationships. The vendor base organizes around three tiers: vertically integrated Andean operators controlling seed-to-powder supply chains, precision breeding technology specialists, and regional trading houses with SENASA-certified logistics networks. Dominant competitive moves include multi-year offtake agreements with named farming collectives and retrofitting extraction lines for enzymatic processing at commercial scale.
Within the cooperative-sourcing tier, Andean Naturals Inc exemplifies long-standing relationships with high-altitude Altiplano growers, while CK Ingredients anchors its position through coastal export hub infrastructure. Equinom occupies a position among technology-driven specialists leveraging computational breeding platforms. These three represent distinct archetypes: cooperative-integrated sourcing, processing infrastructure control, and seed genetics optimization.
| Leading Market Players |
|---|
| Andean Naturals Inc |
| Equinom |
| YT Biochem |
| Organic Meets Good (OMG) |
| BI Nutraceuticals |
| CK Ingredients |
| Active Concepts LLC |
| Northern Quinoa Production Corporation |
| Avena Foods Limited |
| Others |
Value Network & Pricing Analysis
German plant-based meat manufacturers concentrate procurement leverage through multi-year offtake agreements, locking in contract-based long-term pricing that insulates against Altiplano seed volatility. This buyer archetype's sustainability compliance mandates enforce premium tiers for certified organic isolates with verified carbon documentation.
Pricing Analysis
Service bundling separates organic certification audit support from unbundled commodity concentrate transactions, with SENASA compliance packages commanding substantial premiums over spot-market isolates. Three-tier pricing structure across premium certified-organic, standard conventional, and economy feed-grade levels reflects protein purity and documentation depth. Pricing pressure stems from climate-driven quinoa seed cost instability propagating through isolate production. Contract manufacturers exhibit highest price sensitivity due to working capital constraints, while branded sports nutrition companies absorb premiums for single-source positioning.
Supply Chain Analysis
Reverse-logistics flows for organic certification documentation and SENASA phytosanitary re-verification create administrative bottlenecks at Peruvian coastal export hubs. Feedstock concentrates in Peru's Altiplano region, with Bolivia and Ecuador contributing secondary volumes. Processing draws from quinoa seed, enzymatic extraction agents, and spray-drying energy inputs. Single-origin geographic concentration exposes buyers to Andean climate volatility and regulatory approval delays. Distribution runs through Rotterdam and Hamburg logistics clusters for European formulation facilities, with direct cooperative contracting displacing trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vertically integrated operators with validated SENASA compliance packages, as EU carbon border documentation requirements force trader-dependent entrants toward acquisition or exit.
For Market Incumbents: Anticipate enzymatic extraction technology displacement of aqueous methods by retrofitting coastal processing lines for higher-yield, cleaner-label output. Secure backward integration into Altiplano cooperative equity stakes to lock organic-certified feedstock against emerging precision fermentation substitutes. Prioritize carbon documentation pre-validation to capture preferential procurement status under EU Green Deal enforcement. For New Entrants and Emerging Players: Computational breeding platforms offer technology-first entry against incumbent germplasm control, enabling protein content optimization without multi-year cooperative relationship buildout. Target North American direct-to-consumer sports nutrition channels where single-source storytelling commands premium positioning absent in European commodity contracting. Pursue white-label spray-drying partnerships with established Peruvian operators to bypass 14-18 month SENASA qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Peruvian cooperatives with SENASA registration but insufficient working capital for extraction infrastructure expansion. Long-term viability hinges on carbon border adjustment compliance positioning across the analysis window. Monitor EU Farm to Fork strategy enforcement intensity as inflection indicator for accelerated supplier consolidation toward documented low-emission cultivators.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Retrofit | Higher yields and preserved amino acid integrity strengthen isolate positioning against soy alternatives. |
| Cooperative Equity Stakes | Backward integration into Altiplano farming collectives secures organic-certified feedstock volumes. |
| Carbon Documentation Pre-Validation | Early EU Green Deal compliance creates preferential procurement status among German manufacturers. |
| Direct-to-Consumer Channel Entry | Single-source protein storytelling captures premium positioning in North American sports nutrition. |
| Computational Breeding Investment | Seed genetics optimization reduces dependency on established cooperative sourcing relationships. |
Research Methodology
Trade databases, SENASA export registration records, and EU Farm to Fork strategy documentation formed the secondary backbone, cross-referenced with primary interviews across plant-based meat procurement officers, Altiplano cooperative federation managers, sports nutrition brand formulation directors, and Peruvian spray-drying facility operators. Bottom-up volume modeling from cooperative output data and top-down demand calibration from German and Dutch manufacturer offtake agreements enabled triangulation. Customs records and organic certification audit disclosures provided pricing tier validation.
Historical trendline analysis of quinoa seed price movements and isolate export volumes established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type tiers, application end-uses, physical form factors, and distribution channel structures. CAGRs derived from regression analysis of documented contract values and disclosed capacity expansions. Forecast inputs included EU carbon border adjustment implementation timelines and enzymatic extraction technology adoption curves.
Several conditions sit outside the modeled scope, including unregulated amino acid fortification claim reversals and precision fermentation protein cost parity breakthroughs. Forecasts reflect documented assumptions regarding SENASA audit timeline stability and Altiplano climate variability patterns. Practitioners should monitor EU Green Deal enforcement intensity and computational breeding platform commercialization rates for early signals of competitive displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Global Algae Market