
 Germany Feed Additives Market | 2026-2036
Germany Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Feed Additives Market Foresight
Buyer concentration among large-scale swine integrators in northwest Germany is pivoting procurement toward volume-contracted enzyme and amino acid supply. Cargill Inc. leverages its compound feed network to secure long-term additive offtake from vertically coordinated farms. BASF SE anchors micronutrient demand through direct technical service relationships with Bavarian dairy cooperatives. Evonik Industries AG specializes in precision amino acid formulations that reduce crude protein requirements for nitrogen-excretion compliance.
Feed additives comprise biologically active substances incorporated into compound feeds at inclusion rates typically below one percent to enhance nutrient utilization, animal health, or growth performance; phytase enzymes, for example, liberate phosphorus from plant-derived phytic acid, reducing inorganic phosphate supplementation by up to eighty percent. Amino acids command the largest product-type value pool due to their irreplaceable role in least-cost feed formulation, while enzymes represent the fastest-expanding category as German livestock operations face escalating environmental permit scrutiny. Digestibility enhancers generate disproportionate margin capture because they deliver measurable feed-conversion improvements that justify premium pricing against generic nutritional supplements.
The EU Green Deal's Farm to Fork Strategy, enforced through Germany's Federal Ministry of Food and Agriculture, mandates livestock emission reductions that directly expand demand for methane-inhibiting feed additives and precision nutrition tools. REACH chemical registration requirements administered by ECHA govern novel additive approval timelines, creating regulatory moats around established suppliers with dossier completion capabilities. Stakeholders must monitor pending revisions to the EU Feed Hygiene Regulation and Germany's national fertilizer ordinance, as stricter phosphorus output limits will reshape enzyme and amino acid formulation priorities across the value chain.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy enforces methane emission caps that compel German livestock operators to adopt precision nutrition tools and enzyme-based feed reformulations, restructuring procurement relationships around environmental compliance rather than cost optimization alone.
Growth Catalysts
- EU Green Deal methane targets:Binding emission reduction mandates for livestock operations expand demand for phytase enzymes and amino acid premixes that lower nitrogen excretion and enteric fermentation.
- Lower Saxony swine concentration:Dense integrator clusters in northwest Germany create volume-contracting opportunities for additive suppliers serving large-scale operations with standardized nutritional protocols.
- Phytase enzyme performance:Eighty-percent reduction in inorganic phosphate supplementation drives cost savings and regulatory alignment with Germany's national fertilizer ordinance phosphorus limits.
Market Restraints
- REACH registration timelines:ECHA dossier requirements for novel additives extend approval cycles, freezing out smaller suppliers lacking regulatory affairs capabilities.
- Input concentration in enzyme production:Fermentation substrate supply depends on concentrated corn-processing regions, exposing formulators to agricultural commodity volatility.
- Technical limitation in ruminant application:Enzyme stability in rumen conditions remains inconsistent, constraining product efficacy in dairy-dominant Bavarian cooperatives.
Strategic Opportunities
- Bavaria dairy corridor precision nutrition:Underpenetrated micronutrient customization for high-yield herds offers margin expansion through direct technical service models.
- EU Feed Hygiene Regulation revision:Pending stricter contamination thresholds will force additive upgrades, creating replacement demand for certified suppliers.
- Digital feed formulation convergence:Real-time nutrient optimization software paired with sensor-based intake monitoring enables subscription-based additive dosing services.
Industry Challenges
- Regulatory affairs talent scarcity:REACH dossier preparation requires specialized toxicology and environmental fate expertise that outpaces German university output.
- Legacy compound feed system integration:Additive dosing equipment must interface with existing mill automation, creating retrofit complexity and implementation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Feed Additives Market |
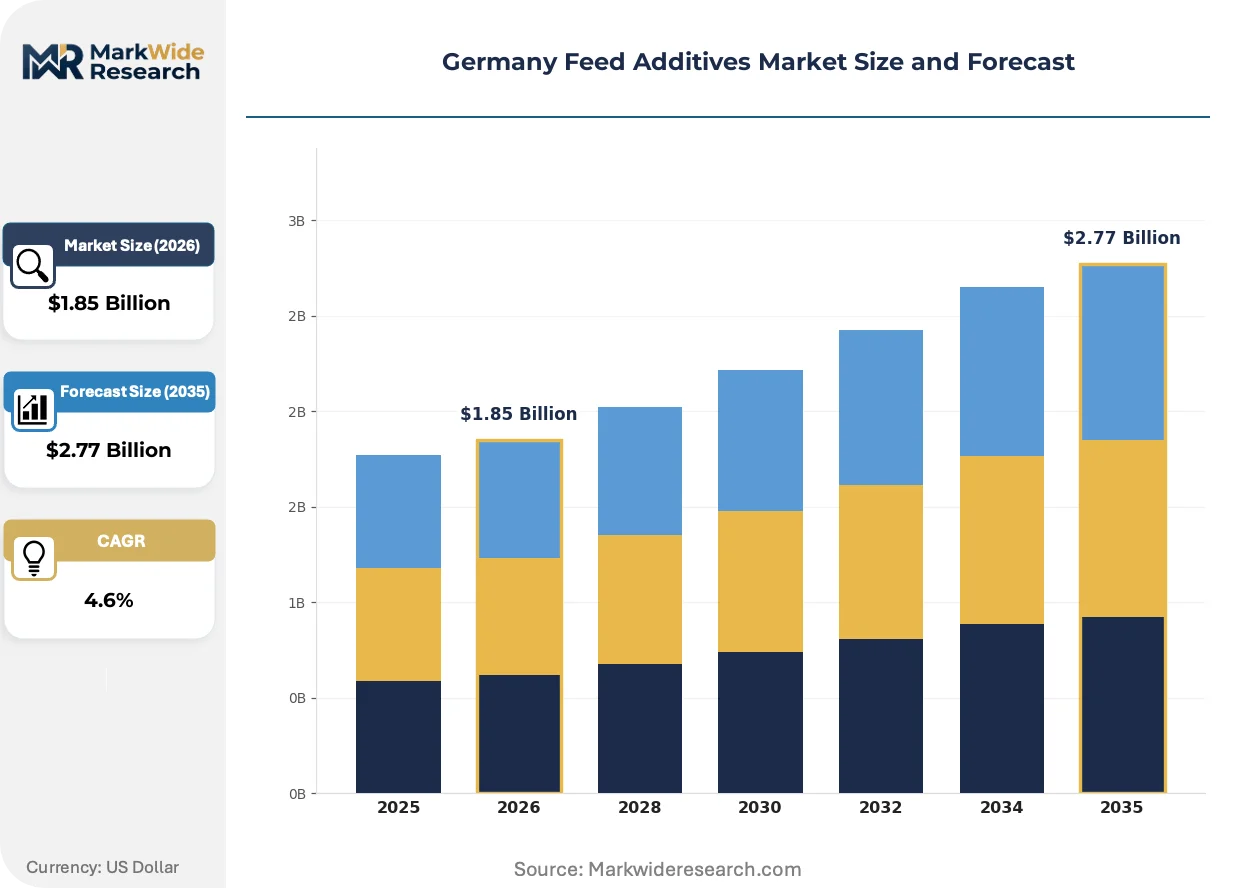
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Amino Acids, Antioxidants, Enzymes End User: Poultry, Swine, Ruminants, Aquaculture Functionality: Digestibility Enhancers, Growth Promoters, Health Protectants, Nutritional Supplement Form: Powder, Liquid, Granular, Capsule |
| Companies Covered | Cargill Inc., DSM-Firmenich AG, Archer Daniels Midland Co., SHV (Nutreco NV), Alltech, Inc., BASF SE, Evonik Industries AG, Novonesis Group, Kemin Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Feed Additives Market Shifts & Advancements
Precision fermentation and digital nutrition platforms are restructuring how German livestock operations formulate feed, shifting value capture from commodity inputs toward data-enabled performance guarantees and environmental compliance services.
Phytase enzyme engineering is converging with thermostability coatings that protect activity during pelleting temperatures exceeding eighty-five degrees Celsius. Bavarian pork processors and Lower Saxony integrators are adopting these next-generation formulations within eighteen-month replacement cycles. This convergence is compressing the performance gap between standard and premium enzyme tiers, forcing suppliers to differentiate through technical service rather than unit activity claims.
Germany's Federal Ministry of Food and Agriculture is tightening enforcement of the EU Feed Hygiene Regulation through expanded national residue monitoring programs. Additive suppliers now face batch-level traceability requirements that extend from manufacturing through on-farm delivery. Enzyme and amino acid formulators serving dairy cooperatives are responding by deploying blockchain-verified chain-of-custody systems to preempt regulatory penalties.
Volume-contracted procurement is displacing spot-market purchasing among large-scale swine integrators in northwest Germany. These buyers now demand multi-year additive supply agreements tied to feed-conversion-ratio performance benchmarks, transferring outcome risk to suppliers. The shift is most visible in Lower Saxony, where vertically coordinated farms have consolidated purchasing decisions through compound feed network partnerships.
Germany Feed Additives Market Segmentation
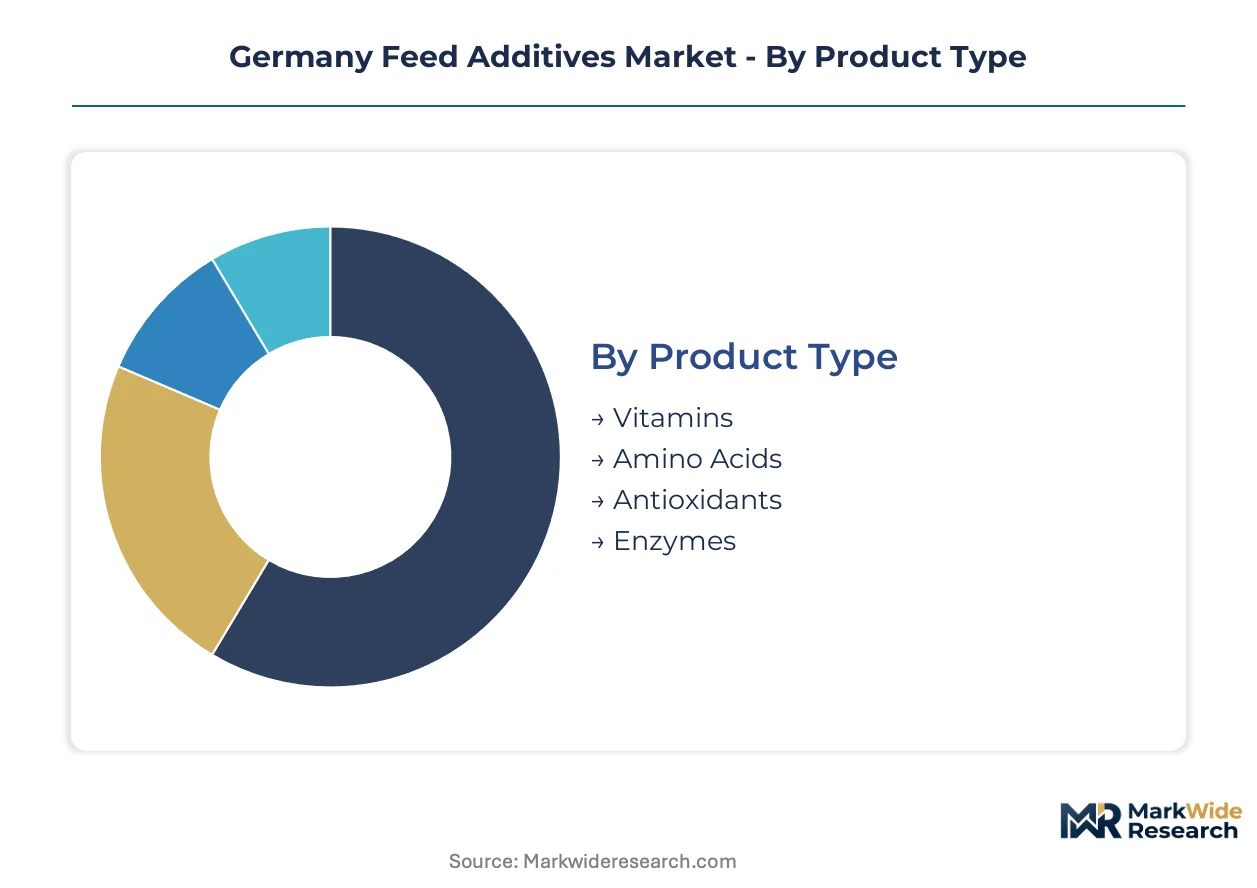
Feed additive purchasing in Germany stratifies across four critical dimensions that determine formulation priorities and supplier relationships. Product type and end-user concentration drive volume contracting patterns, while functionality and form specifications dictate equipment compatibility and dosing precision requirements.
Product Type:
Replacement cycles for core nutritional inputs are compressing as environmental compliance tightens, forcing integrators to reassess enzyme and amino acid specifications against reformulated compound feeds.
- Amino Acids:Irreplaceable building blocks for least-cost feed formulation, lysine and methionine premixes dominate procurement volumes across Bavaria's pork processing corridor. Demand concentrates among vertically coordinated swine operations seeking nitrogen-excretion compliance through reduced crude protein diets.
- Enzymes:Phytase variants liberate phosphorus from plant-derived phytic acid, cutting inorganic phosphate supplementation by up to eighty percent. Lower Saxony integrators drive fastest category expansion amid tightening EU Green Deal methane targets and national fertilizer ordinance phosphorus limits.
- Vitamins:Micronutrient premixes stabilize metabolic function and reproductive performance in high-yield dairy herds across southern Germany.
- Antioxidants:Preservation additives extend feed shelf stability during extended storage periods common in decentralized farm operations.
Volume placements concentrate in amino acids; the faster expansion belongs to enzymes.
End User:
Livestock category margins determine additive specification tiers, with premium formulations reserved for high-turnover species and economy blends serving longer-cycle production.
- Swine:Intensive finishing operations in Lower Saxony and North Rhine-Westphalia generate concentrated demand for phytase and amino acid premixes. Procurement runs through compound feed network partnerships that standardize nutritional protocols across coordinated farm clusters.
- Poultry:Broiler and layer operations prioritize feed-conversion efficiency through enzyme-supplemented diets, with southern German integrators leading precision nutrition adoption.
- Ruminants:Bavarian dairy cooperatives anchor micronutrient demand, though rumen enzyme stability constraints limit certain formulation categories.
- Aquaculture:Emerging recirculating systems in northern coastal regions test specialized digestibility enhancers for salmonid and freshwater species.
Swine operations command the largest volume commitments; poultry applications are climbing the fastest.
Functionality:
Performance guarantee structures reshape supplier-buyer relationships, with outcome-based contracting favoring additives delivering measurable conversion or health metrics.
- Digestibility Enhancers:Enzyme and acidifier combinations improve nutrient absorption coefficients, justifying premium pricing through demonstrable feed-conversion-ratio improvements. German livestock operators facing environmental permit scrutiny prioritize these formulations for regulatory alignment.
- Nutritional Supplement:Vitamin-mineral premixes address baseline deficiency risks in high-production systems, with direct technical service relationships driving supplier selection among Bavarian dairy cooperatives.
- Health Protectants:Gut-conditioning additives reduce therapeutic intervention requirements amid antibiotic reduction mandates.
- Growth Promoters:Regulatory restrictions limit category scope, with residual demand concentrating in non-medical performance optimization tools.
Digestibility enhancers capture disproportionate margin premiums; nutritional supplements maintain the broadest penetration base.
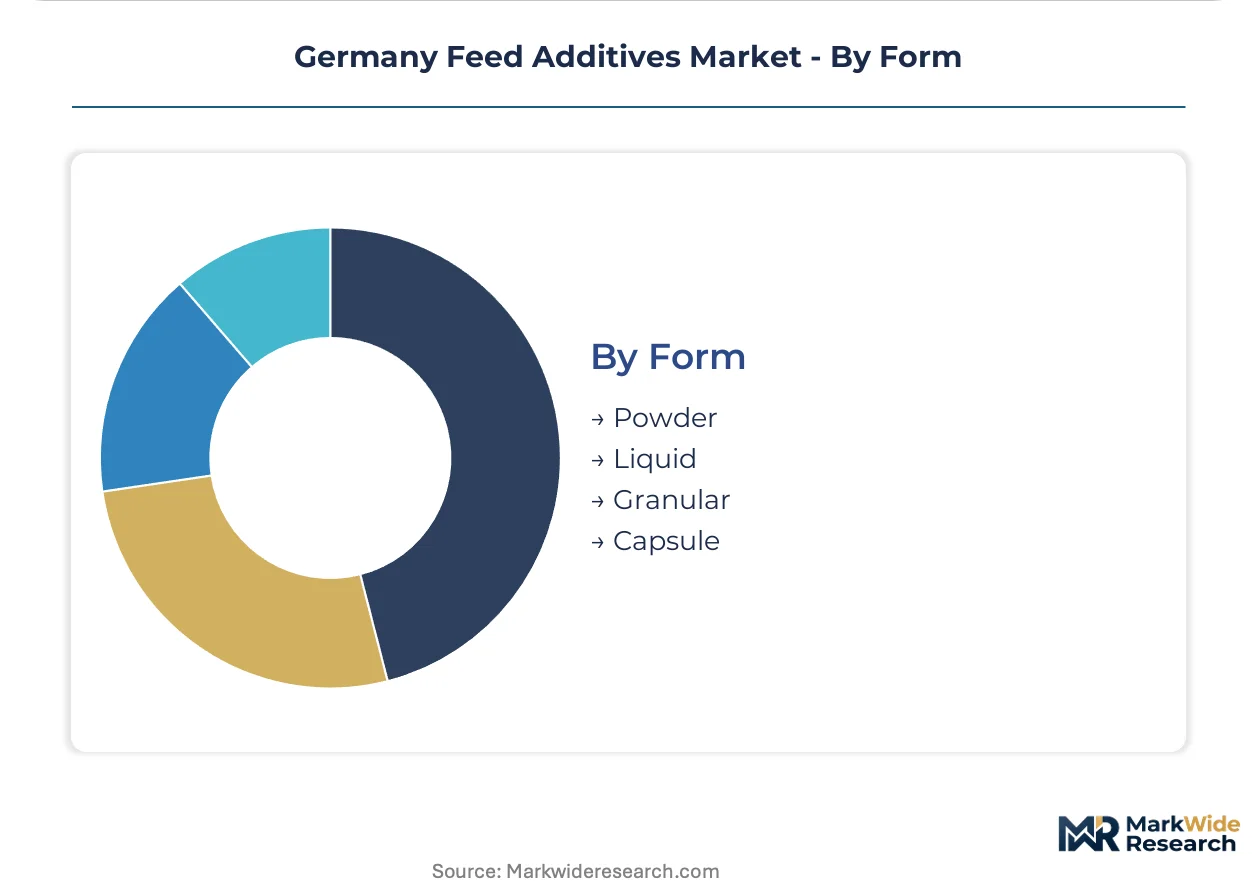
Form:
Equipment retrofit requirements and handling logistics determine form selection, with existing mill automation compatibility constraining adoption of novel delivery systems.
- Powder:Standard inclusion format for amino acid and vitamin premixes, requiring precise dosing equipment integration with compound feed production lines. Legacy mill automation compatibility challenges slow specification upgrades in smaller operations.
- Liquid:Post-pelleting application enables heat-sensitive enzyme preservation, gaining traction among specialized additive suppliers serving high-volume integrators.
- Granular:Flowability advantages suit automated handling systems in large-scale northwest German operations.
- Capsule:Protected-release formats target ruminant applications where rumen bypass requirements limit standard formulation efficacy.
Powder dominates current volume placements; liquid formats are gaining share fastest among technology-leading integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swine integrators in northwest Germany concentrate additive procurement volumes, while Bavaria's dairy cooperatives anchor micronutrient demand. Federal environmental enforcement is tightening phosphorus and methane limits across both corridors. Sub-regional specialization shapes supplier relationship structures.
Bavaria
Dairy cooperatives in southern Germany drive premium vitamin-mineral premix consumption for high-yield herds. The Federal Ministry of Food and Agriculture enforces EU Feed Hygiene Regulation standards through expanded residue monitoring. Munich and Nuremberg processing clusters demand precision amino acid formulations for nitrogen-excretion compliance.
Lower Saxony
Dense swine finishing operations generate concentrated phytase enzyme demand amid tightening EU Green Deal methane targets. Germany's national fertilizer ordinance imposes binding phosphorus output limits on livestock operations. Hannover and Oldenburg integrators have consolidated purchasing through compound feed network partnerships with volume-contracted supply terms.
North Rhine-Westphalia
Mixed livestock operations sustain steady demand for digestibility enhancers and gut-conditioning additives. ECHA administers REACH registration requirements that extend novel additive approval timelines. Cologne-Düsseldorf industrial zones host formulation facilities serving both domestic and Benelux export markets.
Baden-Württemberg
Specialized poultry integrators prioritize feed-conversion efficiency through enzyme-supplemented diets. State-level agricultural departments coordinate with federal regulators on antibiotic reduction mandate implementation. Stuttgart-area operations lead adoption of thermostability-coated enzymes for high-temperature pelleting processes.
Hesse
Central location advantages position Frankfurt-Rhine-Main as a logistics hub for additive distribution networks. Federal environmental permit scrutiny applies uniform pressure across livestock categories regardless of operation scale. Giessen and Kassel agricultural research centers test novel fermentation-derived additives for commercial scalability.
Germany Feed Additives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital nutrition platforms and precision fermentation capabilities. The supplier base stratifies across three tiers: multinational chemical conglomerates with dossier completion capabilities, specialized enzyme and amino acid formulators, and regional compound feed network partners. Strategic archetypes include environmental compliance specialists, precision nutrition technologists, and volume-contracting integrators. Dominant competitive moves center on multi-year performance-guarantee contracts and technical service relationship deepening.
Within the multinational chemical tier, BASF SE and Evonik Industries AG exemplify archetypes built on regulatory affairs capabilities and precision formulation expertise. Cargill Inc. occupies a position representing compound feed network leverage and vertically coordinated farm cluster access. These three entities anchor competitive positioning around distinct vectors: direct technical service relationships, volume-contracting procurement structures, and environmental compliance solution bundling.
| Leading Market Players |
|---|
| Cargill Inc. |
| DSM-Firmenich AG |
| Archer Daniels Midland Co. |
| SHV (Nutreco NV) |
| Alltech, Inc. |
| BASF SE |
| Evonik Industries AG |
| Novonesis Group |
| Kemin Industries |
| Others |
Supply & Pricing Matrix
EU Green Deal methane targets gate qualified supply and premium-tier pricing access, restricting enzyme and amino acid procurement to suppliers with completed REACH dossiers and thermostability certification. Large-scale swine integrators in Lower Saxony leverage volume-contracting power to compress margins on standard-grade formulations while paying premiums for environmental compliance-guaranteed supply.
Pricing Analysis
Volume placements concentrate in contracted amino acid supply while margin capture clusters in precision enzyme formulations with performance guarantees. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and technical service bundling. Pricing pressure stems from integrator consolidation in northwest Germany, with spot-market buyers in smaller Bavarian dairy operations showing highest price sensitivity.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled additive batches remain underdeveloped, exposing distributors to write-off risks under tightened EU Feed Hygiene Regulation traceability mandates. Fermentation substrate supply draws from concentrated corn-processing regions in Germany, Belgium, and the Netherlands. Single-source vulnerability in phytase enzyme production strains distribution through compound feed network partnerships serving vertically coordinated farm clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH dossier completion capacity constrains qualified supplier availability, propping pricing premiums for established players with regulatory affairs capabilities. This supply-constrained structure favors incumbents with sunk compliance investments.
For Market Incumbents: To counter emerging precision fermentation entrants, BASF SE and Evonik Industries AG should deepen technical service relationships with Bavarian dairy cooperatives and secure backward integration into fermentation substrate supply. Capacity expansion in Lower Saxony compound feed corridors reinforces volume-contracting leverage against spot-market competitors. For New Entrants and Emerging Players: Digital feed formulation platforms offer the most penetrable route, enabling subscription-based dosing services that bypass legacy mill automation retrofit barriers. Target underpenetrated micronutrient customization for high-yield dairy herds through direct sensor-integration partnerships with Stuttgart-area equipment suppliers. For Investors and Strategic Acquirers: Pending EU Feed Hygiene Regulation revision is the leading indicator that replacement demand will spike for certified suppliers with blockchain-verified chain-of-custody systems. Five-to-ten year viability favors precision nutrition technologists with environmental compliance bundling capabilities. Monitor ECHA approval timelines for novel methane-inhibiting additives as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | Regulatory moat creation locks out smaller competitors lacking ECHA toxicology expertise. |
| Precision Fermentation Scale-Up | Next-generation phytase engineering with thermostability coatings commands premium positioning. |
| Compound Feed Network Partnership | Volume-contracting access to Lower Saxony integrators secures multi-year offtake commitments. |
| Blockchain Traceability Deployment | Batch-level chain-of-custody systems preempt Federal Ministry enforcement penalties. |
| Digital Nutrition Platform Launch | Real-time dosing software paired with sensor monitoring enables subscription revenue models. |
Research Methodology
Document review covered EU regulatory filings, ECHA registration databases, and compound feed production statistics, complemented by interviews with plant managers at enzyme fermentation facilities, procurement leads at swine integrators, regulatory affairs directors, and technical service specialists at additive formulators. Secondary validation drew from Federal Ministry of Food and Agriculture enforcement reports, customs trade data, and SEC filings of multinational suppliers. Bottom-up volume estimates triangulated against top-down market sizing.
Segmentation outputs across product type, end-user species, functionality tier, and geographic production cluster informed the analytical framework over the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory enforcement intensity and integrator consolidation patterns. Industry-specific inputs included phytase inclusion rate trends and nitrogen-excretion compliance adoption curves.
The model holds under stable REACH approval timelines and continued EU Green Deal enforcement; deviation in ECHA backlog clearance or fertilizer ordinance phosphorus limit revisions would shift enzyme demand trajectories. Practitioners should monitor Federal Ministry residue monitoring expansion and pending Feed Hygiene Regulation amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Italy Food Acidulants Market