
 Bulking Agents Market | 2026-2036
Bulking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Bulking Agents Market Analysis
North American specialty ingredient production is consolidating as wheat and corn processors expand modified starch and maltodextrin capacity for downstream food clients. Ingredion Incorporated leverages its wet-milling infrastructure across the Midwest to supply consistent modified starch grades to bakery and dairy formulators. Cargill, Incorporated anchors regional supply through backward integration into corn refining, while Roquette Frères competes from its European base with pea-derived specialty starches.
Bulking agents are functional additives that increase product volume, improve texture, and reduce caloric density without altering taste profiles, typically comprising polysaccharides such as starch, cellulose, or inulin with particle sizes engineered between 10 and 150 microns for uniform dispersibility. Powdered cellulose dominates pharmaceutical tableting due to its inertness and compressibility, while liquid maltodextrin gains share in sports nutrition beverages where rapid solubility matters. Inulin occupies a premium niche in nutraceutical gummies and dairy alternatives, commanding higher margins as prebiotic positioning differentiates finished products.
FDA food additive regulations and EFSA novel food assessments shape which bulking agents achieve broad commercial approval, with cellulose derivatives holding GRAS status in the United States and inulin requiring individual safety dossiers in Europe. REACH chemical registration thresholds in the European Union constrain synthetic bulking agent introductions, while India's FSSAI additive schedules limit which starch modifications enter packaged food channels. Stakeholders must monitor evolving clean-label definitions across FDA, EFSA, and FSSAI jurisdictions to anticipate which plant-derived bulking technologies will secure regulatory clearance ahead of competitor filings.
Market Dynamics
Clean-label reformulation pressures are restructuring procurement patterns as food manufacturers abandon synthetic fillers for plant-derived cellulose and inulin alternatives to satisfy tightening disclosure requirements.
Growth Catalysts
- FDA added-sugar labeling rules:North American bakery and dairy formulators are expanding modified starch and maltodextrin procurement to maintain volume while reducing sugar declarations on nutrition panels.
- Sports nutrition beverages:Liquid maltodextrin demand is accelerating as fitness-focused brands prioritize rapid solubility in ready-to-drink protein formulations.
- Germany:EFSA novel food approvals and REACH chemical safety standards are pushing European reformulation toward pea-derived specialty starches and inulin prebiotic positioning.
Market Restraints
- Corn and wheat input volatility:Modified starch producers face margin compression from agricultural commodity price swings across Midwest grain belts.
- European supply concentration:REACH registration thresholds constrain synthetic bulking agent introductions, limiting new market entrants to well-capitalized incumbents with dossier resources.
- Particle size engineering costs:Achieving uniform 10-150 micron dispersibility requires capital-intensive milling infrastructure that smaller compounders cannot access.
Strategic Opportunities
- India:FSSAI additive schedule revisions are opening packaged food channels for novel starch modifications previously excluded from formal retail.
- Nutraceutical gummies:Inulin's prebiotic positioning commands premium margins in functional confectionery, creating white space for differentiated dairy alternative formulations.
- Pharmaceutical tableting:Powdered cellulose demand is expanding beyond food into drug delivery as compressibility and inertness specifications tighten.
Industry Challenges
- Clean-label definition divergence:FDA, EFSA, and FSSAI jurisdictions maintain inconsistent standards for what constitutes acceptable plant-derived bulking, forcing multi-territory formulators to maintain parallel specification sheets.
- Novel food dossier timelines:EFSA safety assessments for inulin variants extend 18-24 months, delaying product launches and tying up regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulking Agents Market |
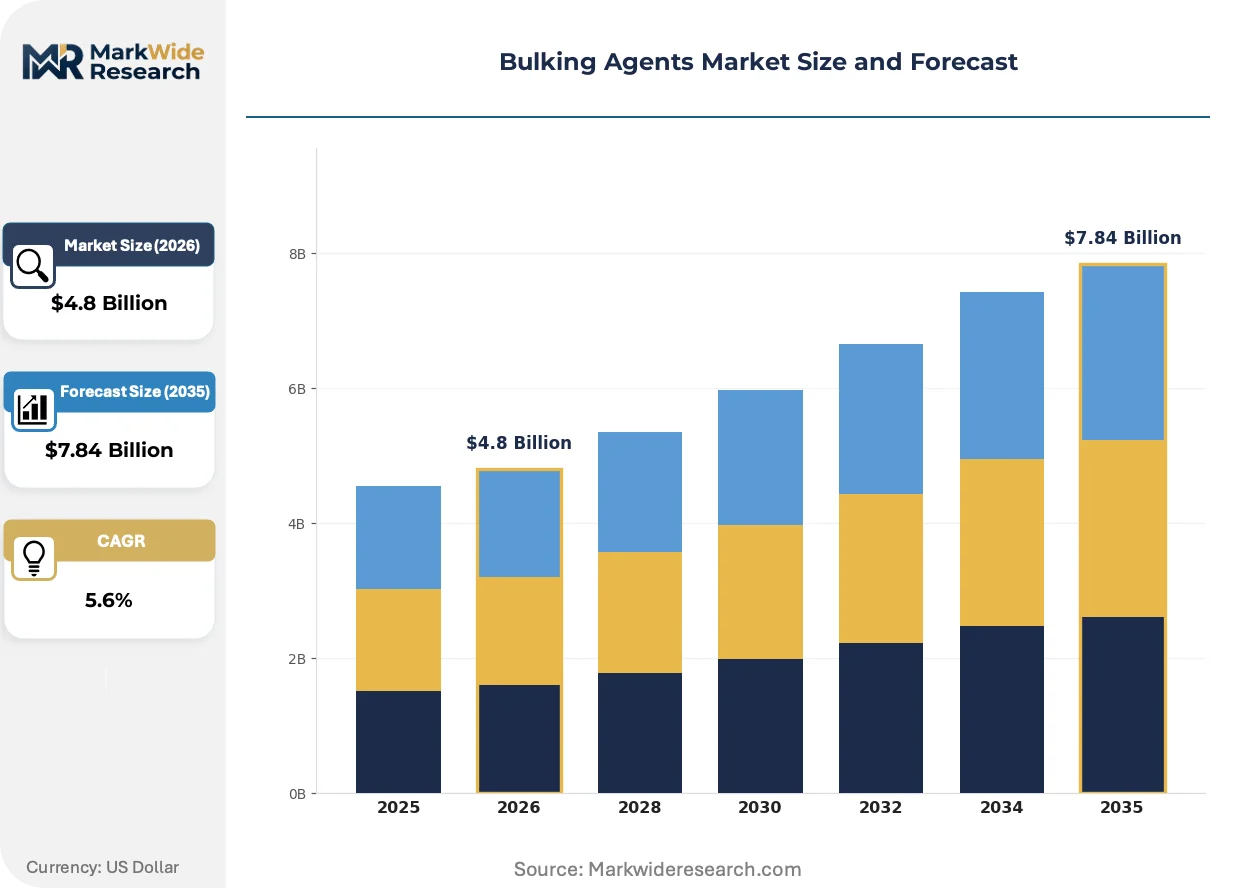
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Cellulose, Maltodextrin, Inulin Application: Food, Pharmaceuticals, Cosmetics, Agriculture Form: Powder, Granules, Liquid, capsules End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Nutraceuticals |
| Companies Covered | Ingredion Incorporated, Cargill, Incorporated, Archer Daniels Midland Company, DuPont Nutrition & Biosciences, BEHN MEYER, Symrise, CP Kelco, Roquette Frères, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulking Agents Market Emerging Trajectories
Automation of particle engineering and real-time quality monitoring is compressing development cycles for custom bulking grades, while regulatory divergence between major jurisdictions forces simultaneous multi-track approval strategies.
Precision milling technology is automating particle size distribution control for cellulose derivatives, enabling pharmaceutical tablet manufacturers to achieve tighter compressibility specifications without batch-to-batch variation. Wet-milling infrastructure operators are retrofitting sensor arrays to capture real-time granularity data, reducing specification drift and reprocessing rates. This automation is compressing the competitive advantage of manual quality-control-dependent compounders.
REACH chemical registration thresholds in the European Union are constraining synthetic bulking agent introductions while accelerating plant-derived alternatives through EFSA's novel food pathway. Industrial consequence includes reformulation bottlenecks as manufacturers await dossier approvals for modified starches with new acetylation profiles. German and French food technologists are responding by pre-submission engagement with EFSA scientific panels to compress assessment timelines.
Direct procurement relationships between bakery chains and specialty starch producers are disintermediating traditional ingredient distributors, with volume buyers demanding custom viscosity grades and just-in-time delivery guarantees. This channel compression is most visible in North American Midwest manufacturing clusters where Cargill and Ingredion maintain captive wet-milling capacity. Smaller regional bakeries lacking procurement scale remain dependent on distributor networks with limited technical support.
Bulking Agents Market Segmentation
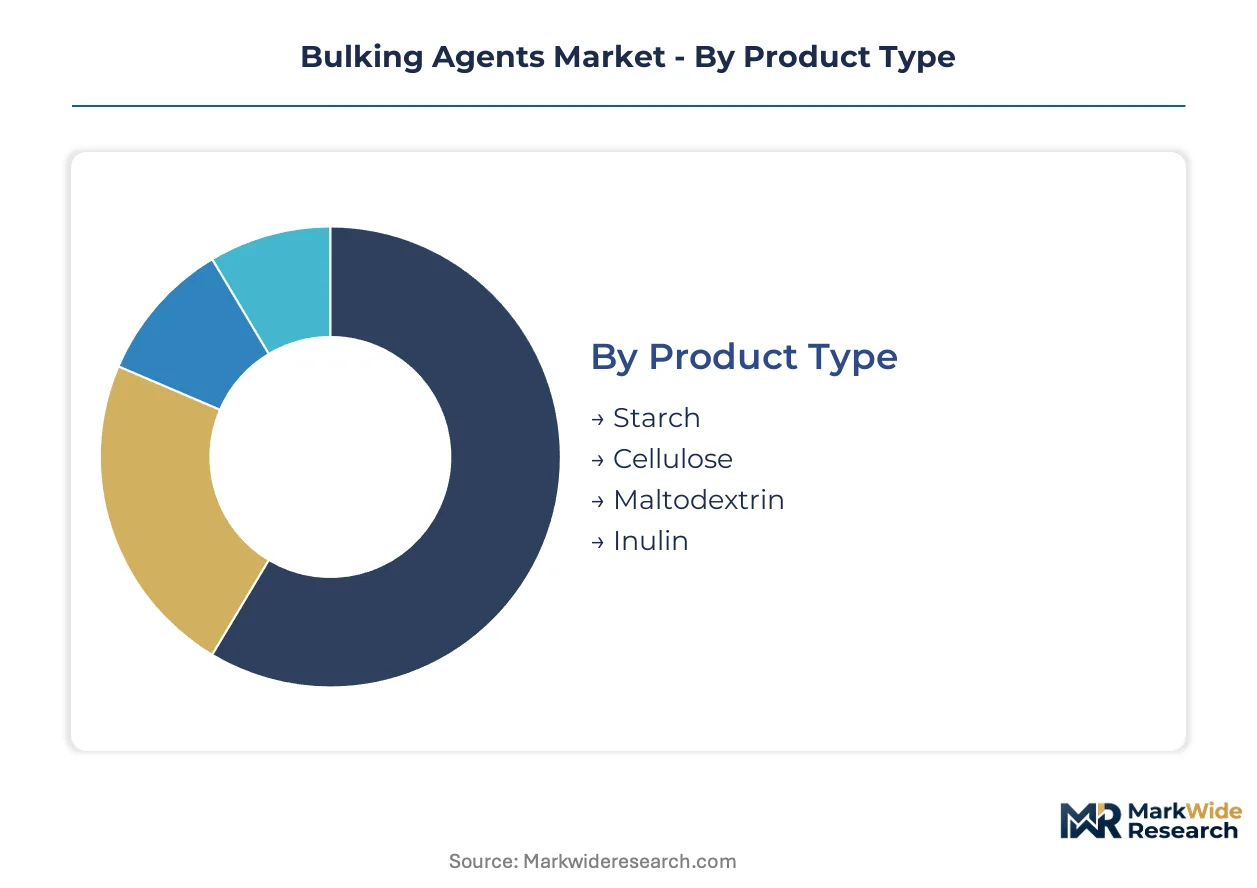
Bulking agent procurement patterns diverge sharply across product chemistry and downstream application, with modified starches commanding scale economics while cellulose derivatives capture specification premiums. Form factor and end-user concentration further stratify supplier relationships, as pharmaceutical compressibility requirements and food clean-label mandates create non-overlapping competency zones.
Product Type:
Supply concentration clusters around wet-milled corn and wheat derivatives where Midwest grain processors maintain captive starch capacity, while specialty cellulose production concentrates among pulp-refining specialists with particle engineering infrastructure.
- Starch:Modified corn and wheat starches dominate volume procurement through enzymatic and acid-thinning processes that tailor viscosity for bakery and dairy applications. Midwest wet-milling clusters in the United States supply consistent grades to North American food manufacturers reformulating under FDA added-sugar disclosure rules.
- Cellulose:Powdered cellulose engineered to 10-150 micron specifications serves pharmaceutical tableting for its inertness and compressibility, with demand concentrating among German and French drug manufacturers facing EMA stability requirements. REACH registration thresholds constrain new synthetic entrants, entrenching established pulp-derived suppliers.
- Maltodextrin:Enzymatically hydrolyzed starch syrup solids with dextrose equivalence ratings between 3 and 20.
- Inulin:Chicory-root-derived fructan requiring EFSA novel food dossiers for new extraction variants.
Starch absorbs the bulk of installed capacity; cellulose is expanding most quickly.
Application:
Cost tier stratification separates commodity food volume from pharmaceutical specification premiums, with cosmetics and agriculture occupying intermediate value positions.
- Food:Bakery, dairy, and beverage formulators deploy modified starches and maltodextrins to maintain mouthfeel while reducing sugar declarations. German clean-label reformulation under EFSA scrutiny accelerates pea-derived specialty starch adoption.
- Pharmaceuticals:Tablet manufacturers specify microcrystalline cellulose for direct compression and disintegration control, with United States FDA GRAS status enabling faster qualification than European novel food pathways.
- Cosmetics:Powdered cellulose and starch derivatives function as talc replacements in pressed powders and dry shampoos.
- Agriculture:Granular carriers for active ingredients in pesticide and fertilizer formulations.
Food commands the largest revenue base; pharmaceuticals sustain the steepest margin expansion.
Form:
Volume throughput favors powder handling infrastructure, while liquid and encapsulated formats require differentiated dissolution engineering.
- Powder:Spray-dried and roller-dried starches with controlled particle size distribution dominate bulk handling systems. United States bakery chains specify powder grades for silo-fed continuous mixing operations.
- Liquid:Maltodextrin syrups and hydrolyzed starch solutions serve ready-to-drink sports nutrition where rapid solubility eliminates clumping. Fitness-focused brands in Germany prioritize liquid concentrate logistics.
- Granules:Agglomerated starch products for controlled-release pharmaceutical applications.
- Capsules:Pre-metered cellulose and inulin doses for nutraceutical single-serve positioning.
Powder moves the highest tonnage; liquid is gaining share fastest in functional beverages.
End User:
Customer type determines technical service intensity, with pharmaceutical companies demanding batch certification and food manufacturers prioritizing supply security.
- Food Manufacturers:Large bakery and dairy processors negotiate direct procurement relationships bypassing distributors, demanding custom viscosity grades and just-in-time delivery from Midwest wet-milling operations. FDA labeling compliance drives reformulation toward plant-derived alternatives.
- Pharmaceutical Companies:Drug developers specify cellulose compressibility profiles and inertness certificates for tablet stability testing under EMA and FDA chemistry, manufacturing, and controls guidelines.
- Cosmetic Brands:Clean-label positioning drives talc replacement with rice and oat starches.
- Nutraceuticals:Gummy and soft-chew manufacturers specify inulin for prebiotic marketing claims.
Food manufacturers absorb the majority of procurement volume; nutraceuticals show the fastest contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn and wheat belt concentration in the United States Midwest anchors global modified starch supply chains, while European regulatory stringency and Asian manufacturing scale create distinct regional procurement patterns.
United States
Midwest wet-milling clusters around Iowa and Illinois supply modified starches to bakery chains reformulating under FDA added-sugar disclosure rules. The FDA GRAS framework enables faster qualification of cellulose derivatives than European novel food pathways. Ingredion and Cargill maintain captive refining infrastructure across the Corn Belt to serve direct procurement relationships with national food manufacturers.
Germany
EFSA novel food assessments and REACH chemical registration thresholds push reformulation toward plant-derived cellulose and inulin alternatives. German pharmaceutical tablet manufacturers specify microcrystalline cellulose compressibility profiles under EMA stability guidelines. The country's food technologists engage pre-submission with EFSA scientific panels to compress assessment timelines for modified starches with new acetylation profiles.
India
FSSAI additive schedule revisions are opening packaged food channels for novel starch modifications previously excluded from formal retail. Maharashtra and Gujarat host expanding maltodextrin production serving domestic sports nutrition brands. The central food regulator's evolving clean-label definitions create compliance complexity for multi-territory formulators maintaining parallel specification sheets.
China
SAMR food additive regulations and GB standards shape which starch modifications achieve broad commercial approval in the world's largest processed food market. Yangtze River Delta manufacturing clusters concentrate spray-dried starch capacity for regional bakery and dairy clients. The country's national pharmaceutical regulator maintains separate dossier requirements for cellulose excipients used in drug export versus domestic consumption.
Brazil
ANVISA additive regulations limit which modified starches enter packaged food channels, creating reformulation bottlenecks for multinational manufacturers. São Paulo state anchors South American specialty ingredient distribution, with regional bakeries dependent on distributor networks lacking technical support. The country's agricultural commodity volatility affects corn input costs for domestic starch processors.
Bulking Agents Market Vendor Landscape
Global majors compete with regional champions across wet-milling infrastructure and particle engineering capabilities. The market structures around three tiers: multinational grain processors with captive refining capacity, European specialty starch specialists with novel food dossier expertise, and regional compounders serving distributor-dependent smaller manufacturers. Two dominant competitive moves define positioning: backward integration into corn and wheat refining to secure input cost stability, and direct procurement relationships that disintermediate traditional ingredient distributors.
Within the multinational grain processor tier, Ingredion Incorporated and Cargill, Incorporated exemplify scale-driven positioning through Midwest wet-milling infrastructure. Roquette Frères occupies a specialist position among European champions with pea-derived starch capabilities. These three anchors represent distinct geographic and feedstock strategies: United States-based corn refining, diversified North American grain processing, and European plant-protein specialization.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| DuPont Nutrition & Biosciences |
| BEHN MEYER |
| Symrise |
| CP Kelco |
| Roquette Frères |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Midwest bakery chains negotiating direct procurement contracts with wet-milling operators command volume-based pricing leverage unavailable to smaller regional formulators dependent on distributor markups. This buyer concentration creates a bifurcated pricing landscape where contract scale determines access to custom viscosity grades and just-in-time delivery guarantees.
Pricing Analysis
Technical service bundling separates contract structures in the bulking agents market, with pharmaceutical buyers paying premiums for batch certification and compressibility documentation while food manufacturers prioritize unbundled commodity pricing. Three-tier pricing structure across pharmaceutical specification, food-grade standard, and industrial economy levels reflects certification burden and particle engineering precision. Cost compression in modified starch grades is intensifying because agricultural commodity volatility squeezes processor margins. Food manufacturers exhibit highest price sensitivity due to reformulation volume pressures, while pharmaceutical tablet developers accept premium positioning for EMA stability compliance.
Supply Chain Analysis
Return flows of off-specification cellulose derivatives for re-milling create circular material loops that established pulp-refining specialists exploit for yield optimization. Supply concentrates in the United States Midwest corn belt, Germany's industrial corridor, and India's Gujarat processing clusters. Production draws from corn and wheat feedstocks, chicory root for inulin extraction, and specialty pulp for cellulose derivatives. Single-source vulnerability runs through Midwest wet-milling infrastructure where drought conditions disrupt input availability. Distribution runs through direct procurement relationships disintermediating traditional ingredient distributors for volume buyers, while smaller compounders remain tethered to regional distributor networks with limited technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as REACH registration thresholds and EFSA novel food dossier requirements force capital-constrained regional compounders toward exit or acquisition. Regulatory compliance burden functions as the primary mechanism clearing weaker competitors from contested segments.
For Market Incumbents: Lock in backward integration into corn refining to secure input cost stability against agricultural commodity swings. Prioritize captive wet-milling capacity expansion across Iowa and Illinois manufacturing clusters. Defend market position by pre-submission engagement with EFSA scientific panels to compress assessment timelines for modified starch variants, creating regulatory velocity that smaller competitors cannot match.
For New Entrants and Emerging Players: The premium-economy price gap in pharmaceutical-grade cellulose creates entry space for specialized particle engineering specialists. Target nutraceutical gummy manufacturers in Germany seeking prebiotic-positioned inulin alternatives with faster qualification than EFSA novel food pathways permit. Pursue white-label contract manufacturing relationships with Midwest bakery chains lacking technical R&D infrastructure.
For Investors and Strategic Acquirers: The window for entry favors European specialty starch specialists with established EFSA dossier resources and pea-derived processing capabilities. Long-term viability centers on regulatory clearance velocity rather than production scale alone. Monitor EFSA novel food approval timelines as the critical inflection signal distinguishing acquisition targets with pathway advantages from stranded asset risks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Refining | Captive wet-milling infrastructure in Iowa and Illinois secures input cost stability against commodity volatility. |
| EFSA Pre-Submission Engagement | Early scientific panel consultation compresses novel food assessment timelines for modified starch variants. |
| Particle Engineering Automation | Precision milling technology enables pharmaceutical-grade cellulose specifications without batch variation. |
| Direct Procurement Relationship Development | Bypassing distributors captures margin from Midwest bakery chains demanding custom viscosity grades. |
| Pea-Derived Specialty Starch Capacity | Plant-protein processing infrastructure addresses German clean-label reformulation under EFSA scrutiny. |
Methodological Framework
Independent corroboration across FDA GRAS notification filings, EFSA novel food register entries, and FSSAI additive schedule revisions underwrites the qualitative findings in this analysis. Primary interviews with plant managers at Midwest wet-milling operations, procurement leads at North American bakery chains, regulatory affairs directors navigating EFSA dossier preparation, and technical R&D specialists developing cellulose compressibility profiles combined with secondary validation from customs trade data, SEC 10-K disclosures of grain processors, and chemical industry association reports. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical FDA labeling rule implementation and EFSA assessment completion patterns established the forecast reference framework. Segmentation modeling across product chemistry, application vertical, form factor, and end-user concentration dimensions structured volume and value outputs across the analysis window. CAGRs were derived from elasticity-adjusted demand projections incorporating reformulation response rates to regulatory disclosure requirements and sports nutrition beverage formulation trends.
Inputs from EFSA novel food register updates and FSSAI schedule revision notices were available through the study window; gaps in real-time proprietary procurement contract terms introduce uncertainty bands around price elasticity assumptions. Forecasts reflect documented assumptions regarding regulatory clearance timelines and agricultural commodity input stability. Practitioners should monitor EFSA scientific panel queue lengths and Midwest drought severity indices for early signals of timeline compression or input cost disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Alpha-Amylase Baking Enzyme Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
South Africa Food Enzymes Market