
 India Masking Tapes Market | 2026-2036
India Masking Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
India Masking Tapes Market Foresight
Gujarat-based petrochemical feedstock producers is broadening the domestic substrate supply for tape manufacturers. Pidilite Industries leverages its adhesive formulation heritage to dominate consumer and industrial channels. 3M India sustains technology leadership through precision-coated products serving automotive OEMs. Tesa Tapes India Pvt. Ltd. anchors its position with specialized solutions for electronics assembly and paint masking applications.
Masking tapes are pressure-sensitive adhesive tapes engineered with crepe paper, PVC, or polyester backings typically rated for temperature resistance between 60°C and 180°C, designed primarily to protect surfaces during painting, coating, and assembly operations. Paper masking tapes occupy the mature volume segment, while silicone-adhesive polyester variants command premium positioning in automotive and electronics thermal masking. Acrylic adhesive formulations are gaining fastest in building and construction, where clean removal and UV stability differentiate contractor-grade offerings.
BIS standards govern tensile strength and adhesion metrics for industrial tapes sold in India, while CEA electrical safety codes shape insulation-grade product requirements in power infrastructure applications. The PLI scheme for specialty chemicals indirectly supports domestic adhesive raw material capacity, altering import dependency for tape manufacturers. Stakeholders must monitor evolving automotive paint-shop specifications and state-level construction certification norms to align product development with procurement gatekeeping.
Market Dynamics
Automotive OEMs in Maharashtra and Gujarat are consolidating masking tape specifications around silicone-adhesive polyester substrates, compressing supplier qualification timelines and reshaping procurement volumes toward certified domestic manufacturers.
Growth Catalysts
- PLI Scheme for Specialty Chemicals:Domestic adhesive raw material capacity is expanding, reducing import dependency for tape manufacturers serving automotive and electronics sectors.
- Automotive Refinishing Expansion:Collision repair networks and OEM paint shops in Pune and Chennai are standardizing on high-temperature masking tapes rated above 150°C.
- BIS Certification Mandates:Tighter tensile strength and adhesion standards for industrial tapes are filtering out uncertified suppliers and concentrating procurement among qualified manufacturers.
Market Restraints
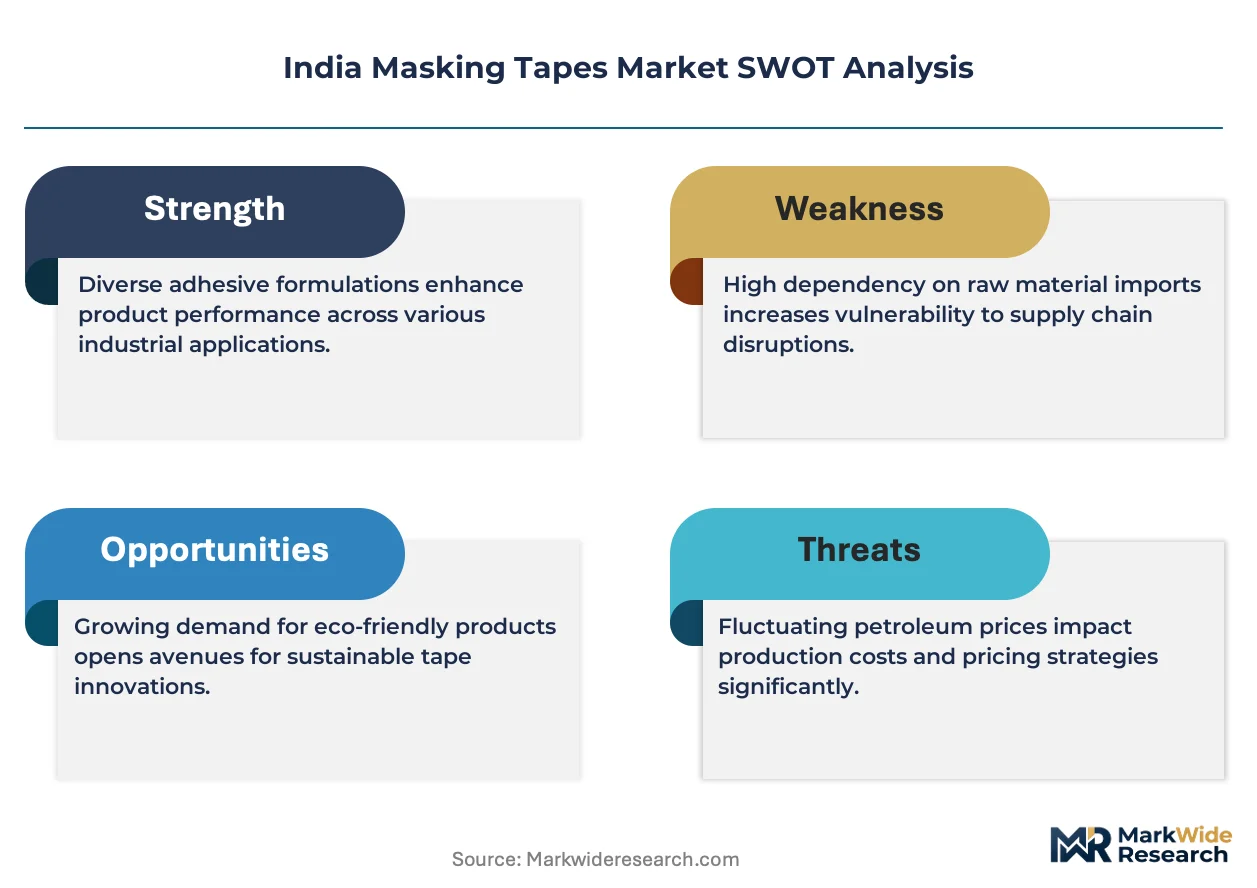
- Petrochemical Feedstock Volatility:Polyester film and silicone adhesive precursor costs fluctuate with crude-linked aromatics pricing, compressing margins for mid-tier tape converters.
- Import Concentration in Specialty Substrates:High-performance crepe paper and precision-coated films remain concentrated among Korean and Japanese suppliers, exposing domestic manufacturers to currency and logistics risk.
- Temperature-Performance Trade-offs:Acrylic adhesive formulations lack the thermal ceiling of silicone alternatives, limiting their penetration in automotive thermal masking above 120°C.
Strategic Opportunities
- Kerala and Tamil Nadu Electronics Clusters:PCB assembly and semiconductor packaging facilities are creating demand for clean-room compatible masking tapes with ultra-low residue.
- Green Building Certification Uptake:IGBC and GRIHA-rated construction projects are specifying low-VOC masking tapes for interior finishing, opening premium contractor-grade segments.
- Water-Based Adhesive Convergence:Solvent-free coating technologies are aligning with state pollution control mandates while reducing hazardous material handling costs.
Industry Challenges
- Adhesive Formulation Talent Scarcity:Polymer chemistry and coating engineering expertise concentrates among legacy industrial adhesive firms, constraining new entrant R&D velocity.
- BIS Testing Timeline Compression:Certification cycles for new tape grades extend 8-14 months, delaying product launches against faster-moving specification changes.
- Legacy Equipment Retrofit Costs:Converting lines for thinner, higher-temperature substrates requires precision tension control upgrades that strain mid-capitalization manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Masking Tapes Market |
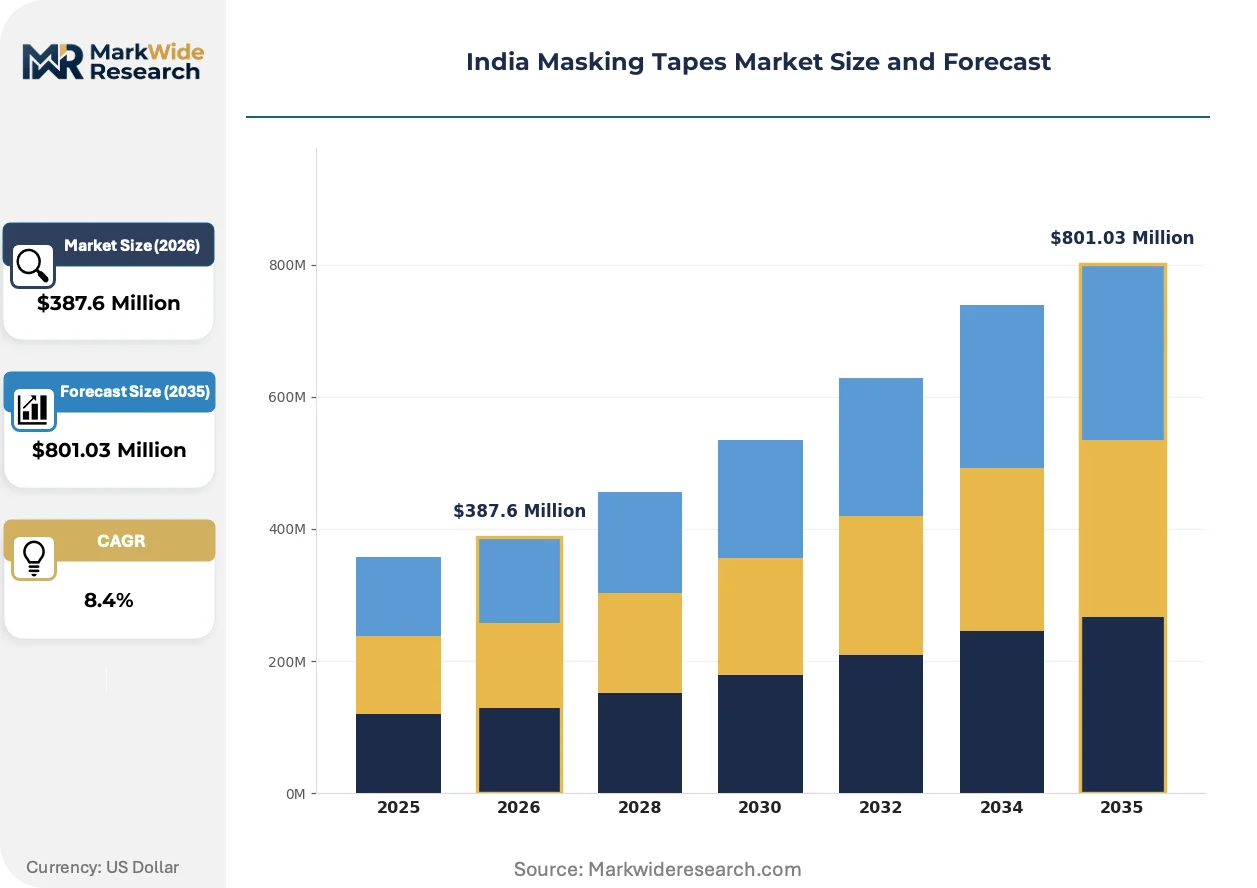
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream Masking Tapes, Paper Masking Tapes, PVC Masking Tapes, Polyester Masking Tapes End User: Building & Construction, Automotive, Electronics, Food & Beverage Adhesive Type: Rubber-Based Adhesives, Acrylic Adhesives, Silicone Adhesives, Hot Melt Adhesives Thickness: Thin Tapes, Medium Tapes, Thick Tapes, Extra Thick Tapes |
| Companies Covered | Pidilite Industries, Berger Paints, 3M India, Lohmann Adhesive Tapes India Pvt. Ltd., Asian Paints, Nitto Denko India Private Limited, Ajit Industries Private Limited, Adhesive Specialties, Tesa Tapes India Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Masking Tapes Market Shifts & Advancements
Silicone-adhesive masking technologies are displacing conventional rubber-based formulations across temperature-critical applications, while regulatory pressure on volatile organic compounds is accelerating coating chemistry transitions.
Silicone adhesive systems with crepe paper backings rated to 180°C are expanding into automotive underhood masking and powder coating operations. Tier-1 suppliers in Pune and Manesar are qualifying these tapes for continuous 150°C exposure cycles. This migration is compressing demand for natural rubber adhesives in thermal applications above 120°C.
BIS IS 13262 standards for pressure-sensitive adhesive tapes are tightening peel adhesion and shear resistance benchmarks for industrial-grade products. Tape converters must reformulate acrylic and rubber adhesives to meet revised tensile strength minimums. Automotive OEMs in Maharashtra are requiring BIS-certified tapes for all paint-shop consumables, forcing supplier base rationalization.
Direct procurement relationships between automotive OEMs and certified tape manufacturers are displacing distributor-mediated purchasing in high-volume segments. Long-term supply agreements with fixed pricing and joint specification development are replacing spot-market buying. This pattern is most visible in Gujarat and Tamil Nadu, where anchor OEM plants are consolidating vendor lists to under ten qualified masking tape suppliers.
India Masking Tapes Market Segmentation
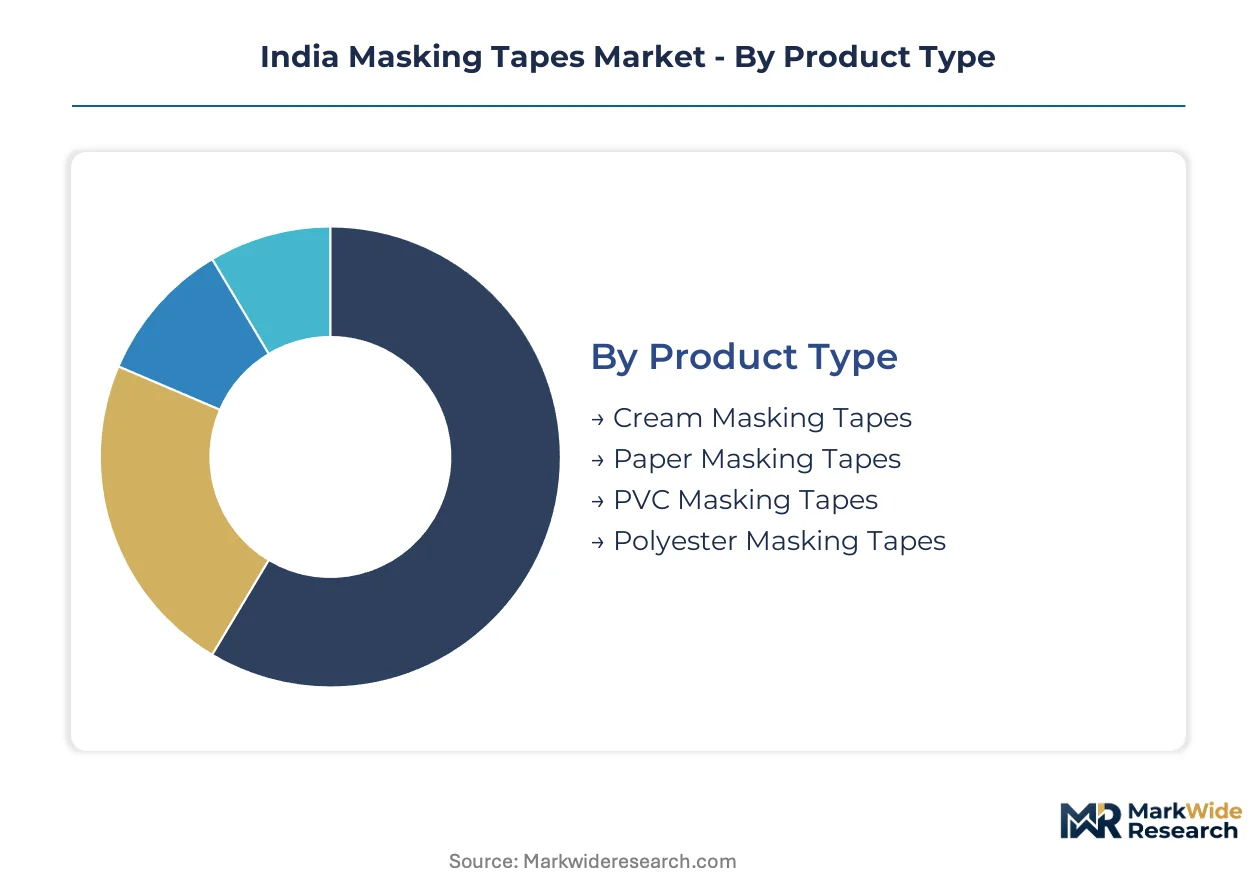
Segmentation in the India masking tapes market reveals how certification requirements, thermal specifications, and end-use complexity fragment procurement patterns across adhesive chemistry and substrate combinations. Manufacturers must align product portfolios with BIS mandates and sector-specific performance thresholds to qualify for automotive OEM and electronics assembly contracts.
Product Type:
BIS IS 13262 certification governs tensile strength and adhesion benchmarks differently across substrate categories, with silicone-compatible variants facing the most stringent thermal cycling tests.
- Paper Masking Tapes:Crepe paper backings with rubber or acrylic adhesive dominate volume in building and construction applications across Maharashtra and Gujarat. Clean removal properties and cost positioning anchor demand among residential painters and interior contractors in Pune and Ahmedabad, though thermal ceiling limitations restrict automotive penetration.
- Polyester Masking Tapes:Silicone-adhesive polyester substrates rated to 180°C command premium positioning in automotive underhood masking and powder coating operations. OEM paint shops in Chennai and Manesar are consolidating procurement around these tapes for continuous 150°C exposure cycles, displacing natural rubber alternatives above 120°C.
- PVC Masking Tapes:Flexible vinyl backings serve electrical insulation and general-purpose bundling where moisture resistance outweighs thermal demands.
- Cream Masking Tapes:Specialized variants for delicate surface protection in furniture and appliance finishing, emphasizing residue-free removal.
Leading the category by volume: Paper Masking Tapes. Growing fastest: Polyester Masking Tapes.
End User:
Customer procurement sophistication varies sharply, with automotive and electronics buyers demanding joint specification development while construction segments prioritize distributor availability and price.
- Automotive:OEM paint shops and collision repair networks in Maharashtra and Tamil Nadu specify high-temperature masking tapes above 150°C. Direct procurement relationships with certified manufacturers are displacing distributor channels, with vendor lists consolidating to under ten qualified suppliers per anchor plant.
- Electronics:PCB assembly and semiconductor packaging facilities in Kerala and Tamil Nadu require clean-room compatible tapes with ultra-low residue. Silicone-adhesive polyester variants dominate thermal masking for reflow soldering and conformal coating operations.
- Building & Construction:IGBC and GRIHA-rated projects in Gujarat and Karnataka are specifying low-VOC masking tapes for interior finishing, opening premium contractor-grade segments.
- Food & Beverage:Limited penetration confined to packaging line maintenance and temporary surface protection during equipment sanitation.
Automotive generates the highest revenue per unit. Electronics shows the steepest expansion trajectory.
Adhesive Type:
Formulation chemistry determines temperature ceiling, removal cleanliness, and regulatory compliance cost, with water-based acrylics gaining ground against solvent-borne rubber systems under state pollution control mandates.
- Silicone Adhesives:Polysiloxane-based systems withstand continuous 180°C exposure while maintaining clean removal, essential for automotive powder coating and electronics thermal masking. PLI scheme support for domestic specialty chemicals is expanding indigenous precursor capacity, reducing import dependency for tape manufacturers.
- Acrylic Adhesives:UV-stable formulations with clean removal properties are gaining fastest in building and construction, where contractor-grade positioning emphasizes residue-free performance on painted drywall and trim.
- Rubber-Based Adhesives:Natural and synthetic rubber systems retain cost advantage in general-purpose applications below 120°C, though thermal limitations are compressing automotive share.
- Hot Melt Adhesives:Thermoplastic formulations serve high-speed converting operations and temporary holding applications where repositionability matters less than initial tack.
Silicone Adhesives anchor premium positioning. Acrylic Adhesives are climbing the fastest.
Thickness:
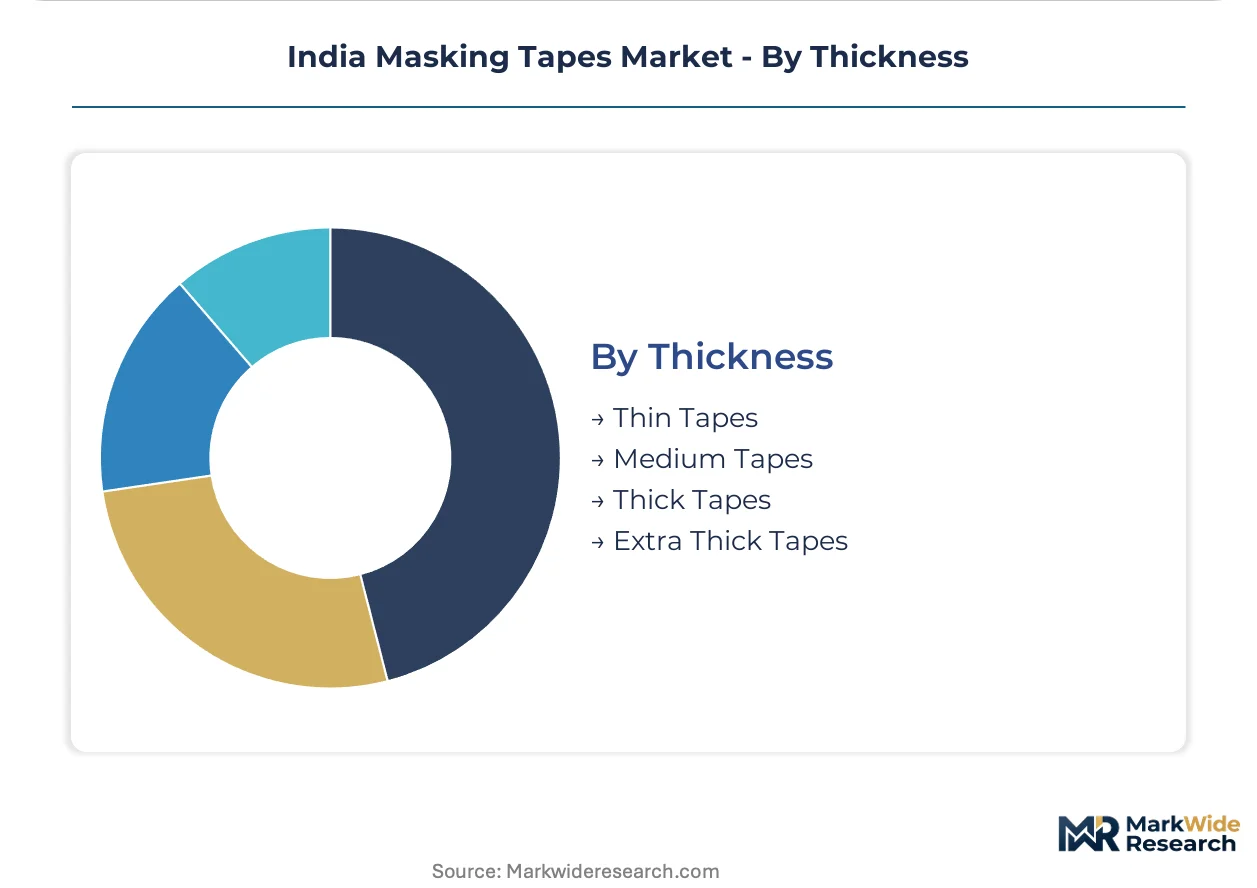
Calender control precision and substrate gauge determine conformability around complex geometries versus structural rigidity for straight-line masking.
- Medium Tapes:Balanced caliper specifications dominate general industrial procurement, offering sufficient body for clean edge definition without excessive bulk in automotive paint masking.
- Thin Tapes:Low-profile gauges serve electronics assembly and precision coating where minimal step height and tight radius conformability are critical.
- Thick Tapes:Heavier constructions provide cushioning and gap-filling in rough surface applications and heavy-duty holding.
- Extra Thick Tapes:Specialized foam-backed variants for severe contour masking and vibration damping in transportation equipment.
Medium Tapes carry the volume base. Thin Tapes are gaining share fastest in electronics penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in Gujarat anchors substrate supply for tape manufacturers serving western India. Domestic adhesive precursor capacity is expanding under PLI scheme incentives, reducing import dependency for converters in Maharashtra and Tamil Nadu.
Maharashtra
Automotive OEM paint shops in Pune and Chakan drive demand for silicone-adhesive polyester tapes rated above 150°C. BIS IS 13262 certification mandates are filtering supplier lists to under ten qualified manufacturers per anchor plant. The Mumbai-Pune industrial corridor concentrates procurement volumes for collision repair networks and refinishing operations.
Gujarat
Petrochemical complexes in Vadodara and Hazira supply polyester film and silicone adhesive precursors to domestic tape converters. State pollution control mandates are accelerating water-based coating technology adoption among manufacturers in Ahmedabad and Surat. Chemical manufacturing clusters anchor backward integration opportunities for mid-tier producers.
Tamil Nadu
Electronics assembly facilities in Sriperumbudur and Oragadam require clean-room compatible masking tapes with ultra-low residue for PCB operations. CEA electrical safety codes shape insulation-grade product specifications for power infrastructure applications. Chennai-based automotive plants are consolidating procurement around BIS-certified thermal masking suppliers.
Karnataka
IGBC-rated construction projects in Bengaluru are specifying low-VOC masking tapes for interior finishing applications. The state's electronics manufacturing policy is attracting semiconductor packaging facilities with demand for precision thermal masking. Contractor-grade acrylic adhesive tapes are gaining share in residential and commercial building segments.
Kerala
PCB assembly operations in Kochi and Thiruvananthapuram are creating niche demand for thin-gauge polyester masking tapes. State-level pollution control mandates are pressuring converters toward solvent-free coating technologies. Electronics clusters are prioritizing residue-free removal properties for conformal coating and reflow soldering applications.
India Masking Tapes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty adhesive formulations and electronics-grade certifications. The vendor base stratifies between integrated chemical conglomerates with captive feedstock access and independent converters dependent on imported substrates. Three archetypes dominate: petrochemical-integrated manufacturers, precision coating specialists, and construction-focused distributors. Competitive dynamics center on BIS certification velocity and long-term supply agreement negotiation with automotive anchor plants.
Within the integrated chemical tier, Pidilite Industries and Asian Paints represent domestic formulation heritage extending into industrial adhesive channels. Among precision coating specialists, 3M India and Tesa Tapes India Pvt. Ltd. exemplify technology-led positioning serving OEM specification requirements. Nitto Denko India Private Limited occupies a position bridging electronics assembly expertise with automotive thermal masking applications.
| Leading Market Players |
|---|
| Pidilite Industries |
| Berger Paints |
| 3M India |
| Lohmann Adhesive Tapes India Pvt. Ltd. |
| Asian Paints |
| Nitto Denko India Private Limited |
| Ajit Industries Private Limited |
| Adhesive Specialties |
| Tesa Tapes India Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Water-based adhesive coating transitions across Gujarat and Maharashtra converters are compressing production costs while concentrating procurement leverage among petrochemical-integrated manufacturers with captive silicone precursor supply. This dual shift rewards backward-integrated players with pricing power in premium thermal-masking tiers while squeezing margin structures for mid-tier converters dependent on imported specialty substrates.
Pricing Analysis
Warranty-backed BIS certification bundles separate qualified suppliers from spot-market converters, with certified manufacturers commanding sustained premiums for automotive OEM paint-shop contracts. Three-tier pricing structure across premium silicone-polyester, standard acrylic-paper, and economy rubber-based tiers tracks certification grade and volume commitment scale. Cost compression in the mid-tier intensifies because Korean and Japanese substrate suppliers maintain pricing discipline on high-performance crepe paper and precision-coated films. Contractor-grade construction buyers exhibit highest price sensitivity, while automotive thermal-masking procurement prioritizes specification compliance over unit cost.
Supply Chain Analysis
Scrap tape collection and substrate recycling flows remain underdeveloped across Indian converter operations, limiting circularity economics and intensifying virgin petrochemical dependency. Raw material sourcing draws from China for silicone adhesive precursors, South Korea for precision polyester films, and domestic Gujarat petrochemical complexes for commodity-grade substrates. Single-source vulnerability concentrates in high-temperature crepe paper grades where Japanese suppliers anchor global capacity. Distribution runs through authorized industrial distributors serving construction segments, while automotive and electronics buyers pursue direct manufacturer relationships with consolidated vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS IS 13262 certification timelines function as a structural moat, filtering supplier participation and concentrating margin capture among incumbents with established testing relationships and reformulation capabilities.
For Market Incumbents: Anticipate specification tightening in automotive thermal masking above 150°C by pre-qualifying next-generation silicone-polyester laminates with Pune and Chennai OEM paint shops. Defensive consolidation through captive adhesive precursor capacity under PLI scheme incentives neutralizes import cost volatility from Korean and Japanese substrate suppliers. For New Entrants and Emerging Players: The price-point gap between premium silicone-adhesive polyester and economy rubber-based paper tapes creates entry space for mid-tier acrylic formulations with enhanced UV stability and clean-removal properties. Kerala and Tamil Nadu electronics clusters offer the most penetrable geography, with clean-room compatible ultra-low-residue specifications still under-supplied by domestic converters. Go-to-market execution should anchor on distributor partnerships with established industrial supply houses serving PCB assembly facilities. For Investors and Strategic Acquirers: Re-rating potential sits with petrochemical-integrated manufacturers given PLI scheme acceleration of domestic specialty chemical capacity and BIS certification velocity advantages. Long-term viability over a multi-year horizon favors archetypes with backward integration into adhesive precursors and established automotive OEM direct procurement relationships. Monitor state-level pollution control mandate enforcement on solvent-based coating operations as an inflection indicator for water-based technology transition winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursors | PLI scheme incentives reduce import dependency for automotive thermal-masking tape manufacturers. |
| BIS Certification Velocity Investment | Compressed 8-14 month testing timelines filter supplier participation toward established reformulation capabilities. |
| Water-Based Coating Technology Transition | Gujarat and Maharashtra state pollution control mandates align solvent-free production with regulatory compliance cost reduction. |
| Long-Term Supply Agreement Negotiation | Automotive OEM anchor plants in Pune and Manesar consolidate vendor lists to under ten qualified masking tape suppliers. |
| Electronics-Grade Clean-Room Certification | Kerala and Tamil Nadu PCB assembly facilities create demand for ultra-low-residue silicone-polyester thermal masking. |
Research Methodology
Multi-period observation of BIS certification timeline compression, PLI scheme disbursement patterns, and automotive OEM vendor consolidation anchored the trend analysis, supplemented by interviews with adhesive formulation chemists, tape converting plant managers, automotive procurement leads at Maharashtra and Tamil Nadu anchor plants, and industrial distribution channel heads. Secondary validation drew from BIS notification records, CEA electrical safety code amendments, customs import data for silicone adhesive precursors, and specialty chemicals industry association capacity reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for industrial consumables demand.
Segment-weighting across adhesive chemistry, substrate material, end-use industry, and regional production cluster dimensions informed the analytical framework across the projection horizon. CAGRs were derived from elasticity modeling of automotive production volumes, electronics assembly capacity expansion, and construction certification uptake against tape consumption intensity coefficients. Industry-specific forecast inputs incorporated thermal specification migration curves in automotive paint shops and clean-room compatibility requirements in semiconductor packaging facilities.
Inputs from BIS testing laboratories and automotive OEM procurement departments were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around mid-tier manufacturer market share estimates. Forecasts reflect assumptions on PLI scheme continuation and state pollution control mandate enforcement trajectories. Practitioners should monitor BIS IS 13262 standard revision announcements and Korean-Japanese substrate supplier pricing actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Paper Masking Tapes Market
Tapes
Tear Tape Dispenser Market
Tapes
Filmic Tapes Market
Tapes
Sterilization Tape Market
Tapes
Custom Printed Tape Market
Tapes
Carry Handle Tape Market
Tapes
Heat Sealing Tape Market
Tapes
Aerospace Tapes Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Application Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Invisible Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Europe Packaging Tapes Market
Tapes
Aluminum Foil Tape Market
Tapes
PVC Tapes Market