
 Module-Level Power Electronics (MLPE) Market | 2026-2036
Module-Level Power Electronics (MLPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Module-Level Power Electronics (MLPE) Market Outlook
The EU Green Deal is expanding module-level monitoring mandates across member states, forcing inverter manufacturers to redesign for component-level data granularity. SolarEdge Technologies leverages its vertically integrated power optimizer and inverter platform to dominate European commercial rooftop retrofits. Enphase Energy sustains its microinverter architecture lead through installer channel density in North American residential markets. Tigo Energy differentiates via rapid shutdown compliance modules that retrofit onto legacy string inverter installations without full system replacement.
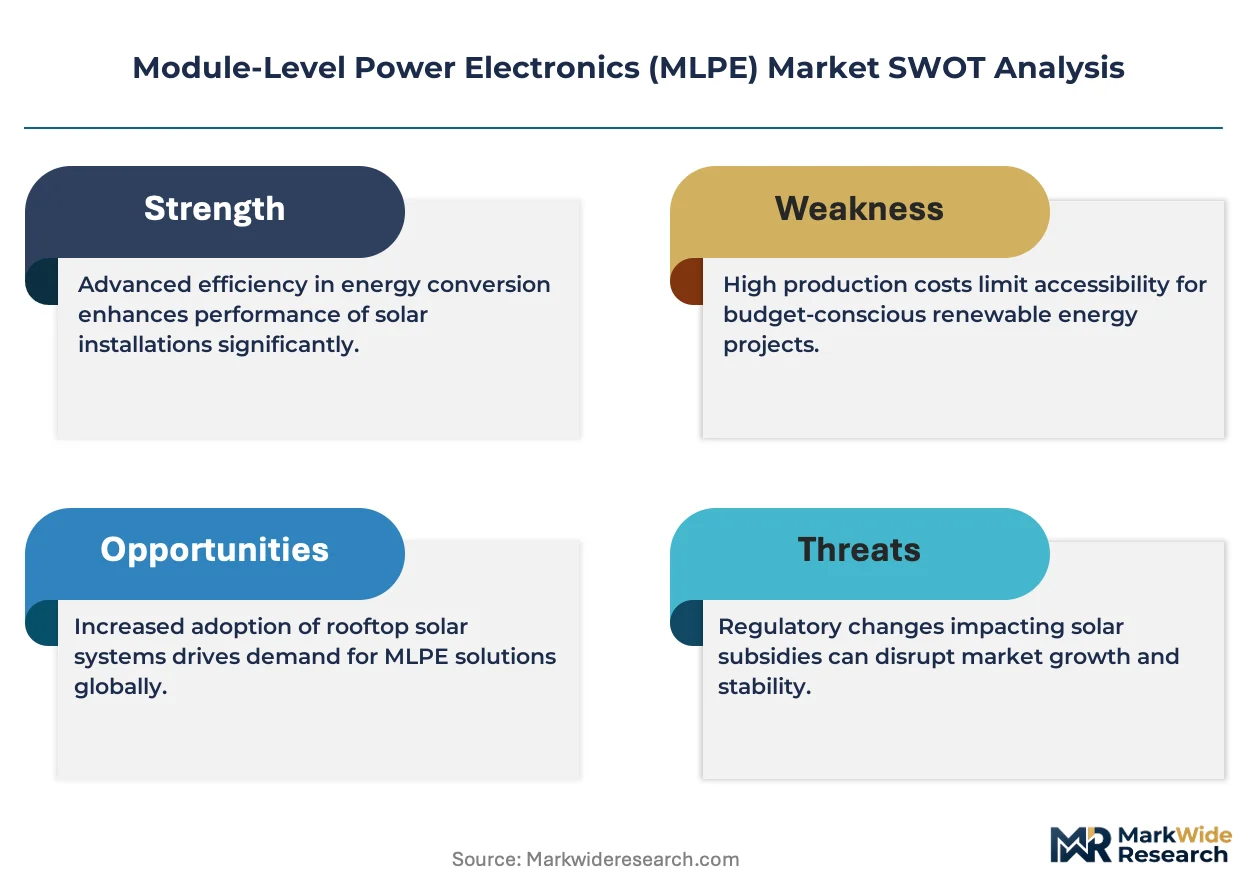
Module-Level Power Electronics encompasses semiconductor-based devices—microinverters, power optimizers, and rapid shutdown equipment—that convert or condition direct current from individual photovoltaic modules into grid-synchronous alternating current, typically operating at 200-480V output with maximum power point tracking precision below one percent deviation. The primary purpose is to maximize energy harvest per panel while enabling safety shutdown and granular performance diagnostics in distributed solar arrays. Microinverters command premium pricing in residential end user segments where shading complexity and fire code stringency elevate module-level architecture value over centralized alternatives. Power optimizers capture commercial and utility installation share by preserving string inverter capital efficiency while adding panel-level monitoring and shutdown capability. Battery ready technology within the product type dimension is accelerating fastest as solar-plus-storage configurations become standard in new rooftop and ground-mounted deployments.
FERC Order 2222 in the United States enables aggregated distributed energy resources to participate in wholesale markets, directly elevating the value proposition of module-level telemetry and control interfaces. California Title 24 building energy standards and the National Electrical Code rapid shutdown provisions collectively reshape product certification requirements, compelling manufacturers to obtain UL 1741-SA certification for grid support functionality. Germany's Bundesnetzagentur network codes and Australia's Clean Energy Council inverter listing requirements impose parallel technical barriers to market access. Stakeholders must monitor evolving interconnection standards that increasingly mandate reactive power capability and frequency-watt control at the module or string level rather than solely at the point of common coupling.
Market Dynamics
Rapid shutdown compliance mandates from the National Electrical Code are forcing wholesale inverter replacements across existing rooftop solar fleets, compressing replacement cycles and elevating module-level architecture over centralized alternatives.
Growth Catalysts
- California Title 24 Standards:Building energy codes mandate solar-plus-storage readiness in new construction, expanding addressable market for battery-ready power electronics.
- Residential Shading Complexity:Rooftop geometry constraints and adjacent vegetation create persistent mismatch losses that module-level maximum power point tracking eliminates.
- FERC Order 2222:Wholesale market participation rules for aggregated distributed resources elevate telemetry value of panel-level monitoring interfaces.
Market Restraints
- Silicon Carbide Supply Concentration:Wide-bandgap semiconductor substrate production clusters in limited foundry capacity, constraining power optimizer and microinverter scaling.
- String Inverter Capital Efficiency:Centralized alternatives retain cost advantage in unshaded utility-scale ground mounts, limiting MLPE penetration in large-scale procurement.
- Installation Labor Intensity:Module-level devices multiply connection points per array, elevating soft costs relative to string architectures in markets with constrained electrician supply.
Strategic Opportunities
- Australian CEC Inverter Listing:Stringent local certification requirements create protected market access for compliant suppliers in distributed commercial segments.
- Vehicle-to-Grid Convergence:Bidirectional charging infrastructure creates shared power electronics architectures between residential solar and electric vehicle platforms.
- Retrofit Rapid Shutdown Modules:Clip-on shutdown devices enable NEC compliance without full inverter replacement, opening legacy string installations to aftermarket attachment.
Industry Challenges
- UL 1741-SA Certification Timeline:Grid support functionality testing for advanced inverter requirements extends product launch schedules by 8-14 months.
- Legacy String Inverter Integration:Power optimizer retrofit onto aging inverter fleets requires firmware compatibility verification that fragments supplier qualification efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Module-Level Power Electronics (MLPE) Market |
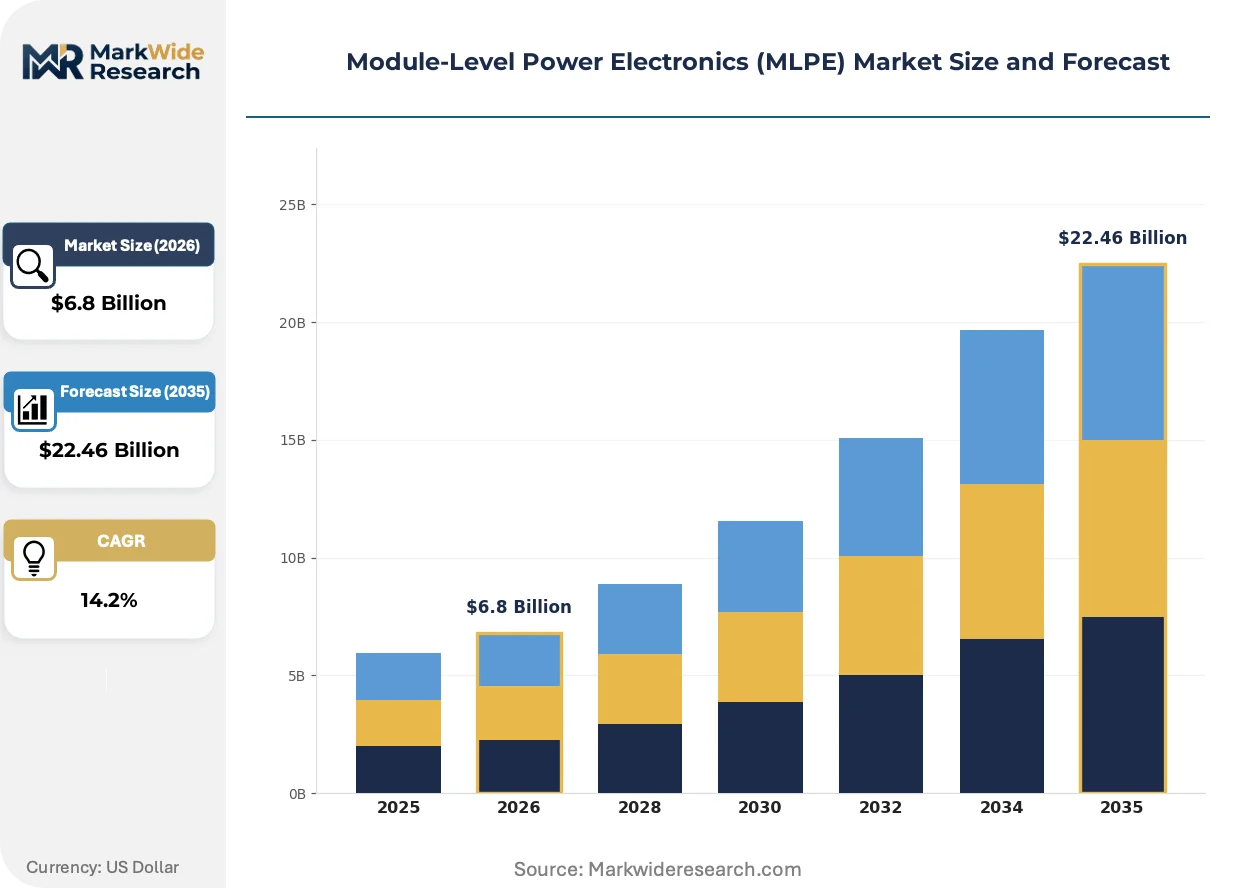
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microinverters, Power Optimizers, String Inverters, Hybrid Inverters End User: Residential, Commercial, Industrial, Utility Installation: Rooftop, Ground-mounted, Carport, Floating Technology: Single-phase, Three-phase, Smart Technology, Battery Ready |
| Companies Covered | SolarEdge Technologies, Enphase Energy, Tigo Energy, APsystems, Huawei, SMA Solar Technology, Chilicon Power, Lead Solar, Alencon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Module-Level Power Electronics (MLPE) Market Strategic Shifts
Semiconductor packaging advances and software-defined control architectures are compressing the functional boundary between power conversion and energy management, collapsing separate hardware categories into unified platforms.
GaN-based switching topologies are unifying power conversion and monitoring telemetry into single semiconductor packages. Residential installers in high-labor-cost markets are specifying these integrated devices to reduce rooftop connection count. The technology is unifying what were separate optimizer and communications hardware tiers, compressing bill-of-materials differentiation between mid-market and premium product lines.
EU Green Deal module-level monitoring mandates are expanding across member states, compelling inverter manufacturers to redesign for component-level data granularity. German Bundesnetzagentur network codes impose reactive power capability requirements that favor architectures with distributed control. Commercial rooftop retrofits across the Netherlands and Belgium are prioritizing panel-level diagnostics to satisfy evolving asset management standards.
Installer channel consolidation is compressing distributor margins and elevating direct procurement relationships between national contractors and power electronics suppliers. Regional solar integrators in Texas and Florida are bypassing traditional electrical distributors for factory-direct volume pricing. The shift is most visible in residential markets where customer acquisition costs now exceed hardware costs, forcing procurement efficiency gains.
Module-Level Power Electronics (MLPE) Market Segmentation
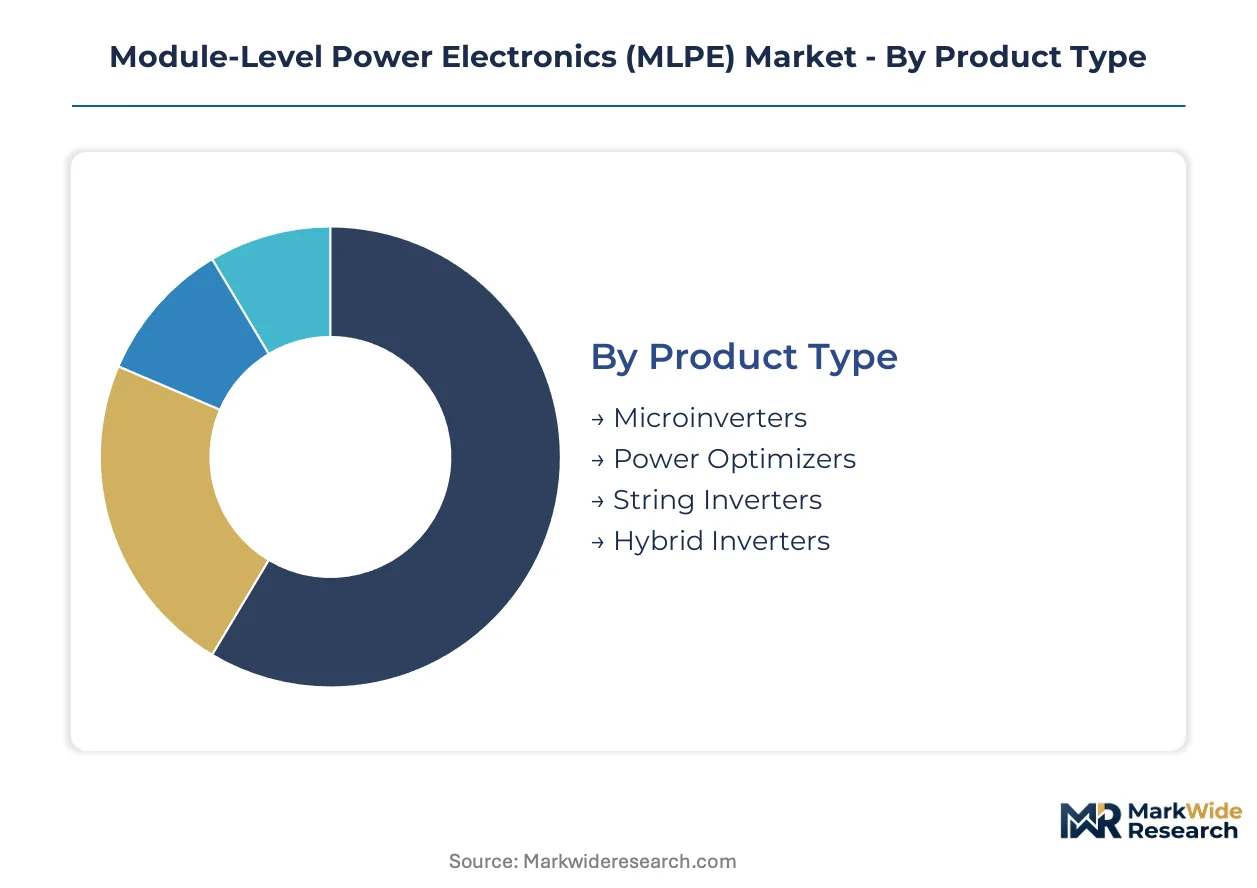
Product architecture in the MLPE market splits between standalone conversion devices and integrated energy management platforms. Each segmentation dimension reveals distinct procurement patterns across installation scales and grid-interconnection requirements.
Product Type:
Standalone microinverters operate independently at each panel, while power optimizers embed into string architectures for retrofit flexibility.
- Microinverters:These semiconductor packages perform DC-to-AC conversion at individual photovoltaic modules, eliminating string mismatch losses. Residential installers in California specify microinverters for complex rooftop geometries where shading from adjacent structures creates persistent performance variation. NEC rapid shutdown mandates accelerate procurement as microinverters inherently satisfy panel-level de-energization without additional hardware.
- Power Optimizers:DC conditioning devices perform maximum power point tracking at the module level while feeding conditioned direct current to downstream string inverters. Commercial retrofit projects in Germany favor power optimizers for their ability to add monitoring granularity to existing inverter assets without full system replacement. Bundesnetzagentur network codes demanding reactive power capability favor architectures with distributed control interfaces.
- String Inverters:Centralized conversion hardware serving multiple panels through series electrical connections.
- Hybrid Inverters:Integrated units managing both photovoltaic generation and battery storage through unified power electronics.
Volume placements concentrate in power optimizers; the faster expansion belongs to hybrid inverters.
End User:
Procurement scale and technical specification intensity vary sharply across customer categories, from individual homeowners to utility procurement departments.
- Residential:Single-family and multi-family rooftop installations where shading complexity and fire code stringency elevate module-level architecture value. Texas installers drive procurement volumes for NEC compliance in new construction markets.
- Commercial:Distributed generation on retail, warehouse, and office rooftops where panel-level diagnostics satisfy asset management requirements. EU Green Deal monitoring mandates accelerate specification across Netherlands and Belgium commercial retrofits.
- Industrial:Large on-site generation for manufacturing facilities with high behind-the-meter consumption.
- Utility:Grid-scale solar farms where capital efficiency pressures favor centralized alternatives with limited MLPE penetration.
Commercial segments dominate current procurement volume; residential applications are climbing the fastest.
Installation:
Mounting configuration dictates environmental exposure, electrical code applicability, and labor intensity for device deployment.
- Rooftop:Building-integrated arrays where rapid shutdown compliance and firefighter access requirements mandate module-level safety equipment. California Title 24 standards expand addressable market for battery-ready power electronics in new residential construction.
- Ground-mounted:Terrestrial fixed-tilt or tracking systems with standardized electrical design and lower soft cost pressure.
- Carport:Dual-purpose structures combining vehicle shelter with solar generation, common in commercial parking installations.
- Floating:Photovoltaic arrays on water bodies where humidity and corrosion resistance specifications intensify.
Rooftop deployments anchor current installation volume; floating configurations show the steepest expansion trajectory.
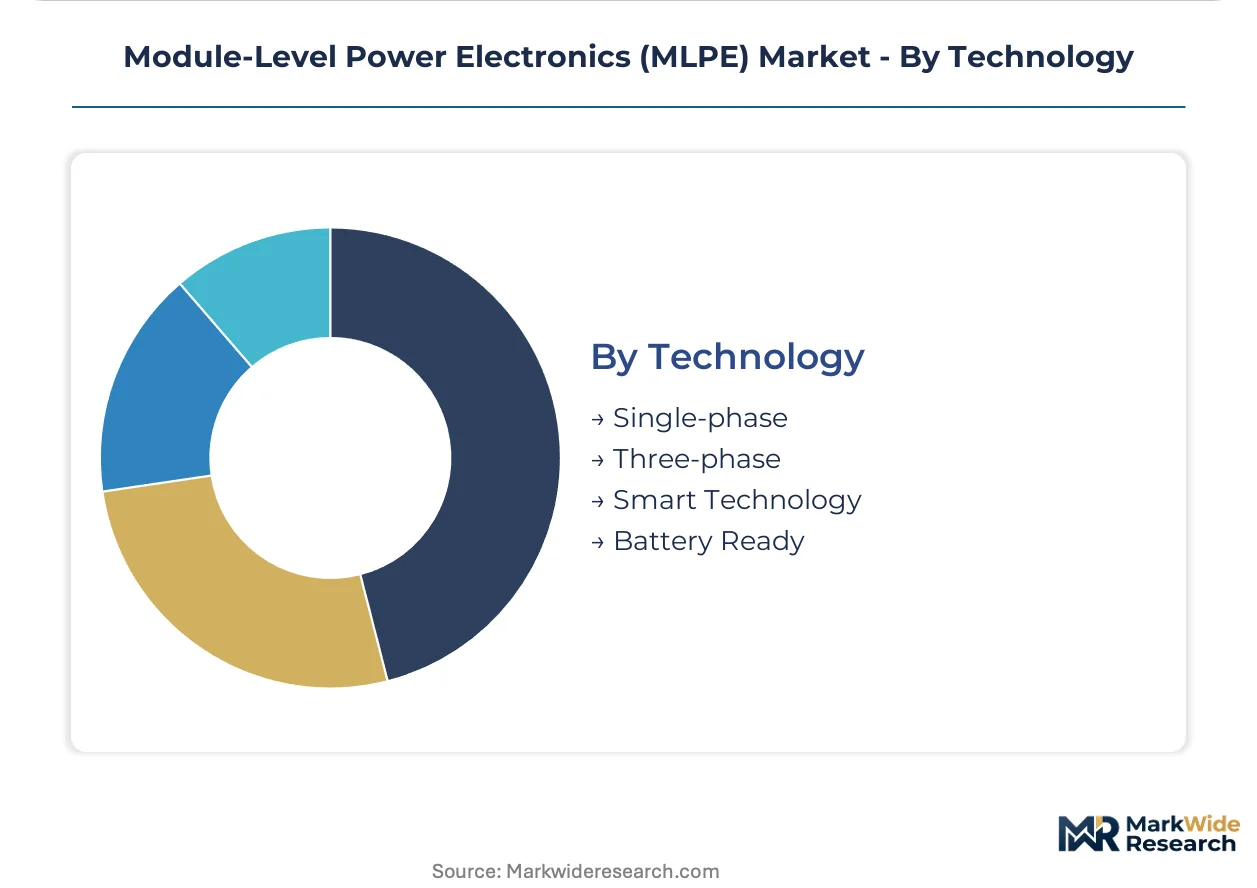
Technology:
Electrical topology and functional integration define performance boundaries and interoperability requirements across grid connection scenarios.
- Single-phase:Residential-scale connection architecture standard in North American and Japanese distribution networks.
- Three-phase:Commercial and industrial interconnection enabling higher power transfer with balanced grid loading.
- Smart Technology:Software-defined control with embedded communications for remote monitoring and predictive maintenance.
- Battery Ready:Power electronics pre-configured for storage integration without hardware replacement. FERC Order 2222 elevates telemetry value of these panel-level monitoring interfaces for aggregated distributed resource participation in wholesale markets.
Smart technology variants lead placement volume; battery-ready configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fremont anchors North American MLPE procurement as California Title 24 standards and NEC rapid shutdown mandates compress replacement cycles across existing rooftop fleets.
United States
Residential installers in California and Texas drive procurement volumes for module-level shutdown compliance. FERC Order 2222 enables aggregated distributed energy resources to participate in wholesale markets, elevating panel-level telemetry value. The National Electrical Code rapid shutdown requirements are compelling inverter replacements across existing rooftop fleets.
Germany
Commercial rooftop retrofits prioritize panel-level diagnostics to satisfy evolving asset management standards under EU Green Deal mandates. Bundesnetzagentur network codes impose reactive power capability requirements that favor architectures with distributed control. Installations across the Netherlands and Belgium mirror German procurement patterns for distributed generation compliance.
Australia
Clean Energy Council inverter listing requirements create protected market access for compliant suppliers in distributed commercial segments. Stringent local certification requirements accelerate specification of module-level monitoring equipment. Sydney and Melbourne metropolitan clusters concentrate residential procurement for solar-plus-storage configurations.
China
Domestic manufacturers supply power electronics components to global MLPE assemblers while policy frameworks emphasize utility-scale deployment. MIIT standards for grid-connected inverters impose technical barriers that favor centralized architectures in domestic procurement. Yangtze River Delta manufacturing clusters produce wide-bandgap semiconductor substrates for export markets.
Module-Level Power Electronics (MLPE) Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification intensity and software integration depth. The vendor base clusters around three strategic archetypes: vertically integrated platform providers, rapid shutdown retrofit specialists, and string inverter incumbents adding modular conditioning. Dominant competitive moves include direct procurement relationships with national contractors and GaN-based semiconductor packaging advances that compress hardware tiers.
Within the integrated platform tier, SolarEdge Technologies and Enphase Energy exemplify divergent architectural approaches to module-level conversion. SolarEdge occupies a position as a vertically integrated power optimizer and inverter platform provider. Enphase represents the microinverter architecture specialist with installer channel density in North American residential markets. Tigo Energy anchors the retrofit compliance segment with rapid shutdown modules that attach to legacy string installations.
| Leading Market Players |
|---|
| SolarEdge Technologies |
| Enphase Energy |
| Tigo Energy |
| APsystems |
| Huawei |
| SMA Solar Technology |
| Chilicon Power |
| Lead Solar |
| Alencon Systems |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide substrate pricing volatility cascades through power optimizer and microinverter manufacturing, compressing margins at mid-tier suppliers while vertically integrated incumbents absorb cost shocks through captive wafer supply.
Pricing Analysis
Energy yield guarantees anchor pricing architecture in residential segments, where installers monetize module-level maximum power point tracking performance through production-based warranties. Three-tier pricing structure across premium, standard, and economy levels separates UL 1741-SA certified grid-support units from basic rapid shutdown compliance modules. Cost compression in the standard tier is intensifying because GaN-based switching topologies collapse hardware tiers. Residential installers in high-labor-cost markets exhibit lowest price sensitivity; utility-scale EPCs drive hardest procurement negotiations.
Supply Chain Analysis
Direct-to-installer channels handle national contractor demand in Texas and Florida, bypassing traditional electrical distributors. Wide-bandgap semiconductor substrate production clusters in the United States, Japan, and Germany. Power optimizer and microinverter assembly draws from silicon carbide wafers, magnetic components, and thermal management materials. Single-source vulnerability in silicon carbide epitaxy equipment constrains capacity expansion. Distribution runs through factory-direct relationships and regional solar distributors serving installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UL 1741-SA certification timelines and GaN packaging R&D intensity are forcing sub-scale manufacturers toward exit or acquisition, consolidating vendor tiers around capital-rich platform providers.
For Market Incumbents: Lock in installer channel exclusivity through volume rebate structures and co-developed training programs. Defensive moves require backward integration into silicon carbide substrate supply and firmware-controlled rapid shutdown retrofit compatibility across legacy string inverter fleets. Threat from string inverter incumbents adding modular conditioning elevates urgency for platform stickiness through battery-ready hardware pre-configuration. For New Entrants and Emerging Players: Launch via clip-on rapid shutdown modules for NEC compliance in legacy installations without full inverter replacement. White-space targets concentrate in Australian CEC-listed commercial retrofits and floating solar corrosion-resistant power electronics. Most penetrable segment: aftermarket attachment to aging string inverter fleets in California and Texas. Go-to-market angle centers on firmware-agnostic shutdown compliance without hardware ecosystem lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor GaN-integrated semiconductor packaging specialists in the United States with UL certification progress. Long-term viability hinges on software-defined control architectures unifying conversion and energy management. Acquisition target archetype: rapid shutdown retrofit specialists with installer channel density. Signal to watch: FERC Order 2222 implementation pace elevating telemetry value for wholesale market participation.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Packaging Scale-Up | GaN-based switching topologies collapse optimizer and communications hardware tiers for labor cost reduction. |
| UL 1741-SA Certification Acceleration | Grid support functionality certification opens California and Texas markets to premium pricing. |
| Battery-Ready Hardware Pre-Configuration | California Title 24 solar-plus-storage readiness mandates expand addressable market for integrated platforms. |
| Installer Channel Direct Procurement | Factory-direct relationships with national contractors in Texas and Florida compress distributor margins. |
| Firmware Retrofit Compatibility Program | Legacy string inverter integration capability fragments competitor qualification efforts and extends replacement cycles. |
Study Parameters
Independent corroboration across utility interconnection officers, residential solar installers, commercial EPC contractors, and power electronics procurement leads underwrites the qualitative findings. Secondary validation draws from FERC filings, EIA distributed generation databases, NEC code revision dockets, and CEC inverter listing records. Bottom-up installation forecasts triangulate against top-down semiconductor substrate demand projections.
Comparable-period anchoring to historical rooftop replacement cycles and rapid shutdown mandate implementation phases structures the projection horizon. Segmentation dimensions span product architecture, end-user scale, mounting configuration, and battery-readiness status across the modeling period. CAGRs derive from unit shipment trajectories weighted by average selling price evolution. Forecast inputs incorporate silicon carbide substrate capacity expansion schedules and installer channel consolidation patterns.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide versus silicon-based power conversion would alter the outlook. Forecasts reflect assumptions on NEC code enforcement consistency, EU Green Deal monitoring mandate timelines, and FERC Order 2222 aggregation rule implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Traction Inverter Market
Power Systems
Global Synchronous Motor Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Central Battery Systems Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Three-Phase String Inverter Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Medium Voltage Drives Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market