
 Modified Milk Powder Market | 2026-2036
Modified Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Milk Powder Market Insights
Premium-grade protein fortification is reorganizing competitive dynamics in modified milk powder. Nestle SA leverages its pediatric nutrition R&D infrastructure across European and Asian markets. Fonterra Co-operative Group anchors Oceania's grass-fed whey supply chains. Danone S.A. differentiates through specialized fermentation capabilities for hypoallergenic formulations.
Modified milk powder refers to dairy solids processed through spray-drying or roller-drying, with adjusted fat content between 1.5% and 26% and standardized protein levels typically near 34%, serving as a shelf-stable ingredient in manufactured foods. Skimmed milk powder dominates volume due to its extended stability and lower fat oxidation risk in industrial bakeries. Infant nutrition commands the highest margin pool, where mineral-fortified instant milk powder formulations attract premium pricing from food manufacturers.
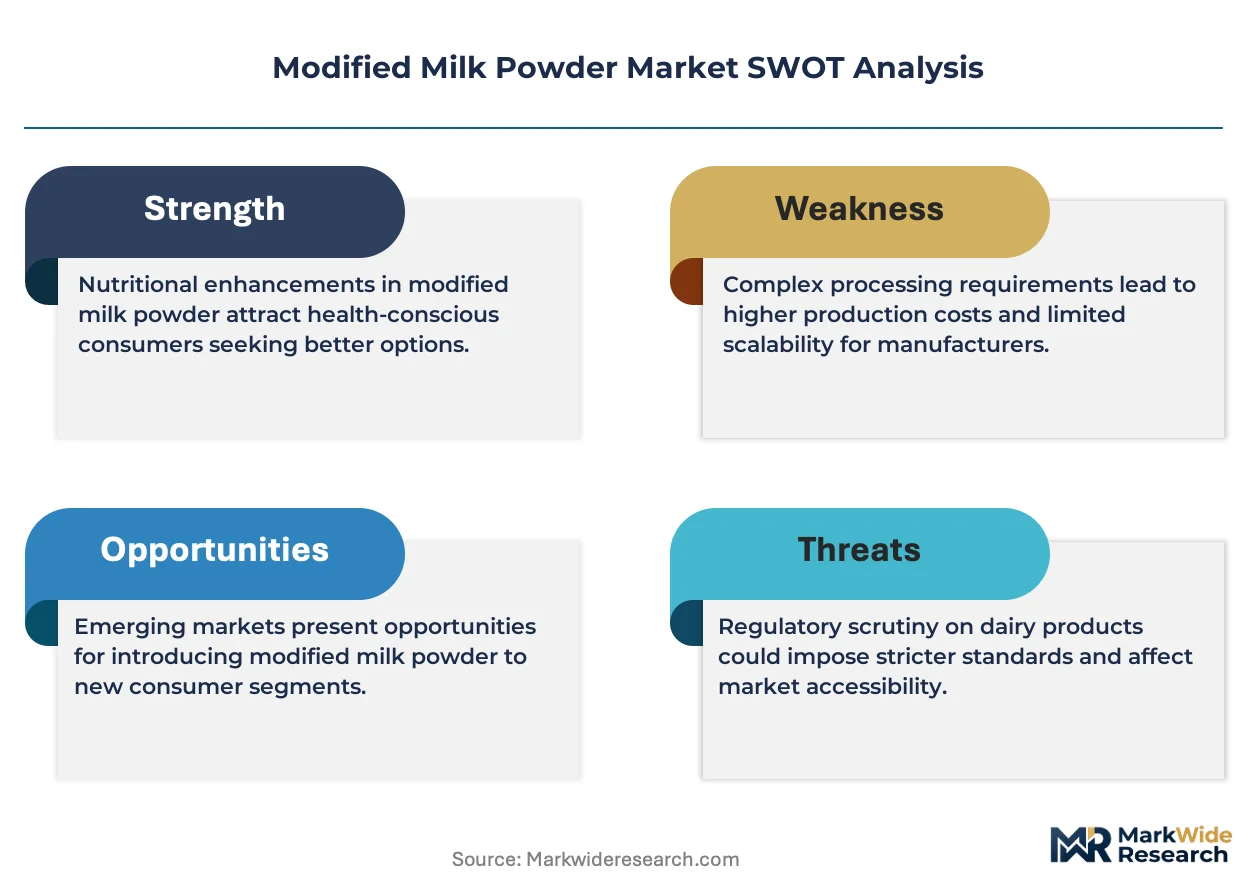
FDA nutrition labeling requirements and China's SAMR dairy safety standards shape product composition thresholds and cross-border market access. The EU's EFSA novel food regulations constrain hydrolyzed protein claims in modified powders sold across member states. Stakeholders must monitor evolving protein origin disclosure rules and fortification ceilings to anticipate reformulation costs and regional supply reallocations.
Market Dynamics
Protein fortification standards are tightening across major dairy-importing jurisdictions, forcing manufacturers to reconfigure sourcing and reformulation strategies. China's SAMR dairy safety standards and the EU's EFSA novel food regulations are compressing margins while elevating technical barriers to market entry.
Growth Catalysts
- Urban food service expansion in Indonesia:Jakarta and Surabaya's quick-service restaurant chains are standardizing modified milk powder for beverage consistency. Procurement volumes from industrial bakeries are accelerating.
- FSSAI fortification mandates:India's food safety regulator is mandating micronutrient enrichment in institutional dairy supplies. School nutrition programs and anganwadi centers are expanding offtake.
- Spray-drying efficiency gains:Advanced atomization technologies are reducing energy intensity in protein-standardized powder production. Processing costs per ton are compressing.
Market Restraints
- Whole milk powder price volatility:New Zealand's grass-fed dairy output fluctuations transmit directly to modified powder input costs. Fonterra's auction clearing prices set regional benchmarks.
- GB standards compliance friction:China's dairy protein content thresholds require dedicated production runs for export-bound inventory. Cross-border certification timelines extend by four to six months.
- Plant-based dairy substitution:Oat and pea protein isolates are capturing share in bakery and beverage applications where functional properties overlap.
Strategic Opportunities
- Vietnam's underpenetrated infant nutrition channel:Ho Chi Minh City and Hanoi's pharmacy networks lack specialized hypoallergenic formulations. Local distribution partnerships remain sparse.
- Dual carbon alignment in China:Beijing's carbon intensity targets for food processing are creating preference for lower-emission spray-drying facilities. Renewable-powered production lines qualify for provincial incentives.
- Precision fermentation convergence:Microbial whey protein synthesis is approaching cost parity with conventional dairy fractions. Hybrid formulations blending dairy and fermentation-derived proteins are emerging.
Industry Challenges
- Spray-drying engineer scarcity:Specialized expertise in atomization parameter optimization and moisture control is concentrated among aging technicians in European equipment manufacturers.
- Legacy ERP integration:Batch traceability requirements under FDA 21 CFR Part 117 are forcing mid-tier processors to replace paper-based production logs with validated digital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Milk Powder Market |
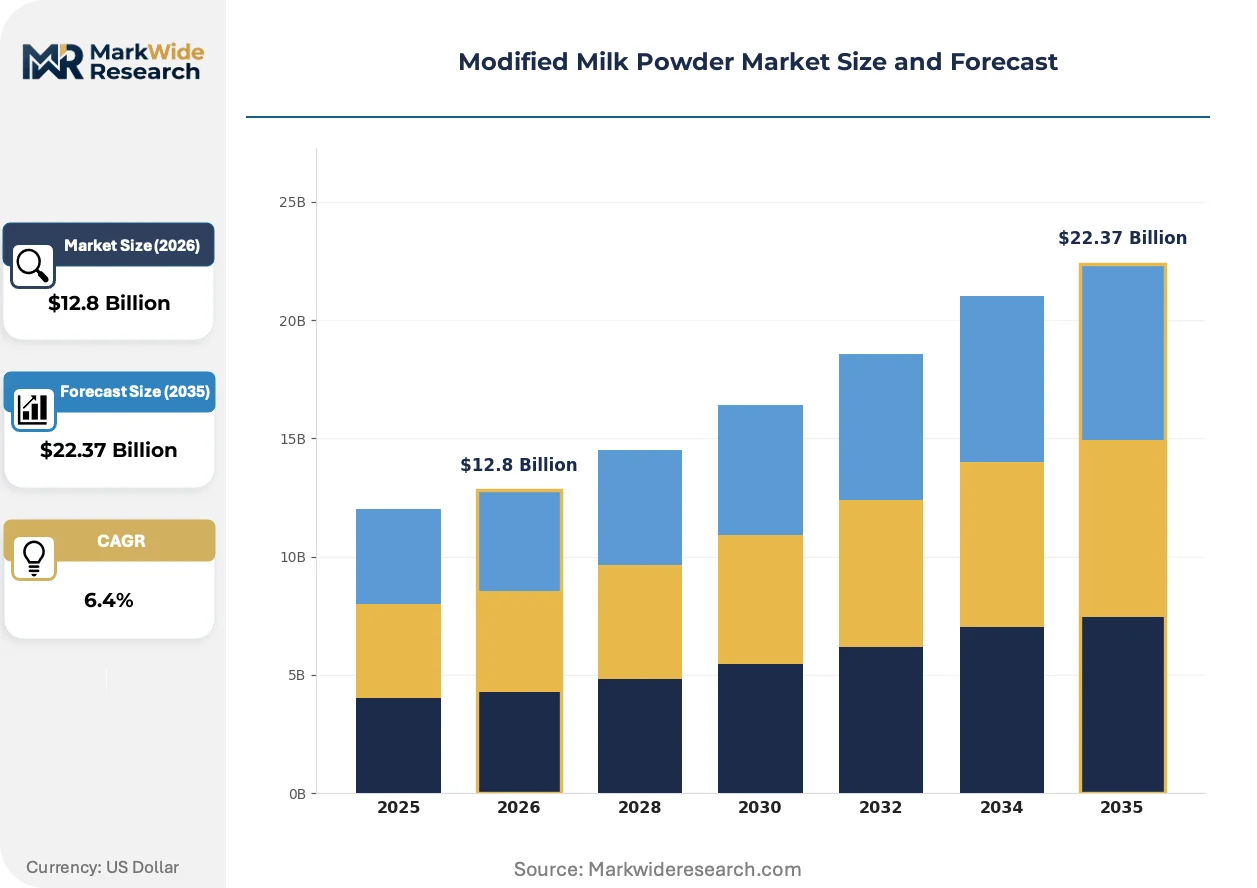
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk Powder, Skimmed Milk Powder, Instant Milk Powder, Evaporated Milk Powder Application: Dairy Industry, Bakery Products, Confectionery, Infant Nutrition End User: Food Manufacturers, Retailers, Food Service Operators, Households Packaging Type: Bulk Packaging, Cartons, Pouches, Tins |
| Companies Covered | Nestle SA, Danone S.A., Lactalis International, Fonterra Co-operative Group, Royal FrieslandCampina N.V., Arla Foods, China Mengniu Dairy Co., Ltd., Saputo Inc., Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Milk Powder Market Trends and Innovations
Processing technology and regulatory disclosure requirements are restructuring how modified milk powder manufacturers compete. Three developments are compressing legacy operating models while opening specialized niches.
Membrane filtration is displacing conventional evaporation in protein concentration stages. European infant nutrition manufacturers are adopting ceramic microfiltration for native whey protein preservation. This technology is displacing heat-denatured protein fractions in premium formulation tiers, compressing commodity-grade powder premiums.
REACH disclosure obligations for processing aids are expanding documentation burdens across EU-bound supply chains. ECHA's updated requirements for spray-drying adjunct chemicals are forcing reformulation of anti-caking agents. Instant milk powder producers serving German and Dutch food manufacturers are substituting mineral-based flow agents for silicon dioxide variants.
Direct procurement from processors is shortening traditional dairy ingredient distribution chains. Southeast Asian bakery conglomerates are establishing volume commitments with New Zealand spray-drying facilities, bypassing regional traders. This pattern is most visible in Indonesia's industrial corridor linking Surabaya to Singapore logistics hubs.
Modified Milk Powder Market Segmentation
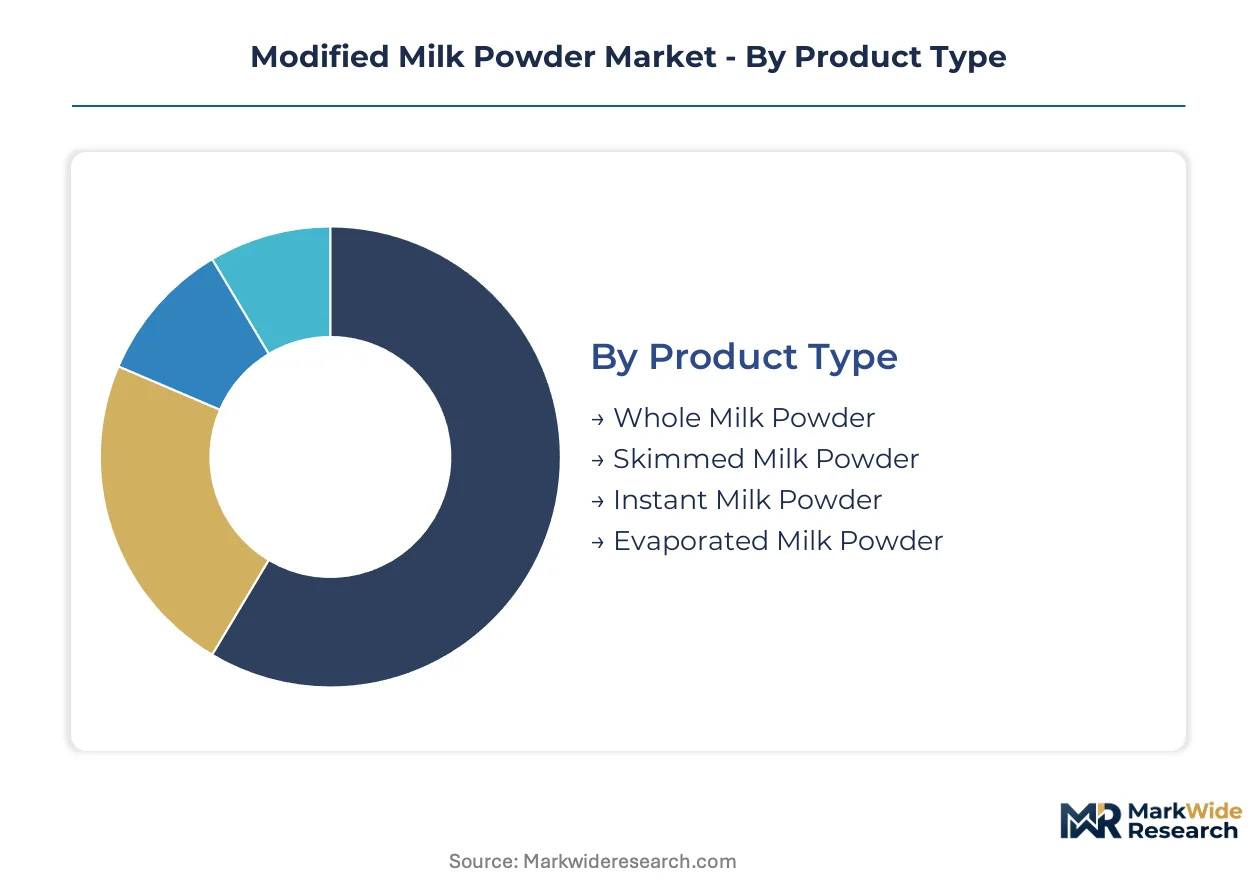
Modified milk powder segments diverge sharply between commodity-grade industrial inputs and specialized nutrition formulations. Procurement patterns split between domestic food service consolidation and export-bound infant nutrition certification requirements.
Product Type:
Skimmed milk powder dominates domestic bakery and confectionery channels across Indonesia and the Philippines. Whole milk powder and instant formulations concentrate in export corridors serving China's SAMR-regulated import standards.
- Skimmed Milk Powder:Fat content reduced below 1.5% through centrifugal separation, yielding extended shelf stability and minimal oxidation in tropical storage. Indonesian industrial bakeries in Surabaya and Jakarta standardize this grade for consistent dough hydration. FSSAI fortification mandates in India's school nutrition programs are accelerating institutional procurement.
- Instant Milk Powder:Agglomerated particles processed through steam lecithination for rapid cold-water solubility. Vietnam's urban food service operators in Ho Chi Minh City favor this grade for beverage consistency in quick-service chains. REACH disclosure requirements for anti-caking agents are forcing reformulation of European-bound shipments.
- Whole Milk Powder:Standardized at 26-28% fat content, serving recombined dairy applications in Middle Eastern import markets.
- Evaporated Milk Powder:Concentrated through vacuum evaporation prior to drying, targeting Southeast Asian confectionery manufacturers.
Skimmed milk powder commands the established base. The steepest expansion runs through instant milk powder.
Application:
Margin structures stratify sharply between commodity food manufacturing and regulated infant nutrition. Dairy industry and bakery applications concentrate in domestic procurement, while infant nutrition channels require dedicated export certification runs.
- Infant Nutrition:Mineral-fortified formulations with protein standardized near 34% and strict microbiological thresholds. China's GB standards for dairy protein content enforce batch-specific testing protocols, extending certification timelines. Pharmacy networks in Vietnam's secondary cities remain undersupplied with hypoallergenic variants.
- Bakery Products:Modified milk powder functions as a shelf-stable dairy solids source for industrial-scale bread and pastry production. Indonesia's quick-service restaurant chains are standardizing procurement specifications across Surabaya-Jakarta corridors. Spray-drying efficiency gains are compressing per-ton processing costs for volume buyers.
- Dairy Industry:Recombined milk and cheese production in import-dependent markets.
- Confectionery:Milk chocolate and caramel applications requiring specific particle size distribution.
Infant nutrition captures the premium tier. Volume concentration sits with bakery products.
End User:
Procurement scale and technical specification intensity vary dramatically across buyer categories. Food manufacturers negotiate direct processor relationships, while retailers and households operate through layered distribution.
- Food Manufacturers:Industrial buyers specifying protein content, particle size, and instant solubility parameters in volume contracts. Southeast Asian bakery conglomerates are establishing direct procurement commitments with New Zealand spray-drying facilities, bypassing regional traders. FDA 21 CFR Part 117 traceability requirements are forcing digital system upgrades among mid-tier processors.
- Food Service Operators:Quick-service chains and institutional caterers prioritizing beverage consistency and storage stability. Indonesia's urban food service corridors in Jakarta and Surabaya are consolidating procurement through centralized distribution hubs. Standardized specifications are displacing variable-quality local sourcing.
- Retailers:Supermarket and pharmacy chains serving household and small commercial buyers.
- Households:Individual consumers purchasing packaged instant milk powder for domestic use.
Food manufacturers anchor volume procurement. Food service operators are expanding most quickly.
Packaging Type:
Packaging selection tracks buyer scale and shelf-life requirements. Bulk formats dominate industrial channels, while retail-facing segments require branded consumer packaging with moisture barriers.
- Bulk Packaging:25kg multi-wall paper bags with polyethylene liners for industrial bakeries and dairy processors. Direct procurement from New Zealand spray-drying facilities is shortening supply chains for Indonesian buyers. Container freight optimization favors this format for high-volume shipments through Singapore logistics hubs.
- Pouches:Flexible laminated films with zipper closures for retail instant milk powder. Vietnam's pharmacy networks favor this format for specialized infant nutrition formulations. Shelf visibility requirements are driving printed film quality upgrades.
- Tins:Metal canisters with vacuum-sealed lids for premium infant nutrition positioning.
- Cartons:Paperboard with polyethylene coating for mid-tier retail segments.
Bulk packaging holds the volume base. Pouch formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spray-drying capacity clusters in New Zealand and the Netherlands, with procurement decisions in Southeast Asia and China transmitting price signals back to these processing hubs. Quality certification requirements fragment export corridors, as China's SAMR standards diverge from EU EFSA protocols. Urban food service consolidation in Indonesia and Vietnam is accelerating volume concentration in specific metropolitan corridors.
China
GB standards for dairy protein content are tightening import thresholds for modified milk powder, forcing dedicated production runs for export-bound inventory. SAMR dairy safety standards extend cross-border certification timelines by four to six months. Beijing-Tianjin-Hebei industrial clusters host recombined dairy facilities serving domestic infant nutrition channels, where dual carbon alignment preferences favor renewable-powered spray-drying lines.
Indonesia
Jakarta and Surabaya's quick-service restaurant chains are standardizing modified milk powder procurement for beverage consistency across urban food service corridors. FSSAI-equivalent local fortification discussions are advancing for institutional dairy supplies. Surabaya's industrial bakery sector anchors domestic skimmed milk powder offtake, with direct procurement commitments to New Zealand spray-drying facilities bypassing regional traders.
New Zealand
Fonterra's auction clearing prices set regional benchmarks for whole milk powder input costs, transmitting volatility directly to modified powder formulations. Grass-fed dairy output fluctuations constrain processing margins during seasonal troughs. Canterbury and Waikato dairy belts concentrate spray-drying capacity serving Southeast Asian bakery conglomerates establishing volume commitments through Singapore logistics hubs.
Vietnam
Ho Chi Minh City and Hanoi's pharmacy networks lack specialized hypoallergenic formulations, creating distribution gaps for infant nutrition variants. Urban food service operators favor instant milk powder grades for quick-service chain beverage consistency. Local distribution partnerships for mineral-fortified formulations remain sparse relative to demand concentration in secondary cities.
India
FSSAI fortification mandates are driving micronutrient enrichment in institutional dairy supplies through school nutrition programs and anganwadi centers. Maharashtra and Gujarat dairy cooperatives are expanding spray-drying capacity to meet standardized protein requirements. Mumbai-Pune industrial corridors concentrate bakery and confectionery offtake for skimmed milk powder grades.
Modified Milk Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the modified milk powder value chain. European and Oceania-based processors dominate protein-standardization expertise and pediatric nutrition certification, while Asian dairy cooperatives compete on scale and proximity to import-dependent markets. The competitive terrain splits between integrated nutrition specialists with fermentation capabilities and commodity-grade processors optimizing spray-drying throughput. Dominant competitive moves include backward integration into grass-fed whey supply chains and geographic expansion through direct procurement relationships with Southeast Asian bakery conglomerates.
Among Swiss and French nutrition conglomerates, Nestle SA and Danone S.A. exemplify the integrated pediatric nutrition archetype, leveraging specialized fermentation infrastructure for hypoallergenic formulations. Fonterra Co-operative Group anchors the Oceania grass-fed supply chain vector, with cooperative structure enabling volume coordination across New Zealand's dairy belt. These three entities occupy distinct competitive positions: Nestle SA and Danone S.A. sit within the premium-tier regulated nutrition segment, while Fonterra represents the commodity-grade industrial input tier with backward integration into raw milk sourcing.
| Leading Market Players |
|---|
| Nestle SA |
| Danone S.A. |
| Lactalis International |
| Fonterra Co-operative Group |
| Royal FrieslandCampina N.V. |
| Arla Foods |
| China Mengniu Dairy Co., Ltd. |
| Saputo Inc. |
| Kerry Group |
| Others |
Pricing and Supply Chain Analysis
Membrane filtration displacement of conventional evaporation is redrawing procurement geography and compressing premium-tier margins simultaneously. Ceramic microfiltration adoption by European infant nutrition manufacturers shifts value capture toward technology licensors while heat-denatured protein fractions face pricing erosion.
Pricing Analysis
China's GB standards dictate the pricing tier structure across export-bound modified milk powder. Three-tier pricing separates infant nutrition certification grades from industrial bakery grades from commodity recombined dairy grades. SAMR dairy safety standards extend cross-border certification timelines, elevating compliance costs for premium tiers. Food manufacturers in Indonesia's Surabaya-Jakarta corridor exhibit highest price sensitivity due to direct procurement scale, while Vietnamese pharmacy networks show lowest sensitivity for hypoallergenic formulations.
Supply Chain Analysis
Singapore logistics hub chokepoints underwrite Southeast Asian distribution reliability for New Zealand-sourced spray-dried powders. Fonterra's auction clearing prices in New Zealand, FrieslandCampina's processing nodes in the Netherlands, and Mengniu's recombined facilities in China anchor global supply. Raw material flows draw from Canterbury grass-fed herds, Waikato dairy cooperatives, and European whey fractionation plants. Single-source vulnerability concentrates in Fonterra's auction mechanism for whole milk powder benchmarks. Distribution runs through bulk 25kg multi-wall bags for industrial buyers and flexible laminated pouches for retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: SAMR, EFSA, and FDA certification timelines create structural switching costs that lock in qualified suppliers.
For Market Incumbents: Fortify backward integration into grass-fed whey supply chains and captive spray-drying capacity in renewable-powered facilities. Plant-based dairy substitution threatens bakery-grade margins; counter with precision fermentation partnerships for hybrid protein formulations. Prioritize certification maintenance investment to defend SAMR and EFSA qualification status. For New Entrants and Emerging Players: Lead with Vietnam's underpenetrated pharmacy networks for hypoallergenic infant nutrition distribution. Ho Chi Minh City and Hanoi's specialized formulation gaps offer white-space entry. Target direct procurement relationships with Indonesian bakery conglomerates seeking to bypass regional traders through Singapore logistics optimization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European mid-cap spray-drying specialists holding EFSA novel food approvals but lacking Southeast Asian distribution scale. Five-to-ten-year viability hinges on membrane filtration technology migration and dual carbon alignment in Chinese processing facilities. Watch Fonterra auction price volatility as margin compression indicator for commodity-grade exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grass-Fed Supply | Fonterra's cooperative structure demonstrates how captive raw milk sourcing stabilizes input cost volatility. |
| Membrane Filtration Technology Adoption | Ceramic microfiltration preserves native whey proteins for European infant nutrition premium positioning. |
| Dual Carbon Alignment Certification | Beijing's provincial incentives for renewable-powered spray-drying create preference in Chinese procurement. |
| Direct Procurement Relationship Establishment | Indonesian bakery conglomerates bypass regional traders through volume commitments with New Zealand processors. |
| Hypoallergenic Formulation R&D Investment | Danone's specialized fermentation capabilities capture pharmacy network premiums in underserved Vietnamese cities. |
Research Methodology
Initial hypotheses were tested against primary input from spray-drying operations managers, infant nutrition regulatory affairs leads, bakery procurement directors, and Southeast Asian food service chain operators and refined through secondary validation. Trade data from New Zealand customs, EU EFSA novel food registers, China's SAMR import certification databases, and Fonterra GlobalDairyTrade auction records anchored volume estimation. Bottom-up facility capacity modeling and top-down consumption surveys were triangulated for cross-verification.
Variance decomposition across product type, application, end user, packaging format, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented volume trajectory modeling and price elasticity calibration throughout the forecast period. Industry-specific inputs included spray-drying energy intensity benchmarks, GB standards compliance cost curves, and membrane filtration adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained SAMR-EFSA regulatory convergence or precision fermentation cost parity timelines would require recalibration. Forecasts assume documented conditions regarding protein fortification mandate expansion and plant-based substitution velocity. Practitioners should keep alternative scenarios live as China's dual carbon enforcement intensity and European REACH disclosure obligations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Commercial Milkshake Machine Market