
 Commercial Milkshake Machine Market | 2026-2036
Commercial Milkshake Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Milkshake Machine Market Outlook
Italian equipment manufacturers are broadening their commercial refrigeration footprint across European foodservice channels. Taylor Freezer Sales Co. leverages its vertical integration into compressor manufacturing to sustain margin control across North American distribution. Carpigiani UK anchors its competitive position through specialized soft-serve and milkshake systems designed for high-traffic hospitality environments. Hamilton Beach Brands competes on countertop footprint reduction, occupying the compact-equipment niche favored by independent cafes.
A commercial milkshake machine is an electromechanical blending and chilling appliance engineered to aerate, homogenize, and freeze dairy-based mixtures to consistent viscosity at output temperatures between 18°F and 24°F, serving the foodservice industry's need for repeatable, high-throughput frozen-beverage production. Countertop configurations dominate unit shipments among independent operators with limited kitchen space, while high-volume systems command the largest margin pools through multi-spindle throughput and extended warranty attach rates. Air-cooled technology leads installed base owing to lower plumbing requirements, though water-cooled variants differentiate in climates where ambient temperatures compromise condenser efficiency.
The US Department of Energy appliance efficiency standards and the EU Ecodesign Directive constrain motor wattage and refrigerant selections, compelling manufacturers to redesign compressor architectures and transition to lower-global-warming-potential coolants. NSF International sanitation certification and CE marking requirements shape market access, with non-compliant units excluded from commercial kitchen procurement channels. Stakeholders must monitor evolving refrigerant phase-down schedules and energy-labeling thresholds to align R&D roadmaps with compliance deadlines.
Market Dynamics
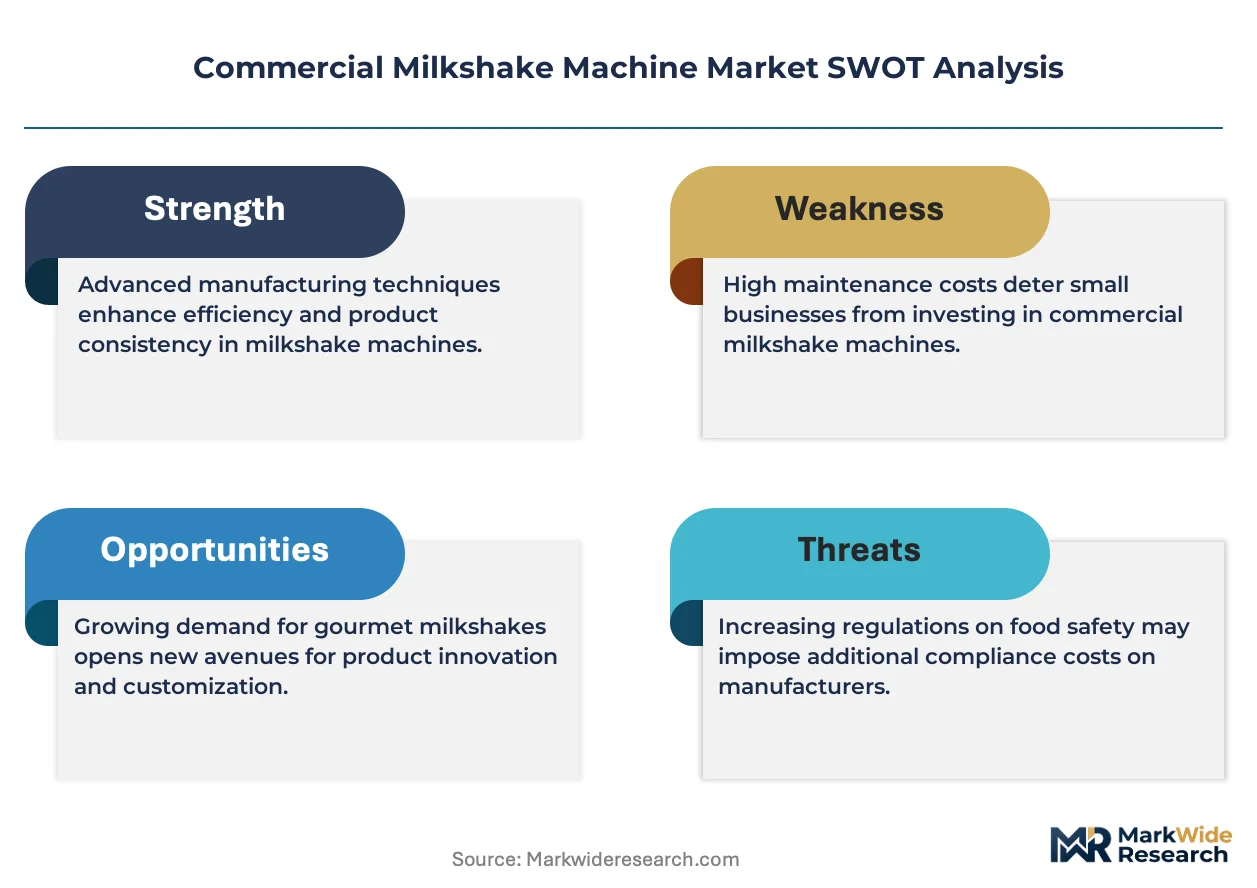
Energy-efficiency mandates from the US Department of Energy and the EU Ecodesign Directive are forcing compressor redesigns and refrigerant transitions across the installed base, compressing product development cycles while opening margin pools for compliant equipment suppliers.
Growth Catalysts
- Quick-service restaurant throughput demands:Chains are upgrading multi-spindle systems to handle peak-hour frozen-beverage volumes. This equipment refresh cycle concentrates in franchise networks with standardized menu expansions.
- EU Ecodesign Directive compliance deadlines:Manufacturers are accelerating R&D roadmaps to meet motor wattage constraints and lower-global-warming-potential coolant requirements. Early movers capture specification locks with institutional buyers.
- Frozen-beverage menu proliferation:Specialty coffee chains and cinema concessions are adding milkshake SKUs, creating incremental equipment demand from non-traditional buyers.
Market Restraints
- Copper and aluminum input volatility:Condenser coil and compressor housing materials face commodity price swings that compress equipment margins. Manufacturers with captive metal supplies defend position better than assembly-only competitors.
- NSF International certification timelines:Sanitation validation protocols add 4-6 months to product launches, freezing smaller competitors out of rapid replacement opportunities.
- Air-cooled efficiency ceilings:Ambient temperature sensitivity limits deployment in high-heat climates without costly water-cooled infrastructure upgrades.
Strategic Opportunities
- Independent cafe countertop penetration:Compact single-spindle units with reduced footprint specifications address space-constrained urban operators. This segment shows replacement-cycle compression versus legacy floor-standing equipment.
- US Inflation Reduction Act efficiency incentives:Commercial kitchen equipment rebates for Energy Star-certified systems create procurement tailwinds. Distributors are bundling rebate navigation into sales support.
- IoT-enabled predictive maintenance convergence:Vibration sensors and refrigerant leak detection are merging with equipment finance packages. This shifts revenue toward recurring service attach rates.
Industry Challenges
- Refrigerant handler certification gaps:EPA Section 608 technician shortages slow field service response times. OEMs are internalizing training programs to protect uptime guarantees.
- Legacy PLC integration complexity:New variable-speed drive controllers often conflict with existing kitchen automation protocols. Retrofit engineering costs erode project economics for mid-size operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Milkshake Machine Market |
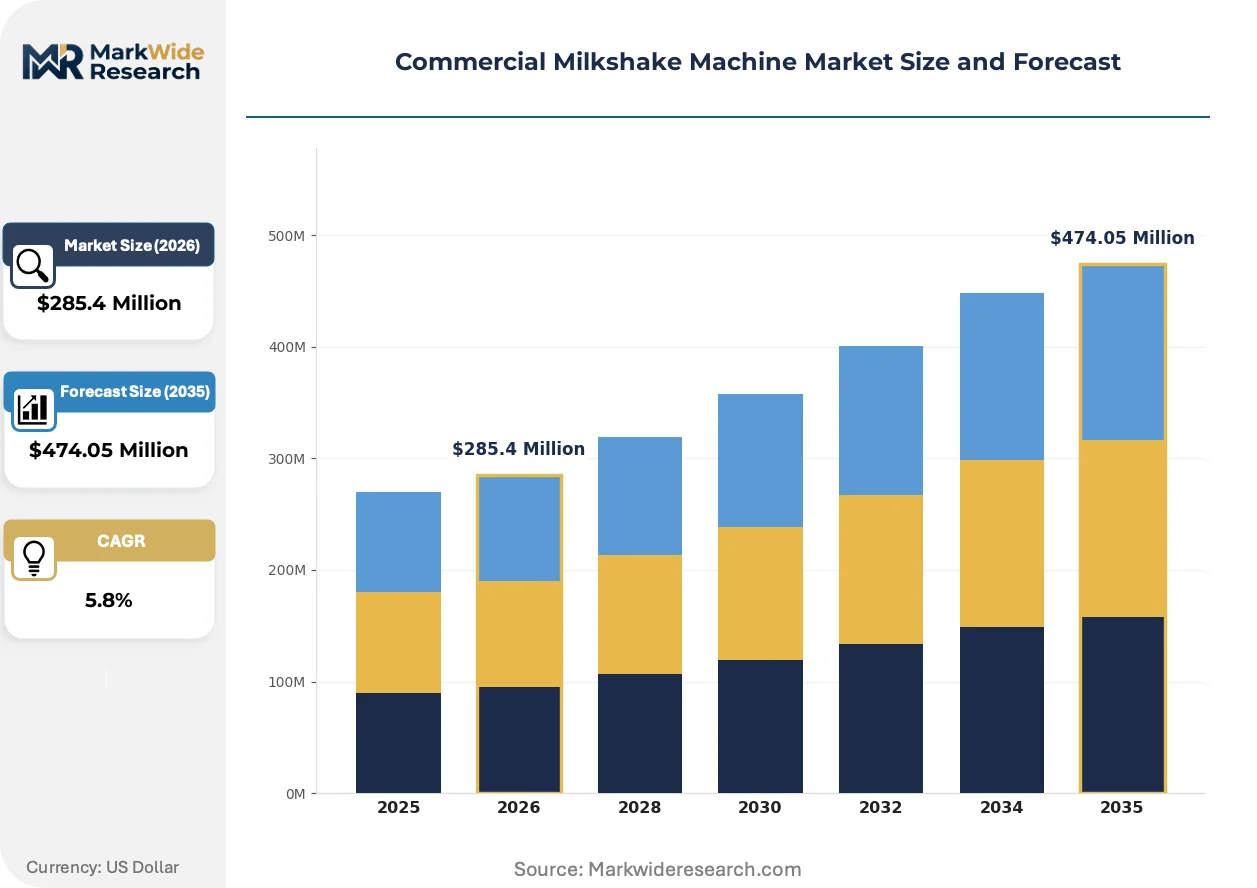
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Countertop, Multi-Function, High-Volume Technology: Air-Cooled, Water-Cooled, Soft Serve, Batch Freezing End User: Restaurants, Cafes, Fast Food Chains, Ice Cream Shops Distribution Channel: Online, Direct Sales, Wholesalers, Retail Stores |
| Companies Covered | Taylor Freezer Sales Co., Carpigiani UK, Hamilton Beach Brands, Robot Coupe, Electro Freeze, Vita-Mix Corporation, Blendtec, Smeg, Waring Commercial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Milkshake Machine Market Strategic Shifts
Equipment intelligence and thermal management architectures are actively reshaping competitive differentiation, with three developments commanding capital allocation across engineering teams.
Variable-speed compressor technology is decentralizing capacity planning across franchise networks. Quick-service operators are deploying these systems to match output to hourly demand curves rather than oversizing for peak loads. This capability compresses energy consumption while extending equipment lifespan through reduced cycling stress.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with aggressive quota reductions through 2030. Manufacturers are redesigning heat exchanger geometries to accommodate propane and carbon dioxide alternatives. Water-cooled variants are gaining specification share in Southern European markets where ambient temperatures challenge air-cooled condenser performance.
After-sales service unbundling is fragmenting buyer-supplier relationships. Large franchise groups are negotiating direct parts contracts with compressor suppliers, bypassing traditional distributor service tiers. This pattern concentrates in the United States where multi-unit operators possess sufficient scale to justify in-house technical staff.
Commercial Milkshake Machine Market Segmentation
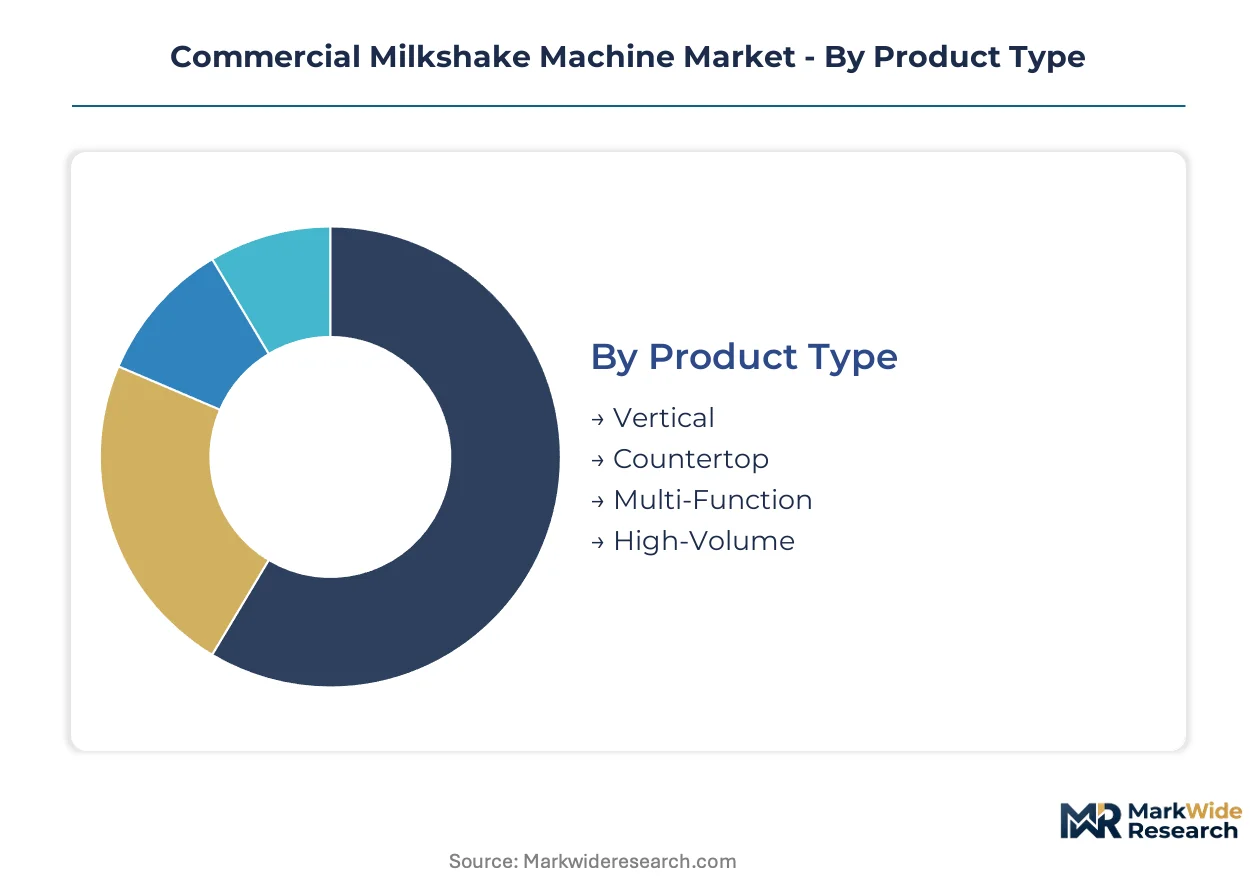
Segmentation in commercial milkshake equipment reveals distinct engineering trade-offs between footprint constraints, thermal management architectures, and throughput specifications. Each axis shapes procurement patterns across operator types with divergent kitchen layouts and volume profiles.
Product Type:
Equipment form factor determines installation feasibility across kitchen configurations with varying ceiling heights and floor space availability.
- Vertical:Floor-standing units with integrated refrigeration compressors and dual-spindle configurations serve high-throughput quick-service environments. Demand concentrates in US franchise networks upgrading legacy equipment to meet peak-hour frozen-beverage volumes.
- Countertop:Compact single-spindle systems with reduced footprint specifications address space-constrained urban cafes and cinema concessions. This segment is expanding most quickly as independent operators replace aging floor-standing equipment.
- Multi-Function:Modular platforms supporting interchangeable spindle attachments for milkshakes, soft-serve, and frozen beverages.
- High-Volume:Continuous-output systems with triple-spindle arrays and extended warranty packages for institutional buyers.
Countertop leads on scale; High-Volume leads on momentum.
Technology:
Cooling methodology selection hinges on ambient climate conditions, local water infrastructure, and energy-efficiency compliance requirements.
- Air-Cooled:Self-contained condenser systems eliminate plumbing dependencies and dominate installed base in temperate climates. The US Department of Energy appliance efficiency standards constrain motor wattage selections, compressing development cycles for compliant architectures.
- Water-Cooled:Heat-rejection systems using closed-loop water circuits maintain condenser efficiency in high-ambient-temperature environments. Southern European markets show specification share gains where summer temperatures compromise air-cooled performance.
- Soft Serve:Integrated freezing and extrusion mechanisms for viscosity-controlled dessert production.
- Batch Freezing:Cyclic production systems for artisanal operators requiring recipe flexibility.
Air-Cooled commands installed base dominance; Water-Cooled shows steepest specification trajectory.
End User:
Operator scale and menu complexity drive divergent equipment requirements across foodservice channels.
- Restaurants:Full-service establishments deploying milkshake equipment as dessert-menu anchors with moderate throughput needs. Replacement cycles accelerate in US casual-dining chains expanding frozen-beverage SKUs.
- Fast Food Chains:High-frequency operators with standardized equipment specifications and multi-unit procurement leverage. EU Ecodesign Directive compliance deadlines are accelerating R&D investment for specification locks with institutional buyers.
- Cafes:Specialty coffee operators with limited counter space and premium positioning requirements.
- Ice Cream Shops:Seasonal businesses with peak-load sizing challenges and extended idle periods.
Fast Food Chains lead on procurement volume; Cafes lead on replacement-cycle compression.
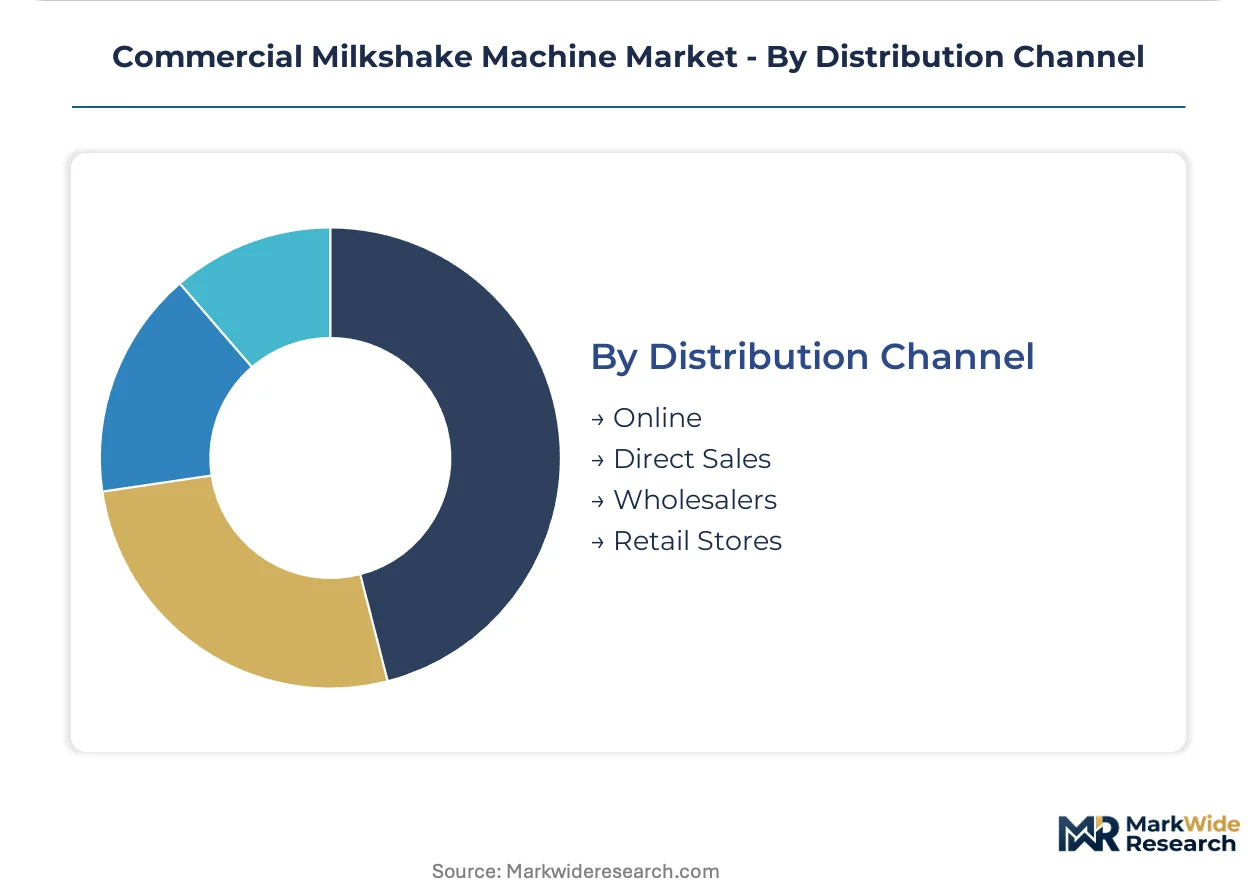
Distribution Channel:
Channel selection reflects buyer technical sophistication, scale economies, and service integration preferences.
- Direct Sales:OEM field teams negotiate equipment-finance packages and predictive maintenance contracts with large franchise groups. US multi-unit operators increasingly source direct from compressor suppliers, bypassing traditional distributor tiers.
- Wholesalers:Broadline foodservice distributors bundle milkshake equipment with refrigeration and smallwares procurement. This channel defends position through rebate navigation support for US Inflation Reduction Act efficiency incentives.
- Online:E-commerce platforms with specification comparison tools for independent operator self-service procurement.
- Retail Stores:Brick-and-mortar equipment showrooms with demonstration capabilities for tactile buyer evaluation.
Wholesalers lead on transaction volume; Direct Sales leads on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for frozen-beverage equipment outpaces German procurement volumes by a factor of three, reflecting divergent foodservice channel maturation. Regulatory pressure from Washington and Brussels is compressing development cycles unevenly across these markets. Equipment specifications now diverge significantly between jurisdictions with stringent efficiency mandates and those with phased compliance timelines.
United States
Franchise networks drive replacement cycles as quick-service chains expand milkshake SKUs to capture afternoon snack occasions. The US Department of Energy appliance efficiency standards constrain motor wattage selections, forcing compressor redesigns. Equipment procurement concentrates in Texas and Florida metropolitan corridors where new store development outpaces national averages.
Germany
Artisanal ice cream parlors and cinema concessions sustain demand for compact countertop systems with premium positioning. The EU Ecodesign Directive and F-Gas Regulation accelerate refrigerant transitions toward propane and carbon dioxide alternatives. Manufacturing clusters in Baden-Württemberg and Bavaria host specialized component suppliers serving pan-European OEM assembly.
Italy
Traditional gelato equipment manufacturers extend product portfolios into milkshake systems for hospitality export markets. CE marking requirements and NSF International sanitation protocols shape export qualification timelines. Industrial concentration in Emilia-Romagna supports integrated supply chains from compressor fabrication to finished equipment assembly.
United Kingdom
Specialty coffee chains and independent cafes compress replacement cycles for space-constrained urban locations. Post-Brexit regulatory divergence from EU Ecodesign timelines creates compliance complexity for multinational equipment suppliers. London and Manchester metropolitan areas anchor procurement volume for compact single-spindle configurations.
Japan
Premium convenience store chains and cinema concessions sustain demand for high-reliability equipment with minimal downtime tolerance. METI energy-efficiency labeling programs and JIS standards constrain product specifications for domestic market access. Equipment procurement concentrates in Kanto and Kansai metropolitan corridors with dense foodservice channel penetration.
Commercial Milkshake Machine Market Competitive Environment
United States producers anchor one tier; Italian specialists hold differentiated positions in premium hospitality configurations. The vendor base separates into three strategic tiers: integrated manufacturers with captive compressor production, regional specialists with hospitality-focused engineering, and assembly-centric competitors dependent on outsourced thermal components. Consolidation pressure concentrates among mid-scale fabricators lacking refrigerant handler certification programs or backward integration into metal forming.
Within the integrated-manufacturing tier, Taylor Freezer Sales Co. represents North American vertical integration archetypes with in-house compressor production. Carpigiani UK occupies a specialist position exemplifying European hospitality-equipment engineering traditions. Hamilton Beach Brands anchors the compact-appliance segment serving independent operators with footprint-constrained requirements. These three entities collectively illustrate divergent competitive positioning across franchise-network, premium-hospitality, and independent-cafe market vectors.
| Leading Market Players |
|---|
| Taylor Freezer Sales Co. |
| Carpigiani UK |
| Hamilton Beach Brands |
| Robot Coupe |
| Electro Freeze |
| Vita-Mix Corporation |
| Blendtec |
| Smeg |
| Waring Commercial |
| Others |
Value Chain & Pricing Dynamics
EPA Section 608 certified technician concentrations in the US Midwest and Northern Italy create labor-cost differentials that widen pricing-tier spreads between premium factory-authorized service bundles and economy third-party maintenance options. Equipment OEMs with captive training programs capture margin premiums through warranty attach rates that independent assemblers cannot match.
Pricing Analysis
Capacity additions in China and Mexico are reshaping price floors for compressor housings and condenser coils, compressing margins for assembly-only competitors lacking backward integration. Pricing stratifies across premium, standard, and economy tiers based on NSF certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because copper and aluminum commodity volatility feeds through to spot-market component sourcing. Independent cafe operators exhibit highest price sensitivity, while US franchise networks prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from large US quick-service chains mandate multi-supplier qualification for compressor and control module procurement, fragmenting order concentration. Manufacturing draws from Italy, the United States, and China for thermal management components, with refrigerant handler certification creating bottlenecks in field service networks. Single-source vulnerability concentrates in variable-speed drive controllers sourced from specialized German and Japanese suppliers. Distribution runs through broadline foodservice wholesalers bundling equipment with rebate navigation for US Inflation Reduction Act incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on refrigerant transition cost-down curves and premium-tier specification locks with institutional buyers upgrading for EU Ecodesign compliance.
For Market Incumbents: Cement specification control by accelerating R&D roadmaps for propane-compatible compressor architectures ahead of F-Gas Regulation phase-down deadlines. Acquire refrigerant handler training capabilities to internalize field service response times, defending against distributor disintermediation by large US franchise groups sourcing direct from component suppliers. For New Entrants and Emerging Players: IoT-enabled predictive maintenance platforms offer a technology-first wedge into recurring revenue pools currently dominated by legacy OEM service contracts. Target UK specialty coffee chains and Japanese convenience store operators with compact single-spindle configurations featuring vibration sensors and remote diagnostics. Pursue channel partnerships with broadline wholesalers bundling rebate navigation for US efficiency incentives. For Investors and Strategic Acquirers: Commercial kitchen equipment manufacturers with captive compressor production are the most active acquirer in this space, seeking refrigerant-certified service networks. Five-to-ten year viability favors integrated manufacturers with backward integration into metal forming and lower-global-warming-potential coolant R&D pipelines. Monitor EPA Section 608 technician certification program expansion as inflection indicator for field service capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition R&D Acceleration | Propane and CO2 compressor redesigns lock EU Ecodesign-compliant specifications with institutional buyers ahead of F-Gas quota reductions. |
| Predictive Maintenance Platform Launch | Vibration sensors and leak detection shift revenue toward recurring service attach rates with franchise network operators. |
| Backward Integration into Compressor Manufacturing | In-house thermal component production defends margin control against copper and aluminum input volatility. |
| Refrigerant Handler Certification Program | Internalized technician training protects uptime guarantees against EPA Section 608 labor shortages. |
| Compact Countertop Configuration Expansion | Reduced footprint specifications capture replacement-cycle compression among UK and US urban cafe operators. |
Study Parameters
Bottom-up foodservice operator modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with quick-service procurement directors, commercial kitchen equipment distributors, refrigerant handler training program administrators, and aftermarket service heads were validated against secondary sources including US Department of Energy appliance efficiency filings, EU Ecodesign Directive implementation reports, and NSF International certification databases. Trade data from customs records and foodservice equipment manufacturer SEC disclosures provided cross-reference points for volume reconciliation.
Historical trendline analysis across installed base replacement cycles and new store development patterns informed projection parameters. The analytical framework segments by product configuration, cooling technology, end-user channel, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating energy-efficiency compliance deadlines and frozen-beverage menu expansion rates. Refrigerant phase-down schedules and technician certification pipeline data served as industry-specific forecast inputs.
The model holds under stable commodity price environments and phased regulatory implementation; deviation in copper and aluminum volatility or accelerated F-Gas Regulation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Dairy Processing Equipment Market