
 Soft Serve Ice Cream Machines Market | 2026-2036
Soft Serve Ice Cream Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Serve Ice Cream Machines Market Analytics
Single-source procurement of compressor and refrigeration assemblies is restructuring into multi-source strategies as OEMs seek supply resilience. Hoshizaki leverages its vertically integrated refrigeration component production to control lead times and quality consistency. Taylor anchors North American market presence through extensive distributor networks and certified technician training programs. Stoelting differentiates via specialized pump-driven systems that reduce operator skill requirements in high-turnover labor environments.
Soft serve ice cream machines are electromechanical freezing systems that aerate and dispense dairy or non-dairy base mixes at controlled temperatures between 18°F and 22°F through continuous scraping freezer barrels; their primary commercial purpose is to produce consistent, overrun-controlled frozen desserts at high throughput rates in foodservice settings. Twin Flavor configurations capture premium positioning by enabling swirl combinations that command higher per-ounce pricing from consumers. Fully Automatic operation modes are displacing manual alternatives as labor costs rise and operators prioritize consistency over artisanal control. Floor Standing units dominate volume shipments due to their capacity advantage, though Countertop variants are gaining traction in space-constrained convenience stores and ghost kitchen formats.
The U.S. FDA and NSF International standards govern equipment sanitation and food contact surface compliance, while the EPA's SNAP program regulates refrigerant transitions that compel R290 propane and CO2 system redesigns. The EU's F-Gas Regulation and CE marking requirements create parallel compliance obligations for manufacturers serving European foodservice chains. Stakeholders must monitor refrigerant phase-down timelines and energy efficiency labeling expansions that will reshape product development priorities and regional market access conditions.
Market Dynamics
The U.S. FDA's Food Safety Modernization Act is compressing equipment replacement cycles as operators face intensified sanitation audits and documentation requirements that legacy machines cannot satisfy.
Growth Catalysts
- Quick-service restaurant expansion:Chain operators are deploying soft serve dessert programs to capture margin-rich traffic during shoulder hours, driving equipment procurement across franchise networks.
- EPA SNAP refrigerant mandates:The phasedown of hydrofluorocarbon refrigerants is compelling system redesigns around R290 propane and CO2 architectures that qualify for utility rebate programs.
- Convenience store format upgrades:Petroleum retailers are retrofitting forecourt locations with frozen treat capabilities to diversify revenue streams beyond fuel sales.
Market Restraints
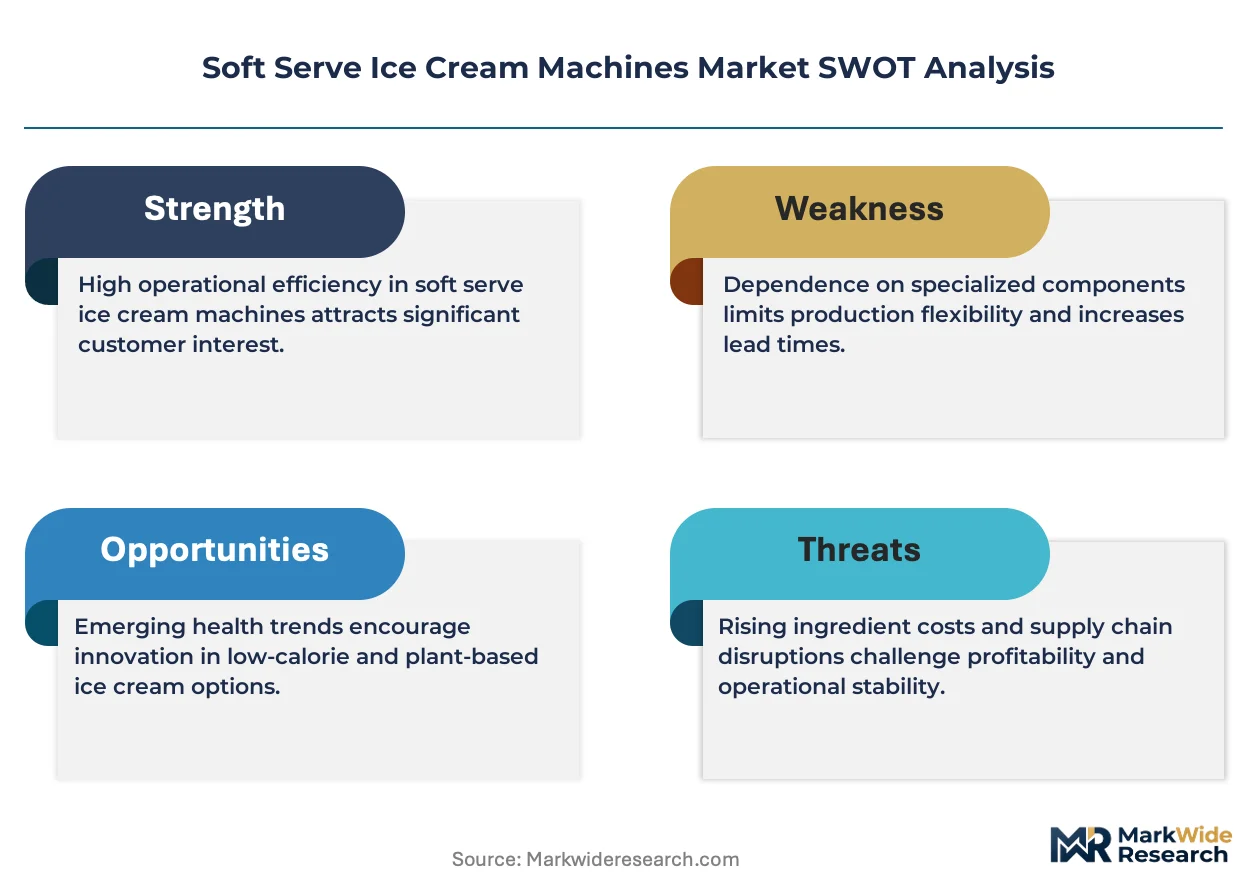
- Copper and aluminum price volatility:Compressor and heat exchanger manufacturing faces input cost instability that OEMs struggle to pass through in fixed-price distributor contracts.
- Single-source compressor dependency:Tier-1 refrigeration component supply concentrates among a handful of European and Asian suppliers, creating vulnerability to geographic disruption.
- NSF/ANSI 6 certification timelines:Sanitation validation protocols for new equipment platforms extend lead times by four to six months, delaying revenue recognition.
Strategic Opportunities
- Ghost kitchen penetration:Delivery-only dessert concepts in dense urban corridors require compact countertop configurations with minimal ventilation infrastructure.
- EU F-Gas Regulation alignment:Manufacturers achieving CE marking and refrigerant compliance gain preferential access to European quick-service chain procurement.
- Non-dairy base compatibility:Equipment engineered for oat, coconut, and almond milk formulations captures plant-based menu expansion in coastal metropolitan markets.
Industry Challenges
- Certified technician scarcity:Refrigeration service networks lack sufficient factory-trained personnel to support warranty obligations and emergency repair demand.
- Legacy control system integration:New automatic dispensing platforms must interface with existing point-of-sale and inventory management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Serve Ice Cream Machines Market |
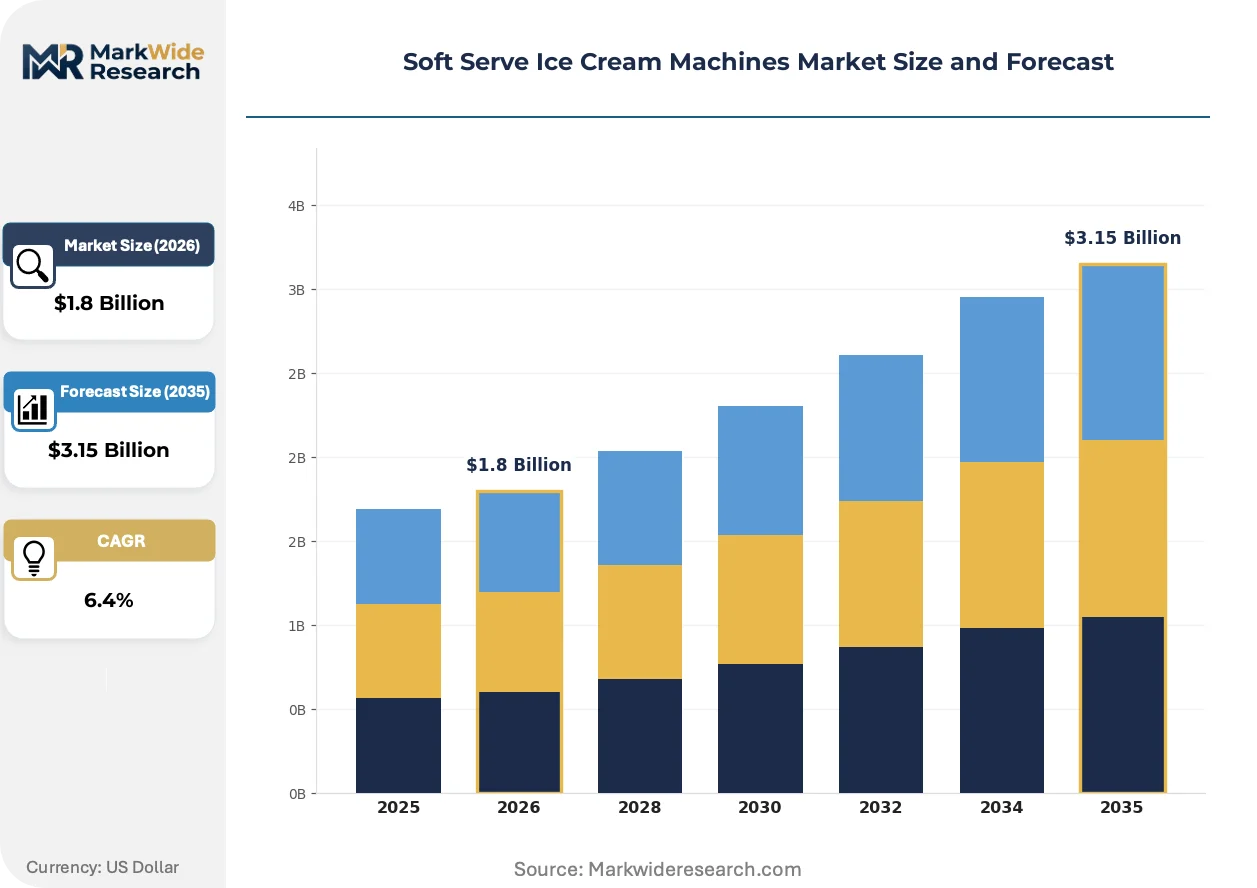
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Flavor, Twin Flavor, Soft Serve Mix, Countertop End User: Restaurants, Ice Cream Shops, Convenience Stores, Catering Services Operation Mode: Manual, Semi-Automatic, Fully Automatic, Self-Serve Configuration: Floor Standing, Wall Mounted, Portable, Built-In |
| Companies Covered | Hoshizaki, Breville, Taylor, Garvee, Cuisinart, Stoelting, Electrolux, Lello, Carpigiani, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Serve Ice Cream Machines Market Evolving Landscape
Equipment architecture is pivoting from mechanical complexity toward sensor-driven automation that reduces operator judgment and standardizes output consistency across high-turnover labor environments.
Predictive maintenance systems leveraging vibration sensors and refrigerant pressure telemetry are electrifying aftermarket service economics. Large franchise operators are mandating connected-machine contracts that bundle remote monitoring with priority technician dispatch, compressing unplanned downtime from days to hours and shifting vendor revenue toward recurring service streams.
The EU F-Gas Regulation's phasedown schedule is accelerating hydrocarbon refrigerant adoption in export-bound product lines. Manufacturers serving European quick-service chains must redesign evaporator and condenser geometries to accommodate flammable refrigerant charge limits, with CE marking validation becoming a gatekeeper for continental procurement eligibility.
Buying committees at multi-unit operators are unbundling equipment procurement from legacy bundled service agreements. Direct sourcing through manufacturer-certified distributors is displacing foodservice equipment broadliners, with procurement teams negotiating extended warranty terms and technician certification guarantees as standalone contract variables in the United States.
Soft Serve Ice Cream Machines Market Segmentation
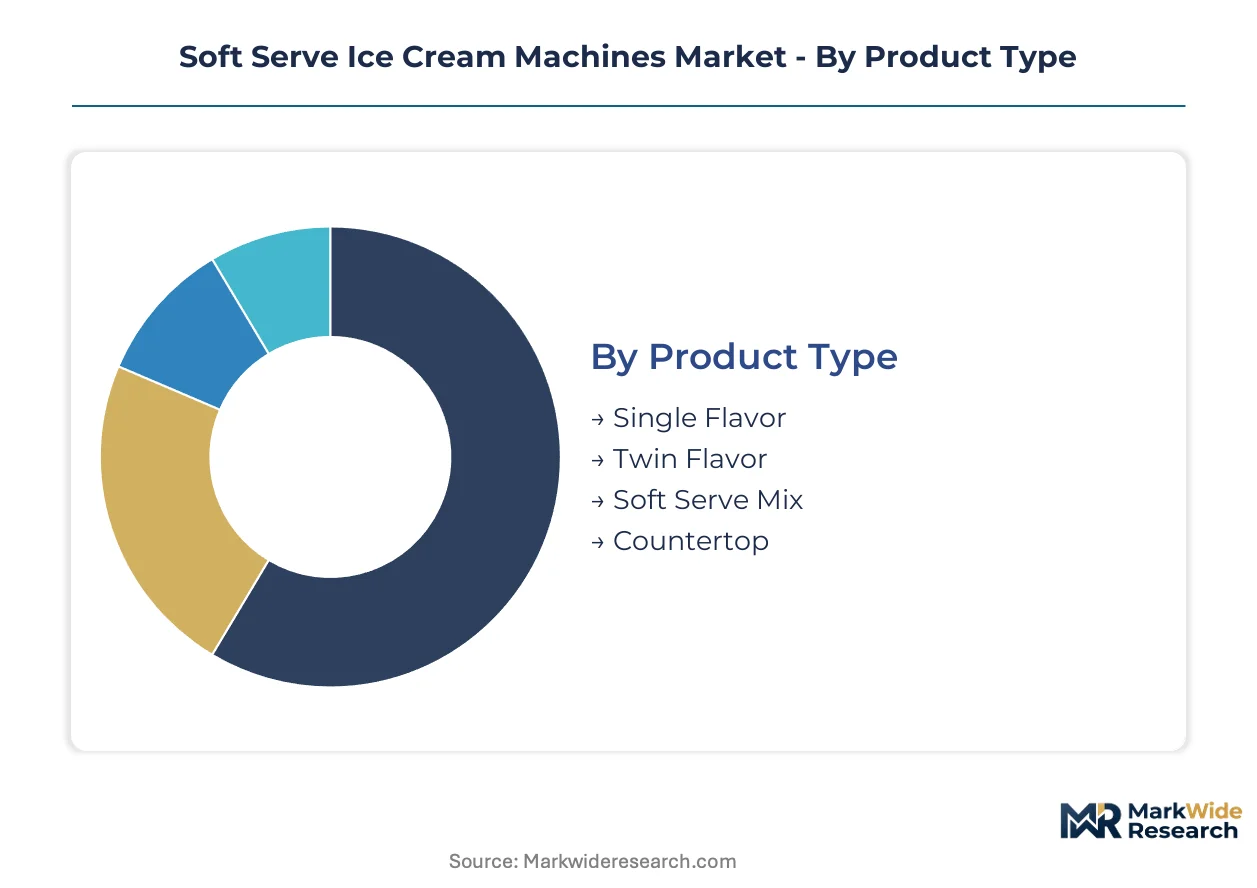
Equipment segmentation in the soft serve market determines capital deployment patterns, operator training requirements, and aftermarket service economics. Distinct product configurations command different price tiers and installation footprints, shaping procurement decisions across franchise networks and independent operators.
Product Type:
Capital intensity varies sharply across product types, with multi-flavor systems requiring dual refrigeration circuits and expanded compressor capacity that drive upfront investment multiples above baseline configurations.
- Single Flavor:These units deploy a single freezing barrel with one hopper and dispensing head, minimizing electrical load and refrigerant charge. Demand concentrates in small-footprint convenience stores and mobile catering operations where throughput requirements remain modest and installation costs must stay contained.
- Twin Flavor:Dual-barrel architectures enable swirl combinations through independent temperature control zones and synchronized dispensing mechanisms. Quick-service restaurant chains in the United States specify these systems for dessert menu premiumization, leveraging visual appeal and flavor customization to justify higher per-ounce pricing.
- Soft Serve Mix:Pre-formulated liquid or powder base products that ship in bag-in-box or bulk tank configurations. The segment ties equipment utilization rates to supply chain reliability and shelf-stable logistics.
- Countertop:Compact units with reduced hopper capacity and ventilation requirements designed for space-constrained environments. Ghost kitchen operators and petroleum retail forecourts specify these for minimal infrastructure retrofit.
Twin Flavor systems absorb the bulk of installed capacity in chain restaurant deployments; Countertop configurations are expanding most quickly in delivery-only and convenience formats.
End User:
Application context dictates duty cycle intensity, sanitation protocol rigor, and service response time expectations that segment the customer base into distinct procurement behaviors.
- Restaurants:Full-service and quick-service operators run machines through extended daily cycles with high peak-to-average load ratios. The FDA's Food Safety Modernization Act documentation requirements favor automatic cleaning systems and HACCP-compliant designs in the United States.
- Ice Cream Shops:Dedicated dessert concepts maximize machine utilization with continuous operation and frequent flavor rotation. These operators prioritize rapid freeze-down capability and consistent overrun control for product density standards.
- Convenience Stores:Petroleum retailers and independent c-stores deploy soft serve as incremental traffic drivers with lower throughput expectations. Equipment must tolerate intermittent use and simplified operator interfaces.
- Catering Services:Mobile and event-based operators require portable power compatibility and rapid setup breakdown. NSF/ANSI 6 certification for food contact surfaces remains mandatory across all deployment contexts.
Restaurants account for the dominant share of annual equipment procurement; Catering Services are climbing the fastest as event-based dessert concepts proliferate in metropolitan markets.
Operation Mode:
Labor cost trajectories and consistency requirements are pushing automation depth as the primary technology differentiator across operator categories.
- Manual:Operator-controlled dispensing with hand-operated levers and visual judgment of product texture. These systems persist in artisanal concepts and low-volume installations where capital constraints outweigh labor cost concerns.
- Semi-Automatic:Pre-programmed portion control with manual initiation, bridging consistency and operator discretion. Mid-scale independent operators favor these for reduced training burden without full automation premium.
- Fully Automatic:Sensor-driven viscosity monitoring, automated dispensing, and integrated cleaning cycles that minimize human intervention. Franchise networks with high staff turnover specify these to standardize output quality and reduce supervision requirements.
- Self-Serve:Customer-operated interfaces with payment integration and portion limiting, common in buffet and family entertainment center deployments.
Fully Automatic systems command the largest installed base among multi-unit operators; Self-Serve configurations are gaining share fastest in experiential retail and entertainment venues.
Configuration:
Physical installation constraints and ventilation infrastructure availability determine the feasible configuration set for each deployment site.
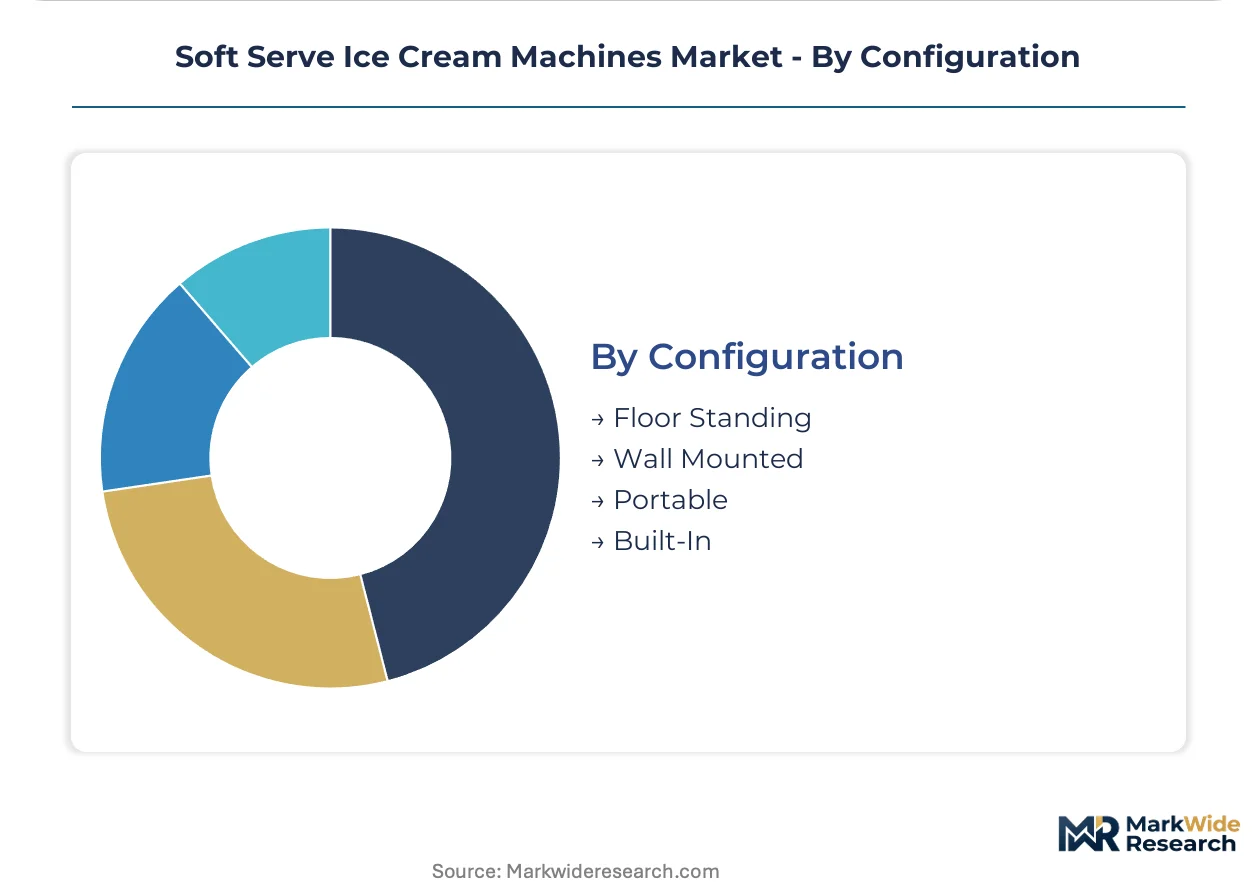
- Floor Standing:Full-capacity units with integrated refrigeration compressors and expanded hopper volumes for high-throughput environments. These dominate quick-service restaurant back-of-house installations.
- Wall Mounted:Space-efficient designs that suspend dispensing heads from structural supports with remote refrigeration. Urban locations with premium square footage utilize these for customer-facing visibility.
- Portable:Castor-mounted or cart-integrated systems with self-contained power and water connections for event and catering mobility.
- Built-In:Custom-integrated units that recess into millwork and counter assemblies for architectural cohesion in flagship locations.
Floor Standing configurations hold the majority of active installed units; Portable systems are expanding most quickly in experiential and temporary retail formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in the United States, where chain restaurant expansion and convenience store format upgrades sustain replacement cycles across quick-service and petroleum retail channels.
United States
Quick-service restaurant chains deploy soft serve dessert programs to capture margin-rich traffic during shoulder hours. The FDA's Food Safety Modernization Act imposes stringent sanitation documentation requirements that compress equipment replacement timelines. Dallas-Fort Worth and Atlanta metropolitan clusters anchor franchise equipment procurement volumes.
Germany
European quick-service chains demand CE-marked equipment compliant with hydrocarbon refrigerant charge limits. The EU F-Gas Regulation's phasedown schedule accelerates R290 propane system redesigns among export-bound manufacturers. Munich and Hamburg industrial corridors concentrate distributor networks serving Central European foodservice chains.
China
Urban convenience store operators retrofit forecourt locations with frozen treat capabilities to diversify beyond fuel sales. The country's national refrigeration equipment standards govern compressor efficiency and food contact surface compliance. Shanghai and Guangzhou manufacturing clusters produce countertop configurations for domestic ghost kitchen penetration.
Japan
Compact equipment formats dominate in space-constrained urban retail environments with high labor turnover. METI energy efficiency labeling programs influence procurement specifications for automatic dispensing systems. Tokyo and Osaka metropolitan markets prioritize sensor-driven viscosity monitoring to standardize output consistency.
United Kingdom
Petroleum retailers and independent convenience operators deploy soft serve as incremental traffic drivers with simplified operator interfaces. CE marking requirements and post-Brexit UKCA conformity assessment procedures extend equipment validation timelines. London and Manchester urban corridors concentrate delivery-only dessert concept proliferation.
Soft Serve Ice Cream Machines Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs respond to supply chain restructuring and refrigerant transition mandates. The vendor base organizes around three strategic archetypes: vertically integrated refrigeration specialists, distributor-network-dependent regional anchors, and pump-driven system innovators. M&A activity concentrates among component suppliers seeking captive compressor capacity. Geographic expansion into European CE-marked product lines represents a secondary competitive vector as manufacturers chase quick-service chain procurement eligibility.
Within the vertically integrated tier, Hoshizaki exemplifies upstream control over refrigeration component production. Taylor anchors North American market presence through extensive distributor networks. Stoelting occupies a specialist position with pump-driven architectures that reduce operator skill requirements in high-turnover labor environments.
| Leading Market Players |
|---|
| Hoshizaki |
| Breville |
| Taylor |
| Garvee |
| Cuisinart |
| Stoelting |
| Electrolux |
| Lello |
| Carpigiani |
| Others |
Value Network & Pricing Analysis
Certified refrigeration technician scarcity in the United States widens pricing-tier spreads as labor-cost differentials between automatic and manual systems reshape procurement decisions across quick-service franchise networks.
Pricing Analysis
Warranty and service-bundling unbundling is restructuring contract negotiations as multi-unit operators separate equipment procurement from legacy maintenance agreements. Three-tier pricing structure across premium, standard, and economy levels differentiates by NSF/ANSI 6 certification grade and factory-trained technician coverage. Cost compression in economy tiers is intensifying because copper and aluminum input volatility strains fixed-price distributor contracts. Independent operators exhibit highest price sensitivity; large franchise networks prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Compressor and refrigeration assembly supply rests on concentrated European and Asian component manufacturers with limited geographic diversification. Copper tubing, aluminum heat exchangers, and hermetic compressors anchor raw material dependencies. Single-source vulnerability dominates structural risk as Tier-1 refrigeration component suppliers concentrate production in discrete manufacturing corridors. Distribution runs through manufacturer-certified distributor networks that bundle installation, training, and aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Food Safety Modernization Act erects a cost-of-compliance barrier that rewards NSF/ANSI 6 certified incumbents while filtering out capital-constrained challengers unable to absorb extended validation timelines.
For Market Incumbents: Lock in distributor exclusivity agreements across Dallas-Fort Worth and Atlanta metropolitan clusters before refrigerant transition mandates accelerate. Anchor aftermarket revenue through connected-machine remote monitoring contracts that compress unplanned downtime. Capacity addition in CE-marked product lines captures European quick-service chain procurement eligibility as EU F-Gas Regulation compliance becomes a gatekeeper.
For New Entrants and Emerging Players: Ghost kitchen operators in dense urban corridors represent the most penetrable buyer archetype given minimal ventilation infrastructure requirements and compact countertop specifications. Delivery-only dessert concepts lack incumbent service coverage and prioritize rapid installation turnaround over brand heritage. Direct sourcing partnerships with petroleum retail forecourt upgraders bypass entrenched foodservice equipment broadliner relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated refrigeration specialists given hydrocarbon refrigerant redesign catalysts and utility rebate program alignment. Long-term viability favors manufacturers with captive compressor capacity and in-house component production. Watch EPA SNAP program enforcement intensity as the inflection indicator for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU F-Gas Regulation compliance unlocks continental quick-service chain procurement eligibility. |
| Backward Integration | Captive compressor production insulates against Tier-1 supplier geographic disruption risk. |
| Connected Machine Platform | Remote monitoring telemetry shifts vendor revenue toward recurring service streams. |
| Hydrocarbon Refrigerant Redesign | R290 propane architectures qualify for utility rebate programs and satisfy EPA mandates. |
| Technician Certification Program | Factory-trained service networks defend warranty obligations and emergency repair demand. |
Research Methodology
Document review covered FDA enforcement guidance, EPA SNAP program filings, and EU F-Gas Regulation implementation schedules, complemented by interviews with quick-service restaurant equipment procurement directors, refrigeration service network managers, NSF certification auditors, and foodservice distributor principals. Secondary validation drew from customs trade data, equipment registration databases, and utility rebate program disclosures. Bottom-up installation unit estimates triangulated against top-down foodservice capital expenditure benchmarks.
Segment-level outputs across the analysis window reflect modeled deployment rates by product configuration, operation mode, and end-user category with refrigerant transition timelines and labor cost trajectories as demand shapers. CAGRs derive from equipment replacement cycle compression, chain restaurant expansion patterns, and convenience store format upgrade intensity.
Revisions become necessary when EPA refrigerant phase-down accelerates, copper and aluminum commodity volatility exceeds historical bands, or certified technician scarcity triggers service network collapse. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Milk Chiller Market