
 Milk Clarifier Market | 2026-2036
Milk Clarifier Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Clarifier Market Foresight
A shift from single-source procurement to multi-source equipment supply is rebalancing vendor relationships across the milk clarifier value chain. GEA Group leverages its centrifuge engineering heritage to anchor premium positions in European dairy cooperatives. Tetra Pak competes through integrated processing line architectures that bundle clarifiers with aseptic packaging systems. Alfa Laval differentiates via aftermarket service contracts and remote monitoring capabilities that extend equipment lifecycles.
A milk clarifier is a centrifugal separation device engineered to remove somatic cells, bacteria, and particulate impurities from raw milk through controlled gravitational force application, typically operating at bowl speeds exceeding 5,000 rpm and discharge temperatures of 50-55°C. Its primary industrial purpose is to standardize milk composition, extend shelf stability, and reduce downstream processing contamination risks in fluid milk and derivative production. Continuous clarifiers dominate installed capacity in large-scale dairy processing plants where uninterrupted 24-hour operation justifies capital intensity, while compact clarifiers occupy the fastest-growing niche among regional creameries and food service distributors seeking modular footprint reductions. Centrifugation technology leads value capture in whey clarification applications where protein recovery rates directly determine margin pools.
EU hygiene standards under EFSA oversight mandate pathogen reduction thresholds that compel clarifier upgrades in member-state dairy facilities, while FDA Grade A Pasteurized Milk Ordinance requirements shape equipment specifications for US export-oriented processors. REACH chemical compliance and CE marking obligations add certification layers that filter non-compliant suppliers from European procurement shortlists. Stakeholders must monitor evolving energy-efficiency benchmarks under the EU Green Deal, as electricity consumption per liter processed becomes a decisive tender criterion.
Market Dynamics
Centrifugation technology is displacing legacy mechanical separation across European dairy processing, driven by EU Green Deal energy-efficiency mandates that penalize high-electricity operations. Equipment procurement now prioritizes clarifiers with sub-0.5 kWh per 1000L throughput ratings.
Growth Catalysts
- EU Green Deal emissions benchmarks:Dairy cooperatives in Bavaria and northern France face binding electricity reduction targets that accelerate clarifier replacement cycles.
- Whey protein recovery economics:Centrifugation technology captures margin pools in high-volume whey processing where protein yield rates determine facility profitability.
- EFSA pathogen thresholds:Hygiene mandates under European Food Safety Authority oversight compel clarifier upgrades in member-state fluid milk operations.
Market Restraints
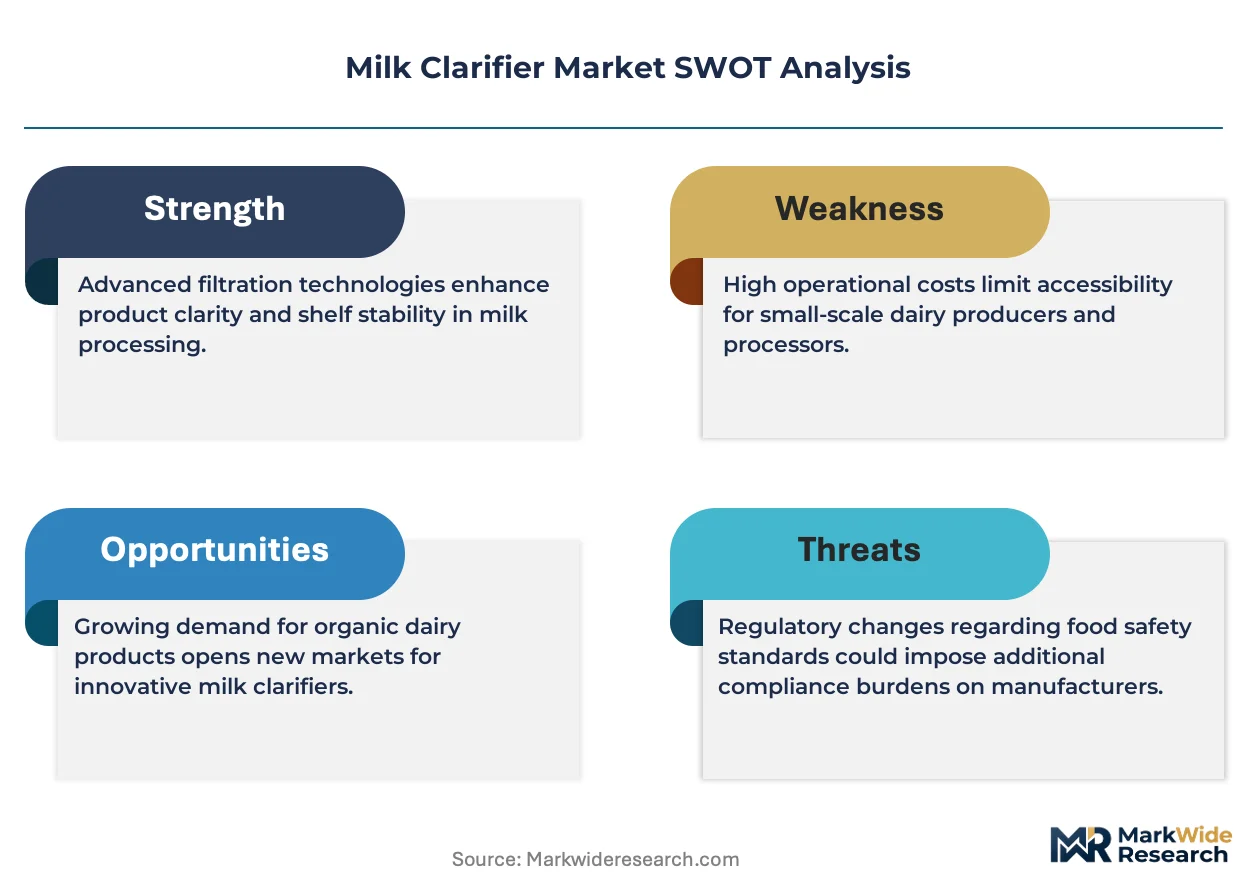
- Stainless steel input volatility:Bowl and disc stack fabrication depends on austenitic steel grades subject to nickel price swings that compress equipment margins.
- Specialized maintenance labor scarcity:High-speed bearing replacement and bowl balancing require certified technicians concentrated in Germany and the Netherlands.
- REACH chemical compliance costs:CE marking and ECHA substance restrictions add certification layers that filter smaller suppliers from European tender shortlists.
Strategic Opportunities
- Modular compact clarifiers:Regional creameries in France's Auvergne-Rhône-Alpes and Italy's Lombardy seek footprint-reduced equipment for flexible batch processing.
- Remote monitoring service contracts:Predictive maintenance platforms using vibration sensors and oil analysis extend equipment lifecycles and lock in recurring revenue.
- CSRD sustainability reporting alignment:Corporate Sustainability Reporting Directive disclosure requirements create demand for clarifiers with embedded energy and water consumption tracking.
Industry Challenges
- High-speed centrifuge technician certification:Bowl speeds exceeding 5,000 rpm require specialized training programs that lag equipment deployment timelines.
- Legacy system integration complexity:Continuous clarifier installation in 24-hour operations demands line shutdown coordination that disrupts just-in-time milk collection schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Clarifier Market |
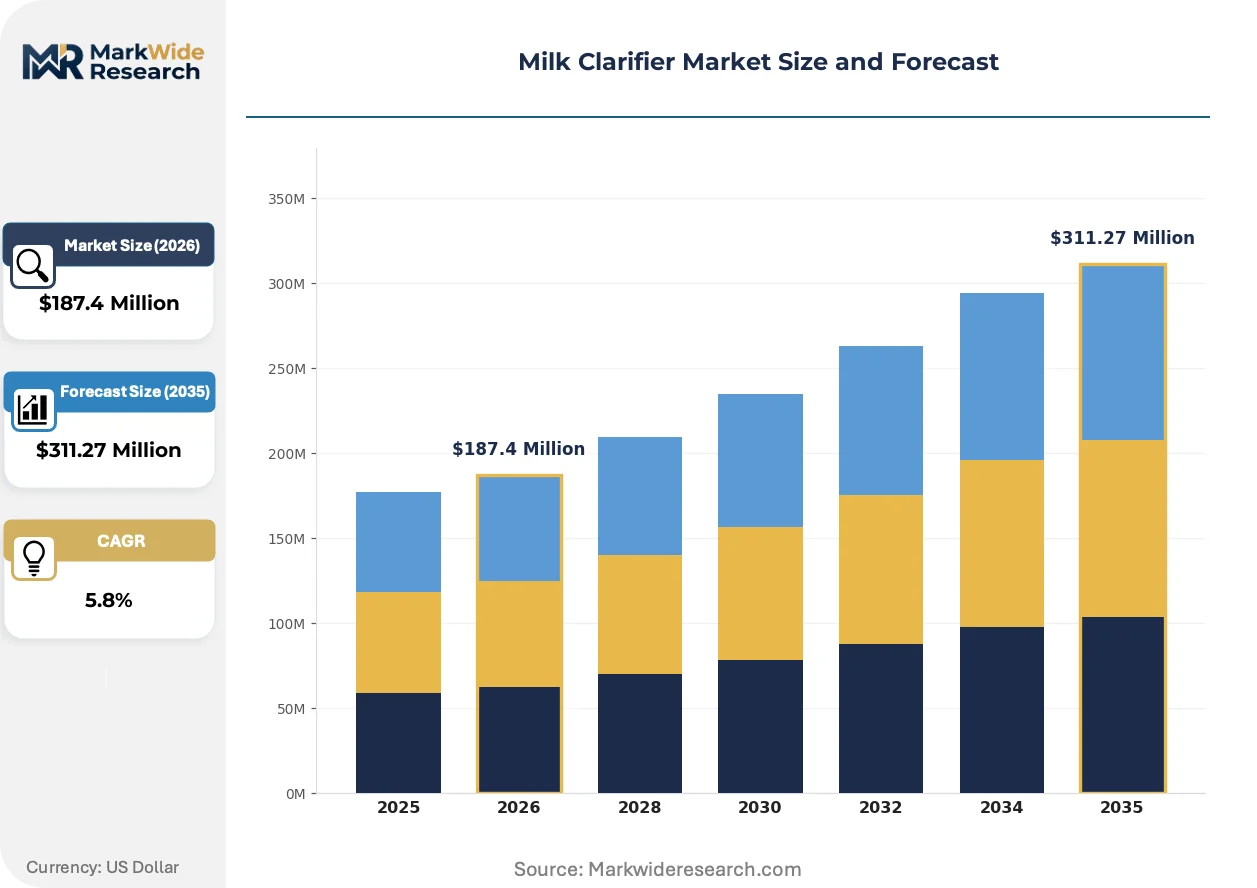
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Clarifiers, Batch Clarifiers, Compact Clarifiers, High-Performance Clarifiers End User: Dairy Processing Plants, Beverage Manufacturers, Food Service Industries, Research Laboratories Technology: Mechanical Separation, Membrane Filtration, Centrifugation, Hydrocyclone Technology Application: Milk Processing, Whey Clarification, Cream Separation, Skimmed Milk Processing |
| Companies Covered | Tetra Pak, GEA Group, SPX Flow, Alfa Laval, ANDRITZ Frautech, Synelco, Westfalia Separator, Flottweg, DeLaval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Clarifier Market Shifts & Advancements
Digitalization of separation equipment is reshaping how dairy processors manage uptime and energy consumption. Real-time data streams from clarifier sensors now feed directly into plant-wide optimization systems.
Self-cleaning bowl technology is integrating automated discharge mechanisms that eliminate manual CIP interruptions. Large-scale processors in the Netherlands and Denmark adopt these systems to sustain 24-hour operation without throughput penalties. This integration compresses labor requirements while maintaining EFSA-mandated hygiene standards.
REACH chemical restrictions and F-Gas Regulation phase-downs are forcing refrigerant and lubricant reformulation in clarifier cooling systems. Equipment manufacturers reformulate hydraulic fluids to meet ECHA substance restrictions. German dairy cooperatives lead compliance adoption, treating certification as a tender differentiator against non-EU suppliers.
Service unbundling is fragmenting traditional equipment-procurement bundles. Regional creameries now source clarifiers, installation, and maintenance from separate vendors rather than single-source suppliers. This pattern concentrates in France's food service distribution channel, where buyers prioritize modular upgrade paths over integrated line architectures.
Milk Clarifier Market Segmentation
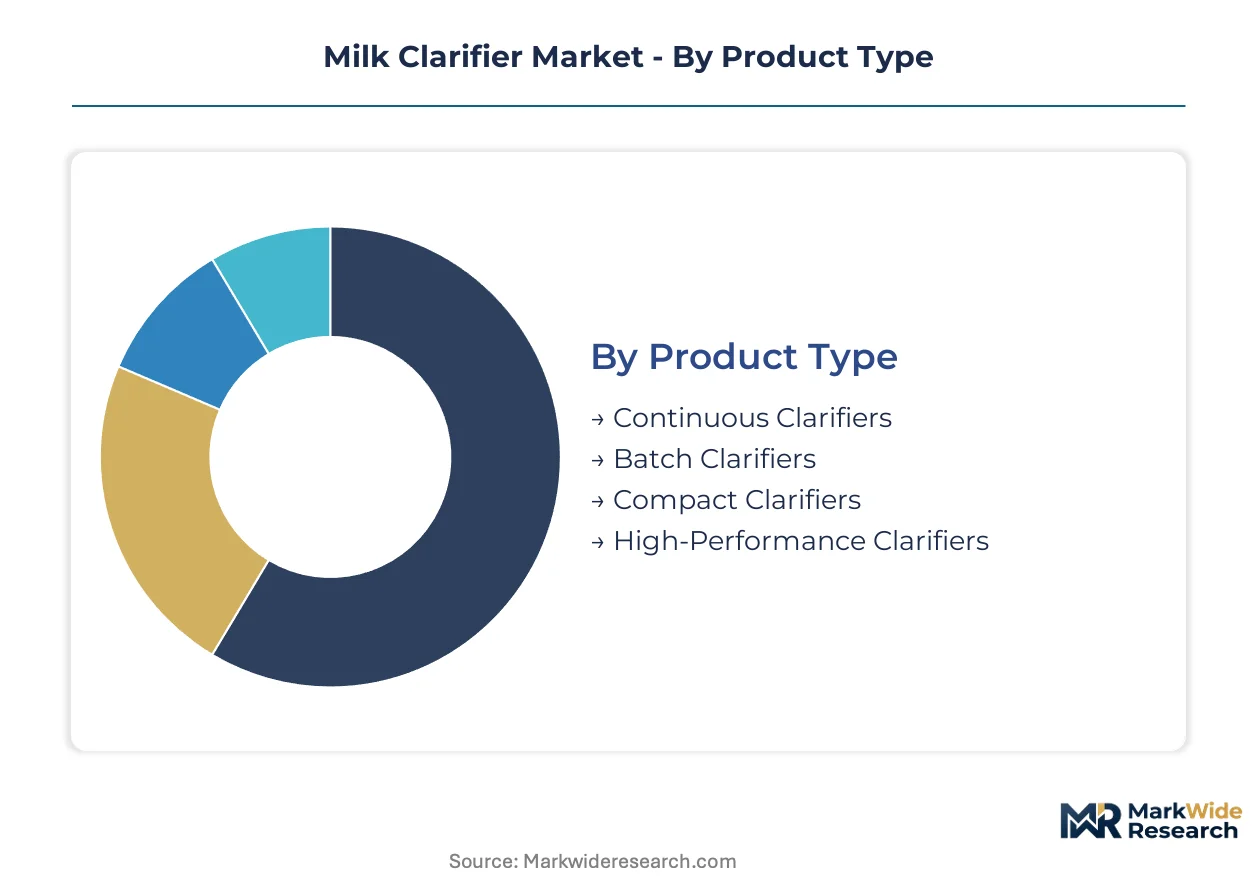
Milk clarifier procurement patterns diverge sharply between high-volume continuous operations and flexible batch configurations. Equipment replacement cycles now favor technologies that reduce electricity consumption per liter processed while maintaining EFSA-mandated pathogen thresholds.
Product Type:
Upgrade cycles in Bavarian and northern French dairy clusters prioritize energy-efficiency ratings over legacy mechanical reliability. Bowl speed optimization and automated discharge mechanisms now dominate tender specifications.
- Continuous Clarifiers:These systems sustain 24-hour operation through self-cleaning bowl technology with bowl speeds exceeding 5,000 rpm. Demand concentrates in the Netherlands' large-scale whey processing facilities where uninterrupted throughput justifies capital intensity against EU Green Deal electricity benchmarks.
- Compact Clarifiers:Modular footprint designs enable regional creameries in France's Auvergne-Rhône-Alpes to deploy flexible batch processing without line reconfiguration. Italian Lombardy food service distributors favor these units for space-constrained urban installations.
- Batch Clarifiers:Smaller dairy cooperatives in Germany's secondary milk belts deploy these for seasonal volume fluctuations.
- High-Performance Clarifiers:Protein recovery specialists in Denmark specify these for whey clarification margin optimization.
Volume placements concentrate in Continuous Clarifiers; the faster expansion belongs to Compact Clarifiers.
End User:
Customer procurement authority varies from centralized cooperative tender boards to fragmented food service distribution channels. REACH compliance certification filters supplier eligibility differently across buyer types.
- Dairy Processing Plants:These facilities operate under EFSA hygiene mandates that compel clarifier upgrades to meet pathogen reduction thresholds. Bavarian cooperatives anchor equipment demand through binding EU Green Deal emissions commitments.
- Beverage Manufacturers:Whey protein isolate producers in the Netherlands prioritize centrifugation technology where yield rates determine facility profitability margins.
- Food Service Industries:French distributors seek modular equipment for refrigerated logistics integration.
- Research Laboratories:Dairy research stations in Germany specify precision clarifiers for somatic cell study protocols.
Capital deployment concentrates in Dairy Processing Plants; Beverage Manufacturers are climbing the fastest.
Technology:
Centrifugation systems displace legacy mechanical methods where electricity costs dominate operating economics. Membrane filtration competes in protein recovery applications requiring selective molecular separation.
- Centrifugation:Controlled gravitational force application removes somatic cells and bacteria at discharge temperatures of 50-55°C. Danish and Dutch whey processors specify these systems where protein recovery rates directly determine margin pools.
- Mechanical Separation:Older sedimentation-based methods persist in small-scale German creameries with limited capital replacement budgets.
- Membrane Filtration:Selective pore-size separation enables specialized whey protein fractionation for sports nutrition manufacturers.
- Hydrocyclone Technology:Pre-clarification stages in large French plants use these for initial solids reduction before centrifugal polishing.
Installed base concentrates in Centrifugation; Membrane Filtration shows the steepest expansion trajectory.
Application:
Fluid milk standardization demands differ from whey clarification economics. Cream separation margins vary with butterfat price volatility.
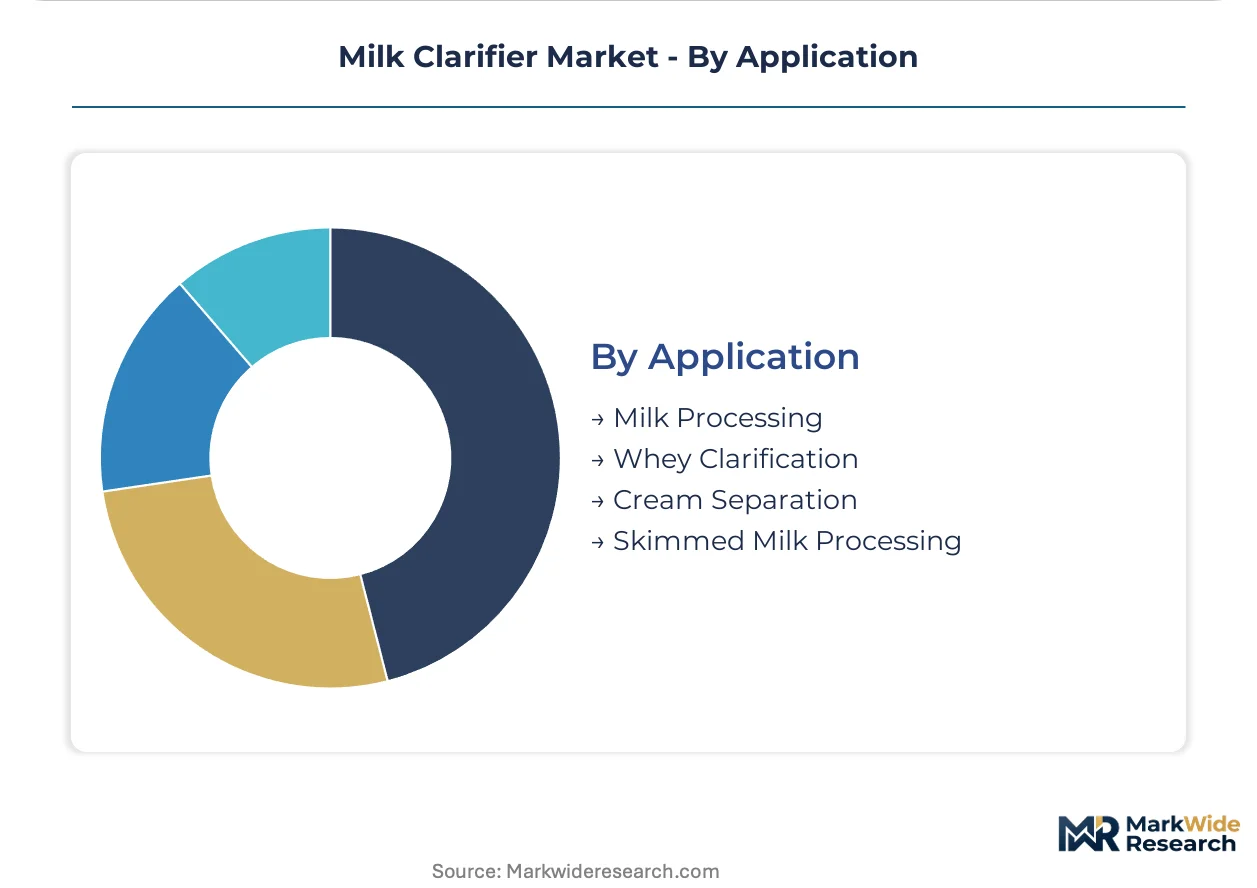
- Whey Clarification:Centrifugal separation recovers protein concentrates for sports nutrition and infant formula. Netherlands processing plants deploy continuous clarifiers here where yield optimization determines facility viability.
- Milk Processing:Pathogen reduction for fluid milk shelf stability drives clarifier deployment across German and French fluid milk operations.
- Cream Separation:Butterfat standardization for dairy product manufacturing occurs in northern France's milk belt cooperatives.
- Skimmed Milk Processing:Low-fat fluid milk production lines in Bavaria specify clarifiers for fat content standardization.
Equipment utilization concentrates in Milk Processing; Whey Clarification is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel supply chains from northern European foundries anchor clarifier manufacturing economics. Dairy processing clusters in Germany, the Netherlands, and Denmark concentrate equipment deployment. Bavarian engineering hubs and Dutch whey processing corridors drive centrifugation technology diffusion.
Germany
Bavarian dairy cooperatives anchor European clarifier demand through binding EU Green Deal emissions commitments. EFSA hygiene mandates under European Food Safety Authority oversight compel pathogen-reduction equipment upgrades in fluid milk operations. The northern German milk belt around Lower Saxony deploys continuous clarifiers for 24-hour processing schedules.
Netherlands
Whey protein recovery specialists in Dutch processing corridors prioritize centrifugation yield optimization for facility profitability. REACH chemical compliance and CE marking obligations filter non-compliant suppliers from procurement shortlists. The Gelderland dairy cluster leads adoption of self-cleaning bowl technology for uninterrupted operation.
France
Northern French milk belt cooperatives standardize butterfat content through cream separation clarifiers for dairy product manufacturing. F-Gas Regulation phase-downs force refrigerant reformulation in cooling systems. The Auvergne-Rhône-Alpes region attracts compact clarifier deployments for flexible batch processing in regional creameries.
Denmark
Danish whey processors specify high-performance clarifiers where protein recovery rates determine margin pools. CSRD sustainability reporting requirements create demand for equipment with embedded energy tracking. The Jutland dairy engineering corridor integrates remote monitoring platforms into plant-wide optimization systems.
Italy
Lombardy food service distributors favor compact clarifiers for space-constrained urban installations. EU Green Deal electricity benchmarks accelerate replacement of legacy mechanical separation methods. The Po Valley dairy cluster concentrates procurement authority among cooperative tender boards seeking modular upgrade paths.
Milk Clarifier Market Competitive Landscape
Global majors compete with regional champions across engineering heritage and service bundling. The vendor base stratifies between integrated processing line architects and specialized centrifuge engineers. Three archetypes dominate: heritage engineering houses with centrifuge DNA, diversified packaging-system integrators, and aftermarket service specialists with predictive maintenance platforms. Capacity expansion in Bavarian engineering corridors and strategic partnerships for remote monitoring capability represent the dominant competitive moves.
Within the heritage engineering tier, GEA Group and Alfa Laval exemplify European centrifuge specialists with deep aftermarket service penetration. Tetra Pak occupies a position among integrated line architects that bundle separation equipment with downstream packaging systems. These three anchors represent distinct strategic postures: engineering-centric premium positioning, diversified system integration, and lifecycle service lock-in through predictive maintenance contracts.
| Leading Market Players |
|---|
| Tetra Pak |
| GEA Group |
| SPX Flow |
| Alfa Laval |
| ANDRITZ Frautech |
| Synelco |
| Westfalia Separator |
| Flottweg |
| DeLaval |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap engineering houses across northern Italy and southern Germany anchor supply-side discipline through generational capital structures that resist short-term pricing pressure. Their captive foundry relationships and multi-decade service contracts with Bavarian dairy cooperatives create pricing power that insulates against commodity volatility in stainless steel inputs.
Pricing Analysis
Warranty and aftermarket service bundling separates premium centrifuge vendors from unbundled equipment-only suppliers competing on capital expenditure alone. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked continuous clarifiers commanding substantial premiums over non-compliant alternatives. Cost compression in the economy tier is intensifying because regional creameries now source installation and maintenance from separate vendors rather than accepting bundled line architectures. Food service distributors in France exhibit the highest price sensitivity due to modular upgrade preferences, while Dutch whey processors show the least sensitivity given protein recovery yield economics.
Supply Chain Analysis
Single-source vulnerability sits with austenitic stainless steel suppliers concentrated in Germany, Sweden, and Finland, where nickel price volatility transmits directly into bowl and disc stack fabrication costs. Component dependencies include high-speed bearings from German precision manufacturers, specialized hydraulic fluids subject to REACH reformulation mandates, and refrigerants facing F-Gas Regulation phase-downs. Tariff exposure on Chinese-sourced electronic sensors for remote monitoring platforms represents the dominant structural risk. Distribution runs through OEM-direct channels for large-scale processors and specialized dairy equipment distributors for regional creameries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precision casting and bearing manufacturing is accelerating as vendors seek captive supply of components subject to raw material volatility and specialized labor scarcity.
For Market Incumbents: Deploy predictive maintenance platforms using vibration sensors and oil analysis to lock in recurring service revenue against unbundled procurement trends threatening equipment-only margins. Prioritize CSRD-aligned energy tracking capabilities in new clarifier designs to capture sustainability reporting demand from Danish and Dutch processors. Capacity addition in Bavarian engineering corridors defends geographic proximity advantages against emerging centrifuge specialists from Italy. For New Entrants and Emerging Players: Launch via aftermarket service specialization targeting the fragmented maintenance labor market where certified high-speed centrifuge technicians remain concentrated in Germany and the Netherlands. Compact clarifiers for France's Auvergne-Rhône-Alpes regional creameries offer the most penetrable white space, with modular footprint requirements and flexible batch processing needs underserved by continuous clarifier architectures. Direct technical training partnerships with dairy engineering programs in Lombardy and Lower Saxony accelerate technician pipeline development. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap centrifuge specialists with established CE marking pathways and existing EFSA compliance documentation in northern European dairy corridors. Long-term viability hinges on service contract recurring revenue ratios exceeding equipment sales cyclicality. Monitor nickel price trajectory and REACH chemical restriction implementation pace as inflection indicators for margin compression severity in the standard equipment tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive supply of austenitic steel bowl components insulates German vendors from nickel volatility. |
| Predictive Maintenance Platform Launch | Remote monitoring contracts with Dutch whey processors extend equipment lifecycles and lock recurring revenue. |
| CSRD-Aligned Energy Tracking Integration | Embedded consumption sensors meet Danish sustainability reporting mandates and differentiate tender submissions. |
| Compact Clarifier Capacity Expansion | Footprint-reduced designs capture French regional creamery demand for flexible batch processing configurations. |
| Technician Certification Program Partnership | Dairy engineering collaborations in Lombardy address specialized maintenance labor scarcity constraining deployment timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dairy plant engineers, cooperative procurement directors, aftermarket service technicians, and centrifuge OEM product managers. EFSA guidance documents, REACH substance restriction updates, EU Green Deal implementation reports, and dairy cooperative sustainability disclosures provided regulatory and demand-side validation. Bottom-up equipment installation tracking across Bavarian, Dutch, and Danish processing facilities reconciled against top-down market sizing from trade flow analysis.
Data-stream reconciliation across shipment records, tender announcements, and capital expenditure disclosures informed the analytical framework. Segmentation dimensions modeled include clarifier type, end-user category, technology architecture, and application focus, cross-referenced with regional regulatory cluster variations. CAGRs were derived from trajectory fitting against historical replacement cycle patterns and policy-mandated upgrade timelines. Whey protein recovery yield economics and EU electricity efficiency benchmarks served as industry-specific demand drivers.
Raw material price swings, regulatory implementation delays, and technician certification program expansion rates are the dominant revision risks. Deviation in nickel price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Dairy Machines Market