
 Dairy Machines Market | 2026-2036
Dairy Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Machines Market Outlook
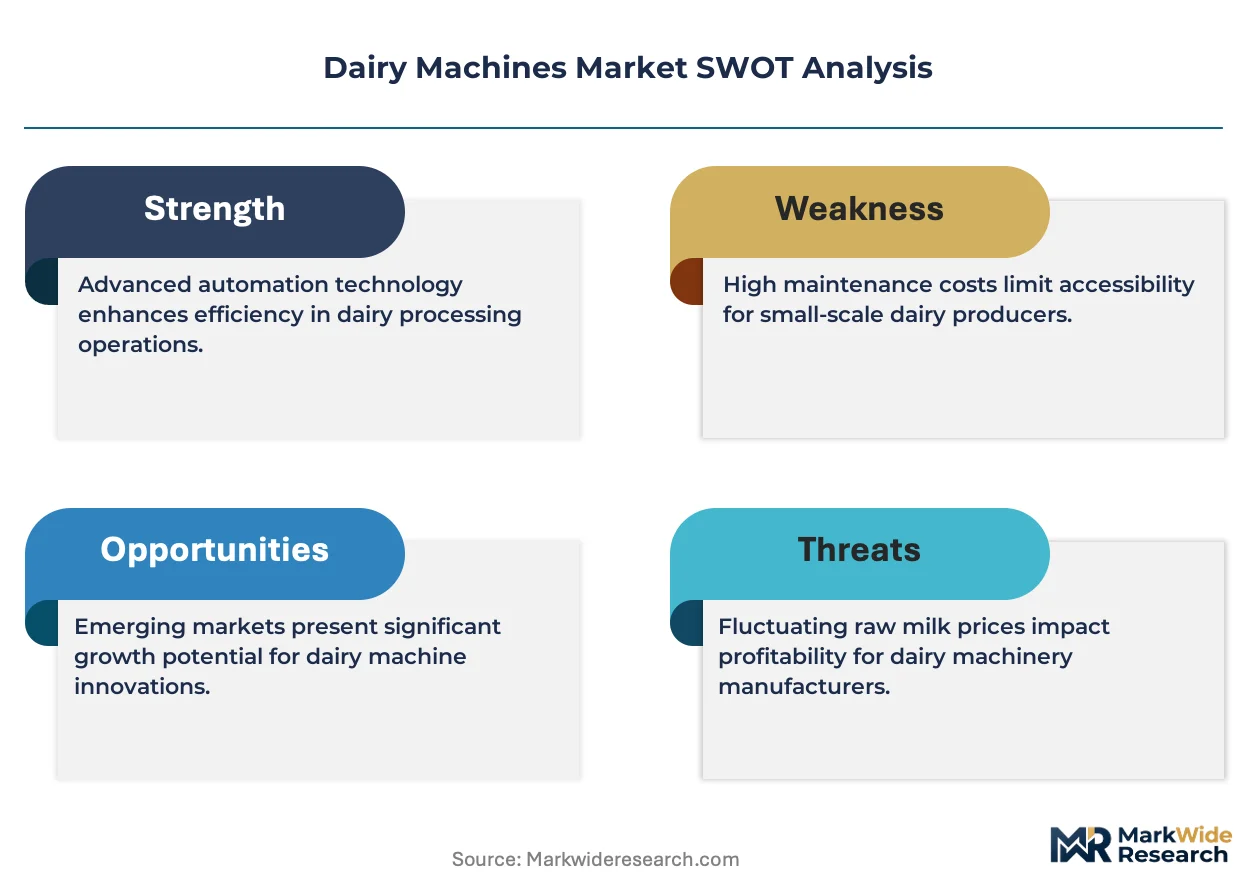
Asset-light leasing and equipment-as-a-service arrangements is tilting competitive dynamics toward mid-sized dairy operations that previously lacked capital for automated infrastructure. GEA Group leverages its integrated processing platform to anchor large-scale plant contracts across European cooperatives. DeLaval sustains technology leadership in robotic milking systems through continuous sensor refinement. Alfa Laval competes on thermal efficiency in pasteurization and separation equipment, occupying premium positions in energy-conscious markets.
Dairy machines encompass mechanical and electromechanical systems engineered for milk handling, thermal processing, fat separation, and coagulation with operational parameters typically spanning CIP-compatible stainless steel construction and temperature control within 0.5 degrees Celsius. These systems serve the industrial transformation of raw milk into standardized, safe, and shelf-stable dairy products for commercial distribution. Milk Pasteurizers command the largest installed base due to universal regulatory requirements for pathogen reduction, while IoT-Enabled Devices represent the fastest-expanding technology category as connectivity enables predictive maintenance and herd-level analytics. Cheese Processing Equipment carries concentrated margin pools where artisanal and industrial scale configurations create divergent equipment specifications.
FDA Grade A standards and USDA dairy plant inspection protocols shape equipment design and validation requirements for US market access, while EFSA hygiene criteria and CE marking obligations govern European product compliance. The EU Green Deal and national carbon accounting frameworks are forcing energy consumption disclosures that favor heat-recovery pasteurizers and variable-frequency drive systems. Stakeholders must monitor evolving MDR-equivalent pressure vessel certifications and carbon border adjustment mechanisms that will determine which equipment configurations retain cross-border eligibility.
Market Dynamics
Robotic milking infrastructure is concentrating capital deployment among mid-scale dairy cooperatives that previously deferred automation due to upfront equipment costs and technical integration complexity.
Growth Catalysts
- EFSA hygiene mandates:European dairy cooperatives accelerate parlour upgrades to meet pathogen reduction protocols, triggering equipment replacement cycles across Germany, Netherlands, and Denmark processing networks.
- Heat-recovery pasteurizers:Energy-conscious processors deploy thermal efficiency systems to satisfy EU Green Deal carbon accounting disclosures and reduce operational expenditure.
- Sensor-integrated milking:IoT-enabled herd analytics drive demand for predictive maintenance capabilities among commercial farms seeking labor optimization.
Market Restraints
- Stainless steel input volatility:CIP-compatible grade 316L price fluctuations compress equipment margins and extend quotation-to-delivery timelines for fabricators.
- Specialized technician scarcity:Robotic system calibration and sensor maintenance require skills concentrated in Northern European service networks, limiting deployment speed.
- CE marking complexity:MDR-equivalent pressure vessel certifications create validation bottlenecks for cross-border equipment shipments.
Strategic Opportunities
- Equipment-as-a-service models:Leasing arrangements open automated infrastructure to capital-constrained mid-sized operations previously excluded from ownership.
- Artisanal cheese processing:Small-batch configurability creates divergent equipment specifications capturing premium margin pools outside commodity dairy.
- Variable-frequency drive integration:Energy recovery systems align with national carbon accounting frameworks mandating consumption transparency.
Industry Challenges
- Legacy system interoperability:Retrofitting IoT sensors onto existing parlour infrastructure demands customized integration protocols and extended commissioning periods.
- Validation timeline compression:FDA Grade A pasteurization certification and USDA dairy plant inspection protocols require simultaneous documentation streams that strain quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Machines Market |
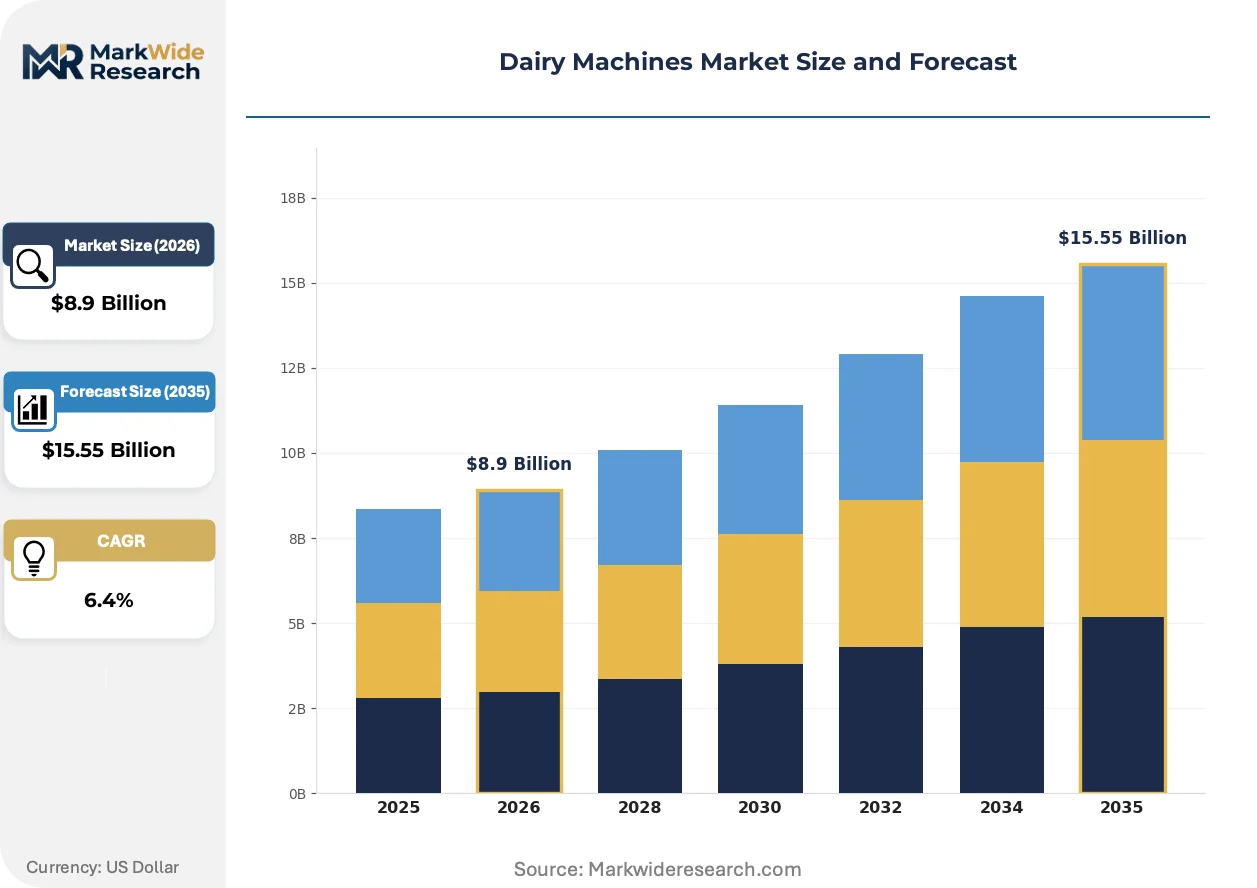
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Pasteurizers, Cream Separators, Butter Churns, Cheese Processing Equipment End User: Dairy Farms, Processing Plants, Milk Distributors, Retail Outlets Technology: Automated Systems, Semi-Automated Systems, Manual Equipment, IoT-Enabled Devices Application: Milk Production, Cheese Production, Yogurt Manufacturing, Ice Cream Production |
| Companies Covered | GEA Group, Alfa Laval, Tetra Pak International S.A., DeLaval, SPX FLOW, IDMC Limited, Lely, Afimilk Ltd., BouMatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Machines Market Strategic Shifts
Connectivity architectures and thermal efficiency standards are restructuring equipment procurement priorities across commercial dairy operations, with regulatory compliance and operational data visibility now co-equal investment drivers.
Robotic milking systems are migrating from fixed-parlour configurations to voluntary-access rotary designs that reduce labour intervention. Large-scale US commercial farms deploy these architectures to meet FDA Grade A throughput requirements while compressing milking duration per animal. The technology is migrating from premium-tier installations toward mid-scale cooperative networks as leasing structures democratize access.
The EU Green Deal carbon accounting framework forces energy consumption disclosures across dairy processing equipment categories. Heat-recovery pasteurizers and variable-frequency drive systems gain preference as processors document thermal efficiency for regulatory compliance. German and Dutch cooperatives lead retrofit deployment, with energy performance now weighted equally against capital expenditure in procurement evaluations.
Service unbundling reshapes vendor-customer relationships as after-sales maintenance separates from initial equipment contracts. Mid-sized dairy operations procure predictive analytics subscriptions independent of hardware purchase, pressuring traditional bundled pricing. This pattern concentrates in European cooperative networks where EFSA-mandated hygiene validation creates recurring compliance service demand.
Dairy Machines Market Segmentation
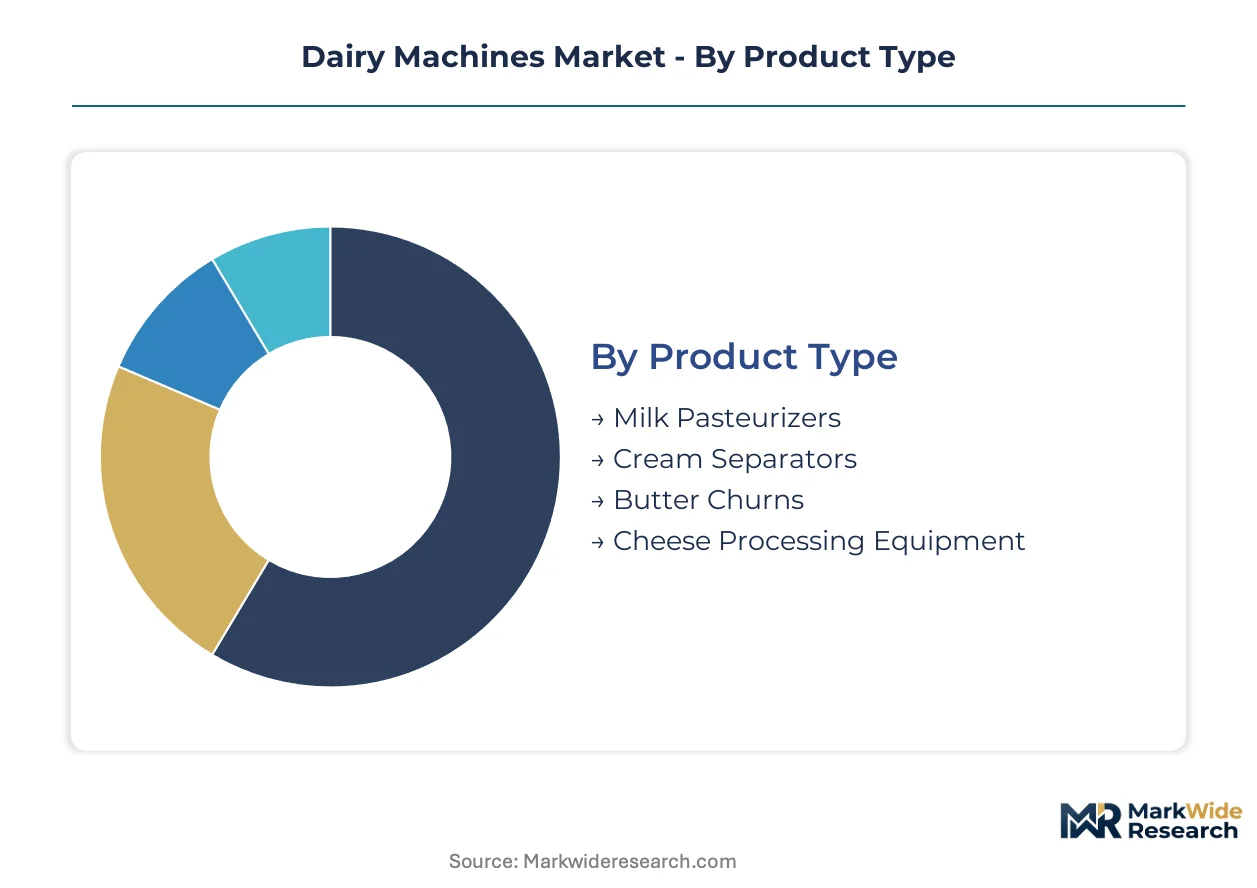
Dairy machine procurement cycles vary dramatically by equipment category, with thermal processing systems requiring decade-long replacement timelines while connected technologies refresh every three to five years. Understanding these velocity differences shapes inventory planning and vendor relationship strategies across the value chain.
Product Type:
Replacement cycles stretch from fifteen-year intervals for static thermal equipment down to three-year refresh rates for sensor-integrated systems, creating divergent revenue recognition patterns for manufacturers.
- Milk Pasteurizers:Stainless steel heat-exchange systems with plate or tubular configurations maintain precise temperature control within regulatory limits. FDA Grade A pasteurization mandates across US commercial processing networks sustain universal demand despite extended replacement intervals.
- Cheese Processing Equipment:Configurable vat and press systems accommodate artisanal small-batch through industrial continuous-flow operations. German and Dutch cooperatives drive specification diversity as EFSA hygiene protocols force equipment segmentation between raw-milk and pasteurized-milk processing lines.
- Cream Separators:Centrifugal disc-stack technology enables fat standardization for fluid milk and butter production.
- Butter Churns:Traditional batch and continuous-flow designs serve regional butter-making traditions with varying automation levels.
Milk Pasteurizers dominate installed base. IoT-Enabled Devices represent the fastest-growing trajectory as connectivity retrofits accelerate.
End User:
Capital intensity and technical sophistication create distinct procurement patterns, with processing plants demanding integrated systems while retail outlets prioritize compact footprint solutions.
- Processing Plants:Large-scale cooperative facilities deploy integrated pasteurization, separation, and packaging lines with centralized CIP infrastructure. EU Green Deal carbon accounting disclosures favor heat-recovery configurations across German, Dutch, and Danish installations.
- Dairy Farms:Robotic milking parlors and automated herd management systems concentrate investment among mid-scale US operations seeking FDA Grade A compliance. Leasing structures now penetrate this segment previously excluded by upfront capital requirements.
- Milk Distributors:Bulk handling and temporary storage equipment supports logistics networks between farm gate and processing facility.
- Retail Outlets:Compact dispensers and on-site processing units serve direct-to-consumer fresh milk and specialty dairy operations.
Processing Plants capture the largest equipment spend. Dairy Farms show the steepest expansion trajectory as automation penetrates mid-tier operations.
Technology:
Automation depth correlates directly with labor cost pressure and regulatory documentation burden, driving tiered adoption across geographies with varying wage structures.
- IoT-Enabled Devices:Sensor networks delivering predictive maintenance alerts and herd-level analytics through cloud-connected platforms. US commercial farms deploy these systems to compress milking duration while meeting FDA throughput requirements.
- Automated Systems:Robotic milking parlors and continuous-flow processing lines with minimal operator intervention. Labor shortages across German cooperative networks accelerate deployment despite specialized technician scarcity.
- Semi-Automated Systems:Human-supervised equipment with automated sub-components balancing capital efficiency and throughput.
- Manual Equipment:Traditional configurations persisting in artisanal cheese operations and developing market smallholdings.
Automated Systems anchor current revenue. IoT-Enabled Devices are where expansion concentrates as predictive analytics subscriptions unbundle from hardware sales.
Application:
Product shelf stability and value-added processing complexity determine equipment specification intensity, with fresh fluid milk requiring standardized thermal treatment while cultured products demand precise fermentation control.
- Milk Production:Pasteurization, homogenization, and packaging systems for fluid milk distribution. Universal regulatory requirements sustain baseline demand across all geographies with equipment refresh tied to energy efficiency upgrades.
- Cheese Production:Curd processing, pressing, aging, and cutting equipment spanning artisanal to industrial scales. Divergent specifications between small-batch and commodity operations create fragmented vendor landscapes.
- Yogurt Manufacturing:Fermentation vessels with precise temperature and pH control for cultured dairy production.
- Ice Cream Production:High-shear mixing and continuous freezing systems for frozen dessert manufacturing.
Milk Production commands the broadest installed base. Cheese Production shows where margin expansion concentrates as artisanal segments capture premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows favor surplus regions with stainless steel fabrication clusters and dairy processing heritage. Import-dependent markets absorb refurbished systems from European cooperatives upgrading to EU Green Deal-compliant configurations.
United States
Commercial dairies in Wisconsin and California deploy automated milking parlors to satisfy FDA Grade A pasteurization throughput mandates. USDA dairy plant inspection protocols enforce simultaneous documentation streams that strain quality assurance resources. The Upper Midwest dairy belt concentrates robotic system deployment among mid-scale operations accessing equipment-as-a-service leasing.
Germany
EFSA hygiene mandates trigger replacement cycles across Bavarian and Lower Saxon cooperative processing networks. The EU Green Deal carbon accounting framework favors heat-recovery pasteurizer retrofits in the Münsterland dairy cluster. Specialized technician scarcity constrains deployment speed despite labor shortages accelerating automation demand.
Netherlands
Dutch cooperatives lead sensor-integrated milking adoption for predictive maintenance and herd-level analytics. CE marking complexity for MDR-equivalent pressure vessels creates validation bottlenecks at Rotterdam port entry. The Friesland dairy region concentrates IoT-enabled device deployment among capital-constrained mid-tier farms.
China
Domestic processors expand pasteurization capacity to meet SAMR dairy safety standards and fluid milk distribution growth. GB standards for stainless steel equipment construction diverge from European CIP specifications, fragmenting vendor qualification. The Yangtze River Delta dairy processing corridor absorbs imported separation technology from European surplus markets.
India
FSSAI dairy safety regulations and PLI scheme incentives accelerate organized sector processing infrastructure. Stainless steel grade 316L price volatility compresses equipment margins for fabricators in Gujarat and Maharashtra. The Anand dairy cooperative cluster pilots robotic milking configurations adapted to smallholder supply aggregation models.
Dairy Machines Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying heat-exchange elements and sensor modules. Market structure tilts toward consolidated processing equipment platforms with fragmented robotic milking subsystems. Three archetypes dominate: integrated processing platforms, robotic automation specialists, and regional stainless steel fabricators. Competitive moves concentrate on service unbundling and predictive analytics subscription models separating from hardware contracts.
Among European-integrated platforms, GEA Group and Alfa Laval exemplify the full-system archetype spanning thermal processing through separation technology. DeLaval occupies a position within the robotic milking specialist tier, representing sensor-integrated automation approaches. Tetra Pak International S.A. anchors the packaging-integrated processing vector where aseptic technology intersects with equipment supply.
| Leading Market Players |
|---|
| GEA Group |
| Alfa Laval |
| Tetra Pak International S.A. |
| DeLaval |
| SPX FLOW |
| IDMC Limited |
| Lely |
| Afimilk Ltd. |
| BouMatic |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors carry stainless steel grade 316L from Northern European mills to German and Dutch dairy equipment fabricators, with container rate volatility amplifying margin compression at mid-tier manufacturers while enabling premium pricing power for integrated processors with captive metallurgical supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA Grade A certification tier and heat-recovery energy efficiency rating serving as primary price differentiation drivers. Pricing pressure stems from stainless steel input volatility compressing equipment margins, particularly for fabricators without long-term metallurgical contracts. Processing plants with integrated thermal systems show least price sensitivity, while capital-constrained mid-sized dairy farms exhibit highest elasticity, driving equipment-as-a-service subscription penetration.
Supply Chain Analysis
Export control regimes on precision sensor technology and industrial IoT modules limit flows from Northern European networks to certain processing markets, forcing Chinese and Indian fabricators to develop alternative sourcing channels. Supply concentrates in Germany, Netherlands, and Denmark for robotic milking systems, while stainless steel grade 316L draws from Finnish and Swedish metallurgical clusters. Single-source vulnerability sits with specialized technician networks for robotic calibration. Distribution runs through cooperative procurement consortia in European markets and direct OEM relationships in North American commercial farm segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy equipment procurement follows a cyclical recovery pattern tied to EFSA-mandated replacement cycles across European cooperative networks, with regulatory deadlines compressing investment timelines into concentrated upgrade windows.
For Market Incumbents: Insulate installed base relationships through predictive maintenance subscription unbundling, separating IoT analytics from hardware contracts to capture recurring revenue streams. Deepen backward integration into stainless steel fabrication to neutralize grade 316L price volatility threatening equipment margins. Prioritize CE marking pre-certification investments to accelerate MDR-equivalent pressure vessel validation timelines. For New Entrants and Emerging Players: Artisanal cheese processing configurations for small-batch European cooperatives represent the most penetrable entry point, as EFSA hygiene mandates force equipment segmentation between raw-milk and pasteurized-milk lines. Capital-constrained mid-tier US dairy farms accessing equipment-as-a-service leasing create secondary white-space. Pursue partnership routes with regional cooperative procurement consortia rather than direct OEM competition. For Investors and Strategic Acquirers: EU Green Deal carbon accounting disclosure mandates reshape the acquisition landscape, elevating thermal efficiency technology targets above pure automation plays. Five-to-ten-year viability favors platforms with integrated heat-recovery pasteurization and variable-frequency drive capabilities. Monitor CE marking validation bottlenecks as inflection signal for cross-border equipment eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Expansion | Leasing structures democratize robotic milking access for mid-scale Wisconsin and California operations. |
| Heat-Recovery Pasteurizer Retrofit | EU Green Deal compliance drives German Münsterland dairy cluster thermal efficiency upgrades. |
| Predictive Maintenance Unbundling | Sensor-integrated analytics subscriptions separate from hardware sales across Dutch cooperative networks. |
| Artisanal Cheese Configuration Development | Small-batch equipment specifications capture premium margin pools outside commodity dairy processing. |
| CE Marking Pre-Certification Investment | MDR-equivalent pressure vessel validation accelerates Rotterdam port entry for cross-border shipments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy cooperative procurement directors, equipment maintenance technicians, robotic system integrators, and thermal processing engineers. Secondary validation drew from FDA Grade A inspection protocols, EFSA hygiene mandate documentation, EU Green Deal carbon accounting frameworks, customs records for stainless steel grade 316L trade flows, and SEC filings from listed processing equipment manufacturers. Bottom-up equipment shipment data triangulated against top-down cooperative capital expenditure surveys.
Calibration approaches anchored volume and value outputs across the analysis window against historical replacement cycle patterns for thermal processing equipment versus sensor-integrated systems. Segmentation dimensions modeled include equipment category, automation depth, end-user scale tier, application shelf-stability requirements, and regional regulatory cluster. CAGRs derived from equipment shipment velocity differentials and capital expenditure intention surveys. Forecast inputs incorporated EFSA-mandated replacement deadlines and FDA Grade A throughput requirements.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity pricing, container freight rates, or dairy commodity price cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and cooperative capital access. Material shifts in CE marking validation protocols or carbon border adjustment mechanism implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Commercial Milkshake Machine Market