
 Whey Protein Microparticulation Systems Market | 2026-2036
Whey Protein Microparticulation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Protein Microparticulation Systems Market Insights
North American dairy processing infrastructure is reconfiguring around higher-value whey fractionation. Glanbia plc leverages its Idaho-based protein innovation campus to sustain R&D leadership in microparticulation scale-up. Leprino Foods anchors its competitive position through captive whey supply from mozzarella operations. Arla Foods Ingredients competes on European technology transfer into North American manufacturing footprints.
Whey protein microparticulation systems employ controlled shear and thermal treatment to reduce particle size below 10 microns, creating fat-mimicking mouthfeel in reduced-fat dairy and sports nutrition applications. The process typically deploys microfluidization or high-pressure homogenization followed by spray drying to preserve functional solubility. Sports nutrition applications command the largest current revenue pool within the application dimension, while functional foods represent the fastest trajectory as clean-label formulators seek texture solutions without hydrocolloid additives. Whey protein isolate processing lines carry premium equipment specifications due to lower starting solids and higher purity requirements compared to whey protein concentrate systems.
The FDA oversees GRAS self-affirmation and food additive petitions for novel protein modification processes, while USDA dairy plant inspection standards govern equipment sanitation protocols. ISO 22000 and 3-A Sanitary Standards constrain equipment design for cross-border dairy ingredient trade. Stakeholders must monitor evolving EPA effluent guidelines for dairy processing wastewater as microparticulation expands water usage intensity relative to conventional drying.
Market Dynamics
Sports nutrition brands are consolidating purchase volumes around microparticulated whey suppliers capable of delivering sub-10-micron particle consistency at industrial scale. This buyer-side concentration is compressing equipment vendor margins while accelerating R&D cycles for next-generation shear systems.
Growth Catalysts
- Clean-label formulation mandates:Formulators in functional foods are eliminating hydrocolloid stabilizers. Microparticulated whey delivers fat-mimicking mouthfeel without additive declarations, satisfying retailer clean-label requirements.
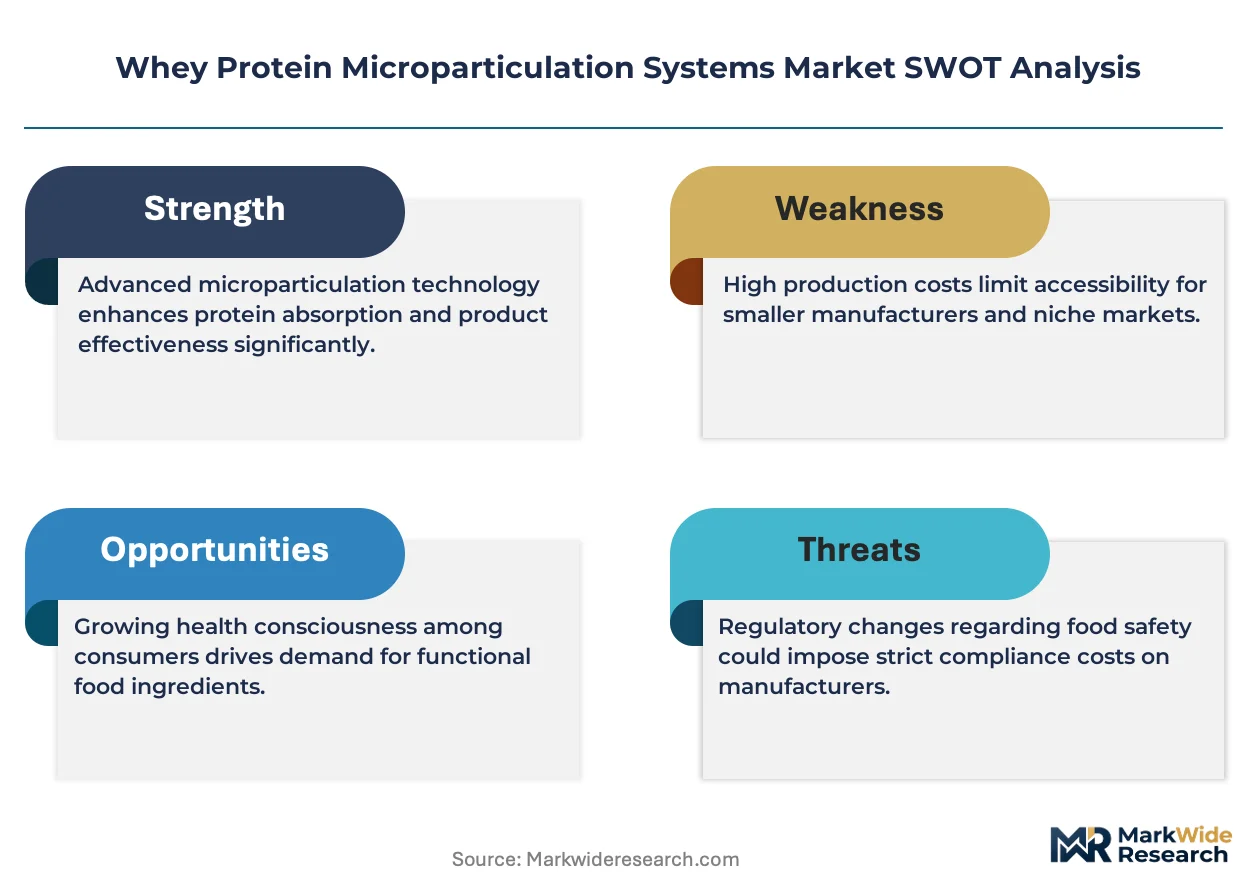
- FDA GRAS pathway efficiency:The GRAS self-affirmation process for novel protein modification methods is shortening commercialization timelines. Equipment vendors benefit from faster customer validation cycles.
- Dairy cluster infrastructure investment:Processing facilities in Wisconsin and California are upgrading fractionation lines. Regional equipment demand is concentrating where whey supply volumes anchor captive processing economics.
Market Restraints
- Input cost volatility:Stainless steel and precision pump components face commodity price swings. Equipment fabricators absorb margin pressure or pass through costs, slowing capital commitment from mid-scale dairy processors.
- Technical limitation in isolate processing:Whey protein isolate systems require lower starting solids handling and higher purity specifications. This elevates engineering complexity and extends commissioning timelines versus concentrate lines.
- Substitution threat from plant proteins:Pea and oat protein texturization technologies are advancing. Some beverage formulators are piloting hybrid formulations that reduce whey dependency.
Strategic Opportunities
- Medical nutrition applications:Enteral and clinical nutrition products represent underpenetrated demand. Microparticulated whey offers palatability advantages in high-protein, low-volume feeding formulations.
- Technology convergence:Integration of inline particle size monitoring with automated shear adjustment is enabling real-time quality control. Early adopters are reducing batch rejection rates.
- EPA effluent incentive alignment:Dairy processors investing in water recovery systems qualify for environmental compliance credits. Microparticulation equipment with closed-loop water design captures this regulatory tailwind.
Industry Challenges
- Specialized commissioning expertise:Microfluidization and high-pressure homogenization systems require dairy engineering specialists. The talent pool for shear-rate optimization and thermal profile calibration remains shallow.
- ISO 22000 certification complexity:Cross-border ingredient trade demands harmonized food safety management. Equipment vendors face extended documentation cycles to satisfy multiple national accreditation bodies.
- Legacy dryer integration:Brownfield installations must synchronize microparticulation shear systems with existing spray drying infrastructure. Retrofit engineering adds project risk and timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Protein Microparticulation Systems Market |
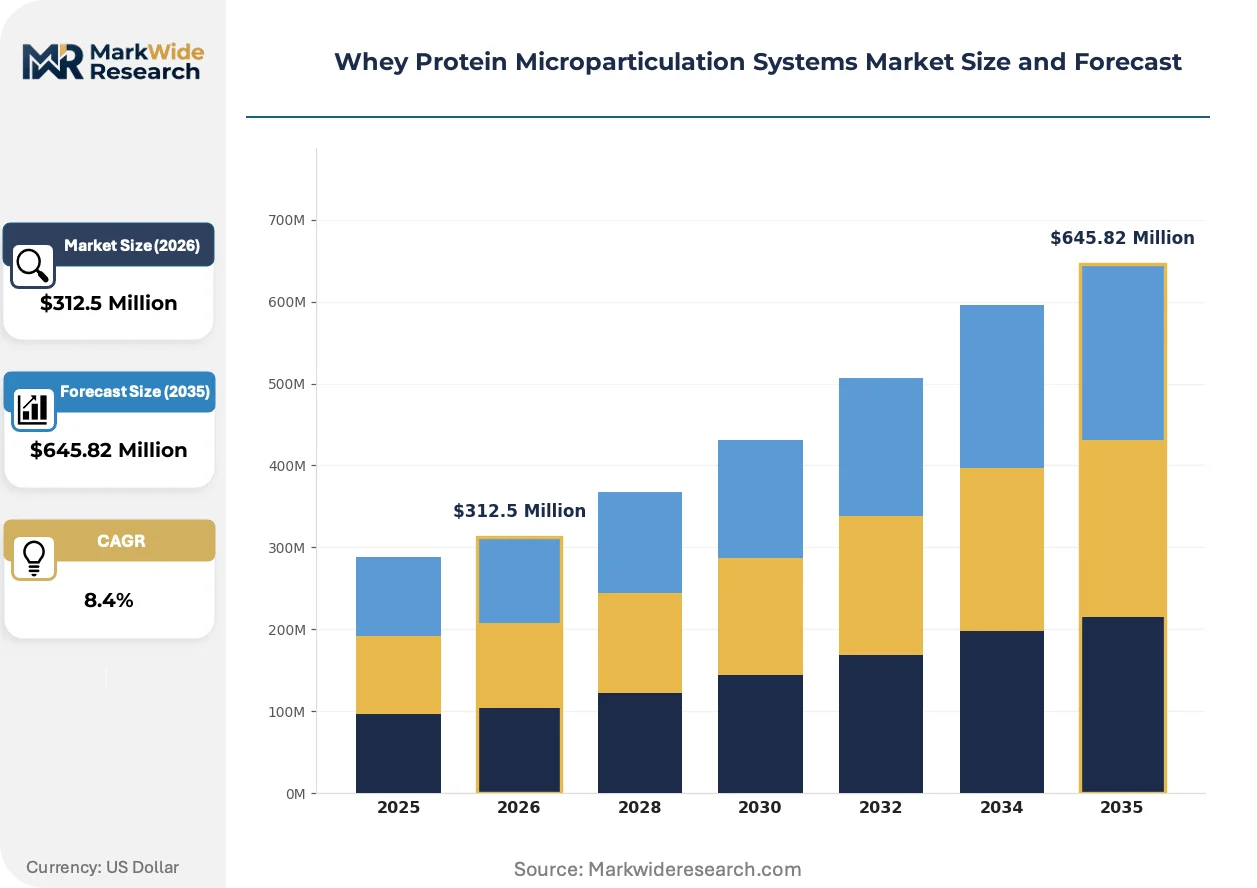
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
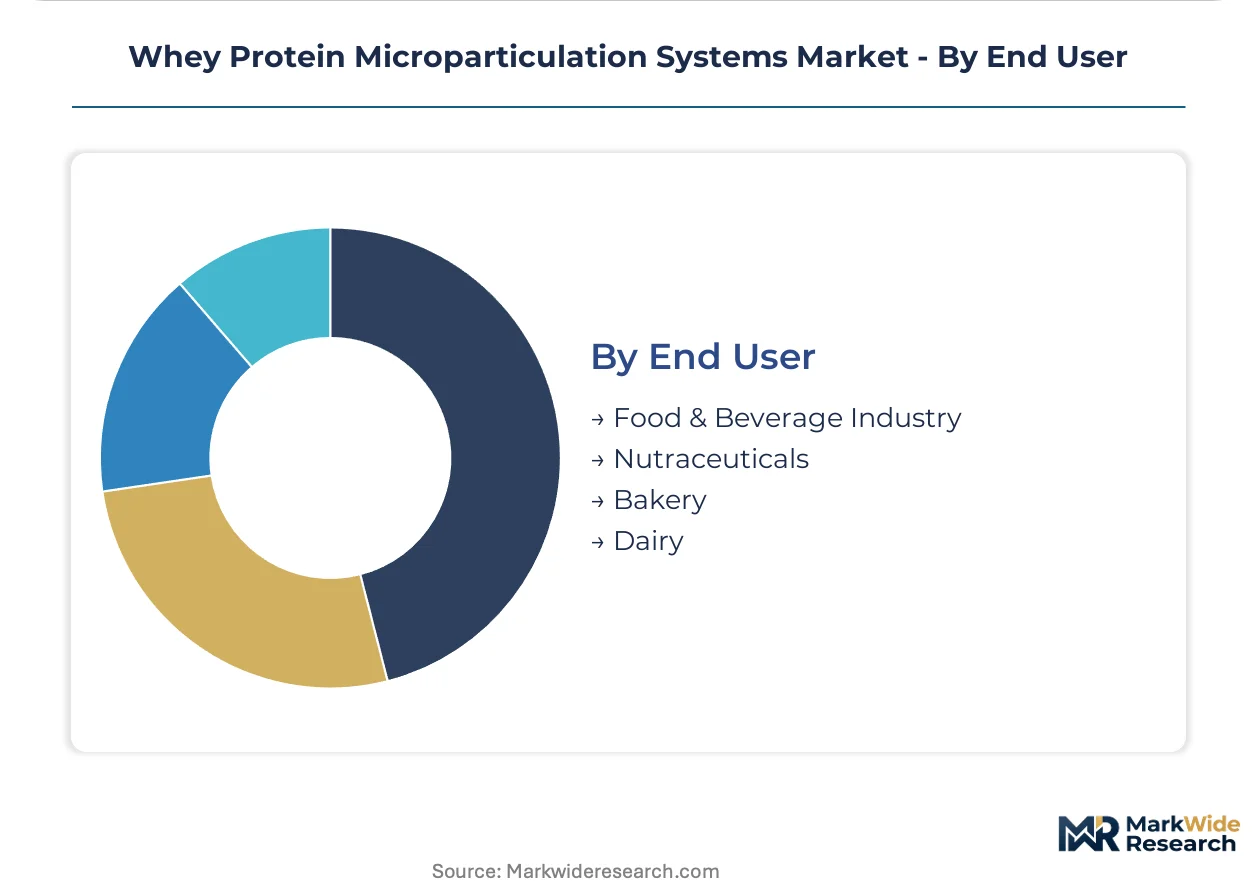
| Segmentation | Product Type: Dry Whey, Liquid Whey, Whey Protein Concentrate, Whey Protein Isolate Application: Sports Nutrition, Functional Foods, Infant Formula, Dietary Supplements Form: Powder, Liquid, Gel, Emulsion End User: Food & Beverage Industry, Nutraceuticals, Bakery, Dairy |
| Companies Covered | Royal FrieslandCampina N.V., Carbery Group, Glanbia plc, Makers Nutrition, LLC, CP Kelco, Fonterra Co-operative Group, Leprino Foods, NMZP, Arla Foods Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Protein Microparticulation Systems Market Trends and Innovations
Process analytical technology and inline sensing are transforming how microparticulation systems maintain particle size distribution consistency. Equipment vendors are embedding real-time feedback loops that previously required offline laboratory verification.
Inline laser diffraction sensors paired with variable-frequency drive control is digitizing quality assurance workflows. Sports nutrition manufacturers are deploying these systems at commercial scale to eliminate batch-to-batch texture variation. Real-time particle size data is compressing release cycle times from hours to minutes while reducing laboratory staffing overhead.
REACH chemical registration requirements in Europe are tightening material specifications for food-contact equipment surfaces. Stainless steel alloy compositions and sealant chemistries face enhanced disclosure obligations. Equipment destined for EU dairy ingredient trade is being redesigned with pre-certified material traceability documentation.
Direct equipment procurement from dairy processors is displacing traditional distributor channel arrangements. Large-scale whey fractionation operators are establishing preferred vendor frameworks with microparticulation system OEMs. This disintermediation is most visible in the United States, where vertically integrated dairy cooperatives negotiate service-inclusive supply agreements that bundle installation, commissioning, and multi-year maintenance.
Whey Protein Microparticulation Systems Market Segmentation
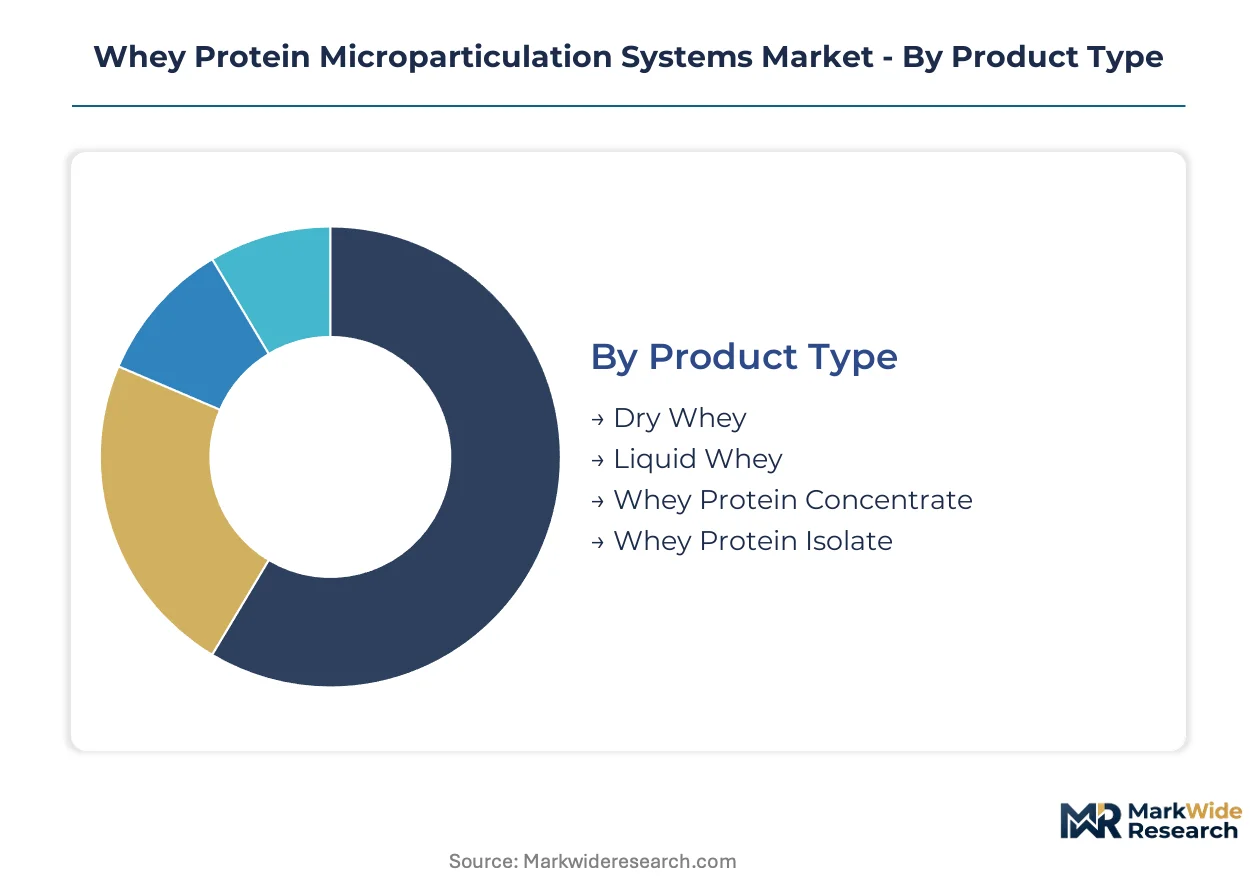
Microparticulation system configurations diverge sharply across whey input types and end-use specifications. Equipment buyers segment procurement by protein purity requirements and thermal sensitivity thresholds that dictate shear system engineering.
Product Type:
Cycle times compress from months for standard concentrate lines to years for isolate systems requiring extended commissioning and validation protocols.
- Whey Protein Concentrate:Systems handle higher starting solids with moderate purity thresholds, enabling faster deployment timelines. Dairy processors in Wisconsin favor these configurations for captive whey supply integration where throughput economics dominate capital planning.
- Whey Protein Isolate:Lower starting solids and elevated purity demands necessitate precision thermal profiling and extended shear calibration. Sports nutrition manufacturers in California absorb longer lead times to secure sub-10-micron particle consistency for texture-critical applications.
- Dry Whey:Reconstitution-based processing lines serve commodity ingredient producers with standardized equipment packages.
- Liquid Whey:Direct-from-cheese operations require immediate cooling and continuous-flow microparticulation to preserve functional properties.
Whey Protein Concentrate anchors the volume base while Whey Protein Isolate gains share at the steepest rate.
Application:
Margin structures stratify across applications, with clinical and premium sports formulations commanding equipment premium tiers versus mass-market functional food deployments.
- Sports Nutrition:Protein beverage brands demand sub-10-micron particle distributions for fat-mimicking mouthfeel in reduced-calorie formulations. Equipment specifications prioritize inline particle monitoring and automated shear adjustment to eliminate batch-to-batch texture variation.
- Functional Foods:Clean-label formulators eliminate hydrocolloid stabilizers by deploying microparticulated whey for texture solutions. Retailer mandates for additive-free declarations accelerate equipment procurement among mid-scale dairy processors.
- Infant Formula:Stringent safety protocols and extended regulatory validation cycles extend equipment commissioning timelines.
- Dietary Supplements:Powder-focused processing requires less complex shear systems compared to ready-to-drink applications.
Sports Nutrition generates the largest current equipment revenue pool while Functional Foods is expanding most quickly as clean-label mandates proliferate.
Form:
Water intensity and drying energy requirements create divergent operating cost profiles across physical state outputs.
- Powder:Spray drying integration dominates commercial-scale deployments, with brownfield retrofits requiring synchronization between shear systems and legacy dryer infrastructure.
- Liquid:Aseptic processing lines serve ready-to-drink manufacturers with shortened shelf-life requirements and cold-chain distribution.
- Gel:Specialized applications in clinical nutrition and enteral feeding demand customized rheological specifications.
- Emulsion:Fat replacement systems in reduced-fat dairy products leverage microparticulated whey for stability without synthetic emulsifiers.
Powder maintains the installed base majority while Liquid configurations are climbing the fastest on beverage format demand.
End User:
Procurement authority concentrates among vertically integrated operators versus fragmented contract manufacturers.
- Food & Beverage Industry:Large-scale dairy cooperatives negotiate service-inclusive supply agreements bundling installation, commissioning, and multi-year maintenance. Direct OEM relationships displace traditional distributor channels.
- Nutraceuticals:Clinical nutrition specialists prioritize batch traceability and ISO 22000 certification for cross-border ingredient trade.
- Bakery:Protein fortification applications utilize microparticulated whey for moisture retention in reduced-fat formulations.
- Dairy:Captive whey processors leverage mozzarella and cheese operations for integrated fractionation economics.
Food & Beverage Industry commands the dominant procurement volume while Nutraceuticals is gaining share fastest on medical nutrition penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys microparticulated whey primarily for sports nutrition texture enhancement, while European processors emphasize clean-label functional food applications. Asian markets concentrate investment in infant formula safety protocols. This consumption-mix differential shapes equipment specification priorities across geographies.
United States
Sports nutrition brands in California and Wisconsin drive demand for sub-10-micron particle consistency systems. The FDA's GRAS self-affirmation pathway accelerates commercialization timelines for novel protein modification methods. Dairy processing clusters in California's Central Valley and Wisconsin's Fox Cities region anchor captive whey fractionation economics, with equipment upgrades concentrating near mozzarella operations in Modesto and Green Bay.
Germany
Clean-label formulators in functional foods prioritize microparticulated whey as hydrocolloid replacement in reduced-fat dairy. EFSA novel food consultations and REACH chemical registration requirements tighten material specifications for food-contact equipment surfaces. Industrial concentration centers on North Rhine-Westphalia's dairy technology corridor, where equipment fabricators coordinate with ingredient processors in Cologne-Düsseldorf metro areas.
China
Infant formula manufacturers absorb extended commissioning timelines for stringent safety validation protocols. SAMR dairy ingredient registration requirements and GB standards for food-contact materials constrain equipment import specifications. Yangtze River Delta processing hubs in Shanghai and Jiangsu province concentrate whey fractionation capacity expansion, with domestic equipment procurement displacing European vendors in mid-scale installations.
Netherlands
Dairy ingredient exporters prioritize ISO 22000 certification alignment for cross-border trade into Asian and Middle Eastern markets. EU Green Deal sustainability reporting obligations and CSRD disclosure requirements influence equipment procurement criteria for water recovery integration. Randstad dairy technology clusters near Wageningen coordinate equipment R&D with ingredient application science, leveraging proximity to research universities.
Japan
Clinical nutrition specialists demand customized rheological specifications for enteral feeding applications. PMDA pharmaceutical-grade ingredient oversight and METI industrial standards govern equipment validation protocols for medical nutrition products. Kanto region manufacturing concentration around Tokyo anchors premium equipment procurement, with processors absorbing longer lead times for isolate system precision engineering.
Whey Protein Microparticulation Systems Market Competitive Landscape
Capability concentration sits with European technology specialists; scale advantage sits with vertically integrated dairy cooperatives. The vendor base stratifies across three tiers: multinational dairy ingredient conglomerates with captive equipment fabrication, specialized shear system OEMs with process analytical technology integration, and regional stainless steel fabricators serving brownfield retrofit demand. Competitive moves concentrate on preferred vendor framework negotiations and technology licensing arrangements for inline particle monitoring systems.
Among European dairy ingredient conglomerates, Royal FrieslandCampina N.V. and Arla Foods Ingredients occupy positions exemplifying technology transfer from regional innovation centers into North American manufacturing footprints. Glanbia plc represents the vertically integrated archetype, anchoring competitive positioning through Idaho-based protein innovation campus infrastructure. Specialized shear system development concentrates with Carbery Group and CP Kelco, whose Irish and Danish origins respectively reflect regional engineering traditions in precision dairy processing equipment.
| Leading Market Players |
|---|
| Royal FrieslandCampina N.V. |
| Carbery Group |
| Glanbia plc |
| Makers Nutrition, LLC |
| CP Kelco |
| Fonterra Co-operative Group |
| Leprino Foods |
| NMZP |
| Arla Foods Ingredients |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Wisconsin dairy processing clusters is forcing equipment vendors to extend lead times and prioritize long-term offtake agreements over spot procurement. This utilization squeeze simultaneously elevates buyer commitment thresholds and compresses margin flexibility for mid-scale processors seeking WPI isolate system upgrades.
Pricing Analysis
Long-term offtake contracts dominate equipment procurement between dairy cooperatives and microparticulation system OEMs, displacing traditional spot-market transactions. Price differentiation hinges on ISO 22000 certification tier and after-sales service bundling, with premium tiers capturing multi-year maintenance inclusions. Pricing pressure stems from stainless steel commodity volatility, which equipment fabricators either absorb or pass through to buyers. Mid-scale dairy processors exhibit highest price sensitivity, while vertically integrated operators absorb premiums for guaranteed commissioning timelines.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized shear system fabricators in Denmark, Ireland, and Germany, where precision dairy processing engineering traditions anchor capacity. Raw material dependencies draw from Swedish stainless steel alloys, German precision pump components, and Italian spray drying integration modules. Single-source vulnerability concentrates in high-pressure homogenization valve assemblies, where qualified secondary suppliers remain scarce. Distribution runs through direct OEM relationships with large-scale whey fractionation operators, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's streamlined GRAS self-affirmation pathway is accelerating commercialization velocity for novel protein modification methods, compressing validation cycles and rewarding early equipment adopters with first-mover positioning in texture-enhanced beverage formulations.
For Market Incumbents: Entrench dominance through captive whey supply integration and preferred vendor framework negotiations that bundle installation with multi-year service agreements. Deepen backward integration into precision pump component fabrication to offset stainless steel commodity volatility. Prioritize ISO 22000 certification investment to secure cross-border ingredient trade access as regulatory harmonization tightens. For New Entrants and Emerging Players: Establish a beachhead in medical nutrition applications, where enteral feeding formulations remain underpenetrated and palatability specifications command equipment premium tiers. Target clinical nutrition specialists in Japan's Kanto region, where PMDA pharmaceutical-grade oversight extends commissioning timelines and deters commoditized competition. Lead with inline particle monitoring integration as a differentiated service offering. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across WPI isolate processing lines, where extended shear calibration and validation protocols extend payback horizons. Acquisition targets should display technology licensing arrangements for real-time quality control systems and established service footprints near California and Wisconsin dairy clusters. Watch for EPA effluent guideline revisions as a signal for water recovery system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Arrangement | Inline particle monitoring patents from Carbery Group accelerate OEM differentiation in sports nutrition. |
| Backward Integration | Captive precision pump fabrication insulates Glanbia plc from stainless steel commodity volatility. |
| Preferred Vendor Framework | Leprino Foods bundles commissioning with multi-year maintenance, displacing traditional distributor channels. |
| Certification Investment | Arla Foods Ingredients prioritizes REACH pre-certification to capture EU Green Deal sustainability procurement criteria. |
| Geographic Manufacturing Footprint | Idaho-based protein innovation campus anchors Glanbia's R&D leadership in microparticulation scale-up. |
Research Methodology
Cross-validation between primary interviews with dairy processing plant managers, equipment procurement leads at whey fractionation operators, aftermarket service heads, and regulatory compliance officers anchors the qualitative findings. Secondary validation draws from FDA GRAS notification databases, USDA dairy plant inspection records, EPA effluent guideline dockets, and ISO 22000 certification registries. Bottom-up equipment shipment tracking and top-down dairy processing capacity modeling were reconciled to establish market sizing boundaries.
Calibration against historical deployment timelines for concentrate versus isolate processing lines informed CAGR derivation across the projection horizon. Segmentation dimensions modeled include whey input type, application category, physical form output, and end-user procurement authority. Forecast inputs incorporated dairy cluster capacity utilization rates, GRAS notification velocity, and REACH chemical registration disclosure obligations.
Stress conditions across stainless steel price volatility, EPA wastewater regulation stringency, and plant protein substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FDA pathway efficiency and dairy cooperative capital commitment cycles. Quarterly review of GRAS notification volumes and Wisconsin processing cluster utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Commercial Cheese Shredder Market