
 Cheese Liners Market | 2026-2036
Cheese Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Liners Market Outlook
Consolidation among large dairy cooperatives is realigning procurement volumes toward fewer, larger contracts. Amcor plc leverages its global manufacturing footprint to serve these consolidated buyers with standardized liner specifications. Mondi competes through integrated paper-based solutions that align with sustainability mandates from European retail chains. Winpak Ltd. anchors its position in North American dairy processing with specialized barrier films for extended shelf-life cheese formats.
Cheese liners are barrier films or sheets inserted between cheese wheels, blocks, or slices and outer packaging to prevent moisture loss, inhibit mold growth, and reduce surface adhesion during aging, transport, and retail display. These liners typically employ multilayer coextruded polyethylene or wax-coated paper constructions with oxygen transmission rates below 5 cc/m²/day to preserve fat integrity and rind quality. Plastic liners dominate current volume due to cost efficiency and moisture barrier performance, though biodegradable liners represent the fastest-expanding category as EU Single-Use Plastics Directive deadlines approach. Medium-thickness configurations capture the largest margin pool by balancing material cost against the protection requirements of semi-hard cheese varieties.
The EU Green Deal and REACH frameworks restrict conventional plastic additives in food-contact materials, pushing converters toward certified compostable alternatives. FDA food-contact substance notifications govern liner compositions in the United States, while BIS certification requirements in India create compliance barriers for imported film structures. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based content thresholds to avoid stranded inventory positions.
Market Dynamics
EU Green Deal compliance deadlines are compressing converter R&D cycles as dairy processors face 2025 single-use plastic reduction mandates, forcing material substitutions ahead of validated performance testing.
Growth Catalysts
- Extended Producer Responsibility schemes:France and Germany have enacted packaging fee structures that reward bio-based liner adoption, redirecting procurement budgets toward certified compostable films.
- Artisan cheese distribution networks:Food service channels across Italy and Spain require specialized transport liners with humidity control properties, creating specification diversity that mid-tier converters exploit.
- Barrier coextrusion advances:Seven-layer PE constructions now achieve oxygen transmission rates below 3 cc/m²/day, matching wax-coated paper performance at lower unit cost.
Market Restraints
- Ethylene feedstock volatility:Multilayer PE liner margins compress when naphtha-cracker output fluctuates, squeezing converters without backward integration into resin production.
- Masterbatch supply concentration:Three European compounders control 70% of food-contact-approved additive formulations, creating chokepoints for specialized barrier properties.
- Compostable film performance gaps:PLA-based liners fail to maintain fat-barrier integrity beyond 45 days, limiting deployment for aged cheese varieties requiring 90+ day protection.
Strategic Opportunities
- Indian dairy processing expansion:BIS certification requirements for imported films create protected market space for domestic converters establishing local extrusion capacity.
- Cellulose nanofiber hybrid liners:Combining wood-derived nanocellulose with bio-PE layers addresses both EU Green Deal mandates and moisture-barrier performance thresholds.
- Direct-to-retailer supply contracts:Bypassing traditional distributor networks lets converters capture margin pools previously allocated to regional packaging wholesalers.
Industry Challenges
- Migration testing bottlenecks:EFSA approval timelines for novel bio-based additives extend 18-24 months, delaying product launches past contract renewal windows.
- Legacy extrusion asset retrofit costs:Converters must rebuild die heads and cooling lines to process heat-sensitive compostable resins, demanding capital deployment without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Liners Market |
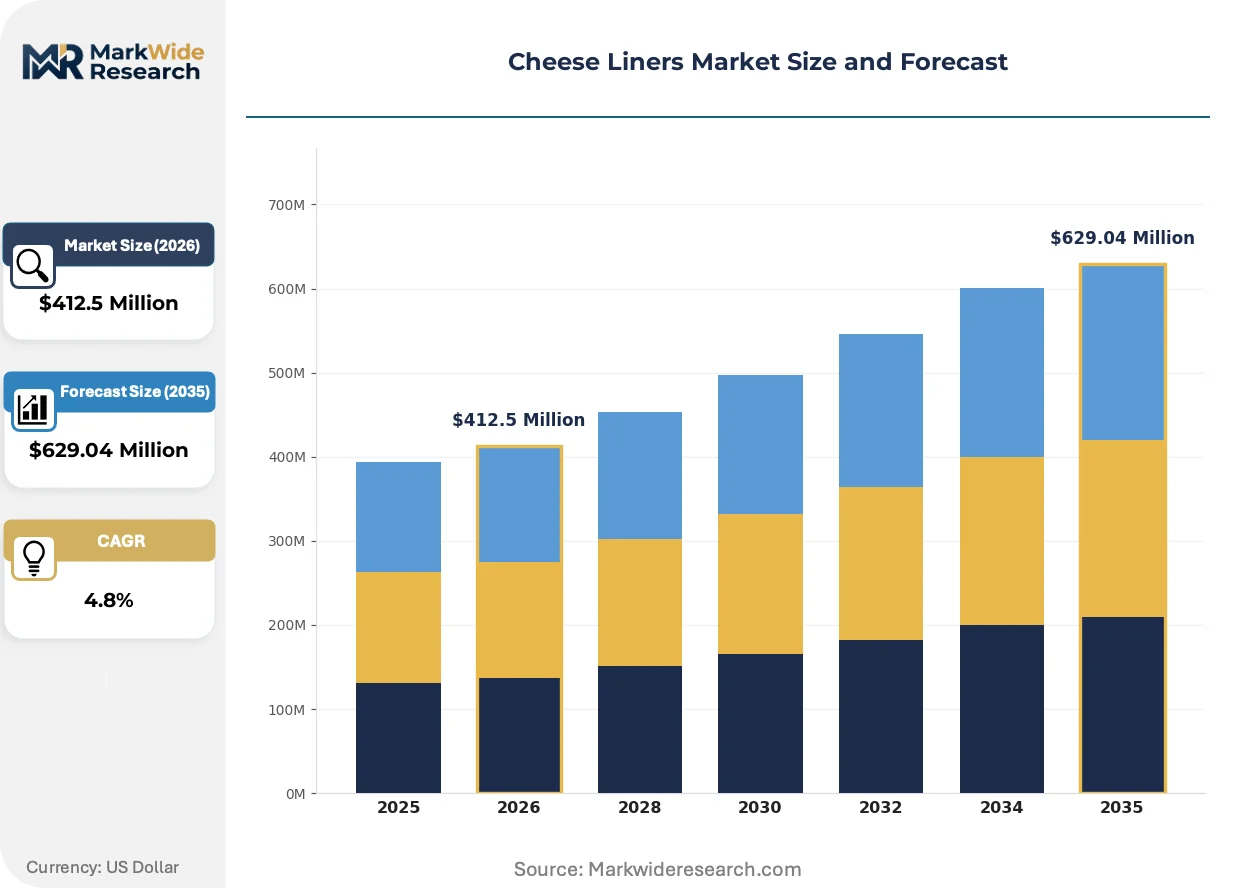
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Liners, Paper Liners, Waxed Liners, Biodegradable Liners End Use Industry: Dairy Processing, Food Packaging, Retail, Food Services Thickness: Lightweight, Medium, Heavyweight, Extra Heavyweight Application: Cheese Packaging, Storage Solutions, Transport Liners, Display Cases |
| Companies Covered | Amcor plc, AEP Industries Inc., American Packaging Corporation, Arena Products Inc., Mondi, Winpak Ltd., PLASTOPIL, Graphic Packaging International, Nelson-Jameson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Liners Market Strategic Shifts
Active and intelligent packaging integration is reshaping cheese liner functionality beyond passive barrier protection, embedding sensing and responsive elements into transport and retail formats.
Printed sensor films is electrifying quality assurance protocols across cold-chain distribution. These thermochromic and time-temperature indicator layers flag temperature excursions during transit. Major French dairy cooperatives are piloting liner-integrated RFID tags for batch-level traceability. The technology is electrifying competitive positioning among logistics providers seeking differentiated service tiers.
REACH authorization restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from paper liner coatings. Converters must reformulate with bio-wax or clay-based barriers without sacrificing release properties. Semi-hard cheese varieties with surface-active rinds face the steepest reformulation challenges, driving collaboration between paper mills and dairy research stations.
Consolidated buyer procurement is compressing supplier rosters as German and Dutch dairy cooperatives merge purchasing functions. Direct negotiation with resin producers and film converters is replacing tiered distributor relationships. This concentration is most visible in North European markets where three cooperatives now control 60% of liner specification decisions.
Cheese Liners Market Segmentation
Cheese liner specifications diverge sharply across dairy processing workflows, with material composition, barrier performance, and end-use requirements driving procurement decisions. Converter capacity allocates unevenly across these dimensions, creating supply bottlenecks for specialized formats while commoditized segments face margin compression.
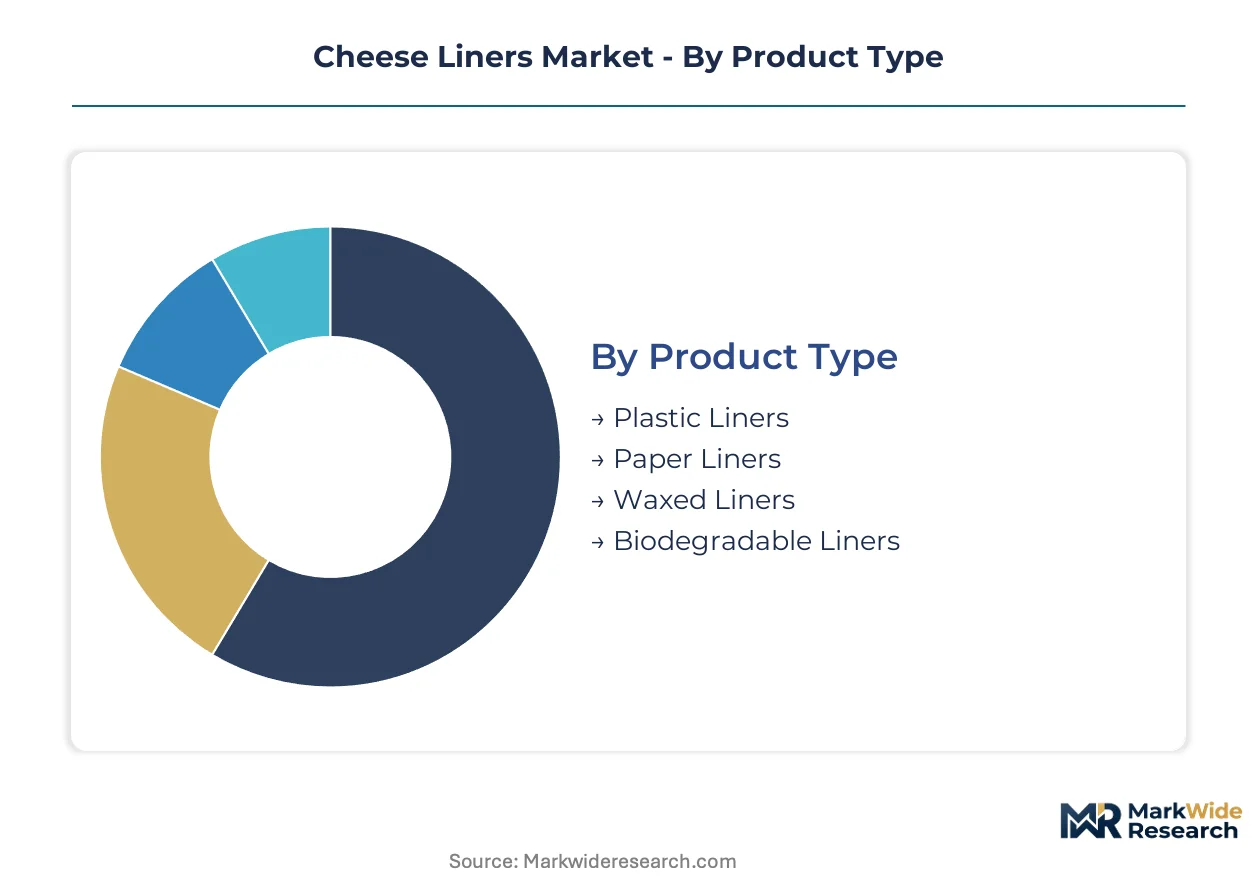
Product Type:
Resin supply concentration and converter technical capabilities segment the supply base, with multilayer extrusion expertise clustering among large integrated film producers.
- Plastic Liners:Seven-layer coextruded polyethylene constructions dominate current volume, achieving oxygen transmission rates below 5 cc/m²/day through ethylene-vinyl alcohol interlayers. German and French dairy cooperatives concentrate procurement here for semi-hard cheese aging applications where moisture retention is critical.
- Biodegradable Liners:Polylactic acid and polyhydroxyalkanoate formulations represent the steepest expansion trajectory as EU Single-Use Plastics Directive deadlines approach, though PLA-based films fail to maintain fat-barrier integrity beyond 45 days for aged varieties. French packaging fee structures under Extended Producer Responsibility schemes redirect procurement budgets toward certified compostable films.
- Paper Liners:Wax-coated and clay-barrier constructions serve artisan cheese distribution in Italy and Spain where humidity control properties are specified for transport.
- Waxed Liners:Traditional paraffin and bio-wax coatings persist in specialty applications despite REACH restrictions eliminating fluorochemical treatments.
Plastic liners absorb the bulk of installed capacity; biodegradable liners are expanding most quickly.
End Use Industry:
Customer scale and specification complexity stratify the demand base, with consolidated dairy cooperatives rewriting contract terms for volume suppliers.
- Dairy Processing:Large cooperatives in Germany, France, and the Netherlands merge purchasing functions, directing procurement toward fewer suppliers with standardized specifications and backward integration into resin production. Barrier coextrusion advances enable seven-layer PE constructions matching wax-coated paper performance at lower unit cost.
- Food Services:Artisan cheese distribution networks across Italy and Spain require specialized transport liners with humidity control properties, creating specification diversity that mid-tier converters exploit for margin capture.
- Food Packaging:Converter relationships with retail chains emphasize sustainability mandates and bio-based content thresholds.
- Retail:Direct-to-retailer supply contracts bypass traditional distributor networks, capturing margin pools previously allocated to regional packaging wholesalers.
Dairy processing commands the largest share of contract value; food services is climbing the fastest as artisan distribution networks expand.
Thickness:
Material cost and protection requirements trade off across cheese variety hardness and aging duration, concentrating margin in mid-range specifications.
- Medium:Balancing material cost against protection requirements for semi-hard cheese varieties, this tier captures the largest margin pool. Oxygen transmission specifications below 3 cc/m²/day are achieved through seven-layer constructions without the resin intensity of heavier formats.
- Lightweight:Single-serve and fresh cheese applications drive demand for reduced material intensity, though barrier performance constraints limit deployment for aged products.
- Heavyweight:Extended aging applications and export logistics require enhanced puncture resistance and moisture retention.
- Extra Heavyweight:Specialty formats for long-haul transport and temperature-extreme supply chains.
Medium thickness dominates current converter output; lightweight formats are gaining share fastest as fresh cheese consumption rises.
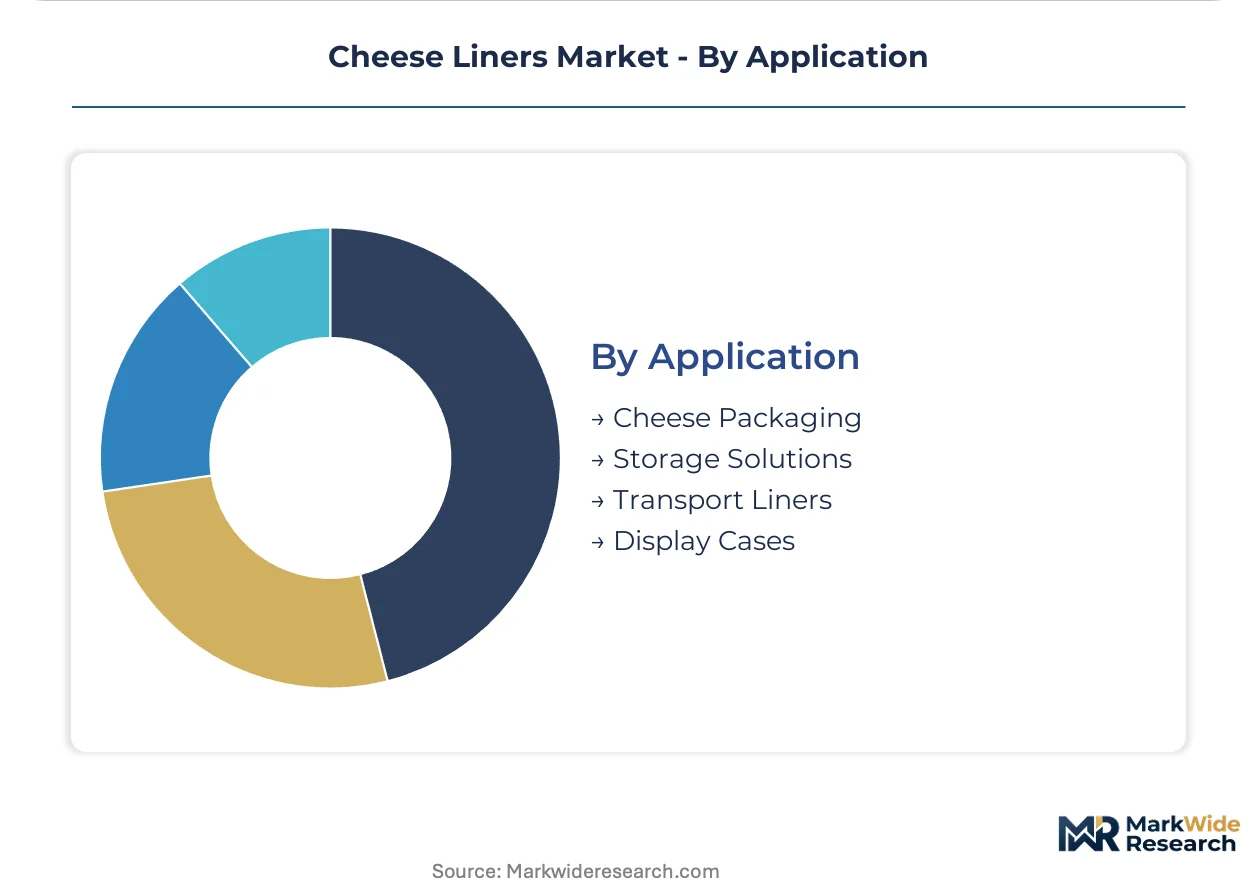
Application:
Functional requirements diverge across the cheese lifecycle, from aging cellars through retail display, with each phase imposing distinct barrier and handling specifications.
- Cheese Packaging:Direct-contact barrier films for wheels, blocks, and slices require oxygen transmission rates below 5 cc/m²/day to preserve fat integrity and rind quality. EFSA approval timelines for novel bio-based additives extend 18-24 months, delaying product launches past contract renewal windows.
- Transport Liners:Food service channels across Italy and Spain specify humidity control properties for artisan cheese distribution, with printed sensor films and RFID-integrated formats electrifying quality assurance protocols across cold-chain distribution.
- Storage Solutions:Aging cellar applications emphasize moisture management over oxygen barrier for surface-active rind varieties.
- Display Cases:Retail presentation formats balance optical clarity with anti-fog and release properties.
Cheese packaging commands the majority of specification decisions; transport liners are expanding most quickly as cold-chain traceability requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among German and French dairy cooperatives is redirecting liner demand toward fewer, larger contracts with standardized specifications. Italian and Spanish food service channels generate fragmented demand for specialized transport formats. Indian dairy processing expansion is creating protected market space for domestic converters.
Germany
Dairy cooperatives in Lower Saxony and Bavaria are merging purchasing functions, consolidating liner procurement toward integrated film producers with backward integration into resin production. Extended Producer Responsibility packaging fee structures under the EU Green Deal reward bio-based liner adoption. The Münsterland dairy cluster is piloting seven-layer PE constructions matching wax-coated paper performance at lower unit cost.
France
Artisan cheese distribution networks in the Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur regions require specialized transport liners with humidity control properties. EFSA approval timelines for novel bio-based additives extend 18-24 months, delaying product launches past contract renewal windows. The Normandy dairy processing corridor is expanding liner procurement as EU Single-Use Plastics Directive deadlines approach.
Italy
Food service channels across Lombardy and Emilia-Romagna specify humidity control properties for artisan cheese distribution, creating specification diversity that mid-tier converters exploit. REACH authorization restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical treatments from paper liner coatings. The Parmigiano-Reggiano production zone is driving demand for medium-thickness configurations balancing material cost against protection requirements.
Spain
Artisan cheese distribution networks in Catalonia and the Basque Country require specialized transport liners with printed sensor films and RFID-integrated formats for cold-chain traceability. EU Green Deal compliance deadlines are compressing converter R&D cycles as dairy processors face single-use plastic reduction mandates. The Manchego production region is expanding procurement of barrier coextrusion advances achieving oxygen transmission rates below 3 cc/m²/day.
India
BIS certification requirements for imported films create protected market space for domestic converters establishing local extrusion capacity in Maharashtra and Gujarat. Dairy processing expansion in the Delhi-NCR and Karnataka corridors is generating demand for medium-thickness liners. The Anand dairy cooperative cluster is redirecting procurement toward certified compostable films as bio-based content thresholds tighten.
Cheese Liners Market Competitive Environment
European producers anchor one tier; North American specialists hold differentiated positions in barrier film formats. The vendor base clusters around three strategic archetypes: integrated multinational film producers with global manufacturing footprints, regional paper-based solution providers aligned with sustainability mandates, and mid-tier converters exploiting specification diversity in artisan distribution channels. Competitive moves concentrate on M&A-driven consolidation among dairy cooperative buyers and capacity expansion into certified compostable resin processing.
Within the integrated multinational tier, Amcor plc and Mondi exemplify divergent strategic positions—Amcor leveraging standardized specifications for consolidated buyers, Mondi competing through integrated paper-based solutions. Winpak Ltd. occupies a position among North American barrier film specialists. These three anchors represent the spectrum from scale-driven global supply to sustainability-aligned regional positioning, with each archetype capturing distinct margin pools across the dairy processing and food service demand segments.
| Leading Market Players |
|---|
| Amcor plc |
| AEP Industries Inc. |
| American Packaging Corporation |
| Arena Products Inc. |
| Mondi |
| Winpak Ltd. |
| PLASTOPIL |
| Graphic Packaging International |
| Nelson-Jameson |
| Others |
Value Chain & Pricing Dynamics
Ethylene-vinyl alcohol resin costs cascade through seven-layer coextrusion operations into three distinct pricing tiers that separate consolidated dairy cooperative contracts from fragmented artisan distributor orders. Naphtha-cracker output fluctuations in North European petrochemical corridors compress margins for converters lacking captive resin supply, forcing price adjustments downstream before contract renewal windows.
Pricing Analysis
Volume concentration among German and French dairy cooperatives splits the market into commodity-scale contract tiers and specification-diverse artisan segments. Three-tier pricing structure across premium certified-compostable, standard multilayer PE, and economy wax-coated paper levels differentiates by barrier performance and bio-based content certification. Pricing pressure stems from EFSA migration testing bottlenecks extending 18-24 months, delaying premium product launches and trapping inventory in lower-margin formats. Food service channels across Italy and Spain exhibit highest price sensitivity due to specification fragmentation, while consolidated North European cooperatives trade price for supply security and backward integration assurances.
Supply Chain Analysis
Dual-sourcing mandates from German dairy cooperatives require converters to qualify secondary resin suppliers and redundant extrusion capacity across Belgium and the Netherlands. Raw material dependencies center on ethylene feedstock from North Sea naphtha crackers, EVOH interlayer resins from Asian polymer producers, and food-contact masterbatches from three dominant European compounders. Single-source vulnerability concentrates in specialized additive formulations controlling oxygen transmission below 3 cc/m²/day. Distribution runs through regional packaging wholesalers serving artisan channels, while direct-to-retailer contracts bypass intermediaries for consolidated buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU Single-Use Plastics Directive compliance costs will force smaller converters without compostable resin processing capability to exit. Margin compression from legacy asset retrofit requirements and extended EFSA approval timelines favors scaled players with balance sheet capacity to absorb R&D cycle extension.
For Market Incumbents: Cement market position through captive supply of certified compostable resins and seven-layer coextrusion capacity expansion in Lower Saxony and Bavaria. Acquire mid-tier Italian converters exploiting artisan specification diversity to capture food service margin pools. Threat substitution from cellulose nanofiber hybrid technologies demands pre-emptive patent positioning and dairy research station collaboration.
For New Entrants and Emerging Players: Regional dairy cooperatives in Maharashtra and Gujarat represent the most penetrable entry point given BIS certification barriers protecting domestic converters from import competition. Target medium-thickness liner specifications for the Anand cooperative cluster where bio-based content thresholds are tightening procurement criteria. Go-to-market leverage rests on local extrusion capacity establishment with EFSA-equivalent migration testing capabilities to serve export-oriented Indian processors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with established Italian and Spanish food service relationships but stranded legacy fluorochemical coating assets requiring REACH-compliant reformulation. Long-term viability over a multi-year horizon hinges on cellulose nanofiber hybrid technology validation and EFSA approval pipeline depth. Monitor EFSA approval timeline compression as the critical inflection signal for premium tier margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive ethylene supply insulates German converters from naphtha-cracker volatility squeezing multilayer PE margins. |
| Cellulose Nanofiber Hybrid Development | Wood-derived nanocellulose layers address EU Green Deal mandates while matching moisture-barrier thresholds for aged cheese. |
| Direct-to-Retailer Contract Conversion | Bypassing regional packaging wholesalers captures margin pools previously allocated to distributor networks serving consolidated buyers. |
| EFSA Pre-Submission Migration Testing | Early engagement with EFSA bio-based additive pathways compresses 18-24 month approval timelines ahead of contract renewals. |
| Indian Domestic Extrusion Capacity Buildout | BIS certification requirements create protected market space for Maharashtra and Gujarat converters serving Anand cooperative demand. |
Study Parameters
Document review covered EU regulatory filings including EFSA food-contact substance notifications and REACH authorization registers, complemented by interviews with dairy processing procurement directors, multilayer film extrusion plant managers, and food service distribution channel heads. Secondary validation drew from customs trade data tracking ethylene-vinyl alcohol resin flows, SEC filings of integrated packaging multinationals, and dairy cooperative annual procurement disclosures. Bottom-up capacity assessments across German, French, and Italian converter installations were triangulated against top-down demand estimates from cheese production statistics and packaging intensity ratios.
Cross-reference between historical pricing panel inputs from resin compounders and forward volume projections from dairy cooperative expansion plans anchored the analytical framework across the modeling period. Segmentation dimensions modeled include material composition tier, end-use industry channel, thickness specification, and application function across the cheese lifecycle. CAGRs were derived from installed capacity utilization trajectories and substitution elasticity estimates between plastic and biodegradable formats. Industry-specific forecast inputs incorporated EFSA approval pipeline status and EU Single-Use Plastics Directive compliance deadline phasing.
Caveats apply where EFSA migration testing timeline extension or ethylene feedstock supply disruption could materially shift the outlook for compostable liner penetration rates. Forecasts reflect assumptions regarding regulatory enforcement consistency and dairy cooperative merger completion. A model refresh is warranted upon material change in EFSA bio-based additive approval velocity or EU extended producer responsibility fee structure revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Cream Separator Market