
 Cream Separator Market | 2026-2036
Cream Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Cream Separator Market Outlook
Skilled dairy equipment technician availability is bifurcating the competitive landscape between premium automated suppliers and maintenance-heavy legacy operators. Alfa Laval leverages its centrifugal R&D pipeline to anchor high-throughput dairy processor contracts across Northern Europe. GEA Group sustains geographic dominance through localized service networks that reduce equipment downtime for creameries. SPX Flow competes on modular system architectures that let mid-sized dairy farms scale capacity without full replacement.
A cream separator is a mechanical device that uses centrifugal force to divide whole milk into cream and skim milk, typically operating at bowl speeds exceeding 5,000 rpm and separation temperatures of 35–50°C to optimize fat globule buoyancy. The equipment serves dairy processors seeking precise butterfat standardization for cheese, yogurt, and ice cream production lines. Continuous cream separators capture the majority of value as industrial dairies prioritize uninterrupted throughput over batch flexibility. Membrane technology segments are gaining traction where processors demand lower energy consumption than conventional centrifugal systems, though centrifugal units still dominate installed base economics. Laboratory cream separators occupy a narrow margin pool serving quality control and R&D functions rather than production scale.
EU Dairy Hygiene Regulation and FDA Pasteurized Milk Ordinance standards shape equipment sanitation design, forcing manufacturers to integrate clean-in-place systems and food-grade stainless steel contact surfaces. CE marking and 3-A Sanitary Standards certification operate as gatekeeping requirements for market access across European and North American dairy processing jurisdictions. Stakeholders must monitor how evolving energy efficiency directives and carbon accounting rules reshape total cost of ownership calculations for separator fleet investments.
Market Dynamics
Centrifugal technology upgrades are compressing equipment replacement cycles as dairy processors chase butterfat recovery efficiency and EU energy efficiency compliance. Bowl speed optimization and clean-in-place integration now dictate capital allocation decisions across industrial creamery operations.
Growth Catalysts
- EU Dairy Hygiene Regulation:Automated separator lines with integrated CIP systems are becoming mandatory for licensed dairy operations across Germany and France, forcing equipment refresh cycles.
- Butterfat standardization demand:Ice cream and cheese manufacturers require precise fat content control, driving investment in continuous-flow centrifugal separators with real-time density monitoring.
- Energy efficiency directives:The EU Green Deal's industrial decarbonization targets are accelerating displacement of aging batch separators with variable-frequency drive units.
Market Restraints
- Stainless steel input volatility:Food-grade 316L stainless steel price swings directly impact separator bowl and housing manufacturing costs, squeezing margin predictability for equipment makers.
- Technician supply concentration:Skilled centrifugal maintenance specialists cluster in Northern European dairy clusters, leaving Southern and Eastern European processors dependent on costly service imports.
- Membrane filtration substitution:Microfiltration systems for skim milk production are capturing share in energy-conscious operations where fat globule damage tolerance permits lower separation precision.
Strategic Opportunities
- Indian dairy cooperative expansion:Amul and state dairy federations are modernizing village-level chilling centers, creating demand for compact, solar-compatible separators with reduced power draw.
- Precision fermentation integration:Cell-cultured dairy fat producers need laboratory-scale separators for R&D scale-up, opening a premium equipment tier adjacent to traditional food processing.
- CE marking harmonization:Mutual recognition agreements between EU and Mercosur standards are reducing certification friction for European equipment exporters targeting Brazilian cooperatives.
Industry Challenges
- 3-A Sanitary Standards compliance timelines:US-bound equipment faces 12-18 month certification cycles for welded bowl assemblies, delaying revenue recognition for export-focused manufacturers.
- Legacy control system integration:Dairy processors running 1990s-era SCADA infrastructure struggle to interface with IoT-enabled separators, requiring costly middleware development or full automation overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cream Separator Market |
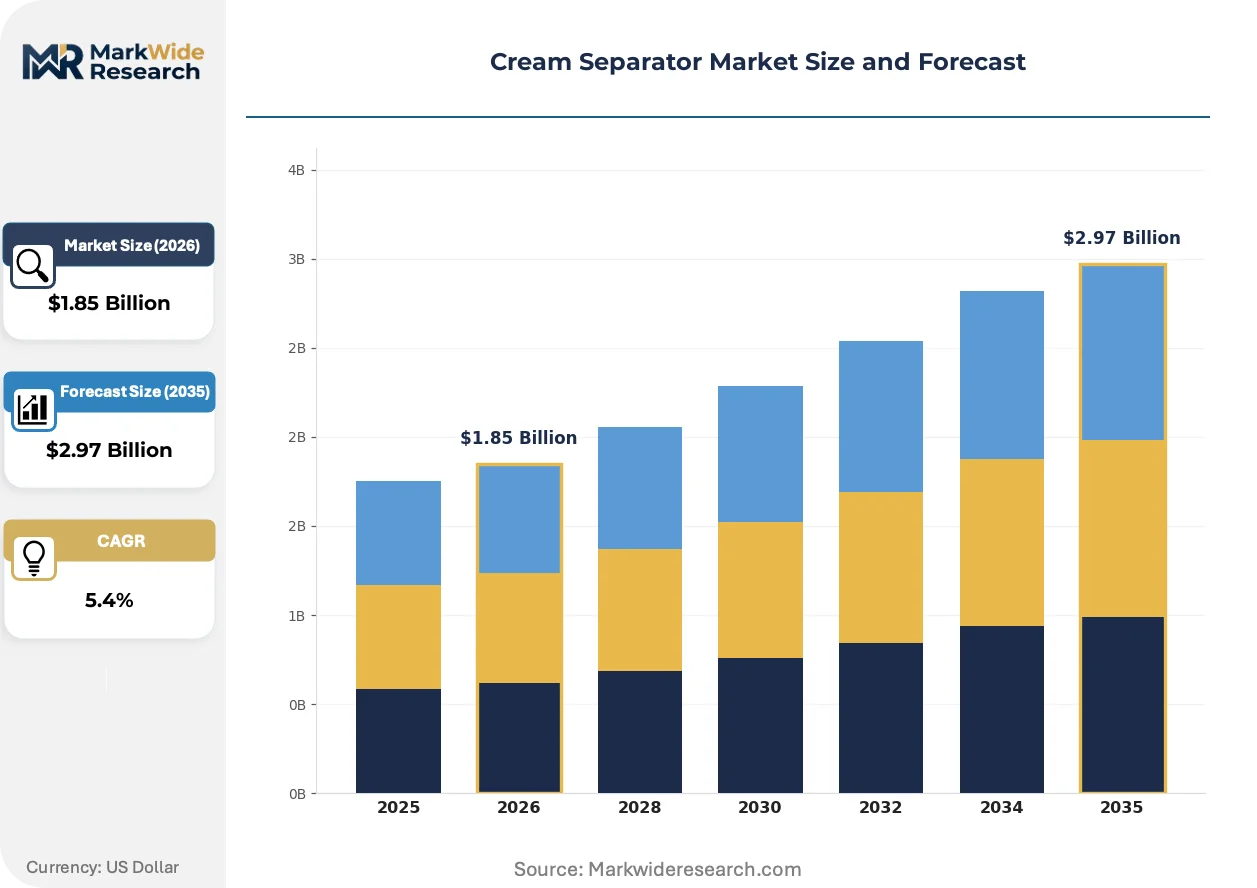
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Cream Separator, Continuous Cream Separator, Laboratory Cream Separator, Industrial Cream Separator End User: Dairy Farms, Creameries, Food Processing Industries, Beverage Manufacturers Technology: Centrifugal, Membrane, Mechanical, Vacuum Application: Milk Processing, Cheese Production, Ice Cream Manufacturing, Yogurt Production |
| Companies Covered | Alfa Laval, GEA Group, Tetra Pak, SPX Flow, Krones AG, Feldmeier Equipment, IDMC, Paul Mueller Company, Marlen International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream Separator Market Strategic Shifts
Equipment architecture is fragmenting between high-throughput industrial units and modular farm-scale systems, with digitalization and energy recovery systems becoming the primary differentiation vectors.
Self-cleaning bowl technology is miniaturizing. Disc stack separators with automatic solid ejection mechanisms now serve mid-sized dairy farms processing 5,000-20,000 liters daily. Dutch and Danish equipment suppliers are shipping these units with pre-configured skids that slash installation time. The technology is miniaturizing what was once exclusive to industrial creameries, compressing the addressable market boundary downward and enabling cooperative purchasing models.
REACH chemical compliance and F-Gas Regulation phase-down schedules are reshaping refrigerant choices in separator cooling circuits. Manufacturers are retrofitting R-404A-dependent units with CO2 transcritical systems or ammonia-based alternatives. German processors face the tightest compliance deadlines, accelerating equipment replacement ahead of 2025-2027 service gas bans and favoring suppliers with certified low-GWP retrofit programs.
Service contract unbundling is disrupting traditional equipment procurement. Dairy processors in the Netherlands and Belgium now separate capital purchase from maintenance agreements, benchmarking service providers on mean-time-between-failures rather than OEM affiliation. Independent technical service networks are capturing aftermarket revenue previously held by manufacturers, compressing lifetime customer value for original equipment suppliers.
Cream Separator Market Segmentation
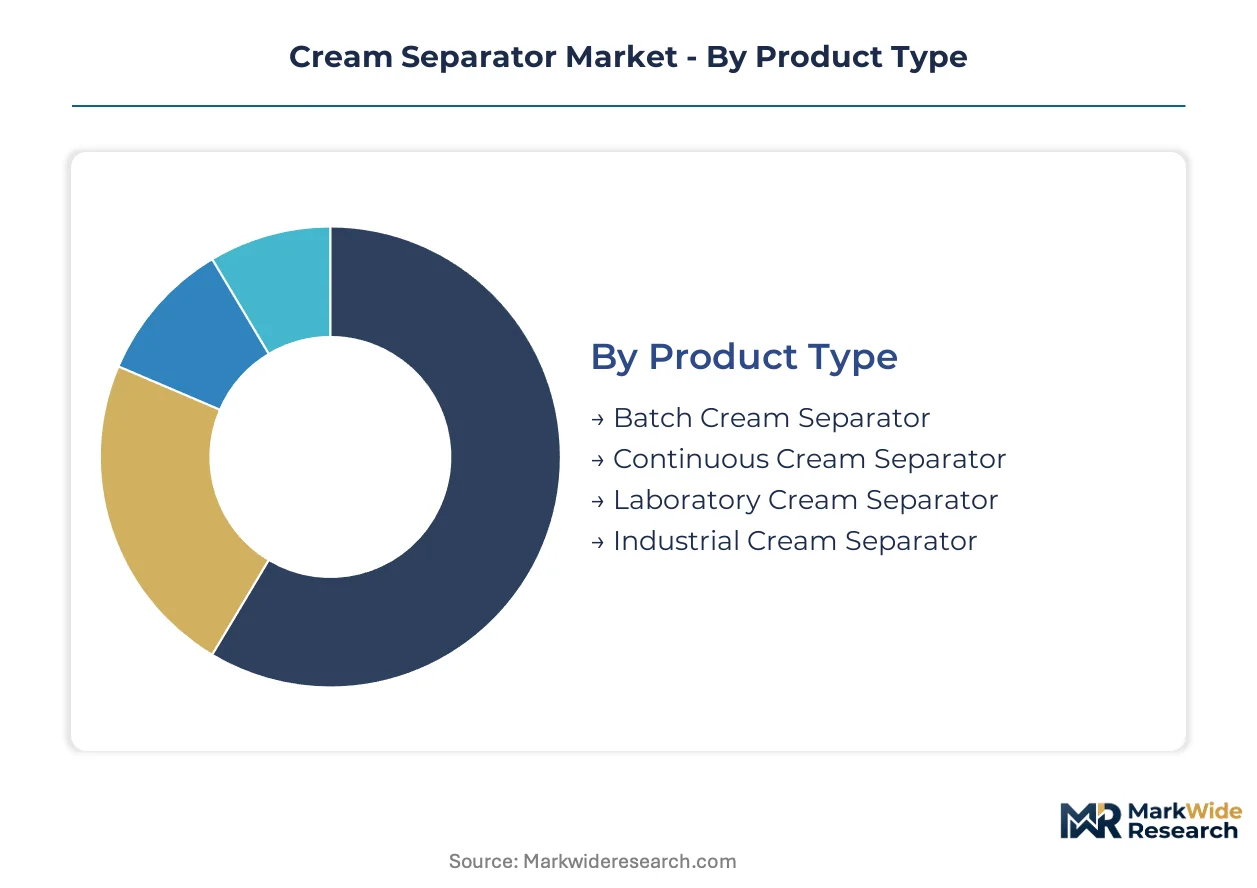
Cream separator procurement channels diverge sharply by operational scale. Industrial dairies source through direct OEM contracts with integrated service agreements, while farm-scale buyers rely on agricultural equipment distributors and cooperative purchasing pools. Understanding these channel dynamics illuminates where margin concentrates and which segments drive replacement cycles.
Product Type:
Continuous separators flow through direct manufacturer relationships with volume pricing tiers, while batch and laboratory units distribute through specialized dairy equipment dealers and scientific supply channels.
- Continuous Cream Separator:Bowl speeds exceed 5,000 rpm with automated solid ejection systems enabling 24-hour operation. German and French industrial creameries specify these units for butterfat standardization lines under EU Dairy Hygiene Regulation mandates. Real-time density monitoring and CIP integration command premium pricing through direct procurement channels.
- Industrial Cream Separator:High-throughput disc stack configurations process 20,000+ liters hourly with energy recovery systems. Northern European dairy processors anchor demand as they displace aging batch infrastructure ahead of EU Green Deal compliance deadlines.
- Batch Cream Separator:Manual or semi-automated units serve small-scale creameries and farmstead operations with lower capital requirements.
- Laboratory Cream Separator:Bench-scale centrifuges support quality control and R&D functions with precise speed control and small sample volumes.
Continuous separators dominate installed base economics. Laboratory units are where expansion concentrates as precision fermentation and cell-cultured dairy R&D scales.
End User:
Equipment specifications and procurement authority vary by buyer sophistication. Industrial processors negotiate multi-year service contracts, while farm cooperatives prioritize modular upgrade paths and local technician availability.
- Dairy Farms:Operations range from village-level chilling centers to automated milking cooperatives. Indian dairy federations drive demand for solar-compatible, reduced-power separators as electrification gaps persist in rural procurement zones.
- Food Processing Industries:Ice cream and cheese manufacturers require precise fat content control with integrated CIP systems. These buyers specify continuous-flow units with real-time monitoring through direct OEM relationships.
- Creameries:Mid-scale butter and specialty dairy producers balance throughput needs against capital constraints.
- Beverage Manufacturers:Specialized applications include cream liqueur production and functional beverage formulation.
Food processing industries anchor equipment value capture. Dairy farms represent the steepest expansion trajectory as cooperative modernization accelerates.
Technology:
Centrifugal systems command the premium tier through performance guarantees, while membrane alternatives penetrate where energy costs outweigh precision requirements.
- Centrifugal:Disc stack separators using density differential principles achieve 99%+ fat recovery rates. Bowl speed optimization and variable-frequency drives satisfy EU energy efficiency directives while maintaining separation precision.
- Membrane:Microfiltration systems reduce energy consumption by 30-40% compared to centrifugal equivalents. These units gain share in skim milk production where fat globule damage tolerance permits lower separation precision.
- Mechanical:Gravity-based or simple rotational methods serve minimal-processing applications and developing market entry points.
- Vacuum:Reduced-pressure separation protects heat-sensitive components in specialty dairy and nutraceutical applications.
Centrifugal technology commands the majority of revenue. Membrane systems are climbing fastest as energy accounting reshapes total cost of ownership calculations.
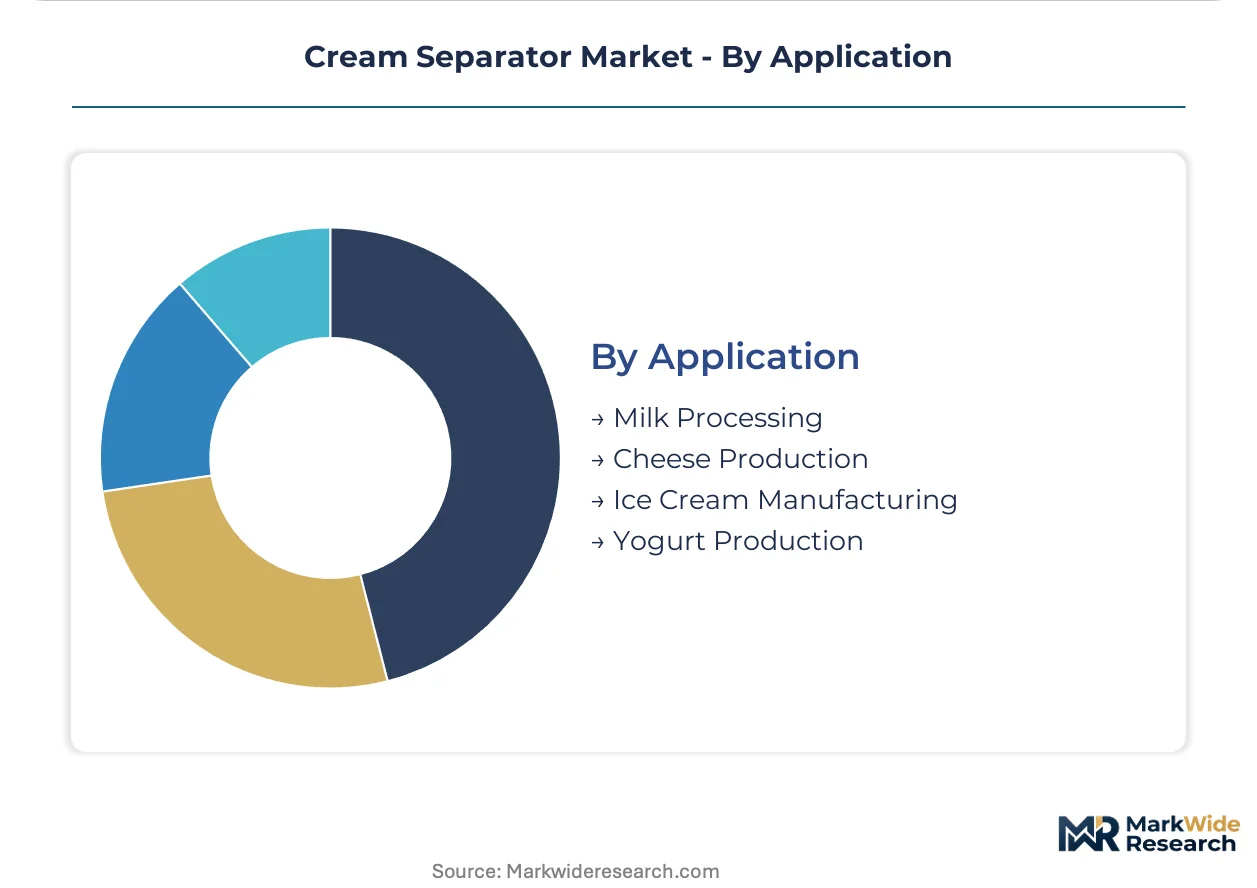
Application:
Application-specific requirements dictate bowl geometry, temperature control, and sanitation protocols. Cheese and ice cream production demand the tightest butterfat tolerances.
- Cheese Production:Standardized milk fat content directly impacts yield and texture profiles. Continuous separators with automated density control enable precise fat adjustment for cheddar, gouda, and mozzarella process lines.
- Ice Cream Manufacturing:Premium formulations require 10-18% butterfat content with minimal variation. Real-time monitoring systems prevent batch defects that destroy margin on high-value product lines.
- Milk Processing:Fluid milk standardization and cream separation for retail distribution.
- Yogurt Production:Fat standardization for Greek, skyr, and traditional yogurt varieties with specific creaming requirements.
Cheese production anchors industrial separator deployment. Ice cream manufacturing is gaining share fastest as premium frozen dessert markets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Dairy Hygiene Regulation enforcement anchors equipment demand across Northern Europe, while Indian dairy cooperative modernization and Brazilian cooperative expansion create parallel growth corridors outside the traditional core.
Germany
Dairy processors in Bavaria and Lower Saxony are retrofitting separator cooling circuits ahead of F-Gas Regulation phase-down deadlines. The KBA enforces strict refrigerant compliance timelines for industrial equipment. Munich-area creameries are accelerating replacement of R-404A-dependent units with CO2 transcritical systems.
France
Cheese producers in Auvergne-Rhône-Alpes require precise butterfat standardization for AOC-certified product lines. ANSM sanitation protocols mandate clean-in-place integration for licensed dairy operations. The Normandy dairy cluster is expanding automated separator lines to meet export certification requirements.
India
Amul and state dairy federations are modernizing village-level chilling centers across Gujarat and Maharashtra. FSSAI food safety standards are driving equipment upgrades at cooperative processing facilities. Karnataka's dairy belt is deploying solar-compatible separators to bridge rural electrification gaps.
United States
Ice cream manufacturers in the Midwest require continuous-flow units with real-time density monitoring for premium formulation consistency. FDA Pasteurized Milk Ordinance standards dictate 3-A Sanitary certification for welded bowl assemblies. Wisconsin's dairy processing corridor is displacing aging batch infrastructure with variable-frequency drive units.
Brazil
Dairy cooperatives in Minas Gerais and São Paulo are importing European equipment under Mercosur-EU mutual recognition agreements. ANVISA food safety regulations are harmonizing with CE marking standards for dairy processing machinery. The southern Brazilian dairy belt is consolidating farm-scale operations into centralized processing hubs.
Cream Separator Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in cream separator supply. Premium automated suppliers compete against maintenance-heavy legacy operators on technician availability and service network density. Three archetypes dominate: centrifugal R&D specialists anchoring high-throughput contracts, localized service network operators reducing equipment downtime, and modular system architects enabling mid-farm scaling. Competitive moves concentrate on geographic expansion through certification harmonization and portfolio diversification into precision fermentation adjacent equipment.
Among European industrial equipment suppliers, Alfa Laval and GEA Group exemplify the integrated leadership tier, while SPX Flow occupies a position within the modular architecture specialist segment. Alfa Laval represents the centrifugal R&D-driven archetype serving Northern European dairy processors. GEA Group exemplifies geographic dominance through service infrastructure. SPX Flow sits within the scaling-without-replacement tier addressing mid-sized farm cooperative demand.
| Leading Market Players |
|---|
| Alfa Laval |
| GEA Group |
| Tetra Pak |
| SPX Flow |
| Krones AG |
| Feldmeier Equipment |
| IDMC |
| Paul Mueller Company |
| Marlen International |
| Others |
Value Chain & Pricing Dynamics
CE marking and 3-A Sanitary Standards certification gate both equipment qualification and price differentiation simultaneously, forcing manufacturers to absorb compliance costs while tiering offerings by automation level and service bundling. Stainless steel input volatility feeds directly into margin compression, compressing the window between qualified supply and viable pricing.
Pricing Analysis
European industrial processors pay 15-25% premiums over Indian dairy cooperatives for equivalent throughput capacity, reflecting certification grade and localized service network density as the primary price differentiation drivers. Three-tier pricing structure across premium automated, standard semi-automated, and economy batch levels segments buyers by operational scale and technician availability. Cost compression in the economy tier is intensifying because membrane filtration substitutes erode centrifugal unit pricing power for skim milk applications. Farm-scale cooperatives in Southern and Eastern Europe exhibit highest price sensitivity, while Northern European industrial creameries prioritize uptime guarantees over capital outlay.
Supply Chain Analysis
Food-grade 316L stainless steel forging capacity concentrates in Germany, Italy, and Sweden, creating single-source vulnerability for precision-machined separator bowls and disc stack assemblies. Manufacturing draws from nickel ore processed in Indonesia and Russia, chromium from South Africa and Kazakhstan, and specialized bearing systems from Japanese and German precision engineering suppliers. Tariff exposure on Chinese-sourced electronic control modules and variable-frequency drives threatens cost predictability for IoT-enabled separator lines. Distribution runs through direct OEM contracts for industrial dairies and agricultural equipment dealer networks for farm-scale buyers, with cooperative purchasing pools emerging as a parallel channel in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled centrifugal maintenance technician scarcity constrains expansion velocity, with equipment uptime guarantees becoming the scarce capability that separates viable suppliers from stranded asset operators.
For Market Incumbents: Shield installed base revenue through captive service contract renewal programs that lock in multi-year maintenance agreements before independent technical networks mature. Deepen backward integration into food-grade stainless steel forging to buffer margin volatility from commodity input swings. Prioritize certification pre-positioning for emerging Mercosur-EU mutual recognition pathways to anchor Brazilian cooperative demand ahead of competitor entry. For New Entrants and Emerging Players: CE marking fast-track programs for modular farm-scale separators open procurement channels among Indian dairy federations modernizing village-level chilling centers. Target Karnataka and Maharashtra solar-compatible equipment demand where electrification gaps persist and incumbent service networks remain thin. Penetrate through cooperative purchasing pool aggregation, bypassing direct OEM relationship requirements that favor established suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dairy equipment roll-ups that consolidated regional service networks but lack centrifugal R&D depth for next-generation energy efficiency compliance. Five-to-ten year viability hinges on separator fleet replacement cycles driven by F-Gas Regulation deadlines and EU Green Deal industrial decarbonization mandates. Watch for membrane filtration share inflection in skim milk production as a signal that centrifugal unit pricing power is structurally eroding.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-in-Place System Integration | ANSM and FDA sanitation mandates make CIP capability non-negotiable for licensed dairy operations. |
| Variable-Frequency Drive Retrofit Programs | EU energy efficiency directives accelerate displacement of fixed-speed batch separator infrastructure. |
| Solar-Compatible Separator Development | FSSAI standards and rural electrification gaps in India create demand for reduced-power equipment. |
| CO2 Transcritical Cooling Conversion | KBA-enforced F-Gas Regulation deadlines force refrigerant system replacement in German creameries. |
| Precision Fermentation Adjacent Equipment | Cell-cultured dairy R&D scale-up opens premium laboratory separator tier beyond traditional food processing. |
Study Parameters
Operator-level perspectives from dairy plant engineers, equipment maintenance directors, cooperative procurement managers, and aftermarket service technicians anchored the qualitative base for this analysis. Primary field engagement combined with secondary validation against EU Dairy Hygiene Regulation enforcement records, FDA Pasteurized Milk Ordinance compliance databases, FSSAI equipment registration filings, and customs trade data for food-grade stainless steel imports. Bottom-up equipment shipment tracking and top-down dairy processing capacity modeling provided cross-verification for market sizing.
Sensitivity analysis tested forecast robustness across alternative energy price trajectories and membrane filtration substitution rates over the projection horizon. Segmentation dimensions modeled include product type, technology, application, end user scale, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and dairy processing capacity expansion pipelines, with specific inputs for EU Green Deal compliance deadlines and Indian cooperative modernization program schedules.
The analysis sits within stated boundaries; outcomes outside sustained stainless steel price stability or accelerated membrane technology cost reduction would require recalibration. Forecasts reflect documented assumptions regarding technician supply concentration and certification harmonization timelines. Practitioners should keep alternative scenarios live as F-Gas Regulation enforcement intensity and precision fermentation commercialization scale evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Yogurt Cup Market