
 Yogurt Cup Market | 2026-2036
Yogurt Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Yogurt Cup Market Analytics
The EU Green Deal is expanding the addressable market for recyclable and renewable yogurt cup substrates across Europe. Danone leverages its integrated dairy and packaging supply chain to secure preferential access to rPET and bio-PBS volumes. Lactalis anchors its competitive position through manufacturing scale across French and Italian dairy clusters. Nestlé S.A. differentiates via proprietary barrier coating technologies that maintain shelf life while enabling mono-material sortability.
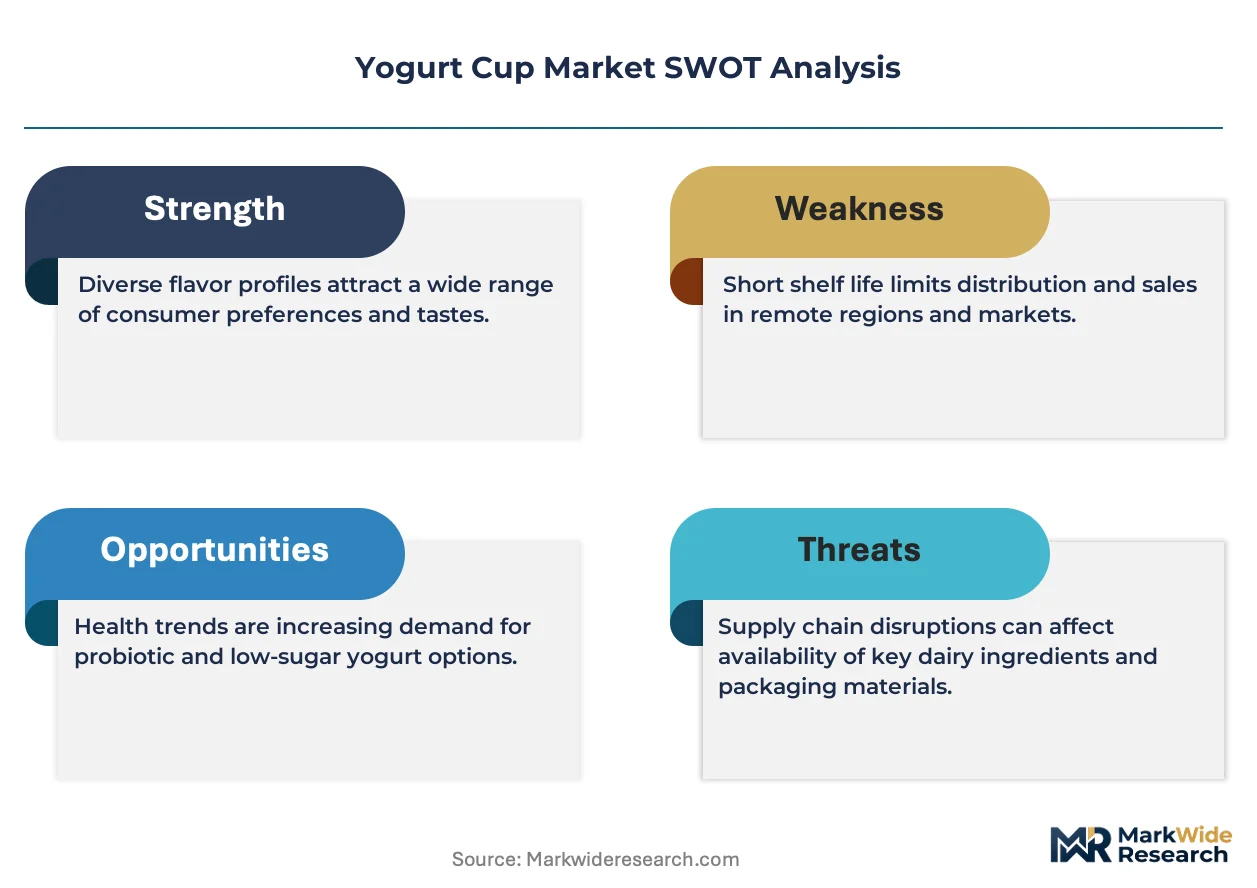
A yogurt cup is a thermoformed or injection-molded single-use container, typically manufactured from polypropylene, polystyrene, or polyethylene terephthalate with optional ethylene vinyl alcohol or polyamide barrier layers, designed to contain fermented dairy products under refrigerated distribution. Its primary commercial purpose is to preserve product integrity, enable portion control, and support retail shelf differentiation. Greek Yogurt commands premium shelf positioning and higher per-unit margins due to protein density and consumer willingness to pay for functional nutrition. Eco-Friendly Packaging represents the fastest-growing structural category as retailer mandates and extended producer responsibility schemes accelerate substitution of multi-layer formats. Single-Serve Cups remain the volume anchor across convenience and on-premise channels.
EMA food-contact regulations, REACH substance restrictions, and EU Packaging and Packaging Waste Directive revisions collectively determine which barrier chemistries and recycling pathways gain market access across European member states. EFSA novel food approvals additionally shape which probiotic and functional claims can appear on cup labels. Stakeholders must monitor polymer recycling quota trajectories and sortation infrastructure investments to align substrate choices with evolving compliance thresholds.
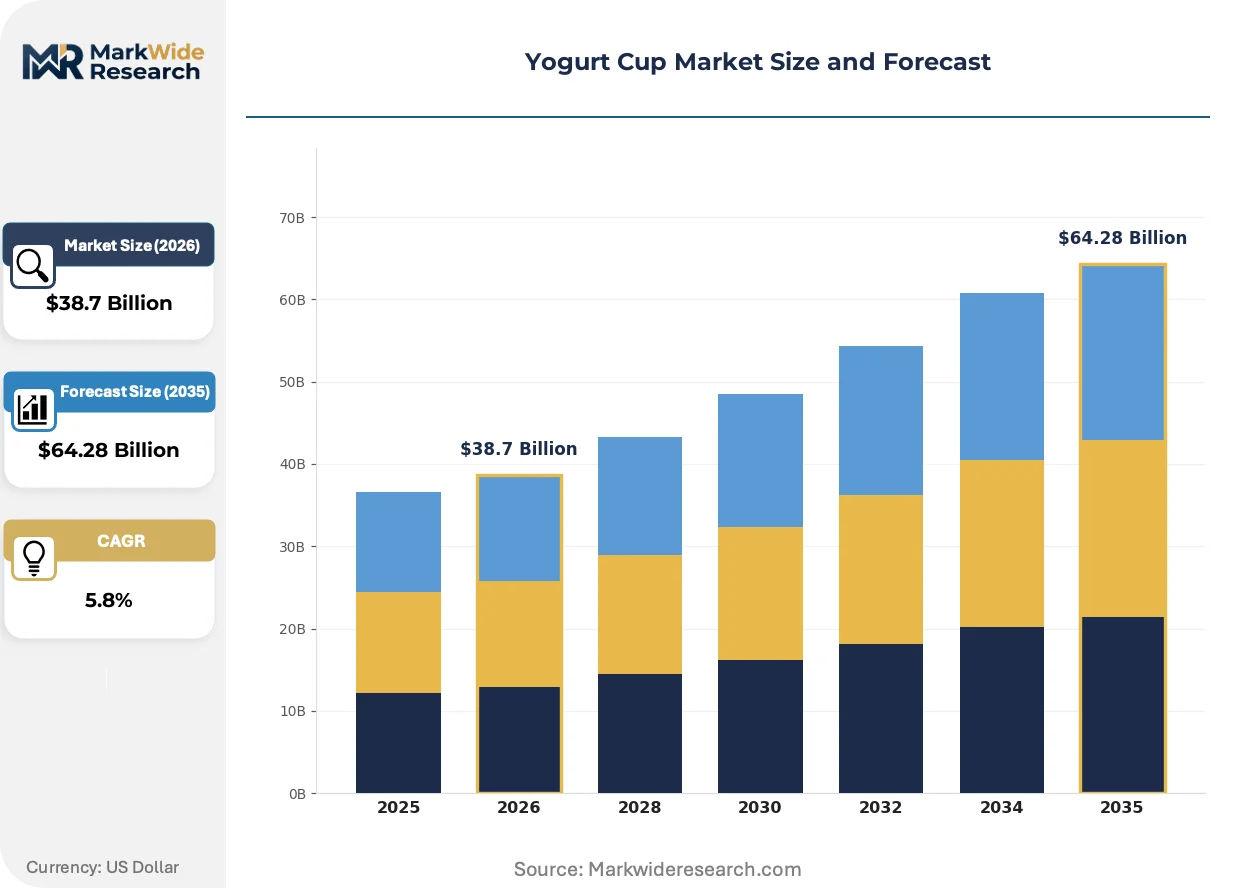
Market Dynamics
Extended producer responsibility schemes and retailer plastic reduction mandates are forcing converters to abandon multi-layer barrier structures in favor of mono-material or bio-based alternatives that maintain shelf stability.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon blowing agents accelerates adoption of bio-PBS and PLA foaming technologies for insulated cup structures.
- German dairy clusters:Concentrated processing capacity in Bavaria and Lower Saxony creates localized demand for rPET supply contracts with guaranteed offtake volumes.
- Probiotic strain diversification:EFSA novel food approvals for Lactobacillus and Bifidobacterium variants expand functional claim eligibility on cup labels.
Market Restraints
- rPET feedstock scarcity:Bottle-to-bottle recycling loops capture most post-consumer PET, leaving limited flake supply for dairy packaging converters.
- Barrier performance gap:Current bio-based coatings fail to match ethylene vinyl alcohol oxygen transmission rates required for extended shelf-life skyr and Greek yogurt formats.
- Sortation infrastructure deficits:Near-infrared detection systems at French and Italian material recovery facilities cannot reliably distinguish mono-PP cups from PS alternatives.
Strategic Opportunities
- Deposit-return expansion:Germany's DRS extension to include dairy cups creates closed-loop collection economics for polypropylene recovery.
- Active packaging convergence:Integration of oxygen-scavenging enzymes with thermoformed structures enables shelf-life extension without external barrier films.
- Direct-store-delivery channels:Cold-chain logistics partnerships with convenience retailers bypass traditional wholesale distribution markups.
Industry Challenges
- Thermoforming tool reconfiguration:Transitioning from PS to PP or PET requires mold redesign and cooling line modifications that extend commissioning timelines.
- Food-contact migration testing:EFSA compliance documentation for new bio-based additives demands 12-18 month evaluation cycles before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yogurt Cup Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Frozen Yogurt, Low-Fat Yogurt, Organic Yogurt Packaging Type: Single-Serve Cups, Multi-Pack Cups, Bulk Containers, Eco-Friendly Packaging Flavor: Strawberry, Vanilla, Chocolate, Mixed Berry Target Audience: Health-Conscious Consumers, Kids, Fitness Enthusiasts, Snackers |
| Companies Covered | Chobani LLC, Danone, Lactalis, General Mills Inc., FAGE International S.A, Nestlé S.A., Fonterra Co-operative Group Limited, Arla Foods amba, Dairy Farmers of America Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yogurt Cup Market Evolving Landscape
Material science advances and regulatory compliance pressures are converging to reshape substrate selection, manufacturing processes, and end-of-life pathways across European yogurt packaging.
Digital watermarking technology is integrating traceability codes directly into cup sidewalls during thermoforming. Retailers in France and the Netherlands are piloting these marked containers to verify sortation accuracy and validate recycling claims. This integration is compressing the timeline for mass balance certification by linking individual packages to polymer batch records.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating oil-grease-barrier coatings previously standard for full-fat yogurt applications. Converters are responding with silicon dioxide and clay-based alternatives that meet ECHA thresholds. High-fat Greek and skyr formats face the steepest reformulation burden, with some suppliers temporarily exiting those segments until compliant barriers achieve scale.
Buyer concentration among German and British supermarket private-label programs is consolidating procurement decisions into sustainability-focused category managers. These buyers now mandate recyclability certifications and carbon footprint disclosures as table stakes for contract renewal. The shift is most visible in discounter channels, where Aldi and Lidl's pan-European buying desks have standardized mono-PP specifications across national subsidiaries.
Yogurt Cup Market Segmentation
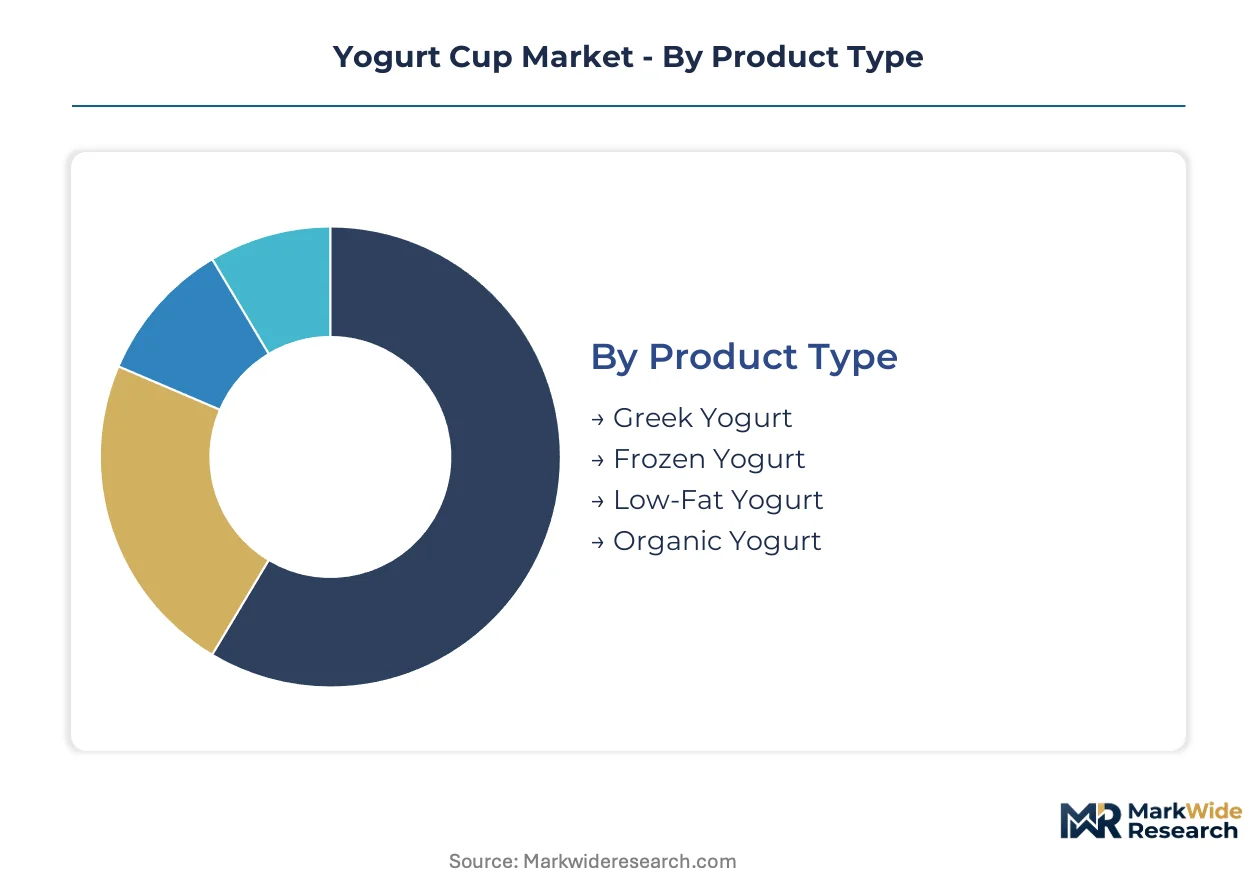
Segmentation in yogurt cup manufacturing dictates thermoforming line investments, barrier coating selections, and shelf-life validation protocols. Each dimension—product viscosity, pack size, flavor stability requirements, and consumer occasion—triggers distinct tooling, material, and distribution specifications that converters must align with retailer mandates.
Product Type:
Capital intensity varies sharply across fermentation and filling technologies, with high-protein formats demanding specialized homogenization and extended incubation infrastructure.
- Greek Yogurt:Triple-strained processing achieves protein densities above 10g per 100g, requiring centrifugal separators and extended fermentation tanks. German and British retailers command premium placement for these skus, though whey disposal costs pressure margin structures.
- Frozen Yogurt:Blast freezing tunnels and controlled ice crystal formation equipment represent the heaviest capex burden in this category. French convenience retailers are expanding freezer-door allocations for portion-controlled formats.
- Low-Fat Yogurt:Fat reduction below 0.5% demands modified starch or gelatin stabilization systems to prevent syneresis.
- Organic Yogurt:EU organic certification requires segregated supply chains and third-party audit documentation for milk sourcing and culture propagation.
Most installed capacity flows through Greek Yogurt. Expansion is steepest in Organic Yogurt.
Packaging Type:
Format selection determines barrier performance requirements and end-of-life compliance pathways, with retailer sustainability mandates now overriding traditional cost optimization.
- Eco-Friendly Packaging:Mono-material PP and bio-PBS substrates with plasma-deposited silicon dioxide barriers satisfy Aldi and Lidl recyclability specifications. Italian converters face steepest requalification timelines as EPR schemes tighten.
- Single-Serve Cups:Thermoformed 125-150g formats dominate grab-and-go consumption occasions across German railway stations and British convenience multiples. High-speed filling lines achieve 60,000 units per hour.
- Multi-Pack Cups:Four- and six-unit configurations with shrink-wrapped secondary packaging serve family replenishment shopping missions.
- Bulk Containers:1-2kg injection-molded pails target foodservice and ingredient manufacturing channels with extended shelf-life requirements.
Volume concentrates in Single-Serve Cups. Steepest expansion trajectory belongs to Eco-Friendly Packaging.
Flavor:
Flavor stability drives barrier specification and cold-chain intensity, with fruit particulate and cocoa formulations presenting distinct oxygen and moisture sensitivity profiles.
- Strawberry:Anthocyanin color degradation above 4°C necessitates high-barrier EVOH or AlOx-coated films for shelf-life targets exceeding 28 days. British multiples prioritize this flavor for private-label ranges.
- Vanilla:Natural vanillin volatility requires nitrogen flushing and minimal headspace design to prevent flavor fade across distribution.
- Chocolate:Cocoa butter bloom and fat oxidation demand exceptional oxygen barriers, often forcing multi-layer structures despite recyclability trade-offs.
- Mixed Berry:Acidic fruit blends accelerate lactic acid migration into packaging substrates, triggering EFSA migration testing protocols.
Strawberry commands the largest production footprint. Mixed Berry is climbing the fastest as formulation complexity attracts premium positioning.
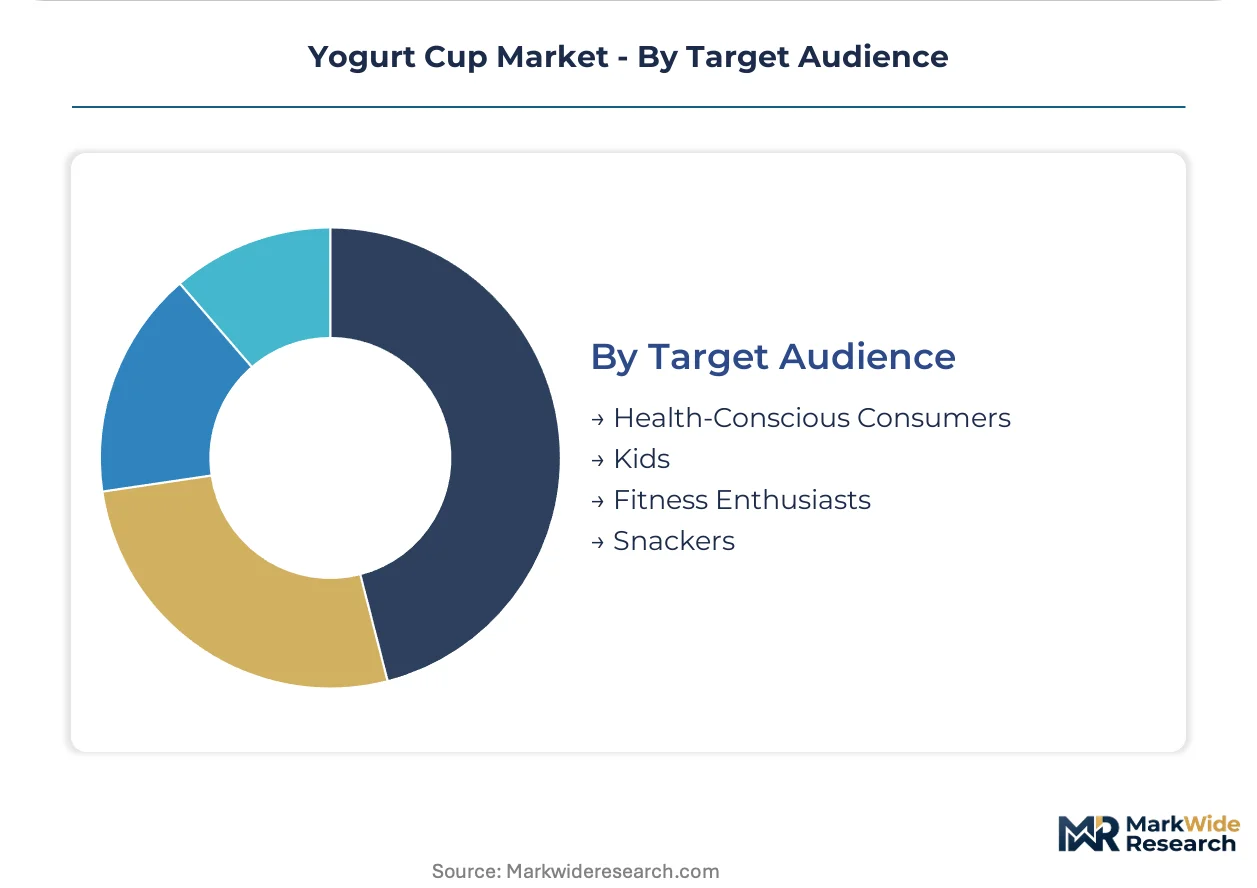
Target Audience:
Consumer occasion segmentation reshapes pack size, protein positioning, and channel strategy, with health credentialing now mandatory for contract access at major retailers.
- Health-Conscious Consumers:Probiotic strain specificity and low-sugar claims drive EFSA novel food investment and on-pack communication real estate. German pharmacy channel distribution requires substantiated health benefit documentation.
- Fitness Enthusiasts:20g+ protein formats with branched-chain amino acid fortification command price premiums in sports nutrition retail.
- Kids:Character-licensed packaging and controlled portion sizes target parental purchase triggers in French and Italian hypermarkets.
- Snackers:Spoon-in-lid convenience features and ambient-stable formulations expand consumption beyond traditional breakfast occasions.
Health-Conscious Consumers absorb the greatest NPD investment. Snackers represent the fastest-growing consumption occasion as meal-boundary erosion continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and dairy technologists concentrate in Germany, France, and the United Kingdom, anchoring Europe's yogurt cup innovation corridor.
Germany
Bavarian and Lower Saxony dairy clusters drive mono-material PP demand as Aldi and Lidl standardize recyclability specifications. The national packaging law implements strict extended producer responsibility quotas. Thermoforming converters in Munich and Hamburg retrofit lines to handle rPET flake streams.
France
Paris-based retailers pilot digital watermarking for sortation verification, accelerating mass balance certification timelines. ANSM enforces EFSA migration testing protocols for bio-based barrier coatings. Dairy processors in Brittany and the Rhône-Alpes region invest in plasma-deposited silicon dioxide alternatives.
United Kingdom
British supermarket private-label programs consolidate procurement through sustainability-focused category managers. The Environment Agency enforces plastic packaging tax thresholds on sub-30% recycled content. Manufacturing gravity centers on West Midlands and Yorkshire thermoforming facilities.
Italy
Emilia-Romagna's dairy cooperatives face requalification pressure as national EPR schemes tighten mono-material compliance deadlines. ECHA REACH restrictions on perfluoroalkyl substances eliminate legacy oil-grease barriers. Converters in Bologna and Parma trial clay-based coating formulations.
Netherlands
Rotterdam's port infrastructure enables bio-PBS resin imports from Asian polymer producers. The national waste management authority invests in near-infrared sortation upgrades. Food packaging R&D clusters in Wageningen develop active packaging with oxygen-scavenging enzymes.
Yogurt Cup Market Competitive Landscape
Capital-heavy dairy processors compete with asset-light packaging converters for control over substrate specifications and shelf-life validation protocols. The vendor base separates into three tiers: integrated multinational dairy groups, specialized thermoforming converters, and bio-based material suppliers. Consolidation pressure intensifies as retailer sustainability mandates compress supplier margins. Dominant competitive moves include backward integration into rPET flake processing and strategic partnerships with mass balance certification bodies.
Within the integrated dairy tier, Danone and Nestlé S.A. exemplify archetypes that combine captive yogurt production with proprietary packaging development. Lactalis occupies a position representing manufacturing scale concentration across French and Italian dairy clusters. These three entities anchor competitive dynamics through their influence over substrate selection standards and barrier technology roadmaps.
| Leading Market Players |
|---|
| Chobani LLC |
| Danone |
| Lactalis |
| General Mills Inc. |
| FAGE International S.A |
| Nestlé S.A. |
| Fonterra Co-operative Group Limited |
| Arla Foods amba |
| Dairy Farmers of America Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap thermoforming specialists in Bavaria and Emilia-Romagna anchor supply-side discipline through long-term rPET offtake contracts that buffer spot resin volatility. Their concentrated ownership structures enable patient capital deployment into mono-material line retrofits, compressing pricing power for asset-light converters competing on spot purchasing.
Pricing Analysis
Barrier-coated substrates and uncoated mono-material grades split the pricing architecture across premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA migration certification status and Aldi recyclability mandates. Cost compression in standard-grade PP runs through rPET feedstock scarcity and flake quality inconsistency. Discounter private-label buyers exhibit highest price sensitivity, while pharmacy-channel health-positioned formats absorb premium positioning.
Supply Chain Analysis
Deposit-return collection flows for dairy cups create reverse-logistics infrastructure that German converters leverage for closed-loop flake recovery. Raw material sourcing concentrates in Germany, France, and the Netherlands, with rPET flake processing anchored in Hamburg and Rotterdam port zones. Barrier coating chemistries draw from Belgian and Swiss specialty chemical suppliers. Single-source vulnerability sits with Asian bio-PBS resin producers serving Dutch thermoformers. Distribution runs through direct-store-delivery partnerships with Aldi and Lidl regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yogurt cup market functions as a regulatory compounder where EU F-Gas Regulation phasedowns and EPR quota escalations mechanically expand demand for compliant substrate alternatives.
For Market Incumbents: Lock in backward integration into rPET flake washing and pelletizing to secure feedstock priority as bottle-to-bottle loops tighten availability. Deepen channel control through exclusive direct-store-delivery contracts with German discounters that freeze out smaller converters on logistics minimums. The threat vector is emerging bio-PBS specialists capturing Lidl sustainability scorecard premiums through mass balance certification. For New Entrants and Emerging Players: Sustainability-focused category managers at British supermarket private-label programs represent the most penetrable buyer archetype, as incumbent dairy groups lack flexible mono-material pilot capacity. Target Italian dairy cooperatives facing EPR requalification deadlines with toll thermoforming services that bypass their capex constraints. A co-development go-to-market with Wageningen active packaging clusters enables oxygen-scavenging enzyme integration without internal R&D infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap French converters with stranded PS tooling assets and pending ANSM barrier requalification costs. The five-to-ten year viability window favors those with secured bio-PBS resin contracts and digital watermarking pilot participation. Monitor German DRS expansion implementation timelines as the inflection signal for polypropylene recovery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Processing | Secures feedstock priority against bottle-to-bottle competition from beverage packaging loops. |
| Digital Watermarking Pilot Participation | Links individual cups to polymer batch records for mass balance certification with French retailers. |
| Active Packaging R&D Partnership | Integrates oxygen-scavenging enzymes with thermoformed structures to bypass external barrier films. |
| Direct-Store-Delivery Channel Expansion | Bypasses wholesale distribution markups through cold-chain logistics partnerships with convenience retailers. |
| Bio-PBS Resin Supply Agreement | Locks in Asian polymer volumes ahead of EU F-Gas Regulation phasedown deadlines for insulated cup structures. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, Italy, and the Netherlands, with primary inputs from each market cluster. The research combines structured interviews with thermoforming plant managers, sustainability procurement leads at Aldi and Lidl, dairy processing technology directors, and EFSA regulatory affairs specialists with secondary validation from EU Packaging and Packaging Waste Directive revision documents, ECHA REACH substance restriction filings, and national extended producer responsibility scheme disclosures. Bottom-up capacity modeling and top-down demand triangulation cross-validate volume estimates.
Granularity-level modeling disaggregates the analysis window by product type, packaging format, flavor stability requirement, and target consumer occasion, with additional dimensioning by regional regulatory cluster and retailer sustainability mandate intensity. CAGRs derive from segmented volume trajectories calibrated to EPR quota implementation schedules and rPET flake availability curves. Forecast inputs include thermoforming line commissioning timelines, EFSA novel food approval pipelines for probiotic strains, and near-infrared sortation infrastructure investment trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bio-based barrier performance gaps and deposit-return scheme expansion beyond Germany. Practitioners should monitor ANSM migration testing backlog durations and Italian EPR compliance deadline extensions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Ice Cream Making Machine Market