
 Milk Homogenizer Machine Market | 2026-2036
Milk Homogenizer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Homogenizer Machine Market Foresight
ISO 3-A Sanitary Standards certification is reorganizing competitive access in the milk homogenizer machine landscape, forcing smaller fabricators toward costly third-party validation. GEA Group leverages its captive valve and pump supply chain to sustain margin control across turnkey dairy lines. Tetra Pak International anchors its position through integrated aseptic packaging-homogenizer bundles that lock in beverage manufacturing customers. Shanghai Samro Homogenizer competes on localized service density across provincial Chinese dairy cooperatives.
A milk homogenizer machine forces fluid milk through a narrow valve or orifice at pressures typically ranging from 100 to 250 bar, shattering fat globules into sub-micron diameters to prevent cream separation and extend shelf stability. The process transforms raw milk into commercially uniform product suitable for standardized retail packaging and downstream ice cream production. High-pressure homogenization technology captures the fastest expansion trajectory as processors pursue extended shelf-life formats and reduced thermal processing. Inline homogenizer configurations dominate installed base economics due to continuous-flow integration with pasteurizer circuits, while laboratory homogenizer demand concentrates in nutritional drinks R&D programs where formulation iteration requires rapid batch turnaround.
FDA pasteurized milk ordinance enforcement in the United States and EU MDR pressure-equipment directives in Europe shape safety-critical component sourcing and welded-seam documentation requirements. BIS certification mandates in India and FSSAI packaging regulations for standardized milk fat content compel domestic dairy cooperatives to upgrade from legacy mechanical units. Stakeholders must monitor evolving national dairy codes and pressure-vessel harmonization timelines to time capital deployment across fragmented regulatory jurisdictions.
Market Dynamics
High-pressure homogenization technology is compressing equipment replacement cycles as dairy processors chase extended shelf-life formats without intensifying thermal processing regimes.
Growth Catalysts
- FSSAI packaging mandates:India's standardized milk fat regulations compel cooperative dairies in Gujarat and Maharashtra to retire legacy mechanical homogenizers for certified high-pressure units.
- Extended shelf-life formats:Ultra-high-temperature milk lines in Southeast Asia require homogenization pressures above 200 bar to stabilize fat emulsions through ambient distribution.
- Inline continuous-flow integration:Dairy processors are embedding homogenizers directly into pasteurizer circuits to eliminate batch handling losses and reduce floor-space requirements.
Market Restraints
- Stainless steel price volatility:316L-grade alloy input costs for valve assemblies and pump housings swing with nickel market fluctuations, compressing fabricator margins on fixed-price contracts.
- ISO 3-A certification concentration:Third-party sanitary validation capacity concentrates among European and North American testing bodies, imposing 12-18 month queue delays for Asian equipment builders.
- Aseptic packaging bundling:Integrated packaging-homogenizer systems from turnkey vendors lock processors into single-source maintenance dependencies, raising lifetime cost exposure.
Strategic Opportunities
- Plant-based milk analogues:Oat and almond protein beverage processors in North America and Europe require homogenization to stabilize oil-in-water emulsions without dairy fat globule structures.
- CE marking harmonization:The EU MDR pressure-equipment directive creates a single conformity pathway for homogenizer exports across 27 member states, reducing national certification fragmentation.
- Laboratory-scale R&D demand:Nutritional drink formulation programs in university and corporate research centers need rapid-batch homogenizers for iterative particle-size testing.
Industry Challenges
- High-pressure seal replacement cycles:Valve seat and plunger wear at 250 bar operating pressures demand specialized technician skills and proprietary tooling that most dairy maintenance teams lack.
- Welded-seam documentation gaps:FDA pasteurized milk ordinance enforcement requires full material traceability for pressure-bearing components, forcing fabricators to rebuild quality systems for US market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Homogenizer Machine Market |
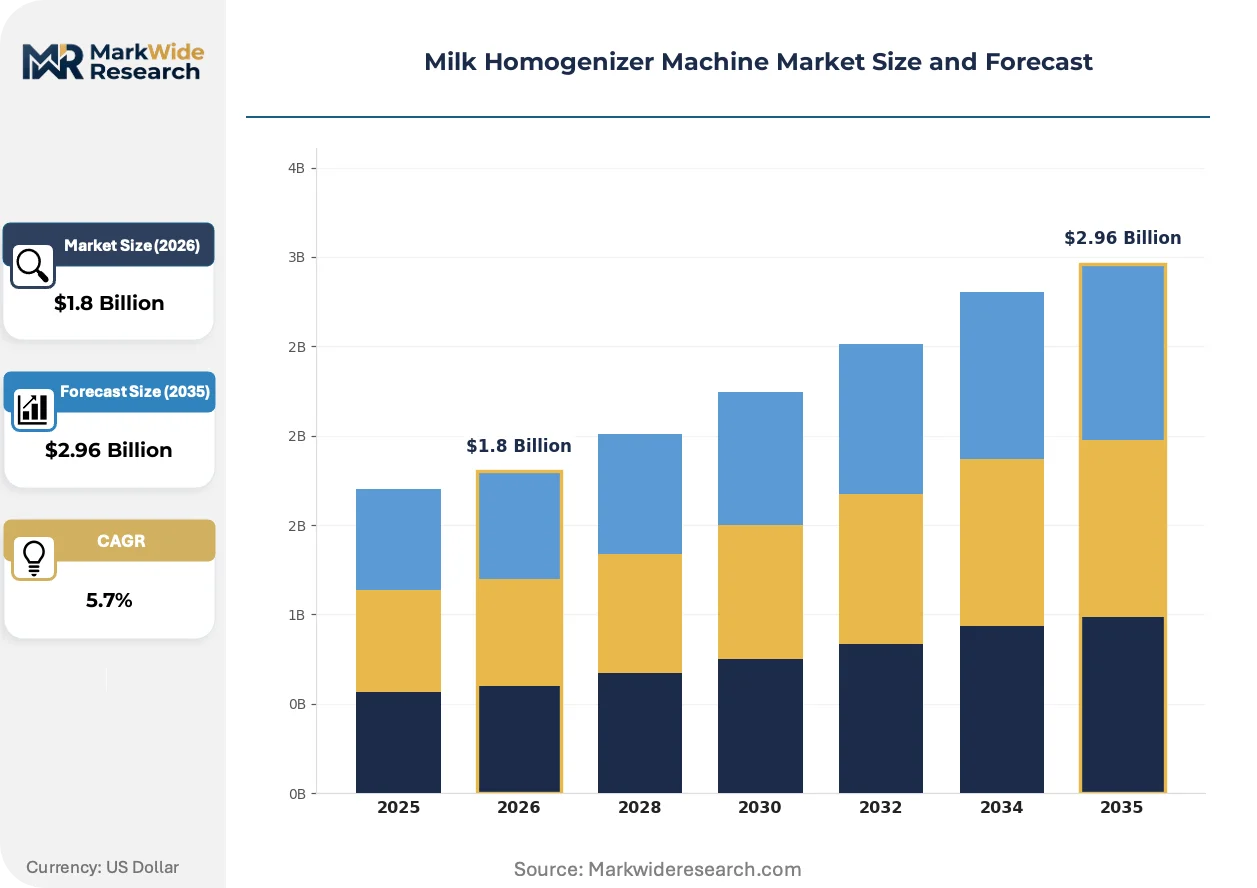
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Homogenizer, Batch Homogenizer, High-Pressure Homogenizer, Laboratory Homogenizer End User: Dairy Industries, Food Processing, Beverage Manufacturing, Research Institutions Technology: Mechanical Homogenization, Ultrasonic Homogenization, High-Pressure Homogenization, Colloid Mill Application: Milk Processing, Cream Separation, Ice Cream Production, Nutritional Drinks |
| Companies Covered | Alfa Laval, HST Maschinenbau GmbH, GEA Group, Shanghai Samro Homogenizer, Ekato Holding GmbH, Krones AG, Tetra Pak International, HOMMAK, SPX Flow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Homogenizer Machine Market Shifts & Advancements
Equipment architecture is splitting between massive continuous-flow units for commodity milk and compact configurable systems serving niche beverage categories.
Two-stage homogenization valve design is fragmenting the traditional single-stage installed base. Dairy cooperatives in India and Southeast Asia are specifying separate first-stage fat disruption and second-stage stabilization to achieve sub-micron particle distributions. This technical bifurcation is enabling regional fabricators to compete on localized valve reconditioning services rather than OEM replacement part premiums.
The EU MDR pressure-equipment directive is reshaping component sourcing documentation requirements. Welded seam traceability and material certification now accompany every pump housing and valve block exported to European dairy processors. German and Italian equipment buyers are demanding third-party notified body verification before installation acceptance, compressing procurement timelines but raising safety-critical quality thresholds.
After-sales service unbundling is disrupting traditional bundled maintenance contracts. Large dairy cooperatives in Gujarat and Maharashtra are negotiating separate valve reconditioning, seal replacement, and remote diagnostic agreements rather than comprehensive annual service packages. This purchasing pattern fragmentation favors regional service depots with localized spare parts inventory over distant OEM technical teams.
Milk Homogenizer Machine Market Segmentation
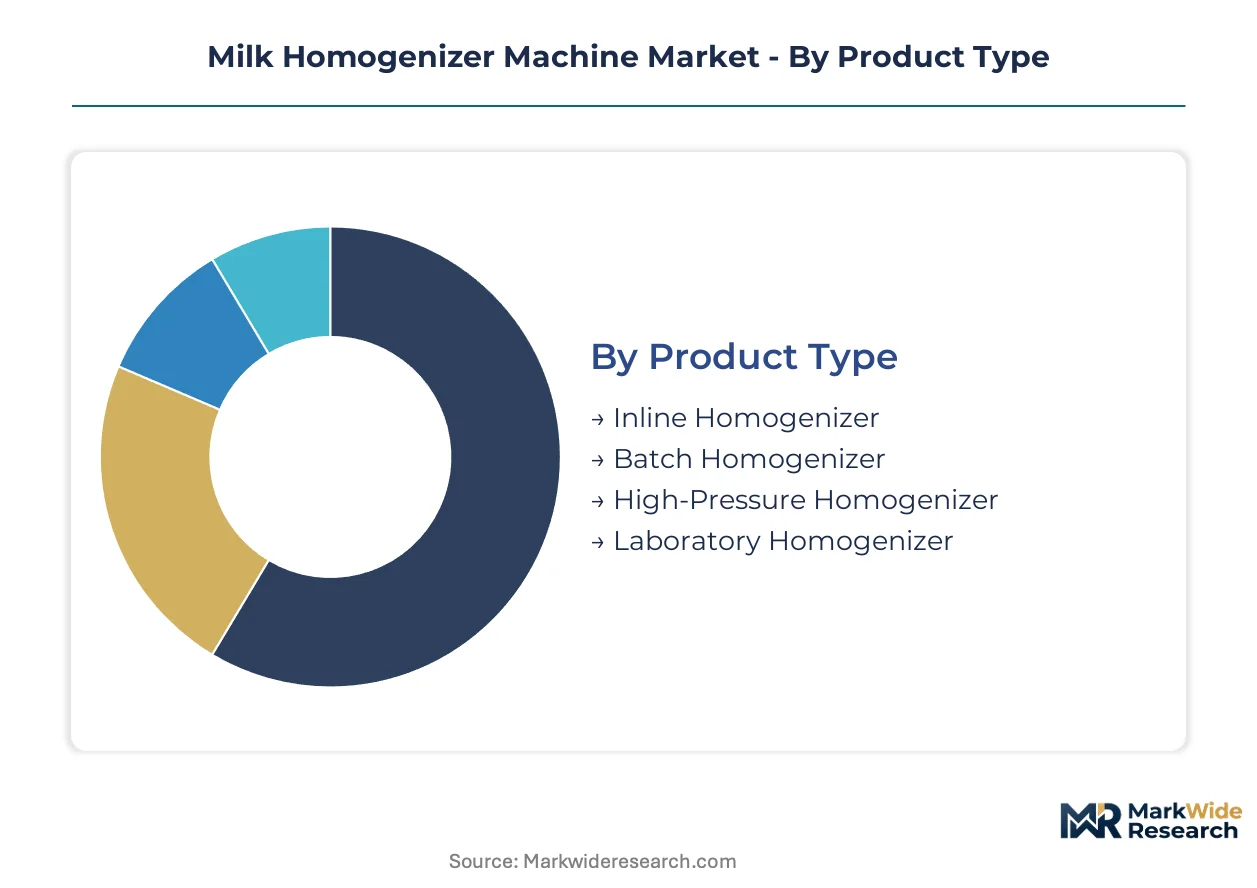
Homogenizer procurement patterns diverge sharply across equipment scale and operational intensity. Dairy cooperatives prioritize continuous-flow integration while beverage startups favor configurable batch systems for formulation flexibility.
Product Type:
Inline configurations dominate capital deployment through pasteurizer circuit bundling, while laboratory units concentrate in nutritional drink R&D channels.
- Inline Homogenizer:Continuous-flow architecture embeds directly into HTST pasteurizer circuits, eliminating intermediate holding tanks. Dairy cooperatives in Gujarat and Maharashtra specify these for standardized milk fat distribution under FSSAI mandates.
- High-Pressure Homogenizer:Operating pressures above 200 bar shatter fat globules for extended shelf-life formats. Southeast Asian UHT processors drive procurement as ambient distribution networks expand.
- Batch Homogenizer:Standalone vessels serve artisanal creameries and small-scale ice cream manufacturers with intermittent production schedules.
- Laboratory Homogenizer:Bench-scale units support particle-size iteration in university food science departments and corporate innovation labs.
By volume, Inline Homogenizer leads. By growth pace, High-Pressure Homogenizer is expanding most quickly.
End User:
Cost tiers separate commodity dairy operations from premium beverage formulation facilities with specialized particle-size requirements.
- Dairy Industries:Cooperative federations anchor equipment procurement for standardized milk packaging. FSSAI fat distribution regulations in India compel fleet upgrades from legacy mechanical units.
- Beverage Manufacturing:Plant-based milk analogues require oil-in-water emulsion stabilization without native dairy fat structures. Oat and almond protein processors in North America specify high-pressure valve configurations.
- Food Processing:Margarine and spread manufacturers utilize homogenization for texture modification in reduced-fat formulations.
- Research Institutions:Corporate R&D centers and university food science departments acquire laboratory-scale systems for iterative emulsion testing.
By installed base, Dairy Industries dominates. By expansion trajectory, Beverage Manufacturing is climbing the fastest.
Technology:
Application intensity dictates technology selection, with thermal-sensitive formulations driving ultrasonic adoption and commodity milk favoring mechanical reliability.
- High-Pressure Homogenization:Valve-orifice configurations at 100-250 bar achieve sub-micron fat globule diameters for shelf-stable emulsions. Extended shelf-life milk lines in Southeast Asia specify this technology exclusively.
- Mechanical Homogenization:Conventional rotor-stator systems serve budget-constrained cooperatives with shorter replacement cycles and lower spare parts costs.
- Ultrasonic Homogenization:Cavitation-based disruption preserves heat-sensitive bioactive compounds in fortified nutritional drinks.
- Colloid Mill:Shear-gap processing suits high-viscosity cream and spread applications with coarse initial particle distributions.
By revenue concentration, High-Pressure Homogenization leads. By technology transition velocity, Ultrasonic Homogenization is gaining share fastest.
Application:
Volume scale separates commodity fluid milk from value-added categories with specialized emulsion requirements and premium positioning.
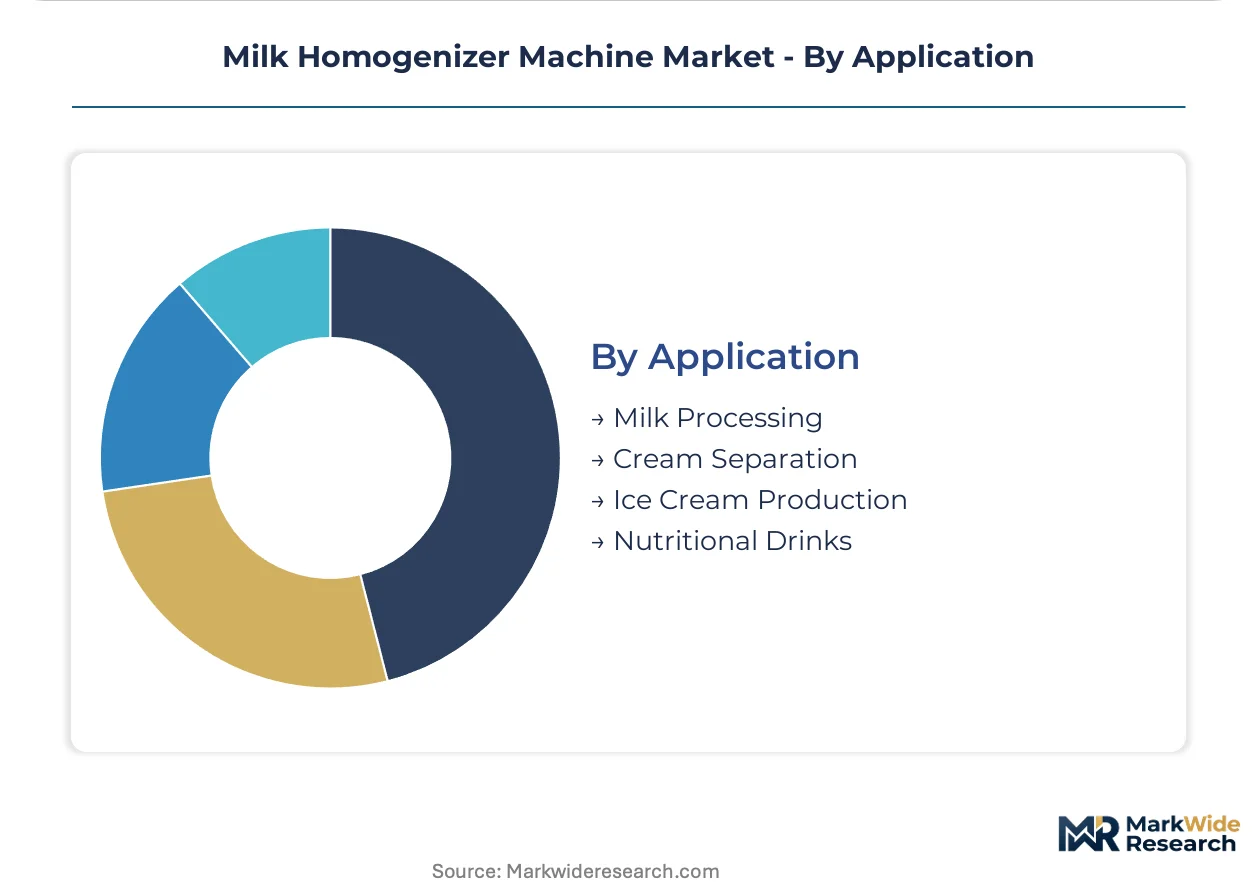
- Milk Processing:Standardized fluid milk production consumes the largest homogenizer installed base. FSSAI packaging mandates in India drive replacement of pre-2015 mechanical units.
- Ice Cream Production:Two-stage homogenization achieves fine fat dispersion for smooth mouthfeel in premium frozen dessert categories.
- Cream Separation:Pre-homogenization disrupts fat globule membranes to accelerate centrifugal separation efficiency in butter manufacturing.
- Nutritional Drinks:Protein-fortified and meal-replacement beverages require sub-micron particle distributions for shelf stability and sensory acceptance.
By unit shipments, Milk Processing leads. By value per installation, Nutritional Drinks commands the steepest premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The JNPT port complex near Mumbai anchors India's dairy equipment import corridor, handling stainless steel valve assemblies and pump housings from European and East Asian fabricators. This maritime infrastructure underwrites procurement timelines for cooperative dairies across the western seaboard.
India
FSSAI packaging mandates for standardized milk fat distribution compel cooperative dairies in Gujarat and Maharashtra to retire legacy mechanical units. BIS certification requirements for pressure-bearing components create compliance bottlenecks for domestic fabricators. The Anand milk district and Pune industrial corridor anchor capacity expansion for high-pressure homogenizer deployment.
China
Provincial dairy cooperatives in Shandong and Heilongjiang provinces scale procurement to meet GB standards for extended-shelf-life milk formats. SAMR enforcement of pressure-equipment safety codes tightens documentation requirements for welded-seam components. The Yangtze River Delta dairy cluster drives demand for inline continuous-flow configurations.
Germany
EU MDR pressure-equipment directives reshape component sourcing documentation for valve assemblies and pump housings exported across the 27-member bloc. CE marking harmonization reduces national certification fragmentation for equipment builders. The Bavarian dairy technology corridor concentrates fabrication capacity for turnkey processing lines.
United States
FDA pasteurized milk ordinance enforcement demands full material traceability for pressure-bearing components in commercial dairy operations. Wisconsin and California dairy cooperatives upgrade homogenizer fleets to comply with evolving thermal-processing regulations. The Upper Midwest dairy belt anchors replacement demand for high-pressure valve configurations.
Indonesia
UHT milk line expansion across Java and Sumatra requires homogenization pressures above 200 bar for ambient distribution network stability. The country's national food and drug regulator tightens packaging material compliance timelines for imported equipment. The Surabaya industrial corridor concentrates procurement for Southeast Asian dairy processors.
Milk Homogenizer Machine Market Competitive Landscape
Listed leaders compete with private specialists across certification access and aftermarket service density. The vendor base splits between turnkey dairy line integrators and component-focused fabricators with regional service footprints. Three archetypes dominate: European engineering conglomerates with captive valve supply chains, Asian equipment builders competing on localized reconditioning services, and North American flow-control specialists leveraging pump technology adjacencies. Consolidation pressure concentrates among mid-scale fabricators facing ISO 3-A validation queue delays, while geographic expansion and technology licensing emerge as primary competitive vectors.
Among European engineering conglomerates, GEA Group and Tetra Pak International exemplify the integrated-systems archetype, bundling homogenizer units with upstream pasteurization and downstream aseptic packaging to lock in beverage manufacturing customers. Shanghai Samro Homogenizer occupies a position within the Asia-Pacific regional specialist tier, competing on service density across provincial Chinese dairy cooperatives rather than OEM replacement part premiums. These three anchors illustrate the competitive tension between turnkey integration and localized aftermarket responsiveness.
| Leading Market Players |
|---|
| Alfa Laval |
| HST Maschinenbau GmbH |
| GEA Group |
| Shanghai Samro Homogenizer |
| Ekato Holding GmbH |
| Krones AG |
| Tetra Pak International |
| HOMMAK |
| SPX Flow |
| Others |
Supply & Pricing Matrix
ISO 3-A Sanitary Standards certification gates both supplier qualification and price tiering simultaneously, compressing fabricator margins for uncertified units while enabling 15-20% premiums for validated European and North American equipment. Dairy cooperatives in Gujarat and Maharashtra face elongated procurement timelines as third-party validation queues stretch capacity, forcing buyers to absorb expedited certification costs or accept longer lead times from qualified vendors.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with cooperative federations negotiating 12-18% reductions on fleet orders above five units while artisanal creameries pay standard list rates. Certification grade and after-sales service bundling drive price differentiation, as FSSAI-compliant high-pressure units command premiums over legacy mechanical configurations. Cost compression in the standard tier is intensifying because stainless steel price volatility squeezes fixed-price contract margins. Small-scale ice cream manufacturers exhibit the highest price sensitivity, whereas extended-shelf-life milk processors prioritize performance specifications over unit economics.
Supply Chain Analysis
Germany and Italy anchor precision machining of valve assemblies and pump housings, while India and China concentrate fabrication of stainless steel pressure vessels and welded-seam components. 316L-grade alloy sourcing draws from nickel market fluctuations in Indonesia and the Philippines, with valve seat ceramics resting on Japanese and German specialty suppliers. Single-source vulnerability concentrates in European third-party certification bodies, creating 12-18 month validation bottlenecks for Asian equipment builders. Distribution runs through regional service depots with localized spare parts inventory rather than direct OEM technical teams, particularly across provincial Chinese dairy cooperatives and Indian state-level federations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician skills for high-pressure seal replacement at 250 bar operating pressures represent a critical capability gap, constraining aftermarket service expansion and locking dairy maintenance teams into proprietary OEM dependencies.
For Market Incumbents: Secure captive valve reconditioning capabilities through backward integration into precision machining operations, insulating margin control from stainless steel price volatility. Anchor certification investment in ISO 3-A validation capacity to compress queue delays and capture cooperative dairy procurement windows in Gujarat and Maharashtra before regional fabricators qualify. For New Entrants and Emerging Players: Lead with localized service density across provincial Chinese dairy cooperatives and Indonesian UHT processors, where incumbent OEMs maintain distant technical teams. Target plant-based milk analogue processors in North America and Europe, as oat and almond protein beverage homogenization requirements lack established supplier relationships and specification lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-pressure homogenization sub-segments, as welded-seam documentation and material traceability requirements force quality system rebuilds for FDA and EU MDR compliance. Mid-scale fabricators facing ISO 3-A validation queue delays present consolidation targets with regional service footprint value. Monitor BIS certification timeline announcements in India as an inflection indicator for domestic equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Valve Machining | Captive supply of precision components insulates margin control from nickel alloy price swings. |
| ISO 3-A Certification Investment | Third-party validation capacity compresses procurement timelines for FSSAI-mandated fleet upgrades. |
| Regional Service Depot Expansion | Localized spare parts inventory displaces distant OEM technical teams in Chinese provincial markets. |
| Two-Stage Valve Design Development | Separate fat disruption and stabilization stages enable reconditioning service competition. |
| Plant-Based Beverage Application Targeting | Oat and almond protein processors require oil-in-water emulsion stabilization without dairy fat structures. |
Research Methodology
A standing panel of dairy processing plant engineers, cooperative federation procurement managers, aftermarket service technicians, and food safety compliance officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with equipment fabricators and dairy operators, validated against secondary sources including FSSAI regulatory filings, BIS certification databases, EU MDR notified body registries, and stainless steel trade flow customs data. Bottom-up unit shipment estimates from regional dairy clusters were triangulated against top-down value projections from equipment vendor revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions spanning product configuration, operating pressure tier, end-use industry, technology type, and geographic regulatory cluster. CAGRs were derived from installed base replacement cycles and capacity expansion announcements. Forecast inputs incorporated FSSAI packaging mandate enforcement timelines and EU MDR pressure-equipment directive harmonization progress.
The analysis sits within stated boundaries; outcomes outside sustained FSSAI enforcement intensity or nickel price stability assumptions would require recalibration. Forecasts reflect documented assumptions regarding certification queue durations, cooperative dairy capital expenditure cycles, and plant-based beverage processor scaling velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Milk Processing Systems Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market
Dairy Processing Machinery
Commercial Cheese Shredder Market