
 Dairy Filtration Systems Market | 2026-2036
Dairy Filtration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Filtration Systems Market Outlook
Pharmaceutical-grade membrane specifications is unwinding across the dairy filtration landscape. Alfa Laval AB leverages its integrated separation technology portfolio to dominate European retrofit installations. GEA Group AG anchors its position through sustained R&D intensity in ceramic membrane architectures. Pall Corporation specializes in hollow-fiber configurations that occupy the high-purity whey protein concentrate segment.
Dairy filtration systems encompass membrane-based and mechanical separation equipment engineered to remove particulates, bacteria, and dissolved solids from milk and derivative streams, typically operating at transmembrane pressures between 1 and 40 bar depending on pore classification. These systems serve the primary industrial purpose of extending shelf life, standardizing composition, and recovering valuable protein fractions for ingredient manufacturing. Ultrafiltration leads product type configurations by installed base, while reverse osmosis captures expanding margin pools in milk concentration and water recovery applications. Membrane separation technology sustains the majority of new capital expenditure, though cross-flow filtration is displacing conventional dead-end configurations in high-capacity cheese plants.
The US FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate minimum pathogen reduction performance, directly shaping membrane pore-size specifications and validation protocols for interstate commerce. The EPA's Clean Water Act provisions and EU F-Gas Regulation constrain refrigerant-based pre-cooling integration, pushing processors toward ambient-energy recovery designs in filtration skids. Stakeholders must weigh ceramic membrane longevity against polymeric capital costs when evaluating plant-wide filtration architecture decisions.
Market Dynamics
Membrane fouling mitigation technology is compressing operating expenditure differentials between ceramic and polymeric configurations, forcing incumbent equipment suppliers to reposition around lifecycle service contracts rather than upfront hardware margins.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in pre-cooling circuits is accelerating capital redeployment toward ambient-energy recovery filtration skids across Dutch and Danish cheese processing clusters.
- Whey protein isolate demand:Sports nutrition ingredient manufacturers are specifying 99% protein purity thresholds that only tight-pore ultrafiltration cascades can deliver, pulling membrane replacement cycles forward.
- Polysulfone membrane chemistry:Advances in hydrophilic surface modification are extending polymeric module lifespans beyond 18 months in high-lactose environments, narrowing the total-cost gap with ceramic alternatives.
Market Restraints
- Stainless steel feedstock volatility:Filtration skid fabrication depends on 316L grade alloy pricing, which fluctuates with nickel exchange benchmarks and compresses project margin visibility for equipment fabricators.
- German engineering concentration:Precision pump and valve subsystems for high-pressure reverse osmosis trains source predominantly from Mittelstand suppliers around Stuttgart, creating single-source vulnerability in turnkey project delivery.
- Clean-in-place water intensity:Membrane regeneration protocols consume 15-20 liters of heated permeate per square meter of surface area, exposing processors to escalating municipal water tariffs in drought-stressed regions.
Strategic Opportunities
- India organized dairy expansion:Cooperative federations in Gujarat and Maharashtra are consolidating village-level collection into centralized processing hubs, opening membrane standardization contracts for 50,000+ liter per day capacities.
- Precision fermentation feedstock:Cell-culture dairy protein startups require pharmaceutical-grade filtration infrastructure for growth media sterilization, extending membrane vendor addressable market beyond traditional processors.
- Carbon border adjustment mechanism:The EU CBAM transitional phase is incentivizing membrane-based water recovery to reduce dairy processing carbon intensity and preserve export competitiveness into European markets.
Industry Challenges
- Membrane integrity testing protocols:FDA Grade A Pasteurized Milk Ordinance requirements for bubble-point validation after every cleaning cycle consume 4-6 hours of productive capacity daily in large ultrafiltration plants.
- Legacy control system integration:1990s-era SCADA architectures in mature cheese facilities lack the data bandwidth to support real-time transmembrane pressure optimization algorithms in modern membrane skids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Filtration Systems Market |
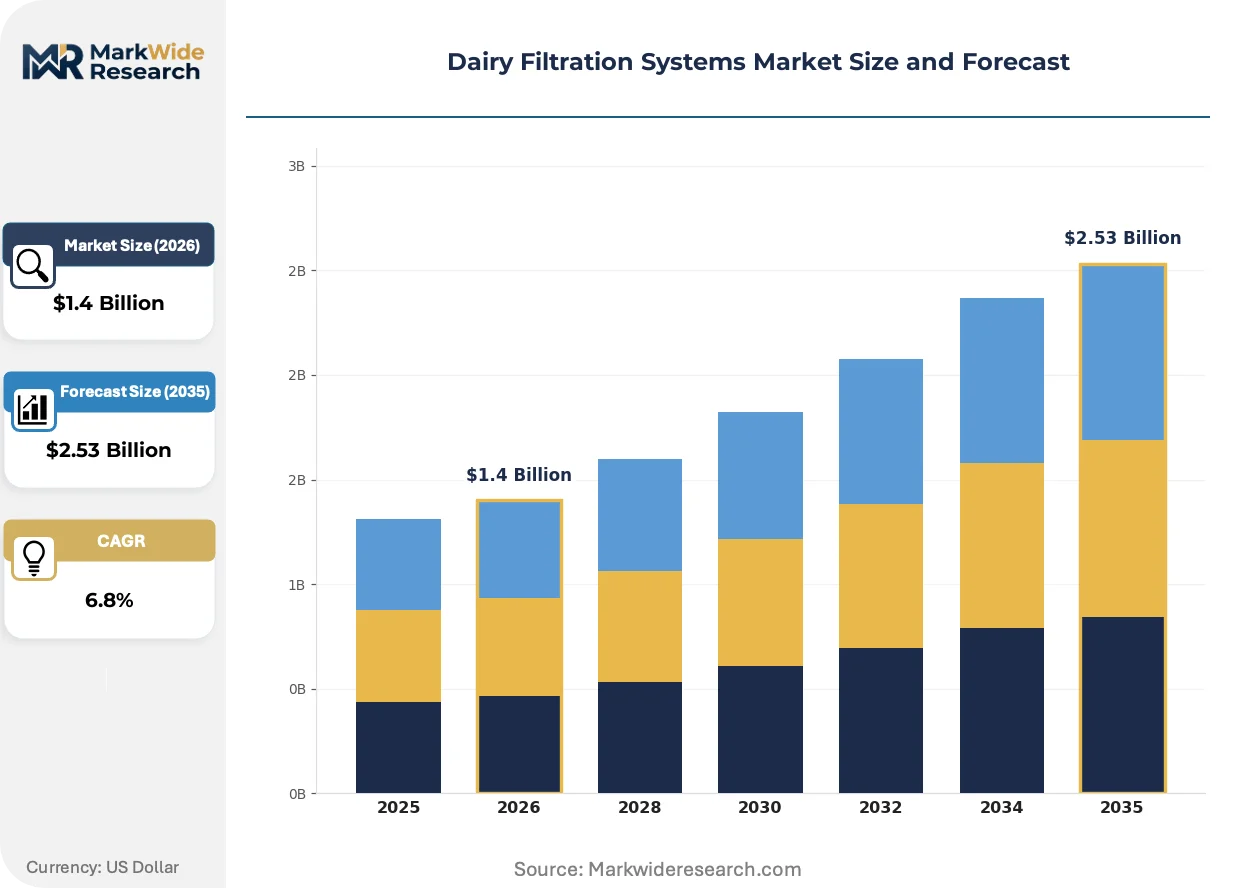
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis End User: Dairy Producers, Cheese Manufacturers, Yogurt Producers, Milk Processors Technology: Membrane Separation, Cross Flow Filtration, Centrifugal Filtration, Gravity Filtration Application: Pasteurization, Separation, Concentration, Clarification |
| Companies Covered | Alfa Laval AB, GEA Group AG, Pall Corporation, 3M Company, SPX Flow, Inc., Tetra Pak International S.A., Suez Water Technologies and Solutions, Veolia Water Technologies, Koch Membrane Systems Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Filtration Systems Market Strategic Shifts
Modular skid architecture and predictive maintenance analytics are converging to compress deployment timelines and shift supplier revenue models toward performance-guaranteed service agreements rather than capital equipment sales.
Multi-stage spiral-wound membrane arrays with automated back-pulse sequencing are miniaturizing footprint requirements for whey fractionation plants. Mid-sized cheese processors in Wisconsin and Bavaria are adopting these compact configurations to retrofit existing buildings without structural expansion. The technology is miniaturizing the minimum viable scale for protein recovery operations from 100,000 liters per day down to 25,000 liters.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating PTFE-coated membrane supports from European dairy equipment supply chains. Membrane manufacturers are accelerating validation of polyethersulfone and regenerated cellulose alternatives that meet migration limits for food contact materials. Ultrafiltration module suppliers serving French and Italian mozzarella producers are absorbing the bulk of reformulation costs and extended certification timelines.
Equipment-as-a-service contracting is displacing traditional capital purchase arrangements for membrane replacement programs. Dairy cooperatives in the Netherlands and Ireland are signing five-year agreements bundling membrane modules, cleaning chemicals, and technical support into per-liter processing fees. This model concentrates with large multi-site operators seeking to offload balance-sheet intensity and technical staffing requirements.
Dairy Filtration Systems Market Segmentation
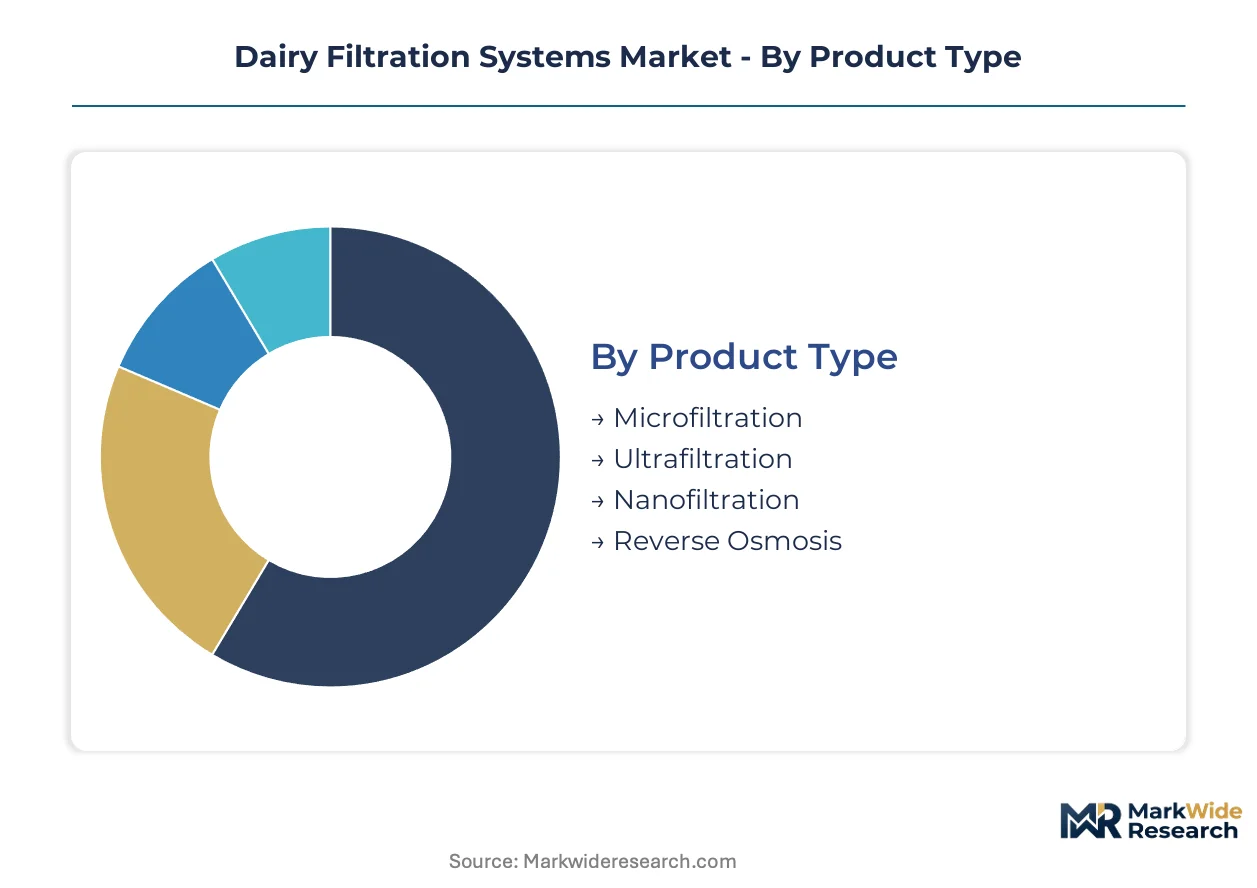
Dairy filtration procurement channels diverge sharply by operational scale and product sophistication. Large cooperatives favor turnkey membrane systems through direct OEM relationships, while mid-sized processors source modular skids via regional distributors with bundled service contracts.
Product Type:
Channel mix varies by pore classification: ultrafiltration and reverse osmosis move predominantly through direct sales with engineering support, while microfiltration and nanofiltration see stronger distributor penetration in smaller dairy operations.
- Ultrafiltration:These systems operate at 1-10 bar transmembrane pressure with molecular weight cutoffs of 10-500 kDa, enabling protein fractionation and lactose concentration. Demand clusters in German and Dutch cheese processing clusters where whey protein isolate specifications drive tight-pore cascade configurations. The EU F-Gas Regulation is accelerating replacement of refrigerant-dependent pre-cooling with ambient-energy ultrafiltration skids.
- Reverse Osmosis:High-pressure trains at 20-40 bar achieve dissolved solids rejection above 99%, supporting milk concentration and water recovery applications. Wisconsin and Bavarian processors are retrofitting compact spiral-wound arrays to reduce hauling costs and municipal discharge volumes. Polysulfone membrane chemistry advances are extending module lifespans beyond 18 months in high-lactose environments.
- Microfiltration:0.1-10 micron pore structures remove bacteria and spores without thermal degradation, serving extended-shelf-life milk production. French and Italian mozzarella producers dominate procurement following REACH restrictions on PTFE-coated supports.
- Nanofiltration:Divalent ion-selective separation at 5-20 bar enables partial demineralization for whey permeate processing. Gujarat and Maharashtra cooperative federations are specifying standardized nanofiltration modules for consolidated village-level hubs.
Ultrafiltration dominates installed base. Reverse osmosis is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive membrane investments: cheese manufacturers and large milk processors deploy ceramic systems with 10-year depreciation horizons, while yogurt producers and smaller dairy operations favor polymeric configurations with lower entry thresholds.
- Cheese Manufacturers:Whey fractionation requirements pull the tightest membrane specifications and most frequent replacement cycles. Dutch and Danish clusters are expanding membrane-based whey processing capacity under EU F-Gas compliance timelines.
- Milk Processors:Standardization and shelf-life extension drive reverse osmosis concentration and microfiltration bacteria reduction. US FDA Grade A Pasteurized Milk Ordinance dictates minimum pathogen reduction performance and bubble-point validation protocols.
- Yogurt Producers:Protein standardization and viscosity control require mid-range ultrafiltration without the purity thresholds of isolate production. Equipment-as-a-service contracting is gaining traction among multi-site operators seeking to offload technical staffing.
- Dairy Producers:Farm-scale and cooperative processing integrates filtration into integrated ingredient recovery flows. Indian organized dairy expansion is opening membrane standardization contracts for 50,000+ liter per day capacities.
Cheese manufacturers absorb the highest membrane replacement intensity. Milk processors represent the broadest installed base.
Technology:
Application environment determines technology selection: high-viscosity whey streams favor cross-flow configurations to mitigate fouling, while clarified milk and permeate processing can deploy simpler membrane or centrifugal separation.
- Membrane Separation:Polymeric and ceramic pore-based systems sustain the majority of new capital expenditure across protein recovery and concentration applications. Advances in hydrophilic surface modification are narrowing total-cost gaps with ceramic alternatives.
- Cross Flow Filtration:Tangential flow patterns sweep particulates from membrane surfaces, enabling sustained flux in high-solids cheese whey. This configuration is displacing dead-end systems in high-capacity plants.
- Centrifugal Filtration:Rotational force separation serves fat standardization and initial clarification upstream of membrane trains. German engineering concentration around Stuttgart creates single-source vulnerability for precision pump and valve subsystems.
- Gravity Filtration:Low-pressure pre-filtration removes coarse particulates before downstream membrane protection. Limited to small-scale operations and emergency bypass configurations.
Membrane separation commands capital deployment. Cross flow filtration is gaining share fastest in retrofit installations.
Application:
Volume throughput requirements segment procurement: pasteurization-adjacent filtration demands sanitary validation and FDA compliance documentation, while clarification and concentration applications prioritize flux rates and energy recovery.
- Concentration:Reverse osmosis and ultrafiltration reduce water content for transport efficiency and ingredient density. Carbon border adjustment mechanism incentives are driving membrane-based water recovery to preserve EU export competitiveness.
- Separation:Protein, fat, and lactose fractionation underpins ingredient manufacturing for sports nutrition and infant formula. Precision fermentation feedstock requirements are extending membrane vendor addressable markets.
- Clarification:Removal of suspended solids and casein fines precedes downstream processing or direct packaging. Modular skid architectures are compressing deployment timelines for mid-sized retrofit projects.
- Pasteurization:Microfiltration delivers non-thermal pathogen reduction with extended shelf-life outcomes. FDA validation protocols consume 4-6 hours of productive capacity daily in large ultrafiltration plants.
Concentration applications lead capital allocation. Separation is where technology differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German buyers prioritize ceramic membrane longevity over upfront capital, while Indian cooperatives optimize for polymeric entry costs. US processors balance FDA compliance burdens against whey protein isolate premiums.
United States
Wisconsin cheese plants drive spiral-wound reverse osmosis retrofit demand for milk concentration and water recovery. The FDA Grade A Pasteurized Milk Ordinance mandates bubble-point validation protocols that consume 4-6 hours of daily productive capacity. Madison-area processors are adopting compact modular configurations to avoid structural expansion costs.
Germany
Dairy cooperatives are modernizing centralized filtration infrastructure with 10-year depreciation horizons for ceramic systems. The EU F-Gas Regulation is accelerating replacement of refrigerant-dependent pre-cooling with ambient-energy recovery skids. Stuttgart-centered Mittelstand suppliers dominate precision pump and valve subsystems for high-pressure trains.
India
Organized dairy expansion in Gujarat and Maharashtra is consolidating village-level collection into 50,000+ liter per day centralized hubs. The FSSAI and cooperative federation procurement standards are driving membrane module standardization contracts. Anand-based cooperatives are specifying nanofiltration for partial demineralization of whey permeate streams.
Netherlands
Dutch cheese processing clusters are expanding membrane-based whey capacity under EU F-Gas compliance timelines. The country's national dairy regulator enforces strict migration limits for food contact materials post-REACH. Wageningen-area research partnerships are validating polyethersulfone alternatives to PTFE-coated membrane supports.
France
Mozzarella producers in the mozzarella belt dominate microfiltration procurement for extended-shelf-life milk. ANSM food contact material regulations are absorbing reformulation costs and extended certification timelines for ultrafiltration module suppliers. Lyon-based equipment distributors are bundling membrane modules into five-year equipment-as-a-service contracts.
Dairy Filtration Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the dairy filtration landscape. The vendor base organizes into three tiers: integrated separation technology houses, specialized membrane manufacturers, and regional skid fabricators. Strategic positioning concentrates on lifecycle service contracts displacing upfront hardware margins, and ceramic-versus-polymeric total-cost optimization.
Within the integrated technology tier, Alfa Laval AB and GEA Group AG exemplify the separation-technology-house archetype with broad filtration portfolios. Pall Corporation occupies a specialist position in high-purity membrane configurations. Tetra Pak International S.A. represents the packaging-to-processing vertical integration model. Koch Membrane Systems Inc anchors the US-based membrane specialization segment.
| Leading Market Players |
|---|
| Alfa Laval AB |
| GEA Group AG |
| Pall Corporation |
| 3M Company |
| SPX Flow, Inc. |
| Tetra Pak International S.A. |
| Suez Water Technologies and Solutions |
| Veolia Water Technologies |
| Koch Membrane Systems Inc |
| Others |
Value Chain & Pricing Dynamics
Polysulfone membrane chemistry replacing ceramic architectures in mid-capacity plants is redrawing procurement geography toward German and Dutch polymer compounders while compressing lifecycle service pricing premiums.
Pricing Analysis
After-sales service contracts and membrane replacement programs now generate the majority of lifetime vendor value. Equipment-as-a-service bundling dominates Dutch and Irish cooperative procurement, converting capital expenditure into per-liter processing fees. Price differentiation hinges on ceramic longevity guarantees versus polymeric entry thresholds, with stainless steel feedstock volatility pressuring skid fabrication margins. Small yogurt producers exhibit acute price sensitivity, while German cheese cooperatives prioritize total-cost optimization over upfront hardware.
Supply Chain Analysis
Inventory lead times for precision pump and valve subsystems stretch 16-20 weeks due to Stuttgart-centered Mittelstand concentration. Ceramic membrane fabrication draws from German and Japanese sintering facilities, while polysulfone polymer production rests on US and Benelux petrochemical feedstocks. Single-source vulnerability in high-pressure reverse osmosis trains constitutes the primary structural risk. Distribution runs through direct OEM relationships for large cooperatives and regional distributors for mid-sized processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dairy filtration sector is undergoing high-growth disruption as EU F-Gas Regulation timelines force refrigerant-dependent pre-cooling replacement with ambient-energy recovery systems.
For Market Incumbents: Shield installed base revenue by locking Dutch and Danish cheese clusters into ten-year lifecycle service contracts before polysulfone alternatives erode ceramic replacement cycles. Deepen backward integration into membrane polymer compounding to offset stainless steel feedstock volatility squeezing skid fabrication margins.
For New Entrants and Emerging Players: FDA Grade A Pasteurized Milk Ordinance certification fast-tracks unlock Wisconsin and Bavarian retrofit demand for compact spiral-wound configurations. Target Indian cooperative federations in Gujarat and Maharashtra where membrane standardization contracts for 50,000+ liter hubs remain underpenetrated. Lead with equipment-as-a-service pricing to bypass capital-constrained buyer resistance.
For Investors and Strategic Acquirers: Capital is best deployed toward membrane chemistry specialists with validated polyethersulfone alternatives to PTFE-coated supports. Long-term viability centers on vendors capturing precision fermentation feedstock demand from cell-culture dairy protein startups. Watch for REACH restriction enforcement tightening as the signal indicating ceramic-to-polymer substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Chemistry Pivot | Polyethersulfone validation absorbs REACH compliance costs for French mozzarella producers. |
| Equipment-as-a-Service Expansion | Per-liter contracting converts Dutch cooperative balance sheets from capital intensity. |
| Compact Skid Retrofit Deployment | Spiral-wound miniaturization unlocks Wisconsin building-constrained cheese plants. |
| Precision Fermentation Feedstock Entry | Pharmaceutical-grade filtration extends vendor addressable market beyond traditional processors. |
| Ambient-Energy Recovery Integration | EU F-Gas Regulation compliance accelerates refrigerant-free pre-cooling replacement cycles. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC equipment manufacturer filings, EU regulatory databases, and dairy cooperative procurement records. Interviews with membrane skid engineering directors, plant managers at cheese processing facilities, aftermarket service heads, and FSSAI compliance officers informed demand-side validation. Top-down trade flow analysis and bottom-up installation database triangulation anchored market sizing.
Segmentation dimensions modeled span membrane pore classification, end-user operational scale, ceramic versus polymeric technology selection, and application purpose across the projection horizon. CAGRs derive from curve-fitting historical capital expenditure patterns against regulatory deadline impacts. Forecast inputs incorporate EU F-Gas phasedown timelines and Indian cooperative consolidation trajectories.
Underlying assumptions cover stainless steel price stability, REACH enforcement consistency, and cooperative procurement standardization adoption, with deviation risk concentrated in membrane polymer migration limit revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Milk Homogenizer Machine Market
Dairy Processing Machinery
Soft Serve Ice Cream Machines Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Milk Powder Analyzing Device Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Concentrated Whey Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Dairy Processing Equipment Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Whey Protein Microparticulation Systems Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market
Dairy Processing Machinery
Global Milk Tank Cooling System Market