
 Modified Milk Ingredients Market | 2026-2036
Modified Milk Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Milk Ingredients Market Foresight
Plant-based fat replacers is recalibrating cost structures across modified milk ingredient portfolios. Fonterra Co-operative Group leverages its New Zealand grass-fed milk pool to sustain premium protein concentrate output. Lactalis International anchors European supply through backward integration into whey processing. Danone SA differentiates via specialized fractionation technology for infant-grade proteins.
Modified milk ingredients encompass dairy-derived components—proteins, fats, lactose, and minerals—that undergo physical, chemical, or enzymatic alteration to achieve specified functional properties such as protein content ranging from 34% to 85% in milk protein concentrates. These ingredients serve as cost-effective substitutes for whole milk solids in formulated foods, enabling standardized nutrition profiles and extended shelf stability. Milk protein concentrate occupies the dominant margin pool due to its versatility across infant formula and sports nutrition applications, while whey protein concentrate represents the fastest-growing segment as functional food brands seek rapid-absorption protein sources. Powder form leads volume shipments given superior storage economics, though liquid concentrates gain traction in food service channels requiring batch-scale reconstitution.
The FDA enforces identity standards for dairy ingredients under the Federal Food, Drug, and Cosmetic Act, directly influencing label claims and cross-border formulation equivalence. EFSA's novel food assessments and China's NMPA dairy registration requirements create layered compliance obligations for exporters targeting multiple jurisdictions. Stakeholders must monitor evolving protein content thresholds and country-of-origin documentation rules that determine market access eligibility.
Market Dynamics
Protein fractionation technology is compressing ingredient differentiation timelines across the Modified Milk Ingredients Market, forcing processors to recalibrate capital allocation toward enzymatic separation capabilities or risk margin erosion in infant formula and sports nutrition supply contracts.
Growth Catalysts
- Sports nutrition formulation:Functional food brands in North America and Western Europe specify rapid-absorption whey protein isolates for ready-to-drink applications, pulling volume through specialized drying infrastructure.
- EFSA novel food assessments:Streamlined approval pathways for enzymatically modified dairy proteins accelerate European market entry for fractionated ingredient portfolios targeting medical nutrition.
- China dairy processor expansion:Domestic ingredient sourcing mandates from the NMPA drive backward integration into milk protein concentrate production, reducing import dependency for infant formula manufacturers.
Market Restraints
- Skim milk powder price volatility:Global dairy commodity auction fluctuations transmit directly to modified ingredient cost structures, compressing processor margins during supply gluts.
- New Zealand supply concentration:Grass-fed milk pool dominance creates single-origin risk for premium protein concentrate buyers seeking consistent fatty acid profiles.
- Plant-based fat replacer substitution:Oat and coconut lipid systems displace dairy-derived fat fractions in bakery and confectionery applications where mouthfeel requirements have relaxed.
Strategic Opportunities
- Southeast Asia medical nutrition:Aging demographics in Thailand and Vietnam drive demand for specialized protein hydrolysates in clinical feeding applications where local production remains limited.
- Precision fermentation convergence:Microbial dairy protein synthesis is converging with traditional fractionation, creating hybrid ingredient categories that bypass agricultural input constraints.
- Direct-to-manufacturer e-procurement:Bulk ingredient platforms eliminate distributor markups for mid-sized food manufacturers seeking certified organic milk protein concentrates.
Industry Challenges
- Fractionation specialist scarcity:Enzymatic protein separation expertise concentrates in European and New Zealand technical institutes, constraining processor expansion in emerging production regions.
- Dual jurisdiction certification timelines:Simultaneous FDA identity standard compliance and NMPA dairy registration requirements extend product launch cycles by 18-24 months for exporters.
- Legacy spray dryer retrofit costs:Existing powder production assets require substantial capital modification to achieve the narrow particle size distributions demanded by instantized protein specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Milk Ingredients Market |
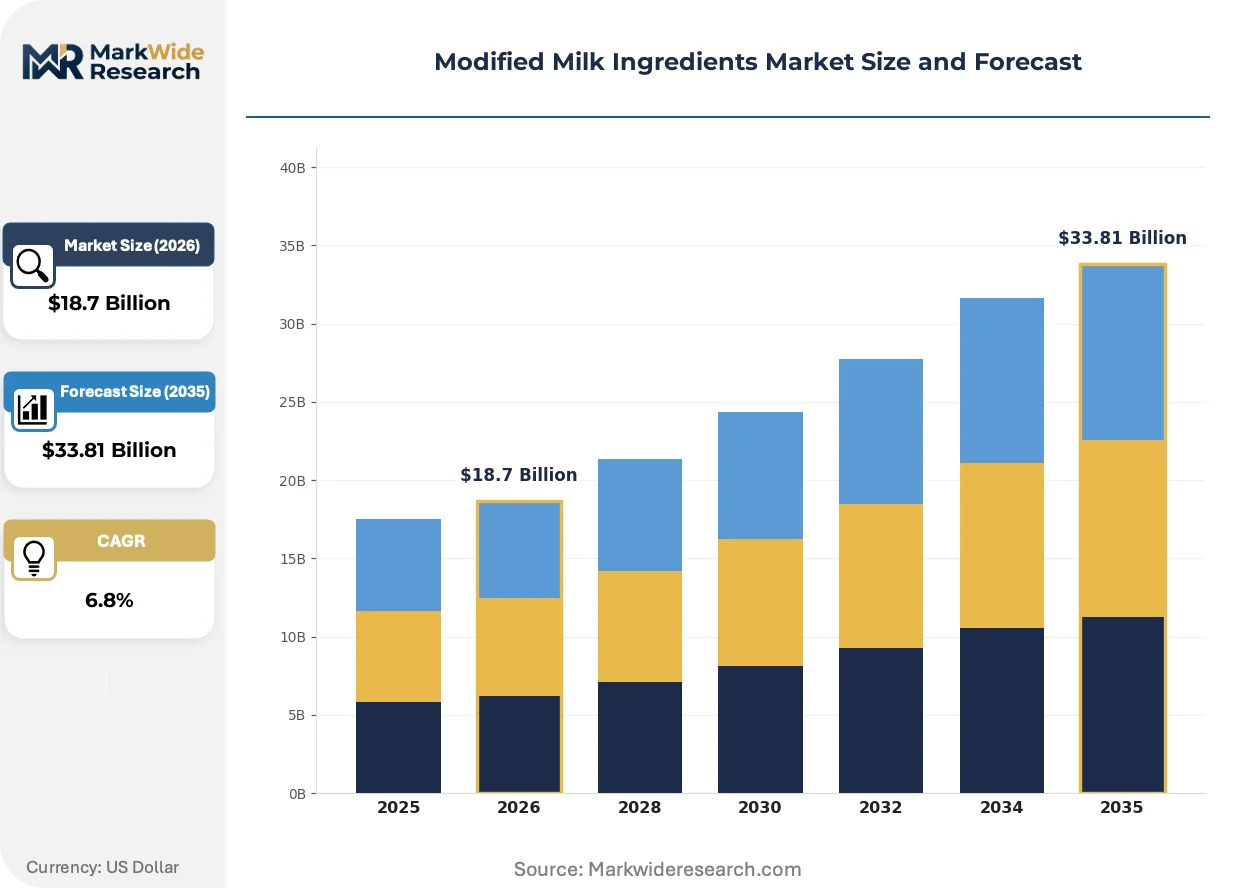
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactose-Free Milk, Milk Protein Concentrate, Milk Powder, Whey Protein Concentrate End User: Dairy Manufacturers, Nutraceutical Companies, Food Service, Retail Application: Infant Formula, Functional Foods, Sports Nutrition, Bakery Products Form: Liquid, Powder, Concentrate, Cream |
| Companies Covered | Nestle SA, Lactalis International, Danone SA, Fonterra Co-operative Group, FrieslandCampina, Arla Foods, Yili Group, China Mengniu Dairy, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Milk Ingredients Market Shifts & Advancements
Membrane filtration advances and enzymatic processing methods are restructuring how dairy solids achieve functional specificity, with protein fractionation now enabling precision targeting of amino acid profiles previously unattainable through conventional separation.
Cross-flow microfiltration combined with selective enzymatic hydrolysis is converging with chromatographic purification to produce protein isolates exceeding 90% purity with retained bioactivity. Sports nutrition contract manufacturers in the United States and Germany adopt these integrated systems within 24-month equipment refresh cycles. The technology is compressing minimum efficient scale thresholds, allowing regional processors to compete with commodity dairy cooperatives on specialized ingredient specifications.
China's GB standards for dairy ingredient labeling now mandate quantitative protein content declarations and origin traceability documentation for all imported modified milk ingredients. This regulatory tightening forces exporters to reconfigure quality management systems around batch-level analytical verification. Infant formula manufacturers targeting Chinese registration certificates face extended technical dossier preparation timelines as SAMR inspectors scrutinize fractionation process validation data.
Ingredient specification contracts now embed outcome-based performance clauses linking protein functionality to finished product shelf stability rather than accepting standard compositional certificates. North American bakery and confectionery manufacturers drive this shift, penalizing suppliers for batch-to-batch viscosity variation in reconstituted milk protein concentrates. The procurement model is most visible in clean-label dessert applications where texture consistency determines brand shelf placement negotiations with retail distributors.
Modified Milk Ingredients Market Segmentation
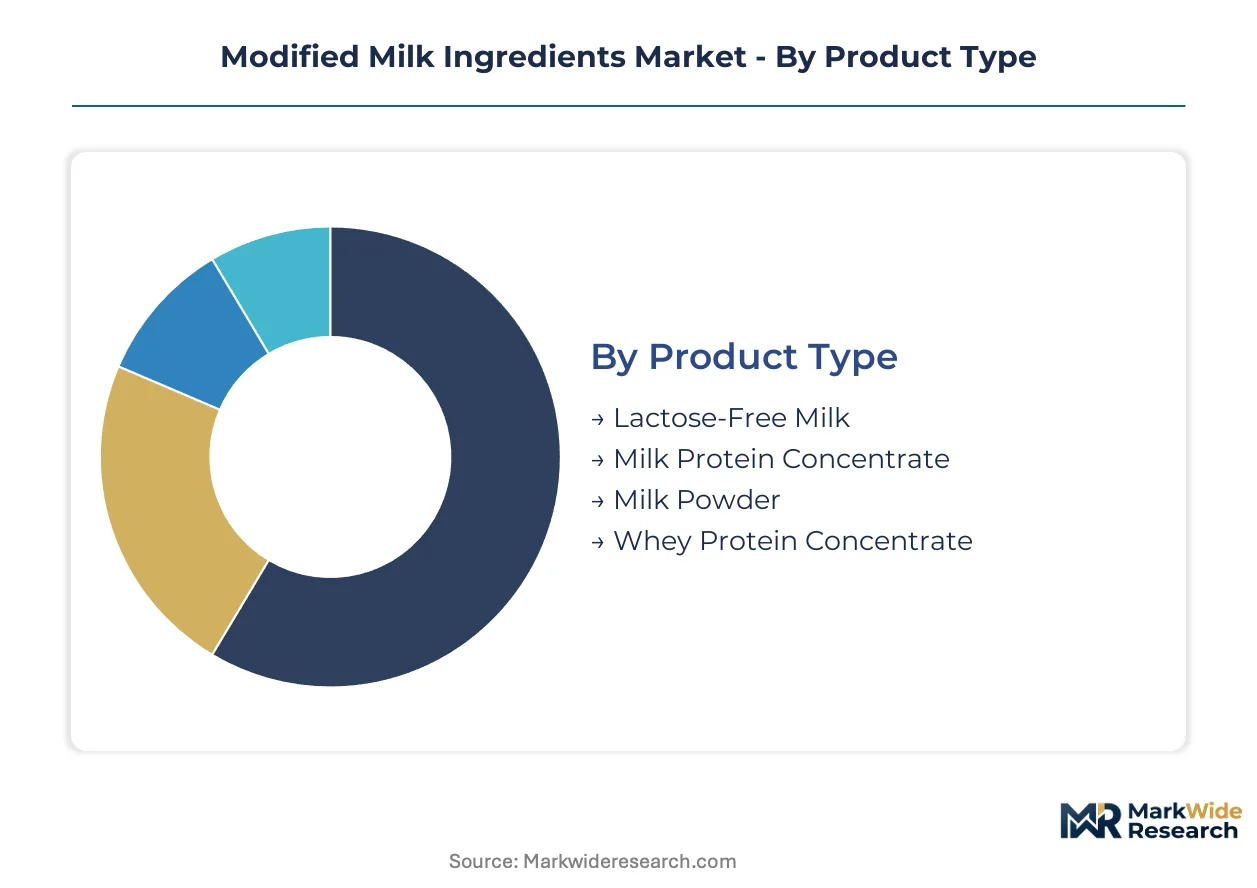
Modified milk ingredients fragment across technical specifications, regulatory thresholds, and end-use performance requirements that determine procurement premiums. Each segmentation axis reveals distinct margin structures and capacity allocation patterns among dairy processors.
Product Type:
Customization intensity varies from commodity-grade milk powders to precision-fractionated protein isolates with certified amino acid profiles.
- Milk Protein Concentrate:Protein content ranges from 34% to 85% depending on ultrafiltration membrane selection and diafiltration stages. Infant formula manufacturers in China specify MPC70 and MPC85 grades for amino acid standardization, with NMPA registration requiring batch-level protein verification. Premium sports nutrition brands in the United States source MPC80 for ready-to-mix applications where solubility and flavor masking compete directly with whey alternatives.
- Whey Protein Concentrate:Rapid-absorption kinetics drive demand from functional food brands seeking 34-80% protein fractions with retained immunoglobulin activity. German contract manufacturers specify WPC80 for clinical nutrition applications where EFSA novel food assessments govern bioactive peptide claims.
- Lactose-Free Milk:Enzymatic lactose hydrolysis produces glucose-galactose syrups for dairy-intolerant consumer segments. Bakery applications in France specify low-lactose milk solids for clean-label positioning.
- Milk Powder:Standardized whole and skim milk powders serve as cost-effective solids replacers in confectionery and UHT beverage formulations. Southeast Asian dairy processors source commodity-grade powders for recombined milk production.
Most installed capacity flows through Milk Protein Concentrate. Expansion is steepest in Whey Protein Concentrate.
End User:
Procurement sophistication separates specification-driven manufacturers from price-sensitive volume buyers.
- Nutraceutical Companies:Clinical-grade protein hydrolysates with documented bioavailability drive premium contracting. Japanese medical nutrition brands specify enzymatically modified casein fractions for enteral feeding applications regulated by PMDA pharmaceutical standards.
- Dairy Manufacturers:Recombined milk and cheese production consumes standardized milk powders and fat-filled derivatives. Brazilian cooperatives source modified ingredients to bypass seasonal raw milk supply fluctuations.
- Food Service:Batch-scale reconstitution requirements favor liquid concentrates and instantized powders with narrow particle size distributions. Hotel chains in the UAE specify UHT-stable modified creams for dessert manufacturing.
- Retail:Private-label sports nutrition and infant formula brands compete on protein content claims and origin traceability. Australian supermarket chains require Fonterra-certified grass-fed protein sourcing for premium positioning.
Contract values concentrate with Nutraceutical Companies. Volume throughput peaks with Dairy Manufacturers.
Application:
Regulatory stringency escalates from commodity bakery applications to pharmaceutical-grade infant nutrition.
- Infant Formula:Protein content, mineral balance, and amino acid profiles must meet codex alimentarius standards with country-specific adaptations. SAMR inspectors in China scrutinize fractionation process validation for registration certificate approval, extending technical dossier timelines.
- Sports Nutrition:Rapid absorption and clean-label positioning drive whey isolate and hydrolysate specifications. North American brands specify leucine-enriched fractions for muscle protein synthesis claims.
- Functional Foods:Protein fortification of beverages and bars requires solubility stability across pH and temperature ranges. South Korean manufacturers integrate milk protein concentrates into meal-replacement products regulated by MFDS health functional food standards.
- Bakery Products:Maillard reaction control and water binding determine milk powder selection for crust color and shelf life. Italian artisan bakeries specify low-heat milk powders for flavor preservation.
Quality certification costs burden Infant Formula most heavily. Reformulation activity runs highest in Sports Nutrition.
Form:
Storage economics and reconstitution speed trade off across physical states.
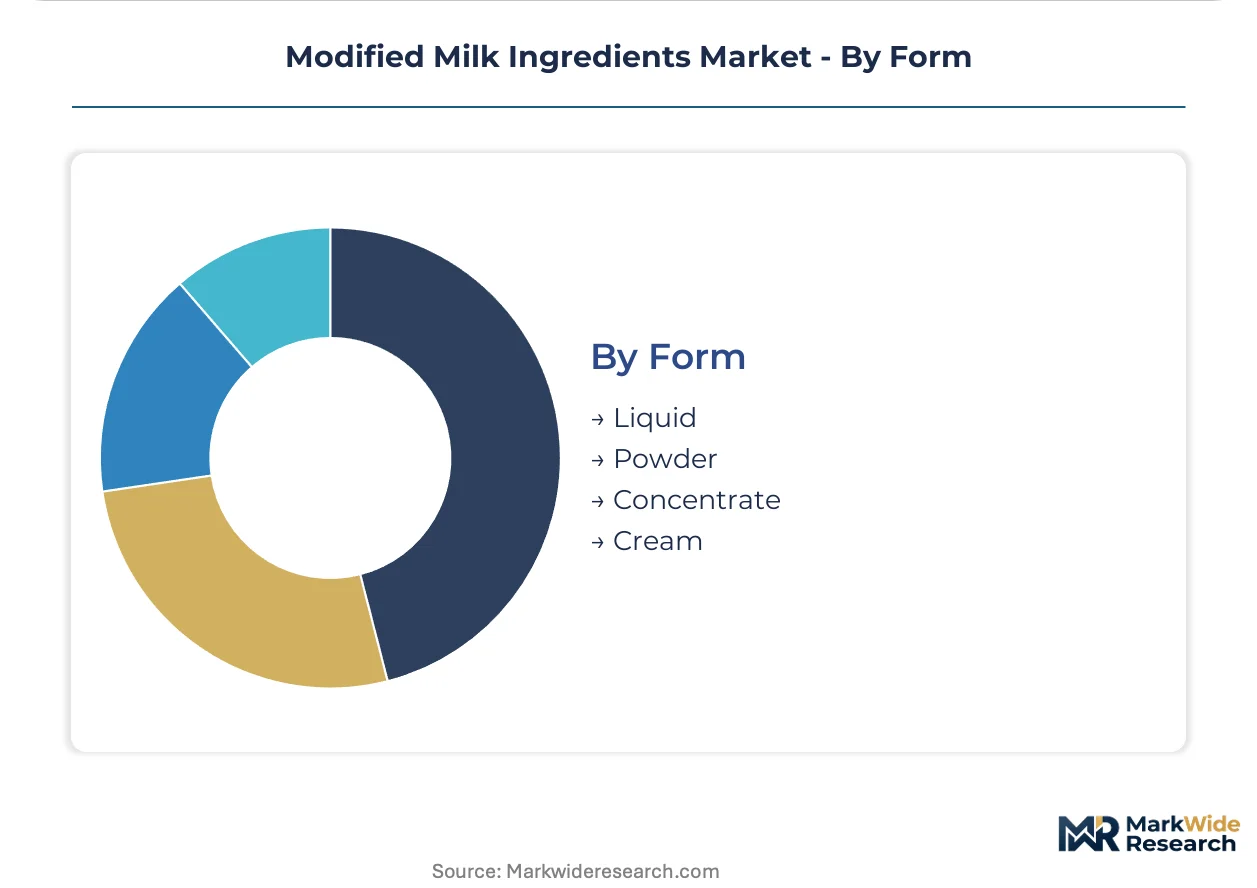
- Powder:Superior shelf stability and transport density dominate ingredient shipments. Spray-dried milk protein concentrates achieve 12-24 month stability with controlled water activity below 0.3.
- Liquid:Food service channels and beverage manufacturers favor UHT-treated concentrates for immediate processing integration. German dairy processors specify liquid MPC for fresh cheese production.
- Concentrate:Intermediate water content reduces transport costs versus liquid while enabling custom reconstitution. Southeast Asian recombined milk plants source 35-45% solids concentrates.
- Cream:Fat-standardized dairy creams serve confectionery and dessert applications requiring specific viscosity and whipping properties. French patisserie suppliers specify 35% fat modified creams with extended ambient stability.
Inventory carrying costs favor Powder. Handling efficiency improvements target Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's grass-fed dairy belt anchors the modified milk ingredient supply base. Fonterra Co-operative Group's processing infrastructure concentrates in the Waikato region. Chinese infant formula manufacturers source premium protein concentrates from this single-origin milk pool.
United States
Sports nutrition brands in California and Texas specify rapid-absorption whey protein isolates for ready-to-drink applications. FDA identity standards under the Federal Food, Drug, and Cosmetic Act govern label claims and cross-border formulation equivalence. Wisconsin dairy processors operate specialized drying infrastructure serving North American contract manufacturers.
China
Domestic dairy processors expand milk protein concentrate production to reduce import dependency for infant formula manufacturing. NMPA dairy registration requirements mandate quantitative protein content declarations and origin traceability documentation. Inner Mongolia and Heilongjiang provinces host backward-integrated fractionation facilities supplying SAMR-registered brands.
Germany
Clinical nutrition manufacturers specify enzymatically modified casein fractions for enteral feeding applications. EFSA novel food assessments streamline approval pathways for fractionated ingredient portfolios targeting medical nutrition. Bavarian dairy cooperatives operate chromatographic purification systems for protein isolates exceeding 90% purity.
Australia
Retail chains require grass-fed protein sourcing certifications for premium private-label positioning. FSANZ standards govern protein content thresholds and country-of-origin documentation rules. Victorian spray-drying facilities serve Southeast Asian recombined milk plants with standardized milk powders.
Netherlands
Food service channels in Amsterdam and Rotterdam favor UHT-stable liquid concentrates for batch-scale reconstitution. EU Green Deal agricultural policies influence sustainable sourcing requirements for dairy-derived ingredients. FrieslandCampina's Wageningen technical center advances membrane filtration capabilities for specialized fractionation.
Modified Milk Ingredients Market Competitive Landscape
Backward integration into whey processing dominates the current landscape among European and Oceania-based processors. The vendor base clusters around dairy cooperatives with captive milk supply, multinational ingredient divisions, and regional fractionation specialists. Three archetypes prevail: grass-fed origin specialists, clinical-grade fractionators, and commodity-scale powder processors. Competitive intensity centers on enzymatic separation licensing and spray dryer retrofit investments for instantized specifications.
Within the cooperative archetype, Fonterra Co-operative Group and Arla Foods occupy positions defined by member-farmer ownership structures and grass-fed milk pool access. Lactalis International represents the multinational ingredient division model with European supply chain integration. These three entities exemplify how upstream control over raw milk supply constrains independent processor expansion in premium protein concentrate segments.
| Leading Market Players |
|---|
| Nestle SA |
| Lactalis International |
| Danone SA |
| Fonterra Co-operative Group |
| FrieslandCampina |
| Arla Foods |
| Yili Group |
| China Mengniu Dairy |
| Kerry Group |
| Others |
Supply & Pricing Matrix
Chinese infant formula manufacturers' NMPA registration mandates for quantitative protein content declarations and origin traceability documentation are forcing exporters to reconfigure quality management systems around batch-level analytical verification, compressing margins on non-compliant shipments and widening spreads between certified and uncertified ingredient tiers.
Pricing Analysis
Skim milk powder auction fluctuations transmit directly to modified ingredient cost structures through commodity-linked contract terms. Three-tier pricing structure across premium, standard, and economy levels separates grass-fed origin-certified protein concentrates from commodity-grade milk powders and fat-filled derivatives. Cost compression in standard-grade whey protein concentrates is intensifying because plant-based fat replacers displace dairy-derived fractions in bakery applications. Dairy manufacturers exhibit highest price sensitivity due to volume procurement and seasonal raw milk substitution needs, while nutraceutical companies absorb premiums for clinical-grade hydrolysates with documented bioavailability.
Supply Chain Analysis
Dual-sourcing requirements from North American sports nutrition brands mandate simultaneous New Zealand and European supplier qualification to mitigate single-origin risk for consistent fatty acid profiles. Geographic supply concentrates in New Zealand, Germany, and the United States, with raw material dependencies on grass-fed milk pools, enzymatic separation reagents, and chromatographic purification resins. Single-source vulnerability from New Zealand's Waikato region concentration exposes buyers to climate-driven milk pool disruptions. Distribution runs through dairy cooperative processing infrastructure, multinational ingredient divisions, and direct-to-manufacturer e-procurement platforms eliminating distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Modified Milk Ingredients Market functions as a stable compounder anchored by irreversible protein fortification trends across infant nutrition and clinical feeding applications that sustain demand through agricultural commodity cycles.
For Market Incumbents: Deepen backward integration into whey processing to defend margin position against enzymatic fractionation specialists eroding premium protein concentrate pricing. Expand chromatographic purification capacity in Bavaria and Waikato to capture medical nutrition contract volumes requiring EFSA novel food assessment compliance. Fortify spray dryer infrastructure for instantized specifications demanded by North American bakery manufacturers embedding outcome-based performance clauses. For New Entrants and Emerging Players: Capture Southeast Asia medical nutrition white space in Thailand and Vietnam where aging demographics drive specialized protein hydrolysate demand and local enzymatic separation expertise remains scarce. Target precision fermentation convergence opportunities creating hybrid ingredient categories that bypass agricultural input constraints. Lead with direct-to-manufacturer e-procurement positioning for certified organic milk protein concentrates serving mid-sized food manufacturers seeking batch-level verification. For Investors and Strategic Acquirers: Asymmetric upside sits with clinical-grade fractionators possessing EFSA novel food assessment track records and NMPA registration dossier capabilities. Long-term viability over a multi-year horizon rests on regulatory compliance infrastructure rather than commodity processing scale. Monitor SAMR inspector scrutiny intensity on fractionation process validation data as inflection indicator for Chinese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Upgrade | Cross-flow microfiltration adoption compresses minimum efficient scale thresholds for regional processors competing on specialized specifications. |
| Backward Integration into Whey Processing | Captive whey supply secures rapid-absorption protein isolate volumes for North American sports nutrition contract manufacturers. |
| NMPA Registration Dossier Investment | SAMR-compliant technical documentation unlocks premium pricing from Chinese infant formula manufacturers reducing import dependency. |
| Precision Fermentation Partnership | Microbial dairy protein synthesis convergence creates hybrid categories bypassing grass-fed milk pool supply constraints. |
| Direct-to-Manufacturer E-Procurement Platform | Elimination of distributor markups captures margin from mid-sized food manufacturers seeking certified organic concentrates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy cooperative procurement directors, enzymatic fractionation specialists, infant formula regulatory affairs leads, and sports nutrition contract manufacturing executives with secondary validation from FDA identity standard filings, EFSA novel food assessment registers, NMPA dairy registration databases, and Fonterra global dairy trade auction data. Bottom-up volume modeling across protein content tiers and top-down macroeconomic anchoring ensured convergence.
Comparable-period anchoring to historical protein fractionation capacity utilization and infant formula registration approval timelines structured the projection horizon. Segmentation dimensions modeled encompass product type, end-user procurement sophistication, application regulatory stringency, and form factor storage economics. CAGRs derived from installed capacity expansion announcements, backward integration project pipelines, and import substitution policy trajectories. Forecast inputs included membrane filtration technology adoption curves and precision fermentation commercialization milestones.
Underlying measurement precision varies by segment; infant formula and medical nutrition applications carry tighter precision than commodity bakery and confectionery uses due to regulatory documentation density. Forecasts reflect assumptions around NMPA registration timeline stability, EFSA novel food assessment pathway continuity, and grass-fed milk pool climate resilience. Deviation in SAMR inspector scrutiny intensity or New Zealand drought frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Spain Food Emulsifiers Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Carob Bean Gum Market