
 Cake Enzyme Market | 2026-2036
Cake Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Cake Enzyme Market Outlook
EU Green Deal is hardening the cost-of-entry calculus for synthetic emulsifier suppliers. DSM Nutritional Products AG leverages its enzyme formulation portfolio to anchor premium positions in clean-label cake production. Novozymes competes through sustained R&D intensity in amylase variants optimized for high-ratio cake systems. Advanced Enzymes dominates Asian supply channels with specialized glucose oxidase grades for sponge cake applications.
Cake enzymes are protein-based biocatalysts, typically active within pH ranges of 5.0 to 7.5 and temperatures between 30°C and 60°C, that hydrolyze starch, modify gluten networks, or generate oxidizing conditions to improve cake volume, crumb structure, and shelf stability. Amylase segments lead volume consumption due to their role in starch modification for soft, moist crumb texture, while glucose oxidase represents the fastest-growing product category as bakers replace potassium bromate and ascorbic acid with enzyme-based dough conditioning. Powder formulations occupy the largest share of commercial procurement, though liquid concentrates gain traction in automated food service operations where dosing precision reduces waste.
EU Green Deal frameworks and REACH chemical restrictions shape ingredient substitution patterns across European bakery chains. FDA GRAS determinations and USDA organic certification standards govern market access for enzyme suppliers targeting North American clean-label segments. Stakeholders must monitor evolving enzyme labeling requirements under EFSA guidance and anticipate how dual carbon goals in China may redirect MEE oversight toward bio-based processing aids.
Market Dynamics
Clean-label reformulation is compressing synthetic additive margins across commercial bakery chains. EU Green Deal chemical restrictions and FDA GRAS determinations are redirecting procurement toward enzyme-based alternatives that deliver equivalent functional performance without declaration penalties.
Growth Catalysts
- EU Green Deal additive limits:REACH restrictions on synthetic emulsifiers force European bakery chains toward amylase and glucose oxidase alternatives. Reformulation mandates accelerate enzyme adoption in Germany, France, and Italy.
- Commercial bakery consolidation:Large-scale industrial bakeries standardize enzyme protocols across multi-site operations to achieve batch consistency and extended shelf stability.
- Potassium bromate replacement:Regulatory bans on oxidizing agents in multiple jurisdictions position glucose oxidase as the functional substitute for dough conditioning in high-ratio cake systems.
Market Restraints
- Temperature sensitivity:Enzyme activity windows between 30°C and 60°C require precise process control that legacy bakery infrastructure cannot accommodate without capital retrofit.
- Raw material concentration:Fungal and bacterial fermentation feedstocks for enzyme production concentrate in specific agricultural regions, exposing supply chains to climate volatility.
- Label declaration complexity:EFSA guidance on enzyme labeling creates formulation disclosure requirements that conflict with clean-label marketing positioning for certain retail segments.
Strategic Opportunities
- Automated food service penetration:Liquid enzyme concentrates enable precision dosing systems in industrial catering operations that powder formats cannot serve effectively.
- USDA organic certification alignment:Organic-compliant enzyme grades unlock premium pricing in North American natural products channels where synthetic additive bans are most stringent.
- Sponge cake specialization:Asian bakery traditions favor specific glucose oxidase performance profiles that Western suppliers have underdeveloped, creating white space for localized formulation.
Industry Challenges
- Enzyme stability engineering:Maintaining activity through freeze-thaw distribution cycles requires formulation expertise that competes for limited protein engineering talent.
- Dual certification timelines:Simultaneous EFSA novel food assessments and FDA GRAS self-determinations extend market entry timelines by 18-24 months for new enzyme variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cake Enzyme Market |
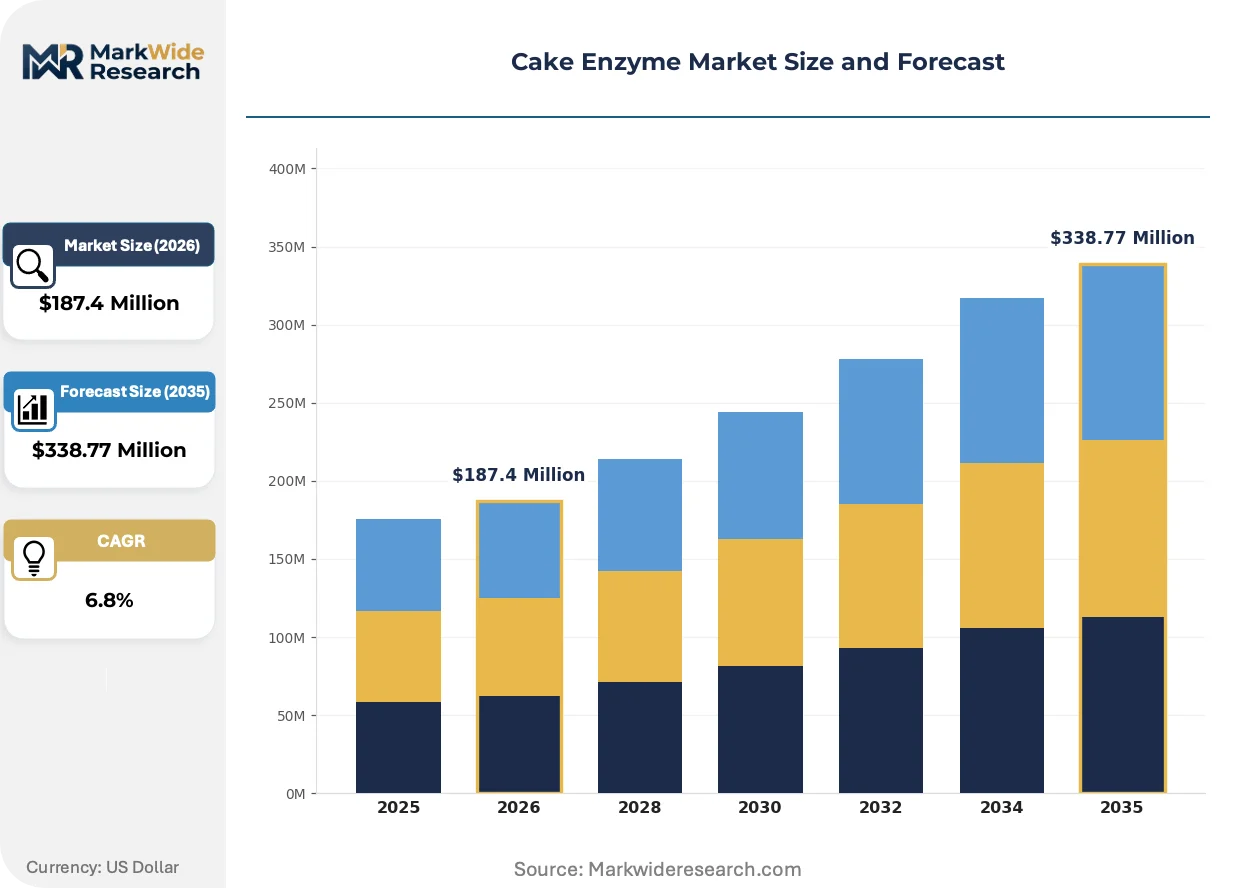
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylopectin, Amylase, Protease, Glucose Oxidase End User: Bakers, Confectioneries, Food Service Providers, Home Bakers Form: Liquid, Powder, Granular, Tablet Application: Cakes, Muffins, Breads, Pastries |
| Companies Covered | DSM Nutritional Products AG, Advanced Enzymes, Novozymes, Dyadic International Inc., Stern Enzyme, DuPont Nutrition & Health, Amano Enzymes, Fermentech Labs, AB Enzymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cake Enzyme Market Strategic Shifts
Enzyme engineering and regulatory chemistry are converging to displace century-old additive paradigms. Three interconnected developments are reshaping how biocatalysts penetrate bakery value chains.
Precision fermentation-derived enzymes are consolidating quality control advantages over traditional extraction methods. Commercial bakeries in Germany and France are adopting these grades to reduce batch-to-batch variation in sponge cake production. The technology is consolidating supplier power toward biotech-enabled manufacturers with in-house strain development capabilities.
REACH chemical restrictions are hardening the compliance burden for synthetic emulsifier incumbents. ECHA substance evaluations now require extensive toxicological dossiers that enzyme alternatives bypass through natural substance classifications. European bakery chains are responding by embedding enzyme specialists directly into procurement teams to accelerate reformulation timelines.
Clean-label purchasing criteria are compressing the acceptable ingredient declaration list for retail cake products. North American supermarket bakery buyers now reject potassium bromate, azodicarbonamide, and DATEM emulsifiers that dominated formulations through 2020. This behavioral shift is most visible in US coastal markets where organic certification penetration exceeds national averages by substantial margins.
Cake Enzyme Market Segmentation
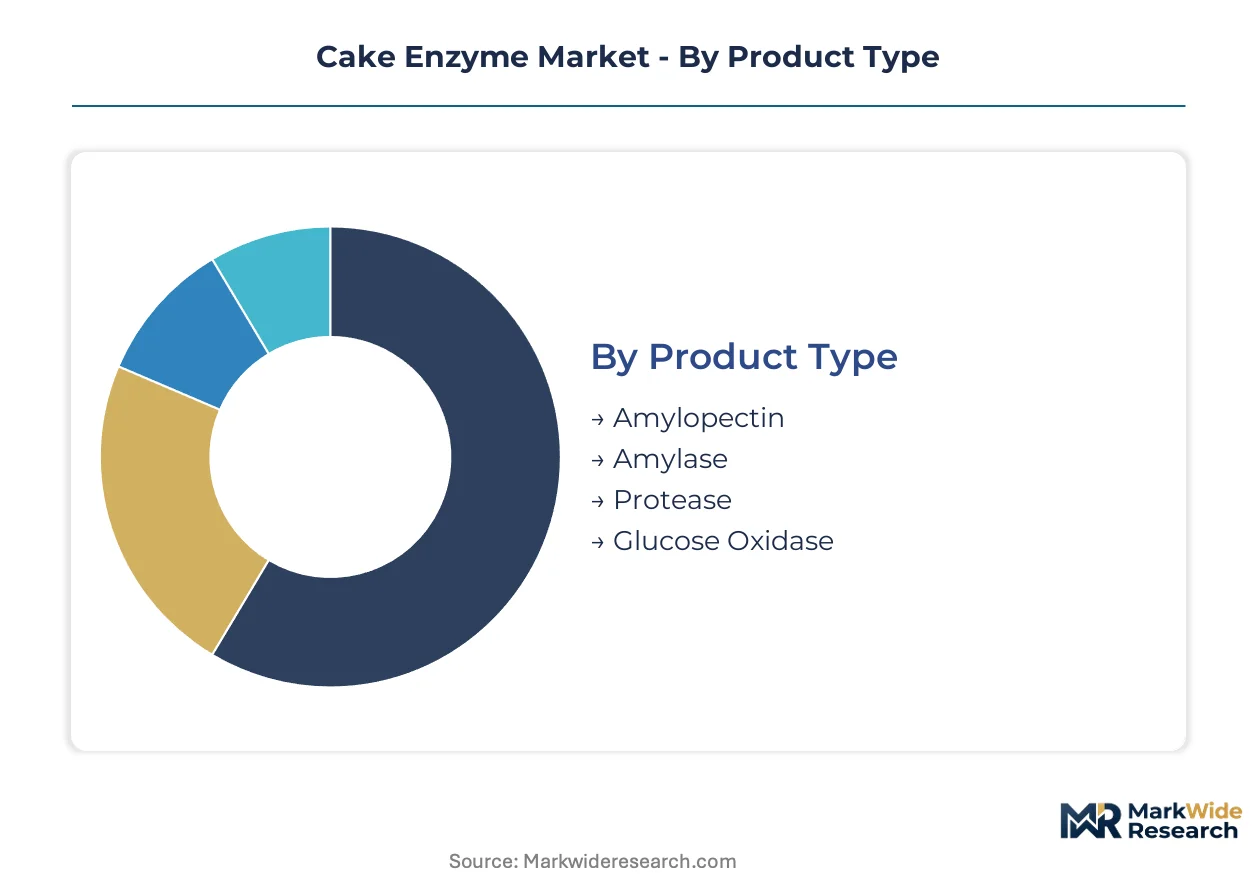
Enzyme selection in commercial baking hinges on precise matching of biocatalytic activity to specific flour matrices and process conditions. Segmentation reveals how formulation requirements diverge across industrial scale, regulatory environment, and end-product texture specifications.
Product Type:
Standardization dominates commodity grades while custom enzyme blends command premium positioning in specialized applications.
- Amylase:Starch-hydrolyzing enzymes that cleave alpha-1,4-glycosidic bonds to reduce amylopectin retrogradation and extend shelf stability. Demand concentrates in Germany and France where industrial bakeries reformulate sponge cakes under EU Green Deal additive restrictions. Amylase variants optimized for high-ratio cake systems displace synthetic softeners in clean-label portfolios.
- Glucose Oxidase:Oxidoreductase enzymes that generate hydrogen peroxide to strengthen gluten networks and replace banned potassium bromate. Food service providers in Italy adopt this category fastest as regulatory deadlines for oxidizing agent phase-outs approach.
- Protease:Protein-cleaving enzymes that modify gluten elasticity for tender crumb structure in layer cakes.
- Amylopectin:Specialized debranching enzymes targeting specific starch fractions for moisture retention in extended-distribution products.
Most installed capacity flows through Amylase. Expansion is steepest in Glucose Oxidase.
End User:
Volume scale separates procurement patterns, with industrial operators driving formulation standardization against fragmented artisan demand.
- Bakers:Industrial and artisan operations requiring consistent enzyme performance across variable flour harvests. Commercial bakery consolidation in France and Italy accelerates protocol standardization for multi-site sponge cake production.
- Food Service Providers:Automated catering operations demanding liquid concentrate formats with precision dosing compatibility. This segment climbs fastest as institutional procurement shifts toward clean-label ingredient declarations.
- Confectioneries:Specialized cake manufacturers prioritizing specific crumb texture and shelf stability for premium retail distribution.
- Home Bakers:Small-format retail enzyme preparations targeting consumer convenience and simplified measuring.
Procurement volume concentrates with Bakers. Reformulation urgency is strongest among Food Service Providers.
Form:
Handling characteristics and dosing precision determine format selection across manual versus automated production environments.
- Powder:Dry enzyme preparations offering extended stability and simplified dry-blending with flour premixes. Dominates commercial bakery procurement in Germany where bulk handling infrastructure supports efficient dispersion.
- Liquid:Concentrated aqueous or glycerol-based solutions enabling automated pump dosing and reduced waste in high-throughput operations. Gaining share fastest in food service channels requiring real-time flow adjustment.
- Granular:Free-flowing particulate formats for dust-controlled handling in artisan bakery settings.
- Tablet:Pre-measured unit doses targeting small-scale bakers and home use segments with minimal weighing equipment.
Current inventory positions favor Powder. Automation investments are redirecting procurement toward Liquid.
Application:
Product-specific rheology requirements drive enzyme blend customization, with cake systems demanding distinct treatment from fermented doughs.
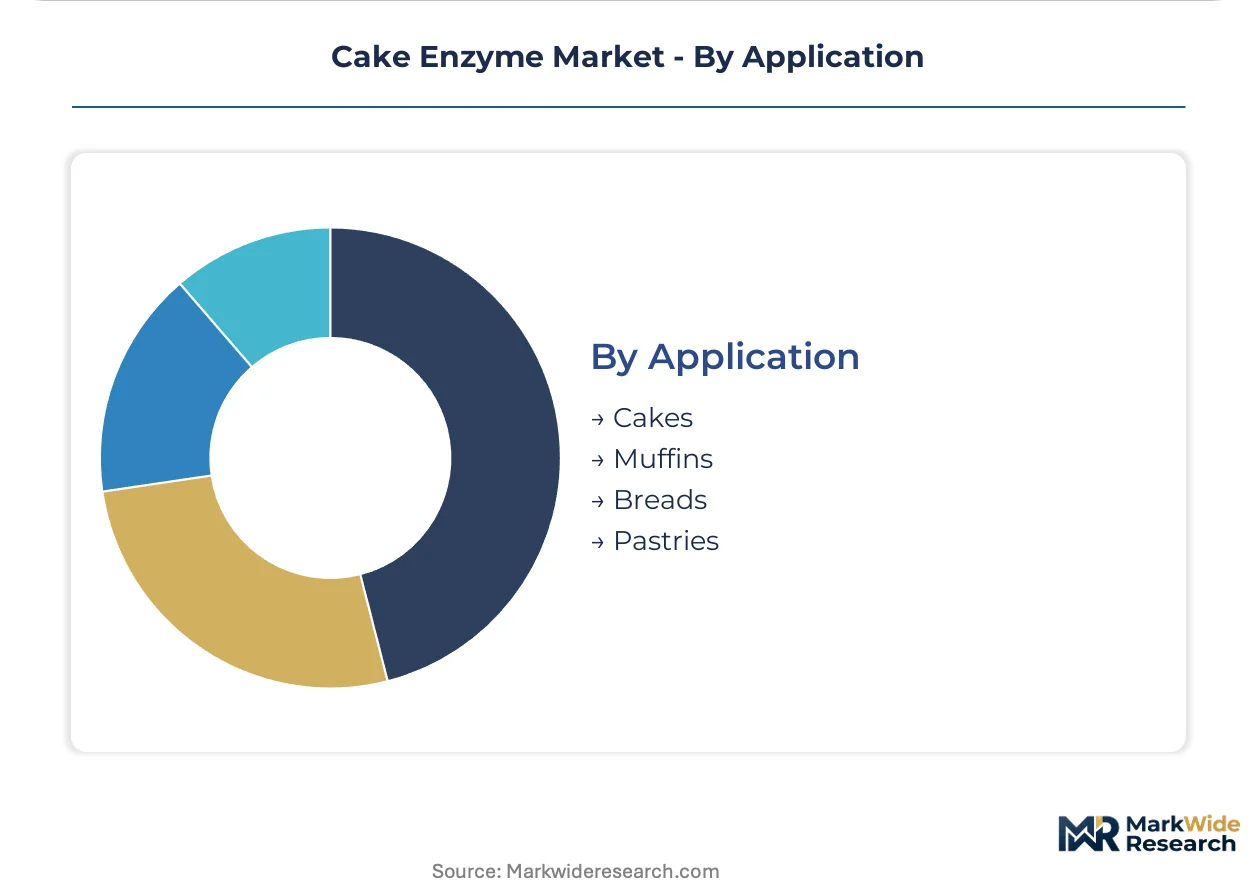
- Cakes:High-ratio formulations requiring precise starch modification and aeration stability without gluten network dependency. Clean-label reformulation in France and Italy concentrates enzyme demand here as synthetic emulsifier bans take effect.
- Muffins:Quick-bread systems with intermediate batter viscosity and specific tunneling control requirements. This application expands most quickly in North American food service channels where portion-controlled breakfast items dominate procurement.
- Breads:Yeast-leavened systems with distinct enzyme requirements for crust color and crumb elasticity.
- Pastries:Laminated dough applications prioritizing extensibility and fat distribution over volume generation.
Formulation complexity peaks in Cakes. Volume growth is accelerating in Muffins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial enzyme production for bakery applications traces its industrial lineage to post-war fermentation technology development in Northern Europe. Germany and the Netherlands established the foundational strain development and large-scale bioprocessing infrastructure that now supplies reformulation-grade enzymes to European bakery chains confronting additive restrictions.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia drive procurement volumes for amylase grades optimized under EU Green Deal additive limits. ECHA substance evaluations under REACH redirect supply contracts toward enzyme-based alternatives that bypass synthetic emulsifier compliance burdens. The Stuttgart-Munich corridor concentrates precision fermentation capacity serving reformulation demand from commercial cake producers.
France
Parisian and Lyon-based bakery chains accelerate glucose oxidase adoption as oxidizing agent phase-out deadlines approach. ANSM oversight of food processing aids aligns with EFSA guidance on clean-label enzyme declarations. The Île-de-France region anchors multi-site standardization protocols for sponge cake production across consolidated industrial bakery operations.
Italy
Food service providers in Lombardy and Emilia-Romagna adopt liquid concentrate formats for automated dosing compatibility. Ministry of Health circulars on potassium bromate replacement position enzyme suppliers for dough conditioning reformulation. Bologna-Milan industrial zones concentrate procurement teams embedding enzyme specialists directly into ingredient sourcing functions.
United States
Coastal supermarket bakery buyers in California and New York Metro reject synthetic additives exceeding organic certification thresholds. FDA GRAS determinations govern market access for enzyme suppliers targeting clean-label segments where USDA organic penetration exceeds national averages. Chicago and Minneapolis-St. Paul industrial baking clusters standardize enzyme protocols across multi-state distribution networks.
China
Dual carbon goals under MEE oversight redirect processing aid procurement toward bio-based alternatives in Yangtze River Delta bakery manufacturing. SAMR food additive standards increasingly favor enzyme classifications over synthetic chemical registrations. Shanghai and Hangzhou industrial zones concentrate sponge cake production demanding specialized glucose oxidase performance profiles.
Cake Enzyme Market Competitive Environment
The competitive structure tilts toward biotechnology-enabled specialists with in-house strain development capabilities. Consolidation patterns favor manufacturers controlling precision fermentation infrastructure over traditional extraction-based suppliers. Three archetypes dominate: integrated life sciences conglomerates with enzyme divisions, dedicated enzyme technology specialists, and regional fermentation houses serving localized bakery traditions. Capacity expansion and geographic licensing agreements constitute the primary competitive moves as suppliers race to anchor reformulation partnerships with consolidating commercial bakery chains.
Within the integrated conglomerate tier, DSM Nutritional Products AG and DuPont Nutrition & Health occupy positions leveraging broad life sciences portfolios to bundle enzyme offerings with adjacent ingredient systems. Novozymes exemplifies the dedicated enzyme technology specialist archetype through sustained positioning in amylase variant development. Advanced Enzymes anchors the regional specialist category with concentration on Asian supply channel penetration. These three represent distinct strategic postures rather than direct functional equivalence across all bakery enzyme applications.
| Leading Market Players |
|---|
| DSM Nutritional Products AG |
| Advanced Enzymes |
| Novozymes |
| Dyadic International Inc. |
| Stern Enzyme |
| DuPont Nutrition & Health |
| Amano Enzymes |
| Fermentech Labs |
| AB Enzymes |
| Others |
Value Chain & Pricing Dynamics
Fungal fermentation feedstock indices in the US Corn Belt and Brazilian sugarcane regions cascade through enzyme manufacturing cost structures, compressing standard-grade amylase margins while premium precision-fermentation grades capture pricing power through batch consistency guarantees demanded by EU bakery chains.
Pricing Analysis
Three-tier pricing structure across precision-fermentation premium, standard microbial-grade, and commodity-extraction economy levels separates contract bakery suppliers from artisan channel distributors. Price differentiation hinges on EFSA novel food certification status and volume scale commitments exceeding multi-site annual offtake. Cost compression in standard-grade segments is intensifying because REACH-compliant synthetic emulsifier displacement accelerates enzyme commoditization. Food service providers exhibit highest price sensitivity due to automated dosing waste tolerance, while organic-certified confectioneries accept substantial premiums for USDA-compliant grades.
Supply Chain Analysis
Dual-sourcing mandates from German and French industrial bakeries require simultaneous qualification of at least two fermentation houses for each enzyme variant, preventing single-source dependency despite concentration advantages. Manufacturing gravity centers on Denmark, the Netherlands, and China, with strain development competence anchored in Bavaria and Jiangsu province. Raw material dependencies include corn steep liquor, beet molasses, and pharmaceutical-grade glycerol carriers. Single-source vulnerability concentrates in precision fermentation starter cultures held by limited strain banks. Distribution runs through temperature-controlled bulk liquid tankers and cold-chain powder logistics serving regional bakery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cake enzyme market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France exceed North American organic certification burdens by substantial margins, redirecting capacity expansion toward US Midwest industrial baking corridors.
For Market Incumbents: Acquire precision fermentation strain libraries to consolidate batch-to-batch consistency advantages that commodity extraction suppliers cannot replicate. Anchor multi-year reformulation partnerships with consolidating French bakery chains before potassium bromate phase-out deadlines harden procurement commitments. Vertical integration into fungal fermentation feedstock sourcing mitigates climate volatility exposure threatening standard-grade margin stability. For New Entrants and Emerging Players: EU Green Deal additive limits in Italy and Germany open a window for specialized glucose oxidase grades optimized for high-ratio sponge cake systems that Western incumbents have underdeveloped. Target Lombardy food service automation corridors where liquid concentrate dosing infrastructure lacks qualified local suppliers. Pursue co-development agreements with Asian bakery equipment manufacturers to embed enzyme protocols directly into batter mixing systems. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap regional fermentation houses possessing strain development capabilities but lacking geographic licensing coverage for EU and North American regulatory pathways. Long-term viability favors targets with captive precision fermentation infrastructure rather than toll-manufacturing dependent models. Watch EFSA guidance publication timelines on enzyme labeling declarations as inflection indicators for clean-label premium capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Consolidates quality control advantages over traditional extraction methods for EU bakery chains. |
| EFSA Novel Food Certification Pathway | Unlocks premium positioning in clean-label segments where declaration complexity creates barriers. |
| Backward Integration into Feedstock Supply | Reduces exposure to corn and sugarcane price volatility concentrated in US and Brazilian agricultural belts. |
| Liquid Concentrate Format Development | Captures food service automation demand in Italian and German institutional catering channels. |
| Regional Licensing Agreement | Accelerates market entry timelines compressed by dual certification requirements across EFSA and FDA jurisdictions. |
Study Parameters
Multiple input streams — technical interviews with fermentation plant managers, procurement leads at German industrial bakeries, regulatory affairs specialists navigating EFSA novel food pathways, and distribution channel partners in European cold-chain logistics — were reconciled against customs trade data, ECHA substance evaluation dossiers, and SEC filings from publicly traded enzyme manufacturers. Bottom-up volume estimates derived from named bakery capacity installations and top-down value reconstructions from reported ingredient procurement patterns were cross-validated to establish segmentation splits across amylase, glucose oxidase, protease, and amylopectin product categories.
Historical volume trajectories were cross-referenced against panel input from commercial bakery technical directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include enzyme product type, end-user scale tier, physical formulation state, and application-specific rheology requirements. CAGRs were derived from slope analysis of normalized adoption curves adjusted for regulatory phase-in schedules. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and FDA GRAS determination backlogs affecting novel variant commercialization.
Revisions become necessary when EFSA guidance on enzyme labeling declarations materializes with stricter disclosure requirements than currently anticipated, or when MEE oversight in China redirects processing aid classifications toward synthetic chemical registrations. Forecasts reflect assumptions about regulatory pathway efficiency and bakery chain consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Egg Stabilizer Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Bulking Agents Market