
 Milk Ingredients Market | 2026-2036
Milk Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Ingredients Market Foresight
Direct procurement between dairy cooperatives and food manufacturers is fragmenting as ingredient traceability requirements multiply. Fonterra Co-operative Group leverages its New Zealand sourcing network to secure long-term whey protein contracts with Asian nutraceutical buyers. Arla Foods anchors its competitive stance through backward integration into Scandinavian organic milk pools. FrieslandCampina competes on lactose refinement capacity for pharmaceutical-grade applications.
Milk ingredients encompass the fractionated and processed outputs derived from bovine milk, including proteins, fats, carbohydrates, and minerals separated through ultrafiltration, microfiltration, chromatography, or spray-drying to achieve defined purity levels and functional performance. These inputs serve as standardized nutritional building blocks across formulated foods, clinical nutrition, and animal feed compounding. Whey protein isolates command premium positioning in sports nutrition and medical foods where protein digestibility-corrected amino acid scores determine formulation value. Casein fractions retain structural advantages in cheese analogs and sustained-release protein matrices. Milk powder volumes flow predominantly into confectionery and recombined dairy operations where solubility and heat stability specifications govern supplier selection.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that constrain interstate ingredient movements, while EFSA purity criteria for lactose monohydrate shape EU export eligibility for pharmaceutical applications. China's NMPA and national food safety standards on infant formula protein ratios directly determine import volumes of demineralized whey and milk protein concentrates. Stakeholders must monitor divergence between Codex Alimentarius guidelines and national infant nutrition mandates as formulation thresholds tighten.
Market Dynamics
Infant formula protein ratio mandates in China are compressing procurement timelines for demineralized whey, forcing ingredient suppliers to pre-qualify volumes against NMPA specifications before shipment. This regulatory pull-through is restructuring contract structures across the entire fractionation value chain.
Growth Catalysts
- EFSA Purity Criteria:Pharmaceutical-grade lactose monohydrate standards in Europe are expanding export eligibility for EU processors into Asian clinical nutrition markets.
- Sports Nutrition Formulation:Whey protein isolates with elevated protein digestibility-corrected amino acid scores command premium positioning in North American performance nutrition.
- China Dairy Self-Sufficiency Gap:Domestic policy shortfalls in raw milk production are accelerating import volumes of milk protein concentrates and specialized fractions.
Market Restraints
- EU F-Gas Compliance Costs:Refrigeration-dependent whey processing faces escalating capital requirements under tightening fluorinated gas phase-down schedules.
- Feed-Food Competition:Skim milk powder diversion into animal feed compounds during price spikes constrains food-grade availability.
- Chromatography Resin Supply:Protein fractionation depends on specialized resin inputs concentrated among a limited supplier base in North America and Europe.
Strategic Opportunities
- Medical Foods Channel:Sustained-release casein matrices for dysphagia and metabolic disorder patients represent underdeveloped formulation territory.
- Precision Fermentation Convergence:Combining traditional dairy fractionation with microbial protein production opens hybrid ingredient positioning.
- India FSSAI Harmonization:Alignment with Codex Alimentarius whey protein standards would unlock import pathways currently blocked by technical barriers.
Industry Challenges
- Fractionation Specialist Shortage:Operating membrane filtration and chromatography systems requires expertise concentrated among aging technician cohorts in New Zealand and the Netherlands.
- Infant Formula Certification Timelines:NMPA facility audits and formula registration cycles in China extend 18-24 months, freezing capital in work-in-progress inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Ingredients Market |
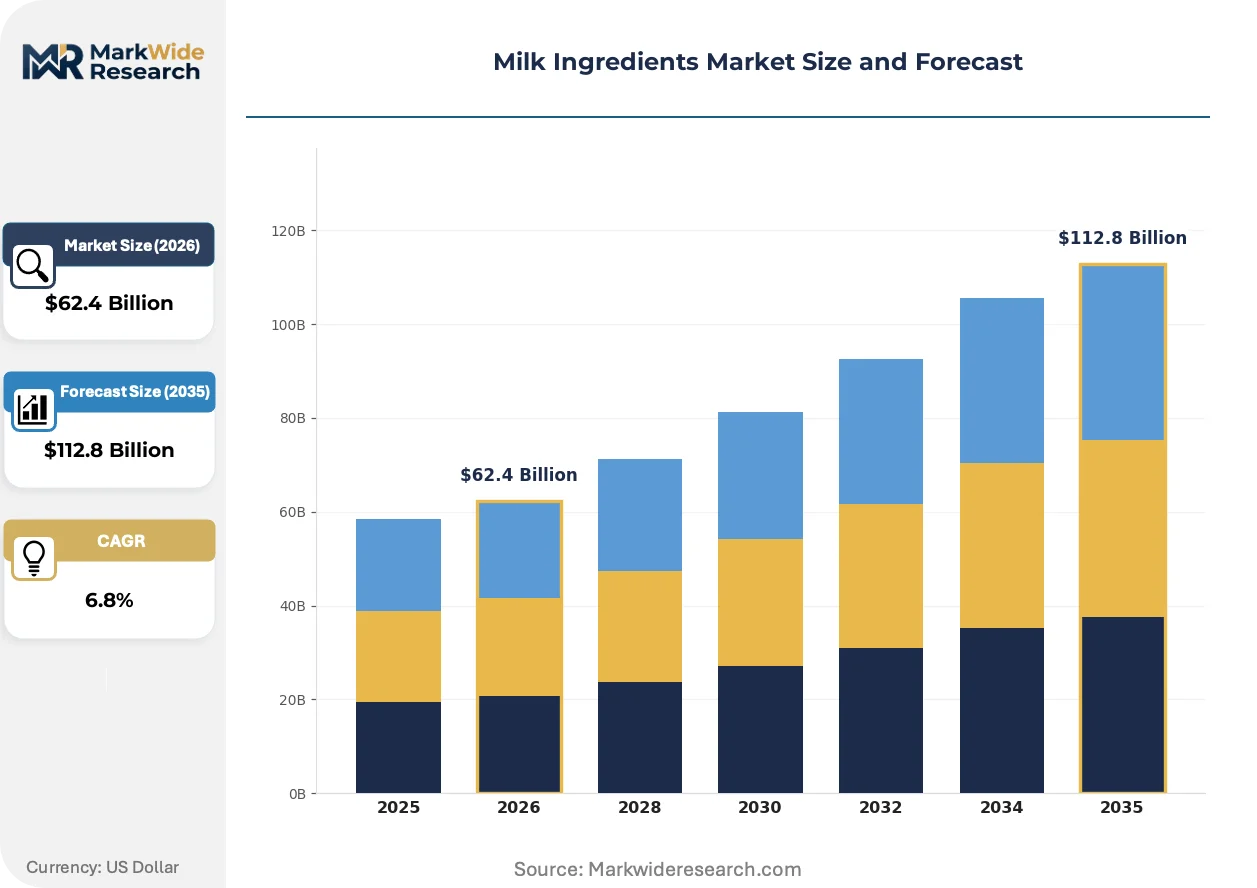
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Lactose, Milk Powder Application: Dairy Products, Bakery, Confectionery, Infant Formula End User: Food Manufacturers, Beverage Industry, Nutraceuticals, Animal Feed Form: Liquid, Powder, Concentrate, Isolate |
| Companies Covered | Fonterra Co-operative Group, Arla Foods, FrieslandCampina, Glanbia, Lactalis Ingredients, Dairy Farmers of America, Saputo, Kerry Group, Agropur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Ingredients Market Shifts & Advancements
Membrane technology advances and regulatory divergence between Codex guidelines and national infant nutrition mandates are compressing traditional supplier margins while opening specialized fractionation niches.
Precision fermentation is collapsing the cost structure for bio-identical milk proteins, enabling ingredient suppliers to bypass herd volatility entirely. Nutraceutical formulators in Germany and California are blending these inputs at 15-30% inclusion rates. The technology is collapsing the historical link between dairy commodity cycles and protein isolate pricing.
REACH framework amendments on residual solvent limits in whey derivative processing are forcing European fractionators to retrofit extraction equipment. This industrial consequence is diverting capital from capacity expansion into compliance infrastructure. Pharmaceutical-grade lactose producers in the Netherlands and Denmark face the most acute retrofit timelines.
Direct contracting between dairy cooperatives and finished goods manufacturers is displacing traditional trader intermediaries in Asian procurement channels. Infant formula makers in China now specify farm-level traceability down to individual herd vaccination records. This pattern is most visible in New Zealand-origin whey protein concentrate transactions.
Milk Ingredients Market Segmentation
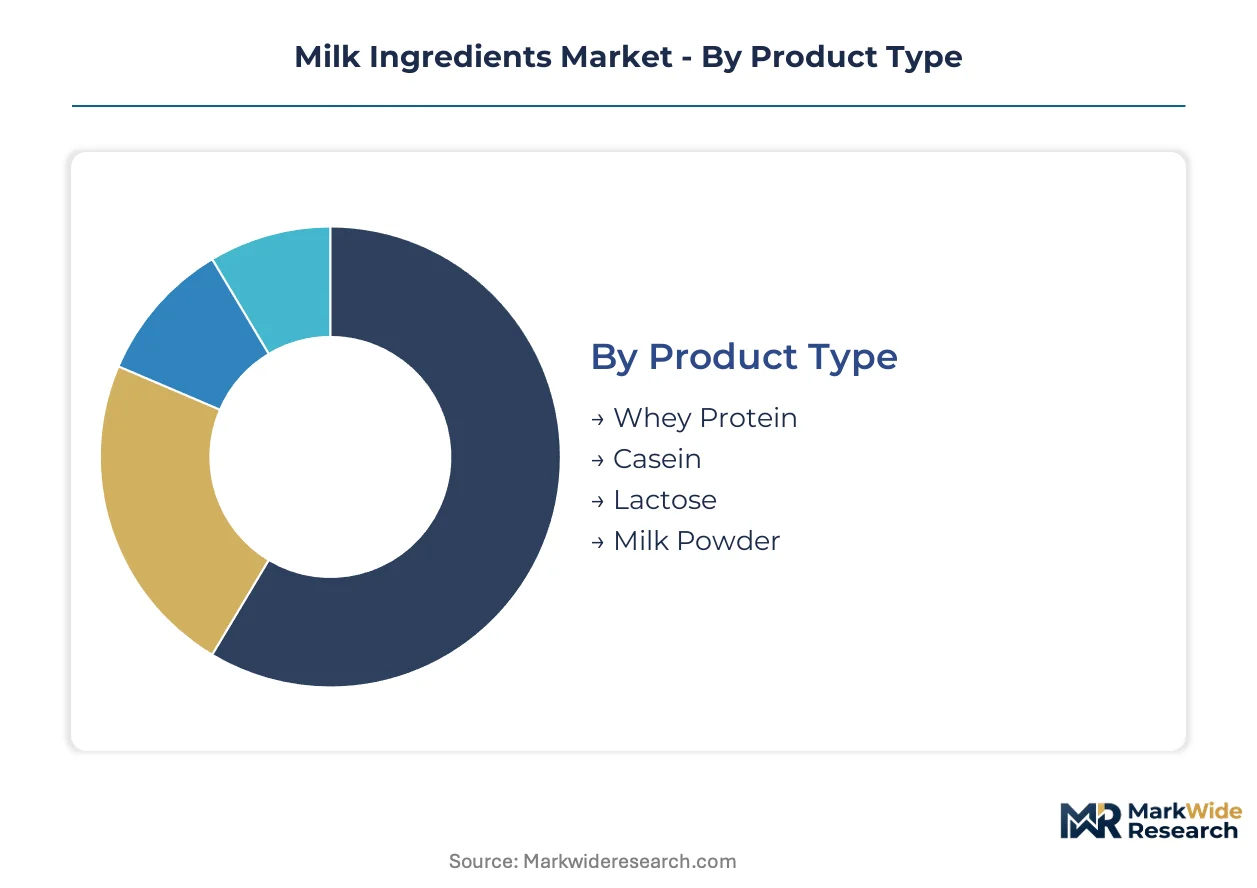
Fractionation technology determines how milk components separate into distinct commercial streams. Each segment carries unique regulatory burdens and end-use specifications that reshape procurement patterns across food, pharmaceutical, and feed channels.
Product Type:
Whey protein isolates serve sports nutrition and medical food formulators seeking elevated protein digestibility-corrected amino acid scores. Casein fractions retain structural advantages in sustained-release matrices and cheese analogs. Lactose and milk powder volumes flow predominantly into confectionery and recombined dairy operations where solubility governs supplier selection.
- Whey Protein:Ultrafiltration and chromatography yield isolates with protein concentrations exceeding 90%. Demand concentrates in Chinese infant formula manufacturing where NMPA protein ratio mandates force pre-qualification of demineralized whey volumes against national food safety standards.
- Casein:Micellar precipitation and membrane separation produce fractions with distinct gelling and emulsifying properties. Sustained-release matrices for dysphagia patients and metabolic disorder formulations in German clinical nutrition channels drive premium positioning.
- Lactose:Crystallization and refining achieve pharmaceutical-grade monohydrate purity under EFSA criteria.
- Milk Powder:Spray-drying standardizes fat and protein ratios for recombined dairy and confectionery applications.
Established volume favors milk powder; emerging adoption favors whey protein isolates.
Application:
Cost tier stratification separates commodity-scale dairy operations from premium infant formula and clinical nutrition channels.
- Dairy Products:Recombined milk, cheese analogs, and fermented products depend on standardized protein and fat inputs. European dairy cooperatives leverage backward integration into organic milk pools to secure traceable supply for yogurt and fresh cheese manufacturing.
- Infant Formula:Protein ratio regulations in China compress procurement timelines and force facility-level pre-qualification. Demineralized whey and specialized fractions command premium positioning as NMPA registration cycles extend capital lockup periods.
- Bakery:Milk powder enhances browning, moisture retention, and shelf stability in industrial baking.
- Confectionery:Lactose and milk powder volumes flow into chocolate and candy manufacturing where solubility specifications determine supplier eligibility.
Volume concentration rests with dairy products; margin expansion concentrates in infant formula.
End User:
Customer type determines specification stringency from feed-grade bulk to pharmaceutical-grade certification.
- Nutraceuticals:Whey protein isolates with elevated bioavailability metrics command premium positioning in North American sports nutrition and German medical food formulations. Precision fermentation inputs now blend at 15-30% inclusion rates, collapsing historical links to dairy commodity cycles.
- Food Manufacturers:Direct contracting with dairy cooperatives displaces trader intermediaries as traceability requirements multiply to herd-level vaccination records.
- Beverage Industry:Protein fortification and emulsion stability drive demand for hydrolyzed fractions.
- Animal Feed:Skim milk powder diversion during price spikes constrains food-grade availability through feed-food competition dynamics.
Procurement scale favors food manufacturers; specification intensity favors nutraceuticals.
Form:
Supply concentration in membrane filtration and chromatography equipment shapes which purity tiers achieve commercial viability.
- Isolate:Chromatography and advanced membrane systems achieve protein concentrations above 90% with minimal fat and lactose residues. REACH framework amendments on residual solvent limits force European fractionators to retrofit extraction equipment, diverting capital from capacity expansion.
- Powder:Spray-drying standardizes moisture content and solubility profiles for intercontinental shipment and extended shelf stability.
- Concentrate:Ultrafiltration yields 35-80% protein fractions for cost-sensitive applications.
- Liquid:Bulk transport constraints limit distribution radius for unpreserved fluid streams.
Processing maturity favors powder; technology investment concentrates on isolate purification systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dairy self-sufficiency policies are accelerating import volumes of milk powder and protein isolates while the EU F-Gas Regulation tightens processing standards for whey derivatives across European fractionation facilities.
China
Domestic raw milk production shortfalls are compressing procurement timelines for demineralized whey used in infant formula manufacturing. The NMPA enforces protein ratio mandates that force facility-level pre-qualification before shipment. Yangtze River Delta processing clusters near Shanghai are absorbing the bulk of New Zealand-origin whey protein concentrate imports.
United States
FDA Grade A Pasteurized Milk Ordinance standards constrain interstate movements of milk ingredients while sports nutrition formulators drive whey protein isolate consumption. The FDA maintains strict purity thresholds for clinical nutrition applications. Wisconsin and California dairy cooperatives anchor domestic fractionation capacity with direct contracting to Asian infant formula manufacturers.
Germany
EFSA pharmaceutical-grade lactose monohydrate criteria are expanding export eligibility into Asian clinical nutrition markets. REACH framework amendments on residual solvent limits are forcing retrofit investments across whey processing facilities. Bavarian and North Rhine-Westphalian industrial zones concentrate lactose refinement operations serving pharmaceutical applications.
Netherlands
REACH compliance costs are diverting capital from capacity expansion into extraction equipment upgrades. The EFSA purity framework shapes lactose monohydrate certification for Asian medical food channels. Rotterdam-area fractionators are retrofitting chromatography systems to meet tightening residual solvent thresholds.
New Zealand
Fonterra's cooperative sourcing network secures long-term whey protein contracts with Asian nutraceutical buyers. The country's national food safety standards align with Codex Alimentarius guidelines for infant formula protein ratios. Canterbury and Waikato dairy regions supply traceable milk fractions with herd-level vaccination documentation.
Milk Ingredients Market Competitive Landscape
On the supply side, the industry is consolidating around dairy cooperatives with captive milk pools and specialized fractionators with chromatography expertise. The competitive terrain separates backward-integrated cooperatives controlling upstream milk supply from technology-focused processors commanding premium isolate purification. Three archetypes dominate: cooperative-owned fractionators with traceable sourcing networks, independent processors competing on lactose refinement certification, and hybrid operators blending traditional dairy with precision fermentation inputs. Dominant competitive moves include direct contracting with finished goods manufacturers and retrofit investments for REACH solvent compliance.
Within the cooperative tier, Fonterra Co-operative Group and Arla Foods exemplify the backward-integrated model with captive organic milk pools. FrieslandCampina occupies a position emphasizing pharmaceutical-grade lactose capacity. These three entities represent the prevailing competitive archetypes: traceable sourcing dominance, premium fractionation specialization, and clinical-grade certification focus.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Arla Foods |
| FrieslandCampina |
| Glanbia |
| Lactalis Ingredients |
| Dairy Farmers of America |
| Saputo |
| Kerry Group |
| Agropur |
| Others |
Supply & Pricing Matrix
Tariff exposure on New Zealand-origin whey protein concentrates determines both pricing tier spreads and supply chain shape across Asian procurement channels. Infant formula manufacturers in China absorb premium spreads for traceable sourcing while European fractionators face REACH-driven cost compression that feeds back into equipment retrofit priorities.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and food-grade lactose monohydrate tiers. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA purity criteria, NMPA facility pre-qualification status, and volume scale commitments. Cost compression in standard-grade whey protein concentrates is intensifying because precision fermentation inputs now blend at 15-30% inclusion rates. Food manufacturers exhibit highest price sensitivity due to feed-food competition dynamics; nutraceutical buyers show lowest sensitivity given protein digestibility-corrected amino acid score requirements.
Supply Chain Analysis
Raw milk sourcing draws from New Zealand, Netherlands, and Wisconsin dairy cooperative networks. Chromatography resin inputs, membrane filtration equipment, and specialized fractionation expertise represent critical dependencies. Single-source vulnerability concentrates in chromatography resin supply anchored among North American and European specialty chemical producers. Distribution runs through direct contracting between dairy cooperatives and finished goods manufacturers, displacing traditional trader intermediaries in Asian channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation convergence is transforming this market into a platform-economics inflection where hybrid ingredient positioning enables interoperability between traditional dairy fractionation and microbial protein production.
For Market Incumbents: Build traceability moats through herd-level vaccination documentation and farm-to-facility digital chains. Fonterra's cooperative sourcing network exemplifies defensive positioning against precision fermentation entrants. Arla Foods' backward integration into Scandinavian organic milk pools offers a second consolidation lever. NMPA registration cycle extensions threaten capital efficiency; pre-qualification infrastructure investment offsets this. For New Entrants and Emerging Players: India's FSSAI harmonization gap with Codex Alimentarius standards represents underpenetrated territory for whey protein isolate market entry. Medical foods channel for sustained-release casein matrices in German clinical nutrition offers second white-space target. Precision fermentation blending partnerships with established nutraceutical formulators provide viable go-to-market angle without captive milk pools. For Investors and Strategic Acquirers: REACH residual solvent limit enforcement reshapes the acquisition landscape toward European fractionators with retrofit completion. Long-term viability centers on hybrid operators combining chromatography expertise with precision fermentation integration. Chromatography resin supply concentration signals inflection when specialty chemical producers announce capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Milk Pools | Arla Foods secures traceable supply for European yogurt and fresh cheese manufacturing. |
| Pharmaceutical-Grade Lactose Certification | FrieslandCampina expands EFSA-compliant export eligibility into Asian clinical nutrition markets. |
| Precision Fermentation Partnership | German nutraceutical formulators blend bio-identical proteins at 15-30% inclusion rates. |
| REACH Compliance Retrofit | Netherlands fractionators divert capital from expansion into residual solvent extraction upgrades. |
| Direct Contracting with Infant Formula Manufacturers | New Zealand cooperatives displace trader intermediaries through herd-level traceability documentation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dairy cooperative procurement directors, infant formula regulatory affairs leads, chromatography equipment specialists, and clinical nutrition formulators; and secondary validation through FDA Grade A Pasteurized Milk Ordinance filings, EFSA purity criteria documentation, NMPA facility registration databases, and Fonterra cooperative disclosure statements. Bottom-up volume modeling triangulated against top-down macro dairy production data.
Forecast inputs span product type segmentation across whey protein, casein, lactose, and milk powder tiers; application channels from infant formula to sports nutrition; and end-user specification intensity from feed-grade bulk to pharmaceutical-grade certification. CAGRs derived from regression analysis against historical dairy commodity cycles, precision fermentation cost curves, and regulatory compliance investment patterns. NMPA registration timelines and REACH phase-down schedules anchored scenario weighting.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation specialists or accelerated FSSAI harmonization would shift outcomes. Cross-checking against EIA dairy production forecasts and Codex Alimentarius guideline revision schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Based Premix Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
South America Lipid Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Oyster Shell Powder Market
Ingredients
Textural Food Ingredients Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Energy Ingredients Market
Ingredients
Phytogenic Market
Ingredients
Pulses Ingredients Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Corn Gluten Meal Market