
 Food Grade Ammonium Carbonate Market | 2026-2036
Food Grade Ammonium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Ammonium Carbonate Market Foresight
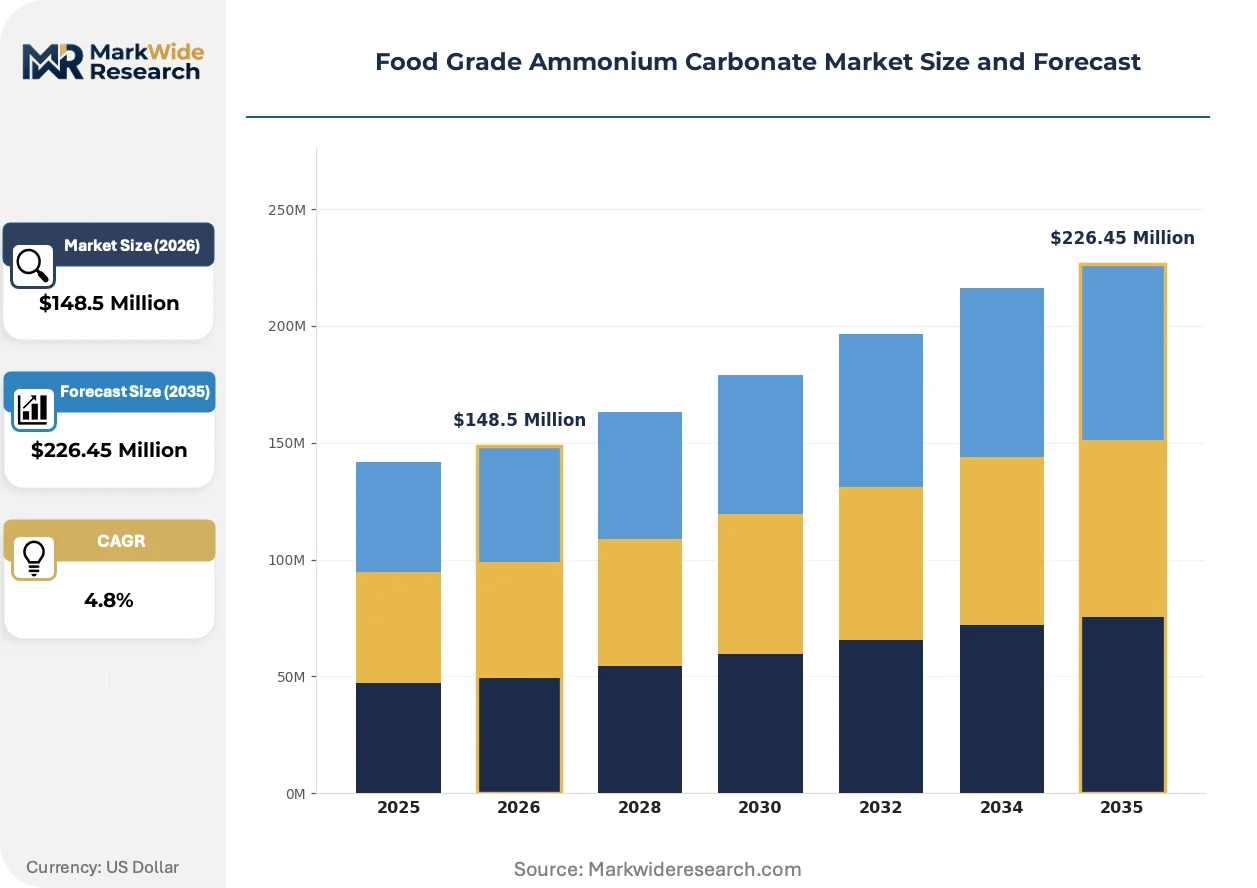
Ingredient sourcing economics is reconfiguring margin pools from commodity trading toward value-added formulation services for bakery and pharmaceutical clients. BASF leverages its integrated ammonia supply chain to control input costs across European production hubs. Solvay S.A. anchors its position through specialized crystal-grade output for premium pharmaceutical contracts. Tata Chemicals competes on manufacturing scale from its Indian base, serving cost-sensitive Asian food processors.
Food grade ammonium carbonate consists of a double salt of ammonium bicarbonate and ammonium carbamate, typically releasing carbon dioxide and ammonia gases at temperatures above 36°C to function as a chemical leavening agent without residual sodium. Powder-grade material commands the widest application footprint across industrial baking operations, while crystal-grade output captures concentrated margin pools in pharmaceutical excipient contracts where purity thresholds exceed standard food codex requirements. Granular formats retain mature demand in traditional European cookie and biscuit manufacturing, though pellet configurations remain nascent outside specialized fire safety applications.
The European Food Safety Authority maintains purity specifications that constrain non-EU import access, while the FDA enforces Food Chemicals Codex standards shaping North American product acceptance. India's FSSAI alignment with Codex Alimentarius protocols is opening formal market pathways for domestic producers serving export-oriented food processing units. Stakeholders must monitor evolving pharmaceutical-grade certification requirements as excipient standards tighten across multiple regulatory jurisdictions.
Market Dynamics
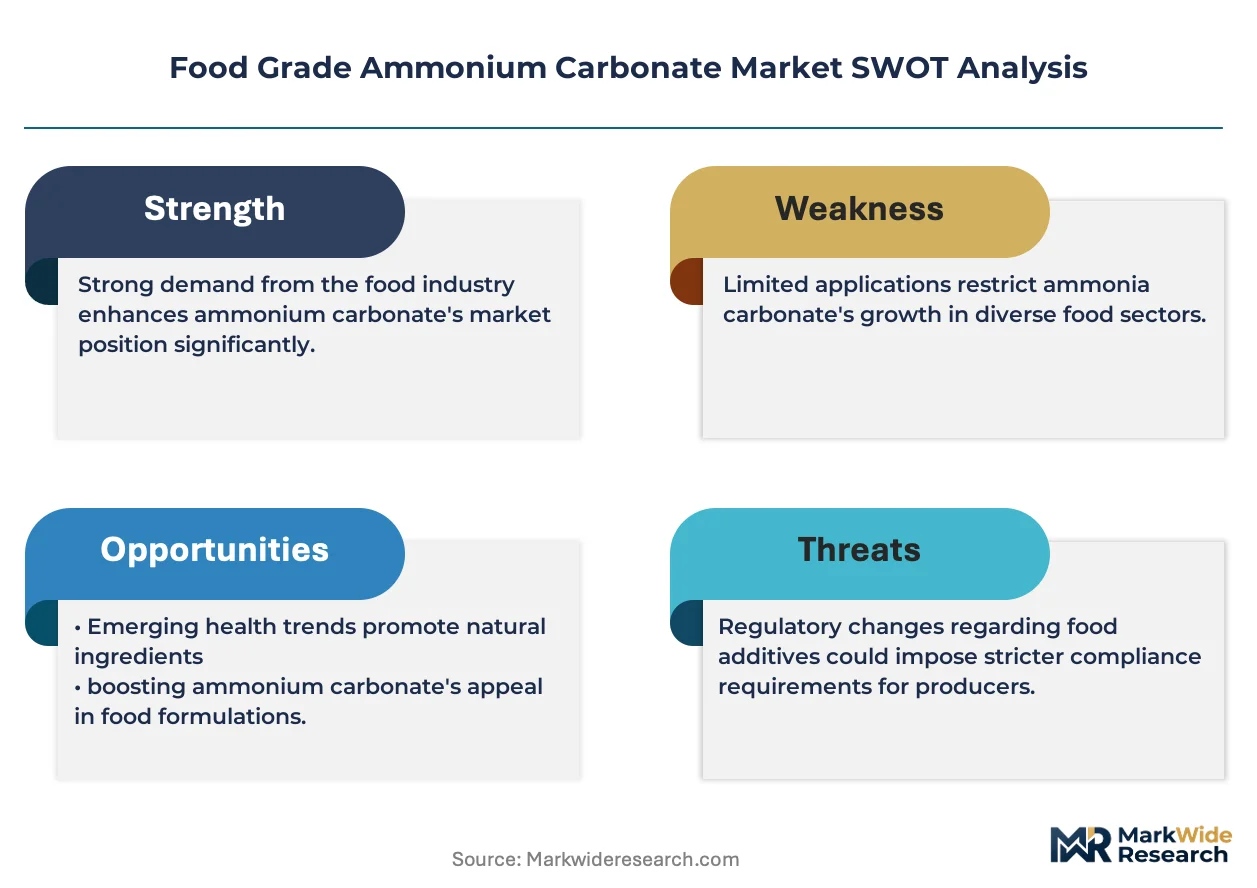
EU purity mandates under EFSA frameworks are compressing import arbitrage opportunities while concentrating supply among integrated ammonia producers with captive certification capabilities. This regulatory tightening is reconfiguring margin capture toward upstream chemical conglomerates.
Growth Catalysts
- EFSA Codex Alignment:Tightening ammonium carbonate purity specifications under EU food safety protocols are disqualifying marginal suppliers and securing volume commitments from established European chemical producers with certified production lines.
- Traditional Bakery Retention:German and French biscuit manufacturers maintain specification-grade demand for ammonium carbonate in heritage product formulations where chemical leavening preserves authentic texture profiles.
- Pharmaceutical Excipient Migration:Crystal-grade material is capturing expanded contract volumes as oral disintegrating tablet formulations require higher-purity gas-releasing agents.
Market Restraints
- Ammonia Feedstock Volatility:Natural gas price swings directly transmit into ammonium carbonate production economics, compressing margins for non-integrated processors lacking captive ammonia supply.
- Western European Supply Concentration:BASF and Solvay S.A. production hubs in Germany and Belgium create geographic dependency risk for buyers without qualified alternative sourcing.
- Baking Powder Substitution:Sodium bicarbonate-based formulations are displacing ammonium carbonate in cost-sensitive industrial baking applications where residual sodium is acceptable.
Strategic Opportunities
- Indian Export Formalization:FSSAI alignment with Codex Alimentarius protocols is opening certified pathways for Tata Chemicals and domestic competitors to supply EU-facing food processors.
- Fire Safety Pellet Expansion:Ammonium carbonate pellet configurations for gas-generating fire suppression systems represent an emerging application beyond traditional food and pharmaceutical uses.
- Clean Label Leavening:EU Green Deal chemical substitution incentives are positioning ammonium carbonate as a sodium-free alternative in reformulated bakery products targeting reduced-sodium claims.
Industry Challenges
- Pharmaceutical Grade Certification Timelines:Excipient GMP compliance under IPEC-PQG guidelines requires 18-24 month qualification periods that delay market entry for new production facilities.
- Crystallization Process Control:Maintaining consistent crystal morphology for pharmaceutical contracts demands capital-intensive purification equipment and specialized technical personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Ammonium Carbonate Market |
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $226.45 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Crystal, Pellet Application: Baking Powder, Leavening Agent, Pharmaceutical, Fire Extinguishing End User: Food Processing Units, Pharmaceutical Manufacturers, Chemical Industries, Fire Safety Providers Packaging Type: Bag, Drum, Box, Bulk Container |
| Companies Covered | BASF, Honeywell, Thermo Fisher Scientific, Solvay S.A., Tata Chemicals, Avantor, ECSA Chemicals, The Chemical Company, Univar Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Ammonium Carbonate Market Shifts & Advancements
Digital quality assurance systems are penetrating ammonium carbonate production facilities, replacing manual batch testing with real-time purity monitoring that compresses release cycles and reduces specification failure rates.
Process analytical technology (PAT) is virtualizing traditional quality control workflows in European ammonium carbonate manufacturing. BASF and Solvay S.A. are deploying in-line spectroscopic monitoring across their German and Belgian production trains. This virtualization is collapsing batch release timelines from days to hours while reducing laboratory headcount requirements.
REACH chemical registration amendments are tightening impurity disclosure thresholds for food-grade ammonium carbonate circulating in EU markets. Industrial bakeries and pharmaceutical formulators must now document full supply chain substance composition. Crystal-grade pharmaceutical contracts face the steepest compliance burden as excipient master file requirements expand.
Specification-driven supplier consolidation is compressing vendor counts among industrial bakery procurement functions. Large German and French biscuit manufacturers are reducing qualified ammonium carbonate sources from multiple traders to single or dual direct chemical producer relationships. This concentration is most visible in automated industrial baking operations where ingredient traceability requirements have escalated.
Food Grade Ammonium Carbonate Market Segmentation
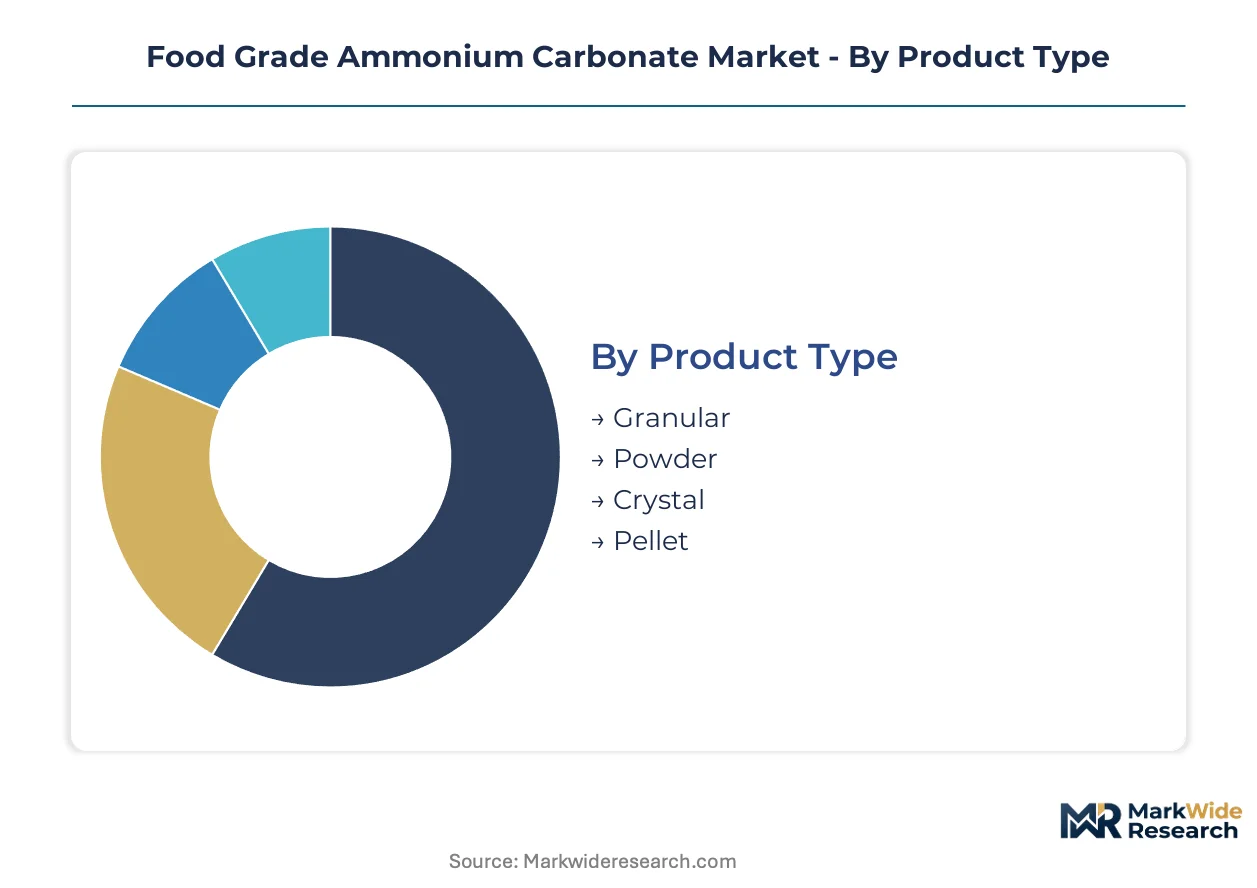
Product format and purity specifications determine margin capture in food grade ammonium carbonate procurement. End-use certification requirements fragment supplier qualification pathways across bakery, pharmaceutical, and industrial safety verticals.
Product Type:
Mature powder formats dominate volume throughput while emerging pellet configurations target specialized industrial gas-release applications.
- Powder:Fine-ground ammonium bicarbonate-carbamate double salt releases carbon dioxide and ammonia gases uniformly above 36°C. German and French industrial bakeries specify powder-grade material for automated dough conditioning systems where rapid dispersion controls texture consistency. EFSA purity mandates under EU food safety frameworks disqualify non-certified imports, securing volume commitments from integrated ammonia producers with captive certification capabilities.
- Crystal:High-purity crystalline output exceeds standard food codex thresholds to meet pharmaceutical excipient specifications for oral disintegrating tablet formulations. Solvay S.A. anchors European supply through specialized crystal-grade production trains in Belgium. IPEC-PQG GMP compliance demands 18-24 month qualification timelines that delay market entry for new production facilities.
- Granular:Coarse particulate format retains established demand in heritage European cookie and biscuit manufacturing where traditional leavening preserves authentic product characteristics.
- Pellet:Compressed spherical configurations for gas-generating fire suppression systems represent a nascent application beyond conventional food and pharmaceutical uses.
Powder retains volume leadership; pellet holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity leavening from premium excipient contracts where purity thresholds command substantial price premiums.
- Leavening Agent:Direct-use chemical leavening in traditional bakery formulations provides sodium-free texture development without residual salts. German biscuit manufacturers maintain specification-grade demand for heritage product lines.
- Pharmaceutical:Crystal-grade material serves as gas-releasing excipient in oral disintegrating tablet formulations requiring impurity profiles below food-grade thresholds.
- Baking Powder:Ammonium carbonate component in compounded baking powder formulations faces substitution pressure from sodium bicarbonate in cost-sensitive industrial applications.
- Fire Extinguishing:Pellet-configured ammonium carbonate generates ammonia and carbon dioxide gases for specialized fire suppression systems in confined industrial environments.
Leavening Agent sustains the broadest installed base; Pharmaceutical climbs the fastest.
End User:
Customer type determines procurement sophistication, with pharmaceutical formulators imposing the most stringent supplier qualification protocols.
- Food Processing Units:Industrial bakeries and biscuit manufacturers in Western Europe concentrate demand for specification-grade ammonium carbonate. Automated production lines require documented supply chain substance composition under REACH chemical registration amendments.
- Pharmaceutical Manufacturers:Oral dosage formulators contract for crystal-grade output with expanded excipient master file requirements. European production hubs in Germany and Belgium create geographic dependency risk for buyers without qualified alternative sourcing.
- Chemical Industries:Intermediate processors compound ammonium carbonate into specialized leavening blends and industrial gas-generating formulations.
- Fire Safety Providers:Specialized system integrators procure pellet configurations for gas-generating fire suppression installations.
Food Processing Units command the largest volume share; Pharmaceutical Manufacturers extract the highest unit margins.
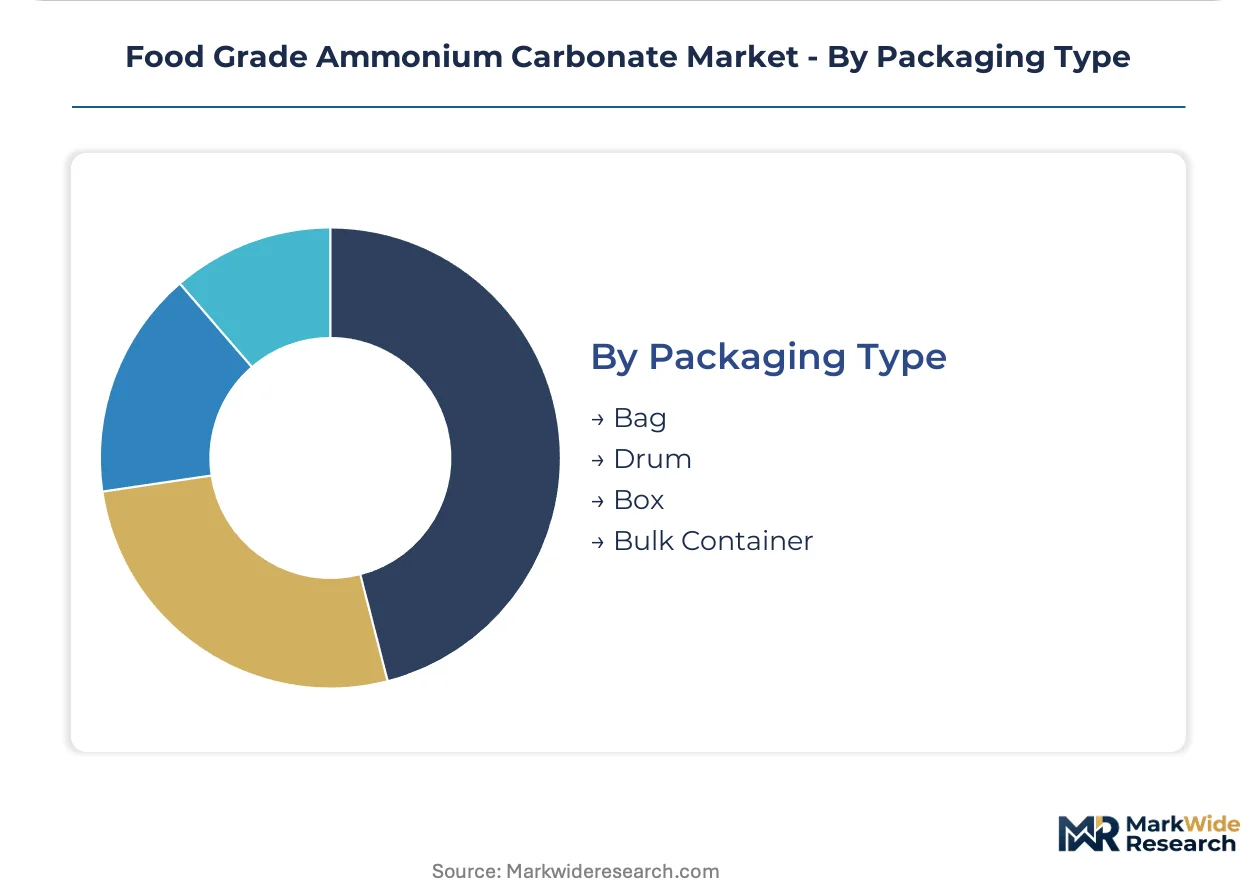
Packaging Type:
Supply concentration in bag and bulk formats reflects downstream automation and inventory economics across customer segments.
- Bag:Multi-wall paper or polyethylene bags serve small-to-medium food processors with manual handling requirements and limited storage infrastructure.
- Bulk Container:Flexible intermediate bulk containers and dedicated tanker deliveries support high-throughput industrial bakeries with automated ingredient handling systems.
- Drum:Steel or fiber drums protect crystal-grade pharmaceutical material from moisture contamination during extended storage periods.
- Box:Corrugated containers with inner liners address specialty chemical distributors and regional food processing units.
Bulk Container dominates automated operations; Drum secures the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Western European buyers absorb purity premiums under EFSA mandates, while Asian processors prioritize cost-efficient supply chains. This divergence shapes procurement patterns and supplier qualification pathways.
Germany
Heritage biscuit manufacturers in Lower Saxony and Bavaria sustain specification-grade demand for traditional leavening applications. EFSA purity specifications under EU food safety frameworks constrain import access and secure volume commitments from domestic ammonia producers. The Cologne-Düsseldorf chemical cluster anchors integrated production with captive certification capabilities serving automated industrial bakeries.
France
Artisan and industrial bakeries in Île-de-France and Hauts-de-France maintain codex-compliant ammonium carbonate demand for authentic texture preservation in heritage formulations. REACH chemical registration amendments tighten impurity disclosure thresholds, elevating documentation burdens across supply chains. The Lyon chemical corridor concentrates crystal-grade output for pharmaceutical excipient contracts requiring expanded master file compliance.
United States
Industrial baking operations in the Midwest and Southeast face substitution pressure from sodium bicarbonate in cost-sensitive applications where residual sodium is acceptable. FDA enforcement of Food Chemicals Codex standards shapes product acceptance and supplier qualification protocols. Chicago-area distribution hubs consolidate procurement for automated production lines requiring documented supply chain substance composition.
India
Export-oriented food processors in Maharashtra and Gujarat leverage FSSAI alignment with Codex Alimentarius protocols to access formal EU market pathways. The national food safety regulator's certification harmonization opens certified supply channels previously blocked by technical barriers. Mundra and Hazira port corridors concentrate manufacturing scale from domestic chemical bases serving cost-sensitive Asian markets.
Belgium
Pharmaceutical formulators in the Flanders region contract for crystal-grade material with impurity profiles exceeding standard food codex thresholds. IPEC-PQG GMP compliance requirements impose 18-24 month qualification timelines that delay market entry for unqualified production facilities. The Antwerp chemical cluster anchors specialized output for oral disintegrating tablet formulations across European pharmaceutical networks.
Food Grade Ammonium Carbonate Market Competitive Landscape
Integrated ammonia producers and specialized crystal-grade manufacturers split the market into distinct capability tiers. Supply concentrates among chemical conglomerates with captive feedstock control and certification infrastructure. Three archetypes dominate: upstream-integrated conglomerates with ammonia supply chain ownership, specialized high-purity crystal producers serving pharmaceutical contracts, and scale-driven regional suppliers competing on manufacturing throughput. Capacity expansion and strategic certification investments constitute the primary competitive moves as regulatory barriers tighten.
Within the integrated conglomerate tier, BASF and Solvay S.A. exemplify upstream control over ammonia feedstock and captive certification capabilities. Tata Chemicals occupies a position among scale-driven suppliers competing from manufacturing bases in cost-sensitive markets. These three anchors represent divergent strategic postures: feedstock integration, purity specialization, and manufacturing scale.
| Leading Market Players |
|---|
| BASF |
| Honeywell |
| Thermo Fisher Scientific |
| Solvay S.A. |
| Tata Chemicals |
| Avantor |
| ECSA Chemicals |
| The Chemical Company |
| Univar Solutions |
| Others |
Supply & Pricing Matrix
The Cologne-Düsseldorf chemical cluster anchors European ammonium carbonate capacity, and its integrated ammonia producers extract pricing premiums through captive certification capabilities that marginal importers cannot replicate under tightening EFSA purity mandates.
Pricing Analysis
After-sales technical service contracts for pharmaceutical excipient qualification drive lifetime value capture beyond base material sales. Three-tier pricing structure across crystal-grade pharmaceutical, powder-grade industrial bakery, and granular heritage applications separates margin pools by certification intensity. Cost compression in standard food-grade tiers is intensifying because sodium bicarbonate substitution erodes volume commitments from cost-sensitive processors. Industrial bakeries in Western Europe exhibit the lowest price sensitivity due to automated line validation requirements, while Asian export-oriented food processors prioritize procurement efficiency.
Supply Chain Analysis
Tariff exposure between India and the European Union dominates supply chain risk calculations for export-oriented processors seeking codex-aligned market access. Manufacturing concentration in Germany, Belgium, and India feeds global demand, with feedstock dependency on natural gas-based ammonia production creating margin volatility. Single-source vulnerability concentrates in the Antwerp-Cologne corridor where Solvay S.A. and BASF control crystal-grade pharmaceutical output. Distribution runs through direct chemical producer relationships for large industrial bakeries, bypassing traditional trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as regulatory divergence between EFSA codex alignment and emerging market formalization creates tiered supplier qualification pathways that favor specialized players over commodity traders.
For Market Incumbents: Entrench pharmaceutical-grade certification barriers by accelerating IPEC-PQG GMP compliance investments before excipient master file requirements expand. Add captive ammonia capacity in the Cologne-Düsseldorf corridor to insulate margins from natural gas feedstock volatility. Sodium bicarbonate substitution in industrial baking represents the core threat requiring defensive specification-grade contracting.
For New Entrants and Emerging Players: Indian export formalization under FSSAI-Codex alignment offers the most penetrable entry vector for certified supply to EU-facing food processors. Target pellet-configured fire safety applications where incumbent chemical producers lack dedicated production trains. Pursue toll manufacturing arrangements with established ammonia producers to bypass 18-24 month pharmaceutical qualification timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with undermonetized food-grade ammonium carbonate divisions lacking pharmaceutical certification infrastructure. Long-term viability hinges on excipient-grade margin expansion outpacing commodity leavening erosion. Monitor REACH chemical registration amendment enforcement intensity as the signal for regulatory barrier escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Feedstock | Captive natural gas supply insulates BASF and Solvay S.A. from input cost volatility. |
| Pharmaceutical GMP Certification Investment | IPEC-PQG compliance opens oral disintegrating tablet excipient contracts with premium pricing. |
| Indian Export Formalization Partnership | FSSAI-Codex alignment enables Tata Chemicals to supply EU-facing food processors. |
| Fire Safety Pellet Capacity Addition | Specialized gas-generating configurations target industrial safety beyond traditional food applications. |
| Digital Quality Assurance Deployment | In-line spectroscopic monitoring at BASF collapses batch release timelines from days to hours. |
Research Methodology
Cross-validation between primary interviews with plant managers at integrated ammonia producers and secondary analysis of EFSA regulatory filings anchors the qualitative findings. Procurement leads at German and French industrial bakeries, pharmaceutical formulators in Belgium and France, and distribution channel partners across Western Europe provided operating data. Customs records, Cefic chemical industry reports, SEC 10-K filings, and REACH registration databases supplied downstream demand validation. Bottom-up volume modeling triangulates against top-down chemical consumption estimates.
Calibration against historical capacity utilization rates and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product format tier, end-use certification requirement, regional production hub concentration, and packaging automation level. CAGRs derive from demand elasticity modeling against bakery and pharmaceutical output trends. Natural gas price trajectory assumptions and excipient master file expansion schedules constitute key forecast inputs.
Practitioners should monitor EFSA purity specification amendments and IPEC-PQG guideline revisions for early signals of qualification barrier escalation. Forecasts reflect assumptions about regulatory enforcement continuity and feedstock cost transmission mechanisms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Powdered Fats Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market