
 Facial Recognition Market | 2026-2036
Facial Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Recognition Market Analysis
The capability gap between cloud-scale infrastructure operators and point-solution vendors is rotating competitive capital allocation toward full-stack platform investments. NEC Corporation leverages its biometric hardware-software integration to anchor government identity programs across multiple continents. Microsoft sustains enterprise channel dominance through Azure AI services that embed facial verification into broader identity workflows. Thales Group differentiates via embedded security modules that harden recognition systems against spoofing attacks in critical infrastructure deployments.
Facial recognition systems capture, process, and match facial geometry data against enrolled templates using infrared depth mapping, convolutional neural networks, or thermal signature analysis to verify or identify individuals. These systems serve commercial and institutional customers by automating identity verification at scale, reducing manual checkpoint labor, and enabling real-time watchlist screening against video streams. Deep learning technology leads algorithm accuracy benchmarks and captures premium pricing in law enforcement and border control procurement, while 3D recognition commands growing share in mobile device authentication where presentation attack resistance determines vendor selection. Cloud-based deployment is expanding fastest among retail analytics buyers seeking elastic compute for seasonal traffic patterns, though on-premise systems retain margin concentration in defense and intelligence applications with data sovereignty requirements.
The EU AI Act imposes strict conformity obligations on biometric identification systems deployed in public spaces, with EDPB guidance shaping product roadmaps for vendors seeking European market access. China's SAMR and MIIT coordinate national standards for facial recognition data collection, consent protocols, and algorithm testing that determine procurement eligibility for domestic security projects. The United States lacks comprehensive federal biometric legislation, leaving NIST testing frameworks and fragmented state-level privacy laws to shape vendor compliance strategies. Stakeholders must monitor divergence between European risk-classification approaches and Chinese state-directed deployment models when allocating R&D and legal compliance resources.
Market Dynamics
The Facial Recognition Market pivots on algorithmic displacement of legacy 2D matching systems by deep learning architectures, a shift compressing procurement cycles for accuracy-critical deployments while redistributing competitive advantage toward full-stack platform vendors with cloud-scale infrastructure.
Growth Catalysts
- EU AI Act conformity frameworks:The European Union's risk-classification approach for biometric identification systems creates procurement clarity for vendors seeking European market access, accelerating standardization investments.
- Airport biometric boarding deployments:EASA and TSA frameworks drive hardware-software integration demand across United States and European Union aviation security checkpoints.
- Smart city surveillance infrastructure:China's domestic public safety procurement pipelines concentrate demand for thermal signature analysis and infrared depth mapping capabilities.
Market Restraints
- GPU and specialized AI accelerator supply concentration:Taiwan-based foundry capacity constraints limit algorithm training throughput for mid-tier vendors.
- EU AI Act strict conformity obligations:EDPB guidance imposes documentation and testing burdens that extend product development timelines for biometric identification systems deployed in public spaces.
- Presentation attack vulnerability in 2D systems:Legacy matching architectures face substitution pressure from 3D recognition and liveness detection technologies in mobile authentication.
Strategic Opportunities
- Retail analytics cloud deployment:Elastic compute for seasonal traffic patterns remains underpenetrated among mid-market retail chains seeking video-based customer flow analysis.
- Defense and intelligence on-premise systems:Data sovereignty requirements in classified environments sustain margin concentration for hardened, air-gapped recognition infrastructure.
- Convolutional neural network-edge AI convergence:Embedded inference chips enable real-time watchlist screening without cloud dependency, opening municipal and transportation verticals.
Industry Challenges
- Biometric data science talent scarcity:Shortage of engineers with combined expertise in computer vision, adversarial robustness, and privacy-preserving computation limits R&D velocity.
- NIST testing framework compliance timelines:Extended evaluation cycles for face recognition vendor tests delay product qualification for federal procurement channels.
- Legacy access control integration friction:Physical security system incumbents resist API openness, complicating multi-modal biometric rollouts in enterprise environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Recognition Market |
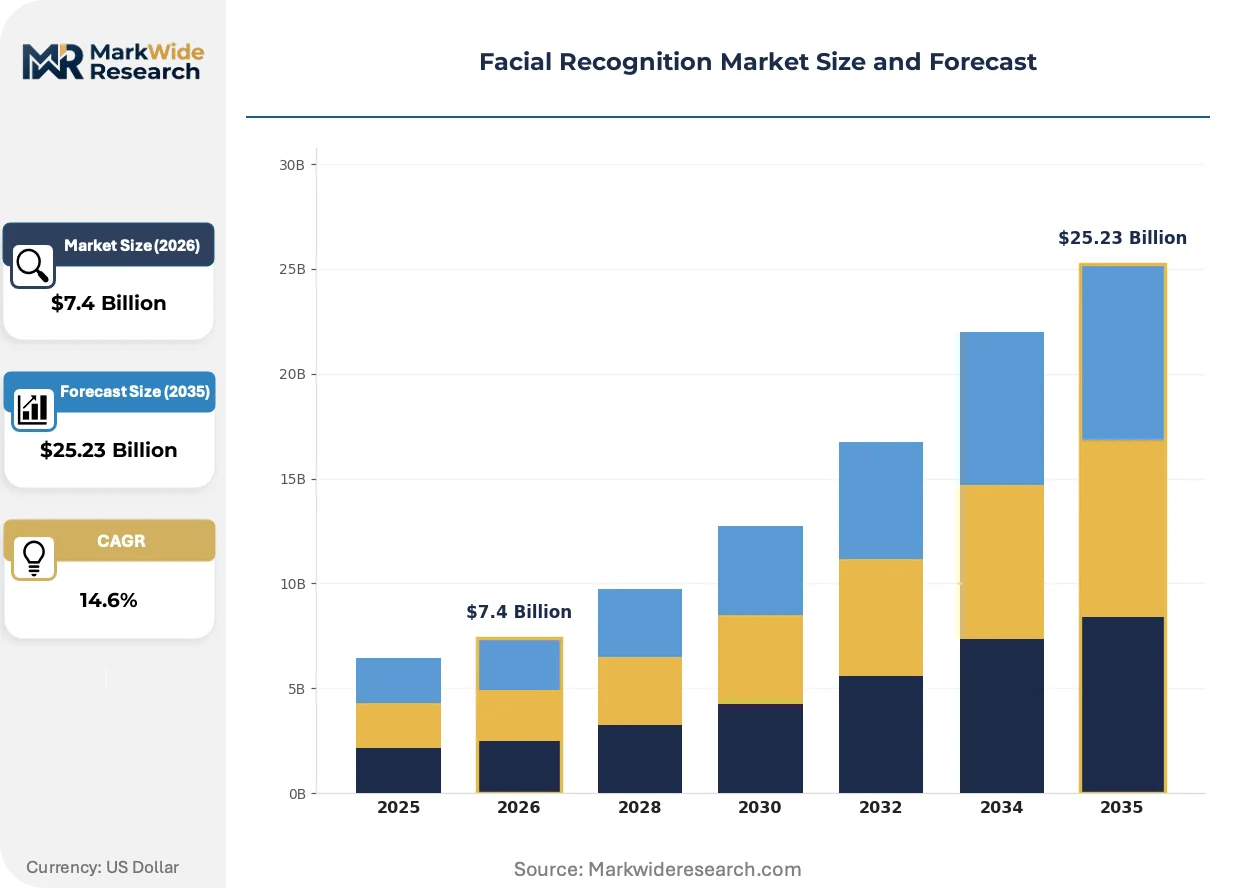
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $25.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Security, Retail Analytics, Personal Devices, Access Control Technology: 2D Recognition, 3D Recognition, Infrared Recognition, Deep Learning End User: Government, Retail, Healthcare, Automotive Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | NEC Corporation, Amazon Web Services, Thales Group, IDEMIA, Microsoft, Aware, FacePhi, Cognitec Systems, Megvii, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Recognition Market Emerging Trajectories
Algorithmic architectures are bifurcating market structure between cloud-scale inference operators and specialized edge device vendors, while regulatory divergence between European risk frameworks and Chinese deployment models forces parallel compliance investments.
Deep learning-based face recognition is bifurcating competitive positioning between accuracy-optimized cloud APIs and latency-constrained edge deployments. Law enforcement and border control agencies adopt cloud-scale inference for 1:N identification against billion-record galleries. Mobile device manufacturers prioritize on-device neural network execution to satisfy presentation attack resistance requirements without network dependency.
The EU AI Act's biometric identification system classifications are reshaping product roadmaps for vendors targeting European market access. High-risk system designations impose conformity assessment obligations that favor established players with dedicated regulatory affairs functions. Smaller point-solution vendors redirect R&D toward non-public-space applications or exit European procurement channels entirely.
Buyers are consolidating vendor relationships around full-stack platform providers capable of spanning enrollment, template management, and cross-modal identity verification. Enterprise security departments previously procuring point solutions for access control now issue unified biometric identity contracts. This concentration is most visible in United States financial services, where Know Your Customer mandates drive demand for integrated document verification and facial matching workflows.
Facial Recognition Market Segmentation
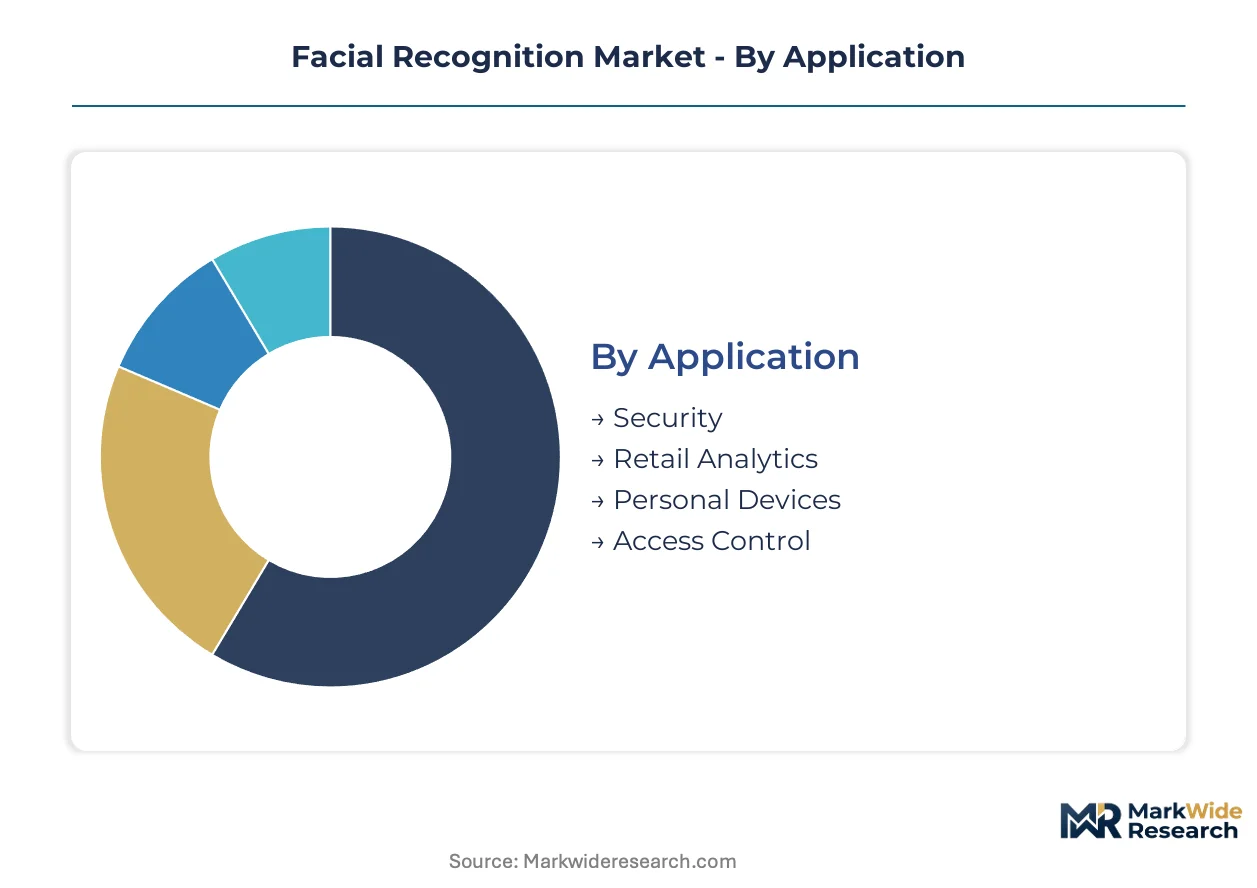
Segmentation in facial recognition reveals how algorithmic sophistication, deployment architecture, and end-use sensitivity create distinct margin pools. Vendors optimize pricing and R&D allocation differently across these dimensions, with security-critical applications commanding premium hardware-software bundles while consumer-facing deployments prioritize unit economics.
Application:
Margin concentration sits in security deployments where accuracy thresholds justify specialized hardware and long-term service contracts.
- Security:Law enforcement and border control agencies deploy 1:N identification against billion-record galleries, requiring cloud-scale inference infrastructure. TSA and EASA procurement frameworks in the United States and European Union drive hardware-software integration demand at aviation checkpoints. Data sovereignty requirements sustain premium pricing for air-gapped systems.
- Retail Analytics:Video-based customer flow analysis enables elastic compute procurement for seasonal traffic patterns. Mid-market retail chains underpenetrate this capability, creating vendor consolidation opportunities around full-stack platform providers.
- Personal Devices:Mobile authentication demands on-device neural network execution with presentation attack resistance. 3D recognition and liveness detection determine vendor selection in smartphone biometric modules.
- Access Control:Enterprise physical security departments issue unified biometric identity contracts spanning enrollment and template management. Legacy system incumbents resist API openness, complicating multi-modal rollouts.
The dominant share belongs to Security, while Retail Analytics is closing the gap fastest.
Technology:
Algorithm architecture determines competitive moat depth, with deep learning systems capturing premium pricing in accuracy-critical deployments while legacy 2D matching faces substitution pressure.
- Deep Learning:Convolutional neural network architectures displace legacy matching systems in law enforcement and border control procurement. Training throughput depends on Taiwan-based foundry capacity for GPU and specialized AI accelerators.
- 3D Recognition:Infrared depth mapping enables presentation attack resistance without network dependency. Mobile device manufacturers prioritize this capability for on-device authentication workflows.
- 2D Recognition:Legacy matching architectures face displacement by deep learning in accuracy-critical segments. Cost-sensitive access control applications sustain residual demand.
- Infrared Recognition:Thermal signature analysis serves China's smart city surveillance infrastructure and domestic public safety procurement pipelines. Night-time operational capability differentiates from visible-spectrum alternatives.
Deep Learning commands the dominant revenue position, though 3D Recognition is expanding most quickly in mobile authentication.
End User:
Procurement authority concentration varies sharply, with government identity programs offering multi-continent contract scale versus fragmented retail deployment decisions.
- Government:National identity programs and public safety procurement span enrollment, template management, and cross-modal verification. EU AI Act conformity obligations favor established vendors with dedicated regulatory affairs functions.
- Retail:Customer flow analysis and loss prevention drive demand for elastic cloud compute. Seasonal traffic patterns complicate capacity planning for mid-market chains.
- Healthcare:Patient identity verification and facility access control impose HIPAA compliance requirements on biometric data handling. Privacy-preserving computation expertise limits vendor qualification.
- Automotive:In-cabin driver monitoring and personalized settings activation embed facial recognition into vehicle electronics. Embedded inference chips enable real-time processing without cloud dependency.
Government retains the largest contract value, while Automotive is gaining share fastest through embedded integration.
Deployment:
Architecture choice reflects data sovereignty sensitivity, with classified environments demanding air-gapped infrastructure and consumer applications prioritizing latency over control.
- Cloud-Based:Elastic compute serves retail analytics buyers with seasonal traffic variability. Azure AI services embed facial verification into broader enterprise identity workflows.
- On-Premise:Defense and intelligence applications require hardened, air-gapped recognition infrastructure with data sovereignty guarantees. Margin concentration sustains despite slower growth.
- Edge Computing:Embedded inference chips enable real-time watchlist screening without network dependency. Municipal and transportation verticals open as latency constraints relax.
- Hybrid:Template enrollment occurs on-premise with cloud-based 1:N matching for scalability. Financial services Know Your Customer mandates drive this architecture for integrated document verification.
Cloud-Based deployment leads in new installations, though Edge Computing is climbing the fastest as inference efficiency improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's smart city programs demonstrate the lowest price sensitivity, absorbing premium hardware-software bundles for surveillance infrastructure, while mid-market retail chains in Europe and North America drive elastic cloud procurement with acute seasonal cost discipline.
United States
TSA biometric boarding gate deployments at major aviation hubs generate sustained hardware-software integration demand. NIST testing frameworks shape vendor qualification timelines for federal procurement channels. Dallas-Fort Worth and Atlanta airport clusters anchor the nation's largest concentration of live facial recognition checkpoint infrastructure.
China
National smart city surveillance infrastructure concentrates procurement for thermal signature analysis and infrared depth mapping capabilities. SAMR and MIIT coordinate standards for data collection consent protocols that determine vendor eligibility. Shenzhen and Hangzhou municipal authorities operate the world's densest networks of public-space biometric identification systems.
Germany
Enterprise access control departments issue unified biometric identity contracts spanning enrollment and template management. EU AI Act conformity obligations favor established vendors with dedicated regulatory affairs functions. Munich and Frankfurt security technology clusters drive adoption of presentation attack-resistant 3D recognition modules.
United Kingdom
Financial services Know Your Customer mandates accelerate integrated document verification and facial matching workflows. EDPB guidance extends product development timelines for biometric identification systems deployed in public spaces. London's fintech corridor concentrates demand for hybrid cloud-on-premise authentication architectures.
Japan
Automotive in-cabin driver monitoring systems embed facial recognition into vehicle electronics with real-time processing requirements. METI standards shape embedded inference chip specifications for latency-constrained deployments. Nagoya's automotive supplier ecosystem anchors development of edge-AI biometric modules for personalized vehicle settings activation.
Facial Recognition Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with full-stack platform vendors commanding premium pricing in accuracy-critical government deployments while point-solution specialists compete on unit economics in retail analytics. The market structure concentrates around three strategic archetypes: cloud-scale infrastructure operators with enterprise channel dominance, hardware-software integrators anchoring multi-continent identity programs, and embedded security specialists hardening systems against spoofing attacks. Dominant competitive moves include M&A activity targeting computer vision talent pools and strategic partnerships between algorithm vendors and Taiwan-based foundries securing AI accelerator supply.
Within the full-stack platform tier, NEC Corporation and Microsoft exemplify divergent approaches to market position—NEC leveraging biometric hardware-software integration for government identity programs, Microsoft embedding facial verification into broader Azure AI enterprise workflows. Thales Group occupies a distinct position among European defense-technology conglomerates, representing the embedded security specialist archetype with focus on critical infrastructure hardening. These three anchors illustrate how vendor consolidation around enrollment-to-verification capabilities is reshaping procurement patterns across security and financial services verticals.
| Leading Market Players |
|---|
| NEC Corporation |
| Amazon Web Services |
| Thales Group |
| IDEMIA |
| Microsoft |
| Aware |
| FacePhi |
| Cognitec Systems |
| Megvii |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity frameworks gate both vendor qualification and price differentiation simultaneously, with high-risk biometric system designations imposing documentation burdens that extend product development timelines while creating tiered compliance premiums for established players with dedicated regulatory affairs functions.
Pricing Analysis
Long-term service contracts and extended maintenance agreements drive lifetime value in security-critical deployments. Pricing stratifies across premium hardware-software bundles for government identity programs, standard SaaS-tiered subscriptions for enterprise access control, and economy per-transaction models for retail analytics. Cost compression in cloud-based tiers intensifies because hyperscaler API commoditization erodes algorithm premiums. Government buyers demonstrate the lowest price sensitivity, absorbing specialized hardware costs for air-gapped systems, while mid-market retail chains enforce acute seasonal cost discipline.
Supply Chain Analysis
Taiwan and South Korea anchor GPU and specialized AI accelerator fabrication for convolutional neural network training throughput. Supply chains draw from Taiwan-based foundry capacity, Chinese sensor module assembly, and Japanese precision optics for infrared depth mapping components. Single-source vulnerability concentrates in advanced node semiconductor manufacturing. Distribution runs through direct government procurement channels, systems integrator partnerships, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial recognition sits in early-cycle expansion as airport biometric boarding deployments accelerate under EASA and TSA frameworks, with penetration still below saturation across mid-market retail chains and municipal transportation verticals.
For Market Incumbents: Secure Taiwan-based foundry allocation for AI accelerator supply continuity against capacity constraints. Deepen embedded security expertise to harden systems against presentation attacks, as 3D recognition modules displace legacy 2D matching in mobile authentication procurement decisions.
For New Entrants and Emerging Players: Differentiate on edge-AI inference efficiency for real-time watchlist screening without cloud dependency. Target municipal transportation verticals and mid-market retail analytics as the most penetrable white-space segments, with go-to-market execution through systems integrator partnerships rather than direct enterprise sales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across convolutional neural network training infrastructure due to GPU cluster requirements. Long-term viability favors full-stack platform providers spanning enrollment-to-verification workflows over point-solution vendors facing consolidation pressure. Watch NIST testing framework compliance timelines as an inflection indicator for federal procurement channel access.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Vendor-Foundry Partnership | Secures Taiwan-based AI accelerator allocation against supply concentration risks. |
| EU AI Act Conformity Investment | Opens European government procurement channels under EDPB guidance frameworks. |
| Edge-AI Inference Chip Development | Enables real-time biometric processing without cloud dependency for transportation verticals. |
| Multi-Modal Biometric Integration | Spans enrollment, template management, and cross-modal verification for enterprise contracts. |
| Presentation Attack Resistance Certification | Qualifies vendors for mobile device authentication and aviation security checkpoint deployments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with biometric system procurement officers at aviation authorities, enterprise security directors, government identity program managers, and computer vision engineering leads. Secondary validation drew from NIST face recognition vendor test reports, EDPB biometric guidance documentation, EU AI Act regulatory filings, and hyperscaler AI service disclosures. Bottom-up unit economics modeling triangulated against top-down procurement budget analysis.
Across the analysis window, forecasts applied segment-level modeling across application type, deployment architecture, technology tier, and end-user industry. CAGRs derived from algorithm adoption curves, infrastructure deployment pipelines, and regulatory enablement timelines. Industry-specific inputs included TSA and EASA procurement schedules, SAMR standards coordination announcements, and Taiwan Semiconductor capacity expansion disclosures.
Forecasts assume regulatory continuity in EU AI Act implementation and Chinese SAMR coordination regimes; material policy shifts would require re-modeling. Specific risks include GPU supply disruption, extended NIST evaluation cycles, and fragmentation in United States state-level privacy legislation. Recalibration cycles align with material shifts in foundry capacity, aviation security procurement awards, and biometric identification system classification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Disk Encryption Software Market
Security Software
Hardware OTP Token Authentication Market
Security Software
Single Sign-On Market
Security Software
Passwordless Authentication Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Digital Credential Management Software Market
Security Software
Extended Detection and Response Market
Security Software
US and Latin America Identity and Access Management (IAM) Market
Security Software
Digital Risk Protection Platform Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Hardware Encryption Market
Security Software
Cloud File Security Software Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Anomaly Detection Tools Market
Security Software
Key Management Service Market